
 Fire Sprinkler Market | 2026-2036
Fire Sprinkler Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Sprinkler Market Intelligence
The European Green Deal's emphasis on building renovation and safety is expanding the addressable market for fire protection systems. Johnson Controls leverages its broad building automation portfolio to integrate fire safety solutions. Viking Group specializes in a comprehensive range of sprinkler components and systems, sustaining its market position through channel strength. Honeywell International competes by offering integrated fire and security platforms for commercial buildings.
Fire sprinklers are active fire protection devices designed to discharge water upon detecting heat from a fire. Each sprinkler head contains a heat-sensitive element, such as a glass bulb or fusible link, that activates at a specific temperature to release water. Wet pipe systems constitute the largest segment by installation type, favored for their reliability in commercial buildings. However, pre-action and dry pipe systems represent the fastest-growing segments, essential for protecting sensitive environments like data centers and museums from accidental water damage.
Regulatory compliance is non-negotiable, with standards from the National Fire Protection Association (NFPA) in the United States serving as a global benchmark. In Europe, CE marking under the Construction Products Regulation and adherence to relevant ISO standards dictate market access. For property managers and developers, the critical decision point is shifting from initial cost to total cost of ownership, factoring in insurance premiums and asset protection levels.
Market Dynamics
The fire sprinkler market's fundamental dynamic is a pivot from compliance-driven installations to risk-based asset protection. This shift is most pronounced in high-value commercial sectors, where insurance industry requirements and the immense cost of downtime now outweigh initial system expense.
Growth Catalysts
- Regulatory Mandates:Stricter building codes, such as those based on NFPA 13 in the United States, are compelling the retrofitting of fire sprinklers in older commercial and multi-family residential buildings, particularly in dense urban areas.
- Industrial Development:The construction of large-scale logistics centers and warehouses, driven by e-commerce, necessitates advanced fire protection to safeguard inventory and ensure business continuity, creating sustained demand for ESFR sprinklers.
- Urbanization in Emerging Economies:Rapid commercial and high-rise construction in countries like India and Brazil creates a foundational demand for fire sprinkler systems as part of new building infrastructure projects.
Market Restraints
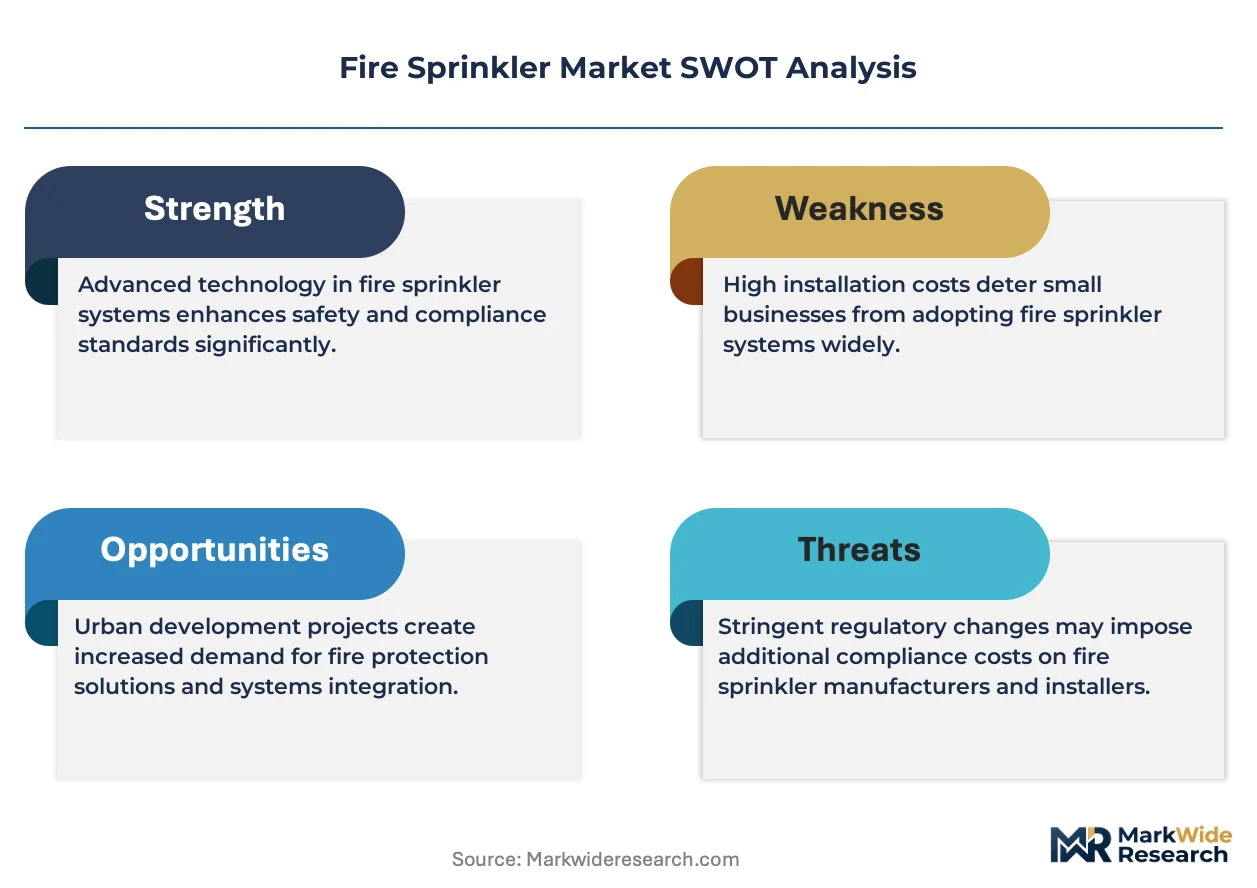
- High Initial Capital Outlay:The significant upfront cost of installation, especially for retrofitting complex systems into existing structures, remains a primary deterrent for property owners in the absence of strict enforcement or financial incentives.
- Risk of Water Damage:Perceived risks of accidental discharge and subsequent water damage from wet pipe systems act as a barrier to adoption in environments housing sensitive electronics or irreplaceable artifacts, like museums.
- Material Price Volatility:The market's reliance on metals such as steel for piping and brass for sprinkler heads exposes manufacturers and installers to price fluctuations in global commodity markets, impacting project bidding and margins.
Strategic Opportunities
- Smart System Integration:Incorporating IoT sensors and connectivity into sprinkler systems offers a transition to predictive maintenance and remote monitoring services, creating new recurring revenue models for installers and manufacturers.
- Residential Sector Penetration:The single-family and low-rise residential housing market in many European nations remains largely underpenetrated, presenting a substantial growth opportunity if regulations align more closely with North American standards.
- Specialized Hazard Protection:Developing and marketing systems specifically for new-risk environments, such as battery energy storage system (BESS) facilities, addresses a critical safety gap that standard sprinklers cannot manage effectively.
Industry Challenges
- Skilled Labor Deficit:A persistent shortage of certified designers and technicians trained to install, inspect, and maintain advanced fire sprinkler systems, such as pre-action systems, leads to project delays and increased labor costs.
- Legacy System Interoperability:Integrating modern, intelligent sprinkler control panels with older, existing fire alarm and building automation systems during retrofit projects presents significant technical and compatibility challenges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Sprinkler Market |
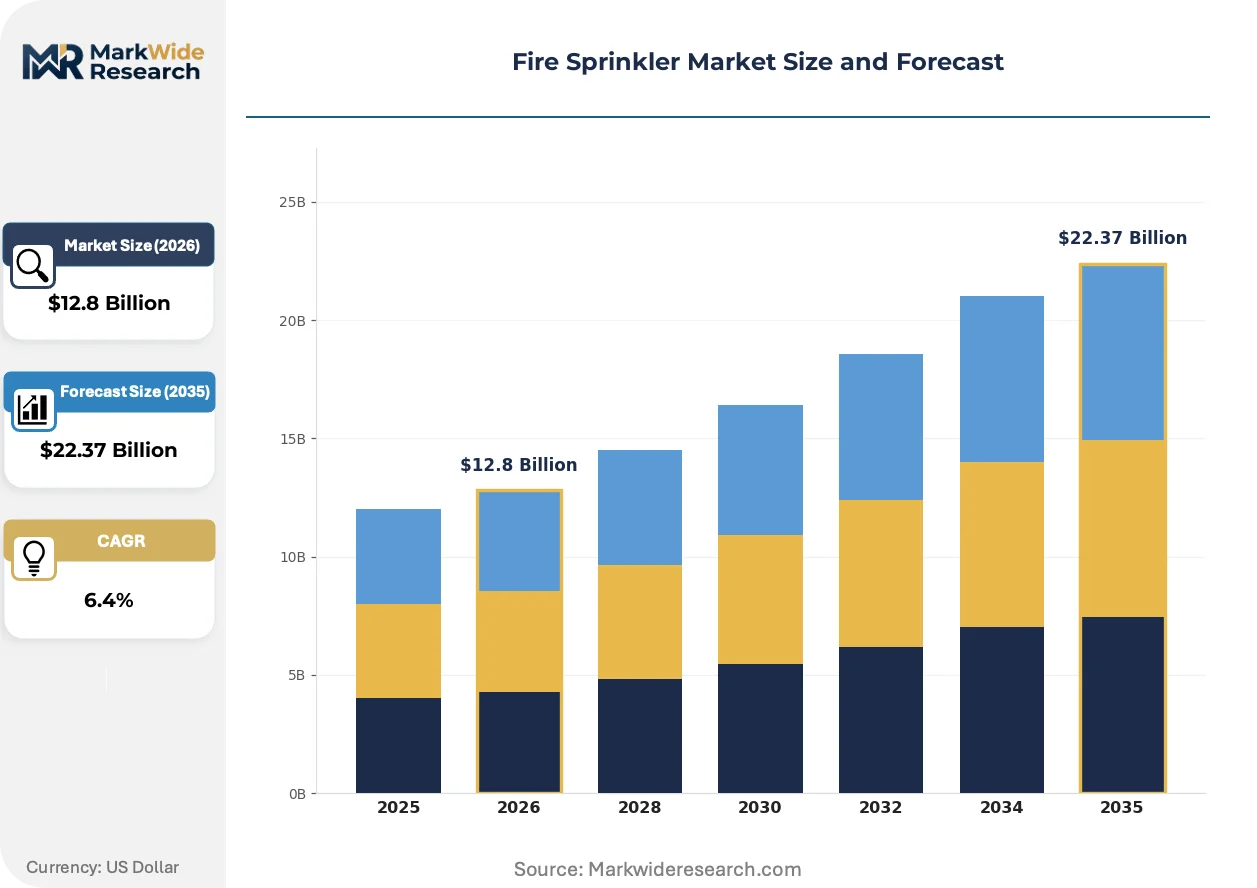
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Sprinklers, Deluge Sprinklers, Pre-action Sprinklers, Dry Pipe Sprinklers, Foam Water Sprinklers Installation Type: Wet Pipe Systems, Dry Pipe Systems, Deluge Systems, Pre-action Systems, Electronic Systems Application: Commercial Buildings, Warehouses, Educational Institutions, Data Centers, Airports, Museums End User: Industrial Facilities, Government Entities, Property Managers, Hospitality Sector, Transportation Hubs |
| Companies Covered | Johnson Controls, Viking Group, Reliable Automatic Sprinkler, Victaulic Company, Honeywell International, Potter Electric Signal Company, Minimax GmbH & Co. KG, API Group, Rapidrop Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Sprinkler Market Strategic Shifts & Innovations
The evolution from standalone mechanical devices to intelligent, networked systems defines the current technological trajectory. This transformation is driven by the need for faster response, greater precision, and seamless integration with overall building management platforms to enhance life safety and protect assets.
Electronically controlled sprinklers represent a significant product evolution. These systems use advanced heat or smoke detectors to send an electrical signal for activation, rather than relying on a localized thermal element. Data centers and semiconductor fabrication plants are the primary adopters, seeking to minimize activation time and water usage. This development is electrifying the response mechanism, enabling more precise, zone-based suppression.
The European Green Deal and its associated "Renovation Wave" initiative are creating powerful regulatory tailwinds. The policy encourages deep energy retrofits of older buildings, providing a critical opportunity for property owners to simultaneously upgrade fire protection systems to meet current EN standards. Commercial and institutional buildings in countries like Germany and France are most affected, as owners bundle safety upgrades with subsidized energy efficiency projects.
Performance-based design is altering specification and procurement behaviors within the industry. This approach allows fire protection engineers to use sophisticated fire modeling software to justify system designs that deviate from prescriptive codes, often achieving higher safety levels with fewer components. The trend is most visible in large, complex projects such as international airports and sports arenas, particularly in North America and the Middle East.
Fire Sprinkler Market Segmentation
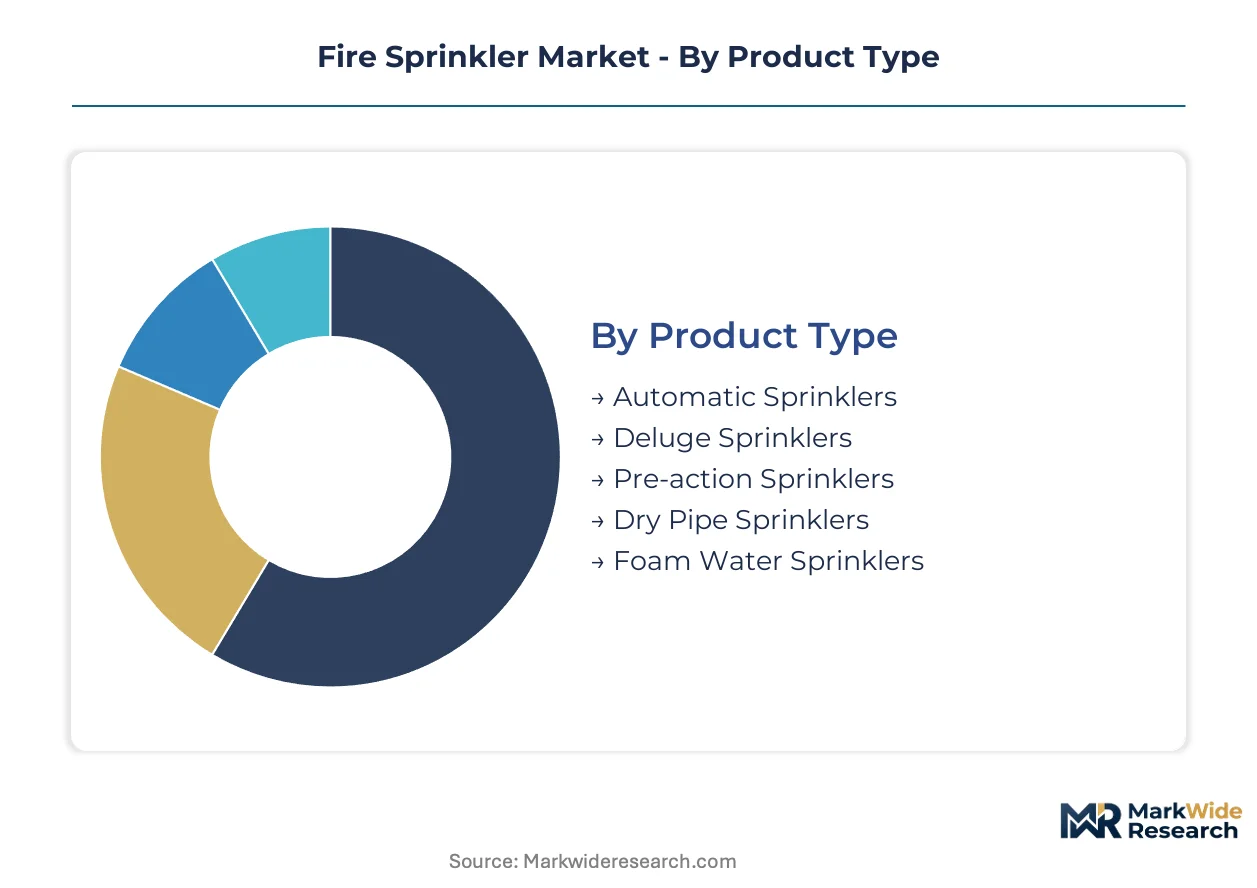
The fire sprinkler market's segmentation reflects diverse requirements across various building types and hazard profiles, enabling specialized solutions for effective fire suppression. Understanding these segments helps manufacturers and installers tailor offerings to specific regulatory demands and asset protection priorities.
Product Type:
The upgrade and replacement cycle for fire sprinkler components is increasingly driven by the need for more precise and water-efficient suppression technologies.
- Pre-action Sprinklers:These systems require two independent activations, typically a detector signal and a sprinkler head activation, before water is released into the piping, protecting sensitive environments like data centers from accidental water damage. Demand concentrates in high-tech facilities in North America and Europe, where asset protection is paramount.
- Dry Pipe Sprinklers:Designed for unheated areas, these systems contain pressurized air in the pipes, which is released upon activation, allowing water to flow. This prevents freezing in cold climates and is crucial for protecting unconditioned warehouses and parking garages in regions like Canada.
- Automatic Sprinklers:These standard sprinklers activate individually upon reaching a specific temperature, discharging water directly onto the fire.
- Deluge Sprinklers:All heads in a deluge system are open, and water is discharged simultaneously from all sprinklers when a separate detection system activates.
- Foam Water Sprinklers:These systems discharge a mixture of water and foam concentrate, effective for suppressing fires involving flammable liquids, often found in industrial facilities.
Volume placements concentrate in Automatic Sprinklers; the faster expansion belongs to Pre-action Sprinklers.
Installation Type:
Application-specific requirements dictate the selection of fire sprinkler installation types, balancing immediate response with protection against collateral damage.
- Wet Pipe Systems:These are the most common and reliable systems, with water constantly present in the pipes, allowing for immediate discharge upon sprinkler activation. Commercial buildings and multi-family residential structures in urban centers, particularly in the United States, widely adopt these systems.
- Electronic Systems:Incorporating advanced heat or smoke detectors, these systems use electrical signals for precise, zone-based activation, minimizing water usage. Data centers and semiconductor fabrication plants globally are primary adopters for their critical infrastructure.
- Dry Pipe Systems:These systems are filled with pressurized air or nitrogen and are used in areas where freezing temperatures are a concern, such as unheated warehouses.
- Deluge Systems:Featuring open sprinkler heads, these systems release a large volume of water simultaneously, suitable for high-hazard industrial applications.
- Pre-action Systems:Requiring dual activation, these systems are preferred for protecting sensitive assets against accidental water discharge, common in museums and archives.
The market's evolution points to increased sophistication for hazard-specific protection.
Application:
Customer type influences the choice and complexity of fire sprinkler applications, with varying needs for life safety, asset protection, and business continuity.
- Data Centers:These facilities demand highly specialized fire suppression systems, such as pre-action or electronically controlled sprinklers, to protect critical IT infrastructure from both fire and accidental water damage. Stricter NFPA standards for critical infrastructure drive demand in North America.
- Warehouses:Large-scale logistics centers and e-commerce warehouses require robust fire protection, often utilizing ESFR (Early Suppression, Fast Response) sprinklers to safeguard vast inventories. Expansion of e-commerce in Brazil fuels demand for advanced systems.
- Commercial Buildings:Office complexes, retail spaces, and high-rise structures represent a foundational demand segment for wet pipe and dry pipe systems, driven by building codes and insurance requirements.
- Educational Institutions:Schools and universities require reliable fire safety solutions to protect students and property, often integrating with existing building management systems.
- Airports:These complex environments necessitate comprehensive fire protection for terminals, hangars, and control towers, often involving a mix of system types.
- Museums:Protecting irreplaceable artifacts requires systems that minimize water damage risk, making pre-action systems a preferred choice.
Demand for fire suppression systems is diversifying across a range of high-value assets.
End User:
Margin considerations and the total cost of ownership significantly impact end-user decisions for fire sprinkler system procurement and maintenance.
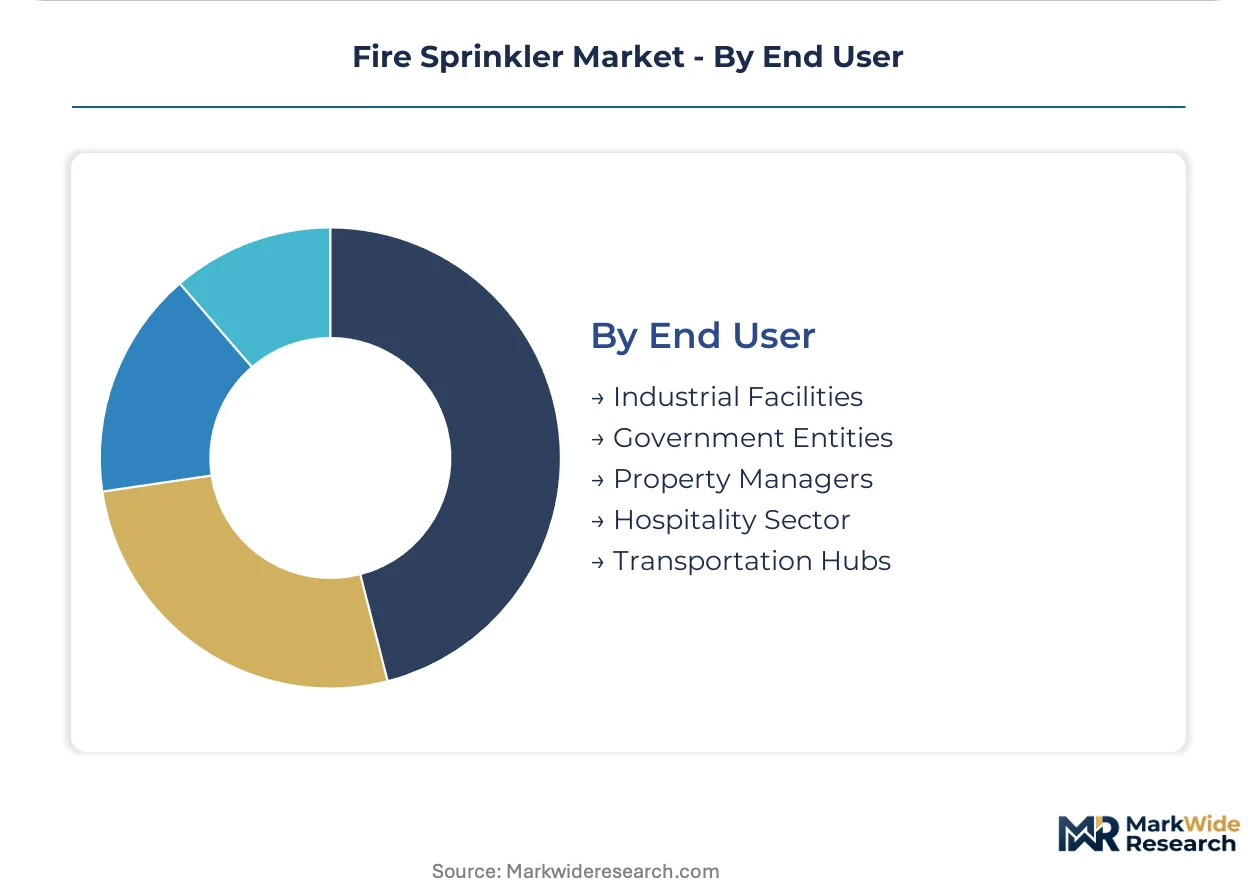
- Property Managers:For large commercial and residential portfolios, property managers prioritize systems that offer long-term reliability, lower insurance premiums, and reduced maintenance costs, shifting from initial capital outlay to total cost of ownership. Regulatory compliance with CE marking in Europe is a key factor.
- Industrial Facilities:Manufacturing plants, chemical processing sites, and power generation facilities require robust fire protection to ensure operational continuity and protect high-value machinery. Compliance with OSHA regulations in the US drives significant investment.
- Government Entities:Public buildings, military bases, and municipal infrastructure projects adhere to strict safety codes, often requiring advanced fire sprinkler systems.
- Hospitality Sector:Hotels, resorts, and convention centers prioritize guest safety and asset protection, often integrating fire systems with broader building automation.
- Transportation Hubs:Train stations, bus terminals, and ports require specialized fire safety measures to protect large public spaces and critical infrastructure.
Stakeholder priorities are shifting towards comprehensive asset protection and operational resilience.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The fire sprinkler market exhibits a distinct divide between mature consumption markets and rapidly expanding installation bases. North America and Europe drive demand for advanced systems and retrofits, while emerging economies like India and Brazil represent foundational growth for new infrastructure. This global dynamic shapes regional investment and regulatory landscapes.
United States
Demand for fire sprinklers in the United States stems from stricter building codes and commercial construction. NFPA 13 mandates installation in many new commercial and multi-family residential buildings. Cities like New York and Chicago are seeing extensive retrofitting projects. Data centers in Virginia also require specialized pre-action systems.
India
India's fire sprinkler market sees significant growth from rapid urbanization and industrial expansion. The country's Bureau of Indian Standards (BIS) sets fire safety norms for commercial and high-rise developments. Major metropolitan areas such as Mumbai and Bangalore are experiencing foundational demand. Logistics parks near Delhi are adopting advanced ESFR sprinklers.
Germany
Germany's fire sprinkler sector benefits from building renovation initiatives and stringent safety standards. The European Green Deal encourages deep energy retrofits, providing opportunities to upgrade fire protection systems to EN standards. Industrial facilities in the Ruhr Valley and commercial complexes in Berlin integrate modern fire safety solutions.
Brazil
Brazil experiences robust demand for fire sprinklers due to e-commerce growth and commercial development. National building codes and insurance requirements drive installations in new construction projects. Large-scale warehouses and logistics centers around São Paulo are investing in advanced fire suppression technologies.
Canada
Canadian demand for fire sprinklers is influenced by cold climate conditions and industrial facility requirements. Provincial building codes often mandate dry pipe systems for unheated warehouses and parking garages. The oil and gas sector in Alberta utilizes specialized foam water systems.
Fire Sprinkler Market Key Industry Players
The competitive structure tilts toward integrated solutions providers offering comprehensive fire safety portfolios. The market features a mix of large, diversified building technology conglomerates and specialized fire protection component manufacturers, creating a tiered landscape. Strategic archetypes include global system integrators, regional installation specialists, and niche product innovators focusing on specific hazard protection. Companies are increasingly focusing on portfolio diversification through smart system integration, forming strategic partnerships, and pursuing geographic expansion to capture new market opportunities.
Among the established industry participants, Johnson Controls and Honeywell International represent large conglomerates leveraging extensive building automation and security portfolios. These organizations occupy a position offering integrated fire and security platforms for commercial buildings, often targeting high-value applications. Viking Group, a specialized component manufacturer, sits within the segment focused on providing a comprehensive range of sprinkler components and systems. This company sustains its market position through strong channel relationships, exemplifying a focus on product breadth and distribution.
| Leading Market Players |
|---|
| Johnson Controls |
| Viking Group |
| Reliable Automatic Sprinkler |
| Victaulic Company |
| Honeywell International |
| Potter Electric Signal Company |
| Minimax GmbH & Co. KG |
| API Group |
| Rapidrop Global |
Cost & Logistics Intelligence
Steel and brass, key raw materials for fire sprinklers, experience price volatility in global commodity markets, impacting manufacturing costs and downstream project bids for installers.
Pricing Analysis
Pricing for fire sprinkler systems anchors on asset protection levels and total cost of ownership, not just initial installation. The dominant pricing model is project-based, often incorporating value-based components for specialized systems. Price differentiation stems from certification levels, such as NFPA or CE marking, and the customization required for sensitive environments like data centers. Material price volatility exerts pricing pressure, though systems for high-value assets command a premium. Property managers often exhibit higher price sensitivity to initial capital outlay, while high-value commercial sectors prioritize comprehensive asset protection over upfront costs.
Supply Chain Analysis
Regional distribution centers facilitate the movement of fire sprinkler components from manufacturing hubs to installation sites, ensuring localized supply. Geographic supply concentration for components draws from countries like China for basic parts, and Germany and the United States for advanced systems. The supply chain relies heavily on raw materials including steel, brass, and specialized heat-sensitive elements for sprinkler heads. Commodity price volatility for these metals represents a significant supply chain risk. Distribution typically runs through a manufacturer-to-distributor-to-installer model, with direct sales for large, complex projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fire sprinkler market faces supply constraints due to a persistent skilled labor deficit for advanced system installation and maintenance, which props up service pricing.
For Market Incumbents: Deploy strategic partnerships with educational institutions to address the skilled labor deficit, securing future installation and maintenance capacity. Investing in R&D for smart system integration can counter the threat from emerging smart system specialists. Acquiring smaller regional installers strengthens channel control and mitigates labor cost inflation. Companies should also focus on expanding predictive maintenance contracts, leveraging their existing client base.
For New Entrants and Emerging Players: Capture niche segments requiring specialized hazard protection, such as battery energy storage systems or sensitive data centers. The underpenetrated European residential sector presents a substantial white-space opportunity if regulations align with North American standards. Offering integrated smart system solutions with predictive maintenance contracts provides a strong go-to-market angle. Focus on demonstrating superior asset protection capabilities for critical infrastructure environments.
For Investors and Strategic Acquirers: Increased regulatory alignment between European and North American residential fire safety standards is the leading indicator that significant growth in the European residential sector is imminent. The market offers stable, long-term growth driven by compliance and asset protection, making it viable for long-term investment. Target vertically integrated mid-cap specialists with strong regional channel presence and smart system capabilities. The adoption rate of performance-based design in new construction projects serves as a key signal to watch for broader market shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in IoT-enabled Sprinkler Systems | Enhances predictive maintenance and creates recurring revenue streams for providers. |
| Expand Training Programs for Technicians | Addresses skilled labor shortages and ensures quality installation of complex systems. |
| Target European Residential Market | Unlocks substantial growth in an underpenetrated, compliance-driven segment. |
| Develop BESS-Specific Suppression Solutions | Addresses critical safety gaps in emerging high-risk energy storage facilities. |
| Acquire Regional Installation Specialists | Consolidates market share and strengthens local channel distribution networks. |
Research Approach
Document review covered NFPA codes, CE marking guidelines, ISO standards, and industry association reports, complemented by interviews with fire safety engineers, property managers, and building developers. Primary interviews with insurance risk assessors and building automation specialists provided granular insights into market dynamics. Secondary data sources included construction project databases and government regulatory publications. This approach ensured robust bottom-up and top-down triangulation of market data.
Historical market data was cross-referenced with expert panel input to project market trajectories across the analysis window. The analytical framework integrated quantitative modeling with qualitative assessments from industry leaders. Segmentation dimensions modeled included product type, installation type, application, end user, and regional regulatory cluster. Compound annual growth rates were derived from projected volume and value changes. Urbanization rates, commercial construction pipelines, and regulatory updates served as key industry-specific forecast inputs.
The model holds under current regulatory frameworks and projected construction activity; deviation in global commodity prices or unforeseen technological disruptions would shift forecast outcomes. Forecasts reflect assumptions regarding economic stability and continued infrastructure development. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Africa Smart Card Market
Others
Ambient Assisted Living and Smart Home Market
Others
Thiamethoxam Market
Others
Thermal Insulation Solution for LNG and LPG Market
Others
Residential Electrical Conduit Market
Others
Asia-Pacific Road Safety Market
Others
Astrology Market
Others
Infant Positioning Aids Market
Others
Global ESD Protection Devices Market
Others
Hopper Dryers Market
Others
India Home Automation Market
Others
Bimodal Identity Management Solutions Market
Others
US Cat Food Market
Others
Asia-Pacific Medium-Density Fiberboard Market
Others
Turkey Health and Medical Insurance Market
Others
Cloud Broadcasting Solutions Market