
 Infant Positioning Aids Market | 2026-2036
Infant Positioning Aids Market Size, Share, and Industry Trends Forecast 2026-2036
Infant Positioning Aids Market Foresight
The gap between premium clinical-grade positioning systems and basic retail commodities is repositioning how manufacturers allocate engineering resources and channel investments. Koninklijke Philips N.V. leverages its hospital-installed base to sustain recurring sales of NICU-compatible positioning platforms. Drägerwerk AG & Co. KGaA anchors its portfolio through European regulatory pre-certification, while Fisher & Paykel Healthcare competes on respiratory-integrated positioning designs for ventilated infants.
Infant positioning aids comprise engineered support devices—typically fabricated from medical-grade foam, gel composites, or breathable textile laminates with specified density ratings and pressure redistribution indices—designed to maintain anatomical alignment, prevent plagiocephaly, and support thermoregulation in preterm and term neonates during sleep or clinical procedures. Wedge pillows and sleep positioners lead volume but face margin compression from safety recalls, whereas gel-based products command premium pricing in tertiary neonatal settings due to thermal conductivity specifications. Specialty stores and baby boutiques capture higher per-unit values than online retail, though e-commerce channels show faster growth in direct-to-consumer foam positioning accessories.
The FDA maintains active enforcement against non-compliant inclined sleep positioners, while the CPSC administers mandatory standards for infant sleep surfaces under the Safe Sleep Act framework, compelling manufacturers to redesign products or exit the US market entirely. ISO 10993 biocompatibility testing and European MDR classification for Class I medical devices add parallel compliance burdens for multinational suppliers. Stakeholders must monitor evolving pediatric sleep safety guidance from the American Academy of Pediatrics and corresponding reimbursement code revisions from CMS to anticipate demand shifts between clinical and homecare positioning segments.
Market Dynamics
FDA enforcement actions against inclined sleep positioners are forcing manufacturers to reallocate R&D spending toward flat-surface positioning systems that satisfy Safe Sleep Act requirements while maintaining clinical efficacy for NICU applications.
Growth Catalysts
- Medicaid reimbursement expansion:CMS coding revisions for positioning interventions in neonatal intensive care units are accelerating hospital procurement cycles across US health systems.
- Gel composite thermal conductivity:Advanced pressure redistribution materials with specified heat dissipation indices are displacing basic foam wedges in tertiary neonatal settings.
- Developmental care protocol upgrades:Hospital systems are standardizing anatomical alignment protocols for preterm infants, creating pull-through demand for engineered positioning platforms.
Market Restraints
- Medical-grade foam supply concentration:Polyurethane foam feedstock production clusters in East Asian chemical manufacturing hubs, exposing converters to freight cost volatility and tariff exposure.
- Biocompatibility testing timelines:ISO 10993 cytotoxicity and sensitization studies for new textile laminates extend product development cycles by 8-14 months.
- Retail commodity substitution:Unregulated basic sleep positioners from direct-to-consumer e-commerce channels undercut clinical-grade pricing in homecare segments.
Strategic Opportunities
- Respiratory-integrated positioning convergence:Ventilator manufacturers are seeking co-developed positioning platforms that maintain airway patency during prone positioning protocols.
- European MDR pre-certification pathways:Early compliance with Class I medical device classification requirements opens preferential tender access in German and French hospital procurement.
- Specialty baby boutique channel expansion:Premium gel-based products command 40-60% per-unit value premiums over online retail through tactile evaluation and trained staff consultation.
Industry Challenges
- Pediatric biomedical engineering talent scarcity:Specialized expertise in neonatal anthropometry and pressure mapping analytics concentrates in academic medical centers, limiting manufacturer access.
- Legacy manufacturing equipment retooling:Foam cutting and textile lamination lines require capital replacement to meet revised flammability standards under CPSC infant sleep surface rules.
- Cross-jurisdictional labeling complexity:Divergent FDA, CE marking, and Health Canada safety claims requirements force SKU proliferation and inventory segmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infant Positioning Aids Market |
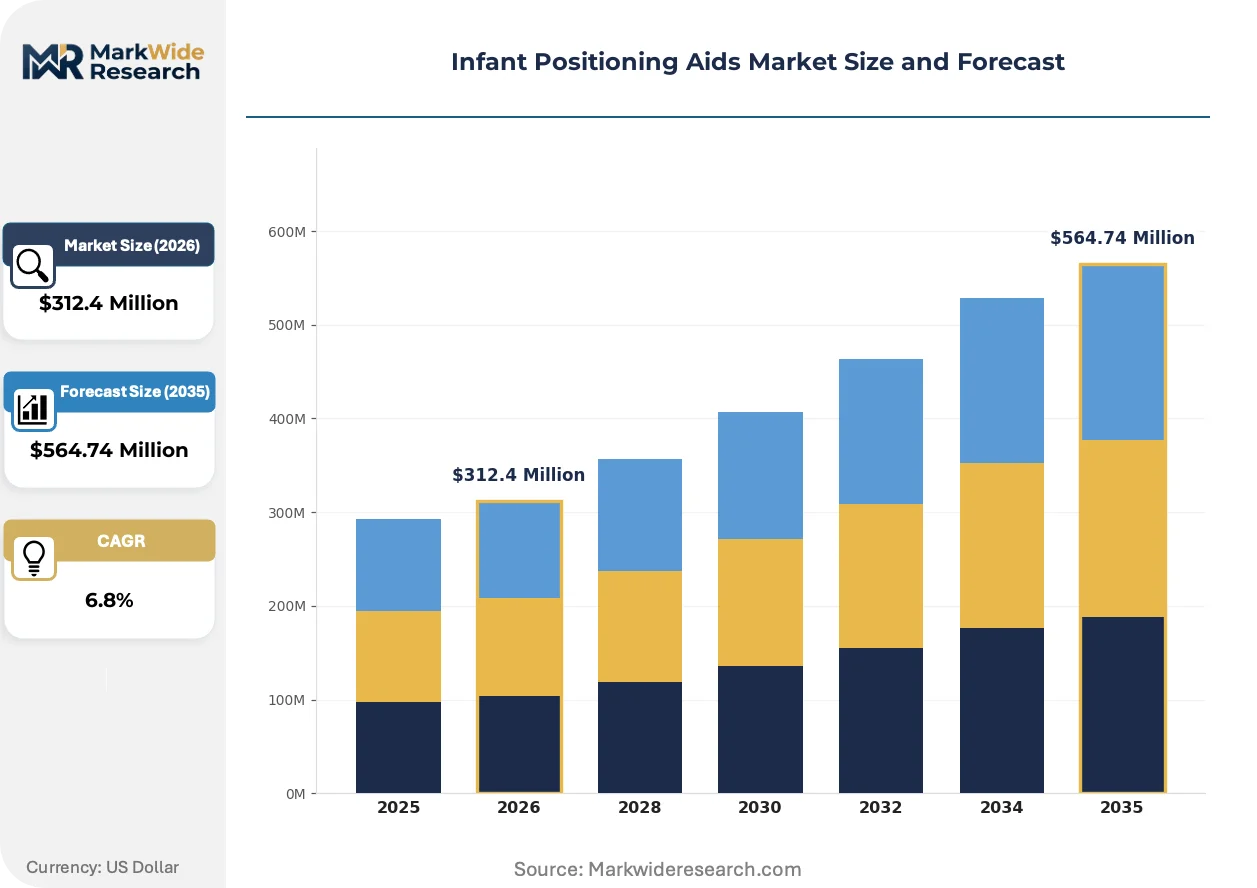
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wedge Pillows, Bolster Cushions, Positioners, Sleep Positioners Material: Foam, Cotton, Polyester, Gel Age Group: Newborns, Infants, Toddlers, Preemies Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Baby Boutiques |
| Companies Covered | Koninklijke Philips N.V., Advanced Global Health Ltd, International Biomedical, Fisher-Price, Inc., GE HealthCare, Drägerwerk AG & Co. KGaA, Medtronic, Masimo, Fisher & Paykel Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infant Positioning Aids Market Shifts & Advancements
Positioning aid engineering is converging with respiratory therapy and thermoregulation disciplines, eroding traditional boundaries between sleep support and acute care devices. Material science advances and regulatory stringency are jointly determining which product architectures survive commercialization.
Sensor-embedded positioning platforms are unifying pressure monitoring, temperature regulation, and positional feedback into single-device architectures. NICU departments at academic medical centers are piloting these systems for ventilated infants requiring continuous prone positioning. The technology is unifying previously separate device categories—sleep surfaces, warming platforms, and respiratory support aids—into integrated care stations that compress capital equipment footprints and consolidate vendor relationships.
The FDA's Safe Sleep Act enforcement framework is eliminating non-compliant inclined positioners from US distribution channels. Manufacturers must redesign products to achieve flat-surface certification or exit the market entirely. Hospital procurement departments are responding by restricting vendor pools to suppliers with documented FDA 510(k) clearances, shifting competitive advantage toward established clinical-grade producers with regulatory affairs infrastructure.
Hospital supply chain departments are consolidating positioning aid procurement through integrated delivery networks that negotiate system-wide contracts. Independent acute care facilities and standalone birthing centers are losing purchasing leverage as buying power concentrates in multi-hospital systems. This concentration is most visible in Texas and California, where large health systems command sufficient volume to demand custom SKU configurations and dedicated inventory allocation from positioning platform manufacturers.
Infant Positioning Aids Market Segmentation
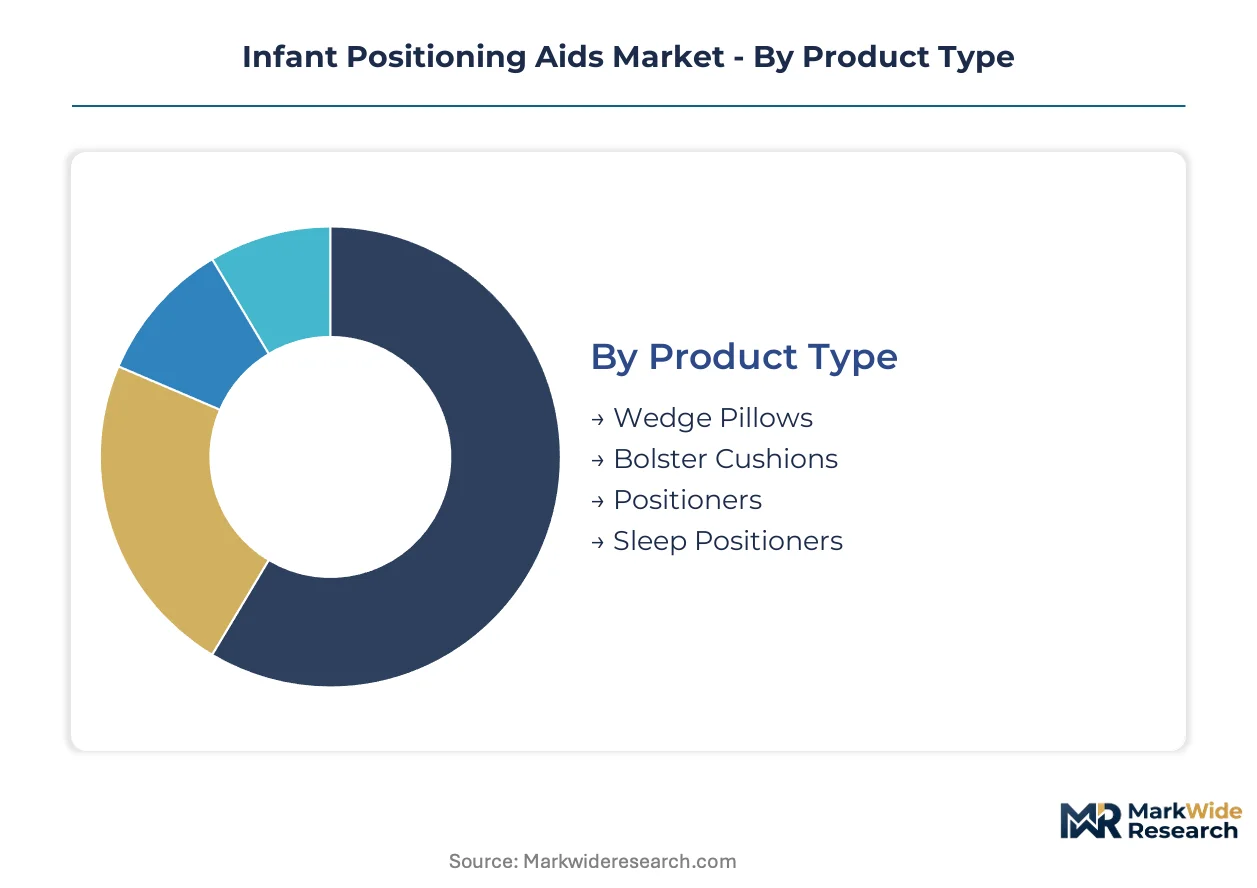
Segmentation in infant positioning aids determines regulatory pathways, margin profiles, and channel access. Product architecture and material composition jointly dictate whether devices qualify for NICU procurement or remain confined to retail homecare segments.
Product Type:
Integration depth separates standalone sleep accessories from systems engineered for ventilator compatibility and continuous monitoring.
- Wedge Pillows:Fabricated from medical-grade foam with specified density ratings and 30-degree incline limits per FDA Safe Sleep Act guidance. Demand concentrates in US hospital systems upgrading developmental care protocols, though enforcement actions against non-compliant inclined designs are compressing margins.
- Positioners:Engineered anatomical support platforms with pressure redistribution indices and thermoregulation specifications for preterm neonates. Tertiary neonatal intensive care units in academic medical centers drive procurement of gel-integrated designs that maintain airway patency during prone positioning.
- Bolster Cushions:Cylindrical foam or fiberfill supports for lateral positioning and reflux management in homecare settings.
- Sleep Positioners:Flat-surface devices redesigned to satisfy CPSC infant sleep surface standards after FDA enforcement eliminated inclined variants from US distribution.
Wedge pillows lead volumes today; positioners are gaining share fastest.
Material:
Cost tier stratification runs from commodity fibers to engineered composites with thermal conductivity specifications.
- Gel:Medical-grade silicone or hydrogel composites with specified heat dissipation indices for thermoregulation in ventilated infants. Tertiary NICU settings in Germany and France command premium pricing for MDR-compliant Class I medical device certification.
- Foam:Polyurethane and memory foam formulations with biocompatibility testing under ISO 10993 for clinical-grade applications. Supply concentration in East Asian chemical manufacturing hubs exposes converters to freight volatility.
- Cotton:Natural fiber batting for breathable, low-cost homecare accessories with limited clinical penetration.
- Polyester:Synthetic fiberfill and textile laminates for durable, washable retail products at economy price points.
Foam dominates unit volumes; gel composites show the steepest expansion trajectory in clinical procurement.
Age Group:
Application severity and reimbursement eligibility diverge sharply between acute neonatal care and developmental homecare.
- Preemies:Devices engineered for infants below 37 weeks gestational age requiring thermoregulation support and positional stability during respiratory therapy. US Medicaid reimbursement for positioning interventions in NICU settings anchors demand.
- Newborns:Term infants in the first 28 days, with positioning needs concentrated in hospital-based developmental care protocols.
- Infants:One to twelve months, representing the largest addressable population for retail sleep positioners and plagiocephaly prevention devices.
- Toddlers:Twelve to thirty-six months, with limited positioning aid requirements outside specialized therapeutic applications.
Infants represent the broadest customer base; preemies command the highest per-unit value in clinical procurement.
Distribution Channel:
Customer type and purchase authority separate institutional procurement from discretionary consumer spending.
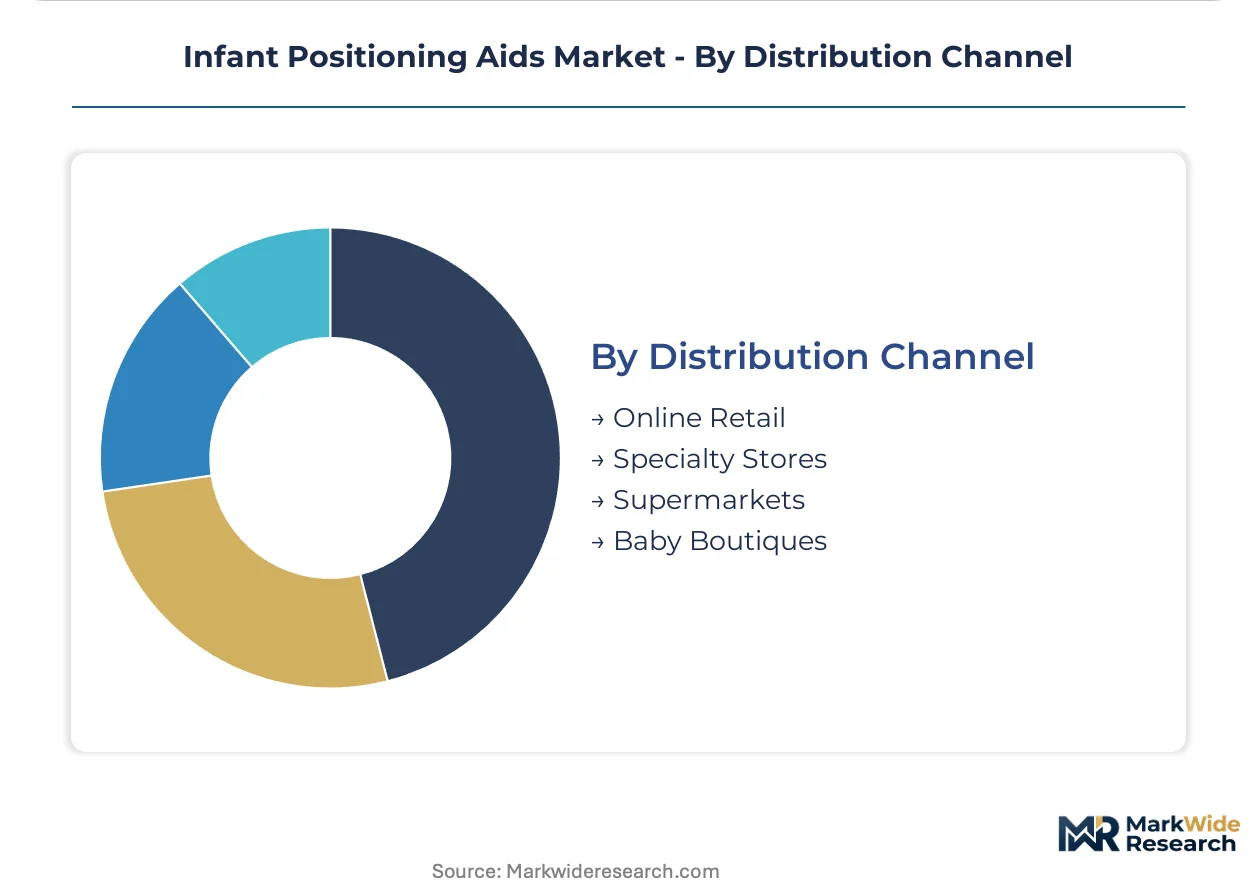
- Specialty Stores:Trained staff consultation and tactile evaluation support 40-60% per-unit value premiums for premium gel-based products. Urban clusters in California and Texas with concentrated high-income demographics anchor this channel.
- Online Retail:Direct-to-consumer foam accessories show fastest volume growth, though unregulated basic positioners undercut clinical-grade pricing. Platform algorithms and review systems increasingly filter out non-compliant SKUs following FDA enforcement.
- Baby Boutiques:Curated premium assortments in affluent suburban markets, with limited scale but highest margin retention.
- Supermarkets:Mass-market economy positioning aids with minimal clinical claims and price-driven competition.
Online retail leads volume expansion; specialty stores retain margin leadership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neonatal biomedical engineers concentrate in academic medical centers across the United States, Germany, Japan, China, and France, anchoring regional demand for clinical-grade positioning systems. These talent clusters shape procurement patterns and regulatory compliance priorities in each market.
United States
Medicaid reimbursement expansion for NICU positioning interventions drives hospital procurement cycles across Texas and California health systems. FDA enforcement against inclined sleep positioners under the Safe Sleep Act compels manufacturers to redesign products for flat-surface certification. The Boston-Cambridge cluster anchors pediatric biomedical engineering research, translating academic protocols into commercial positioning platforms.
Germany
European MDR pre-certification for Class I medical devices opens preferential tender access in tertiary neonatal settings across Bavaria and North Rhine-Westphalia. REACH compliance requirements for medical-grade foam feedstocks add parallel testing burdens for textile laminate suppliers. The Stuttgart industrial corridor concentrates gel composite manufacturing with specified thermal conductivity indices for ventilated infant applications.
Japan
PMDA guidance on neonatal sleep surface safety shapes domestic certification timelines for positioning aid manufacturers serving Tokyo and Osaka metropolitan hospitals. METI standards for medical device quality management systems extend product development cycles for foam-based wedges. The Kansai region hosts specialized textile converters developing breathable laminates for thermoregulation support in preterm care.
China
NMPA classification requirements for infant sleep products are tightening import pathways for foreign positioning platform manufacturers targeting Shanghai and Beijing NICU departments. GB standards for flammability and biocompatibility testing create domestic compliance advantages for local foam converters. The Yangtze River Delta clusters polyurethane chemical production, exposing positioning aid fabricators to feedstock cost volatility.
France
ANSM vigilance reporting requirements for pediatric medical devices influence positioning system design specifications in Paris and Lyon academic medical centers. CE marking under MDR Article 117 mandates notified body involvement for gel-based products with therapeutic claims. The Auvergne-Rhône-Alpes region concentrates silicone composite manufacturing for pressure redistribution platforms serving ventilated neonates.
Infant Positioning Aids Market Competitive Landscape
Top-tier vendors anchor hospital-installed base relationships, while mid-tier specialists compete on material science differentiation and regional regulatory pre-certification. The market structure reflects consolidation around clinical-grade producers with FDA 510(k) clearances and European MDR infrastructure, alongside fragmentation in direct-to-consumer foam accessories. Two strategic archetypes dominate: diversified health technology conglomerates leveraging respiratory therapy integration, and focused neonatal care specialists commanding premium positioning in tertiary settings. Competitive moves center on co-development partnerships with ventilator manufacturers and capacity retooling for flat-surface compliance.
Within the diversified health technology tier, Koninklijke Philips N.V. and GE HealthCare exemplify platform convergence strategies, while Drägerwerk AG & Co. KGaA anchors European regulatory pre-certification pathways. Fisher & Paykel Healthcare occupies a position bridging respiratory-integrated designs with developmental care protocols. These three companies represent distinct competitive vectors: hospital system consolidation leverage, regional regulatory infrastructure, and therapy integration specialization.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Advanced Global Health Ltd |
| International Biomedical |
| Fisher-Price, Inc. |
| GE HealthCare |
| Drägerwerk AG & Co. KGaA |
| Medtronic |
| Masimo |
| Fisher & Paykel Healthcare |
| Others |
Supply & Pricing Matrix
Hospital integrated delivery networks in Texas and California anchor procurement volume, concentrating buying power around contract-based long-term offtake agreements that compress margins for mid-tier suppliers without FDA 510(k) clearances. This buyer concentration forces manufacturers toward three-tier pricing structures separating MDR-certified gel platforms from ISO 10993-tested foam wedges and unregulated cotton accessories.
Pricing Analysis
Bundled service contracts covering installation, training, and preventive maintenance command 25-35% premiums over unbundled per-unit transactions in tertiary NICU settings. Price differentiation hinges on FDA clearance tier and thermal conductivity certification, with gel-integrated platforms resisting downward pressure while foam wedges face cost compression from direct-to-consumer substitution. Homecare segments show highest price sensitivity; academic medical centers prioritize clinical efficacy over unit cost.
Supply Chain Analysis
Freight cost volatility from East Asian chemical manufacturing hubs to North American converters is reshaping inventory strategies for polyurethane foam feedstocks. Medical-grade silicone production concentrates in Germany, China, and Japan, with textile lamination capabilities anchored in the Kansai region and Yangtze River Delta. Single-source vulnerability for specialized hydrogel composites threatens continuity, while distribution runs through GPO-mediated hospital networks and direct-to-consumer e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European MDR pre-certification costs run 40-50% below US FDA 510(k) pathways for Class I medical devices, creating arbitrage opportunities for manufacturers willing to anchor initial commercialization in German and French hospital systems before US market entry.
For Market Incumbents: Anticipate consolidation pressure from respiratory-integrated positioning convergence by deepening partnerships with ventilator manufacturers and securing exclusive co-development agreements. Lock in gel composite supply through backward integration or captive long-term contracts with Stuttgart corridor silicone processors before feedstock allocation tightens. For New Entrants and Emerging Players: Independent birthing centers and standalone acute care facilities outside Texas and California health systems represent the most penetrable channel, as these buyers lack IDN negotiating leverage and prioritize rapid delivery over custom SKU configurations. Partner with regional medical device distributors holding existing GPO relationships to bypass direct hospital procurement barriers. For Investors and Strategic Acquirers: Ventilator manufacturers and respiratory therapy platforms are the most active acquirer category in this space, seeking positioning aid capabilities to complete integrated care station offerings. Target acquisition candidates with documented European MDR infrastructure and existing silicone composite formulation expertise. Watch FDA enforcement intensity against non-compliant inclined sleep products as the signal for accelerated market share redistribution toward clinical-grade producers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Unlocks procurement access to US hospital systems restricting vendor pools to compliant suppliers. |
| European MDR Pre-Certification | Opens preferential tender access in German and French tertiary neonatal settings ahead of competitors. |
| Hospital System Partnership | Secures recurring revenue through integrated delivery network contracts in Texas and California. |
| Silicone Composite Backward Integration | Captures margin and insulates supply continuity from Yangtze River Delta feedstock volatility. |
| Respiratory Platform Co-Development | Positions products for ventilator-integrated care station architectures consolidating NICU capital equipment. |
Research Methodology
Coverage spans the United States, Germany, Japan, China, and France, with primary inputs from each market anchoring regional demand calibration. The research combines structured interviews with neonatal intensive care unit clinicians, hospital procurement committee members, biomedical engineers at academic medical centers, and GPO contracts managers with secondary validation from FDA 510(k) filings, European MDR notified body databases, CMS Medicare reimbursement schedules, and hospital procurement transaction records. Bottom-up unit demand estimates triangulate against top-down market sizing from manufacturer revenue disclosures and trade flow analysis.
Granularity-level modeling disaggregates volume and value across product type, material composition, age group segmentation, and distribution channel, with additional dimensional splits for regulatory certification tier and thermal conductivity specification. CAGRs derive from segment-level growth rate synthesis applied across the projection horizon, incorporating Medicaid reimbursement expansion trajectories, ISO 10993 testing timeline assumptions, and CPSC enforcement intensity scenarios as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA Safe Sleep Act enforcement evolution, European MDR implementation pacing, and polyurethane foam feedstock cost trajectories. Forecasts reflect assumptions about regulatory stability and reimbursement continuity that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Edge Computing in Healthcare Market
Others
Global Snow Sports Apparel Market
Others
Storage Dewar and Dry Shipper Market
Others
Middle East and Africa Electric Vehicle Battery Electrolyte Market
Others
Paraffin Physical Therapy Market
Others
North America Luxury Car Market
Others
Bio-Based Leather Market
Others
Hopper Dryers Market
Others
Global Smart Home Installation Service Market
Others
Global Microcontroller Embedded Systems Market
Others
Animal Feed Alternative Protein Market
Others
Aboveground Storage Tanks Market
Others
ISO Cylinder Market
Others
Africa Lime Market
Others
India Smart Home Market
Others
North America Forklift Truck Market