
 Astrology Market | 2026-2036
Astrology Market Size, Share, and Industry Trends Forecast 2026-2036
Astrology Market Analysis
Subscription-based birth chart analysis is expanding beyond one-time purchases into recurring revenue models. Chani leverages deep personalization algorithms to anchor its premium tier. Nebula competes through aggressive mobile-first distribution across emerging markets. Sanctuary differentiates by blending live human astrologers with automated content pipelines.
Astrology encompasses the calculation and interpretation of celestial body positions relative to Earth coordinates, typically requiring precise birth date, time, and location data processed through ephemeris tables and house systems. Its commercial purpose spans entertainment, self-reflection guidance, relationship counseling adjuncts, and wellness lifestyle integration. Horoscope readings occupy the largest volume share due to low production cost and daily refresh cycles, while birth chart analysis commands premium pricing through customization depth. Mobile app delivery is accelerating fastest as smartphone penetration and micro-payment infrastructure mature across demographics previously excluded from in-person consultations.
The US Federal Trade Commission monitors astrology platforms for deceptive advertising claims, particularly around predictive accuracy guarantees and subscription billing transparency. India's Advertising Standards Council enforces disclaimers on astrological efficacy in digital promotions, affecting how platforms structure user onboarding flows. Content creators must navigate platform-specific terms from Apple App Store and Google Play regarding fortune-telling category restrictions. Stakeholders should track evolving definitions of astrology as entertainment versus wellness service, since this classification determines which regulatory frameworks apply and where liability exposure concentrates.
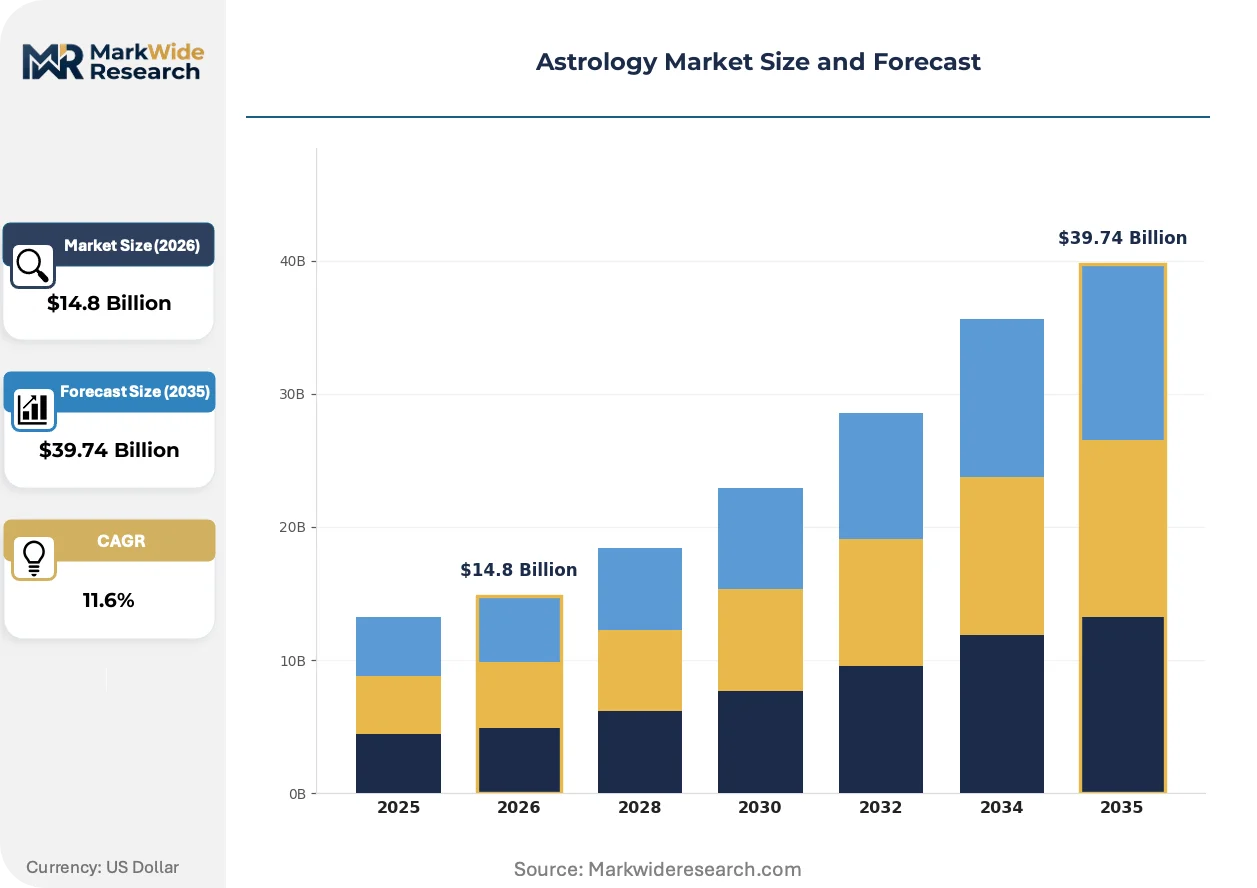
Market Dynamics
Mobile-first delivery is compressing customer acquisition costs while India's Ministry of Electronics and Information Technology guidelines force platform operators to restructure subscription billing flows and content moderation protocols.
Growth Catalysts
- Micro-payment infrastructure maturation:Smartphone penetration across Southeast Asian and African markets enables daily horoscope monetization through carrier billing and digital wallets.
- GDPR-compliant personalization engines:European data protection frameworks legitimize algorithmic birth chart analysis when consent architectures are properly engineered.
- Wellness economy convergence:Corporate employee assistance programs in the United States now reimburse astrology consultations as mental health adjuncts.
Market Restraints
- Ephemeris data licensing costs:Swiss Ephemeris and proprietary astronomical calculation libraries impose recurring royalty burdens on platform operators.
- Fortune-telling category restrictions:Apple App Store and Google Play content policies in multiple jurisdictions cap subscription pricing tiers and restrict predictive health claims.
- Astrologer supply concentration:Certified practitioners cluster in Los Angeles, London, and Mumbai, creating talent procurement bottlenecks for scaled platforms.
Strategic Opportunities
- Brazilian regulatory whitespace:ANVISA has not classified astrology as medical or wellness service, permitting broader efficacy claims than FDA or EMA jurisdictions allow.
- Generative text-to-natal-chart pipelines:Large language models trained on house system interpretations enable real-time synthesis of Placidus and Whole Sign analyses.
- Corporate wellness channel expansion:Human resources departments seek low-cost employee engagement tools, positioning daily transit readings as burnout prevention instruments.
Industry Challenges
- Ephemeris calculation precision standards:Platform operators must validate birth time rectification algorithms against International Astronomical Union coordinate systems to avoid refund disputes.
- Cross-platform identity synchronization:Users expect seamless chart portability between iOS, Android, and web interfaces, requiring complex API standardization across competing data formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Astrology Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $39.74 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Horoscope Readings, Birth Chart Analysis, Compatibility Reports, Tarot Readings Customer Type: Individuals, Couples, Businesses, Organizations Delivery Mode: In-Person, Online, Mobile App, Phone Consultation Content Format: Text Reports, Video Sessions, Live Streams, Podcasts |
| Companies Covered | Chani, AstroMatrix, Co – Personal Astrology, Astro Future, Astrology Zone, Sanctuary, Nebula, Daily Horoscope, TimePassages, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Astrology Market Emerging Trajectories
Algorithmic personalization is displacing generic sun-sign content while regulatory scrutiny intensifies around subscription transparency and predictive accuracy claims.
Machine learning models trained on historical transit data and user-reported outcomes are integrating probabilistic forecasting into premium subscription tiers. Millennial consumers in the United States and United Kingdom adopt these tools for relationship timing decisions. This compression of interpretation labor is reducing per-reading production costs while elevating platform differentiation.
The EU AI Act's risk classification framework subjects astrology platforms deploying automated health or financial predictions to conformity assessment obligations. Platform operators must document algorithmic decision logic and maintain human oversight protocols. Birth chart analysis services targeting European Union consumers face the steepest compliance reconfiguration timelines.
Subscription fatigue among Gen Z users is fragmenting revenue concentration away from annual commitments toward modular micro-purchases. Daily transit notifications and single-question readings now outpace comprehensive natal reports in transaction volume. This behavioral pivot is most pronounced in Indian and Indonesian markets where prepaid mobile data economics favor bite-sized consumption.
Astrology Market Segmentation
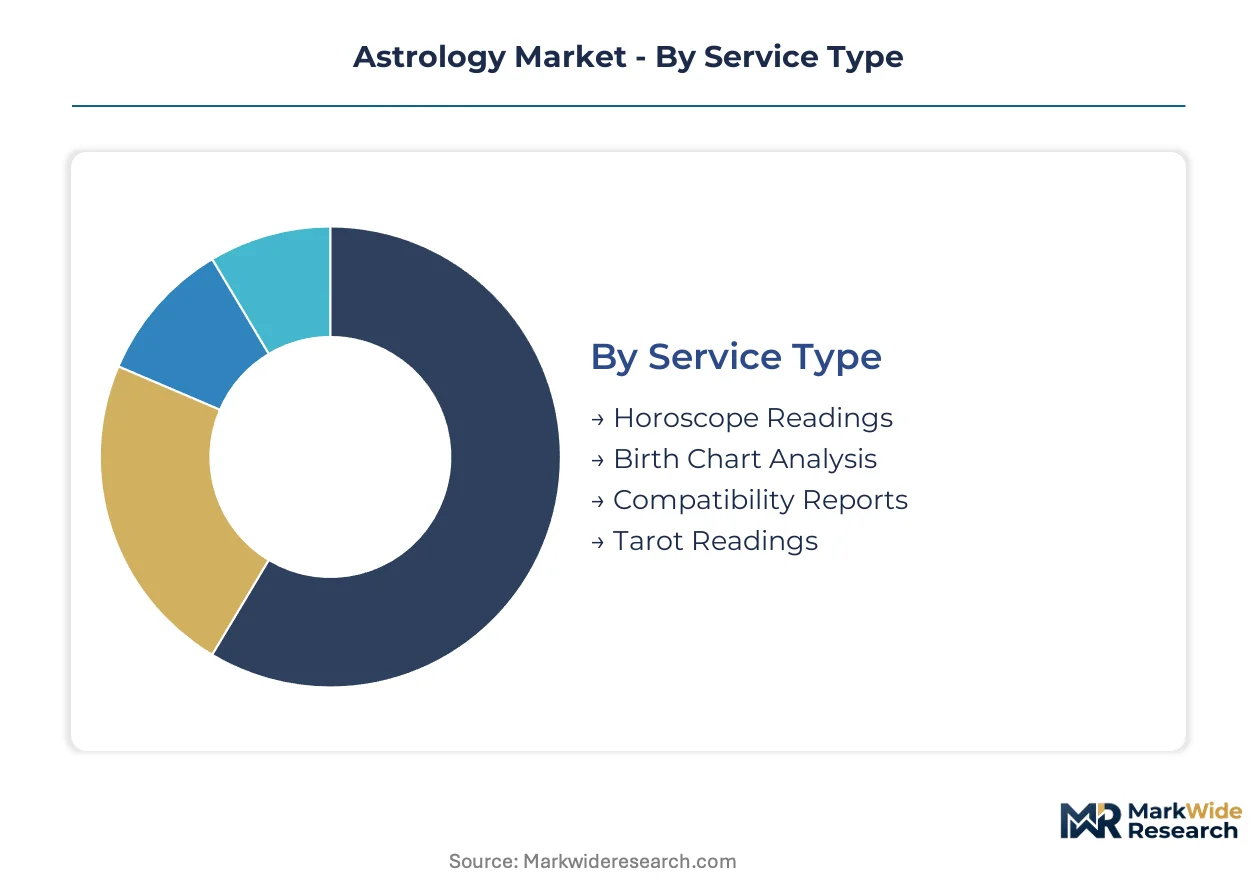
Segmentation in the astrology market reveals how regulatory frameworks, technological infrastructure, and consumer behavior patterns fragment revenue concentration across distinct service configurations. Understanding these divisions exposes where compliance burdens concentrate and which delivery modes capture disproportionate lifetime value.
Service Type:
Horoscope Readings require no specialized practitioner licensing in most jurisdictions, while Birth Chart Analysis and Compatibility Reports trigger stricter consumer protection scrutiny where predictive claims appear. Tarot Readings occupy ambiguous regulatory territory across multiple national frameworks.
- Horoscope Readings:Daily sun-sign content generated through ephemeris automation and template libraries. Demand clusters in prepaid mobile markets across Indonesia and Nigeria where carrier billing supports micro-transactions. Low production cost enables freemium conversion funnels with advertising subsidy.
- Birth Chart Analysis:Computationally intensive natal calculations requiring precise birth time rectification and house system selection. Premium pricing in the United States and United Kingdom reflects certified practitioner scarcity and GDPR-compliant data architecture investments. Corporate wellness programs in California now reimburse these services as mental health adjuncts.
- Compatibility Reports:Synastry algorithms comparing planetary placements across two charts. Relationship counseling channels in Mumbai and London drive B2B procurement.
- Tarot Readings:Interpretive card draws delivered through live video or automated spreads. Platform operators face Apple App Store fortune-telling category restrictions in multiple jurisdictions.
Horoscope Readings sits at the top of the volume ranking, with Birth Chart Analysis climbing the fastest.
Customer Type:
Cost tier stratification separates high-touch enterprise contracts from automated individual subscriptions, with procurement patterns diverging sharply across B2B and B2C channels.
- Individuals:Single-user subscriptions and one-time purchases dominating mobile app revenue. Gen Z consumers in India and Brazil favor modular micro-purchases over annual commitments.
- Couples:Joint account structures for synastry and timing consultations. Premium tier concentration in the United States and United Kingdom.
- Businesses:Corporate wellness contracts and employee assistance program integrations. Human resources departments in Los Angeles and New York seek burnout prevention tools through daily transit readings.
- Organizations:Nonprofit and institutional bulk licensing for community programming. Procurement runs through dedicated account management rather than self-serve platforms.
Individuals commands the largest addressable base, though Businesses delivers the highest contract values per seat.
Delivery Mode:
Geographic penetration patterns favor mobile infrastructure maturity in emerging markets while in-person consultation retains premium positioning in talent-concentrated metros.
- In-Person:Certified practitioner consultations requiring physical presence. Supply concentrates in Los Angeles, London, and Mumbai, creating appointment scarcity and elevated rate cards.
- Online:Web-based platforms with synchronous chat or asynchronous report delivery. Browser-based experiences face conversion friction against mobile-native competitors.
- Mobile App:Native iOS and Android applications with push notification engagement loops. India's Ministry of Electronics and Information Technology guidelines force restructuring of subscription billing flows and content moderation protocols.
- Phone Consultation:Voice-only synchronous sessions bridging digital and traditional service models. Retains demographic penetration among users aged 45 and above.
Mobile App is expanding most quickly across Southeast Asian and African markets, while In-Person maintains the highest revenue per transaction.
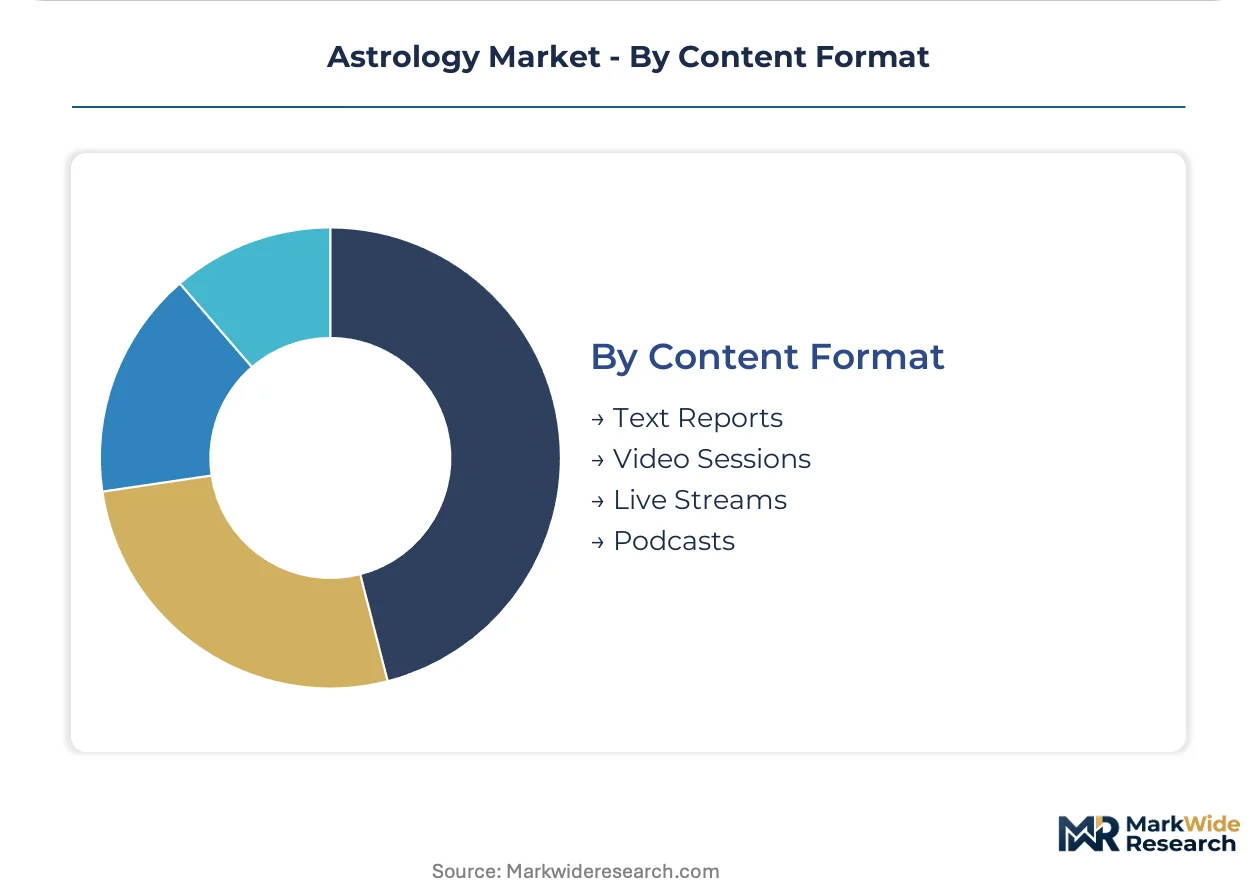
Content Format:
Margin profiles diverge between scalable automated production and labor-intensive live delivery, with format selection determining regulatory exposure under EU AI Act classification frameworks.
- Text Reports:Static document delivery with personalized natal interpretations. GDPR-compliant personalization engines in European markets legitimize algorithmic production when consent architectures are properly engineered.
- Video Sessions:Pre-recorded or live visual consultations with practitioner presence. Production costs scale with astrologer supply concentration in certified talent clusters.
- Live Streams:Real-time broadcast formats enabling audience interaction and tipping monetization. Platform operators must document algorithmic decision logic and maintain human oversight protocols under EU AI Act conformity assessment obligations.
- Podcasts:Audio-only serialized content with episodic advertising or subscription gating. Low production barrier supports creator economy participation without certification requirements.
Text Reports leads transaction volume through automation, while Live Streams gains share fastest among millennial consumers seeking parasocial practitioner relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping platform headquarters decisions, with operators relocating engineering and billing infrastructure to jurisdictions where fortune-telling category restrictions impose lighter compliance burdens on subscription pricing and predictive claim scope.
United States
Corporate wellness reimbursement policies in California and New York are normalizing astrology consultations as employee assistance program benefits. The FTC monitors platforms for deceptive advertising around predictive accuracy guarantees and subscription billing transparency. Los Angeles hosts the densest cluster of certified practitioners and content creator talent, driving premium in-person consultation rates.
United Kingdom
Millennial consumers in London and Manchester adopt algorithmic birth chart tools for relationship timing decisions, compressing demand for traditional sun-sign content. GDPR-compliant personalization engines legitimize automated natal analysis when consent architectures are properly engineered. The Advertising Standards Council enforces disclaimers on astrological efficacy in digital promotions.
India
Gen Z users in Maharashtra and Karnataka favor modular micro-purchases over annual subscriptions, fragmenting revenue concentration toward daily transit notifications. The Ministry of Electronics and Information Technology guidelines force restructuring of subscription billing flows and content moderation protocols. Mumbai's practitioner concentration creates procurement bottlenecks for scaled platforms seeking certified talent.
Brazil
ANVISA has not classified astrology as medical or wellness service, permitting broader efficacy claims than FDA or EMA jurisdictions allow. São Paulo and Rio de Janeiro emerge as regional headquarters for Latin American market expansion. Prepaid mobile data economics in the Southeast region favor bite-sized consumption patterns over comprehensive natal reports.
Germany
The EU AI Act's risk classification framework subjects automated health or financial predictions to conformity assessment obligations. Berlin and Munich platform operators must document algorithmic decision logic and maintain human oversight protocols. Birth chart analysis services face steep compliance reconfiguration timelines for European Union consumers.
Astrology Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with algorithmic-first platforms capturing volume in mobile app distribution while human-augmented services retain premium positioning. The vendor base concentrates around three strategic archetypes: deep personalization engines, aggressive mobile-first distributors, and blended human-automation pipelines. Consolidation pressure is accelerating through M&A activity targeting proprietary ephemeris calculation libraries and strategic partnerships with certified practitioner networks.
Within the personalization-engine tier, Chani anchors algorithmic natal analysis capabilities. Nebula exemplifies mobile-first distribution archetypes with emerging market penetration strategies. Sanctuary occupies a position blending live human astrologers with automated content generation, representing the human-augmented service model. These three entities collectively illustrate how competitive positioning diverges across technological sophistication and practitioner integration depth.
| Leading Market Players |
|---|
| Chani |
| AstroMatrix |
| Co – Personal Astrology |
| Astro Future |
| Astrology Zone |
| Sanctuary |
| Nebula |
| Daily Horoscope |
| TimePassages |
| Others |
Supply Flow & Price Mechanics
Swiss Ephemeris licensing fees cascade through platform operator cost structures, compressing margins on algorithmic birth chart services while elevating premium tiers that absorb royalty burdens through practitioner-augmented delivery.
Pricing Analysis
Direct-to-consumer subscription discounts dominate mobile app distribution, with three-tier pricing structure across premium, standard, and economy levels separating certified practitioner consultations from automated natal reports and ad-supported daily horoscopes. Price differentiation hinges on ephemeris calculation precision and live astrologer access, with Gen Z users in prepaid mobile markets exhibiting highest price sensitivity and corporate wellness buyers in California showing lowest. Pricing pressure stems from subscription fatigue fragmenting annual commitments toward modular micro-purchases.
Supply Chain Analysis
Single-source vulnerability sits with Swiss Ephemeris and proprietary astronomical calculation libraries for ephemeris data, creating royalty concentration risk for scaled platforms. Supply concentrates in the United States for certified practitioner talent, India for engineering and content moderation labor, and Switzerland for core astronomical datasets. Raw material dependencies span ephemeris tables, house system algorithms, and large language model training corpora. Tariff exposure runs minimal given digital delivery dominance. Distribution runs through Apple App Store and Google Play with carrier billing overlays in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in algorithmic personalization engines that compress per-reading production costs while commanding premium positioning through GDPR-compliant consent architectures.
For Market Incumbents: Anticipate regulatory fragmentation across FTC subscription transparency enforcement and EU AI Act conformity obligations by diversifying billing infrastructure across multiple jurisdictions. Invest in proprietary ephemeris calculation libraries to reduce Swiss Ephemeris royalty exposure. Prioritize certified practitioner network exclusivity in Los Angeles, London, and Mumbai to defend against talent poaching from emerging platforms.
For New Entrants and Emerging Players: Generative text-to-natal-chart pipelines offer technology-first wedge into Brazilian and Southeast Asian markets where ANVISA regulatory whitespace and prepaid mobile economics favor bite-sized consumption. Target modular micro-purchase formats over annual subscriptions in India and Indonesia. Pursue carrier billing partnerships as primary go-to-market angle to bypass credit card penetration gaps.
For Investors and Strategic Acquirers: Asymmetric upside sits with algorithmic-first platforms possessing proprietary ephemeris engines and GDPR-compliant personalization architectures. Long-term viability favors entities demonstrating compliance reconfiguration agility across EU AI Act and India's Ministry of Electronics and Information Technology guideline evolutions. Monitor subscription billing flow restructuring announcements as inflection indicator for platform operational maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Ephemeris Engine Development | Reduces Swiss Ephemeris royalty burdens while enabling real-time Placidus and Whole Sign synthesis. |
| Certified Practitioner Network Exclusivity | Locks talent supply in Los Angeles, London, and Mumbai against scaled platform competition. |
| GDPR-Compliant Consent Architecture | Legitimizes algorithmic birth chart analysis under EU AI Act risk classification frameworks. |
| Carrier Billing Infrastructure Partnership | Unlocks prepaid mobile markets across Indonesia, Nigeria, and Brazil with micro-transaction economics. |
| Corporate Wellness Channel Integration | Positions daily transit readings as reimbursable employee assistance program benefits in California and New York. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with platform engineering leads, certified astrologers, mobile app product managers, and corporate wellness procurement officers with secondary validation against App Store and Google Play content policy filings, FTC enforcement actions, and EU AI Act regulatory texts. Bottom-up transaction volume estimates triangulated against top-down market sizing from subscription billing disclosures and practitioner rate card surveys.
Historical reference periods anchored the projection horizon through documented platform launches, regulatory guideline effective dates, and smartphone penetration inflection points across target demographics. Segmentation dimensions modeled include service type, customer archetype, delivery mode, and content format with regional regulatory cluster overlays. CAGRs derived from fitted growth curves against mobile app download velocity and subscription renewal rate trajectories, with ephemeris licensing cost inflation and practitioner supply scarcity as key forecast inputs.
The model holds under stable regulatory classification of astrology as entertainment rather than wellness or medical service; deviation in FDA, EMA, or ANVISA reclassification triggers would shift liability exposure and pricing tier viability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Aerospace Tester Market
Others
Europe Smart Homes Market
Others
Grna Market
Others
Gas Radiators Market
Others
North America Ultraviolet Disinfection Equipment Market
Others
Football Sportswear Market
Others
Vegan Confectionery Market
Others
Folding Screen Mobile Phone Market
Others
Middle East & Africa Air Insulated Switchgear Market
Others
Cathode Battery Material Market
Others
Global Sports and Fitness Wears Market
Others
LAMEA Astrology Market
Others
Global Hair Loss Treatment Products Market
Others
Liquid-Cooled Heat Sink Market
Others
Drum Motor Market
Others
Boston Round Bottle Market