
 Global ESD Protection Devices Market | 2026-2036
Global ESD Protection Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global ESD Protection Devices Market Intelligence
China's foundry capacity expansion is reshaping supply dynamics for ESD protection components. STMicroelectronics leverages its integrated device manufacturing model to sustain captive supply chains across European automotive accounts. Nexperia anchors discrete protection portfolios through dedicated wafer fabs serving handset and base-station OEMs.
ESD protection devices are semiconductor or passive components engineered to clamp transient overvoltage events within nanoseconds, typically exhibiting response times below one nanosecond and clamping voltages tailored to specific interface standards. These devices safeguard integrated circuits from electrostatic discharge damage during manufacturing, handling, and field operation across electronic systems. Silicon avalanche technology dominates high-speed data-line applications where low capacitance preserves signal integrity, while polymer ESD protectors compete in cost-sensitive consumer electronics where board-space constraints matter less than unit economics. CMOS capacitor variants are gaining traction in RF front-end modules for 5G smartphones, where integration density and parasitic control determine design wins.
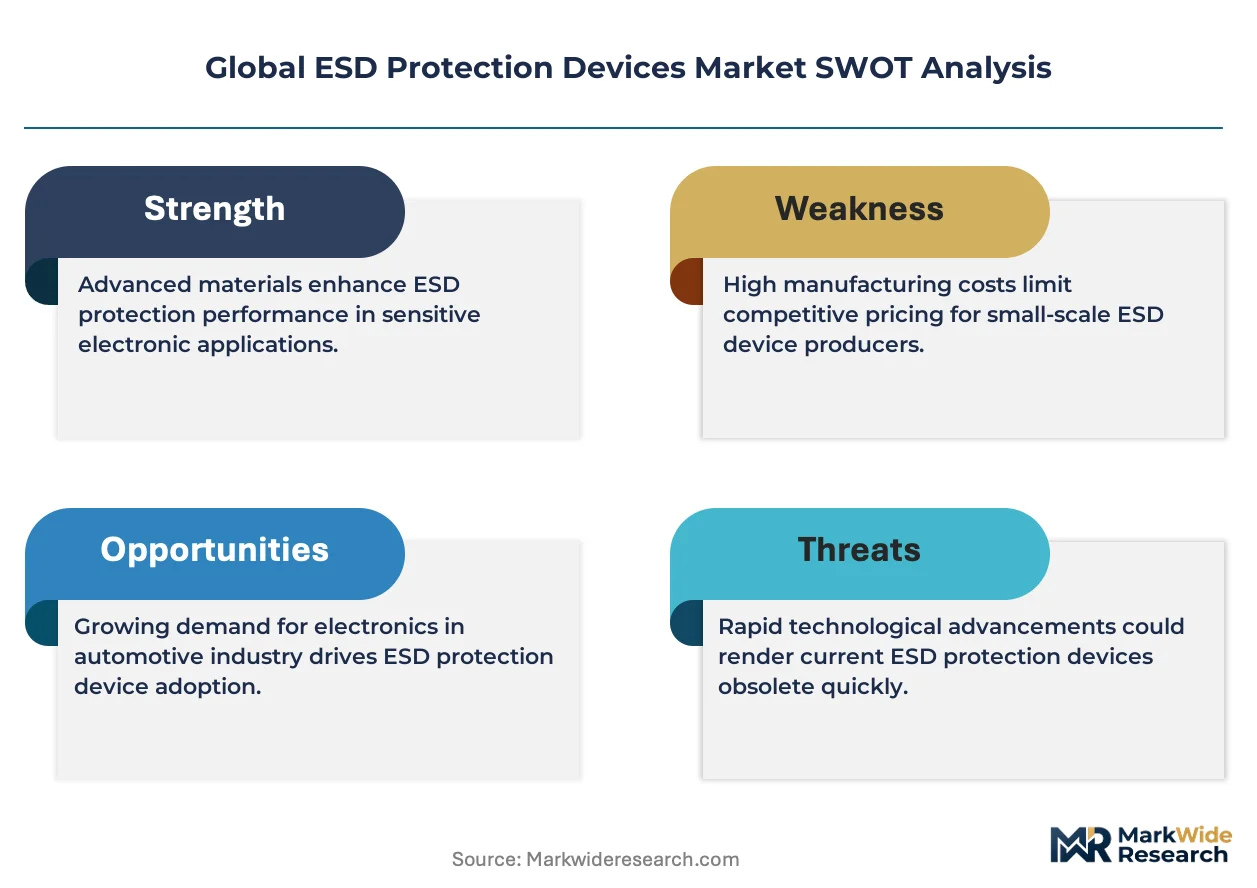
FDA medical device electromagnetic compatibility requirements, EPA restrictions on halogenated flame retardants, and China's GB standards for telecommunications equipment collectively tighten material and performance specifications for ESD component suppliers. REACH substance-of-very-high-concern listings are forcing reformulation of polymer matrix materials in devices sold into European automotive and industrial channels. Stakeholders must monitor how automotive functional safety standards and evolving data-interface speeds redefine clamping-performance thresholds before committing to next-generation process nodes.
Market Dynamics
Automotive sensor architectures are multiplying ESD node counts per vehicle, forcing protection suppliers to reconcile nanosecond response times with AEC-Q100 reliability grades across 48V mild-hybrid and battery-electric platforms.
Growth Catalysts
- EU Green Deal material mandates:REACH substance-of-very-high-concern listings are accelerating reformulation of halogen-free polymer matrices, creating first-mover advantages for suppliers with certified green portfolios in European automotive channels.
- China foundry localization:Domestic semiconductor packaging expansion is concentrating procurement of discrete protection components within China's eastern coastal manufacturing clusters, reducing lead times for handset and base-station OEMs.
- 5G RF front-end integration:CMOS capacitor variants are penetrating smartphone RF modules where parasitic control and density requirements outstrip traditional silicon avalanche performance.
Market Restraints
- Silicon wafer supply concentration:Captive wafer capacity at integrated device manufacturers limits merchant market access for fabless protection specialists during automotive demand surges.
- REACH compliance cost escalation:European chemical registration requirements are elevating fixed costs for polymer-based protector suppliers serving automotive and industrial accounts.
- Polymer response time limitations:Polymer ESD devices exhibit slower clamping speeds than silicon avalanche counterparts, excluding them from USB4 and Thunderbolt 4 interface certifications.
Strategic Opportunities
- India electronics manufacturing incentives:PLI scheme subsidies for semiconductor packaging are attracting protection device assembly investments to Gujarat and Tamil Nadu industrial corridors.
- Medical device EMC convergence:FDA electromagnetic compatibility requirements for implantable devices are opening premium pricing tiers for hermetic protection solutions in diagnostic equipment.
- Automotive functional safety integration:ISO 26262 ASIL-rated protection architectures are enabling silicon suppliers to displace passive components in battery management systems.
Industry Challenges
- Signal integrity engineering scarcity:Specialized talent capable of optimizing capacitance-loading trade-offs for 112Gbps SerDes interfaces commands premium compensation and limits R&D throughput.
- Dual certification timelines:Simultaneous AEC-Q101 and IEC 61000-4-2 qualification cycles extend product introduction schedules by 8-14 months for automotive-grade devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global ESD Protection Devices Market |
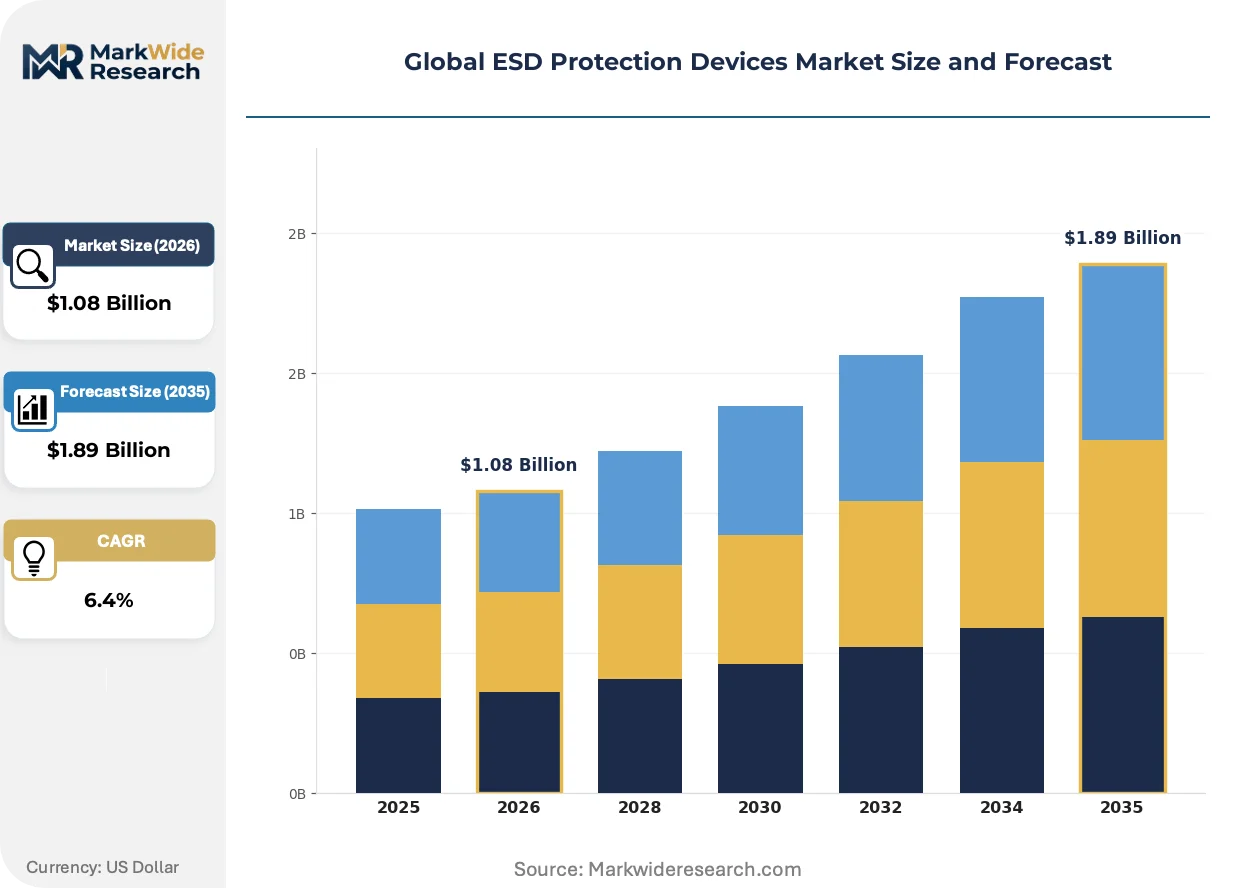
| Market Size in 2026 | $1.08 Billion |
| Market Size in 2035 | $1.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Transient Voltage Suppressors, ESD Diodes, Gas Discharge Tubes, Polymer ESD Protectors, Zener Diodes Technology: Silicon Avalanche, Silicon PN Junction, Metal Oxide Varistors, Thin Film, CMOS Capacitor Application: Consumer Electronics, Automotive Electronics, Telecommunications Equipment, Aerospace Systems, Industrial Automation End User: Original Equipment Manufacturers, Electronics Contract Manufacturers, Printed Circuit Board Assemblers, Testing Laboratories |
| Companies Covered | STMicroelectronics, Littelfuse, Nexperia, Texas Instruments, ON Semiconductor, Infineon Technologies, Murata Manufacturing, TDK Corporation, Semtech Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global ESD Protection Devices Market Strategic Shifts & Innovations
Protection technologies are bifurcating between silicon precision for high-speed data and polymer economy for cost-sensitive consumer applications, with regulatory chemistry constraints now dictating material selection roadmaps.
Silicon avalanche diodes are migrating from standard discrete packages to wafer-level chip-scale formats in smartphone USB-C port protection. Handset OEMs in South Korea and Taiwan are adopting these reduced-footprint devices to reclaim board area for battery expansion. The shift is compressing margins for traditional SOD-323 package suppliers while rewarding foundries with advanced wafer-bumping capabilities.
EPA restrictions on halogenated flame retardants are forcing reformulation of molding compounds in devices sold into US telecommunications infrastructure. Suppliers serving FCC-certified base-station equipment must now qualify phosphorus-nitrogen flame-retardant systems that maintain UL 94 V-0 ratings without bromine or chlorine content. This regulatory pressure is accelerating consolidation among compounders capable of certifying alternative chemistries at production scale.
Automotive Tier 1 suppliers are consolidating vendor lists for ESD protection to reduce qualification overhead across multiple vehicle programs. Procurement teams at German and Japanese OEMs are favoring suppliers offering AEC-Q100 and AEC-Q101 dual certification from single manufacturing sites. This concentration behavior is visible most acutely in powertrain controller applications where functional safety documentation requirements exceed consumer electronics standards by an order of magnitude.
Global ESD Protection Devices Market Segmentation
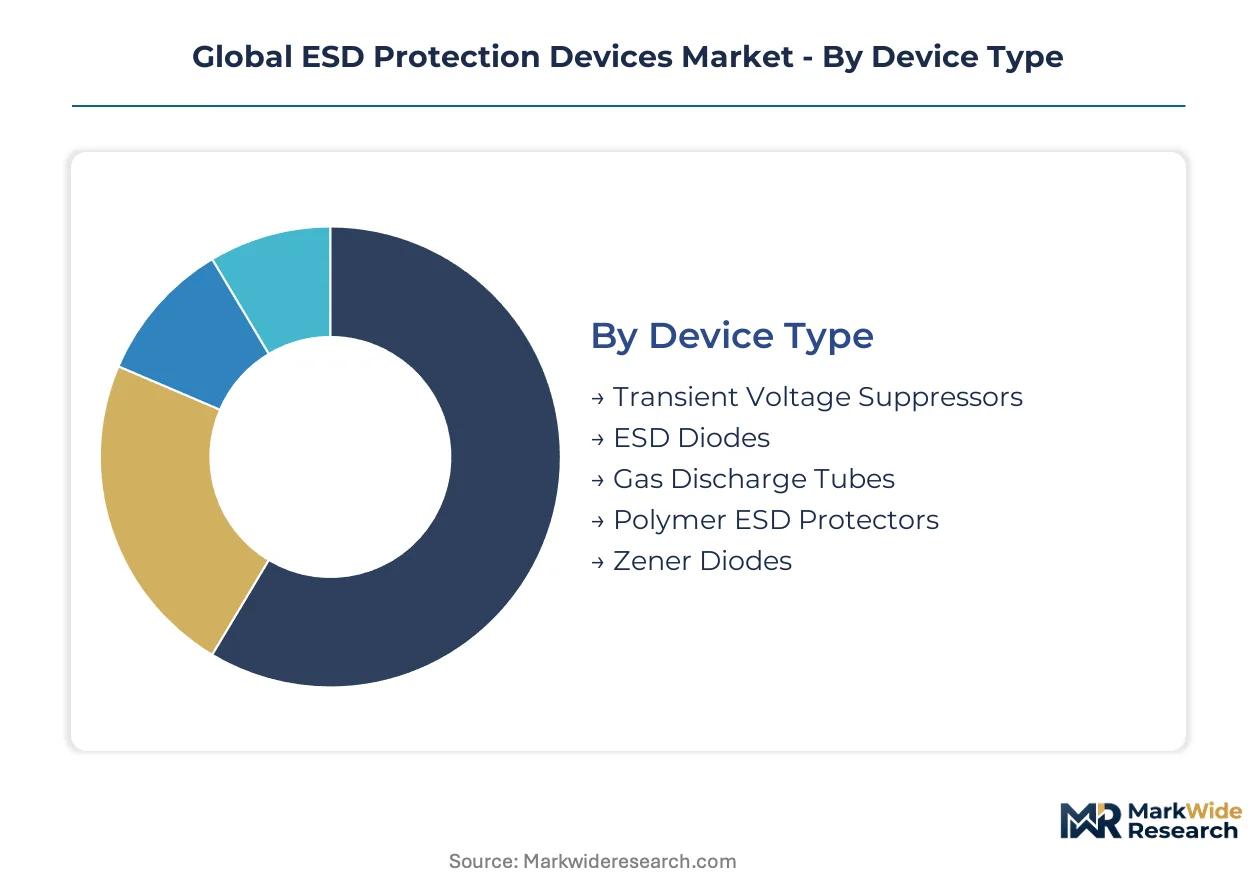
ESD protection devices fragment across multiple technical and commercial dimensions that determine supplier positioning. Device architecture, manufacturing technology, and end-use certification requirements create distinct competitive arenas with divergent margin structures and qualification barriers.
Device Type:
Mature discrete formats dominate high-volume consumer channels while emerging integrated solutions capture automotive and telecommunications sockets demanding tighter clamping precision.
- Transient Voltage Suppressors:Silicon-based bidirectional clamps engineered for power-line protection in industrial motor drives and automotive alternator circuits. German OEMs specify these devices for 48V mild-hybrid platforms where load-dump transients exceed standard diode ratings.
- ESD Diodes:Unidirectional and bidirectional variants optimized for data-line protection with sub-picofarad capacitance specifications. South Korean smartphone manufacturers route procurement through domestic packaging houses to secure wafer-level chip-scale formats for USB-C port integration.
- Gas Discharge Tubes:Ceramic-enclosed spark-gap devices handling kilovolt surges in telecommunications infrastructure.
- Polymer ESD Protectors:Conductive composite devices molded into surface-mount packages for cost-sensitive consumer electronics.
- Zener Diodes:Voltage-regulating elements repurposed for ESD clamping in legacy industrial control systems.
Transient voltage suppressors retain volume leadership; ESD diodes hold the steepest expansion curve.
Technology:
Cost tiers separate precision silicon processes from commodity passive formulations, with mid-range variants competing on integration density rather than raw performance.
- Silicon Avalanche:Breakdown-engineered junctions delivering sub-nanosecond response times and tight voltage clamping tolerances. Taiwan foundries process these wafers for 5G base-station OEMs requiring IEC 61000-4-2 Level 4 compliance at 40Gbps data rates.
- Silicon PN Junction:Standard diode structures offering intermediate protection levels for general-purpose interfaces. Japanese automotive Tier 1 suppliers qualify these devices for body electronics modules where AEC-Q101 reliability grades supersede speed requirements.
- Metal Oxide Varistors:Zinc-oxide ceramic discs absorbing high-energy surges in mains-connected equipment.
- Thin Film:Sputtered-metal precision resistors integrated with protection functions in RF front-end modules.
- CMOS Capacitor:Monolithic integration of protection and passive elements for space-constrained smartphone designs.
Silicon avalanche technology commands the premium tier; CMOS capacitor variants are climbing the fastest.
Application:
Volume concentration varies sharply across end-use sectors, with automotive and telecommunications procurement patterns diverging on qualification timelines and supplier consolidation behavior.
- Consumer Electronics:High-volume smartphone, laptop, and wearable device production demanding minimal unit costs and compressed lead times. Chinese contract manufacturers in Shenzhen and Dongguan dominate procurement for USB port and touchscreen controller protection.
- Automotive Electronics:Sensor-rich architectures multiplying ESD node counts per vehicle while imposing AEC-Q100 reliability mandates. German powertrain suppliers consolidate vendor lists to reduce qualification overhead across battery management and inverter control modules.
- Telecommunications Equipment:Base-station and fiber-optic infrastructure requiring hermetic packaging for outdoor deployment.
- Aerospace Systems:Satellite and avionics applications with extended temperature range and radiation hardness specifications.
- Industrial Automation:Programmable logic controllers and motor drives operating in electrically noisy factory environments.
Consumer electronics retains volume leadership; automotive electronics holds the steepest expansion curve.
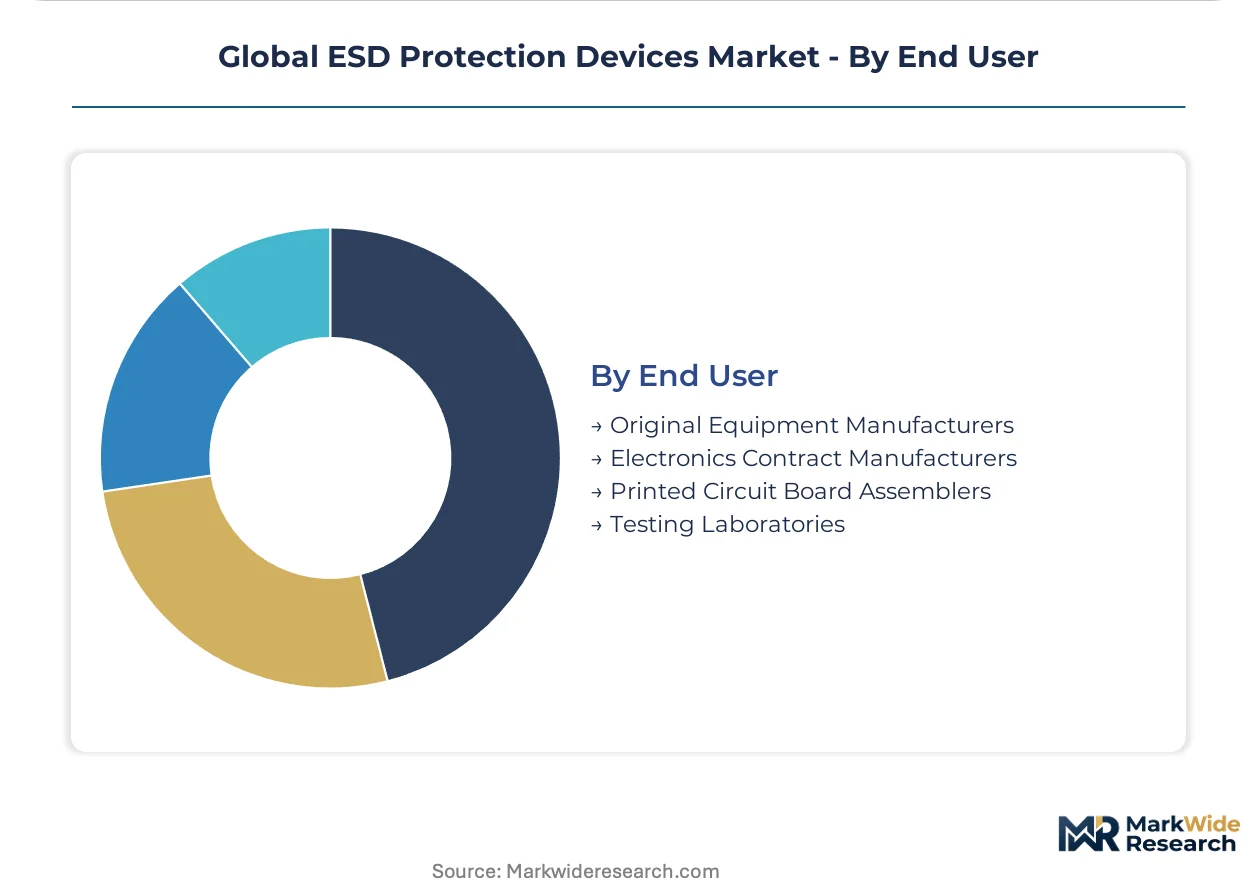
End User:
Customer type determines pricing leverage and technical engagement depth, with captive semiconductor operations diverging from merchant procurement patterns.
- Original Equipment Manufacturers:Integrated device manufacturers and systems houses with internal component engineering teams. STMicroelectronics and Nexperia maintain captive wafer fabs serving European automotive and Asian handset accounts respectively.
- Electronics Contract Manufacturers:Foxconn, Jabil, and Flex facilities executing high-volume assembly for brand-name device vendors. These procurement teams prioritize component availability and logistics integration over technical specification negotiation.
- Printed Circuit Board Assemblers:Regional subcontractors sourcing protection devices through distribution channels.
- Testing Laboratories:Third-party qualification facilities purchasing reference devices for EMC compliance verification.
Original equipment manufacturers retain volume leadership; electronics contract manufacturers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH substance-of-very-high-concern listings are reshaping procurement patterns across European automotive channels, while China's domestic semiconductor packaging expansion concentrates discrete protection component sourcing within its eastern coastal manufacturing clusters.
China
Domestic foundry capacity expansion is driving localized procurement of ESD protection components for handset and base-station OEMs. MIIT's GB standards for telecommunications equipment tighten material specifications for devices sold into national infrastructure projects. Shenzhen and Dongguan contract manufacturers dominate USB port and touchscreen controller protection procurement, compressing lead times for consumer electronics assembly.
Germany
Automotive sensor architectures are multiplying ESD node counts per vehicle across 48V mild-hybrid and battery-electric platforms. KBA vehicle-type approval requirements intersect with REACH chemical compliance to elevate qualification barriers for polymer-based protectors. Bavarian powertrain suppliers consolidate vendor lists to reduce documentation overhead across battery management and inverter control modules.
United States
EPA restrictions on halogenated flame retardants are forcing reformulation of molding compounds in devices sold into FCC-certified telecommunications infrastructure. FDA electromagnetic compatibility requirements for implantable devices are opening premium pricing tiers for hermetic protection solutions in diagnostic equipment. Texas and California host the primary design centers optimizing capacitance-loading trade-offs for 112Gbps SerDes interfaces.
South Korea
Smartphone manufacturers route ESD diode procurement through domestic packaging houses to secure wafer-level chip-scale formats for USB-C port integration. MFDS medical device regulations align with international EMC standards to create dual-certification pathways for diagnostic equipment suppliers. Seoul-area handset OEMs are adopting reduced-footprint silicon avalanche devices to reclaim board area for battery expansion.
India
PLI scheme subsidies for semiconductor packaging are attracting protection device assembly investments to Gujarat and Tamil Nadu industrial corridors. BIS certification requirements for telecommunications equipment are elevating technical barriers for imported components. Maharashtra-based electronics manufacturing services are prioritizing component availability and logistics integration over specification negotiation for high-volume consumer device assembly.
Global ESD Protection Devices Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another. The vendor base organizes around integrated device manufacturers with captive wafer capacity and fabless specialists dependent on merchant foundry access. Three archetypes dominate: silicon precision specialists serving high-speed data applications, polymer economy suppliers competing on unit cost, and diversified component houses leveraging cross-selling into automotive accounts. Competitive moves center on dual-certification consolidation and wafer-bumping capacity expansion for chip-scale formats.
Within the integrated-manufacturing tier, STMicroelectronics and Infineon Technologies exemplify European-based suppliers sustaining captive supply chains across automotive accounts. Nexperia anchors the discrete protection portfolio archetype through dedicated wafer fab operations. These three companies represent contrasting geographic origins—Swiss-Italian, German, and Dutch respectively—while occupying positions that emphasize manufacturing control over outsourced production.
| Leading Market Players |
|---|
| STMicroelectronics |
| Littelfuse |
| Nexperia |
| Texas Instruments |
| ON Semiconductor |
| Infineon Technologies |
| Murata Manufacturing |
| TDK Corporation |
| Semtech Corporation |
| Others |
Cost & Logistics Intelligence
Single-source wafer dependency in Taiwan and South Korea determines both the premium-mid-economy pricing differentiation across ESD protection tiers and the geographic clustering of assembly capacity. REACH compliance cost escalation in Europe and EPA halogen-free mandates in the United States simultaneously compress margins for polymer-based suppliers while rewarding silicon avalanche specialists with certified green portfolios.
Pricing Analysis
Chinese contract manufacturers command 15-25% unit cost advantages over European automotive channels due to consolidated procurement through Shenzhen and Dongguan packaging houses. Three-tier pricing structure across premium, standard, and economy levels separates AEC-Q101 dual-certified silicon avalanche devices from general-purpose PN junction diodes and commodity polymer protectors. Pricing pressure stems from wafer-bumping capacity constraints at Taiwan foundries serving 5G smartphone OEMs. Electronics contract manufacturers exhibit highest price sensitivity; German Tier 1 automotive suppliers prioritize qualification documentation over unit economics.
Supply Chain Analysis
Foxconn, Jabil, and Flex facilities in China, Vietnam, and Mexico concentrate final assembly capacity for consumer electronics protection devices. Raw material flows draw from silicon wafer output in Taiwan and South Korea, halogen-free molding compounds from Japanese compounders, and ceramic substrates for gas discharge tubes from German suppliers. Single-source vulnerability concentrates at Taiwan foundries processing sub-nanosecond avalanche junctions for 40Gbps data rates. Distribution runs through authorized distributors serving regional PCB assemblers and direct OEM contracts for automotive accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
USB4 and Thunderbolt 4 interface standardization is shifting competitive advantage toward silicon precision specialists capable of sub-picofarad capacitance engineering, creating platform economics where interoperability certification becomes the primary barrier to substitution.
For Market Incumbents: Entrench AEC-Q100 and AEC-Q101 dual certification from single manufacturing sites to capture German and Japanese OEM vendor consolidation. Expand wafer-bumping capacity in Taiwan and South Korea to secure wafer-level chip-scale format supply for South Korean smartphone manufacturers. Polymer response time limitations threaten commodity tier incumbents; accelerate phosphorus-nitrogen flame-retardant compound qualification to defend European automotive positioning against REACH compliance cost escalation. For New Entrants and Emerging Players: Pursue India PLI scheme subsidies for semiconductor packaging assembly in Gujarat and Tamil Nadu corridors where BIS certification requirements elevate barriers for imported components. Medical device EMC convergence offers premium pricing tiers with lower incumbent density than saturated consumer electronics channels. Target hermetic protection solutions for FDA-regulated diagnostic equipment through direct hospital system partnerships rather than distribution channel competition. For Investors and Strategic Acquirers: Fabless protection specialists with IEC 61000-4-2 Level 4 design IP and merchant foundry relationships represent the most defensible acquisition archetype as captive wafer capacity constraints intensify. Long-term viability hinges on RF front-end module penetration where CMOS capacitor variants displace discrete silicon avalanche devices. Watch 112Gbps SerDes interface adoption rates as the inflection signal for next-generation clamping performance thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Consolidation | Single-site AEC-Q100 and AEC-Q101 qualification reduces German OEM documentation overhead by 8-14 months. |
| Wafer-Level Chip-Scale Expansion | Advanced wafer-bumping capabilities at Taiwan foundries secure design wins with South Korean handset OEMs. |
| Halogen-Free Compound Reformulation | Phosphorus-nitrogen flame-retardant systems maintain UL 94 V-0 ratings for EPA-compliant US telecommunications infrastructure. |
| India Assembly Investment | PLI scheme subsidies in Gujarat and Tamil Nadu attract protection device packaging for domestic BIS-certified markets. |
| RF Front-End Integration | CMOS capacitor variants penetrate 5G smartphone modules where parasitic control outstrips traditional silicon avalanche performance. |
Research Approach
A standing panel of semiconductor packaging engineers, automotive Tier 1 procurement directors, telecommunications equipment EMC specialists, and polymer compounder R&D leads provided ongoing calibration across primary interview cycles. Secondary validation drew from MIIT GB standards filings, EPA flame-retardant restriction notices, REACH SVHC candidate list updates, and SEC 10-K disclosures from listed component suppliers. Bottom-up unit demand modeling across device architectures triangulated against top-down semiconductor wafer consumption data.
Scenario-bracketing framed low, base, and high cases across the projection horizon without fixed-year anchoring. Segmentation dimensions modeled include device architecture, manufacturing technology, end-use certification requirements, and regional regulatory cluster. CAGRs were derived from installed base expansion rates and content-per-unit trajectories in automotive sensor architectures and 5G smartphone RF modules. Input assumptions incorporated foundry capacity utilization rates and dual-certification timeline distributions.
Sensitivities concentrate around Taiwan foundry capacity allocation shifts, REACH substance-of-very-high-concern list expansions, and automotive functional safety standard revisions. Forecasts reflect documented assumptions regarding interface speed evolution and polymer response time technical limits. Quarterly review of AEC-Q101 qualification backlog durations and wafer-bumping capacity expansion announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Connected Living Room Market
Others
Global Emergency Spill Response Market
Others
Live IP Broadcast Equipment Market
Others
Smart Electric Curtain Market
Others
Radiation Detection Monitoring and Safety Market
Others
Wearable AI Market
Others
Coalescing Filter Market
Others
Global Smart Devices Market
Others
5G Devices Market
Others
Receiving Scales Market
Others
Calcined Petroleum Coke Market
Others
Air Separation Module Kit Market
Others
Digital Transformation of Maritime Freight Market
Others
Global Platform Trolley Market
Others
Communication Base Station Body Market
Others
North America Halal Food and Beverage Market