
 India Home Automation Market | 2026-2036
India Home Automation Market Size, Share, and Industry Trends Forecast 2026-2036
India Home Automation Market Insights
Premium-grade whole-home integration is unwinding across metropolitan India as buyers demand unified climate, lighting, and security orchestration rather than isolated gadgetry. Schneider Electric India leverages its industrial automation heritage to anchor large-format residential developments with centralized building management architectures. Havells India competes through deep electrical distribution channel control that extends from switchgear into connected device ecosystems. Legrand India specializes in modular wiring infrastructure that positions its automation modules inside premium apartment fit-outs before competitors reach the specification stage.
India home automation encompasses sensor-actuator networks, communication gateways, and centralized control platforms that coordinate lighting, HVAC, security, and energy management across residential and commercial premises through protocols including Zigbee, Z-Wave, Wi-Fi, and emerging Matter standards. Smart Lights and Security Systems currently occupy the largest addressable bases, though Smart Thermostats represent the fastest-expanding category as energy efficiency mandates tighten and commercial building codes evolve. The Wireless and Hybrid connection types dominate new installations, with Cloud-Based architectures gaining traction in multi-dwelling units where remote facility management reduces on-site staffing costs.
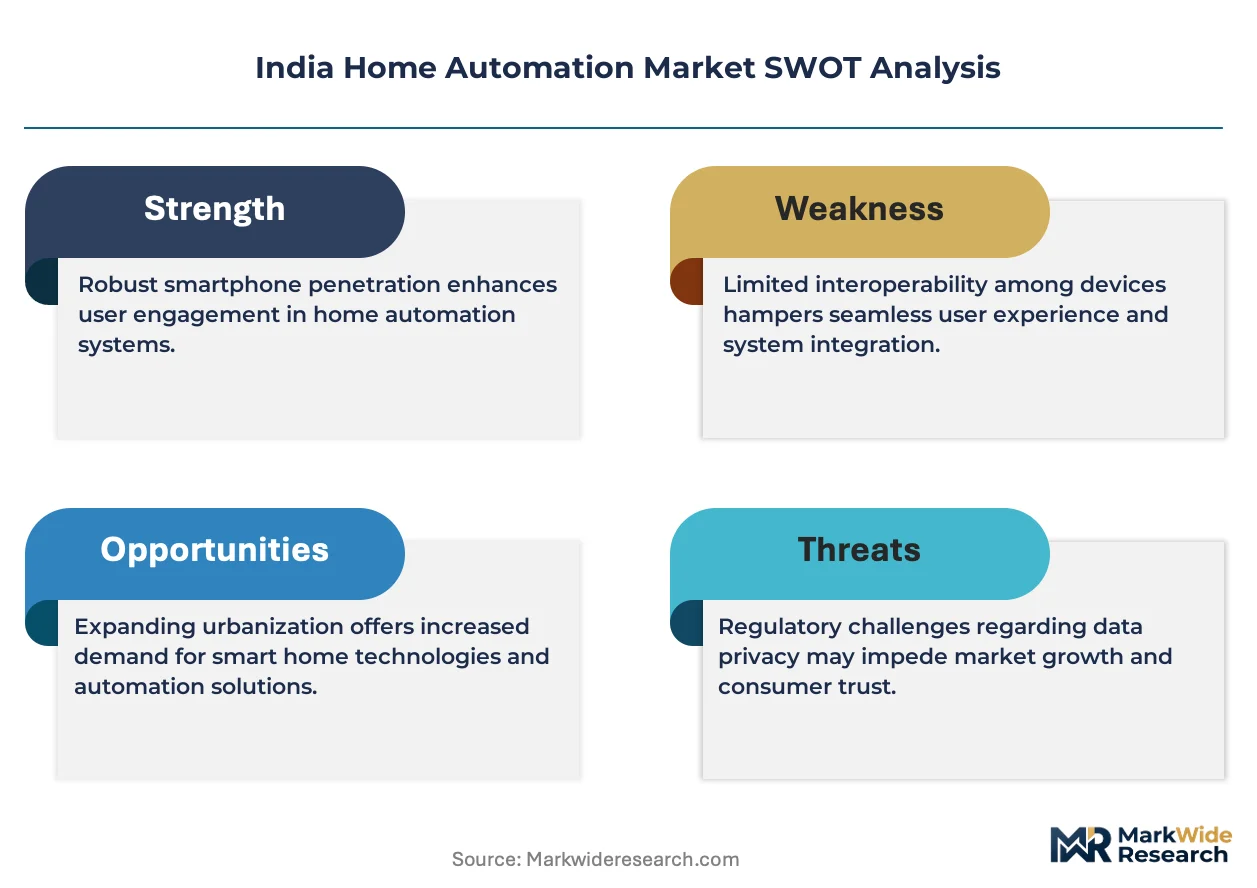
BIS certification requirements for smart electrical devices, combined with CEA building energy codes and state-level RERA construction standards, are elevating compliance costs for entrants while favoring established players with testing laboratory relationships and regulatory affairs capabilities. Stakeholders must monitor how BIS harmonization with international IEC frameworks reshapes import barriers for foreign component suppliers and whether state-level smart city tenders will mandate domestic value-add thresholds that alter sourcing strategies for system integrators serving municipal projects.
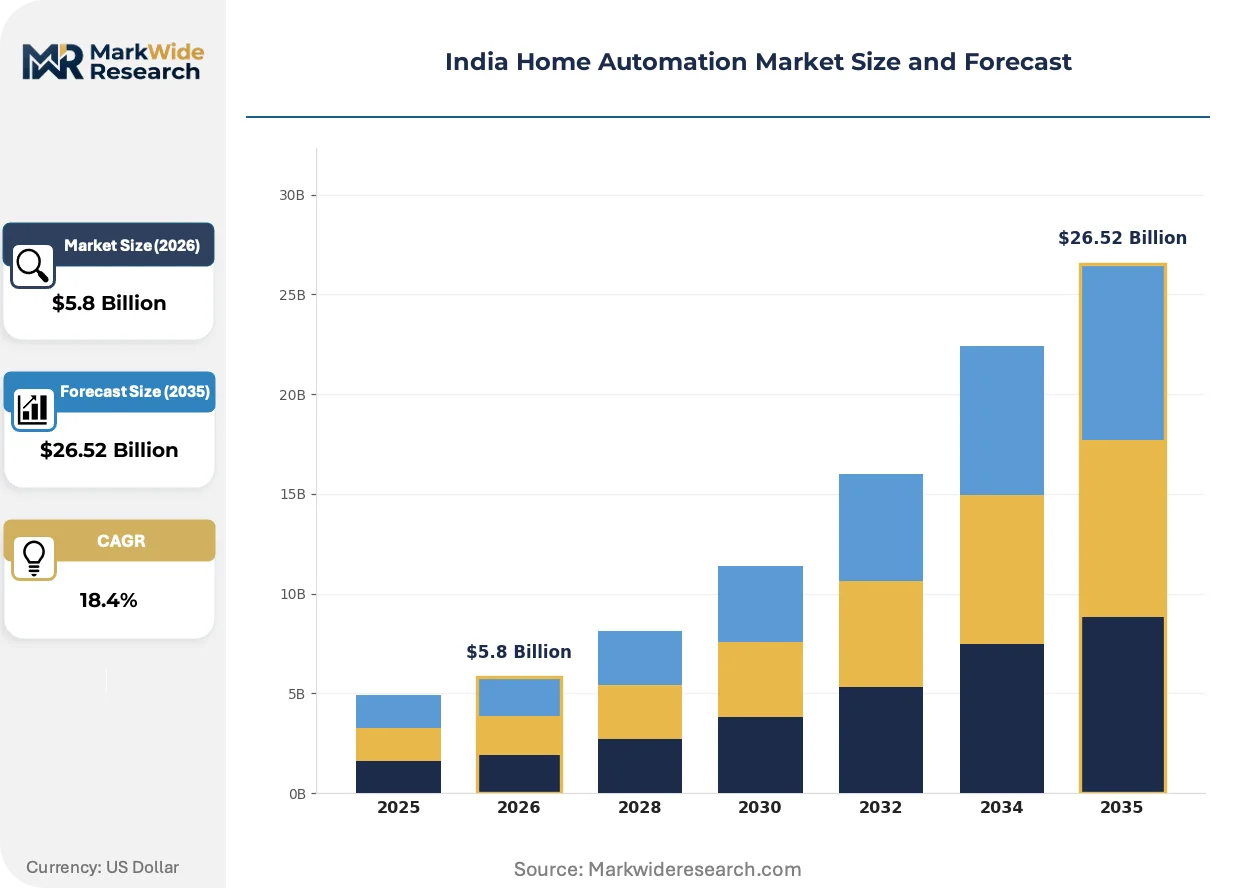
Market Dynamics
Matter-over-Thread protocol adoption is fragmenting legacy Zigbee and Z-Wave ecosystems across Indian residential developments, forcing system integrators to rebuild compatibility layers while BIS certification mandates compress product launch timelines.
Growth Catalysts
- CEA Building Energy Codes:Commercial retrofit mandates in Maharashtra and Karnataka are accelerating HVAC automation procurement in IT corridor office complexes.
- Luxury residential construction:Premium villa developments in Gurugram and Bengaluru specify integrated lighting-climate-security suites as standard fit-out.
- Matter protocol harmonization:Cross-brand interoperability is reducing consumer lock-in friction and expanding addressable device ecosystems.
Market Restraints
- BIS certification timelines:Smart electrical device testing bottlenecks at accredited laboratories extend product-to-market cycles by 4-8 months.
- Import component dependency:RF modules and semiconductor gateways concentrate in East Asian supply chains, exposing integrators to forex volatility.
- Skilled installation scarcity:Certified system integrators capable of commissioning centralized building management architectures remain concentrated in six metropolitan clusters.
Strategic Opportunities
- Tier-2 city underpenetration:Pune, Hyderabad, and Chennai residential automation adoption lags Mumbai and Delhi NCR by 40-60% in connected device density.
- State smart city tenders:Municipal integrated command and control center projects are creating bundled automation procurement vehicles for lighting and surveillance.
- Cloud-based facility management:Multi-dwelling unit operators are adopting remote monitoring platforms to reduce on-site staffing costs.
Industry Challenges
- Legacy electrical infrastructure retrofit complexity:Pre-2010 residential stock lacks neutral wiring, forcing expensive rewiring or limiting device compatibility.
- Interoperability certification fragmentation:BIS, TEC, and WPC approvals for wireless devices create overlapping compliance burdens without mutual recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Home Automation Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $26.52 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Lights, Smart Thermostats, Security Systems, Smart Locks End User: Residential, Commercial, Hospitality, Retail Connection Type: Wired, Wireless, Hybrid, Cloud-Based Control Method: Mobile App, Voice Control, Remote Control, Web Interface |
| Companies Covered | Philips Smart Home (Signify India), Havells India, Schneider Electric India, Zicom Electronic Security Systems, Wipro Smart Home Automation, Honeywell Home India, Anchor (Panasonic) Smart Home, i3 Systems, Legrand India, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Home Automation Market Trends and Innovations
Protocol convergence and energy efficiency mandates are compressing technology refresh cycles while reshaping how Indian buyers evaluate automation investments across residential and commercial verticals.
Thread mesh networking is displacing Zigbee as the dominant low-power protocol in new Indian installations. Premium apartment developers in Bengaluru and Mumbai are specifying Thread-native devices for whole-home deployments. This shift is compressing margins for legacy gateway manufacturers dependent on proprietary bridge architectures.
BIS harmonization with IEC frameworks is elevating import testing requirements for foreign component suppliers. The Bureau's smart device certification mandate now requires electromagnetic compatibility validation at Indian accredited laboratories. European and East Asian module vendors are establishing local testing partnerships to maintain access to Maharashtra and Karnataka project pipelines.
Builder-direct procurement is consolidating channel power away from traditional electrical distributors. Large-format residential developers in Gurugram now negotiate centralized automation packages at the construction specification stage. This bypasses retail markup structures and locks component vendors into multi-year supply agreements.
India Home Automation Market Segmentation
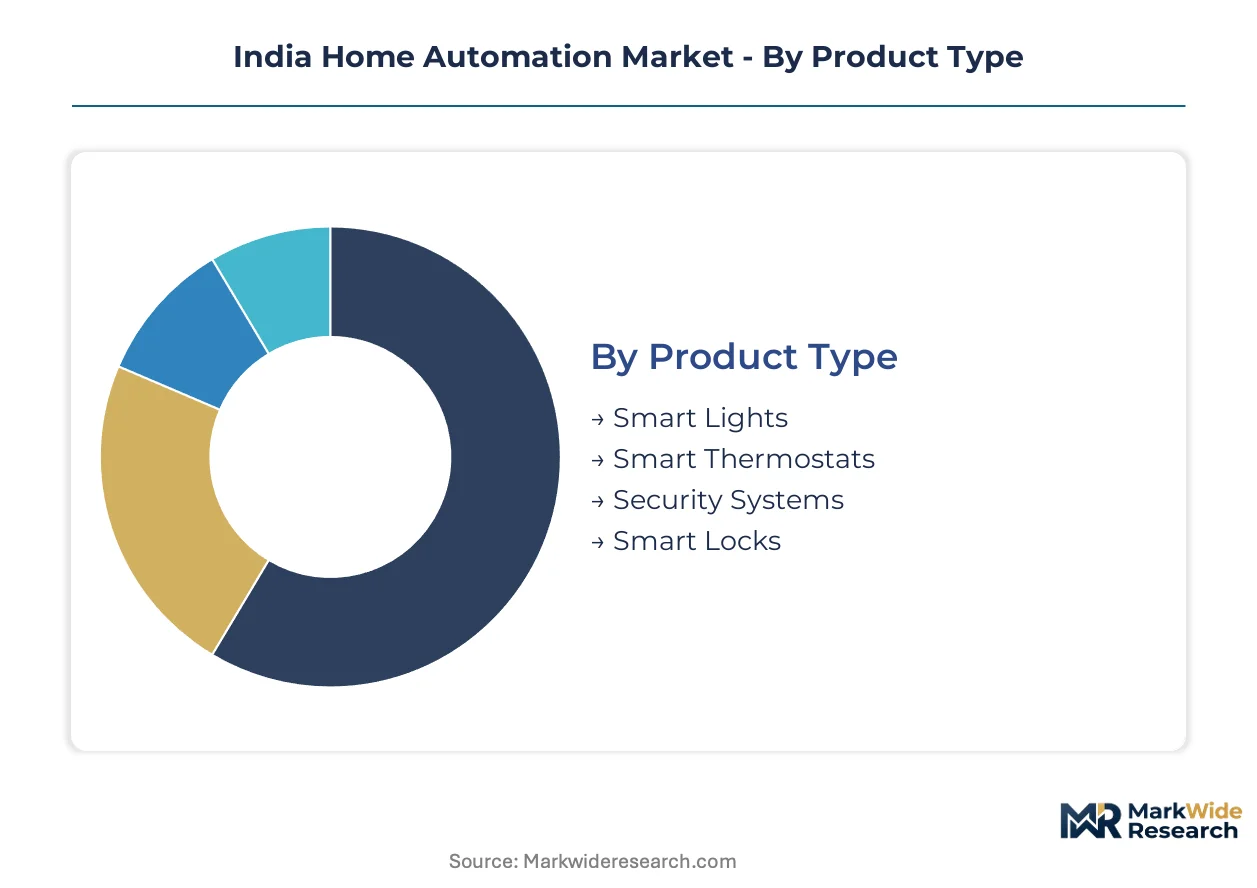
Segmentation in the India home automation market reveals how protocol standards, infrastructure readiness, and buyer sophistication create divergent deployment economics across product categories and control architectures.
Product Type:
Domestic demand concentrates in retrofit-friendly categories where wireless installation bypasses legacy wiring constraints, while export-oriented component manufacturing clusters around semiconductor gateways and RF modules in Tamil Nadu and Karnataka special economic zones.
- Smart Lights:LED drivers with integrated Zigbee or Thread radios enable dimming, color temperature adjustment, and scheduling through mesh networks. Maharashtra and Karnataka luxury residential projects specify whole-home lighting suites as standard fit-outs, with CEA energy codes tightening efficacy requirements for commercial retrofits.
- Security Systems:IP cameras, motion sensors, and centralized alarm panels coordinate through hybrid cloud-edge architectures. IT corridor office complexes in Bengaluru and Hyderabad drive procurement volume as RERA compliance and insurance mandates harden physical security requirements.
- Smart Thermostats:HVAC control units with occupancy sensing and weather-responsive algorithms.
- Smart Locks:Biometric and PIN-entry deadbolts with audit trail logging and remote access revocation.
Smart Lights commands the established base. The steepest expansion runs through Security Systems.
End User:
Cost tier stratification separates premium integrated deployments from modular entry-level installations, with hospitality and retail segments demanding centralized fleet management capabilities that residential buyers rarely specify.
- Residential:Single-family villas and premium apartments in Gurugram and Mumbai deploy unified climate-lighting-security orchestration through centralized building management architectures. BIS certification mandates and Matter protocol adoption are compressing product launch timelines for device vendors serving this segment.
- Commercial:IT corridor office complexes and co-working spaces in Bengaluru and Pune procure HVAC automation and access control through facility management contracts. CEA building energy codes in Maharashtra and Karnataka mandate automated lighting and climate systems for buildings above specified floor areas.
- Hospitality:Hotels and serviced apartments requiring guest room management systems with energy recovery.
- Retail:Chain stores and malls deploying synchronized lighting and surveillance networks.
Residential holds the revenue concentration. Commercial is expanding most quickly as retrofit mandates proliferate.
Connection Type:
Volume deployment favors wireless and hybrid architectures that minimize structural modification, though cloud-based systems gain traction where multi-dwelling operators seek to eliminate on-site technical staffing.
- Wireless:Mesh networks using Zigbee, Z-Wave, or Thread protocols eliminate dedicated cabling infrastructure. New Bengaluru and Mumbai apartment developments specify Thread-native devices, displacing legacy gateway-dependent ecosystems and compressing margins for proprietary bridge manufacturers.
- Hybrid:Wired power with wireless control signaling balances reliability and retrofit feasibility. Large-format residential developers in Gurugram negotiate centralized automation packages at construction specification, locking vendors into multi-year supply agreements that bypass retail distribution markups.
- Wired:Dedicated bus architectures for high-reliability commercial and industrial applications.
- Cloud-Based:Remote monitoring platforms enabling facility managers to oversee distributed property portfolios from centralized operations centers.
Wireless dominates installation count. Cloud-Based is climbing the fastest as property operators consolidate remote oversight.
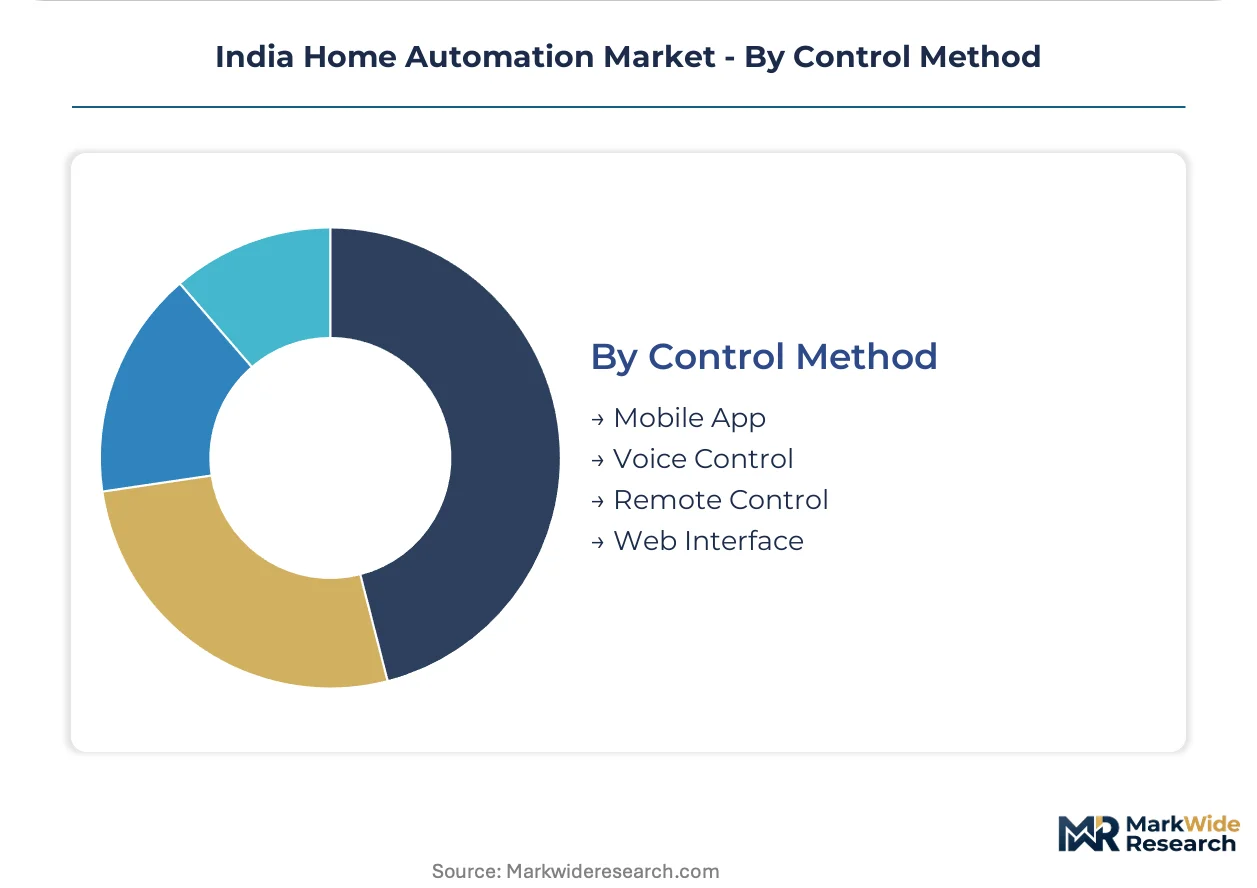
Control Method:
Customer type differentiation separates tech-forward early adopters demanding voice and mobile integration from institutional buyers prioritizing audit-capable web interfaces for compliance documentation.
- Mobile App:Smartphone-centric interfaces with geofencing, scene programming, and energy dashboards. Younger demographics in Tier-1 cities drive specification, though Tier-2 adoption in Pune and Chennai lags Mumbai and Delhi NCR by substantial margins in connected device density.
- Voice Control:Natural language interfaces through Alexa, Google Assistant, and Siri integrations. Matter protocol harmonization is reducing consumer lock-in friction and expanding cross-brand device compatibility for residential buyers.
- Remote Control:Dedicated hardware interfaces for elderly users and accessibility requirements.
- Web Interface:Browser-based dashboards for commercial facility managers requiring multi-site oversight and compliance reporting.
Mobile App captures the consumer preference base. Voice Control is gaining share fastest as Matter-enabled interoperability reduces ecosystem fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's home automation sector exhibits pronounced regional asymmetry, with component imports concentrated through Tamil Nadu and Karnataka special economic zones while domestic demand clusters around six metropolitan construction corridors. State-level regulatory divergence and infrastructure readiness create divergent deployment economics across sub-markets.
Maharashtra
Mumbai's luxury residential pipeline and Pune's IT corridor commercial retrofits drive procurement volume for integrated lighting-climate systems. CEA building energy codes mandate automated HVAC controls for commercial structures above specified floor plates. Thane and Navi Mumbai industrial zones host assembly operations for RF modules serving western India distribution networks.
Karnataka
Bengaluru's premium apartment developers specify Thread-native whole-home deployments as standard fit-outs, displacing legacy gateway architectures. BIS certification requirements for smart electrical devices compress product launch timelines for vendors serving this market. Electronic City and Whitefield clusters concentrate system integrator capabilities for commercial building management commissions.
Delhi-NCR
Gurugram's villa developments negotiate centralized automation packages at construction specification, bypassing retail distribution channels. RERA compliance mandates harden physical security requirements across Noida and Faridabad commercial stock. Manesar industrial belt hosts captive testing facilities for electromagnetic compatibility validation required under BIS harmonization with IEC frameworks.
Telangana
Hyderabad's residential automation adoption lags Mumbai and Delhi NCR by substantial margins in connected device density, creating underpenetration opportunity. State smart city tenders for integrated command and control centers bundle lighting and surveillance procurement. HITEC City and Gachibowli corridors concentrate commercial retrofit demand from IT services campuses.
Tamil Nadu
Chennai's manufacturing base exports semiconductor gateways and RF modules to ASEAN markets while domestic absorption remains constrained by skilled installation scarcity. PLI scheme incentives attract component assembly investments in Sriperumbudur and Oragadam special economic zones. Domestic demand concentrates in Anna Salai and OMR commercial corridors where facility management contracts drive cloud-based platform adoption.
India Home Automation Market Competitive Landscape
Concentration sits with diversified electrical conglomerates possessing BIS laboratory relationships and regulatory affairs capabilities that compress compliance timelines for foreign entrants. The vendor base stratifies across three tiers: legacy electrical distributors extending into connected devices, industrial automation specialists repurposing building management architectures, and pure-play security integrators bundling surveillance with access control. Dominant competitive moves include construction-stage specification capture through builder-direct procurement and backward integration into semiconductor gateway assembly to mitigate import dependency exposure.
Within the electrical conglomerate tier, Havells India and Legrand India exemplify channel control strategies that extend from switchgear into automation module specification. Schneider Electric India anchors the industrial automation specialist position, leveraging centralized building management heritage for large-format residential developments. Zicom Electronic Security Systems occupies the security-integrator archetype, bundling physical surveillance with smart lock and access control deployment.
| Leading Market Players |
|---|
| Philips Smart Home (Signify India) |
| Havells India |
| Schneider Electric India |
| Zicom Electronic Security Systems |
| Wipro Smart Home Automation |
| Honeywell Home India |
| Anchor (Panasonic) Smart Home |
| i3 Systems |
| Legrand India |
| Others |
Pricing and Supply Chain Analysis
Thread-native device substitution for legacy Zigbee gateways is redrawing procurement geography toward Karnataka and Tamil Nadu assembly clusters while compressing margins for proprietary bridge manufacturers locked into older silicon architectures. This component transition simultaneously elevates BIS certification costs for entrants and consolidates pricing power with established vendors possessing accredited laboratory relationships.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures across large-format residential developments, with three-tier pricing structure across premium, standard, and economy levels differentiating on BIS certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because of import component dependency and forex volatility exposure. Facility management contractors demonstrate highest price sensitivity due to volume procurement mandates, while luxury villa developers in Gurugram show lowest sensitivity when specifying centralized automation packages at construction stage.
Supply Chain Analysis
Container availability fluctuations on the Shenzhen-Chennai trade lane are elevating inbound logistics costs for RF module shipments into Tamil Nadu special economic zones. Semiconductor gateways and wireless control chipsets draw from Taiwan, South Korea, and China, with BIS electromagnetic compatibility testing requirements creating regulatory chokepoint risk. Distribution runs through electrical distribution channels extending from switchgear into connected device ecosystems, with builder-direct procurement consolidating channel power away from traditional retail markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Matter protocol harmonization is triggering platform-economics inflection as cross-brand interoperability collapses ecosystem lock-in value and redistributes margin capture toward specification-stage channel control.
For Market Incumbents: Fortify construction-stage specification capture through deepened builder-direct relationships before competitors reach the project pipeline. Backward integration into semiconductor gateway assembly mitigates East Asian supply chain exposure. Prioritize BIS laboratory accreditation investments to compress certification timelines as regulatory harmonization with IEC frameworks elevates import testing barriers.
For New Entrants and Emerging Players: Anchor in Hyderabad and Pune residential automation markets where connected device density lags Mumbai and Delhi NCR by substantial margins. Target cloud-based facility management platforms for multi-dwelling unit operators seeking remote oversight capabilities. Pursue state smart city tender participation as bundled procurement vehicles for municipal lighting and surveillance projects.
For Investors and Strategic Acquirers: BIS smart device certification mandate reshapes the acquisition landscape toward targets with established regulatory affairs capabilities and testing laboratory partnerships. Five-to-ten year viability hinges on protocol convergence positioning as Thread displacement of Zigbee accelerates. Monitor Matter-native device certification velocity as inflection indicator for ecosystem consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | BIS-accredited laboratory partnerships secure faster product-to-market cycles for Thread-native devices. |
| Builder-Direct Procurement Consolidation | Construction-stage specification capture bypasses retail distribution markups in Gurugram villa developments. |
| Cloud-Based Facility Management Platform Launch | Remote oversight capabilities reduce on-site staffing costs for multi-dwelling unit operators in Bengaluru. |
| Semiconductor Gateway Assembly Investment | Captive production in Tamil Nadu special economic zones mitigates East Asian import dependency exposure. |
| Tier-2 City Channel Expansion | Pune and Hyderabad underpenetration creates white-space opportunity ahead of IT corridor commercial retrofit waves. |
Research Methodology
Operator-level perspectives from system integrators, facility management contractors, electrical distribution channel heads, and BIS certification laboratory directors anchored the qualitative base. These primary insights combined with secondary validation from CEA building energy code filings, state smart city tender documentation, BIS harmonization notices with IEC frameworks, and customs records for RF module imports. Bottom-up installation volume estimates triangulated against top-down construction pipeline valuations across Maharashtra, Karnataka, and Delhi-NCR metropolitan corridors.
Sensitivity analysis around protocol adoption velocity and certification timeline compression informed projection boundaries across the analysis window. Segmentation dimensions modeled include product type, end-user vertical, connection architecture, and control method, with state-level regulatory divergence and infrastructure readiness as cross-cutting variables. CAGRs derived from weighted scenario outcomes incorporating BIS enforcement intensity and Matter protocol penetration assumptions.
Material uncertainties — BIS testing laboratory capacity constraints, East Asian semiconductor supply disruptions, and state-level RERA construction standard divergence — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding certification harmonization timelines and protocol ecosystem consolidation trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Snus Market
Others
Europe Meditation Market
Others
Global Military Apparel Market
Others
Military Sensors Software Market
Others
Commercial Aircraft Angle of Attack Sensors Market
Others
Global Process Equipment Market
Others
Global Telemetry Market
Others
Metal Ore Mining Market
Others
Global Retail Media Networks Market
Others
Gym Wipes Market
Others
Germany 3D Printing Construction Market
Others
Ambient Assisted Living and Smart Home Market
Others
Molybdenum-99 Market
Others
Embedded Computer Market
Others
Edge Computing in Healthcare Market
Others
Safety Critical Software Testing Market