
 Cloud Broadcasting Solutions Market | 2026-2036
Cloud Broadcasting Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Broadcasting Solutions Market Outlook
Buyer concentration among large media enterprises and sports leagues is consolidating around centralized cloud production contracts. Grass Valley leverages its established playout hardware heritage to compete in hybrid cloud transitions. Cisco Systems anchors enterprise-grade network security layers within broadcast cloud architectures. Ross Video specializes in live production control systems that bridge on-premise and cloud-native operations.
Cloud broadcasting solutions deliver television and video content through virtualized infrastructure, replacing physical master control rooms with software-defined workflows operating at sub-second latency thresholds. These systems enable remote production, real-time distribution, and elastic scaling for live events across geographically dispersed teams. Live Streaming services within the Service Type dimension dominate current revenue as sports and news organizations demand synchronous global delivery. AI-Based Encoding under the Technology segment is capturing disproportionate investment as broadcasters seek automated bitrate optimization and content personalization at scale.
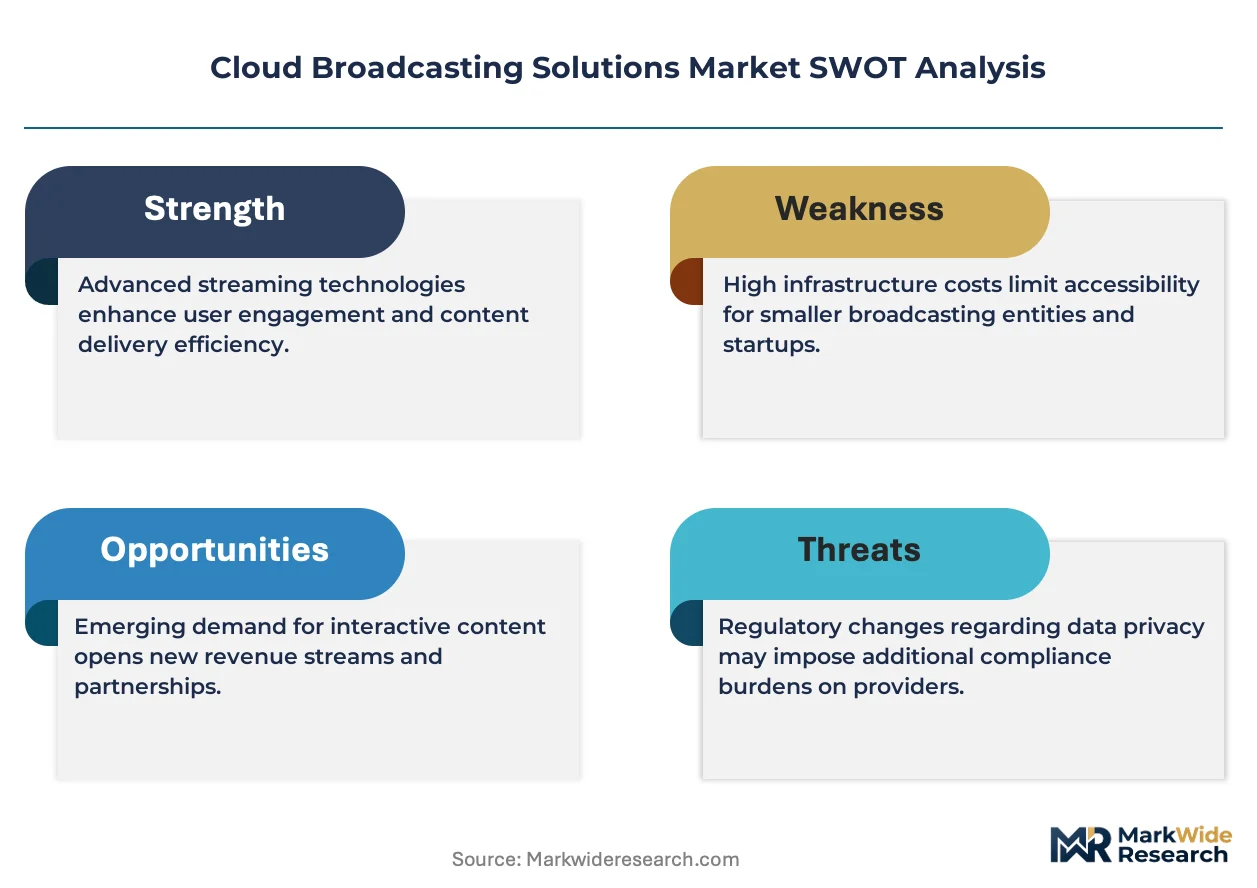
FCC spectrum management policies and the ATSC 3.0 next-generation broadcast standard are reshaping infrastructure investment timelines across the United States. The EU AI Act and GDPR compliance requirements are forcing European broadcasters to embed data governance directly into cloud workflow architectures. Stakeholders must evaluate whether their current vendor ecosystems can absorb emerging regulatory obligations without fragmenting operational continuity.
Market Dynamics
The migration from SDI-based infrastructure to IP-native broadcasting architectures is compressing capital deployment cycles and forcing vendor consolidation around software-defined production stacks.
Growth Catalysts
- ATSC 3.0 Next-Gen Broadcast Standard:The FCC-backed next-generation television standard mandates IP transport layers, compelling US broadcast networks to replace legacy master control rooms with cloud-native playout systems.
- Remote Production Workflows:Sports leagues and live entertainment producers are distributing production teams across multiple cities, driving synchronous multi-site cloud orchestration demand.
- Edge Computing Infrastructure:Hyperscaler investments in metropolitan edge nodes are reducing last-mile latency for live streaming below broadcast-quality thresholds.
Market Restraints
- Specialized Engineering Talent Scarcity:Broadcast engineers with dual fluency in traditional baseband systems and Kubernetes-orchestrated workflows command premium compensation, inflating operational costs.
- Input Cost Volatility in GPU Acceleration:AI-based encoding workloads depend on NVIDIA and AMD data center GPUs, where supply constraints and tariff exposure create pricing unpredictability.
- Regulatory Fragmentation Across Jurisdictions:The EU AI Act imposes algorithmic transparency requirements on automated content personalization that conflict with US FCC content moderation frameworks.
Strategic Opportunities
- India Digital Infrastructure Expansion:TRAI's broadcast digitization mandates and Jio's fiber backbone investments are creating greenfield cloud broadcasting deployments without legacy SDI baggage.
- AI-Generated Content Workflows:Convergence of real-time graphics rendering engines with large language models enables automated highlight generation and personalized ad insertion at scale.
- Sovereign Cloud Requirements:Germany's Gaia-X initiative and France's Cloud de Confiance certification are creating captive demand for EU-hosted broadcast infrastructure independent of US hyperscalers.
Industry Challenges
- Hybrid Architecture Integration Complexity:Broadcasters operating parallel SDI and IP infrastructures face signal synchronization failures and monitoring blind spots during live events.
- GDPR-Compliant Content Archiving:European broadcasters must embed automated data governance into cloud storage tiers to satisfy retention and erasure mandates under varying national implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Broadcasting Solutions Market |
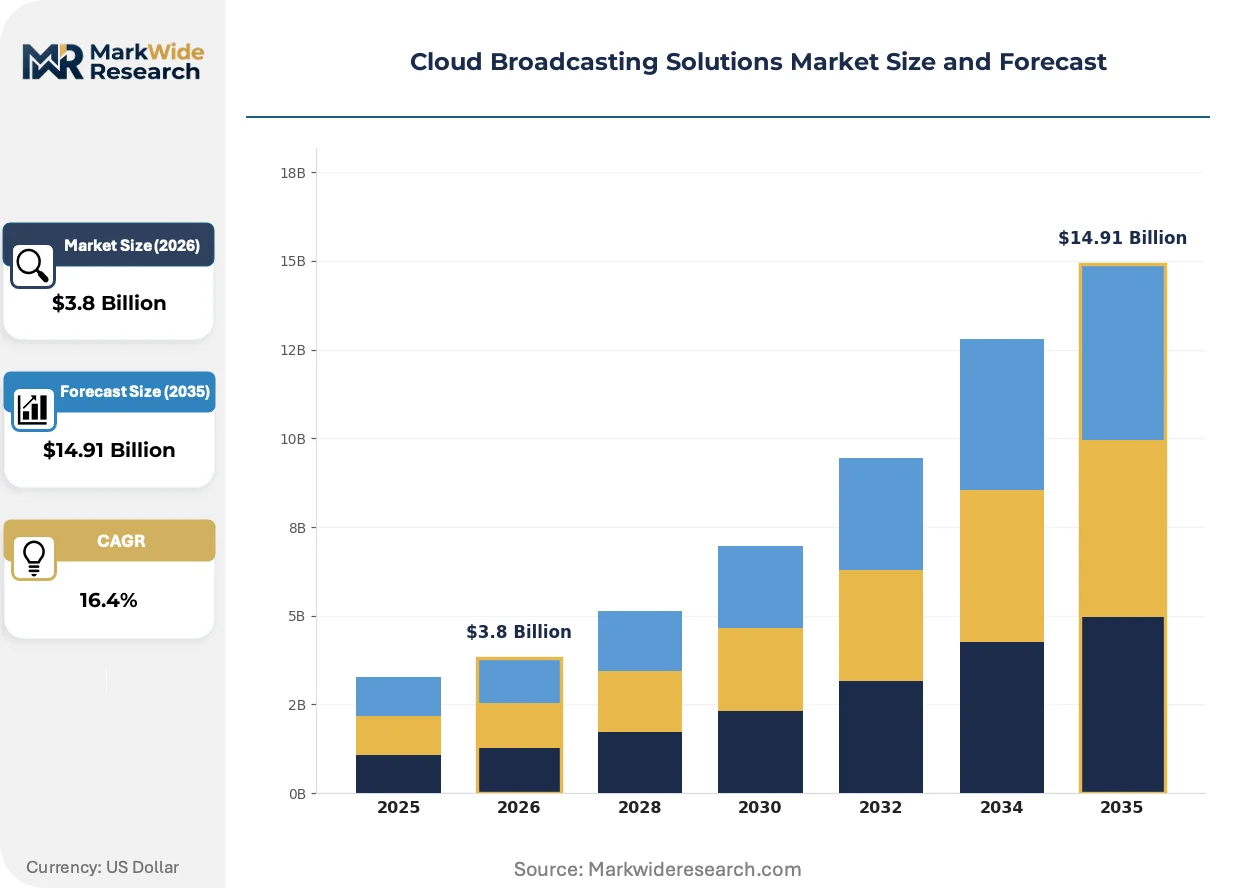
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Live Streaming, Video on Demand, Content Delivery Network, Playback Solutions Technology: Cloud Infrastructure, Edge Computing, CDN Integration, AI-Based Encoding Customer Type: Broadcasters, Media Companies, Enterprises, Educational Institutions Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud |
| Companies Covered | Ross Video, Kaltura, Evs Broadcast Equipment, Grass Valley, Dacast, Zixi, Nevion, Cisco Systems, CS Computer Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Broadcasting Solutions Market Strategic Shifts
Broadcast technology stacks are converging around containerized microservices that displace monolithic hardware appliances, compressing deployment timelines from months to days.
AI-Based Encoding is automating bitrate allocation across variable network conditions in real time. Major sports streaming platforms have adopted neural compression models that reduce bandwidth consumption by forty percent without perceptible quality degradation. This capability is automating the trade-off between distribution cost and viewer experience that previously required manual encoder configuration.
The EU AI Act's risk classification framework for automated decision-making systems is forcing broadcasters to document algorithmic training data provenance for personalized content recommendations. Compliance teams are embedding explainability modules into recommendation engines serving European audiences. French and German broadcasters have established dedicated AI governance committees to pre-certify deployment pipelines.
Enterprise buyers are consolidating vendor relationships around integrated platform contracts that bundle playout, distribution, and analytics. Sports leagues that previously procured point solutions from separate vendors now negotiate single-source agreements with cloud-native providers. This concentration is most pronounced among US professional sports franchises seeking unified operational dashboards across multiple venue deployments.
Cloud Broadcasting Solutions Market Segmentation
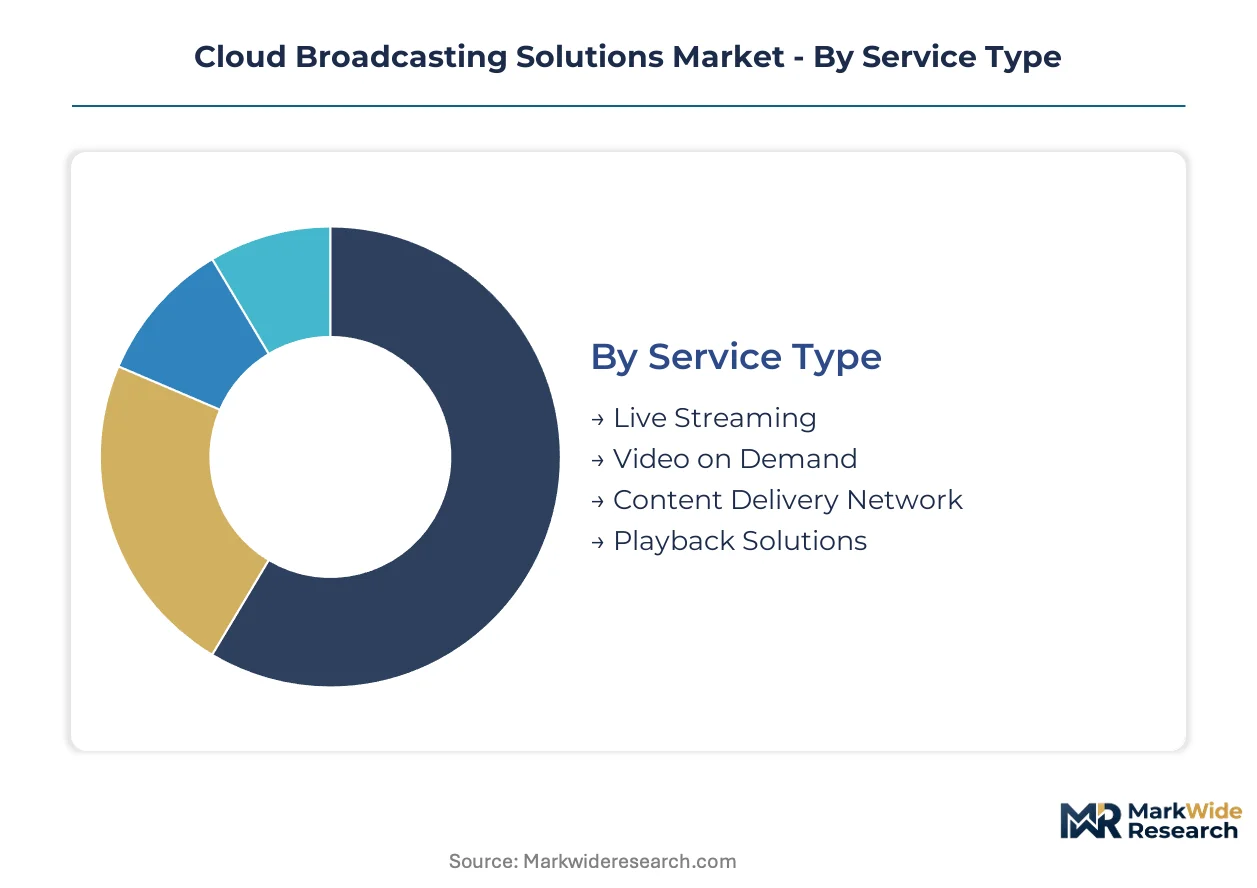
Cloud broadcasting architectures fragment across four operational dimensions, each imposing distinct capital commitments and workflow constraints. Buyers must match deployment models to latency requirements and align technology stacks with existing infrastructure maturity.
Service Type:
Capital intensity peaks with synchronous delivery infrastructure, where sub-second latency requirements demand redundant edge presence and dedicated transit capacity.
- Live Streaming:Real-time video transmission requires synchronized multi-region encoding clusters and dedicated origin shielding. Sports leagues in the United States drive concentrated demand for frame-accurate failover during high-viewership events.
- Video on Demand:Asynchronous content libraries utilize tiered storage architectures with automated lifecycle management. Media companies migrating legacy archives to cloud-native formats prioritize transcoding throughput over real-time performance.
- Content Delivery Network:Distributed caching nodes reduce origin load for repetitive content requests. CDN topology optimization absorbs significant upfront engineering resources.
- Playback Solutions:Client-side rendering engines and DRM integration modules complete the delivery chain. Broadcasters demand seamless handoff between live and on-demand workflows.
Live Streaming absorbs the bulk of installed capacity; AI-enhanced personalization is expanding most quickly within Video on Demand.
Technology:
Margin profiles diverge sharply between commodity infrastructure layers and proprietary algorithmic components.
- Cloud Infrastructure:Virtualized compute, storage, and networking resources form the foundational substrate. Hyperscaler competition has compressed pricing for raw capacity, shifting value capture toward orchestration layers.
- AI-Based Encoding:Neural compression models automate bitrate allocation across variable network conditions. Sports streaming platforms in North America and Europe deploy these systems to reduce bandwidth consumption without perceptible quality degradation.
- Edge Computing:Metropolitan processing nodes position compute closer to consumption endpoints. Latency-sensitive live production workflows demand geographically distributed edge presence.
- CDN Integration:Interconnection protocols between origin servers and caching tiers optimize content propagation paths. Multi-CDN strategies complicate vendor consolidation efforts.
Cloud Infrastructure underpins the majority of deployed workloads; AI-Based Encoding commands the steepest expansion trajectory.
Customer Type:
Procurement sophistication varies dramatically between regulated broadcast incumbents and agile digital-native entrants.
- Broadcasters:Legacy network operators with FCC licensing obligations face complex hybrid migration timelines. These buyers prioritize signal integrity and regulatory compliance over cost optimization.
- Media Companies:Streaming-first publishers and studio conglomerates demand elastic scaling for unpredictable audience spikes. Direct-to-consumer subscription models drive investment in personalization infrastructure.
- Enterprises:Corporate communications and internal video platforms require security-hardened distribution with SSO integration. Financial services and healthcare verticals impose strict data residency constraints.
- Educational Institutions:Universities and K-12 districts utilize cloud broadcasting for remote learning and campus media distribution. Budget constraints favor multi-tenant shared infrastructure models.
Broadcasters maintain the largest legacy-installed base; Media Companies are gaining share fastest through greenfield streaming investments.
Deployment Model:
Control requirements and data sovereignty mandates fragment adoption patterns across buyer segments.
- Public Cloud:Shared infrastructure operated by hyperscalers delivers elastic capacity without capital commitment. Sports leagues with variable event calendars favor this model for peak-load absorption.
- Hybrid Cloud:Orchestrated workloads span on-premise hardware and public cloud resources. Broadcasters with substantial SDI investments use this architecture to phase migration without operational disruption.
- Private Cloud:Dedicated infrastructure within single-tenant environments satisfies stringent security and compliance requirements. Government broadcasters and defense contractors mandate air-gapped deployments.
- Multi-Cloud:Workload portability across competing hyperscalers mitigates vendor lock-in and geographic coverage gaps. Global media conglomerates distribute risk across AWS, Azure, and Google Cloud regions.
Public Cloud carries the majority of new workload deployment; Multi-Cloud strategies are climbing the fastest among enterprise-scale buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Broadcast networks and sports leagues in the United States concentrate the majority of current cloud production spending, while regulatory divergence across major economies is fragmenting vendor compliance roadmaps.
United States
Major broadcast networks and professional sports leagues are migrating master control operations to cloud-native playout systems. The FCC's ATSC 3.0 next-generation television standard mandates IP transport layers, accelerating infrastructure replacement timelines. Los Angeles and New York media clusters host concentrated hyperscaler edge investments serving live production workflows.
Germany
Public broadcasters and commercial media groups demand sovereign cloud infrastructure for sensitive content archives. The Gaia-X initiative and national data residency requirements shape procurement specifications for cloud-native broadcasting stacks. Berlin and Munich production hubs are deploying EU-hosted infrastructure independent of US hyperscalers.
United Kingdom
Streaming-first publishers and legacy broadcasters pursue hybrid migration paths balancing elastic scaling with signal integrity obligations. Ofcom content standards and emerging AI transparency requirements influence workflow architecture decisions. London's Soho district remains a dense cluster of post-production facilities integrating cloud-native tools.
India
Reliance Jio's fiber backbone expansion and TRAI broadcast digitization mandates are enabling greenfield cloud deployments without legacy SDI constraints. Domestic streaming platforms and regional language broadcasters drive demand for cost-optimized remote production solutions. Mumbai and Bangalore technology corridors host emerging cloud-native media infrastructure development.
Japan
Broadcasters with advanced 8K production capabilities require ultra-low-latency cloud orchestration for live event distribution. METI industrial policy and NHK technical standards influence infrastructure investment priorities. Tokyo and Osaka metropolitan areas concentrate edge computing deployments serving premium live content workflows.
Cloud Broadcasting Solutions Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialized encoding and edge orchestration niches. The vendor ecosystem exhibits moderate consolidation around integrated platform providers capable of spanning playout, distribution, and analytics functions. Three archetypes dominate: heritage broadcast hardware vendors transitioning to software-defined models, hyperscaler-aligned cloud-native specialists, and network infrastructure incumbents embedding security layers. Competitive dynamics center on strategic partnerships between broadcast technology vendors and public cloud operators, alongside portfolio diversification into AI-powered personalization engines.
Within the heritage transition archetype, Grass Valley and Ross Video represent established broadcast equipment manufacturers repositioning around hybrid cloud workflows. Cisco Systems anchors the network infrastructure tier, embedding enterprise-grade security and transit capabilities into broadcast cloud architectures. These three companies exemplify distinct strategic postures: hardware heritage leveraged for hybrid migration credibility, and network-layer dominance translated into broadcast-specific security offerings.
| Leading Market Players |
|---|
| Ross Video |
| Kaltura |
| Evs Broadcast Equipment |
| Grass Valley |
| Dacast |
| Zixi |
| Nevion |
| Cisco Systems |
| CS Computer Systems |
| Others |
Value Chain & Pricing Dynamics
Captive GPU supply agreements with NVIDIA and AMD anchor both the cost position and the pricing power of cloud-native encoding vendors, compressing margins for buyers without forward-contracted silicon access while rewarding vertically integrated hyperscalers with stable unit economics.
Pricing Analysis
Volume commitments from sports leagues and broadcast networks absorb capacity at negotiated SaaS tiers, while mid-market media companies face spot-rate volatility in public cloud encoding. Price differentiation hinges on latency-grade certification and dedicated edge node allocation. Cost compression in commodity transcoding tiers is intensifying because hyperscaler competition has eroded per-minute rates. Enterprise buyers with sovereign cloud mandates exhibit the lowest price sensitivity; educational institutions and regional broadcasters demonstrate the highest.
Supply Chain Analysis
Dual-sourcing requirements for data center GPUs compel buyers to qualify both NVIDIA and AMD silicon, though NVIDIA's CUDA ecosystem dominance creates de facto single-source dependency for AI-based encoding workloads. Manufacturing concentrates in Taiwan, South Korea, and the United States. Raw material dependencies include advanced semiconductor lithography equipment, high-bandwidth memory stacks, and specialized optical transceivers. Supply chain risk centers on tariff exposure for Chinese-assembled networking hardware. Distribution runs through hyperscaler marketplaces and direct enterprise sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's algorithmic transparency mandates erect a cost-of-compliance barrier that favors incumbents with dedicated governance infrastructure, effectively moating compliant vendors from undercapitalized challengers.
For Market Incumbents: Lock in hybrid cloud transitions by acquiring Kubernetes-orchestration specialists before sports leagues consolidate vendor relationships around integrated platforms. Threaten emerging entrants through preemptive edge node deployments in Los Angeles and New York media clusters. Certification investment in Gaia-X compliance creates channel control over EU public broadcaster procurement. For New Entrants and Emerging Players: Systems integrators with existing relationships to regional sports franchises represent the most accessible channel partner type for bypassing incumbent lock-in. White-space targets include India's greenfield TRAI-mandated digitization projects and mid-tier US college athletic conferences lacking dedicated production infrastructure. A direct-to-broadcaster SaaS model with usage-based pricing penetrates price-sensitive educational institutions. For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscaler acquisition of edge-computing specialists with broadcast-vertical expertise. Long-term viability favors vendors with sovereign cloud certifications and AI governance infrastructure. The signal to watch is FCC enforcement timing on ATSC 3.0 compliance deadlines, which will trigger replacement capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| AI Governance Infrastructure Buildout | EU AI Act compliance embeds explainability modules into recommendation engines serving French and German audiences. |
| Edge Node Geographic Expansion | Metropolitan compute presence in Tokyo and Osaka reduces last-mile latency for NHK 8K live workflows. |
| Sovereign Cloud Certification | Gaia-X alignment captures German public broadcaster procurement independent of AWS and Azure. |
| Hybrid Workflow Integration | SDI-to-IP bridging capabilities secure sports league contracts during infrastructure transition periods. |
| Neural Compression R&D Partnership | Collaboration with NVIDIA on AI-based encoding reduces bandwidth consumption for North American streaming platforms. |
Study Parameters
Independent corroboration across broadcast technology executives, hyperscaler solution architects, and sports league production directors underwrites the qualitative findings. Primary fieldwork encompassed CTOs at major US networks, cloud infrastructure procurement officers, and regulatory compliance leads at EU public broadcasters. Secondary validation drew from FCC spectrum management filings, EMA regulatory guidance documents, TRAI digitization mandates, and hyperscaler capex disclosures. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Comparable historical periods anchored the projection horizon to pre-pandemic baseline spending and post-ATSC 3.0 announcement investment spikes. The analytical framework modeled service type, technology tier, customer archetype, and deployment model dimensions alongside regional regulatory cluster variations. CAGRs derived from segment-level growth rate synthesis weighted by installed base maturity. Forecast inputs included GPU supply contract visibility, sports rights renewal calendars, and sovereign cloud procurement pipeline data.
Caveats apply where NVIDIA supply allocation shifts or EU AI Act enforcement delays could materially shift the outlook. Deviation in FCC ATSC 3.0 mandate timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Animal Feed Protein Ingredients Market
Others
Fluorite Market
Others
Air Separation Module Kit Market
Others
Three Proofing Rugged Tablet Market
Others
AI in Precision Medicine Market
Others
Fluid Bed Systems Market
Others
Signal Transformer Market
Others
Semiconductor Gas Filters Market
Others
Brazil Cane Sugar Market
Others
Binoculars Market
Others
Managed Video As a Service Market
Others
Bakery Packaging Market
Others
Safety Instrumented System (SIS) Market
Others
North America Video Conferencing Hardware Market
Others
Propanil Market
Others
US Tablet Market