
 Asia-Pacific Medium-Density Fiberboard Market | 2026-2036
Asia-Pacific Medium-Density Fiberboard Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Medium-Density Fiberboard Market Outlook
Buyer concentration among large-scale furniture manufacturers is pivoting toward direct mill partnerships, bypassing traditional distributor networks. EGGER Group leverages integrated resin and substrate operations across Southeast Asian plants to secure raw material continuity. Century Plyboards anchors its position through specialized moisture-resistant grades tailored to India's monsoon-exposed construction cycles. Kastamonu Entegre competes on European-grade fire-resistant formulations manufactured at its Turkish-Asian supply nodes.
Medium-density fiberboard is an engineered wood product formed from refined wood fibers bonded with synthetic resin under heat and pressure, typically achieving densities between 600 and 800 kg per cubic meter. Its uniform surface and absence of grain patterns make it the preferred substrate for laminated cabinetry and precision-molded interior components. Moisture-resistant MDF commands widening application in tropical construction environments where standard grades deteriorate rapidly, while fire-resistant variants capture premium positioning in commercial building codes across the region. Standard MDF retains volume leadership through cost efficiency in mass furniture production, though ultralight grades are gaining traction in transport-sensitive applications such as mobile retail fixtures and modular exhibition systems.
China's SAMR enforces GB standards limiting formaldehyde release from wood-based panels, directly elevating compliance costs for domestic and imported supply. Japan's METI maintains JIS certification requirements that restrict market access for uncertified foreign producers. India's BIS marking mandate for interior-grade panel products is expanding enforcement to secondary manufacturing hubs. Stakeholders must monitor regulatory divergence between national standards regimes when configuring regional production footprints and certification investments.
Market Dynamics
China's tightening GB standards for formaldehyde emissions are compressing supplier margins while forcing rapid certification upgrades across Southeast Asian export-oriented mills. This regulatory pressure is accelerating consolidation among mid-scale panel producers unable to absorb compliance costs.
Growth Catalysts
- Modular furniture manufacturing:Ready-to-assemble cabinetry production in Gujarat and Maharashtra is pulling premium MDF grades into India's western states. Domestic manufacturers are expanding bonded warehouse capacity near these clusters.
- GB 18580-2017 enforcement:China's SAMR is driving E0-grade panel adoption through stricter emission testing protocols. Importers must now pre-certify shipments at designated third-party laboratories.
- Moisture-resistant formulation demand:Tropical construction cycles in Indonesia and the Philippines are elevating specification rates for MR-grade substrates. Architects in Jakarta and Manila are embedding these requirements into commercial tender documents.
Market Restraints
- Urea-formaldehyde resin cost volatility:Methanol feedstock prices fluctuate with natural gas benchmarks across Middle Eastern supply corridors. This input squeeze limits margin predictability for non-integrated mills.
- Import dependency for specialty papers:Decorative overlay sourcing concentrates among Korean and Japanese suppliers. Any disruption to Busan or Nagoya port throughput cascades through laminating operations.
- Technical ceiling in fire-resistant grades:Current resin systems struggle to achieve Euroclass B ratings without density penalties that price out mass-market furniture applications.
Strategic Opportunities
- Vietnam's northern industrial zones:Underpenetrated versus southern hubs like Binh Duong, provinces such as Thai Nguyen offer tax incentives and proximity to China-border raw fiber flows.
- Cross-laminated timber hybrid panels:Convergence of MDF surface quality with CLT structural cores opens commercial building envelopes previously reserved for plywood or solid timber.
- Direct mill procurement channels:Large furniture manufacturers are bypassing distributor markups through long-term offtake agreements with Indonesian and Malaysian producers.
Industry Challenges
- Resin chemistry expertise scarcity:Formulation specialists capable of tuning melamine-urea ratios for tropical humidity conditions command premium compensation. Technical universities in the region lack dedicated wood adhesive curricula.
- JIS certification timeline compression:Japanese METI approval cycles for new panel grades now exceed eighteen months. Exporters must front-load documentation costs before revenue recognition.
- Legacy finishing equipment incompatibility:Older membrane press lines in Thailand and Malaysia cannot process ultralight MDF without caliper consistency issues. Retrofit capex demands strain SME balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Medium-Density Fiberboard Market |
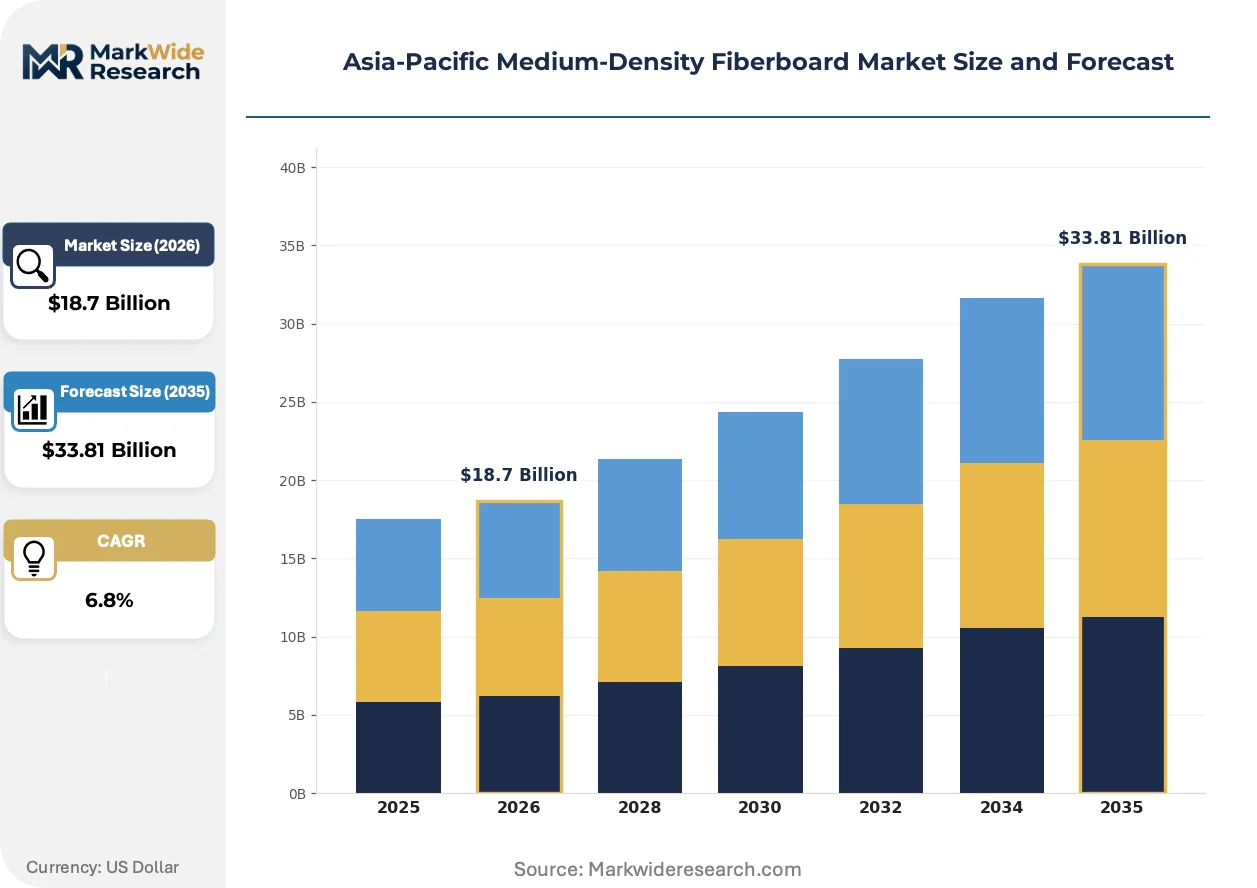
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard MDF, Moisture-Resistant MDF, Fire-Resistant MDF, Ultralight MDF End User: Furniture Manufacturers, Flooring Companies, Construction Industry, Interior Designers Application: Cabinets, Wall Paneling, Doors, Moldings Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Dare Wood-Based Panels Group Co. Ltd, Dongwha Malaysia Holdings Sdn. Bhd., EGGER Group, Kastamonu Entegre, Century Plyboards (India) Limited, West Fraser Timber Co. Ltd, DAIKIN CORPORATION, Greenply, Evergreen Fiberboard Berhad, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Medium-Density Fiberboard Market Strategic Shifts
Digital specification tools and bio-based resin chemistry are compressing traditional product development cycles across the Asia-Pacific panel industry. These shifts are reconfiguring how architects, contractors, and furniture manufacturers source and validate substrate performance.
Low-emission bio-adhesive formulations utilizing lignin and tannin extracts are electrifying product positioning in specification-sensitive segments. High-end kitchen cabinetry manufacturers in Shanghai and Singapore are qualifying these grades for export-bound production. The technology is compressing competitive differentiation previously held by European suppliers with mature E1-E0 portfolios.
India's BIS marking mandate for interior-grade panel products is tightening enforcement across secondary manufacturing hubs beyond Mumbai and Delhi. The regulation is forcing informal sector producers either into compliance investments or market exit. Kerala and Tamil Nadu fabricators are consolidating testing laboratory relationships to maintain certification currency.
Buyer concentration among large-scale furniture exporters is disintermediating traditional distributor networks in favor of direct technical partnerships. Vietnamese and Indonesian mill sales teams now embed directly with procurement functions at major ready-to-assemble brands. This channel compression is most visible in China's Zhejiang and Guangdong furniture manufacturing belts where distributor margins have halved since 2022.
Asia-Pacific Medium-Density Fiberboard Market Segmentation
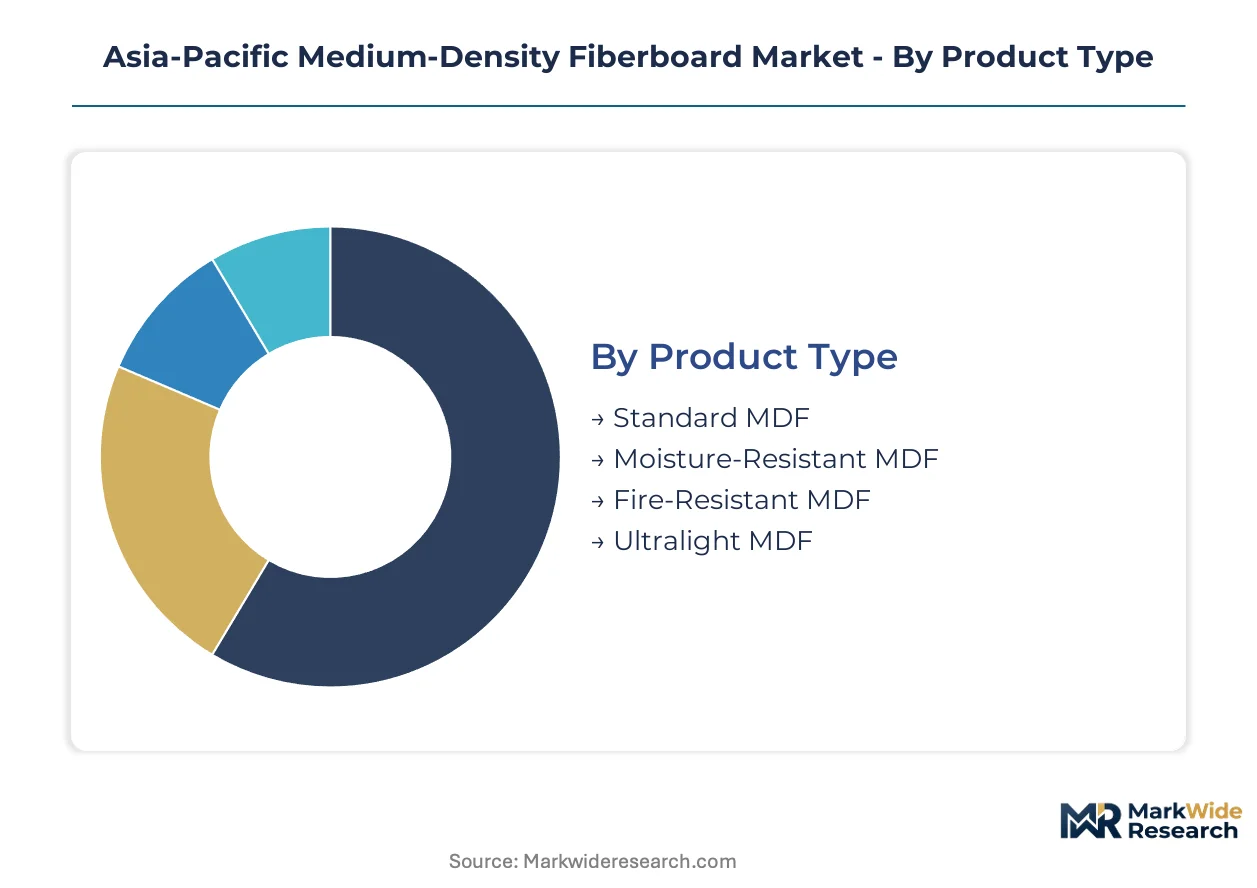
MDF segmentation in Asia-Pacific reflects divergent performance requirements across tropical construction cycles, export furniture manufacturing, and evolving fire safety codes. Specification-grade differentiation now determines procurement patterns more than commodity pricing alone.
Product Type:
Resin formulation and density calibration define competitive positioning across the specification spectrum.
- Standard MDF:Urea-formaldehyde bonded panels at 600-800 kg/m³ density serve mass furniture production across China's Zhejiang and Guangdong belts. Cost efficiency sustains volume leadership despite margin compression from emission compliance upgrades.
- Moisture-Resistant MDF:Melamine-enhanced resin systems achieve <8% thickness swelling under tropical humidity testing. Demand concentrates in Indonesia's Jakarta commercial construction and Philippines infrastructure where monsoon exposure degrades standard grades within 24 months.
- Fire-Resistant MDF:Intumescent additive formulations target Euroclass C ratings for Singapore and Hong Kong high-rise fit-outs. Density penalties limit penetration in price-sensitive residential furniture.
- Ultralight MDF:Sub-600 kg/m³ densities enable mobile retail fixtures and exhibition systems where transport costs dominate total landed cost calculations.
Standard MDF leads on scale; Moisture-Resistant MDF leads on momentum.
End User:
Procurement sophistication varies sharply between specification-driven and cost-driven buyer segments.
- Furniture Manufacturers:Ready-to-assemble cabinetry producers in Gujarat and Maharashtra pull premium grades through direct mill partnerships. EGGER and Kronospan embed technical sales teams with procurement functions at major exporters.
- Construction Industry:Commercial contractors in Manila and Jakarta specify MR-grade substrates in tender documents. Payment cycle friction with mid-tier developers constrains working capital for distributors.
- Flooring Companies:Laminate substrate demand concentrates in Vietnam's export-oriented processing zones. Korean decorative paper sourcing creates import dependency exposure.
- Interior Designers:Boutique specification influence in Singapore and Shanghai drives sampling volume for bio-adhesive grades. Project scale limitations prevent direct mill engagement.
Furniture Manufacturers dominate revenue capture; Interior Designers show steepest specification influence growth.
Application:
Surface quality requirements and dimensional stability demands segment value capture potential.
- Cabinets:Laminated kitchen and wardrobe components require uniform density for membrane press compatibility. China's SAMR emission testing protocols now disqualify non-E0 grades from premium export production.
- Wall Paneling:Commercial interior fit-outs in Bangkok and Kuala Lumpur specify fire-resistant formulations for code compliance. Installation labor shortages delay project conversion to specification.
- Doors:Solid-core flush door production favors standard density grades with screw-holding strength optimization. Indian BIS marking enforcement is expanding to secondary hubs beyond Mumbai.
- Moldings:Precision-profiled trim and baseboard applications demand consistent machining properties. Ultralight grades enable one-person installation in renovation markets.
Cabinets anchor volume throughput; Wall Paneling commands premium realization.
Distribution Channel:
Channel economics reflect buyer scale concentration and technical service requirements.
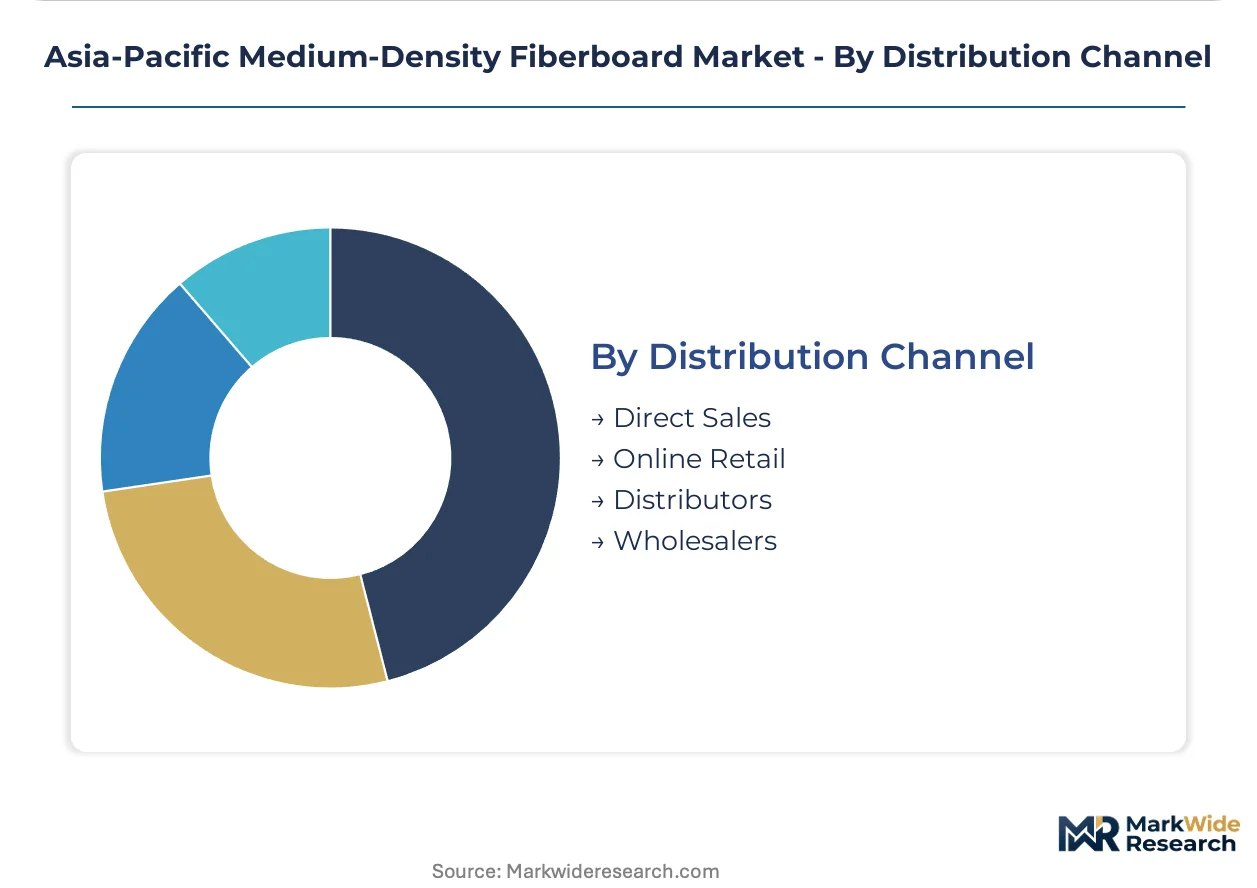
- Direct Sales:Long-term offtake agreements between Indonesian mills and Chinese furniture exporters eliminate distributor markups. Technical partnership models require dedicated quality assurance staffing.
- Distributors:Regional inventory positioning in India's western states supports just-in-time delivery to modular furniture clusters. Working capital intensity limits viable player count.
- Wholesalers:Bulk consolidation of standard grades serves SME fabricators in Thailand's secondary cities. Price transparency from Chinese import competition compresses margins.
- Online Retail:Sample ordering and small-lot procurement for independent designers in Singapore and Sydney. Logistics constraints prevent panel-sized shipment economics.
Direct Sales captures margin expansion; Online Retail shows fastest channel experimentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's formaldehyde emission enforcement contrasts with India's cluster-driven expansion, revealing divergent regulatory pathways across the region. Southeast Asian export hubs navigate compliance cost pressures while building direct procurement relationships. Sub-regional specialization is accelerating as manufacturers optimize for distinct certification regimes.
China
Zhejiang and Guangdong furniture belts pull standard MDF volumes for ready-to-assemble cabinetry exports. SAMR's GB 18580-2017 enforcement mandates E0-grade pre-certification at designated third-party laboratories. Yangtze River Delta mills are absorbing compliance costs through backward integration into resin production.
India
Gujarat and Maharashtra host expanding modular furniture production clusters demanding moisture-resistant grades. BIS marking mandate enforcement is tightening across secondary hubs beyond Mumbai and Delhi. Kerala and Tamil Nadu fabricators are consolidating testing laboratory relationships to maintain certification currency.
Vietnam
Export-oriented processing zones in Binh Duong drive laminate substrate demand for flooring applications. Northern provinces such as Thai Nguyen offer tax incentives and proximity to China-border raw fiber flows. Direct mill procurement channels are displacing traditional distributor networks among large furniture exporters.
Indonesia
Jakarta commercial construction specifies MR-grade substrates in tender documents for tropical humidity resilience. Moisture-resistant formulation demand elevates as monsoon exposure degrades standard grades within 24 months. Mill sales teams embed directly with procurement functions at major ready-to-assemble brands.
Japan
High-rise fit-outs in Tokyo and Osaka specify fire-resistant formulations for code compliance. METI maintains JIS certification requirements that restrict market access for uncertified foreign producers. Approval cycles for new panel grades now exceed eighteen months, front-loading documentation costs.
Asia-Pacific Medium-Density Fiberboard Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the Asia-Pacific MDF landscape. The vendor base fragments across integrated resin-substrate operators, regional distributors, and specification-grade formulators. Three archetypes dominate: vertically integrated multinationals with captive chemical operations, regional champions anchored to single-country demand clusters, and specialty formulators serving premium certification tiers. Capacity expansion and direct procurement partnerships represent the dominant competitive moves.
Among European-anchored multinationals, EGGER Group and Kastamonu Entegre exemplify integrated operational models with resin chemistry capabilities. Century Plyboards (India) Limited occupies a position as a regional champion with specialized moisture-resistant grades tailored to monsoon-exposed construction cycles. Dare Wood-Based Panels Group Co. Ltd represents the scale-driven Chinese fabricator archetype serving mass furniture production belts.
| Leading Market Players |
|---|
| Dare Wood-Based Panels Group Co. Ltd |
| Dongwha Malaysia Holdings Sdn. Bhd. |
| EGGER Group |
| Kastamonu Entegre |
| Century Plyboards (India) Limited |
| West Fraser Timber Co. Ltd |
| DAIKIN CORPORATION |
| Greenply |
| Evergreen Fiberboard Berhad |
| Others |
Value Chain & Pricing Dynamics
Resin chemistry specialists clustered in China's Yangtze River Delta command premium compensation that widens pricing spreads between E0-certified premium grades and standard urea-formaldehyde panels. Labor-cost differentials between integrated mills with captive formulation capabilities and non-integrated competitors translate directly into three-tier pricing stratification across certification tiers.
Pricing Analysis
Capacity additions in Vietnam's northern industrial zones are reshaping price floors for standard-grade exports to China's furniture belts. Pricing stratifies across E0-certified premium, E1-compliant standard, and uncertified economy tiers driven by formaldehyde emission testing costs and brand positioning. Cost compression in standard grades intensifies because Indonesian and Malaysian mills absorb resin feedstock volatility through long-term methanol contracts. Small-scale fabricators in Thailand's secondary cities exhibit highest price sensitivity, while Singapore-based commercial contractors show lowest sensitivity due to fire-code compliance mandates.
Supply Chain Analysis
Dual-sourcing qualification requirements from Japanese METI-certified buyers mandate Indonesian mills maintain parallel resin formulation relationships with Korean and Japanese decorative paper suppliers. Raw fiber supply concentrates in Malaysia, Indonesia, and Vietnam with pulp imports from Australia and New Zealand. Decorative overlay sourcing rests on Busan and Nagoya port throughput, creating single-source vulnerability exposure for laminating operations. Distribution runs through bonded warehouse networks positioned near Gujarat and Maharashtra furniture clusters, supplemented by direct mill procurement channels displacing traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
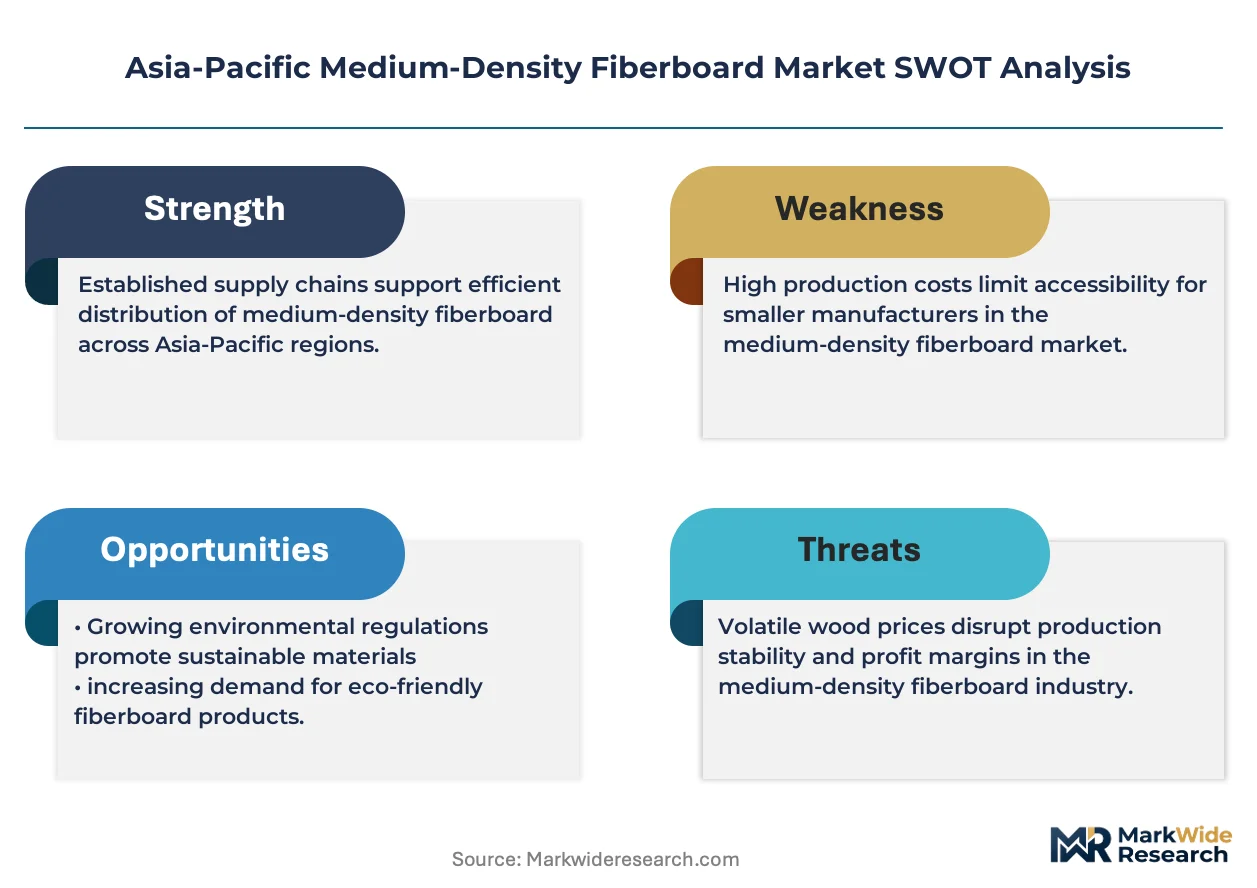
This market functions as a regulatory compounder where China's SAMR enforcement of GB 18580-2017 E0-grade mandates is systematically elevating compliance investments across Southeast Asian export supply chains.
For Market Incumbents: Anticipate margin compression from methanol feedstock volatility by securing captive resin production or backward integration into urea-formaldehyde chemistry. EGGER-style integrated operations across Southeast Asian plants defend against non-integrated mills vulnerable to input cost spikes. Certification currency maintenance through SAMR-designated third-party laboratories represents the critical defensive lever.
For New Entrants and Emerging Players: Digital specification platforms targeting Singapore and Shanghai interior designers offer low-friction entry without direct mill capex requirements. Vietnam's Thai Nguyen province presents the most penetrable geography given tax incentives and underpenetrated northern industrial zones versus saturated southern hubs. Direct technical partnerships with ready-to-assemble brands bypass distributor margin capture.
For Investors and Strategic Acquirers: European-anchored multinationals with resin-substrate integration are the most active acquirers in this space, consolidating mid-scale Southeast Asian mills unable to absorb compliance cost escalations. Target mills with SAMR pre-certification relationships and established raw fiber supply from China-border corridors. Watch for JIS certification timeline compression as inflection indicator for Japanese market access viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Yangtze River Delta mills absorb GB 18580-2017 compliance costs through captive urea-formaldehyde chemistry. |
| Direct Mill Procurement Partnerships | Vietnamese and Indonesian sales teams embed with Zhejiang furniture exporters, eliminating distributor markups. |
| Moisture-Resistant Grade Expansion | Century Plyboards anchors market position through monsoon-exposed construction cycle specialization in Gujarat. |
| Fire-Resistant Formulation Development | Kastamonu Entegre competes on Euroclass C ratings for Singapore and Hong Kong high-rise fit-out codes. |
| Northern Vietnam Capacity Buildout | Thai Nguyen tax incentives and China-border fiber proximity attract export-oriented mill investment. |
Study Parameters
Bottom-up furniture manufacturer demand modeling reconciled against top-down resin and substrate capacity tracking forms the analytical core of this study. Primary interviews with procurement directors at ready-to-assemble cabinetry exporters, plant managers at Indonesian and Malaysian mills, resin formulation specialists in the Yangtze River Delta, and BIS certification laboratory directors in Mumbai and Delhi were validated against secondary sources including SAMR regulatory filings, JIS certification databases, Indian customs trade records, and ASEAN wood-based panel association statistics.
Historical trendline analysis of E0-grade adoption rates, moisture-resistant specification penetration in Jakarta and Manila commercial construction, and direct procurement channel displacement of distributor networks informed the projection framework. Segmentation dimensions modeled include product type by resin formulation and density, end-user procurement sophistication tier, application surface quality requirements, and distribution channel structure. CAGRs were derived from capacity utilization trajectories and regulatory compliance cost absorption curves across the analysis window.
The model assumes a particular technology adoption path for lignin and tannin bio-adhesive formulations; alternative pathways for synthetic resin chemistry optimization would alter the outlook. Forecasts reflect assumptions about SAMR enforcement consistency, JIS certification timeline stability, and methanol feedstock price correlation with natural gas benchmarks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
3D Printing Construction Market
Others
Electric Chainsaw Market
Others
Thermal Insulation Solution for LNG and LPG Market
Others
GCC Health and Wellness Market
Others
Diamond Mining Market
Others
Reusable Wine Bags Market
Others
Medical Simulation Market
Others
Global Food Fiber Market
Others
Augmented Reality in Energy and Utilities Market
Others
Global Tobacco Market
Others
Industrial Air Purifiers Market
Others
South America Orange Market
Others
Global Solder Balls Market
Others
Fresh Apples Market
Others
Agitator Bead Mill Market
Others
Global Snow Sports Apparel Market