
 Asia-Pacific Road Safety Market | 2026-2036
Asia-Pacific Road Safety Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Road Safety Market Insights
Market Context with Strategic Players
India's Motor Vehicles Amendment Act is repositioning vendor qualification standards across the Asia-Pacific Road Safety Market. Kapsch TrafficCom leverages its integrated tolling and enforcement platform to sustain long-term contracts with Indian and Australian transport authorities. Siemens anchors its regional presence through manufacturing scale in digital traffic management infrastructure. Huawei Technologies competes aggressively on AI-based video analytics for intersection monitoring, though its access faces scrutiny under evolving procurement frameworks.
Technical Definition and Structural Segments
Asia-Pacific road safety encompasses engineered systems and services designed to reduce collision frequency and severity on public roadways, incorporating sensor arrays, automated enforcement hardware, and protective physical infrastructure rated for regional climate and load conditions. The primary commercial purpose centers on reducing fatalities and economic losses while ensuring compliance with national transport codes. Traffic Management Systems dominate current revenue pools given their integration complexity and recurring maintenance contracts, while AI-Based Solutions within the technology dimension represent the fastest-expanding segment as municipalities replace legacy camera networks with machine-vision platforms. Safety Apparel remains a mature, price-sensitive category where margin pools have compressed amid standardized procurement.
Regulatory Frame and Forward-Looking Close
India's BIS certification requirements, Australia's state-level intelligent transport system standards, and Japan's JIS road equipment specifications collectively shape product design cycles and market access timelines across the region. TRAI's spectrum allocation decisions in India directly determine deployment feasibility for connected-vehicle and telematics networks that underpin next-generation enforcement architectures. Stakeholders must monitor divergence between national certification regimes and emerging sub-regional procurement blocs that could fragment vendor scale economics.
Market Dynamics
India's Motor Vehicles Amendment Act is compressing vendor qualification timelines while accelerating replacement of legacy camera networks with AI-native enforcement platforms across state transport departments.
Growth Catalysts
- TRAI spectrum allocation:India's telecommunications regulator has released dedicated bandwidth for connected-vehicle networks, enabling real-time telematics deployment for commercial fleet monitoring mandated by the Ministry of Road Transport and Highways.
- Urban infrastructure investment:Municipal corporations in Mumbai, Delhi, and Bangalore are bundling intelligent traffic management systems with metro rail expansions, creating bundled procurement opportunities for integrated sensor-software vendors.
- AI-based video analytics:Machine-vision platforms are replacing rule-based camera systems at intersections, with Australian state transport authorities piloting edge-computing architectures for sub-100-millisecond violation detection.
Market Restraints
- BIS certification timelines:India's Bureau of Indian Standards requires 18-24 month validation cycles for imported sensor hardware, delaying market entry for European and North American equipment suppliers.
- Semiconductor supply concentration:Edge-AI processors for traffic cameras depend on TSMC fabrication capacity in Taiwan, creating vulnerability to regional logistics disruptions.
- Legacy system lock-in:Japanese prefectures maintain extensive proprietary traffic signal networks using JIS-1987 communication protocols, fragmenting procurement standards and raising integration costs for new entrants.
Strategic Opportunities
- Vietnam's unpenetrated expressway network:The country's north-south highway expansion lacks centralized enforcement infrastructure, presenting first-mover potential for integrated tolling-violation platforms.
- Philippines provincial digitization:Local government units outside Metro Manila are accessing national digital infrastructure funds to deploy first-generation automated number-plate recognition systems.
- Telematics-insurance convergence:India's IRDAI has approved usage-based motor insurance frameworks, creating demand for certified onboard diagnostic devices that feed real-time driver behavior data to underwriters.
Industry Challenges
- Embedded systems engineering scarcity:Firmware development for automotive-grade sensor fusion requires specialized talent concentrated in Bangalore and Hyderabad, constraining rollout velocity for secondary cities.
- Interoperability with legacy tolling:Australian state transport departments operate incompatible electronic toll collection protocols, forcing vendors to maintain multiple hardware SKUs and fragmenting maintenance economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Road Safety Market |
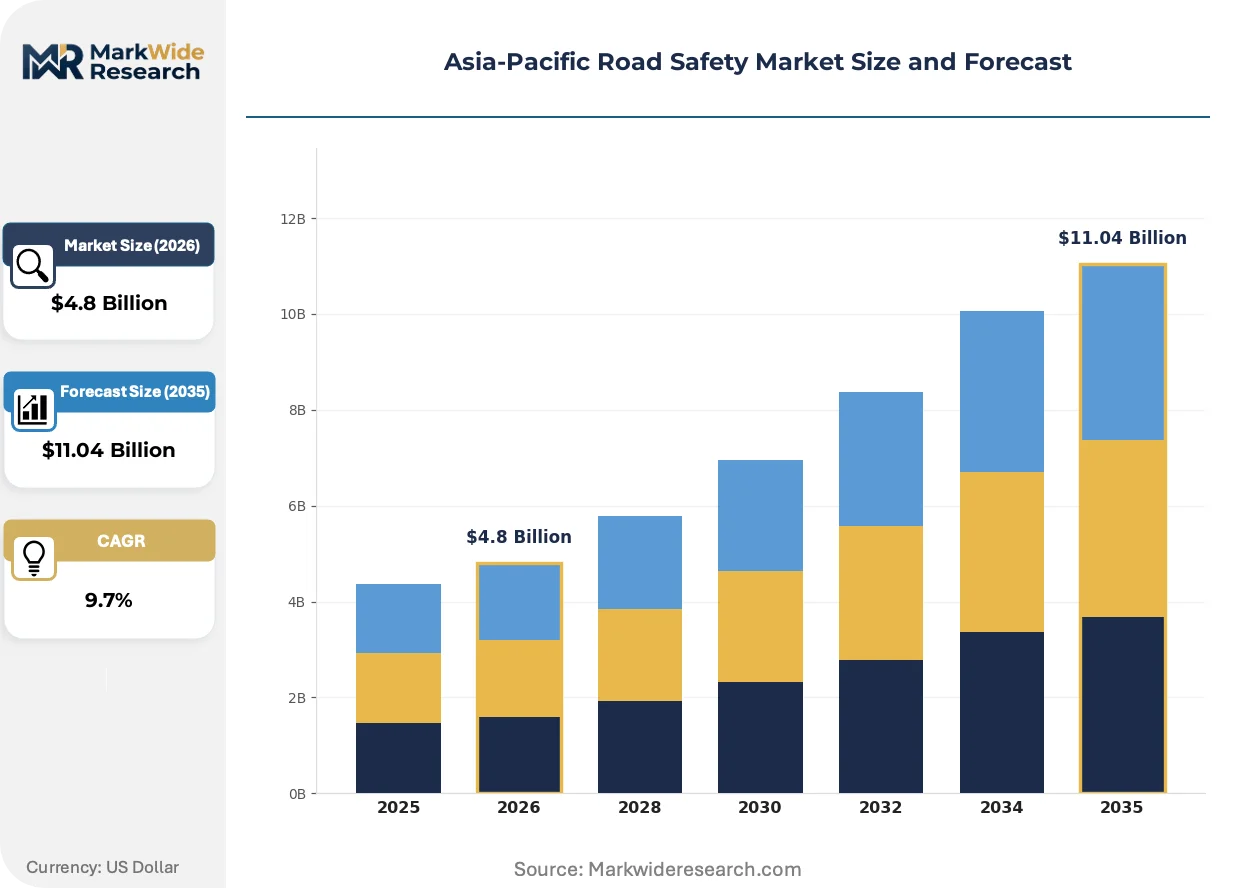
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traffic Management Systems, Road Barriers, Safety Apparel, Signage Application: Public Transport, Infrastructure Development, Emergency Services, Insurance Technology: Telematics, AI-Based Solutions, GPS Systems, Data Analytics End User: Government Agencies, Municipalities, Private Developers, Logistics Companies |
| Companies Covered | Kapsch TrafficCom, Conduent, Verra Mobility, Huawei Technologies, Sensys Gatso, Motorola Solutions, Siemens, Zhejiang Dahua Technology, Jenoptik, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Road Safety Market Trends and Innovations
Edge computing architectures are displacing centralized traffic management models, while regulatory mandates for commercial fleet transparency are accelerating sensor deployment density across the region's logistics corridors.
Multi-sensor fusion platforms is unifying radar, lidar, and optical inputs into single-chip processing units for intersection monitoring. State transport authorities in Queensland and New South Wales are piloting these consolidated units to reduce hardware footprint and cabling complexity. The technology is unifying previously separate enforcement and traffic flow optimization budgets into unified procurement streams.
Australia's state-level intelligent transport system standards are mandating cybersecurity certification for all connected roadside units, following breach incidents in European deployments. Equipment vendors must now demonstrate IEC 62443 compliance before tender qualification, extending product development cycles by 8-12 months. Queensland's Department of Transport and Main Roads has established the region's most stringent validation protocol, becoming a de facto reference for neighboring states.
Fleet operators are consolidating vendor relationships from point-solution providers to full-stack telematics platforms capable of integrating driver monitoring, route optimization, and compliance reporting. This concentration is displacing standalone dashcam vendors in India and Indonesia, where transport aggregators now demand API-native systems. The shift is most visible in India's long-haul trucking sector, where platform economics favor vendors offering predictive maintenance modules alongside basic location tracking.
Asia-Pacific Road Safety Market Segmentation
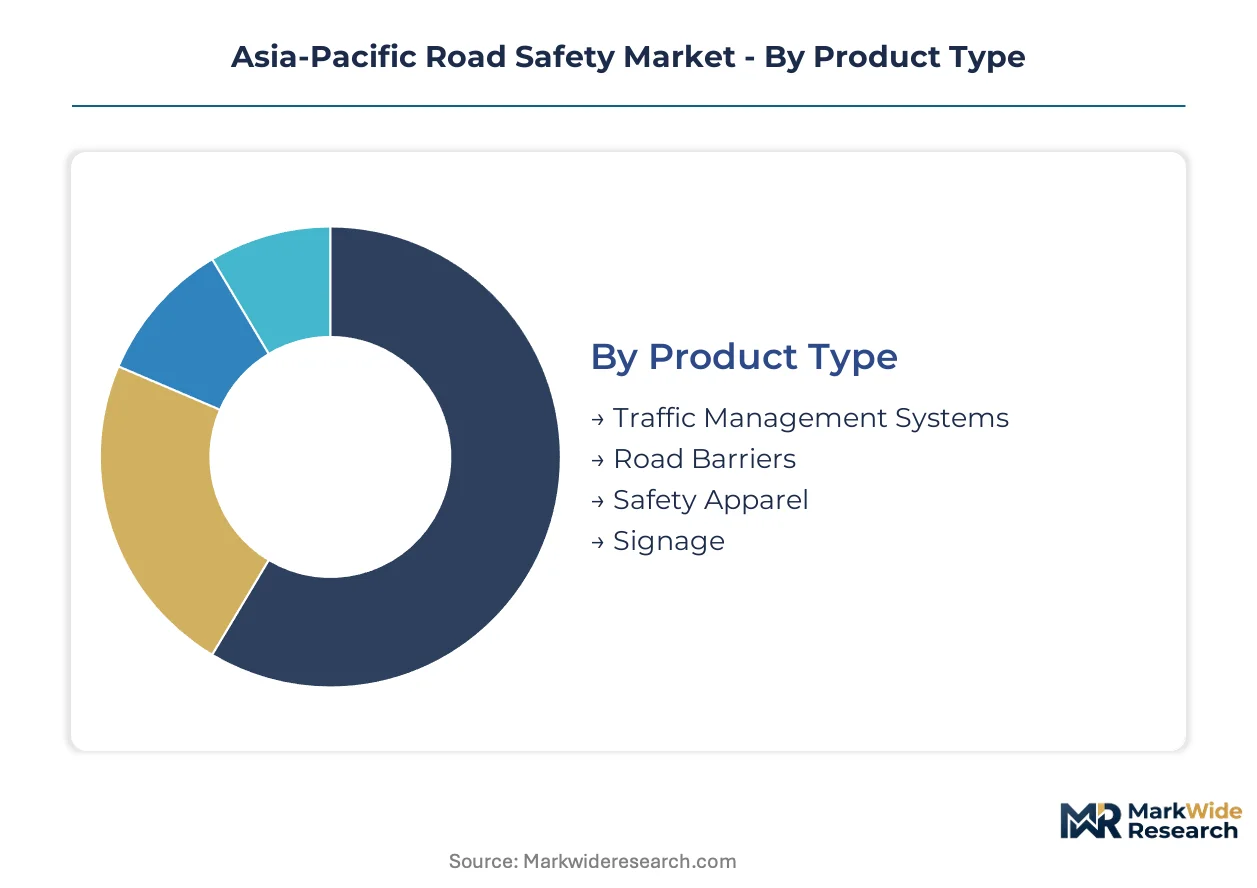
Segmentation in the Asia-Pacific Road Safety Market reveals divergent procurement logics across hardware-intensive and software-native categories. Government buyers prioritize integration complexity and certification compliance, while private fleet operators optimize for real-time data throughput and insurance-certification alignment.
Product Type:
Traffic Management Systems command premium pricing through bundled sensor-software contracts, while Safety Apparel competes on volume scale with compressed margins.
- Traffic Management Systems:Integrated platforms combining radar arrays, edge-computing nodes, and centralized control software for intersection monitoring. Demand concentrates in Indian state transport departments replacing legacy signal networks under Motor Vehicles Amendment Act mandates.
- Road Barriers:Crash-rated physical protection systems engineered for regional climate loads and vehicle impact velocities. Australian state highway authorities specify these for expressway expansion corridors, with procurement tied to infrastructure bond issuance cycles.
- Safety Apparel:High-visibility garments and protective equipment for construction and enforcement personnel.
- Signage:Retroreflective and electronic variable message displays for route guidance and hazard warning.
Today's leader: Traffic Management Systems. Tomorrow's challenger: Road Barriers.
Application:
Infrastructure Development absorbs capital expenditure through multi-year government contracts, while Insurance represents the emerging software-revenue frontier.
- Infrastructure Development:Large-scale deployment of intelligent transport systems alongside highway and urban rail construction. Indian municipal corporations in Mumbai, Delhi, and Bangalore bundle these procurements with metro expansions, creating integrated vendor opportunities.
- Insurance:Usage-based risk assessment platforms leveraging telematics data for dynamic premium calculation. IRDAI's approved frameworks in India are accelerating certified onboard diagnostic device deployment across commercial fleets.
- Public Transport:Fleet monitoring and passenger safety systems for bus and rail operators.
- Emergency Services:Priority signal preemption and incident response coordination technologies.
Infrastructure Development dominates current procurement volume. Insurance is gaining share fastest through regulatory-enabled data monetization.
Technology:
AI-Based Solutions attract venture-scale investment for machine-vision enforcement, while Telematics delivers recurring revenue through fleet management subscriptions.
- AI-Based Solutions:Machine-vision platforms processing optical, radar, and lidar inputs for real-time violation detection and traffic flow optimization. Australian state transport authorities pilot edge-computing architectures achieving sub-100-millisecond detection latency.
- Telematics:Connected-vehicle systems transmitting location, diagnostics, and driver behavior data to centralized monitoring platforms. India's Ministry of Road Transport and Highways mandates these for commercial fleets, with TRAI spectrum allocation enabling real-time network deployment.
- GPS Systems:Satellite-based positioning for fleet tracking and route optimization.
- Data Analytics:Predictive platforms for collision risk assessment and infrastructure maintenance scheduling.
Telematics anchors current installed base. AI-Based Solutions show the steepest expansion trajectory as municipalities replace rule-based camera networks.
End User:
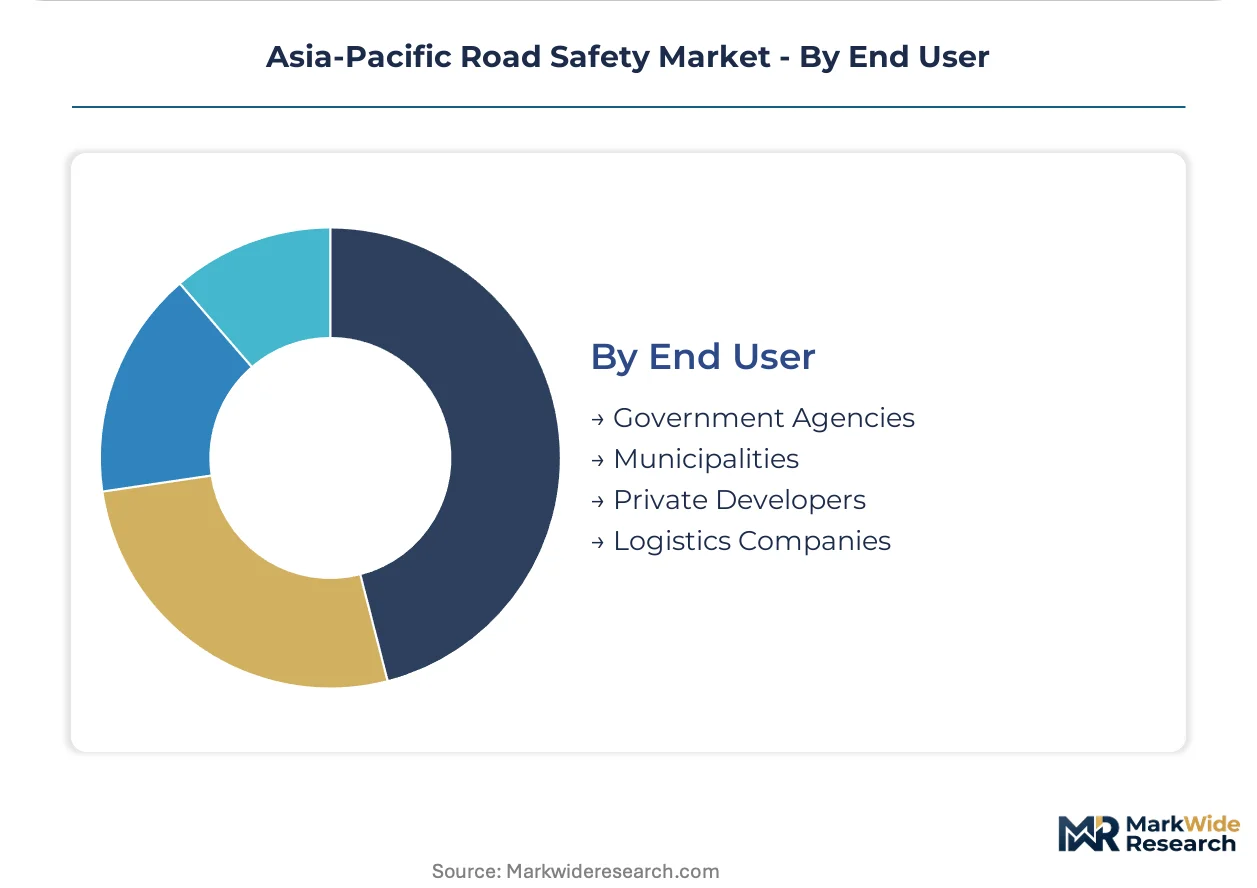
Government Agencies consolidate procurement through framework agreements, while Logistics Companies drive telematics specification through insurance-linked compliance requirements.
- Government Agencies:National and state transport authorities enforcing compliance through mandated technology adoption. India's state transport departments compress vendor qualification timelines under updated road safety directives.
- Logistics Companies:Fleet operators integrating driver monitoring, route optimization, and compliance reporting into unified platforms. Long-haul trucking operators in India favor vendors offering predictive maintenance modules alongside basic tracking.
- Municipalities:Urban local bodies managing traffic congestion and pedestrian safety in dense metropolitan corridors.
- Private Developers:Commercial and residential construction firms procuring site safety equipment and temporary traffic management systems.
Government Agencies control premium contract flow. Logistics Companies are forcing platform consolidation through API-native procurement requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Intelligent transport systems in the Asia-Pacific region trace their commercial scale to Australian state-level deployments in the early 2000s, where centralized traffic management platforms first demonstrated measurable collision reduction. This foundation expanded through Japanese precision manufacturing exports and Indian federal safety mandates, creating today's heterogeneous procurement landscape across five distinct national markets.
India
Urban infrastructure investment and commercial fleet telematics mandates are compressing vendor qualification timelines. The Ministry of Road Transport and Highways requires vehicle telematics integration for all commercial vehicles under amended motor vehicle regulations. State transport departments in Maharashtra and Karnataka are replacing legacy camera networks with AI-native enforcement platforms at major metropolitan intersections.
Australia
State-level intelligent transport system standards and expressway expansion bonds are driving procurement of integrated sensor-software bundles. The Department of Transport and Main Roads in Queensland mandates IEC 62443 cybersecurity certification for all connected roadside units. Transport authorities in New South Wales and Queensland pilot edge-computing architectures achieving sub-100-millisecond violation detection latency.
Japan
Prefectural maintenance of JIS-1987 proprietary traffic signal protocols creates integration complexity for new enforcement technology vendors. METI oversees alignment between domestic equipment specifications and emerging connected-vehicle standards. Industrial concentration in the Chubu region around Nagoya sustains specialized manufacturing for automotive-grade sensor fusion systems.
China
MIIT standards for vehicle-to-infrastructure communication are accelerating deployment of machine-vision platforms across provincial expressway networks. GB standards for road equipment shape product design cycles for domestic and export-bound manufacturers. The Yangtze River Delta cluster around Shanghai anchors production capacity for edge-AI processors used in traffic camera networks.
Vietnam
North-south highway expansion without centralized enforcement infrastructure presents first-mover opportunities for integrated tolling-violation platforms. The country's national transport regulator is developing technical specifications for automated number-plate recognition systems. Provincial transport departments along the expressway corridor are accessing national infrastructure funds for initial digitization efforts.
Asia-Pacific Road Safety Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with embedded government contracting capabilities. Vendor qualification requirements in India and Australia favor established players with existing transport authority relationships and certified manufacturing footprints. Two strategic archetypes dominate: integrated platform providers bundling hardware-software-maintenance contracts, and specialized component suppliers focused on sensor arrays or edge-computing modules. Competitive moves concentrate on strategic partnerships with state transport departments and technology licensing arrangements to accelerate certification timelines.
Among European-anchored systems integrators, Kapsch TrafficCom and Siemens occupy positions exemplifying the integrated platform archetype through sustained government contracting relationships. Huawei Technologies represents the AI-native video analytics specialization, competing on machine-vision capabilities for intersection monitoring despite procurement scrutiny under evolving framework conditions. Sensys Gatso sits within the enforcement technology tier, with company naming indicating Swedish origins and Gatso-branded speed detection heritage.
| Leading Market Players |
|---|
| Kapsch TrafficCom |
| Conduent |
| Verra Mobility |
| Huawei Technologies |
| Sensys Gatso |
| Motorola Solutions |
| Siemens |
| Zhejiang Dahua Technology |
| Jenoptik |
| Others |
Pricing and Supply Chain Analysis
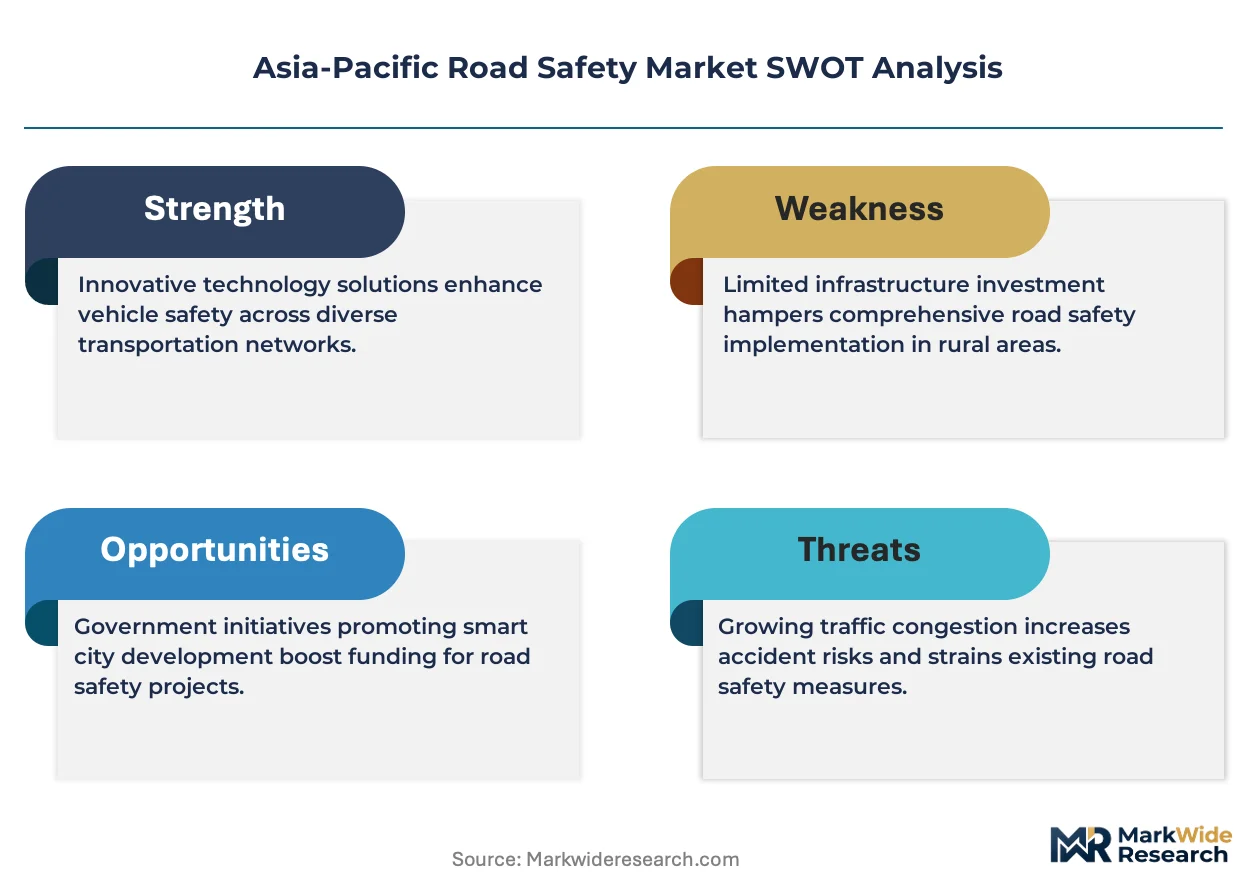
Certification-grade bifurcation between BIS-validated premium systems and uncertified commodity hardware manifests in divergent pricing architectures and supply chain sourcing strategies across Indian and Australian procurement channels. Government transport authorities in Maharashtra and Queensland mandate IEC 62443 and BIS compliance, compressing vendor pools and elevating contract values, while provincial buyers in Vietnam and Philippines access lower-tier equipment through regional distributors with truncated validation cycles.
Pricing Analysis
Bundled sensor-software-maintenance contracts versus unbundled hardware-only transactions defines the dominant pricing split across Asia-Pacific transport authorities. Premium tiers command valuation multiples tied to cybersecurity certification and multi-year service agreements, while commodity tiers compete on unit economics for provincial digitization budgets. Cost compression in the safety apparel category intensifies as standardized procurement erodes brand premiums. Municipal corporations in India exhibit acute price sensitivity for initial deployment phases, whereas Australian state departments prioritize lifecycle cost optimization over upfront capital expenditure.
Supply Chain Analysis
Freight cost escalation from Taiwan and South Korea to Indian and Australian assembly sites elevates landed costs for edge-AI processors and automotive-grade sensor modules. Manufacturing concentration in China's Yangtze River Delta and Japan's Chubu region supplies optical components and radar arrays to regional integrators. Single-source vulnerability at TSMC fabrication capacity for traffic camera processors creates exposure to logistics disruptions. Distribution runs through authorized systems integrators holding state transport department framework agreements, with direct procurement limited to maintenance spares and consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific road safety market represents a late-cycle quality story as Indian and Australian authorities displace legacy camera networks with AI-native enforcement platforms demanding validated cybersecurity architecture and predictive maintenance integration.
For Market Incumbents: Extend maintenance contract durations into ten-year frameworks to lock out emerging AI-native competitors seeking footholds in Australian state pilot programs. Deepen backward integration into edge-computing module production to defend margin position against semiconductor cost volatility. Counter the threat of Huawei's machine-vision pricing aggression through bundled telematics-insurance certification offerings that emerging entrants cannot replicate without IRDAI validation timelines. For New Entrants and Emerging Players: Launch via provincial government unit partnerships in Vietnam's north-south expressway corridor and Philippines local government digitization funds, where centralized enforcement infrastructure remains unpenetrated and qualification barriers sit below Australian and Indian thresholds. Target first-generation automated number-plate recognition deployments outside Metro Manila and Ho Chi Minh City, positioning as full-stack platform providers against fragmented point-solution incumbents. For Investors and Strategic Acquirers: Consolidation pressure builds where firmware development talent concentrates in Bangalore and Hyderabad, constraining rollout velocity for secondary Indian cities and creating acquisition opportunities for embedded systems engineering teams. Long-term viability favors vertically integrated platform providers with captive BIS certification capabilities and recurring telematics subscription revenue. The signal to watch is TRAI spectrum auction outcomes for connected-vehicle bandwidth allocation, which would accelerate real-time enforcement network deployment and reshape valuation multiples for telematics-native assets.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies radar-lidar-optical inputs into single-chip units for Queensland's edge-computing pilots. |
| Certification Investment | Accelerates BIS and IEC 62443 validation timelines to qualify for Indian and Australian framework tenders. |
| Geographic Expansion | Captures first-mover positioning in Vietnam's unpenetrated expressway enforcement corridors. |
| Strategic Partnership | Aligns with IRDAI-approved insurers to embed usage-based motor insurance frameworks in fleet telematics. |
| Acquisition of Specialist Firm | Consolidates Bangalore-based firmware engineering teams to overcome embedded systems scarcity. |
Research Methodology
Multiple input streams — primary interviews with state transport department procurement officers, intelligent transport system integrators, and fleet telematics platform engineers; secondary validation through BIS certification databases, TRAI spectrum allocation records, and Australian state tender archives; plus customs data on sensor hardware imports — were reconciled through bottom-up deployment tracking and top-down market sizing across the analysis window.
Data-stream reconciliation anchored the analytical framework across product type, application, technology, and end-user segmentation dimensions, with additional modeling of certification-tier and procurement-channel variables. CAGRs were derived from installed-base replacement cycles and mandate-driven adoption curves, incorporating TRAI spectrum release timelines and Motor Vehicles Amendment Act implementation phases as demand-acceleration inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply disruption or divergence between national certification regimes and sub-regional procurement blocs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Air Separation Unit Market
Others
Security Envelopes Market
Others
High-End Servers Market
Others
Global Car Wax Market
Others
Industrial Wearable Devices Market
Others
Industrial Hooters Market
Others
Asia-Pacific IVD Regulatory Affairs Outsourcing Market
Others
Asia-Pacific Induced Pluripotent Stem Cells (Ipscs) Market
Others
Corn Fiber Market
Others
Italy Automotive Adaptive Lighting System Market
Others
Pollen Allergy Market
Others
Insoluble Sulfur Market
Others
Air Separation Module Kit Market
Others
Diamond Mining Market
Others
Electric Pallet Jack Truck Market
Others
Propanil Market