
 Brazil Lime Market | 2026-2036
Brazil Lime Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Lime Market Outlook
Aftermarket service revenue in post-harvest handling and cold-chain logistics is tilting toward integrated packers with captive export infrastructure. Cutrale leverages backward integration into orchard management and juice extraction to sustain year-round supply continuity. Citrosuco anchors its position through proprietary varietal development programs and port-adjacent processing facilities. Fischer S/A Agroindustria competes by dominating organic lime certification channels for European retail buyers.
Lime denotes the acid citrus fruit of species primarily Citrus latifolia (Persian lime) and Citrus aurantifolia (Key lime), characterized by peel oil content of 0.5-2.5 percent by weight and juice acidity ranging 5-8 percent citric acid, serving as raw material for beverages, flavoring, and essential oil distillation. Persian Lime commands the volume lead in fresh export trade due to seedless flesh and extended shelf life, while Essential Oils extraction generates disproportionate margin capture from peel residue streams. Online distribution is accelerating fastest among domestic channels as São Paulo-based platforms bypass traditional wholesale markups for restaurant and small-batch processor accounts.
ANVISA regulates maximum pesticide residue limits for citrus destined for domestic consumption and export certification, while the Ministry of Agriculture's MAPA export protocols govern phytosanitary clearance for European and North American shipments. BIS-equivalent metrology standards for Brix and acidity testing shape contract terms between processors and international beverage manufacturers. Stakeholders must monitor pending revisions to EU F-Gas Regulation analogs affecting refrigerated transport fleets serving the Port of Santos corridor.
Market Dynamics
ANVISA's tightened pesticide residue protocols are forcing São Paulo and Minas Gerais processors to reconfigure cold-chain compliance infrastructure, concentrating operational risk among exporters serving European and North American buyers.
Growth Catalysts
- Premium beverage concentrate demand:Juice manufacturers in São Paulo state are expanding Persian and Key lime procurement for high-acidity concentrate production, pulling volume through integrated packer channels.
- MAPAs phytosanitary digitization:Brazil's Ministry of Agriculture is accelerating electronic certification for citrus exports, compressing port clearance timelines at Santos.
- Essential oil distillation margins:Peel residue streams from juice extraction are capturing disproportionate value as European fragrance houses contract directly for cold-pressed oil.
Market Restraints
- Input cost volatility:Refrigerant prices under pending EU F-Gas Regulation analogs are pressuring transport fleet operating costs along the Santos corridor.
- Supply concentration risk:São Paulo state's citrus belt controls over 70 percent of export-grade cold-chain capacity, creating single-point vulnerability to climate events.
- Regulatory friction:ANVISA's updated maximum residue limits for domestic consumption are misaligned with EU MRL standards, forcing dual testing protocols.
Strategic Opportunities
- Organic certification channels:European retail buyers are unbundling conventional procurement to source certified organic limes through dedicated Minas Gerais cooperatives.
- Domestic platform disintermediation:São Paulo-based digital marketplaces are bypassing wholesale markups to serve restaurant and small-batch processor accounts directly.
- Proprietary varietal development:Investment in seedless Persian lime breeding programs offers shelf-life extension for Asian market entry.
Industry Challenges
- Cold-chain technician scarcity:Qualified personnel for refrigerated transport fleet maintenance are concentrated in São Paulo metropolitan area, constraining Minas Gerais expansion.
- Dual certification timelines:Simultaneous ANVISA domestic and MAPA export clearance processes are extending inventory holding periods for mid-tier packers.
- Legacy orchard renovation costs:Replanting programs for disease-affected groves in older São Paulo corridors require capital deployment without immediate yield recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Lime Market |
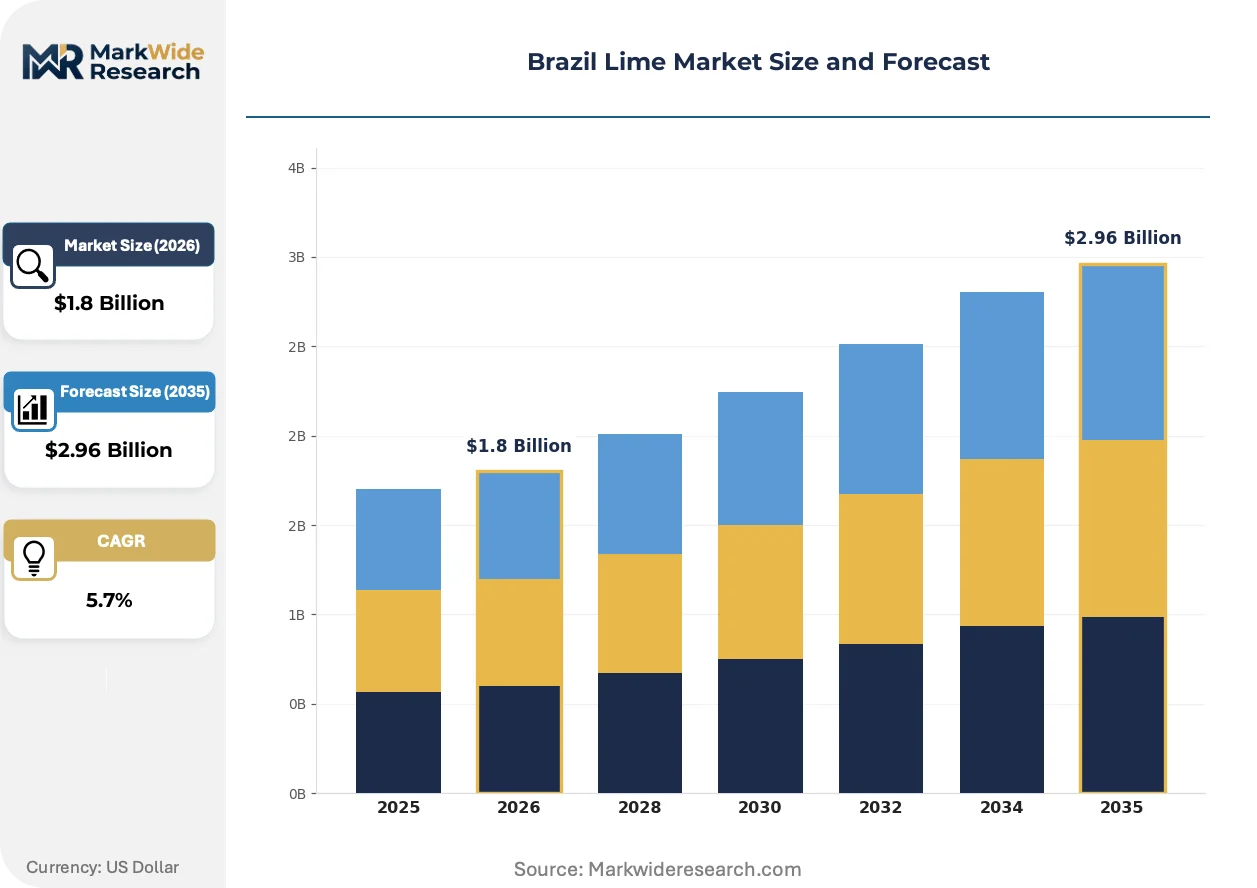
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Persian Lime, Key Lime, Finger Lime, Sweet Lime End Use: Beverages, Culinary, Essential Oils, Cosmetics Packaging Type: Bulk, Bottles, Pouches, Cans Distribution Channel: Online, Supermarkets, Wholesale, Specialty Stores |
| Companies Covered | Itacitrus, Peru Comercial Exportadora de Frutas, Four Seasons Harvest, Jaguar The Fresh Company, Citrosuco, Cutrale, Sucos Citrosuco, Fischer S/A Agroindustria, Montecitrus, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Lime Market Strategic Shifts
Processing technology and distribution architecture are converging to compress margins at traditional wholesale layers while elevating traceability requirements across the value chain.
Hyperspectral sorting systems for peel defect detection are hybridizing quality control workflows at port-adjacent packing facilities. Large integrated processors in São Paulo's coastal zone are deploying this technology to replace manual grading lines. The convergence of optical sensing and automated rejection mechanisms is compressing labor costs while tightening Brix and acidity consistency for export contracts.
ANVISA's phased implementation of electronic traceability mandates for fresh citrus exports is restructuring documentation workflows. Processors must now integrate farm-level pesticide application records with lot-level barcoding for European customs pre-clearance. Mid-tier packers without ERP integration are facing exclusion from supermarket retail procurement channels in Germany and France.
Restaurant procurement through specialized produce platforms is displacing traditional CEASA wholesale market purchases in São Paulo and Rio de Janeiro. These platforms offer lot-specific acidity certificates and next-day cold-chain delivery that municipal wholesalers cannot match. The shift is most visible among high-volume ceviche and cocktail bar segments concentrated in São Paulo's Pinheiros and Vila Madalena districts.
Brazil Lime Market Segmentation
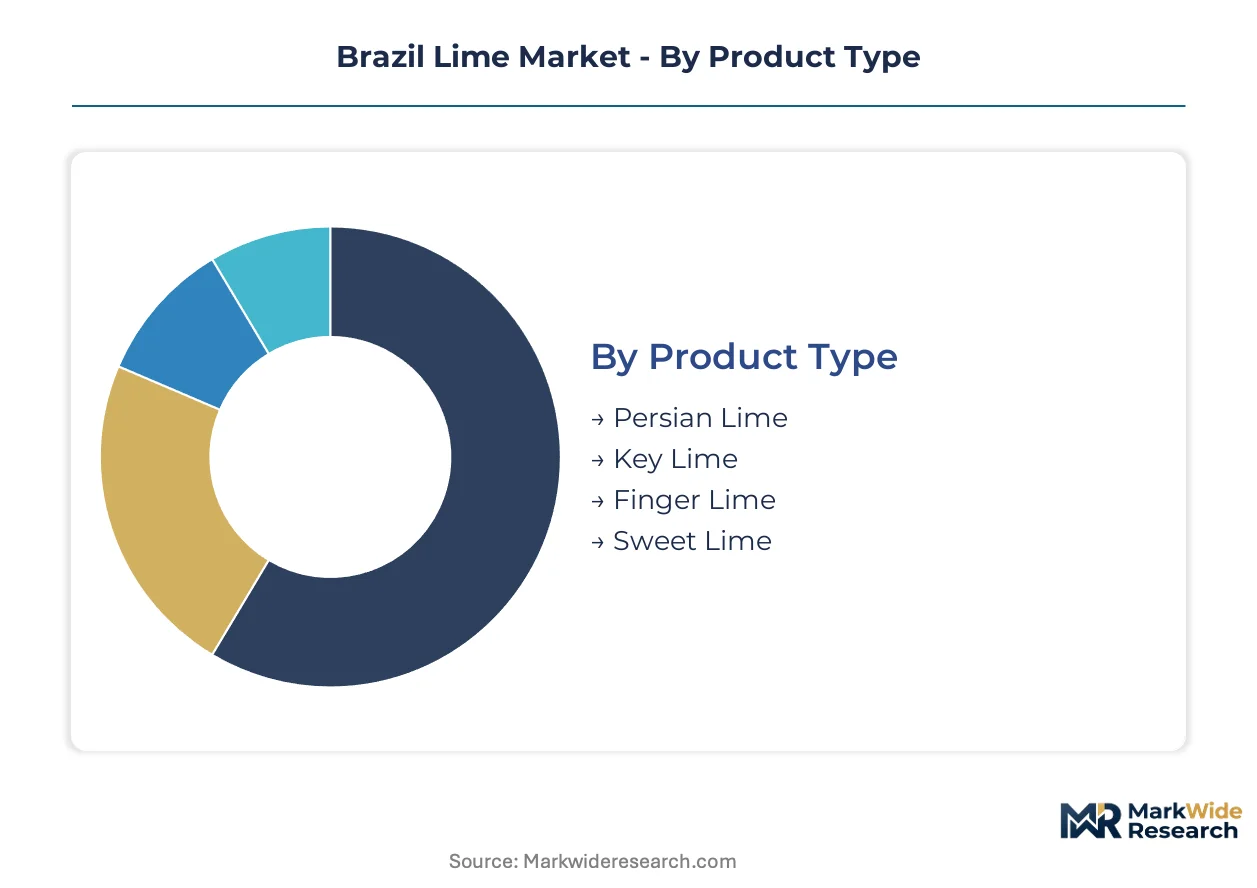
Brazil's lime market segments reflect divergent margin structures across fresh export, processed concentrate, and essential oil extraction channels. Understanding these divides exposes where integrated packers capture value versus where commodity pressure concentrates.
Product Type:
Cost tier differentiation separates seedless premium varieties from commodity-grade alternatives with shorter shelf stability.
- Persian Lime:Seedless flesh and extended post-harvest durability make this the dominant export-grade variety. São Paulo's integrated packers control cold-chain logistics for European retail contracts demanding consistent Brix and acidity specifications.
- Key Lime:Higher acidity levels and distinctive aromatic oil profile command premium positioning in beverage concentrate manufacturing. Procurement is tightening around Minas Gerais cooperatives with organic certification for North American buyers.
- Finger Lime:Caviar-like vesicle structure targets high-end culinary applications in São Paulo and Rio de Janeiro restaurant channels.
- Sweet Lime:Lower acidity limits industrial processing suitability, constraining demand to fresh domestic consumption in Northeast Brazil.
Persian Lime commands the established base. The steepest expansion runs through Key Lime as premium beverage manufacturers reformulate for higher acidity concentrates.
End Use:
Application-specific requirements reshape procurement patterns across beverage manufacturing, food service, and industrial extraction verticals.
- Beverages:Juice concentrate production pulls volume through São Paulo state processing corridors where ANVISA-compliant packers serve multinational soft drink and cocktail mixer manufacturers.
- Essential Oils:Peel residue streams from juice extraction capture disproportionate margin through direct contracts with European fragrance houses for cold-pressed oil.
- Culinary:Fresh fruit demand concentrates in Rio de Janeiro and São Paulo restaurant clusters, with platform-based procurement displacing traditional CEASA wholesale purchases.
- Cosmetics:Limonene and citral extraction for personal care formulations represents a developing outlet for secondary-grade fruit rejected from fresh export channels.
Beverage applications anchor volume throughput. Essential Oils deliver the most concentrated margin capture per kilogram of raw material processed.
Packaging Type:
Volume scale and shelf-life requirements segment procurement between industrial bulk and retail-ready formats.
- Bulk:10kg cartons and 500kg bins dominate export-grade fresh shipments to European supermarket distribution centers, with MAPA phytosanitary certification tied to lot-level traceability.
- Bottles:200ml to 1-liter PET and glass containers serve ready-to-drink juice and cocktail mixer segments in domestic retail.
- Pouches:Flexible packaging gains traction in food service concentrate portions for São Paulo-based restaurant platforms.
- Cans:Aluminum packaging for carbonated lime beverages remains limited by canning line concentration in Southeast Brazil.
Bulk formats command export volume leadership. Pouches are climbing fastest as platform distribution penetrates food service procurement.
Distribution Channel:
Customer type and purchase frequency determine channel economics, with digital intermediation compressing traditional wholesale markups.
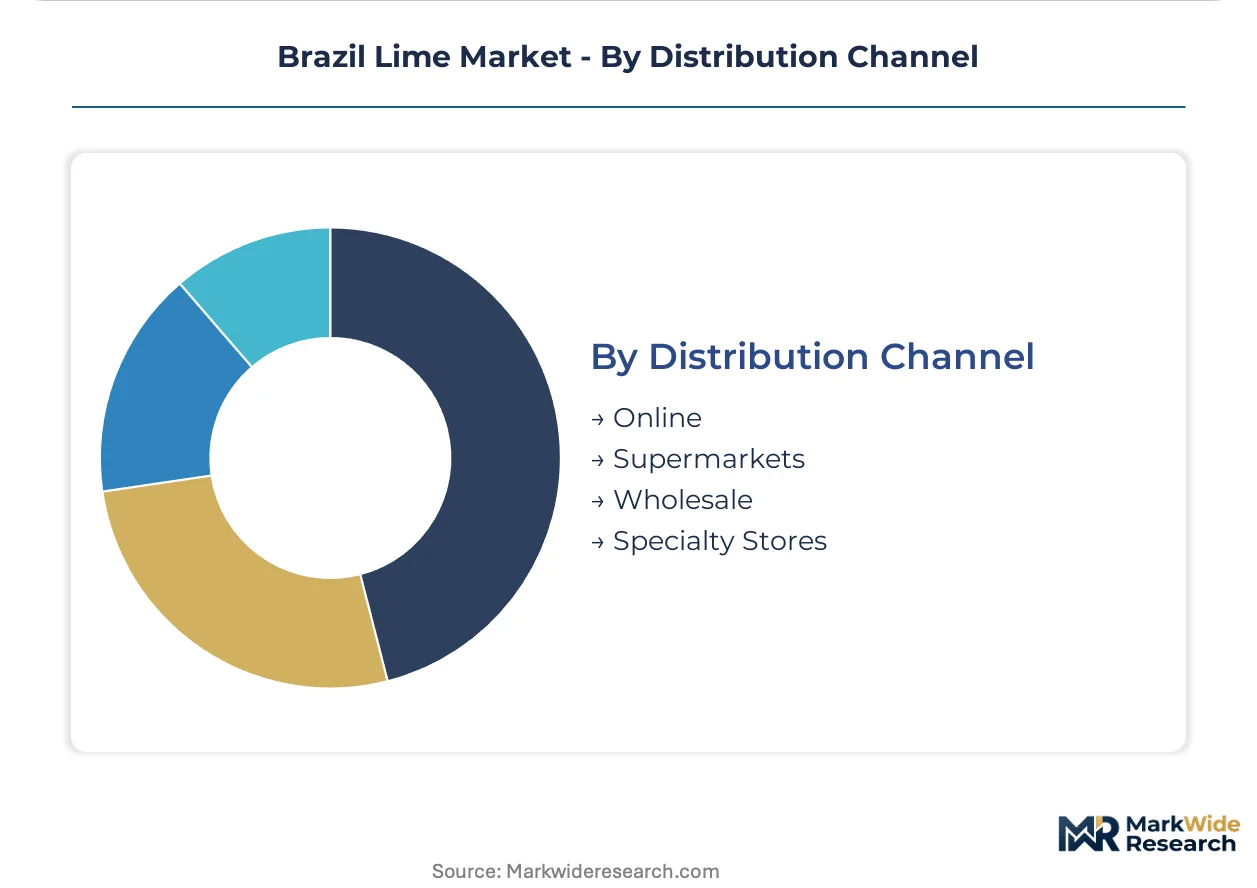
- Online:São Paulo-based produce platforms bypass CEASA wholesale layers to serve restaurants and small-batch processors with lot-specific acidity certificates and next-day cold-chain delivery.
- Supermarkets:Carrefour and GPA chains dominate domestic retail, with private-label lime juice concentrate sourced through Citrosuco and Cutrale direct supply agreements.
- Wholesale:CEASA municipal markets in São Paulo and Rio de Janeiro retain volume for traditional restaurant and street vendor procurement, though share is eroding to platform alternatives.
- Specialty Stores:Organic and gourmet retailers in Pinheiros and Vila Madalena districts source certified organic limes through Fischer S/A Agroindustria's dedicated Minas Gerais cooperative channels.
Supermarkets retain the volume base. Online channels are gaining share fastest among high-frequency restaurant and processor accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Brazil's lime-producing states diverge sharply, with São Paulo driving export-grade cold-chain throughput while Minas Gerais channels organic-certified volume toward European retail buyers.
São Paulo
Premium beverage concentrate manufacturers in São Paulo state's citrus belt pull Persian lime volume through integrated packer channels. ANVISA's updated pesticide residue protocols force processors to reconfigure compliance infrastructure for European and North American export certification. The port-adjacent processing corridor between Santos and São Paulo city anchors cold-chain logistics for supermarket distribution contracts.
Minas Gerais
Organic lime certification for European retail buyers concentrates procurement through dedicated cooperatives in Minas Gerais. MAPA's phytosanitary digitization programs compress port clearance timelines for exporters shipping through Santos. The Triângulo Mineiro region hosts Fischer S/A Agroindustria's certified organic channels serving German and French supermarket chains.
Rio de Janeiro
Restaurant procurement through specialized produce platforms displaces traditional CEASA wholesale purchases in Rio de Janeiro's metropolitan zone. ANVISA's electronic traceability mandates require farm-level pesticide records integrated with lot-level barcoding. High-volume ceviche and cocktail bar segments in Rio's South Zone drive platform-based next-day cold-chain delivery demand.
Rio Grande do Sul
Domestic sweet lime consumption for fresh fruit markets dominates Rio Grande do Sul's lower-acidity procurement patterns. The state's agricultural extension services align orchard management with ANVISA domestic consumption standards rather than export certification. Porto Alegre's municipal wholesale markets retain traditional procurement relationships with Northeast Brazil distribution networks.
Bahia
Emerging citrus cultivation in Bahia's semi-arid corridors targets domestic juice processing to reduce transport costs to São Paulo concentrate manufacturers. MAPA regional offices coordinate phytosanitary baseline establishment for potential future export corridor development. The Petrolina-Juazeiro agricultural cluster experiments with drip-irrigation Persian lime cultivation for shelf-life extension trials.
Brazil Lime Market Competitive Environment
Capability concentration sits with integrated packers controlling captive cold-chain infrastructure; scale advantage sits with diversified agroindustrial conglomerates spanning multiple citrus varieties. The market structures around three tiers: multinational juice processors with port-adjacent extraction facilities, mid-tier packers dependent on third-party logistics, and specialized organic certifiers serving premium European retail. Dominant competitive moves include backward integration into orchard management and proprietary varietal development programs.
Among Brazil-based integrated agroindustrial groups, Citrosuco, Cutrale, and Fischer S/A Agroindustria occupy distinct archetype positions. Citrosuco exemplifies the port-adjacent processor model with proprietary breeding programs. Cutrale represents backward integration into year-round supply continuity through captive orchard management. Fischer S/A Agroindustria anchors the organic certification specialist tier, channeling Minas Gerais cooperative production toward European retail buyers demanding segregated supply chains.
| Leading Market Players |
|---|
| Itacitrus |
| Peru Comercial Exportadora de Frutas |
| Four Seasons Harvest |
| Jaguar The Fresh Company |
| Citrosuco |
| Cutrale |
| Sucos Citrosuco |
| Fischer S/A Agroindustria |
| Montecitrus |
| Others |
Value Chain & Pricing Dynamics
The Santos-Port of São Paulo refrigerated transport corridor anchors cost dynamics across Brazilian lime export channels, where cold-chain concentration in São Paulo state amplifies pricing power for integrated packers while downstream tiers stratify between premium organic certification and commodity-grade spot markets.
Pricing Analysis
Long-term offtake contracts dominate export-grade Persian lime procurement, with multinational beverage manufacturers locking in volume commitments against ANVISA-compliant supply bases. Three-tier pricing structure across premium organic, certified export-grade, and domestic commodity levels separates Fischer S/A Agroindustria's European retail channels from integrated packer spot sales and CEASA wholesale transactions. Cost compression in domestic commodity tiers is intensifying because platform-based disintermediation erodes traditional wholesale markups. Small-batch processors and independent restaurants exhibit highest price sensitivity, while fragrance houses contracting for cold-pressed essential oils show lowest elasticity.
Supply Chain Analysis
ANVISA's electronic traceability mandates function as de facto export-control protocols, restricting fresh citrus flows to processors with ERP-integrated farm-level documentation systems. Geographic supply concentration centers on Brazil, with secondary sourcing from Mexico and Argentina for counter-seasonal coverage. Raw material dependencies include refrigerant gases for transport fleets, corrugated packaging for export cartons, and agricultural inputs for orchard management. Single-source vulnerability concentrates in São Paulo state's citrus belt, where climate events threaten over 70 percent of export-grade cold-chain capacity. Distribution runs through port-adjacent packing facilities direct to European supermarket distribution centers, bypassing traditional wholesale layers for certified organic channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified cold-chain technicians for refrigerated transport fleet maintenance are concentrated in São Paulo's metropolitan core, creating a binding constraint on Minas Gerais expansion and organic certification growth.
For Market Incumbents: Build captive orchard management moats through backward integration into year-round supply continuity. Cutrale's model of controlling extraction-to-export logistics should be replicated to defend against platform-based disintermediation threatening wholesale margins. Priority lever: proprietary varietal development programs extending shelf life for Asian market entry. For New Entrants and Emerging Players: Build out specialized organic certification infrastructure in Minas Gerais cooperatives, where European retail buyer demand outstrips Fischer S/A Agroindustria's current capacity. The most penetrable white space sits in platform-based restaurant procurement for Rio de Janeiro's high-volume ceviche and cocktail bar segments. Go-to-market angle: lot-specific acidity certificates with next-day cold-chain delivery guarantees. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified agroindustrial conglomerates with underperforming citrus divisions lacking ANVISA-compliant export certification infrastructure. Long-term viability over the coming decade hinges on regulatory compliance scalability rather than commodity volume scale. Signal to watch: MAPA phytosanitary digitization adoption rates among mid-tier packers as inflection indicator for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchard Management | Captive supply of Persian lime volume insulates Cutrale against seasonal price volatility from third-party growers. |
| Proprietary Varietal Development Program | Citrosuco's seedless breeding investments extend post-harvest durability for Asian supermarket distribution contracts. |
| Organic Certification Channel Expansion | Fischer S/A Agroindustria's Minas Gerais cooperative network captures premium pricing from German and French retail buyers. |
| Platform-Based Direct Distribution | São Paulo digital marketplaces bypass CEASA wholesale markups to serve Pinheiros district restaurants with traceable lot documentation. |
| Port-Adjacent Processing Facility Upgrade | Cold-chain infrastructure at Santos corridor compresses clearance timelines under MAPA's electronic certification protocols. |
Study Parameters
A standing panel of integrated packer operations directors, ANVISA compliance officers, European supermarket category buyers, cold-chain logistics managers, and Minas Gerais cooperative administrators provided ongoing calibration across primary interview cycles. Secondary validation drew from MAPA phytosanitary certification databases, ANVISA pesticide residue limit publications, Port of Santos cargo throughput records, and EU F-Gas Regulation analog proposals affecting refrigerated transport. Bottom-up volume modeling triangulated against top-down value estimates from beverage manufacturer procurement disclosures.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning product variety, end-use application, packaging format, and distribution channel. CAGRs were derived from trend extrapolation of procurement volume commitments and pricing trajectories observed in contract disclosures. Industry-specific forecast inputs included essential oil distillation margin capture rates from peel residue streams and platform-based channel penetration curves in São Paulo metropolitan restaurant procurement.
Practitioners should monitor ANVISA protocol revisions, EU F-Gas Regulation analog implementations, and climate event frequency in São Paulo's citrus belt for early signals requiring forecast reassessment. Material shifts in cold-chain technician labor availability or MAPA digitization timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Smart Card Market
Others
Safety Critical Software Testing Market
Others
Massive Machine Type Communication in Healthcare Market
Others
UK Real Estate Hospitality Market
Others
North America Wiring Duct Market
Others
South Korea Intellectual Property Market
Others
Eye Balm Market
Others
Aircraft Lighting Market
Others
Bio-Imaging Technologies Market
Others
Double Card Mobile Phone Market
Others
Solar Panel Testers Market
Others
Allogeneic Human Chondrocyte Market
Others
Canada Laser Hair Removal Market
Others
China Cloud Gaming Technology Market
Others
Mobile Computer Cart Market
Others
Europe Indoor LBS Market