
 Hopper Dryers Market | 2026-2036
Hopper Dryers Market Size, Share, and Industry Trends Forecast 2026-2036
Hopper Dryers Market Outlook
The capital-intensity divergence between integrated thermal-system vendors and component assemblers is reorganizing competitive tiers in hopper dryers. Wittmann Battenfeld leverages its captive injection molding ecosystem to bundle drying units with processing lines. Conair sustains broad geographic coverage through distributed service networks. Matsui Mfg. Co., Ltd. anchors its position with compact, energy-efficient designs tailored to Asian electronics molding clusters.
Hopper dryers are enclosed vessels engineered to reduce moisture content in granular or pelletized feedstocks, typically operating at dew points between -40°C and -20°C using desiccant beds or heated air streams, before conveying material directly into extrusion or injection units. Continuous hopper dryers command the largest installed base across high-volume plastics plants, while vacuum hopper dryers capture expanding share in pharmaceutical and hygroscopic polymer applications where oxidation-sensitive resins require sub-atmospheric moisture removal. Heat pump technology segments are gaining traction as facilities retrofit away from conventional hot-air systems constrained by rising energy costs and refrigerant compliance burdens.
OSHA ventilation standards and the EPA National Emission Standards for Hazardous Air Pollutants shape equipment specifications for resin drying operations in U.S. manufacturing facilities. EU REACH compliance and CE marking requirements for thermal processing machinery govern market access across European plastics processing hubs. Buyers must weigh total cost of ownership against retrofit compatibility as regulatory pressure on energy efficiency and refrigerant chemistry intensifies.
Market Dynamics
EU F-Gas Regulation phaseout timelines are forcing plastics processors across Germany, France, and Italy to retire conventional refrigerant-based drying systems ahead of planned replacement cycles, compressing capital expenditure timelines and reshaping vendor contract structures.
Growth Catalysts
- Automotive lightweighting mandates:OEM specifications for engineering-grade polymers in electric vehicle battery housings require moisture levels below 0.02%, driving specification upgrades at Tier-1 molding facilities.
- REACH compliance enforcement:ECHA substance restrictions on residual monomers in medical-grade resins mandate validated drying documentation, expanding equipment procurement in pharmaceutical packaging clusters.
- Heat pump efficiency gains:Coefficient of performance improvements above 4.0 in industrial heat pump dryers cut specific energy consumption versus conventional hot-air systems, accelerating retrofit decisions at energy-intensive compounding plants.
Market Restraints
- Refrigerant supply concentration:EU F-Gas quota reductions have tightened R-134a and R-410A availability, inflating service costs for legacy desiccant wheel systems and extending lead times for replacement compressors.
- Copper and aluminum price volatility:Heat exchanger fabrication costs swing with London Metal Exchange pricing, compressing margins for equipment assemblers without captive metal sourcing.
- Technical limitation in ultra-low dew points:Heat pump systems struggle to achieve -40°C dew points consistently below 5°C ambient, restricting deployment in unheated Nordic processing halls without supplemental desiccant stages.
Strategic Opportunities
- Poland and Czech Republic processing expansion:Automotive supply chain relocation from Germany into lower-cost Central European manufacturing zones creates greenfield equipment demand without legacy infrastructure constraints.
- Infrared drying convergence with optical sorting:Near-infrared moisture detection integrated with short-wave infrared heating enables real-time closed-loop control, opening premium positioning in hygroscopic engineering polymer applications.
- EU Green Deal industrial decarbonization funding:Member state recovery facility grants covering 30-50% of energy-efficient equipment capex accelerate payback calculations for heat pump dryer investments.
Industry Challenges
- Thermodynamics and heat transfer engineering skills gap:Equipment vendors struggle to hire process engineers capable of modeling coupled heat and mass transfer in multi-zone drying simulations, delaying custom system commissioning.
- CE marking timeline compression:Notified body backlogs for thermal processing machinery safety assessments extend market entry by 4-6 months for novel heat pump architectures, advantaging incumbents with established certification portfolios.
- Legacy SCADA integration complexity:Brownfield plants running 1990s-era injection molding cells require costly protocol bridges to connect smart dryer monitoring systems, fragmenting upgrade decisions across maintenance budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hopper Dryers Market |
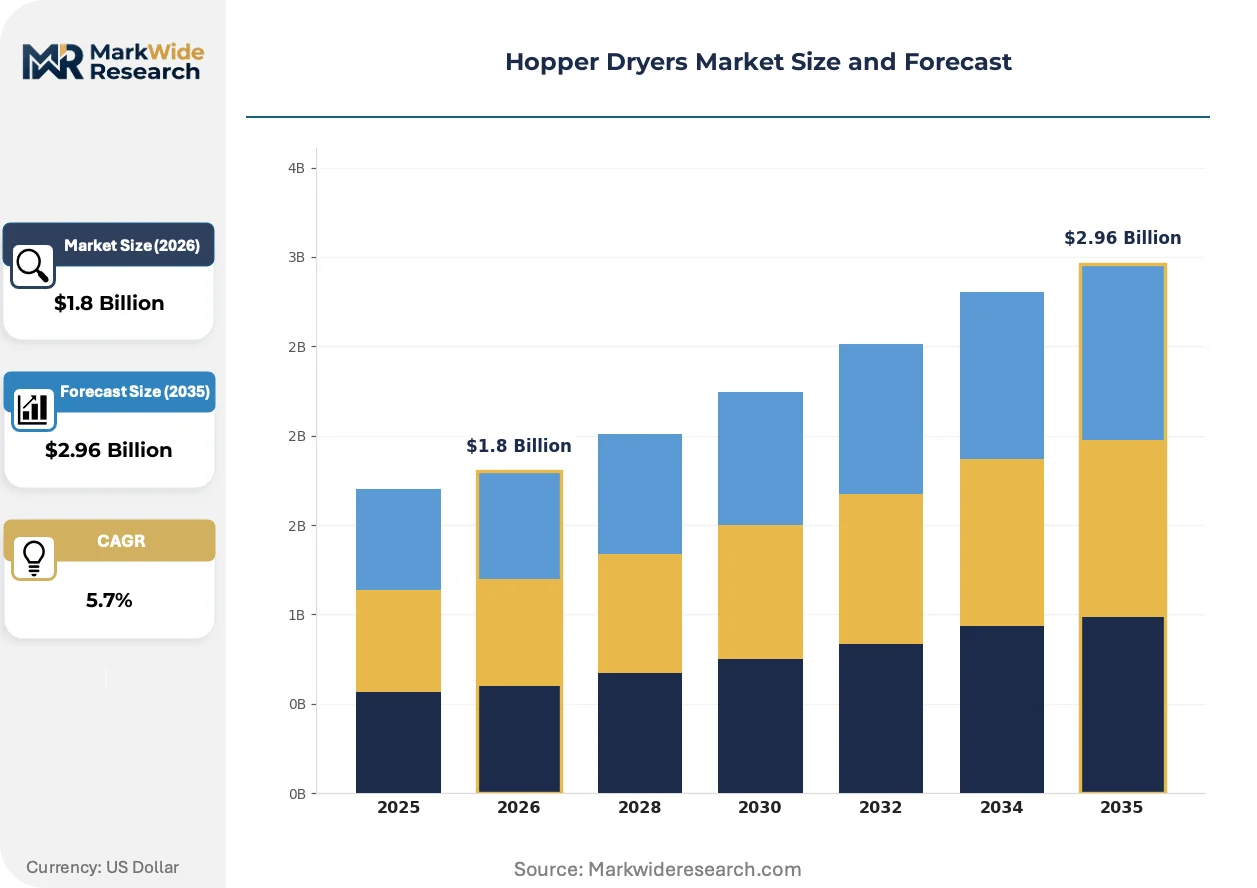
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Hopper Dryers, Continuous Hopper Dryers, vacuum Hopper Dryers, Portable Hopper Dryers Technology: Hot Air, Infrared, Microwave, Heat Pump End User: Food Processing, Plastics Manufacturing, Pharmaceutical, Textile Connectivity: Wired, Wireless, IoT-Enabled, Manual |
| Companies Covered | Shini Plastics Technologies, Conair, Wittmann Battenfeld, Motan Colortronic, Novatec, Matsui Mfg. Co., Ltd., Piovan, Dri-Air Industries, Bry-Air, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hopper Dryers Market Strategic Shifts
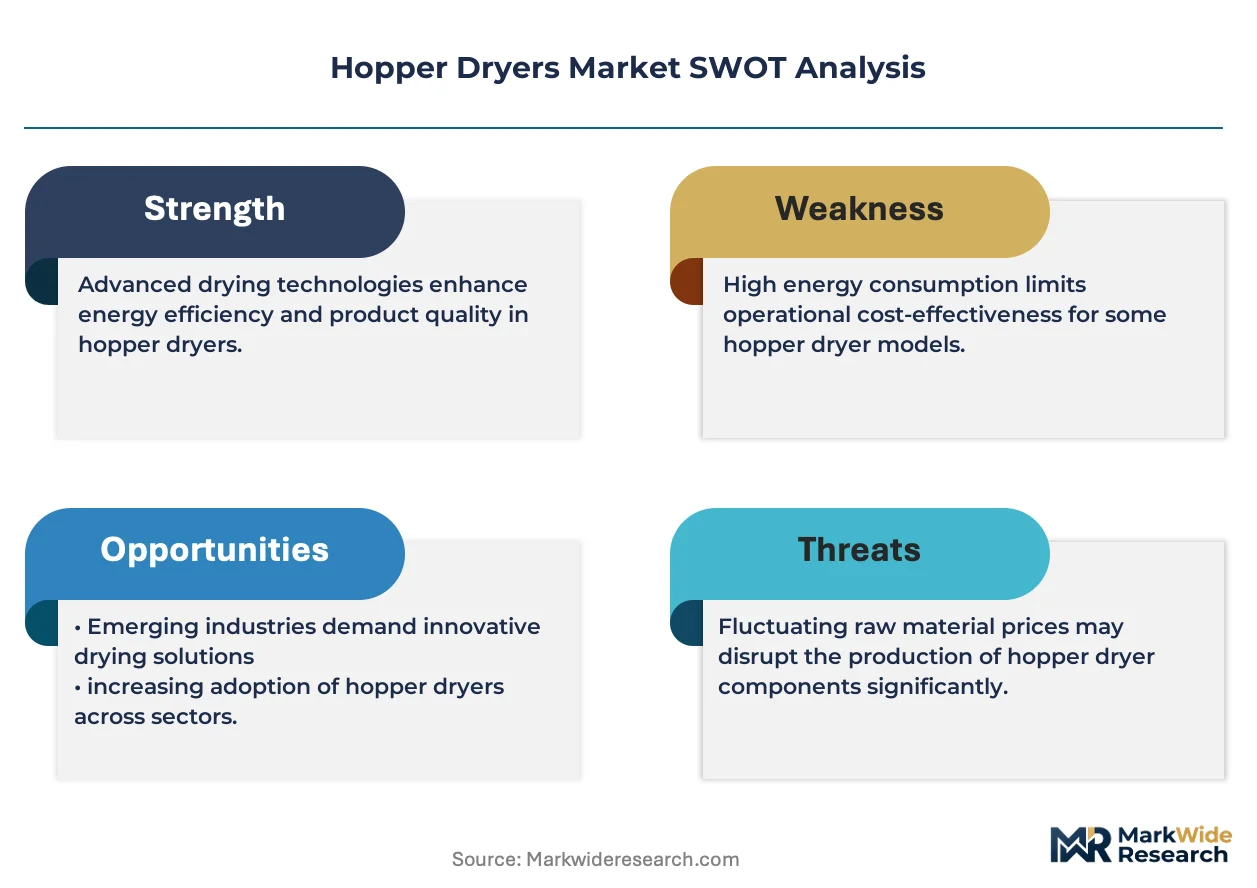
Moisture control technology is bifurcating between premium heat pump systems for energy-conscious volume processors and specialized vacuum dryers for oxidation-sensitive resins, with digital monitoring layers becoming standard across both tiers.
Heat pump dehumidification is displacing conventional desiccant wheel dryers in high-throughput polyolefin processing plants. Automotive bumper and interior trim molders in Germany and the US Midwest are specifying these systems for 40-60% energy reduction. The technology is compressing the total cost of ownership gap that previously favored hot-air systems in regions with low electricity tariffs.
EU F-Gas Regulation refrigerant phaseout schedules are accelerating equipment replacement decisions ahead of technical end-of-life. Processors face 2027 bans on virgin R-134a service fills, forcing mid-cycle capital deployment. Medical device manufacturers in Ireland and Switzerland are prioritizing heat pump and infrared alternatives to avoid compliance documentation burdens on legacy systems.
Service contract unbundling is separating dryer maintenance from captive molding line agreements. Tier-2 automotive suppliers in Spain and Mexico now procure drying-as-a-service from specialized regional providers rather than OEM service networks. This shift is visible most acutely in injection molding clusters where equipment utilization rates fluctuate with OEM production schedules, favoring opex-over-capex financing structures.
Hopper Dryers Market Segmentation
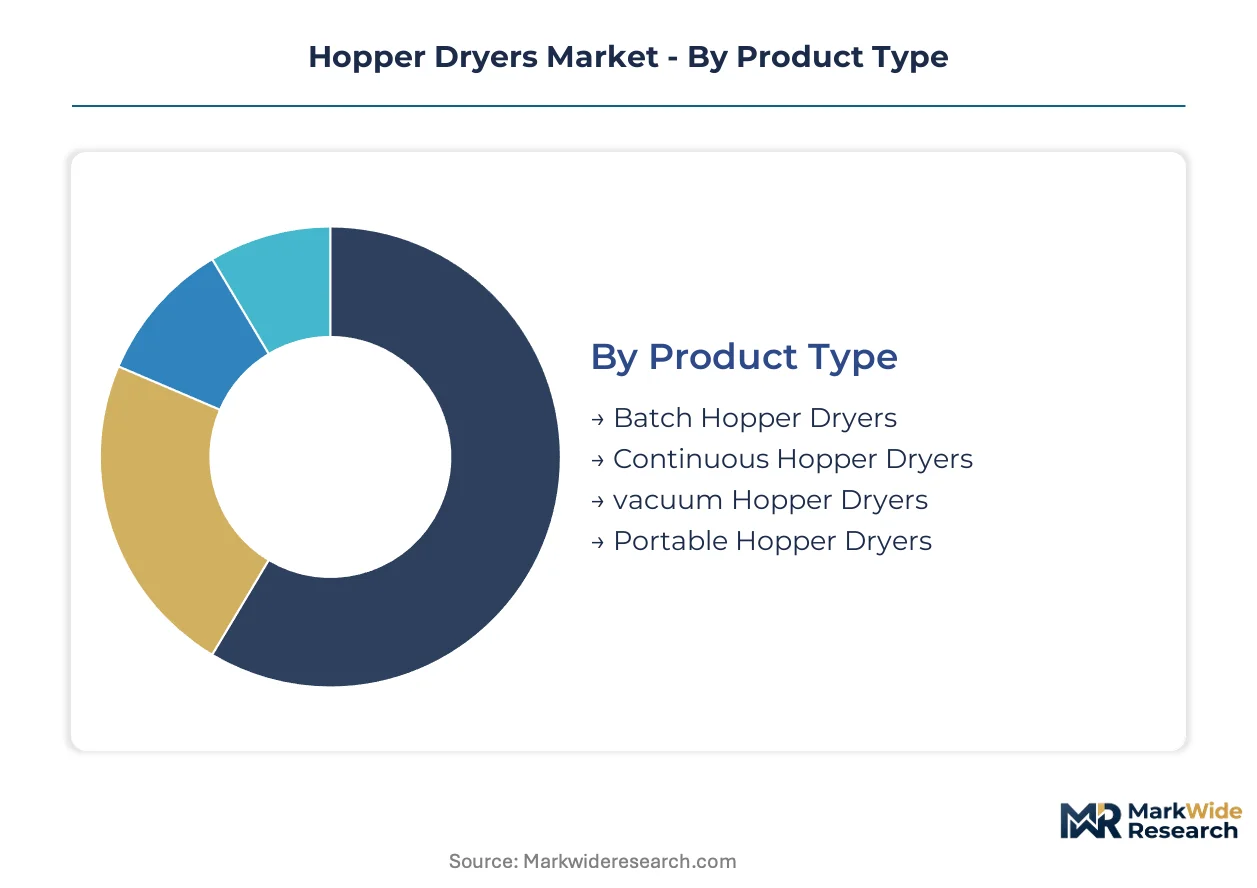
Segmentation in hopper dryers reflects divergent compliance burdens and energy economics across processing industries. Equipment specification varies sharply between F-Gas-regulated European automotive suppliers and FDA-validated pharmaceutical operations, with connectivity architecture now emerging as a procurement differentiator.
Product Type:
EU F-Gas Regulation enforcement and OSHA ventilation standards create divergent equipment replacement timelines across batch, continuous, and vacuum configurations.
- Continuous Hopper Dryers:These systems maintain uninterrupted material flow through heated air streams or desiccant beds, achieving sustained throughput rates for high-volume polyolefin processing. Demand concentrates in Germany's automotive bumper and interior trim molding facilities, where 24/7 production schedules and energy efficiency mandates favor integrated thermal systems over batch alternatives. Tier-1 suppliers specify these units for electric vehicle battery housing production requiring moisture levels below 0.02%.
- Vacuum Hopper Dryers:Sub-atmospheric operation removes moisture at reduced oxygen exposure, protecting oxidation-sensitive hygroscopic polymers from thermal degradation. Pharmaceutical packaging clusters in Ireland and Switzerland prioritize these systems for REACH-compliant medical-grade resin processing, where validated drying documentation satisfies ECHA substance restrictions on residual monomers.
- Batch Hopper Dryers:Intermittent operation suits small-lot custom compounders and specialty polymer processors with frequent material changeovers.
- Portable Hopper Dryers:Mobile configurations serve job-shop molders and contract manufacturers with distributed production footprints across Mexico and Spain.
Continuous hopper dryers handle the majority of throughput; vacuum configurations are climbing the fastest on share in pharmaceutical and medical device applications.
Technology:
Cost tier differentiation separates mature hot-air installations from premium heat pump and infrared systems commanding 40-60% energy reduction claims.
- Heat Pump:Refrigerant-based dehumidification achieves coefficient of performance above 4.0, slashing specific energy consumption versus conventional thermal systems. Germany's automotive processing hubs lead retrofit adoption as EU F-Gas quotas tighten R-134a and R-410A availability for legacy equipment, compressing replacement cycles ahead of 2027 service fill bans.
- Hot Air:Convection heating through direct-fired or electric resistance elements dominates installed base in regions with historically low electricity tariffs, though rising energy costs erode total cost of ownership advantages.
- Infrared:Short-wave radiation enables rapid surface moisture removal with precise zone control, integrating with near-infrared detection for closed-loop moisture management in engineering polymer applications.
- Microwave:Dielectric heating penetrates material bulk for uniform moisture reduction, finding niche application in specialty compounding where conventional surface drying proves insufficient.
Hot air retains the largest installed base; heat pump configurations are expanding most quickly as F-Gas compliance deadlines accelerate capital deployment.
End User:
Application-specific moisture tolerances and validation requirements segment procurement behavior across processing industries.
- Plastics Manufacturing:Injection molding and extrusion operations constitute the dominant demand source, with automotive lightweighting mandates and electric vehicle polymer specifications driving precision drying requirements. German Tier-1 suppliers and US Midwest bumper molders specify heat pump systems for energy reduction and dew point consistency.
- Pharmaceutical:FDA and EMA validation protocols for medical device packaging demand documented moisture control with full batch traceability, expanding equipment procurement in Irish and Swiss manufacturing clusters.
- Food Processing:Hygienic design requirements and USDA moisture standards for ingredient drying create specialized equipment demand distinct from industrial polymer applications.
- Textile:Fiber and filament drying operations in Asian manufacturing zones favor compact, high-throughput configurations suited to synthetic polymer feedstock preparation.
Plastics manufacturing commands the dominant equipment volume; pharmaceutical applications are gaining share fastest on regulatory compliance intensity.
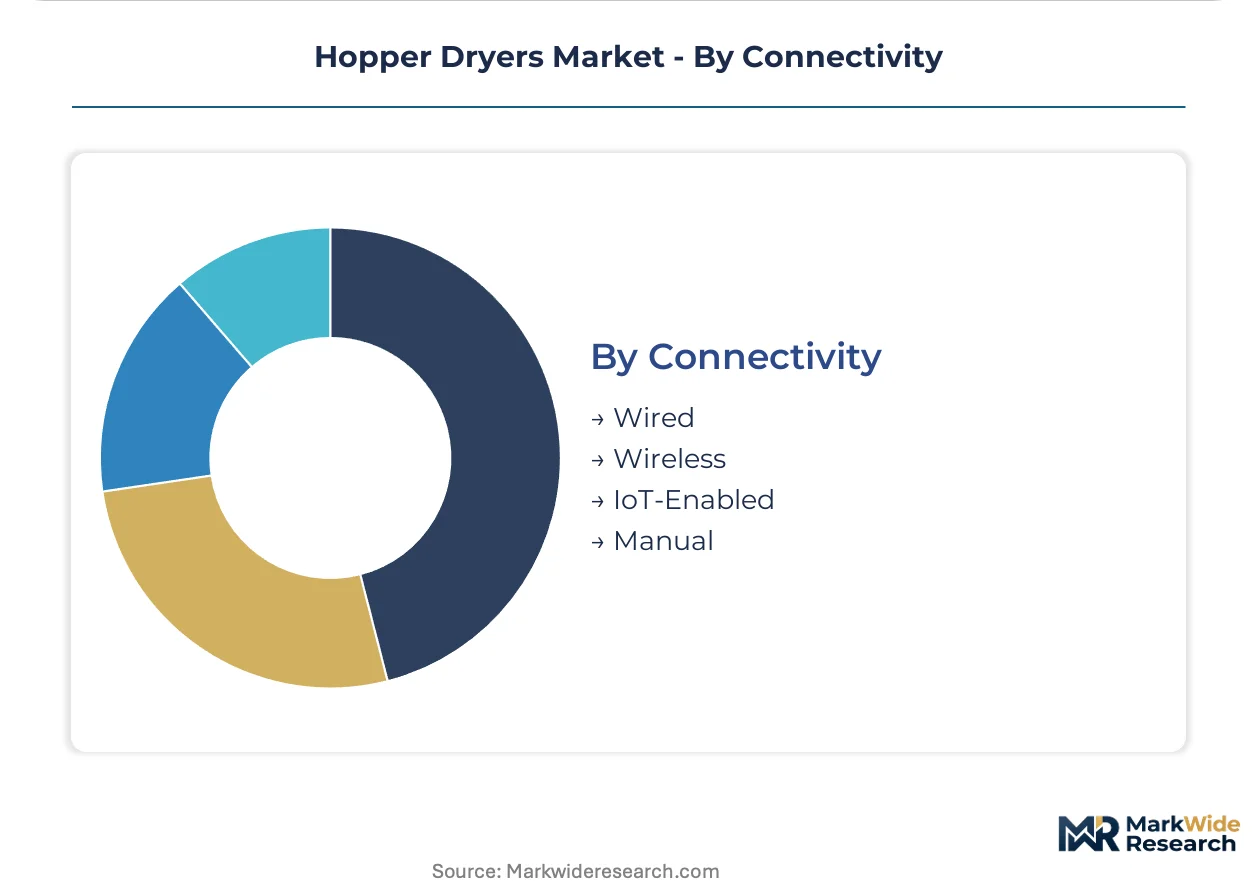
Connectivity:
Customer type and facility maturity determine digital architecture adoption, with brownfield integration costs fragmenting upgrade decisions.
- IoT-Enabled:Cloud-connected sensors and predictive maintenance algorithms reduce unplanned downtime for high-utilization automotive suppliers. Real-time moisture monitoring and automated setpoint adjustment appeal to processors seeking ISO 50001 energy management certification, though legacy SCADA protocol bridges impose integration costs at 1990s-era injection molding facilities.
- Wired:Hardwired control systems dominate existing installations, with RS-485 and Ethernet/IP protocols providing reliable data transmission without wireless infrastructure vulnerabilities.
- Wireless:Wi-Fi and proprietary radio implementations reduce cabling costs in greenfield Central European facilities and portable equipment deployments.
- Manual:Basic operator-controlled interfaces persist in low-volume job shops and developing market installations where digital infrastructure investment remains constrained.
Wired connectivity handles the majority of installed base; IoT-enabled architectures are expanding most quickly among Tier-1 automotive suppliers with integrated smart factory initiatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment trade flows in hopper dryers tilt toward net-importing industrial clusters with dense automotive and pharmaceutical processing footprints. Germany, the United States, and China absorb the dominant import volumes, while Italy and Japan maintain selective export specialization in precision thermal systems.
Germany
Automotive Tier-1 suppliers in Bavaria and Baden-Württemberg drive specification-grade procurement for electric vehicle battery housings. EU F-Gas Regulation phaseout deadlines compress replacement cycles for conventional refrigerant-based systems. Stuttgart and Munich processing clusters lead retrofit adoption of heat pump configurations ahead of 2027 service fill bans.
United States
OSHA ventilation standards and EPA National Emission Standards for Hazardous Air Pollutants shape equipment specifications across Midwest bumper molding facilities. Automotive lightweighting mandates from Detroit OEMs push moisture specifications below 0.02% for engineering-grade polymers. Michigan and Ohio injection molding corridors concentrate demand for continuous high-throughput configurations.
China
Dual carbon goals and provincial energy efficiency targets accelerate displacement of conventional hot-air systems in Yangtze River Delta processing hubs. MIIT industrial upgrading programs subsidize heat pump dryer adoption at compounding plants. Suzhou and Ningbo electronics molding clusters favor compact, high-throughput designs for synthetic polymer feedstock preparation.
Italy
REACH compliance enforcement at pharmaceutical packaging facilities in Lombardy and Emilia-Romagna expands validated drying documentation requirements. ECHA substance restrictions on residual monomers mandate equipment procurement with full batch traceability. Bologna and Milan medical device manufacturing zones prioritize vacuum configurations for oxidation-sensitive hygroscopic polymers.
Japan
METI energy conservation standards and JIS certification requirements govern thermal processing machinery specifications for precision electronics molding. Compact, energy-efficient designs dominate procurement in Kansai and Chubu regional clusters. Osaka and Nagoya automotive supply chain density sustains premium equipment procurement for engineering polymer applications.
Hopper Dryers Market Competitive Environment
Concentration sits with integrated thermal-system vendors possessing captive injection molding ecosystems and distributed service networks. The vendor base organizes into three strategic archetypes: diversified plastics processing equipment conglomerates, specialized drying technology pure-plays, and regional component assemblers. Competitive moves center on bundling dryer units with processing lines and unbundling service contracts into drying-as-a-service offerings.
Within the diversified equipment tier, Wittmann Battenfeld and Conair exemplify integrated positioning through processing line bundling and geographic coverage expansion. Matsui Mfg. Co., Ltd. occupies a specialist position with compact design orientation toward Asian electronics molding clusters. These three anchors illustrate the archetype divergence between captive ecosystem leverage and regional specialization.
| Leading Market Players |
|---|
| Shini Plastics Technologies |
| Conair |
| Wittmann Battenfeld |
| Motan Colortronic |
| Novatec |
| Matsui Mfg. Co., Ltd. |
| Piovan |
| Dri-Air Industries |
| Bry-Air |
| Others |
Value Chain & Pricing Dynamics
CE marking requirements for thermal processing machinery gate both vendor qualification and price tiering simultaneously, compressing margins for assemblers without established certification portfolios while enabling premium positioning for incumbents with notified body relationships. Buyers face trade-offs between retrofit compatibility and total cost of ownership as refrigerant compliance deadlines reshape procurement timelines.
Pricing Analysis
The customization-premium spread separates configured-to-order heat pump systems from standard hot-air configurations, with pricing stratifying across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Price differentiation hinges on CE marking complexity and IoT connectivity architecture, with Tier-1 automotive suppliers showing lowest price sensitivity due to energy efficiency mandates. Cost compression in standard hot-air tiers is intensifying because copper and aluminum price volatility squeezes heat exchanger fabrication margins.
Supply Chain Analysis
Germany and Italy anchor precision thermal system fabrication, with Taiwan and South Korea supplying control electronics and sensor arrays. Heat pump compressors and desiccant wheel substrates draw from Japanese and German component specialists, while aluminum extrusions and copper tubing feed from Chinese and Southeast Asian metal processors. Single-source vulnerability concentrates in refrigerant supply chains where EU F-Gas quotas constrain R-134a and R-410A availability. Distribution runs through OEM captive networks and specialized industrial equipment distributors serving plastics processing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The shortage of process engineers capable of modeling coupled heat and mass transfer in multi-zone drying simulations is constraining custom system commissioning timelines and fragmenting vendor delivery performance. This capability gap advantages incumbents with established simulation teams while delaying new entrant market entry.
For Market Incumbents: Fortify service contract unbundling capabilities to capture drying-as-a-service revenue from Tier-2 automotive suppliers in Spain and Mexico, while deepening backward integration into heat pump compressor sourcing to offset refrigerant supply concentration risks. Expand CE marking certification portfolios ahead of notified body backlogs to compress market entry timelines for novel heat pump architectures. For New Entrants and Emerging Players: CE marking fast-track partnerships with established notified bodies in Germany and Italy enable accelerated market access for compact vacuum dryer configurations targeting pharmaceutical packaging clusters in Ireland and Switzerland. White-space concentration appears in Central European greenfield automotive processing facilities in Poland and the Czech Republic where legacy infrastructure constraints are absent. Lead with infrared drying convergence offerings integrating near-infrared moisture detection for closed-loop control in engineering polymer applications. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across heat pump technology segments as refrigerant-phaseout mandates compress replacement cycles ahead of technical end-of-life. Long-term viability favors vendors with captive injection molding ecosystems and distributed service networks capable of bundling dryer units with processing lines. Acquisition target archetypes include specialized drying technology pure-plays with validated pharmaceutical documentation capabilities and regional component assemblers in Central European manufacturing zones. Monitor EU Green Deal industrial decarbonization funding disbursement rates as inflection indicator for heat pump dryer capex acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Pump Technology Migration | EU F-Gas Regulation phaseout deadlines compress replacement cycles for conventional refrigerant-based systems. |
| Service Contract Unbundling | Tier-2 automotive suppliers in Spain and Mexico favor opex-over-capex financing structures for drying equipment. |
| Infrared Drying Convergence | Near-infrared moisture detection integration enables real-time closed-loop control in engineering polymer applications. |
| Central European Geographic Expansion | Automotive supply chain relocation into Poland and Czech Republic creates greenfield equipment demand without legacy constraints. |
| CE Marking Certification Investment | Notified body backlogs for thermal processing machinery safety assessments extend market entry timelines for novel architectures. |
Study Parameters
Desk research of trade association publications, customs and trade flow databases, and regulatory filing repositories preceded structured interviews with plant engineers at Tier-1 automotive suppliers, procurement leads at pharmaceutical packaging facilities, aftermarket service heads at industrial equipment distributors, and technical R&D directors at thermal system manufacturers. Primary intelligence combined with secondary validation from SEC filings, EU ECHA substance restriction databases, and MIIT industrial upgrading program disclosures. Bottom-up equipment shipment tracking and top-down end-use demand modeling provided triangulation across analysis approaches.
Variance decomposition across product type, technology configuration, end-use industry, and connectivity architecture segments informed projection construction over the analysis window. CAGRs derived from segment-level growth rate reconciliation against macroeconomic drivers including automotive production forecasts and plastics processing capacity expansion plans. Industry-specific inputs incorporated EU F-Gas Regulation phaseout timelines, REACH compliance enforcement intensity, and heat pump coefficient of performance improvement trajectories.
Underlying assumptions cover refrigerant availability constraints, metals price volatility ranges, and notified body certification timeline norms, with deviation risk concentrated in regulatory enforcement intensity variations and brownfield SCADA integration complexity at legacy facilities. Recalibration cycles align with material shifts in EU Green Deal funding disbursement patterns and automotive OEM lightweighting specification releases.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Latin America Fire Sprinklers Market
Others
Receiving Scales Market
Others
Flexible PVC Films and Sheets Market
Others
Qatar Smartphone Market
Others
UK Automotive LED Lighting Market
Others
Short Video Applications Market
Others
Caster Wheels Market
Others
Semiconductor Gas Filters Market
Others
Mainframe Computers Market
Others
Cat Dry Food Market
Others
Refractometer Market
Others
US Quantum Computing Market
Others
Legal Services Market
Others
Middle East 3D Printing Construction Market
Others
Europe Medical Simulation Market
Others
Super Computer Market