
 Turkey Health and Medical Insurance Market | 2026-2036
Turkey Health and Medical Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Turkey Health and Medical Insurance Market Analytics
Multi-source distribution is repositioning how Turkish insurers reach policyholders. Allianz Sigorta A.Ş. leverages bancassurance partnerships to extend rural penetration. Türkiye Sigorta A.Ş. anchors its portfolio through state-backed credibility and public-sector employee schemes. AXA Sigorta A.Ş. competes via digital direct-to-consumer platforms that reduce intermediary costs.
Turkey health and medical insurance constitutes risk-pooling financial instruments covering hospitalization, outpatient treatment, and preventive care against premium payments, with actuarial reserves maintained per Turkish Commercial Code provisions. The primary purpose involves reducing catastrophic health expenditure exposure for individuals and employer groups while enabling private healthcare provider access. Group policies dominate premium volume through employer-sponsored enrollment, while individual comprehensive coverage extracts higher margins from affluent urban households. Dental riders remain underpenetrated relative to European benchmarks, suggesting latent expansion potential.
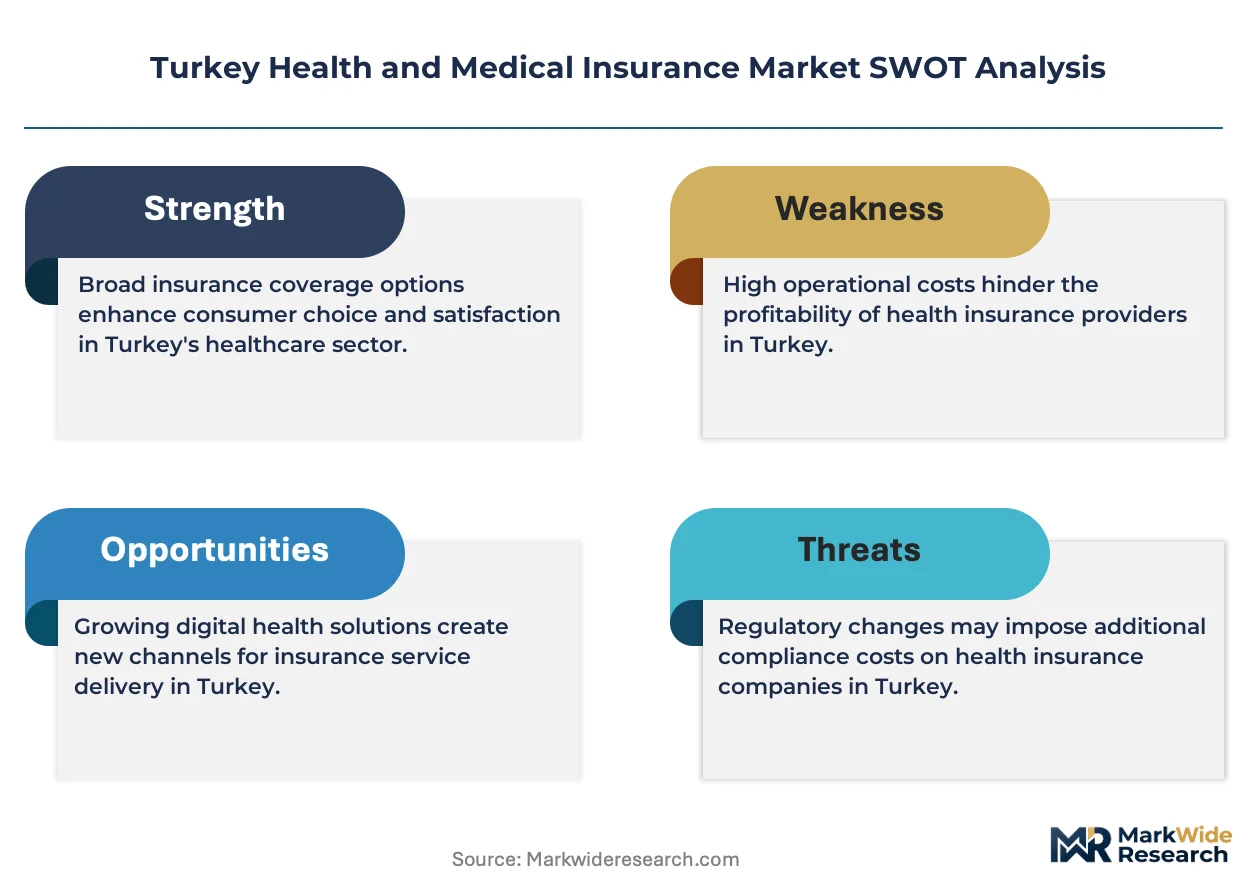
Turkish insurance regulation falls under the Banking Regulation and Supervision Agency and the Turkish Statistical Institute reporting frameworks, with compulsory medical malpractice reserves and solvency ratios dictating capital allocation. The Social Security Institution coordinates public-private interface rules that determine supplementary reimbursement eligibility. Stakeholders must monitor potential shifts in mandatory private health insurance obligations for foreign residents and evolving digital policy issuance standards.
Market Dynamics
The Social Security Institution's universal coverage mandate creates a dual-track structure where private insurers compete for supplementary gaps rather than primary coverage, compressing pricing power while expanding addressable volume through employer-sponsored group schemes.
Growth Catalysts
- Employer mandate expansion:Mid-sized enterprises across Anatolia face rising workforce retention pressure, accelerating group policy adoption as a standard compensation component.
- Telemedicine infrastructure:Remote diagnostic platforms are automating pre-authorization workflows, reducing claims processing friction and expanding rural subscriber bases beyond traditional branch networks.
- Banking Regulation and Supervision Agency digital guidelines:Streamlined e-policy issuance frameworks lower distribution costs for direct-to-consumer channels, enabling mobile-first penetration among urban millennials.
Market Restraints
- Actuarial reserve requirements:Turkish Commercial Code provisions mandate solvency ratios that tie up capital in low-yield instruments, constraining product innovation budgets.
- SGK reimbursement ceilings:Public sector price caps on supplementary coverage create margin compression for comprehensive policies, particularly in high-cost tertiary care segments.
- Medical inflation divergence:Healthcare provider fee escalations outstrip premium adjustment cycles in Istanbul and Ankara, eroding loss ratios for inpatient-heavy portfolios.
Strategic Opportunities
- Black Sea and Eastern Anatolia provinces:Penetration rates in Trabzon, Samsun, and Erzurum lag western benchmarks by substantial margins, offering first-mover consolidation potential for regional bancassurance partnerships.
- Dental and vision riders:Ancillary coverage modules remain underdeveloped relative to European standards, presenting attach-rate expansion opportunities within existing group contracts.
- Preventive care integration:Wellness program tie-ins with private hospital networks differentiate offerings beyond claims reimbursement, locking in employer loyalty through measurable health outcomes.
Industry Challenges
- Actuarial talent scarcity:Specialized health underwriters with SGK interface expertise concentrate in Istanbul, forcing regional insurers to outsource core pricing functions.
- Legacy IT migration:Core policy administration systems at established carriers require multi-year modernization to support real-time claims adjudication and API-based distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turkey Health and Medical Insurance Market |
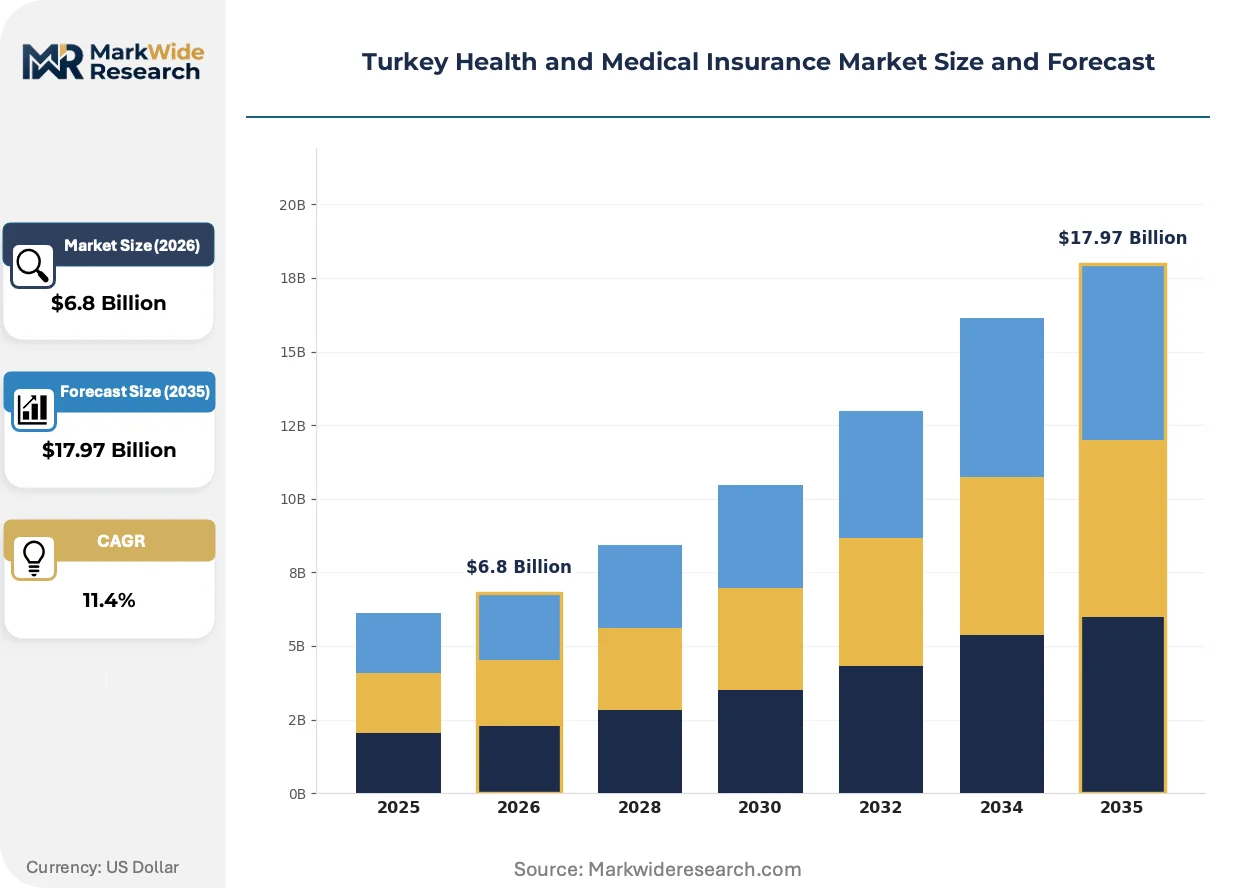
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Individual, Family, Group, Travel Coverage Type: Basic, Comprehensive, Catastrophic, Dental Customer Type: Employees, Self-Employed, Expatriates, Students Payment Mode: Monthly, Annually, Employer-Sponsored, Out-of-Pocket |
| Companies Covered | Anadolu Anonim Türk Sigorta Şirketi, Allianz Sigorta A.Ş., Türkiye Sigorta A.Ş., AXA Sigorta A.Ş., Acıbadem Sigorta, Bupa Acıbadem Sigorta A.Ş., Aksigorta, Güne Sigorta, AvivaSA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turkey Health and Medical Insurance Market Evolving Landscape
Digital distribution architectures and predictive risk modeling are compressing traditional intermediary roles while elevating data analytics as a core competitive capability across Turkish health insurance.
Artificial intelligence underwriting engines are automating risk stratification for individual comprehensive policies, cutting quote-to-bind cycles from days to minutes. InsurTech platforms serving affluent Istanbul households deploy these tools most aggressively. The technology is automating manual medical history reviews that previously required nurse practitioner involvement, reallocating human capital toward complex chronic case management.
The Social Security Institution's evolving public-private interface rules are tightening documentation standards for supplementary reimbursement eligibility. Insurers must now integrate real-time SGK claims verification into policy administration systems. Group policy administrators face the steepest compliance burden as they reconcile employer-sponsored benefits against public coverage gaps.
Subscription-based micro-policies are displacing annual comprehensive contracts among gig economy workers and young professionals in Izmir and Bursa. Digital-native distributors offer modular coverage activated through mobile wallets, unbundling traditional inpatient-outpatient bundles. This behavioral pivot concentrates in technology and creative services verticals where employment relationships lack formal employer sponsorship structures.
Turkey Health and Medical Insurance Market Segmentation
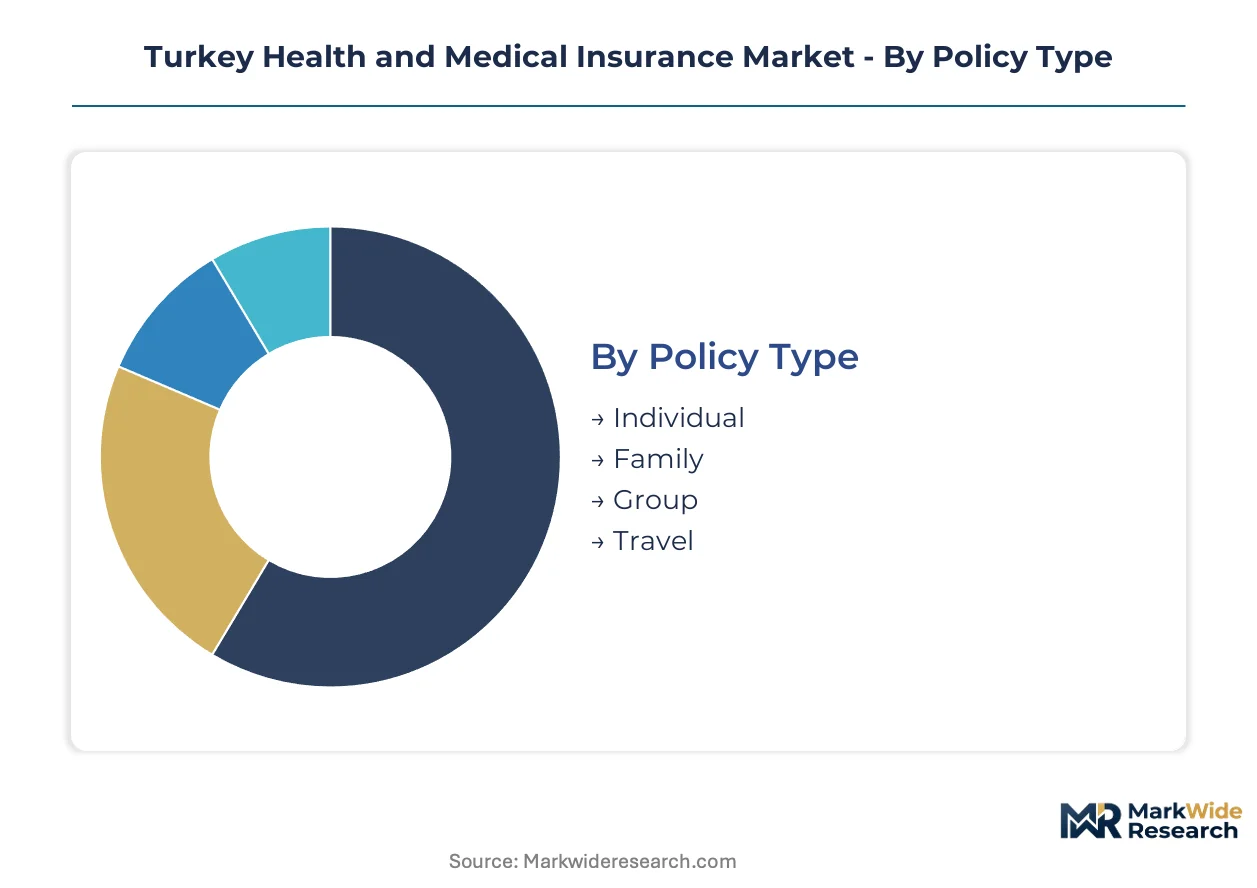
Segmentation in Turkish health insurance reflects the dual-track structure shaped by SGK universal coverage and private supplementary demand. Distinct policy architectures serve employer groups, individual households, and transient populations with varying regulatory compliance burdens.
Policy Type:
Banking Regulation and Supervision Agency licensing requirements vary by policy structure, with group schemes facing streamlined capital reserves compared to individual comprehensive products.
- Individual:Tailored coverage for single policyholders with full medical underwriting and portable benefits across employment changes. Istanbul and Ankara households drive demand for premium outpatient networks and direct specialist access beyond SGK referral constraints.
- Family:Multi-life contracts covering spouses and dependents under unified premium structures with dependent age caps. Mid-sized enterprises in Bursa and Izmir favor family riders as retention tools for senior technical staff with household coverage expectations.
- Group:Employer-sponsored risk-pooling with simplified underwriting and guaranteed issue provisions. Anatolian manufacturing clusters adopt these schemes fastest as competition for skilled labor intensifies.
- Travel:Short-duration coverage for international visitors and outbound Turkish nationals requiring emergency medical evacuation. Antalya and Bodrum hospitality corridors generate concentrated demand tied to seasonal tourism flows.
Group policies sit at the top of the volume ranking, with individual comprehensive climbing the fastest.
Coverage Type:
Premium differentiation across coverage tiers correlates directly with reimbursement ceilings and provider network breadth rather than actuarial risk alone.
- Basic:Inpatient hospitalization with limited outpatient allowances and SGK-aligned provider networks. Lower premiums attract price-sensitive subscribers in Eastern Anatolia where supplementary coverage penetration lags western benchmarks substantially.
- Comprehensive:Full inpatient-outpatient coverage with private hospital access and zero or low deductibles. Istanbul's affluent professional services sector sustains margins despite SGK reimbursement compression on high-cost tertiary procedures.
- Catastrophic:High-deductible designs covering severe illness and extended hospitalization with annual benefit limits. Younger demographics in technology sectors favor these products as income-protection instruments against ruinous health expenditure.
- Dental:Standalone or rider coverage for preventive, restorative, and orthodontic treatment. European comparison standards reveal substantial underpenetration, positioning dental as the steepest expansion trajectory among coverage modules.
Comprehensive coverage commands premium revenue leadership, while catastrophic designs gain share fastest among under-35 subscribers.
Customer Type:
Eligibility documentation requirements diverge sharply across customer categories, with expatriates facing mandatory private coverage obligations distinct from citizen enrollment pathways.
- Employees:Formal sector workers accessing employer-sponsored group benefits with automatic payroll deduction. Ankara public-sector employees represent a captive base for Türkiye Sigorta through state-backed enrollment schemes.
- Self-Employed:Independent professionals and small business owners purchasing individual policies without risk-pooling advantages. Tradespeople in Black Sea coastal provinces show rising uptake as SGK gaps in private provider access become salient.
- Expatriates:Foreign residents subject to compulsory private health insurance for residence permit renewal. Istanbul's international corporate assignees demand English-language policy administration and direct billing with private hospital networks.
- Students:University enrollees accessing institutional group schemes or individual travel-style products. Erasmus exchange participants and medical faculty candidates drive seasonal enrollment spikes.
Employees constitute the volume anchor, with expatriate segments expanding most quickly under tightening residence permit regulations.
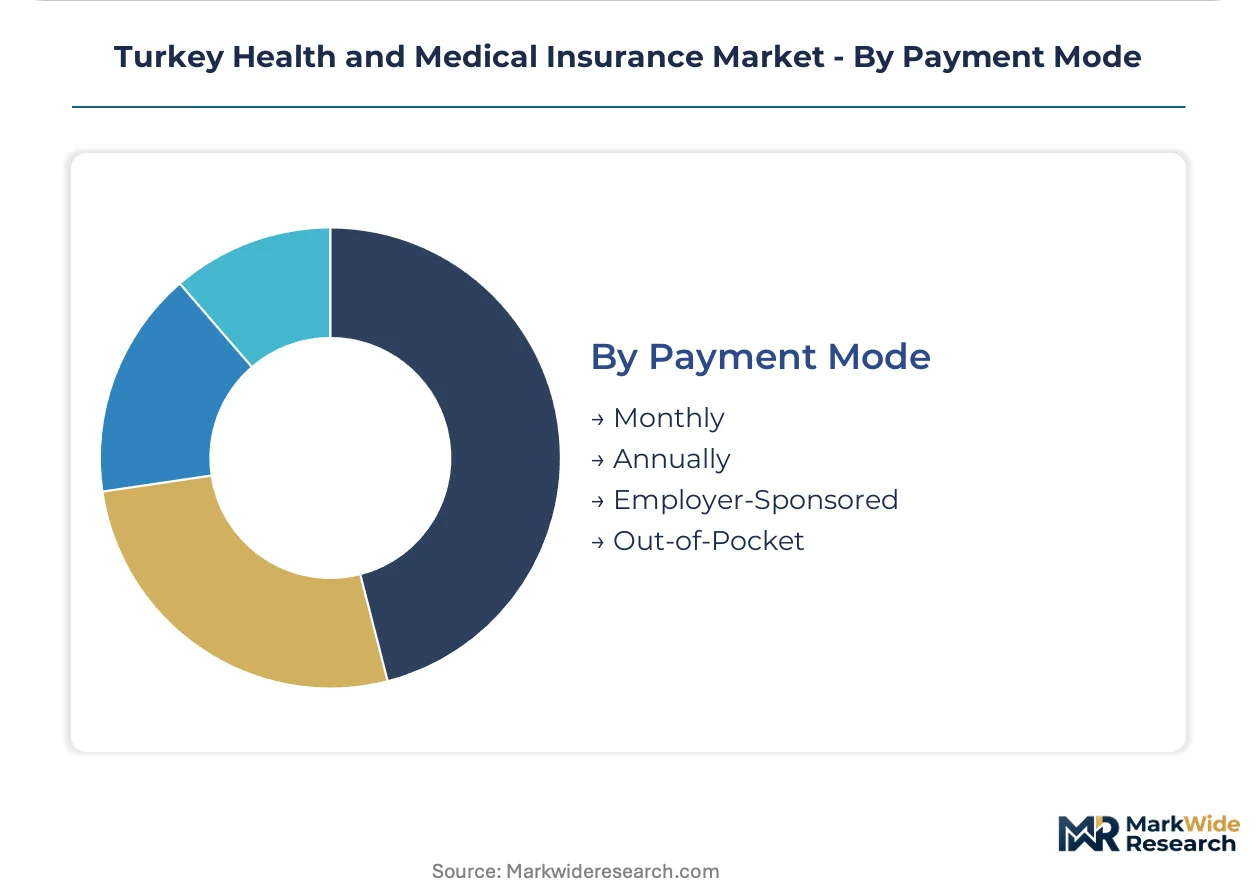
Payment Mode:
Capital allocation and liquidity management at carriers vary significantly by payment structure, with annual prepayment improving loss ratio predictability against monthly collection costs.
- Monthly:Recurring premium collection through automated bank transfers or mobile payment platforms. Urban millennials in Izmir prefer this structure for budget alignment despite higher administrative overhead.
- Annually:Single upfront payment with modest discount incentives and reduced lapse risk. Individual comprehensive subscribers favor this mode for tax documentation simplicity.
- Employer-Sponsored:Corporate bulk payment with employee cost-sharing ratios varying by sector. Mid-sized Anatolian enterprises increasingly standardize full employer contribution as competitive necessity.
- Out-of-Pocket:Direct subscriber payment without intermediation, concentrated in informal economy workers and transitional coverage gaps. Digital wallet integration is displacing cash collection in this segment.
Employer-sponsored payment dominates premium volume, with monthly billing gaining traction fastest among platform economy workers lacking formal employment structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Istanbul anchors policyholder density and insurer headquarters concentration, with Ankara and Izmir forming secondary metropolitan clusters where employer-sponsored enrollment accelerates fastest.
Marmara Region
Corporate headquarters and private hospital networks concentrate in Istanbul, driving premium comprehensive coverage uptake among professional services firms. The Banking Regulation and Supervision Agency's digital guidelines streamline e-policy issuance for mobile-first distribution. Bursa's manufacturing base expands group policy adoption as workforce retention pressures mount.
Central Anatolia Region
Ankara's public-sector employee schemes sustain Türkiye Sigorta's captive enrollment base through state-backed credibility. The Social Security Institution coordinates supplementary reimbursement eligibility rules that shape private insurer product design. Konya's agribusiness clusters show rising individual policy uptake among self-employed tradespeople.
Aegean Region
Izmir's technology and creative services verticals favor subscription-based micro-policies over traditional annual contracts. Digital-native distributors target gig economy workers through mobile wallet activation. The city's port logistics sector drives employer-sponsored group scheme standardization.
Black Sea Region
Trabzon and Samsun lag western penetration benchmarks substantially, presenting first-mover consolidation potential for regional bancassurance partnerships. SGK-aligned provider networks dominate basic coverage tiers. Samsun's shipping and logistics corridors generate concentrated travel policy demand.
Eastern Anatolia Region
Erzurum's underpenetrated market offers expansion terrain for telemedicine-enabled distribution beyond traditional branch networks. Price-sensitive subscribers favor basic inpatient coverage with limited outpatient allowances. The region's university medical faculties attract student policy enrollment spikes.
Turkey Health and Medical Insurance Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital direct-to-consumer channels and modular micro-policy formats. The market exhibits tiered concentration with state-backed credibility anchoring public-sector schemes, bancassurance partnerships extending rural reach, and InsurTech platforms compressing intermediary roles. Three archetypes dominate: legacy carriers with branch infrastructure, digital-native distributors, and hybrid insurers blending state affiliation with private innovation. Competitive moves center on M&A consolidation in underpenetrated provinces and API-based distribution partnerships with banking networks.
Among Turkey-based carriers, Anadolu Anonim Türk Sigorta Şirketi and Allianz Sigorta A.Ş. exemplify the established tier with diversified distribution architectures, while AXA Sigorta A.Ş. occupies a position within the digital-first vector emphasizing direct-to-consumer platforms. Türkiye Sigorta A.Ş. anchors the state-affiliated segment through public-sector employee scheme dominance.
| Leading Market Players |
|---|
| Anadolu Anonim Türk Sigorta Şirketi |
| Allianz Sigorta A.Ş. |
| Türkiye Sigorta A.Ş. |
| AXA Sigorta A.Ş. |
| Acıbadem Sigorta |
| Bupa Acıbadem Sigorta A.Ş. |
| Aksigorta |
| Güne Sigorta |
| AvivaSA |
| Others |
Value Network & Pricing Analysis
Family-owned regional insurers across Eastern Anatolia and the Black Sea provinces anchor supply-side concentration, channeling capital toward telemedicine-enabled distribution rather than branch infrastructure while compressing premium pricing for basic inpatient tiers to defend market share against Istanbul-based national carriers.
Pricing Analysis
Medical inflation pass-through from private hospital networks in Istanbul and Ankara drives premium adjustment cycles for comprehensive coverage tiers. Pricing stratifies across premium comprehensive, standard group, and economy basic tiers based on SGK reimbursement alignment and provider network breadth. Cost compression in economy segments is intensifying because SGK price caps limit supplementary coverage margins. Price-sensitive subscribers in Eastern Anatolia favor basic inpatient-only designs, while affluent Istanbul households absorb premium comprehensive premiums with minimal elasticity.
Supply Chain Analysis
Turkish Commercial Code solvency requirements and domestic-content mandates for actuarial reserve instruments reshape capital sourcing toward lira-denominated instruments. Supply concentration centers on Istanbul for specialized health underwriters, Ankara for public-sector scheme administrators, and Izmir for digital-native distribution platforms. Raw material dependencies include medical cost data feeds, claims adjudication software licenses, and telemedicine platform APIs. Single-source vulnerability concentrates in SGK real-time claims verification systems. Distribution runs through bancassurance partnerships, employer-sponsored payroll deduction, and direct-to-consumer mobile platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Turkey's health insurance market reads as a geographic-arbitrage play where SGK reimbursement ceilings in Ankara and Istanbul create margin compression that regional carriers in Trabzon and Erzurum escape through lower medical cost baselines and reduced competitive intensity.
For Market Incumbents: Lock in employer-sponsored group schemes across Anatolian manufacturing clusters before mid-sized enterprises consolidate vendor relationships. Defend against InsurTech entrants by accelerating legacy IT migration toward API-based policy administration. Prioritize certification investment in SGK interface compliance to maintain reimbursement eligibility as documentation standards tighten. For New Entrants and Emerging Players: Banking Regulation and Supervision Agency digital guidelines in Turkey open a window for modular micro-policy formats targeting gig economy workers in Izmir and Bursa. White-space targets include subscription-based dental riders and telemedicine-first catastrophic coverage for technology sector employees. Go-to-market through mobile wallet integration bypasses established branch networks entirely. For Investors and Strategic Acquirers: Valuations sit cheapest among regional carriers with Eastern Anatolia and Black Sea footprints but underdeveloped digital infrastructure. Long-term viability over a 5-10 year window hinges on successful telemedicine distribution deployment and bancassurance partnership density. Watch SGK mandatory private health insurance obligations for foreign residents as the inflection signal for expatriate segment expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Telemedicine Platform Integration | Automates pre-authorization workflows for rural subscribers beyond branch networks. |
| Bancassurance Partnership Expansion | Extends penetration into underpenetrated Black Sea provinces through banking channels. |
| SGK Interface Compliance Investment | Secures supplementary reimbursement eligibility as documentation standards tighten. |
| Modular Micro-Policy Launch | Captures gig economy workers in Izmir through mobile wallet activation. |
| Dental Rider Development | Addresses European underpenetration gap within existing group contracts. |
Research Methodology
Direct dialogue with health insurance product managers, SGK liaison officers, private hospital network contracting directors, and employer benefits administrators grounded qualitative insights. Secondary validation drew from Banking Regulation and Supervision Agency licensing disclosures, Turkish Statistical Institute insurance sector reports, Social Security Institution reimbursement bulletins, and Turkish Commercial Code regulatory filings. Bottom-up policy volume modeling and top-down premium value estimation were triangulated against carrier financial disclosures.
Top-down macroeconomic projections anchored the analytical framework across the analysis window, with bottom-up segmentation by policy type, coverage tier, customer category, and payment mode. CAGRs were derived from trend extrapolation of employer mandate expansion rates, telemedicine adoption curves, and medical inflation differentials between Istanbul-Ankara and regional provinces. Modeled inputs included SGK reimbursement ceiling trajectories and digital policy issuance volume growth.
Revisions become necessary when SGK public-private interface rules shift materially, mandatory private health insurance obligations for foreign residents change, or Banking Regulation and Supervision Agency solvency requirements are amended. Forecasts reflect documented assumptions about medical cost escalation and employer sponsorship penetration rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Spain Feed Additives Market
Others
Griffin Beaker Market
Others
Printing Machines Market
Others
Hybrid System Market
Others
Europe Astrology Market
Others
Retail Digital Signage Market
Others
Middle East and Africa Surface Analysis Market
Others
United States Printed Signage Market
Others
Augmented Reality in Energy and Utilities Market
Others
Ceramic Machinery Market
Others
Infant Fever Stickers Market
Others
Europe Tablet PC Market
Others
Thermoformed Plastics Market
Others
Global Maritime Freight Transport Market
Others
Silicone Molding Machinery Market
Others
Global Snow Sports Apparel Market