
 US Cat Food Market | 2026-2036
US Cat Food Market Size, Share, and Industry Trends Forecast 2026-2036
US Cat Food Market Insights
FDA pet food safety standards are hardening the cost-of-entry calculus for new entrants. Mars Incorporated leverages its integrated supply chain to sustain cost advantages across wet and dry formats. Nestlé Purina PetCare Co anchors its position through R&D intensity in therapeutic nutrition formulations. Hill's Pet Nutrition Inc. differentiates via veterinary channel control and prescription diet specialization.
Cat food encompasses nutritionally complete and complementary formulations manufactured through extrusion, canning, or raw processing to meet feline obligate carnivore requirements for protein, taurine, and arachidonic acid. Wet food leads value generation due to higher moisture content aligning with feline hydration needs, while grain-free dry formats compete on convenience and shelf stability. Raw food occupies a premium niche with margin pools concentrated in direct-to-consumer channels. Supermarkets and pet specialty stores remain the dominant distribution infrastructure, though online retail captures the fastest expansion in subscription-based replenishment.
USDA and FDA jointly oversee ingredient safety and facility sanitation under the Food Safety Modernization Act, while state feed control officials enforce label adequacy claims. The Association of American Feed Control Officials establishes nutrient profiles that shape product development priorities. Stakeholders must monitor evolving state-level raw food restrictions and shifting consumer litigation around grain-free diet safety claims.
Market Dynamics
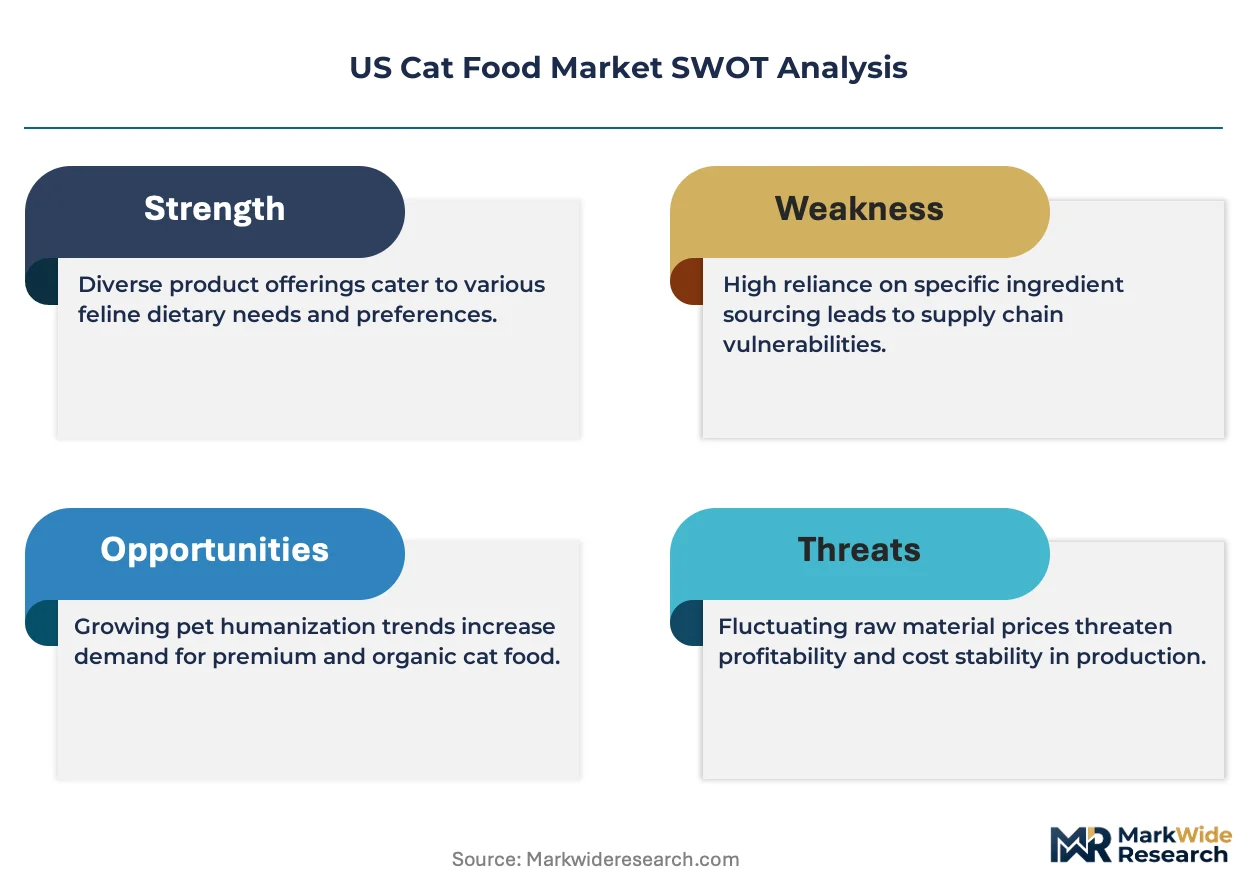
The FDA's Food Safety Modernization Act enforcement is compressing ingredient sourcing timelines and elevating compliance costs, forcing manufacturers to reconfigure supplier relationships and facility certifications.
Growth Catalysts
- Pet Humanization:Urban millennial households in California and the Northeast corridor are trading up to premium wet formulations that mirror human-grade ingredient standards.
- FSMA Implementation:The FDA's preventive controls mandate is professionalizing the supplier base, advantaging scaled manufacturers with in-house laboratory testing capabilities.
- Veterinary Channel Expansion:Prescription diet protocols are anchoring therapeutic nutrition as a recurring revenue stream tied to feline diabetes and renal disease management.
Market Restraints
- Animal Protein Cost Volatility:Chicken and fish meal prices fluctuate with commodity feed markets, compressing margin pools in mid-tier dry food segments.
- Midwest Rendering Concentration:Specialty protein meal supply clusters in Illinois and Nebraska, creating single-source vulnerability for regional processors.
- Raw Food Regulatory Friction:State feed control officials in multiple jurisdictions are imposing pathogen testing burdens that freeze small-batch raw format expansion.
Strategic Opportunities
- Subscription Replenishment:Direct-to-consumer platforms are capturing recurring purchase patterns in urban coastal markets, bypassing traditional retail slotting fees.
- Therapeutic Nutrition:Urinary tract and weight management formulations are expanding the addressable base beyond commodity feeding into clinical intervention.
- Sustainable Packaging Mandates:California's extended producer responsibility frameworks are creating first-mover advantage for recyclable pouch and can formats.
Industry Challenges
- Veterinary Nutritionist Scarcity:Board-certified animal nutritionists command premium salaries, constraining R&D throughput for mid-sized manufacturers.
- Legacy ERP Integration:Lot-tracking requirements under FSMA are forcing costly upgrades to traceability systems in family-owned processing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Cat Food Market |
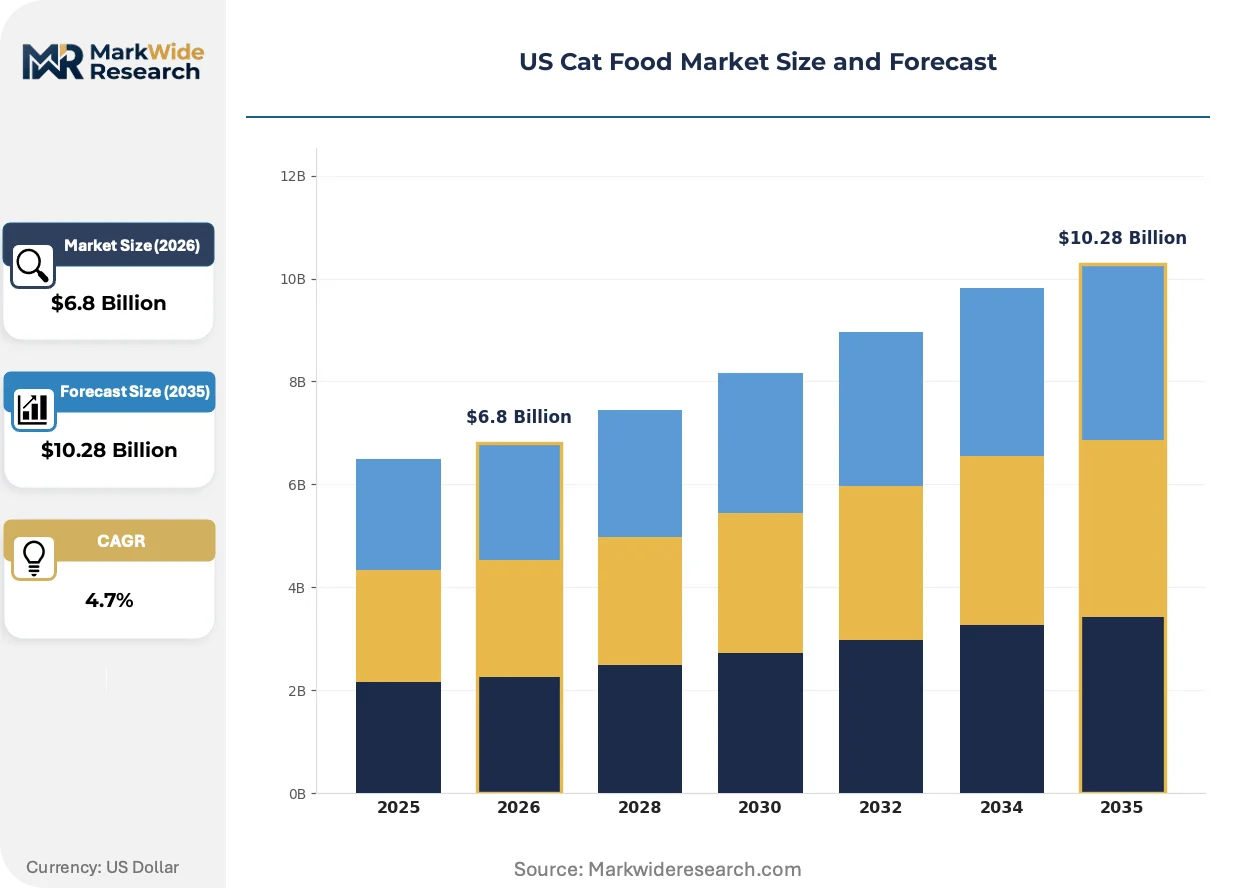
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Raw Food Distribution Channel: Online Retail, Supermarkets, Pet Specialty Stores, Convenience Stores Ingredient Type: Meat-Based, Fish-Based, Grain-Free, Vegetarian Price Tier: Premium, Mid-Range, Budget, Value |
| Companies Covered | Nestlé Purina PetCare Co, Mars Incorporated, Colgate-Palmolive Company, General Mills Inc., The J. M. Smucker Company, Hill's Pet Nutrition Inc., Royal Canin SAS, Blue Buffalo Co Ltd, Diamond Pet Foods, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Cat Food Market Trends and Innovations
Formulation science is diverging along hydration-centric and shelf-stable paths, with processing technology and channel strategy determining competitive positioning rather than brand equity alone.
Cold-pressed raw and gently cooked formats are converging with high-pressure processing (HPP) pathogen reduction systems. Premium urban consumers are adopting these formats at accelerating velocity through veterinary and direct channels. This convergence is compressing the traditional raw food safety liability premium while expanding addressable household penetration.
The FDA's expanded animal food rule under FSMA is mandating hazard analysis and risk-based preventive controls across all registered facilities. Ingredient suppliers now face documented safety verification requirements that extend upstream to foreign sourcing. Wet food canning operations in the Pacific Northwest and Southeast are absorbing the heaviest compliance retrofit costs.
Subscription-based replenishment is displacing episodic retail purchasing among multi-cat households. Chewy and Amazon's subscribe-and-save models are capturing California and Northeast urban demand, while Petco's Vital Care membership anchors in-store pickup integration. This behavioral shift concentrates lifetime value metrics and erodes traditional supermarket impulse purchase economics.
US Cat Food Market Segmentation
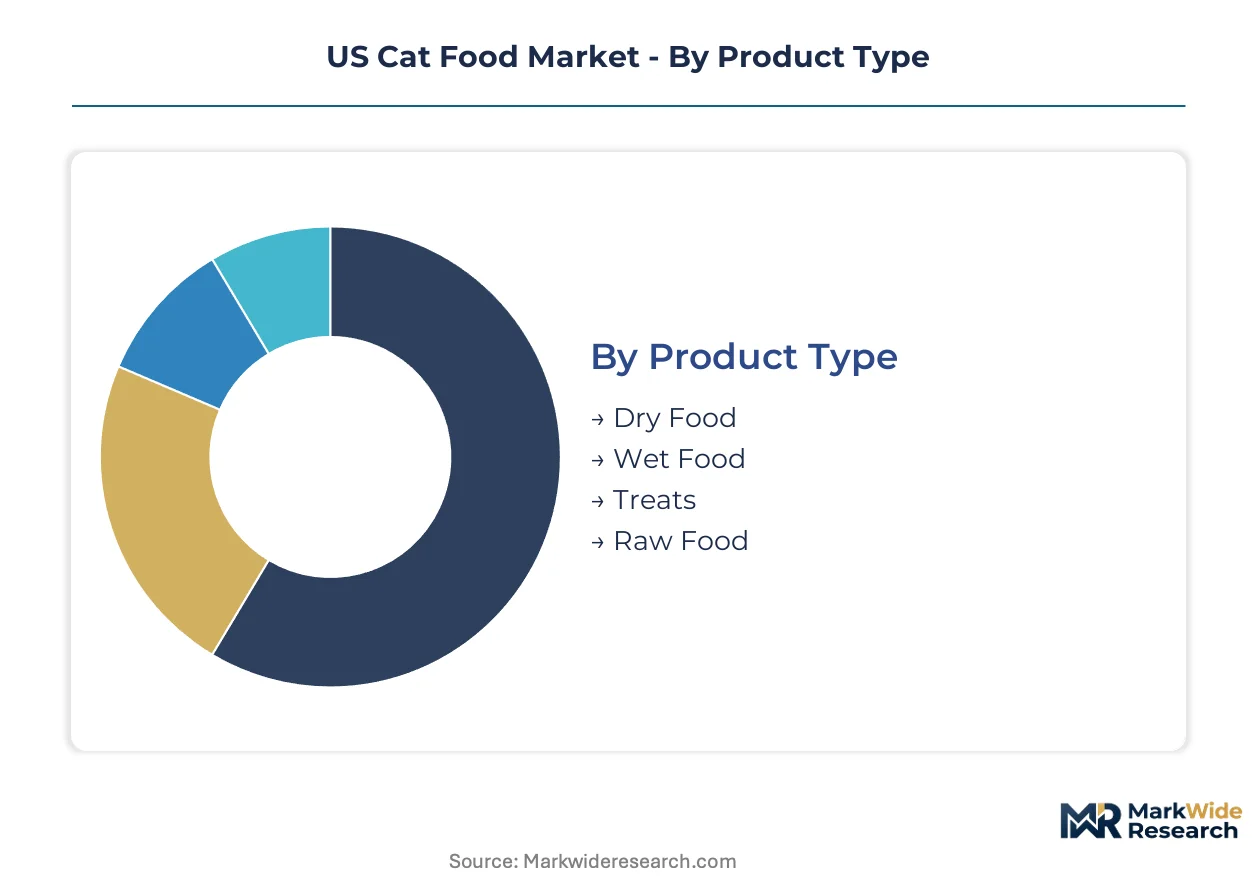
Segmentation in the US cat food market reveals how capital deployment, regulatory exposure, and channel economics fragment competitive strategy. Manufacturers must align production infrastructure with specific segment requirements rather than pursuing horizontal scale.
Product Type:
Wet food and raw formats demand the heaviest upfront investment in canning lines, cold-chain infrastructure, and pathogen control systems.
- Wet Food:High-moisture formulations packaged in cans or pouches require retort processing and aseptic filling equipment. California and Northeast urban households drive demand for human-grade ingredient declarations and single-serve portions.
- Dry Food:Extruded kibble offers extended shelf stability and lower per-unit logistics costs. The Midwest and Sun Belt concentrate volume due to multi-cat household density and price-sensitive purchasing patterns.
- Treats:Functional and dental varieties command impulse purchase placement in pet specialty and grocery checkout.
- Raw Food:Frozen or freeze-dried formats carry elevated cold-chain costs and state-level pathogen testing burdens that constrain small-batch producers.
Wet food absorbs the bulk of installed canning capacity; raw food is expanding most quickly through veterinary and direct-to-consumer channels.
Distribution Channel:
Channel selection determines working capital intensity, with online retail requiring inventory flexibility and supermarkets demanding slotting fee commitments.
- Online Retail:Subscription models capture recurring replenishment in coastal urban markets. Chewy and Amazon's infrastructure anchors fulfillment economics, while DTC native brands bypass traditional retail margin stacking.
- Supermarkets:Mass-market dry food dominates shelf space, with private label penetration highest in price-compressed regions. Slotting fees and promotional calendars strain mid-tier brand economics.
- Pet Specialty Stores:Premium assortment and staff consultation support therapeutic nutrition and novel protein introductions.
- Convenience Stores:Emergency and travel-size formats occupy limited shelf space with high turnover velocity.
Supermarkets absorb the bulk of volume throughput; online retail is climbing the fastest as subscription behavior displaces episodic purchasing.
Ingredient Type:
Protein sourcing geography and certification requirements segment manufacturing cost structures and FDA compliance exposure.
- Meat-Based:Chicken, turkey, and beef formulations anchor complete nutrition profiles. USDA-inspected rendering facilities in Illinois and Nebraska supply protein meals, with price volatility tracking commodity feed markets.
- Fish-Based:Tuna and salmon varieties appeal to palatability preferences but carry mercury exposure litigation risk and sustainable sourcing certification costs.
- Grain-Free:Legume and potato carbohydrate substitutes respond to consumer perception trends despite FDA investigation into dilated cardiomyopathy correlations.
- Vegetarian:Synthetic taurine and arachidonic acid supplementation enables formulation for niche ethical positioning, though veterinary acceptance remains limited.
Meat-based formulations absorb the bulk of procurement volume; grain-free is gaining share fastest as manufacturers reformulate to address safety concerns.
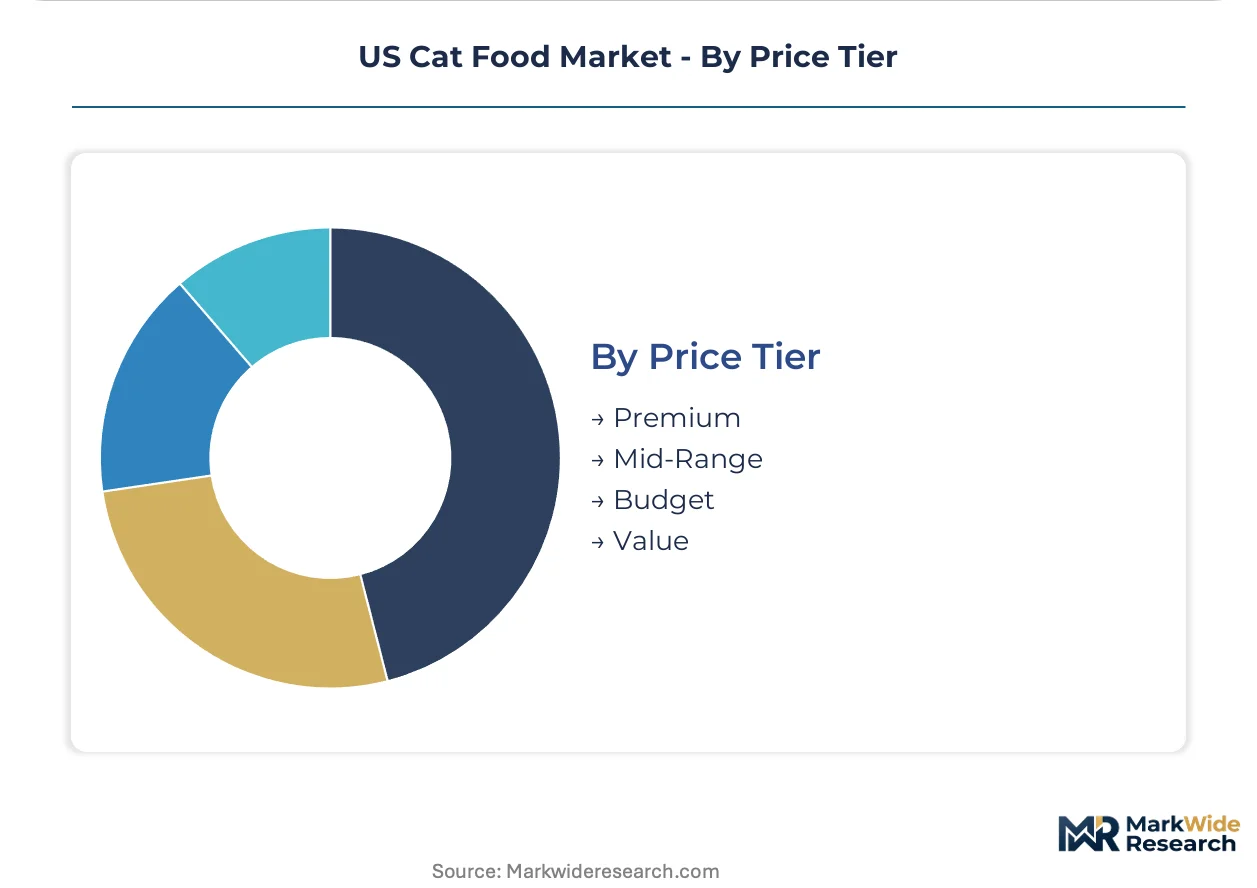
Price Tier:
Premium positioning requires R&D investment in therapeutic claims and packaging differentiation, while budget tiers compete on procurement scale and formulation standardization.
- Premium:Human-grade ingredient sourcing, veterinary endorsement, and sustainable packaging justify price multiples. California's extended producer responsibility mandates favor recyclable pouch and can formats.
- Mid-Range:Balanced nutrition claims with moderate ingredient quality serve mainstream household budgets across suburban and secondary metro markets.
- Budget:Commodity protein meals and simplified formulations target price-elastic consumers in rural and exurban geographies.
- Value:Private label and promotional SKUs capture temporary trade-down behavior without loyalty retention mechanics.
Mid-range tiers absorb the bulk of household penetration; premium is expanding most quickly as millennial pet owners trade up on humanization cues.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand clusters in coastal metropolitan corridors where pet humanization trends concentrate purchasing power toward premium formulations. California and the Northeast corridor anchor volume generation, while interior regions exhibit sharper price elasticity and private label preference.
California
Los Angeles and San Francisco Bay Area households drive premium wet food adoption with human-grade ingredient expectations. The state's extended producer responsibility mandates under CalRecycle are forcing packaging transitions toward recyclable pouches and aluminum cans. San Diego hosts specialized cold-chain distribution hubs serving raw and gently cooked format startups.
Northeast Corridor
New York Metro and Greater Boston concentrate multi-cat urban households with subscription replenishment penetration exceeding national averages. FDA's FSMA preventive controls enforcement elevates compliance costs for regional co-packers in New Jersey and Pennsylvania. Philadelphia anchors therapeutic nutrition R&D clustering tied to veterinary school partnerships.
Pacific Northwest
Seattle and Portland households exhibit elevated willingness-to-pay for sustainable sourcing certifications including Marine Stewardship Council seafood claims. Washington State Department of Agriculture enforces pathogen testing protocols for raw food processors that exceed federal baselines. Portland hosts emerging direct-to-consumer brands leveraging regional cold-chain infrastructure.
Southeast
Florida and Georgia concentrate retirement-age pet owners with therapeutic diet requirements for renal and diabetic feline management. USDA-inspected rendering facilities in Georgia supply protein meals to national manufacturers. Atlanta serves as a distribution node for wet food canning operations serving the Sun Belt.
Midwest
Chicago and Detroit metropolitan areas balance price-sensitive volume purchasing with emerging premium trade-up in urban cores. Illinois and Nebraska rendering concentration creates procurement advantages for scaled dry food manufacturers. Minneapolis-St. Paul anchors private label formulation services for retail channel brands.
US Cat Food Market Competitive Landscape
Midwest producers anchor one tier with integrated rendering-to-extrusion infrastructure; coastal specialists hold premium wet and raw format positions through cold-chain control and veterinary channel access. The market exhibits consolidated leadership in dry food with fragmented competition in emerging formats. Three archetypes dominate: multinational CPG conglomerates with veterinary prescription platforms, family-owned regional processors with private label capacity, and venture-backed direct-to-consumer brands with subscription infrastructure. Competitive moves concentrate on backward integration into protein meal supply and therapeutic nutrition R&D licensing.
Within the multinational tier, Nestlé Purina PetCare Co, Mars Incorporated, and Hill's Pet Nutrition Inc. exemplify divergent strategic positioning. Nestlé Purina represents the R&D-intensive therapeutic nutrition archetype with veterinary channel anchoring. Mars Incorporated occupies a position defined by supply chain integration across wet and dry manufacturing formats. Hill's Pet Nutrition Inc. exemplifies prescription diet specialization with clinic-based distribution control. These three entities collectively represent the scale-driven consolidation logic shaping competitive dynamics.
| Leading Market Players |
|---|
| Nestlé Purina PetCare Co |
| Mars Incorporated |
| Colgate-Palmolive Company |
| General Mills Inc. |
| The J. M. Smucker Company |
| Hill's Pet Nutrition Inc. |
| Royal Canin SAS |
| Blue Buffalo Co Ltd |
| Diamond Pet Foods |
| Others |
Pricing and Supply Chain Analysis
Premium wet-to-budget dry bifurcation splits the US cat food market into divergent margin architectures, with human-grade ingredient sourcing and cold-chain infrastructure commanding price multiples while commodity extrusion competes on procurement scale. This tier divergence manifests in supply chain configurations: coastal premium producers tether to specialized canning and refrigerated distribution, while Midwest dry food anchors draw from integrated rendering-to-extrusion corridors.
Pricing Analysis
Volume concentrates in mid-range dry food where price compression runs deepest, while margin pools concentrate in premium wet and therapeutic nutrition tiers. Three-tier pricing structure across premium, standard, and economy levels separates human-grade ingredient declarations from commodity protein meals and private label formulations. Cost compression in mid-tier segments is intensifying because animal protein meal volatility tracks commodity feed markets. Budget-tier rural households exhibit highest price sensitivity; urban coastal millennials trading up to premium formats show lowest elasticity.
Supply Chain Analysis
Direct-to-veterinary and direct-to-consumer channels handle subscription replenishment demand, while mass retail distribution runs through supermarket and pet specialty intermediaries. Protein meal supply concentrates in Illinois and Nebraska rendering facilities, with wet food canning clustering in the Pacific Northwest and Southeast. Chicken, fish meal, and synthetic taurine constitute critical input dependencies. Single-source vulnerability in Midwest rendering creates geographic concentration risk for regional processors lacking diversified supplier bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US cat food market functions as a vertical-integration race where upstream protein meal control and downstream subscription infrastructure determine sustainable margin capture. Players are pursuing captive supply of rendering capacity to insulate against commodity volatility and FSMA compliance cost escalation.
For Market Incumbents: Anchor therapeutic nutrition R&D licensing to veterinary school partnerships, locking in prescription diet protocol control before mid-tier competitors achieve board-certified nutritionist staffing. Defend wet food margin pools by retrofitting Pacific Northwest and Southeast canning operations for FSMA preventive controls compliance ahead of enforcement waves. Channel consolidation through Chewy and Amazon subscription platforms threatens traditional supermarket slotting fee economics. For New Entrants and Emerging Players: Multi-cat households in secondary Midwest metros represent an underserved buyer archetype with subscription penetration lagging coastal benchmarks. Target this segment through private label formulation services for regional retail chains, bypassing national slotting fee barriers. Raw and gently cooked formats in veterinary channels offer the most penetrable premium entry point given FDA's pathogen testing burdens freezing small-batch expansion in retail. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational CPG conglomerates seeking veterinary prescription platform augmentation. Long-term viability hinges on backward integration into protein meal supply or forward integration into subscription infrastructure, not brand equity alone. Watch California extended producer responsibility enforcement as an inflection indicator for packaging transition capex requirements that will strain undercapitalized regional processors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rendering | Captive protein meal supply insulates Mars and Nestlé from Illinois-Nebraska concentration risk. |
| Veterinary Channel Expansion | Hill's prescription diet specialization demonstrates recurring revenue anchoring through clinic-based distribution. |
| Subscription Platform Buildout | Chewy's infrastructure captures California and Northeast urban lifetime value metrics from episodic retail. |
| FSMA Compliance Retrofit | Wet food canning operations in Pacific Northwest absorb heaviest preventive controls mandate costs. |
| Sustainable Packaging Transition | CalRecycle mandates create first-mover advantage for recyclable pouch and aluminum can formats. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across pet food manufacturing executives, veterinary nutritionists, retail category buyers, and state feed control officials. AAFCO nutrient profile databases, FDA FSMA enforcement disclosures, USDA rendering facility inspection records, and Nielsen retail audit data provided triangulation points. Bottom-up SKU-level volume builds and top-down category expenditure reconciliations cross-validated market sizing.
Segment-level granularity modeled product type, distribution channel, ingredient sourcing, and price tier dimensions across wet, dry, treats, and raw formats. CAGRs derived from trend extrapolation of premium wet adoption rates and subscription penetration curves, stress-tested against protein meal price volatility assumptions. Therapeutic nutrition growth trajectories incorporated feline diabetes and renal disease prevalence modeling.
Revisions become necessary when FDA raw food rulemaking tightens, California packaging mandates accelerate, or rendering facility consolidation eliminates regional supplier alternatives. Forecasts reflect assumptions about millennial pet owner humanization persistence and FSMA compliance cost pass-through feasibility. Periodic stress-testing of base assumptions against state-level pathogen testing burden expansion is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Radar Speed Signs Market
Others
Europe Street Lighting Market
Others
Europe Electric Forklift Market
Others
North America Machine Vision Systems Market
Others
Tripod Market
Others
Nyerereite Market
Others
Japan Indoor LBS Market
Others
Interference Mitigation Filters Market
Others
Wearable Solar Devices Market
Others
Digital Audio Decoders Market
Others
South America Automotive LED Lighting Market
Others
Lepidolite Market
Others
Connected Living Room Market
Others
Japan Smart Home Market
Others
Over the Top Devices and Services Market
Others
Sound Reinforcement Market