
 Africa Smart Card Market | 2026-2036
Africa Smart Card Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Smart Card Market Outlook
Banking agent networks across Sub-Saharan Africa are reshaping how smart card issuers reach unbanked populations. Thales Group leverages its regional manufacturing partnerships to supply dual-interface EMV cards to central banks in Nigeria and Kenya. IDEMIA anchors its position through large-scale national ID contracts with governments prioritizing biometric voter and citizen registration. Giesecke & Devrient competes by specializing in secure element operating systems tailored for mobile financial services interoperability.
Africa smart cards are pocket-sized plastic or composite substrates embedding microprocessor chips, magnetic stripes, or RFID antennas that execute encrypted authentication protocols through ISO 7816 or ISO 14443 interfaces. These devices store cryptographic keys, biometric templates, and account credentials to enable secure physical and digital access across financial, governmental, and transit systems. Contactless technology leads volume deployment as transport authorities in Cairo, Lagos, and Nairobi replace token-based fare collection with tap-to-pay systems. Chip-based credentials dominate government identity verification applications where national biometric databases require tamper-resistant storage. Banking applications sustain the largest revenue pool as EMV migration accelerates across West and East African commercial banks replacing magnetic stripe debit cards.
South Africa's National Credit Regulator enforces payment card data protection standards that compel issuers toward PCI-DSS certified chip personalization. Kenya's Central Bank mandates interoperability standards for mobile money-linked smart cards, creating compliance-driven refresh cycles across financial services. Nigeria's National Identity Management Commission requires ISO 7816-4 compliant smart cards for all citizen biometric enrollment, directly shaping product specifications for domestic and imported credentials. Stakeholders must monitor how evolving data localization laws across African monetary zones alter chip manufacturing and personalization location decisions.
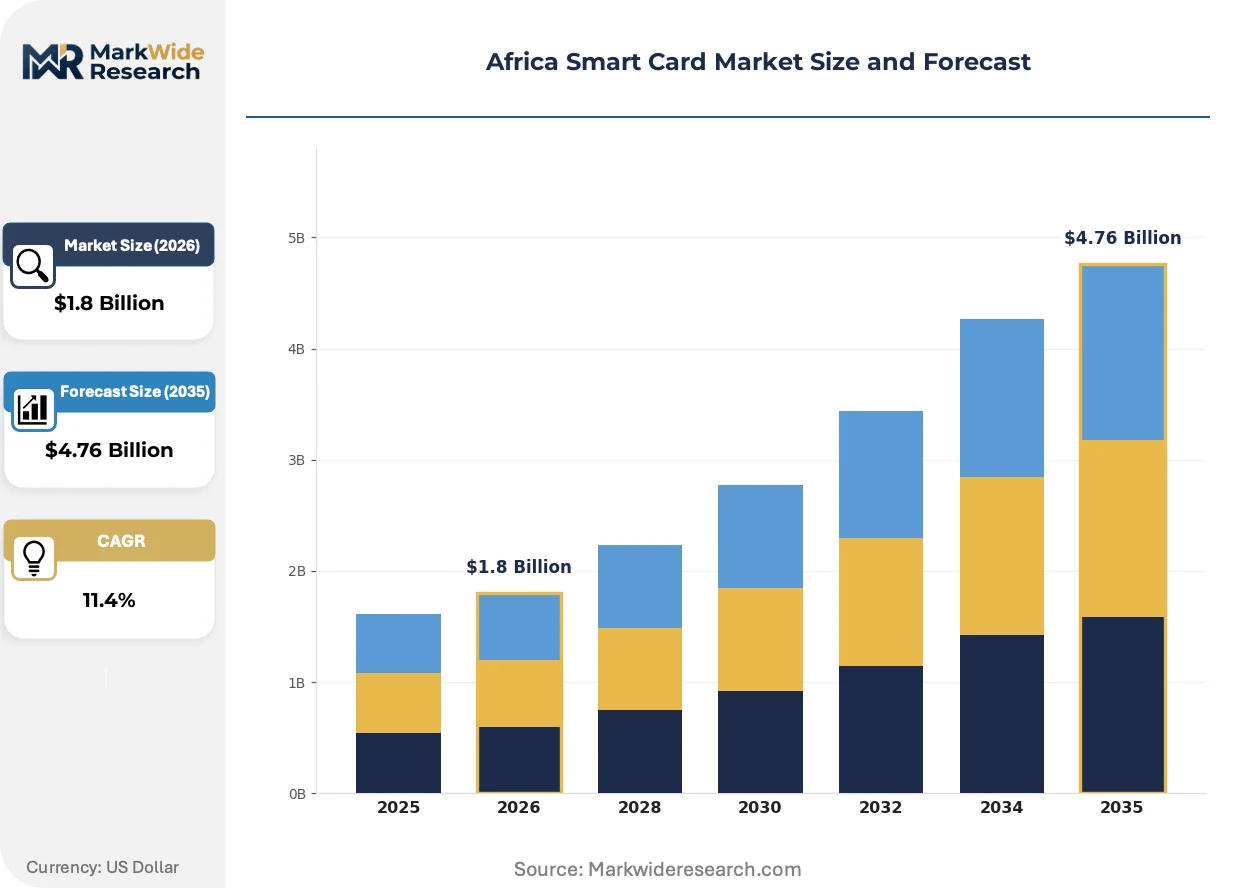
Market Dynamics
EMV migration mandates across Sub-Saharan banking sectors are compressing refresh cycles for magnetic stripe credentials while biometric enrollment programs reshape government procurement specifications.
Growth Catalysts
- Central Bank EMV Directives:Kenya's Central Bank interoperability standards for mobile-linked smart cards compel commercial banks to replace legacy magnetic stripe debit credentials. This creates compliance-driven demand for dual-interface chip cards across East African financial institutions.
- National Biometric ID Mandates:Nigeria's National Identity Management Commission requires ISO 7816-4 compliant credentials for citizen enrollment. Government procurement volumes accelerate as biometric voter registration expands ahead of electoral cycles.
- Contactless Transit Modernization:Transport authorities in Cairo, Lagos, and Johannesburg are replacing token-based fare collection with tap-to-pay systems. Dual-interface technology demand concentrates in urban mobility infrastructure upgrades.
Market Restraints
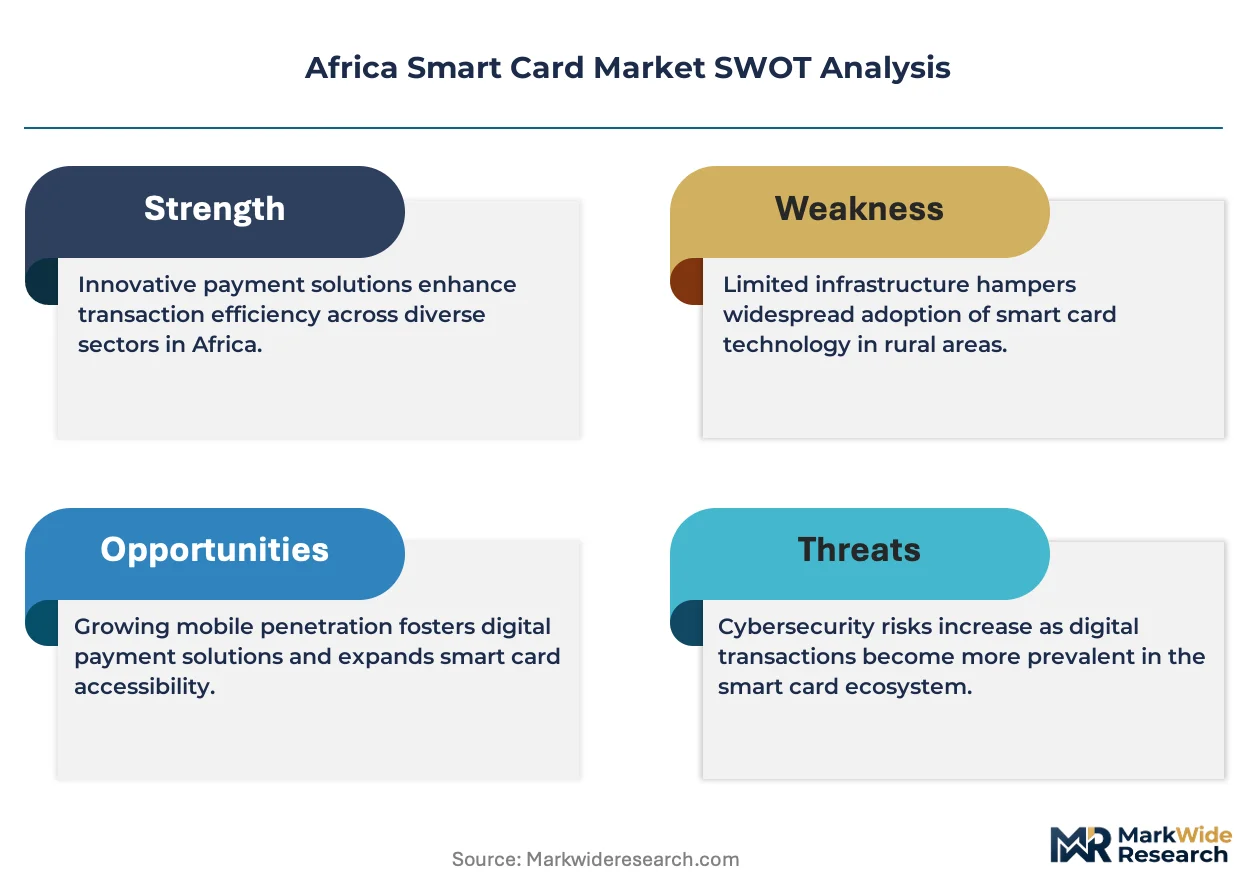
- Semiconductor Import Dependency:Secure element fabrication concentrates in Asian foundries. African card issuers face extended lead times and currency exposure when sourcing EMV chips for domestic personalization.
- Personalization Infrastructure Gaps:Centralized manufacturing in South Africa and Morocco creates distribution bottlenecks. Logistics costs escalate for credentials requiring field-level biometric data loading.
- Mobile Money Substitution:USSD-based financial services in Kenya and Tanzania reduce card dependency among underbanked populations. Smartphone penetration enables biometric authentication without physical credential issuance.
Strategic Opportunities
- East African Community Harmonization:Regional payment system integration creates cross-border credential standardization demand. Interoperable transit and banking cards can penetrate Rwanda, Uganda, and Burundi markets.
- eIDAS-Aligned Digital Identity:European technical standards influence donor-funded African digital ID programs. Qualified electronic signature capabilities on national ID cards open government service digitization contracts.
- Offline-Capable Payment Credentials:Intermittent connectivity in rural Nigeria and Ethiopia drives demand for stored-value cards with local transaction authorization. Offline EMV kernels enable merchant acceptance without real-time authorization.
Industry Challenges
- Biometric Template Standardization:Fragmented fingerprint and facial recognition formats across national ID programs force card vendors to maintain multiple personalization software stacks. ISO 19795 compliance testing extends product qualification timelines.
- Data Localization Enforcement:Evolving African monetary zone regulations restrict cross-border personalization of credentials containing citizen biometric data. Chip manufacturing location decisions require continuous legal monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Smart Card Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Contactless, Magnetic Stripe, Chip-Based, Hybrid Application: Banking, Access Control, Transportation, Identity Verification End User: Government, Retail, Financial Services, Healthcare Feature: Multi-Purpose, NFC, Secure Element, Biometric Integration |
| Companies Covered | Bundesdruckerei, Samsung Electronics, Thales Group, HID Global Corporation, Infineon Technologies, IDEMIA, IntelCav, Oberthur Technologies, Giesecke & Devrient, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Smart Card Market Strategic Shifts
Hardware security module integration and antenna miniaturization are reshaping credential form factors while regulatory data localization pressures reconfigure manufacturing geography.
Polycarbonate substrate adoption for national ID cards is rendering obsolete PVC-based credentials in high-durability applications. Nigeria's National Identity Management Commission and South Africa's Department of Home Affairs specify polycarbonate for ten-year validity documents. The material's laser-engraved personalization layer eliminates delamination risks in tropical climates while complicating in-country manufacturing equipment requirements.
South Africa's National Credit Regulator enforces PCI-DSS certified personalization for payment credentials. The mandate compels domestic card bureaus to upgrade hardware security module infrastructure. Commercial banks absorb compliance costs through centralized procurement contracts that favor vendors with certified South African personalization facilities.
Agent banking networks across Nigeria and Kenya now distribute pre-personalized smart cards to rural merchants. Traditional branch-based credential issuance loses share to last-mile activation models where biometric enrollment occurs at point of service. This channel transformation concentrates demand for secure logistics providers capable of managing blank-to-active card supply chains.
Africa Smart Card Market Segmentation
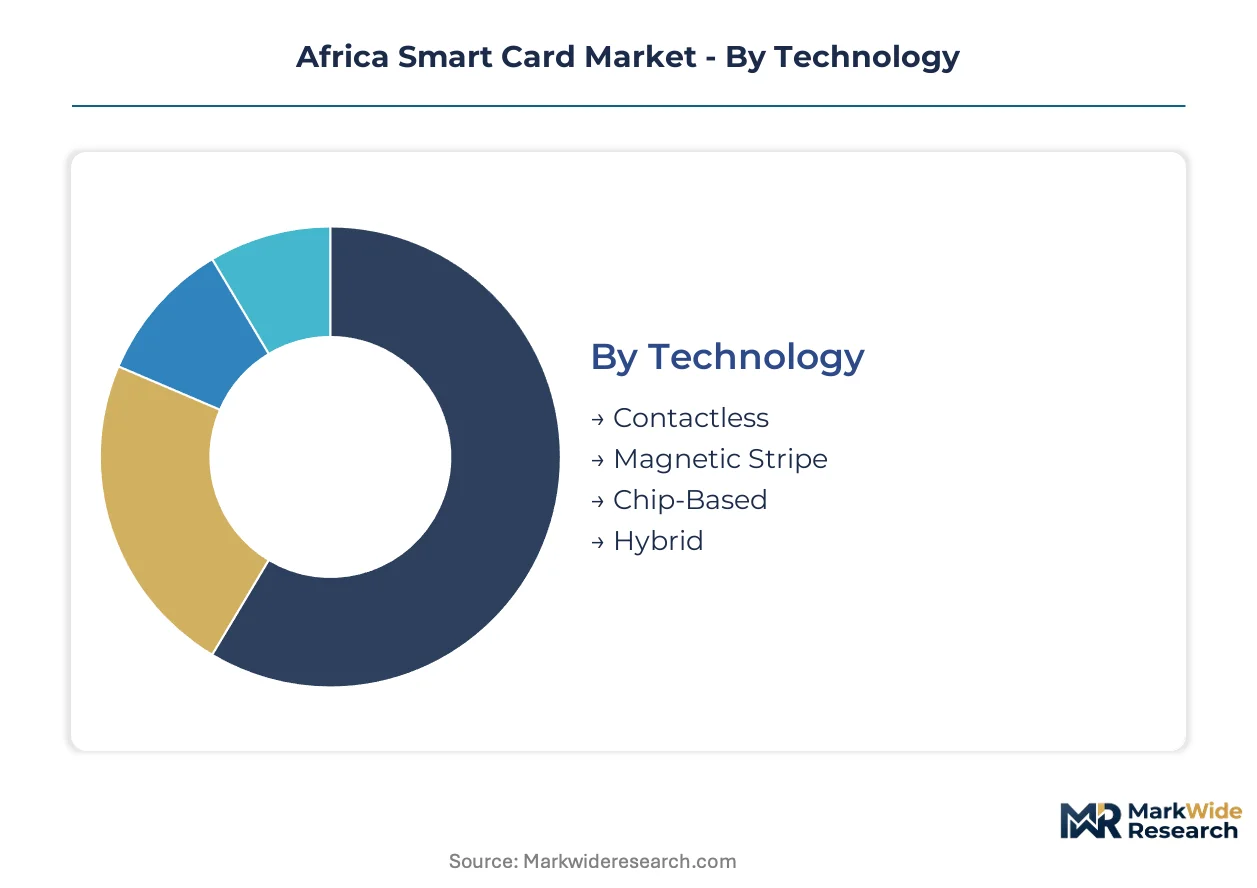
Smart card segmentation across Africa reveals how credential specifications diverge between financial inclusion mandates and high-security government applications. Technology choices and feature configurations directly determine manufacturing partnerships and personalization infrastructure investments for regional vendors.
Technology:
Technology segmentation captures the interface architecture defining transaction speed, security protocols, and manufacturing cost structures across African deployment contexts.
- Contactless:Dual-interface cards embedding ISO 14443 antennas enable tap-to-pay transit systems in Cairo, Lagos, and Johannesburg. Transport authorities concentrate procurement for fare modernization, though antenna miniaturization raises unit costs versus contact-only alternatives.
- Magnetic Stripe:Legacy credentials persist in rural banking networks with limited EMV terminal penetration. Kenya's Central Bank interoperability mandates are accelerating replacement cycles, compressing remaining volume windows for stripe-based issuance.
- Chip-Based:EMV-compliant microprocessor cards dominate Nigerian and Kenyan banking sectors with PCI-DSS certified personalization requirements.
- Hybrid:Dual-technology credentials bridge magnetic stripe and chip interfaces for phased migration scenarios in West African commercial banks.
Contactless commands the established base. The steepest expansion runs through chip-based EMV credentials as central bank directives harden.
Application:
Application segmentation tracks how credential functionality aligns with sector-specific regulatory compliance and infrastructure maturity across the continent.
- Banking:EMV debit and credit cards sustain the largest revenue pool as West and East African commercial banks replace magnetic stripe portfolios. South Africa's National Credit Regulator enforces PCI-DSS certified chip personalization that shapes vendor qualification requirements.
- Identity Verification:National biometric ID programs in Nigeria, South Africa, and Kenya drive polycarbonate credential demand with ten-year validity specifications. Nigeria's National Identity Management Commission mandates ISO 7816-4 compliance for all citizen enrollment cards.
- Transportation:Urban mobility authorities deploy tap-to-pay systems replacing token-based fare collection in Cairo, Lagos, and Nairobi.
- Access Control:Corporate and government facility security systems utilize secure element credentials for physical entry management.
Banking applications anchor current procurement volumes. Identity verification is climbing the fastest as electoral cycles accelerate biometric enrollment timelines.
End User:
End user segmentation distinguishes procurement patterns between centralized government tenders and distributed commercial channel structures.
- Government:National ID, voter registration, and social benefit distribution programs concentrate large-volume tenders with extended contract durations. Nigeria's biometric enrollment and South Africa's home affairs specifications directly shape domestic manufacturing investments.
- Financial Services:Commercial banks and mobile money operators drive refresh cycles through compliance mandates and customer acquisition strategies. Agent banking networks in Nigeria and Kenya now distribute pre-personalized cards to rural merchants.
- Retail:Loyalty and stored-value programs serve urban consumer segments with lower security requirements than financial or government credentials.
- Healthcare:Patient identification and insurance eligibility systems utilize smart cards for portable medical record access.
Government contracts secure the longest revenue visibility. Financial services channels are expanding most quickly through last-mile distribution innovations.
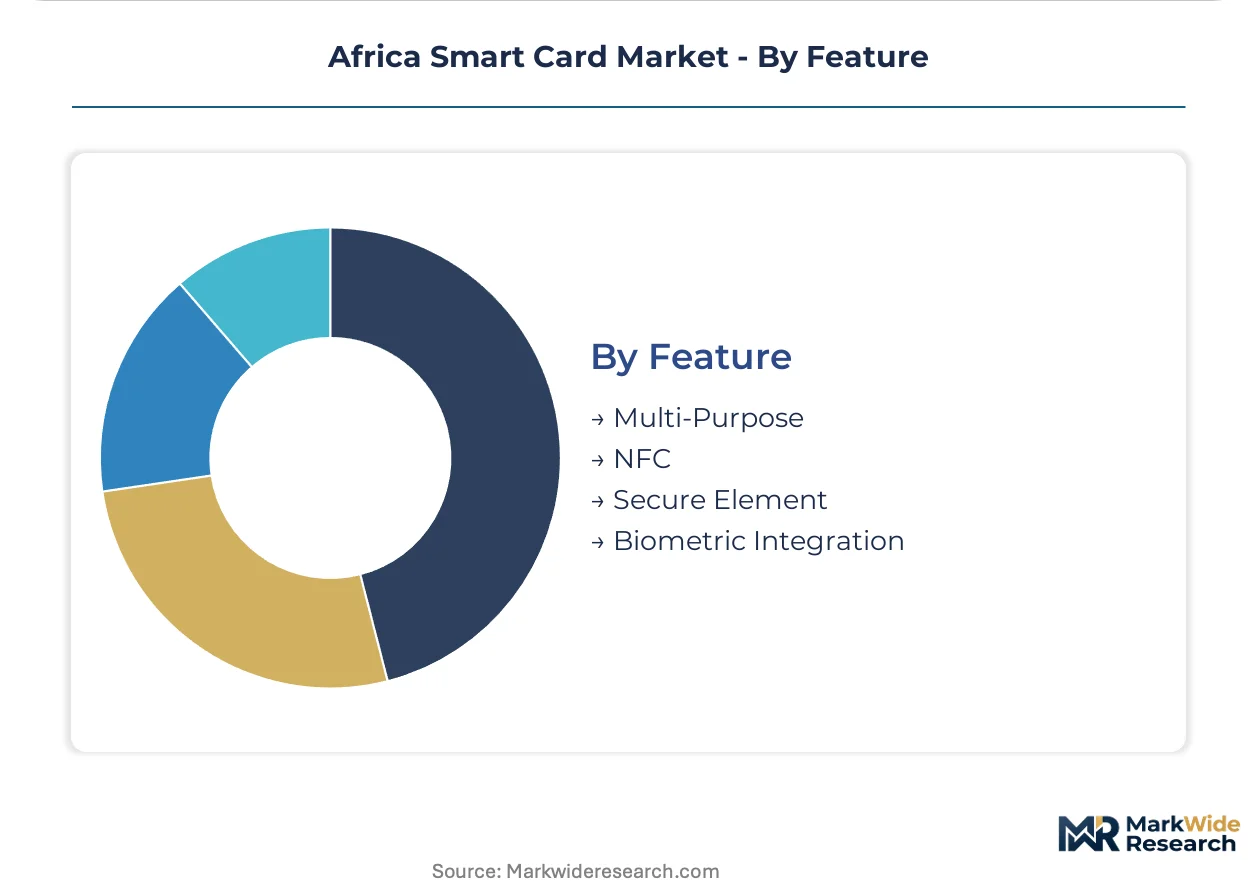
Feature:
Feature segmentation isolates value-added capabilities that differentiate premium credentials from baseline offerings in procurement evaluations.
- Secure Element:Tamper-resistant hardware storing cryptographic keys dominates EMV and national ID specifications. South African personalization bureaus upgrade hardware security module infrastructure to meet National Credit Regulator certification requirements.
- Biometric Integration:On-card fingerprint sensors or template storage enable offline identity verification in intermittent connectivity environments. Nigeria's National Identity Management Commission requirements drive template standardization investments across personalization software stacks.
- NFC:Near-field communication capabilities support mobile device pairing and transit tap-to-pay applications.
- Multi-Purpose:Combined payment, transit, and identity functions converge in East African Community harmonization scenarios.
Secure element capabilities command baseline requirements. Biometric integration is gaining share fastest as offline authentication needs intensify in rural deployment contexts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Lagos-Ibadan rail corridor and Mombasa-Nairobi Standard Gauge Railway underpin East and West Africa's credential distribution networks, enabling centralized personalization facilities to serve dispersed banking agent networks.
Nigeria
EMV migration and national biometric enrollment drive dual-interface card demand. The National Identity Management Commission mandates ISO 7816-4 compliant credentials for citizen registration, compelling domestic personalization capacity investments. Lagos hosts the primary manufacturing cluster serving West African banking sectors.
South Africa
PCI-DSS certified chip personalization requirements concentrate high-security credential production. The National Credit Regulator enforces payment card data protection standards that shape vendor qualification. Johannesburg anchors the region's secure element distribution infrastructure.
Kenya
Central Bank interoperability standards for mobile-linked smart cards accelerate magnetic stripe replacement cycles. Agent banking networks distribute pre-personalized credentials to rural merchants. Nairobi's technology corridor hosts personalization bureaus serving East African Community markets.
Egypt
Cairo's metro tap-to-pay modernization concentrates contactless transit card procurement. Government financial inclusion programs expand chip-based credential issuance beyond urban centers. The Nile Delta industrial zone supports domestic card finishing operations.
Morocco
Gateway positioning enables personalization exports to Francophone West African markets. Banking sector EMV compliance deadlines compress legacy credential refresh timelines. Casablanca's manufacturing facilities serve regional central bank procurement tenders.
Africa Smart Card Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying secure elements and operating systems. Market structure concentrates around three to five full-service credential vendors with end-to-end personalization capabilities. Strategic archetypes include integrated security technology conglomerates, specialized smart card pure-plays, and semiconductor component suppliers. Competitive intensity manifests through national ID contract bidding and central bank EMV certification races.
Within the integrated security tier, Thales Group and IDEMIA occupy positions shaped by large-scale government biometric enrollment programs and central banking partnerships. Giesecke & Devrient represents the specialized credential vendor archetype with focused expertise in secure element operating systems. Samsung Electronics anchors the semiconductor supply dimension, exemplifying component-scale players enabling downstream personalization. Bundesdruckerei and Infineon Technologies sit within adjacent technology layers, representing European-origin manufacturing and chip design specializations respectively.
| Leading Market Players |
|---|
| Bundesdruckerei |
| Samsung Electronics |
| Thales Group |
| HID Global Corporation |
| Infineon Technologies |
| IDEMIA |
| IntelCav |
| Oberthur Technologies |
| Giesecke & Devrient |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in South African personalization bureaus concentrates pricing leverage among PCI-DSS certified vendors serving Nigerian and Kenyan central bank mandates. This utilization squeeze elevates premium tier rates for EMV chip credentials while compressing margins on magnetic stripe replacements.
Pricing Analysis
Volume-discount tiering structures stratify procurement across three certification-grade levels. Premium pricing attaches to polycarbonate national ID cards with laser-engraved personalization meeting Nigeria's National Identity Management Commission ten-year validity specifications. Standard tiers cover dual-interface EMV banking credentials with domestic personalization. Economy positioning persists for magnetic stripe credentials in rural networks with limited terminal penetration. Price differentiation hinges on secure element grade and personalization location, with South African PCI-DSS certified facilities commanding premiums over Moroccan or Egyptian alternatives. Cost compression in the economy tier is intensifying because Kenyan Central Bank interoperability deadlines are accelerating legacy replacement cycles.
Supply Chain Analysis
Tariff exposure between Asian foundries and African card bureaus dominates supply chain risk calculations for secure element procurement. Semiconductor fabrication concentrates in Taiwan, South Korea, and China, with African issuers drawing from these sources for EMV chip modules. Polycarbonate substrate supply rests on European and Middle Eastern petrochemical producers, while antenna components for dual-interface cards source from Chinese manufacturers. Single-source vulnerability concentrates in secure element operating systems, where three vendors control the majority of African banking sector deployments. Distribution runs through Johannesburg and Casablanca hub facilities serving regional agent banking networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive moat anchored in regulatory entrenchment. Central bank EMV mandates and national ID biometric enrollment programs create multi-year contract visibility that locks out unqualified competitors.
For Market Incumbents: Harden personalization infrastructure investments in South Africa and Nigeria to defend against emerging fintech credential platforms. Secure PCI-DSS certification renewals ahead of Kenyan Central Bank interoperability enforcement timelines. Deepen backward integration into secure element distribution partnerships to offset Asian foundry lead time volatility.
For New Entrants and Emerging Players: Francophone West African banking sectors outside Nigeria's orbit present the most penetrable white-space for EMV credential vendors. Morocco's gateway positioning enables export to Senegal, Côte d'Ivoire, and Burkina Faso markets with compressed compliance deadlines. Target agent banking channel partnerships rather than direct central bank certification races.
For Investors and Strategic Acquirers: Capital is best deployed toward personalization bureau operators with existing African regulatory certifications and hardware security module infrastructure. The long-term viability window favors vendors positioned for polycarbonate national ID contract waves and offline-capable payment credential development. Watch biometric template standardization alignment across Nigeria, Kenya, and South Africa as the signal for consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| PCI-DSS Certification Investment | South Africa's National Credit Regulator enforces data protection standards that disqualify uncertified vendors from banking procurement. |
| Polycarbonate Substrate Transition | Nigeria's National Identity Management Commission specifications for ten-year validity documents render PVC credentials obsolete. |
| Agent Banking Channel Partnership | Last-mile distribution to rural merchants in Kenya and Nigeria replaces branch-based issuance with pre-personalized card logistics. |
| Offline EMV Kernel Development | Intermittent connectivity in rural Nigeria and Ethiopia drives demand for stored-value cards with local transaction authorization. |
| East African Community Harmonization | Regional payment system integration creates cross-border credential standardization demand across Rwanda, Uganda, and Burundi. |
Study Parameters
Initial hypotheses were tested against primary input from central bank payment system officers, national ID program directors, card bureau operations managers, and secure element vendor account executives and refined through secondary validation. Trade data from South African Revenue Service and Nigerian Customs Service captured import volumes for EMV chip modules and polycarbonate substrates. Central bank directive filings, national ID commission procurement notices, and transit authority modernization tenders supplied policy-driven demand signals. Bottom-up credential shipment estimates from personalization facilities were triangulated against top-down banking sector card portfolio data.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include interface technology, application sector, end-user procurement channel, and credential feature configuration. CAGRs were derived from fitted growth curves calibrated to central bank mandate implementation schedules and electoral cycle biometric enrollment waves. Forecast inputs incorporated EMV terminal deployment trajectories and mobile money substitution elasticity estimates for underbanked populations.
The forecast holds incumbent behavior within observed patterns; aggressive moves by fintech platform operators or semiconductor foundry direct sales teams would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Rugged Devices Market
Others
Griffin Beaker Market
Others
Global Military and Aerospace Sensors Market
Others
Education and Learning Analytics Market
Others
Global Webinar and Webcast Market
Others
Spain Smart Home Market
Others
Telecom Transformers Market
Others
Prunes Market
Others
AI in Home Automation Market
Others
Performance Testing Tools Market
Others
Hot Air System Market
Others
Italy Smart Home Market
Others
Mobile Edge Computing Market
Others
Basketball Apparel Market
Others
Europe Tablet PC Market
Others
Global Aircraft Sensors Market