
 Bimodal Identity Management Solutions Market | 2026-2036
Bimodal Identity Management Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Bimodal Identity Management Solutions Market Outlook
Platform licensing revenue is narrowing as vendors shift toward consumption-based identity governance pricing. Microsoft Corporation leverages its Azure Active Directory ecosystem to anchor enterprise hybrid deployments across cloud and on-premises environments. IBM Corporation competes through deep mainframe identity integration and zero-trust consulting services for regulated industries. SailPoint Technologies, Inc. specializes in access certification workflows that sustain premium pricing in financial services and healthcare verticals.
Bimodal identity management solutions orchestrate user credentials across legacy directory services and modern cloud identity providers, typically employing SCIM provisioning protocols and SAML or OIDC federation standards to maintain continuous authentication states. The primary commercial purpose is eliminating security gaps during multi-year cloud migrations while preserving operational continuity for critical on-premises applications. Access Management and Identity Governance segments command the largest margin pools as enterprises prioritize privileged access controls and compliance audit automation over basic directory synchronization. Cloud-Based and Hybrid deployment models represent the fastest-expanding configuration categories, though On-Premises retains substantial share in defense and classified government environments where data sovereignty requirements prohibit external identity federation.
NIST, the EU AI Act, and HIPAA shape product development trajectories by mandating multi-factor authentication, explainable access decisions, and audit trail retention for protected health information environments. These frameworks force vendors to embed continuous risk assessment engines and granular consent management modules directly into core platform architectures rather than treating compliance as a peripheral feature set. Stakeholders must evaluate whether their current identity infrastructure can adapt to emerging requirements for cross-border data residency and algorithmic transparency in automated access decisions.
Market Dynamics
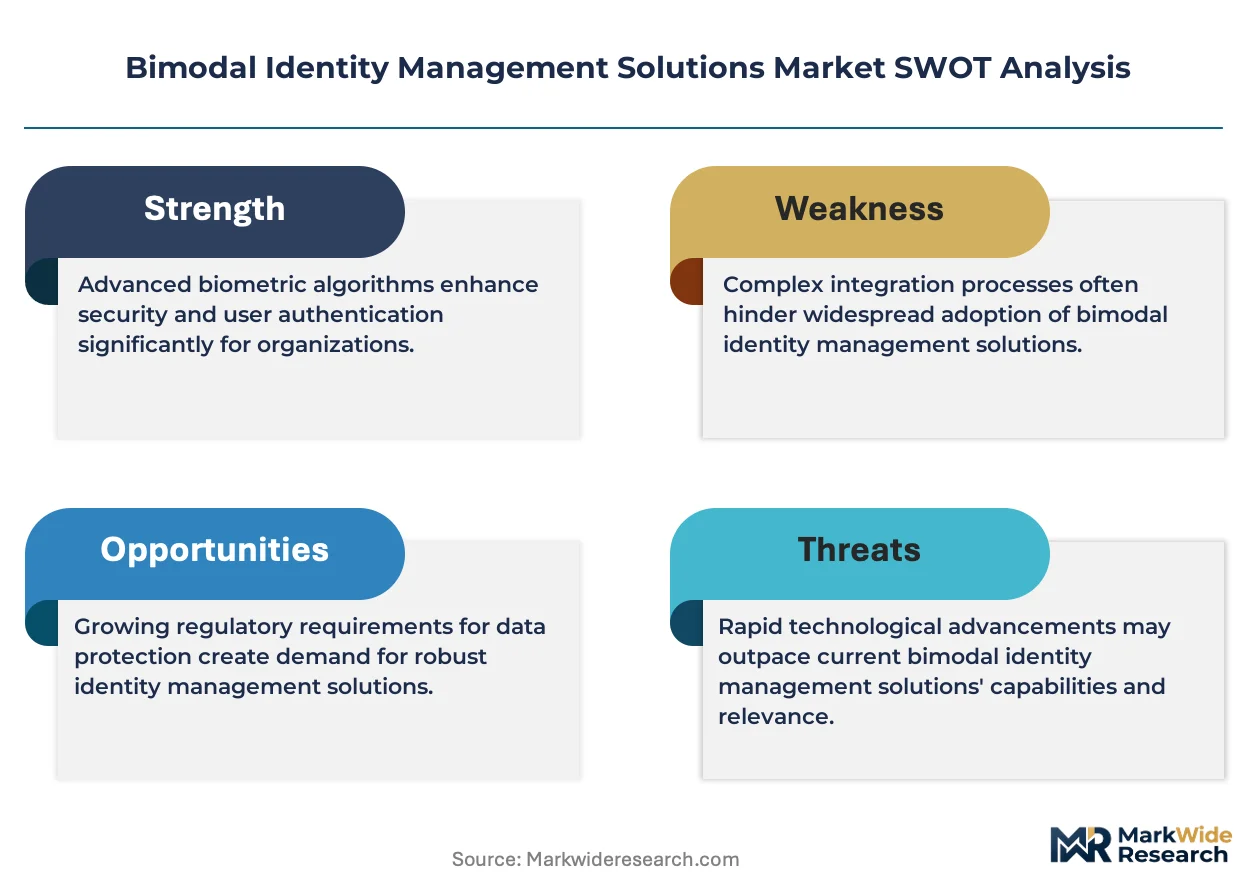
Enterprise cloud migration timelines are compressing identity infrastructure refresh cycles, forcing security teams to maintain parallel authentication systems while modernizing access governance without service interruption.
Growth Catalysts
- NIST zero-trust mandates:Federal agencies and defense contractors must implement continuous verification architectures, accelerating procurement of bimodal identity platforms that bridge legacy directories with cloud-native controls.
- Critical infrastructure operators:Power utilities and water treatment facilities face escalating cyber insurance requirements that demand privileged access monitoring across hybrid IT-OT environments.
- SCIM protocol standardization:Automated user provisioning between on-premises HR systems and SaaS applications reduces manual identity lifecycle management overhead in large enterprises.
Market Restraints
- Specialized engineering talent scarcity:Organizations struggle to hire identity architects proficient in both legacy LDAP implementations and modern OAuth 2.0 federation patterns.
- Defense sector data sovereignty rules:Classified environments in the United States, Germany, and Japan prohibit external identity federation, constraining cloud-native feature adoption.
- Legacy mainframe authentication:Decades-old RACF and ACF2 systems in banking and insurance resist standard API-based integration without expensive middleware layers.
Strategic Opportunities
- Healthcare access certification automation:HIPAA audit requirements create demand for AI-assisted access reviews that reduce compliance preparation from months to days.
- EU NIS2 Directive enforcement:Critical entity designation expands mandatory identity governance procurement across energy, transport, and digital infrastructure sectors.
- Convergence of identity and endpoint detection:Unified platforms correlating user behavior with device trust signals address gaps between identity and security operations centers.
Industry Challenges
- Multi-vendor integration complexity:Enterprises average 15-25 distinct identity tools, creating authentication silos that resist unified policy enforcement without costly consolidation projects.
- Algorithmic access decision explainability:Risk-based authentication engines must produce auditable reasoning for automated denials to satisfy regulatory scrutiny in financial services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bimodal Identity Management Solutions Market |
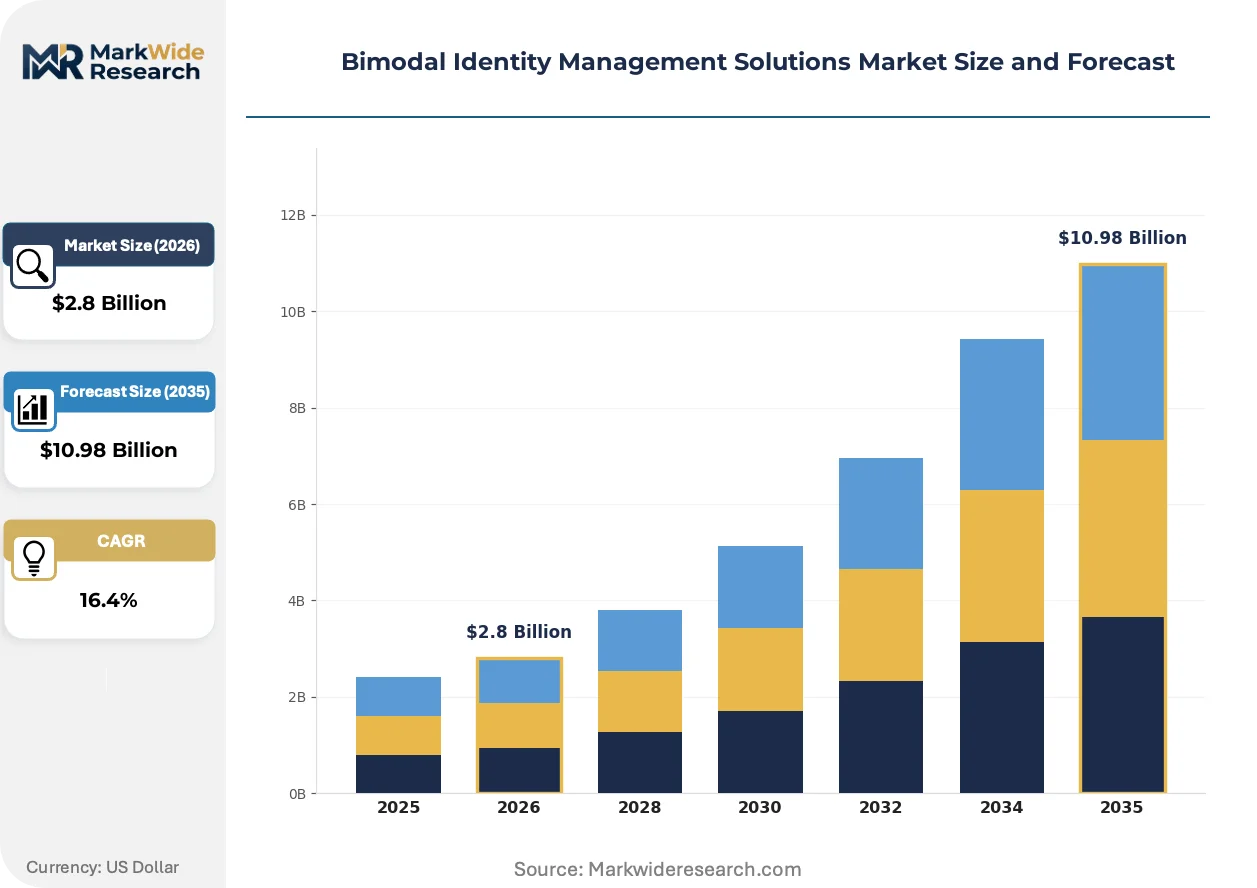
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.98 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Access Management, Identity Governance, Directory Services, Authentication Services Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS End User: Enterprises, Government Agencies, Educational Institutions, Healthcare Providers Integration Level: API Integration, Deep Integration, Single Sign-On, Multi-Factor Authentication |
| Companies Covered | Microsoft Corporation, IBM Corporation, Oracle Corporation, Okta, Inc., Ping Identity, SailPoint Technologies, Inc., CyberArk, Cloud Software Group, Inc., Ivanti, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bimodal Identity Management Solutions Market Strategic Shifts
Continuous authentication architectures are displacing session-based login models, embedding risk scoring into every resource access decision rather than treating identity verification as a one-time gateway event.
Passwordless authentication is hybridizing credential architectures across FIDO2 hardware keys, biometric sensors, and mobile device attestations. Financial services institutions in Singapore and the Netherlands are deploying these methods for high-value transaction authorization. This convergence is hybridizing procurement patterns, with buyers demanding unified platforms that accommodate both legacy password vaults and emerging cryptographic authenticators without rip-and-replace disruption.
The EU AI Act's risk classification system for automated decision-making is forcing identity vendors to document training data provenance and model performance metrics for access scoring algorithms. Vendors serving European multinational enterprises must now maintain algorithmic impact assessments as standard contract deliverables. Healthcare and banking sectors face the steepest compliance burdens, with some institutions pausing AI-assisted access recommendations until audit frameworks stabilize.
Enterprise buying committees are unbundling identity governance from bundled security suites, evaluating standalone access certification and privileged session management tools against point solutions with deeper vertical specialization. This pattern is most pronounced in United States healthcare systems and German automotive suppliers, where compliance officers now hold veto power over consolidated procurement decisions that previously favored single-vendor relationships.
Bimodal Identity Management Solutions Market Segmentation
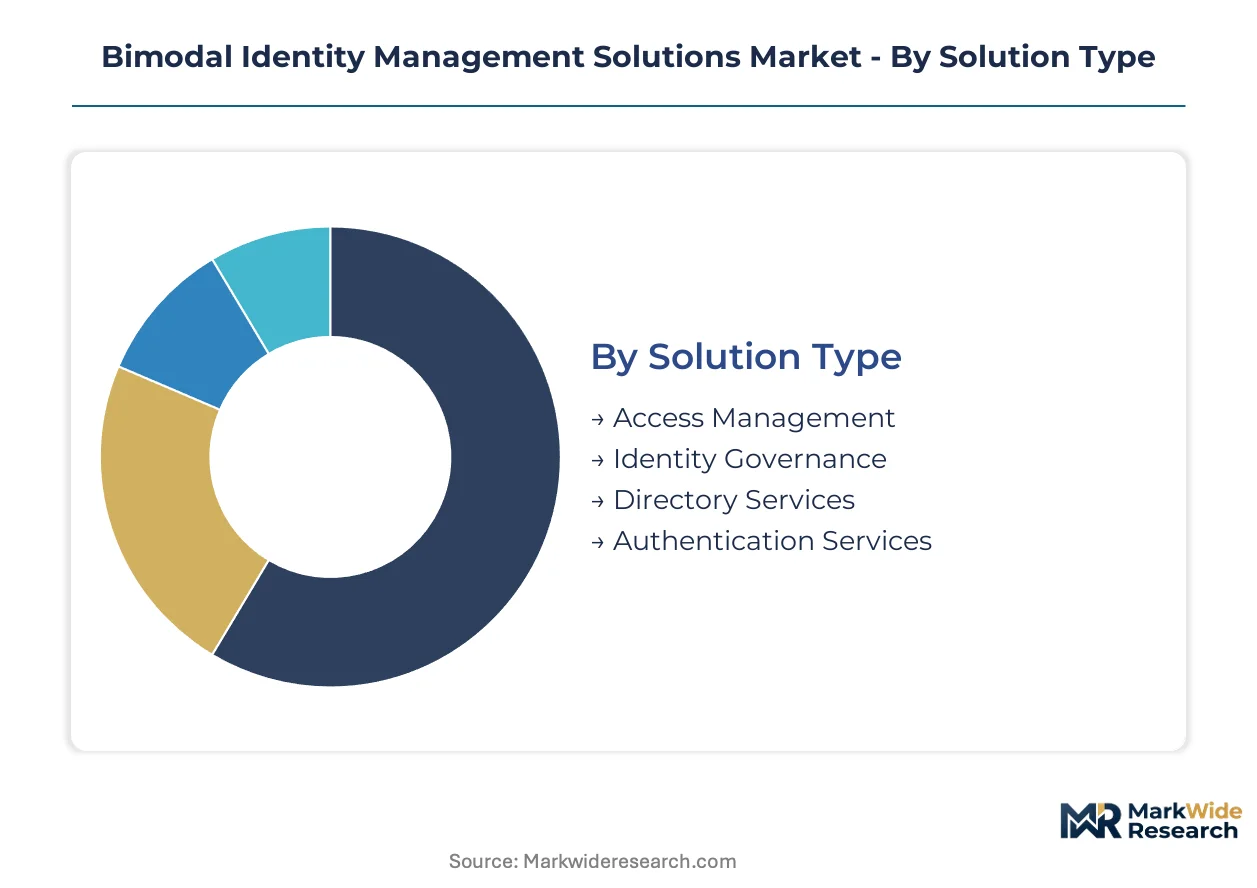
Bimodal identity architectures fragment procurement decisions across multiple technical and organizational dimensions. Security teams must reconcile legacy infrastructure constraints with cloud-native capabilities when selecting solution components. Each segmentation axis reveals distinct buyer priorities, pricing dynamics, and implementation complexity profiles.
Solution Type:
Access Management platforms refresh on 18-24 month cycles as threat vectors evolve, while Directory Services deployments persist for 7-10 years given their deep embedding in enterprise authentication flows.
- Access Management:Orchestrates real-time authentication decisions across hybrid environments using policy engines that evaluate device trust, user behavior, and resource sensitivity. Financial services institutions in Singapore and the Netherlands prioritize these platforms for high-value transaction authorization. NIST zero-trust mandates accelerate federal procurement of continuous verification capabilities.
- Identity Governance:Automates access certification workflows, role mining, and compliance reporting for regulated industries. HIPAA audit requirements drive healthcare systems toward AI-assisted access review modules. Premium pricing persists where vendors demonstrate audit preparation compression from months to days.
- Directory Services:Maintains authoritative user attribute stores bridging legacy LDAP with cloud-native identity providers.
- Authentication Services:Delivers passwordless, biometric, and cryptographic credential verification.
Access Management anchors the volume base while Identity Governance gains share at the steepest rate.
Deployment Model:
Cloud-Based configurations command 40-60% lower total cost of ownership over five years versus On-Premises equivalents, though Hybrid deployments absorb the largest professional services attach rates.
- Cloud-Based:Delivers elastic identity capacity without capital infrastructure commitment. European multinational enterprises favor these deployments where EU AI Act algorithmic transparency requirements can be enforced through vendor-managed compliance modules. Data residency controls remain a procurement veto point.
- Hybrid:Synchronizes on-premises directory services with cloud-native authentication endpoints using SCIM provisioning and SAML federation. United States federal agencies and defense contractors require these architectures to satisfy NIST zero-trust mandates while preserving legacy system connectivity. Implementation timelines average 12-18 months.
- On-Premises:Retains dominance in classified government environments where data sovereignty rules prohibit external identity federation.
- SaaS:Offers consumption-based pricing with rapid deployment for mid-market enterprises.
Hybrid deployments capture the largest professional services revenue pool while Cloud-Based configurations expand most quickly.
End User:
Enterprise buyers average 15-25 distinct identity tools, creating consolidation urgency that Government Agencies avoid through centralized procurement mandates.
- Enterprises:Span multinational corporations with heterogeneous IT estates requiring unified policy enforcement across acquired subsidiaries. German automotive suppliers and United States healthcare systems demonstrate pronounced unbundling tendencies, with compliance officers now vetoing bundled security suite purchases in favor of specialized point solutions.
- Government Agencies:Operate under strict data sovereignty and classified handling requirements that constrain cloud-native feature adoption. United States, German, and Japanese defense sectors maintain substantial On-Premises directory investments given RACF and ACF2 mainframe dependencies.
- Educational Institutions:Manage seasonal identity lifecycle spikes and federated research collaborations.
- Healthcare Providers:Face HIPAA audit automation imperatives and protected health information access trail retention mandates.
Enterprises generate the broadest solution diversity while Government Agencies impose the strictest architectural constraints.
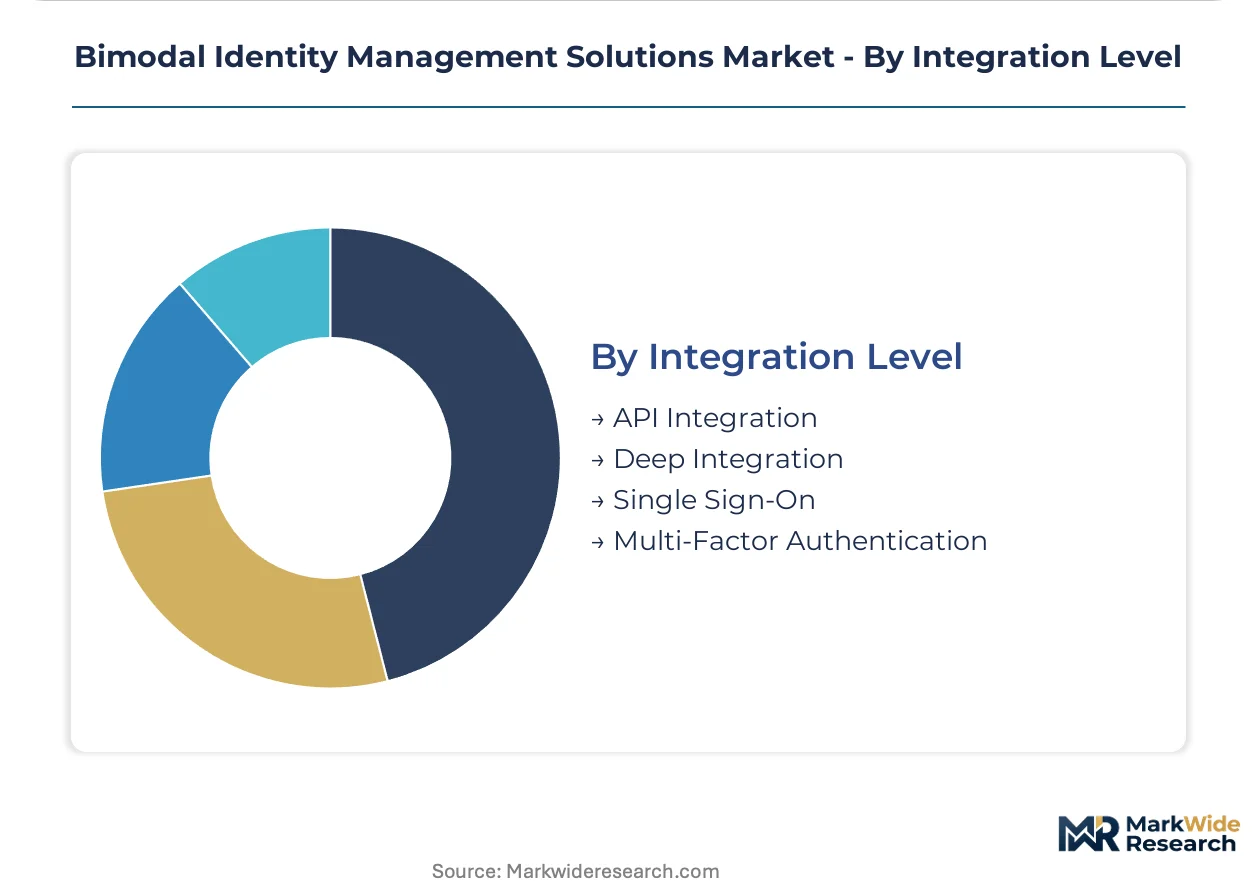
Integration Level:
Deep Integration projects consume 3-5x the engineering hours of API Integration engagements but deliver unified policy enforcement that fragmented toolchains cannot replicate.
- Deep Integration:Embeds identity controls directly into application codebases and mainframe transaction monitors, requiring specialized RACF and ACF2 expertise scarce in contemporary identity architect labor pools. Banking and insurance carriers in Japan and Germany sustain these investments to preserve decades-old core system functionality.
- Multi-Factor Authentication:Enforces stepped verification through FIDO2 hardware keys, biometric sensors, and mobile device attestations. Financial services deployment in Singapore demonstrates production-scale passwordless transaction authorization. EU NIS2 Directive enforcement expands mandatory adoption across energy and transport critical entities.
- API Integration:Enables rapid connectivity through standardized REST and SCIM interfaces.
- Single Sign-On:Reduces credential fatigue through centralized session management.
API Integration handles the highest transaction volume while Deep Integration commands the steepest premium pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States and Germany accept premium pricing for zero-trust compliance, while Japanese defense contractors and Indian mid-market enterprises drive hard bargains on hybrid deployment costs.
United States
NIST zero-trust mandates and cyber insurance requirements power federal agency procurement of continuous verification platforms. HIPAA audit automation drives healthcare systems toward AI-assisted access governance. Washington DC defense contractors and Silicon Valley cloud-native vendors anchor the largest professional services revenue pool for hybrid identity architectures.
Germany
Automotive suppliers and critical infrastructure operators demand granular consent management under EU NIS2 Directive enforcement. The country's national cybersecurity regulator BSI mandates multi-factor authentication for energy and transport sectors. Bavarian industrial clusters and Frankfurt financial services firms sustain premium pricing for identity governance platforms with explainable access decision engines.
Japan
Banking and insurance carriers resist cloud-native feature adoption due to decades-old RACF and ACF2 mainframe dependencies. METI guidelines on critical infrastructure protection shape procurement specifications for hybrid deployments. Tokyo financial districts and Osaka manufacturing hubs concentrate demand for deep integration expertise scarce in contemporary labor markets.
Singapore
Financial services institutions deploy passwordless authentication for high-value transaction authorization at production scale. The Monetary Authority of Singapore's technology risk management guidelines accelerate FIDO2 hardware key adoption. Marina Bay fintech clusters and R&D partnerships with Netherlands-based institutions drive cross-border identity federation pilots.
India
Mid-market enterprises favor SaaS consumption-based pricing with rapid deployment timelines over capital-intensive on-premises investments. RBI cybersecurity guidelines for banks and SEBI mandates for securities firms shape authentication requirements. Bengaluru IT services corridors and Mumbai financial districts concentrate API integration demand for seasonal workforce identity lifecycle management.
Bimodal Identity Management Solutions Market Competitive Environment
Capability concentration sits with specialized governance vendors; scale advantage sits with cloud platform incumbents. The market structures around three tiers: hyperscale platform providers with directory service ecosystems, vertical specialists commanding premium pricing in regulated industries, and mid-tier integrators competing on professional services attach rates. Dominant competitive moves include strategic partnerships bridging legacy mainframe expertise with cloud-native development, plus portfolio diversification into adjacent endpoint detection markets.
Within the hyperscale tier, Microsoft Corporation anchors enterprise hybrid deployments through Azure Active Directory ecosystem integration. IBM Corporation occupies a position serving regulated industries with mainframe identity heritage and zero-trust consulting capabilities. SailPoint Technologies, Inc. exemplifies the vertical specialist archetype, sustaining premium positioning through access certification workflow depth in financial services and healthcare procurement cycles.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Oracle Corporation |
| Okta, Inc. |
| Ping Identity |
| SailPoint Technologies, Inc. |
| CyberArk |
| Cloud Software Group, Inc. |
| Ivanti, Inc. |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on specialized identity architects proficient in both legacy LDAP and modern OAuth 2.0 patterns determines both pricing tier spreads and supply chain shape across the bimodal identity management market. Talent scarcity in Japan and Germany forces premium pricing for deep integration projects while compressing margins on standardized SaaS deployments.
Pricing Analysis
Professional services and extended support contracts drive lifetime value, with three-tier pricing structure across premium, standard, and economy levels. Subscription-based SaaS tiers dominate cloud-native deployments, while project-based pricing persists for hybrid implementations requiring mainframe integration expertise. Price differentiation rests on certification depth—vendors with FedRAMP or BSI approval command substantial premiums—and vertical specialization in HIPAA-regulated healthcare. Cost compression in mid-market SaaS tiers is intensifying because Indian IT services firms are pushing consumption-based models. Government agencies in the United States and Germany show least price sensitivity due to zero-trust mandate compliance deadlines, while Indian mid-market enterprises drive hardest bargain negotiations.
Supply Chain Analysis
Contract manufacturing concentration remains minimal as identity software development centers on the United States, Ireland, and India for engineering talent pools. Platform development draws from open-source cryptographic libraries, cloud infrastructure APIs, and specialized hardware security modules sourced from Taiwan and South Korea. Single-source vulnerability exists for FIDO2 hardware key components where Taiwanese foundries dominate secure element fabrication. Distribution runs through direct enterprise sales forces for large accounts, supplemented by systems integrator channels for mid-market penetration and managed security service providers for ongoing operational support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bimodal identity management market sits in early-cycle expansion as NIST zero-trust mandates and EU NIS2 Directive enforcement accelerate replacement of legacy directory infrastructures.
For Market Incumbents: Pre-empt consolidation pressure from hyperscale platform providers by deepening mainframe identity heritage through targeted acquisition of RACF and ACF2 specialist consultancies in Japan and Germany. Anchor enterprise relationships with zero-trust consulting capabilities that resist pure-play SaaS displacement, while embedding continuous risk assessment engines directly into core architectures to satisfy EU AI Act algorithmic transparency requirements. For New Entrants and Emerging Players: Indian mid-market enterprises represent the most penetrable geography where consumption-based SaaS pricing and rapid deployment timelines outcompete capital-intensive on-premises investments. Target healthcare access certification automation as the whitespace application where AI-assisted access review modules compress HIPAA audit preparation timelines. Pursue channel partnerships with Bengaluru-based IT services firms for seasonal workforce identity lifecycle management. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors vertical specialists with deep workflow expertise over horizontal suite vendors. Long-term viability across the projection horizon favors vendors demonstrating audit preparation compression and explainable access decision engines in financial services and healthcare procurement cycles. Watch for inflection signals in cross-border identity federation pilot adoption between Singapore and Netherlands-based institutions.| Strategic Initiative | Industry Significance |
|---|---|
| Strategic Partnership with Mainframe Specialists | Bridges decades-old RACF and ACF2 expertise with cloud-native development for Japanese banking carriers. |
| Acquisition of Access Certification Workflow Vendor | Secures premium positioning in HIPAA-regulated United States healthcare systems with AI-assisted review modules. |
| Platform Integration with Endpoint Detection Systems | Addresses SOC-identity operations gaps through unified user behavior and device trust correlation. |
| Geographic Expansion into Indian Mid-Market | Captures SaaS consumption growth through channel partnerships with Bengaluru IT services corridors. |
| Product Launch of Algorithmic Transparency Module | Satisfies EU AI Act mandatory documentation requirements for European multinational enterprise procurement. |
Study Parameters
A standing panel of chief information security officers, identity architects, healthcare compliance officers, and federal procurement specialists provided ongoing calibration across primary fieldwork. Secondary validation drew from NIST guidance publications, EU NIS2 Directive implementation texts, HIPAA audit protocol documentation, and hyperscaler identity platform disclosure filings. Bottom-up sizing of deployment model segments triangulated against top-down enterprise IT spending pattern analysis.
Scenario bracketing anchored projections across baseline, accelerated cloud migration, and extended legacy retention pathways. Segmentation modeling spanned solution type, deployment architecture, organization scale, vertical regulatory intensity, and regional mandate enforcement patterns. CAGRs derived from segment-level growth rate reconciliation with aggregate market boundary constraints, incorporating identity governance automation adoption curves and zero-trust infrastructure refresh timelines as industry-specific inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscale platform providers into mainframe integration services would shift outcomes substantially. Quarterly review of federal agency procurement velocity and EU NIS2 Directive penalty enforcement actions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Military Sensors Software Market
Others
Shear Testing Equipment Market
Others
Pin Mills Market
Others
Level Measuring Instrument Market
Others
ISO Cylinder Market
Others
Balsa Wood Market
Others
Czech Republic Market
Others
Asia Pacific Contract Packaging Market
Others
Europe Refrigerated Display Cases Market
Others
Hot Air System Market
Others
Propanil Market
Others
Global Smart Kitchen Market
Others
Gem Faceting Machine Market
Others
Data Center CPU Market
Others
Heavy Duty Vacuum Bottle Market
Others
South America Orange Market