
 Thiamethoxam Market | 2026-2036
Thiamethoxam Market Size, Share, and Industry Trends Forecast 2026-2036
Thiamethoxam Market Analysis
Aftermarket technical support revenue is fragmenting across regional service networks as generic manufacturers erode branded product margins. Syngenta Crop Protection leverages its proprietary Actara and Cruiser formulations to sustain premium positioning in seed treatment channels. BASF SE anchors its competitiveness through backward integration into active ingredient synthesis, while Bayer AG competes via extensive field trial databases that validate performance claims under variable pest pressure.
Thiamethoxam is a second-generation neonicotinoid insecticide with the chemical formula C8H10ClN5O3S, formulated as a systemic compound that translocates through plant vascular tissues to protect against sucking and chewing insects. The liquid formulation segment dominates volume sales due to ease of tank-mixing with fungicides and micronutrients during foliar application windows. Water dispersible granule formulations represent the fastest-expanding category as growers prioritize reduced dust exposure and precise dosing in aerial and ground-based equipment. Agricultural crops occupy the largest application share, though horticultural crops command higher per-hectare pricing due to residue sensitivity in export-oriented fruit and vegetable markets.
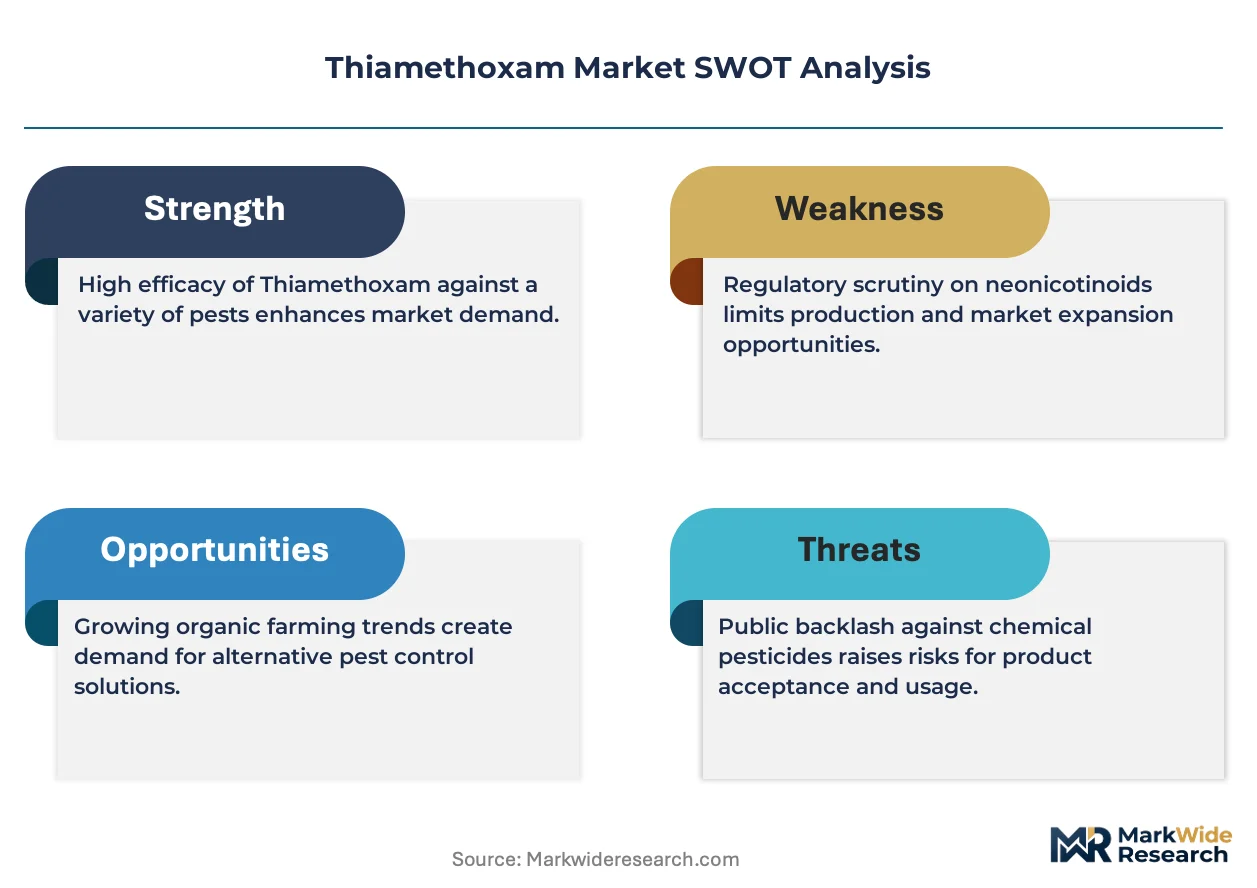
The EPA governs thiamethoxam registration under FIFRA with ongoing pollinator risk assessments, while the EU's REACH framework and F-Gas Regulation constrain neonicotinoid deployment across member states. Brazil's ANVISA and India's CIBRC impose distinct maximum residue limits that shape export-oriented formulation standards and label specifications. Stakeholders must monitor evolving pollinator protection mandates and pre-emptively diversify into combination chemistries or precision delivery systems before regulatory thresholds tighten further.
Market Dynamics
The EU's Farm to Fork strategy is compressing neonicotinoid deployment windows while Brazil's Cerrado soybean belt sustains systemic insecticide demand, creating divergent regulatory-commercial pressures across major agricultural markets.
Growth Catalysts
- Seed treatment expansion:Corn and soybean farmers in Brazil's Mato Grosso state prioritize early-season systemic protection against soil-dwelling pests, driving volume uptake in liquid formulation channels.
- REACH framework adaptations:ECHA's accelerated substance evaluation timeline is forcing manufacturers to pre-emptively submit combination chemistry dossiers, creating first-mover advantages for compliant portfolios.
- Horticultural export premium:Water dispersible granule formulations command price premiums in Chilean grape and Peruvian asparagus operations where residue sensitivity shapes procurement specifications.
Market Restraints
- Active ingredient concentration:Three Chinese manufacturers control over 70 percent of technical-grade thiamethoxam supply, exposing formulators to input cost volatility and quota-driven allocation disruptions.
- Pollinator risk assessment friction:EPA's ongoing FIFRA-mandated pollinator exposure studies are extending registration review cycles, delaying label expansion for foliar application windows in specialty crops.
- Biological substitution pressure:Bacillus thuringiensis-based seed treatments and RNA interference technologies are capturing share in European cereal markets where neonicotinoid bans have taken full effect.
Strategic Opportunities
- Precision delivery systems:Drone-mounted micro-dosing equipment in Australian cotton regions enables targeted thiamethoxam application at 10-20 percent of broadcast rates, opening premium service revenue streams.
- India's CIBRC fast-track pathway:The streamlined registration process for combination chemistries with reduced active ingredient loadings rewards early entrants in rice and vegetable seed treatment segments.
- Carbon credit alignment:Reduced-tillage farming systems in Argentina's Pampas region pair thiamethoxam seed treatments with cover crop protocols qualifying for voluntary carbon market participation.
Industry Challenges
- Residue analytical capacity:Commercial laboratories in Brazil and India face 8-12 week backlogs for maximum residue limit compliance testing, delaying export shipments to EU and Japanese markets.
- Equipment calibration complexity:Ground-based applicators struggle to maintain consistent dosing accuracy across varying tank-mix viscosities when combining thiamethoxam with biological fungicides.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thiamethoxam Market |
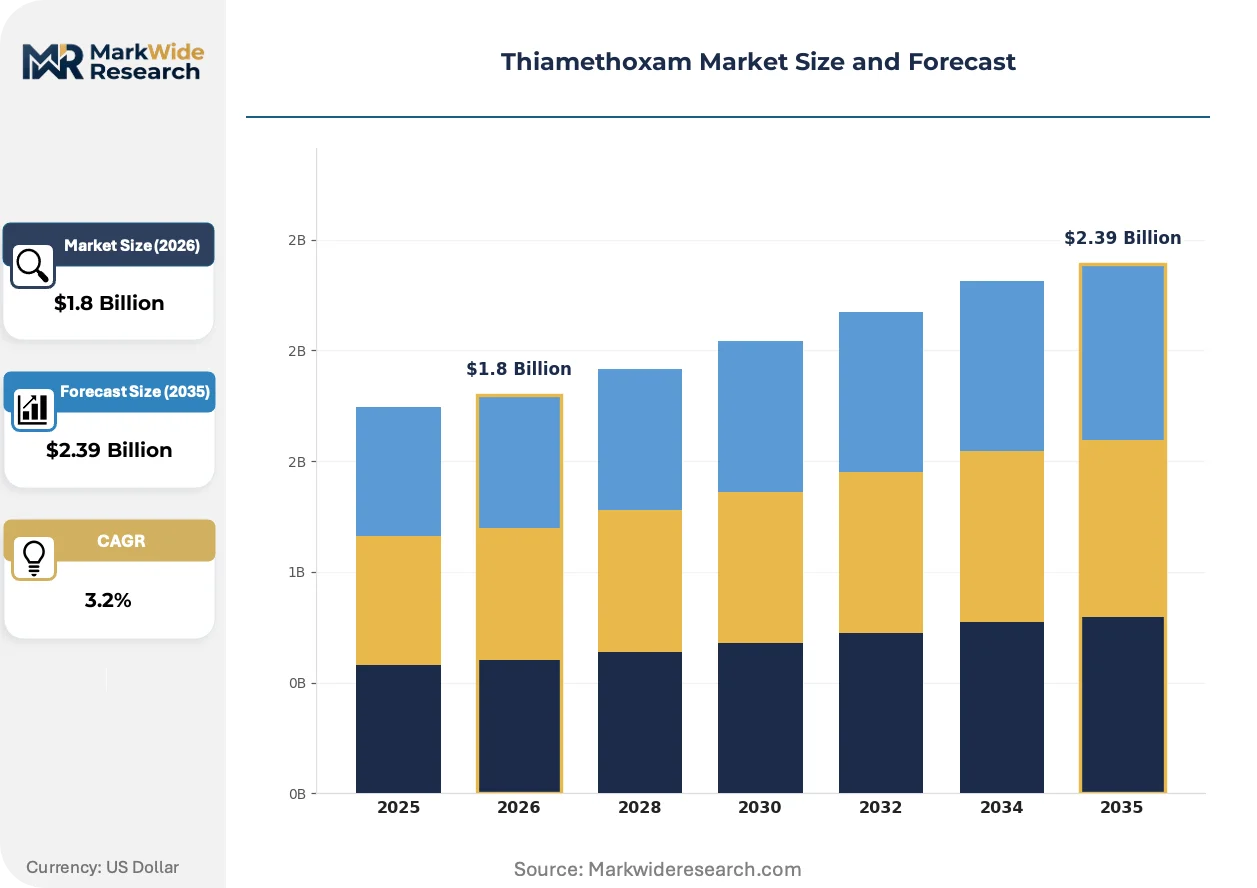
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.39 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granule, Liquid, Powder, Tablet Application: Agricultural Crops, Horticultural Crops, Turf, Ornamentals Formulation: Emulsifiable Concentrate, Suspension Concentrate, Water Dispersible Granule, Others Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Syngenta Crop Protection, BASF SE, Bayer AG, United Phosphorus Limited (UPL), FMC Corporation, Sumitomo Chemical, Corteva, Nufarm, Adama Agricultural Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thiamethoxam Market Emerging Trajectories
Digital agriculture platforms are restructuring how pest management decisions integrate real-time field data, while formulation chemistry advances target operator exposure reduction and environmental fate improvement.
Microencapsulation technology is virtualizing traditional emulsifiable concentrate delivery by embedding thiamethoxam in polymer shells that release active ingredient in response to soil moisture triggers. Large-scale soybean operators in Brazil's Goiás state are piloting these formulations to extend protection windows through variable rainfall patterns. This controlled-release architecture is compressing the frequency of reapplication intervals and reducing total active ingredient load per hectare.
REACH's F-Gas Regulation and accompanying EFSA bee guidance documents are mandating pollinator exposure assessments for all systemic insecticide renewals, extending regulatory timelines by 18-24 months. Formulators are responding by submitting combination product dossiers pairing thiamethoxam with synergists that enable reduced application rates. Specialty crop segments in Southern Europe face the most acute compliance pressure, with Spanish citrus and Italian stone fruit operations accelerating adoption of integrated pest management protocols to satisfy export market residue requirements.
Farmer purchasing cooperatives in the US Corn Belt are consolidating procurement volumes to negotiate direct supply agreements with generic manufacturers, disintermediating traditional distribution channels. These consolidated buying pools now represent 35-40 percent of seed treatment volume in Iowa and Illinois, compressing branded product margins and shifting competitive emphasis toward technical support bundling. The behavioral shift is most visible among operations exceeding 5,000 planted hectares, where procurement committees prioritize total cost of ownership over upfront product pricing.
Thiamethoxam Market Segmentation
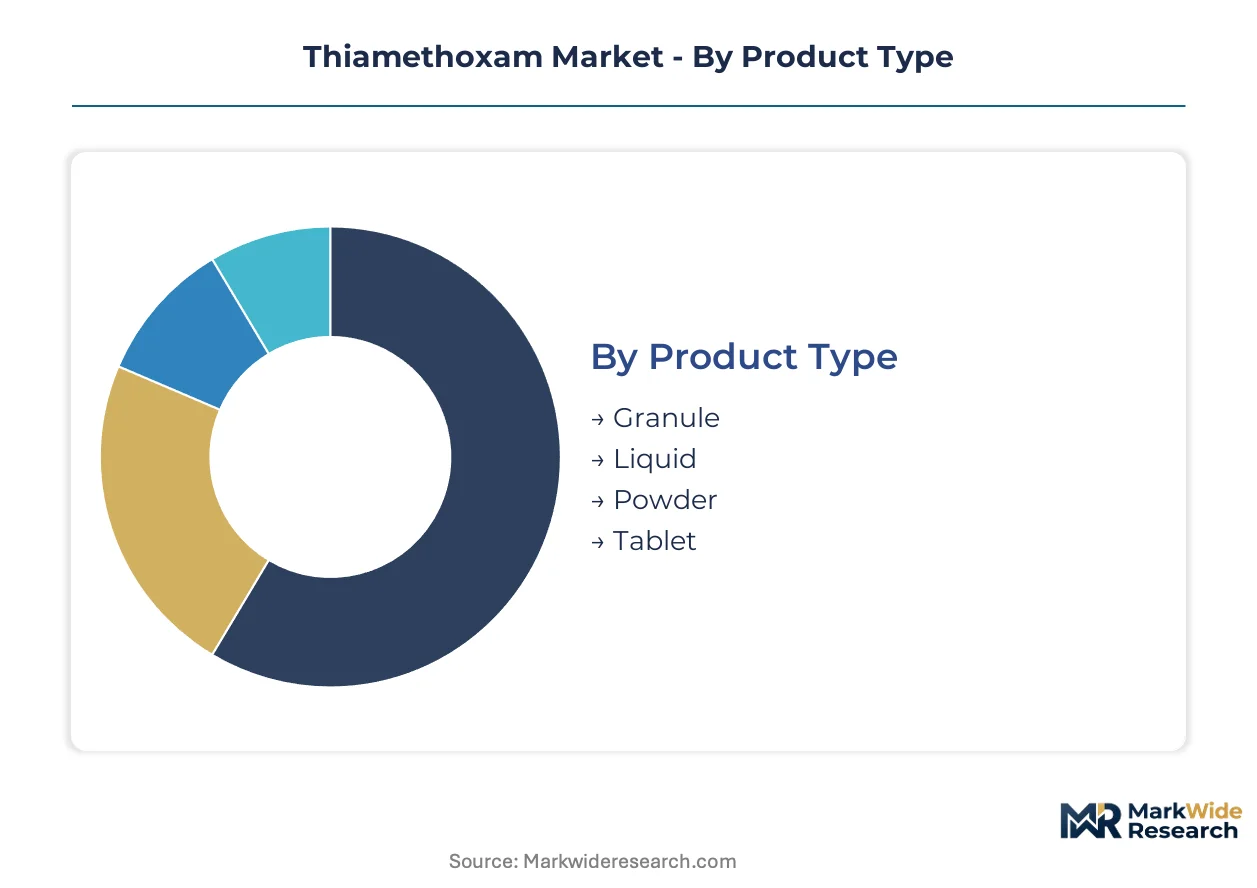
Thiamethoxam formulation choices directly determine application economics, residue compliance windows, and operator safety protocols across divergent cropping systems. Segmentation reveals where technical specification drives procurement decisions versus where channel convenience or regulatory pressure shapes purchasing behavior.
Product Type:
Liquid formulations turn over fastest in high-volume agricultural channels where tank-mixing flexibility matters most, while tablet and granule formats cycle more slowly through specialized horticultural and ornamental segments where precision dosing predominates.
- Liquid:Dominates commercial volume through ease of blending with fungicides and micronutrients during foliar application windows. Brazilian soybean operators in Mato Grosso and Goiás states specify liquid thiamethoxam for aerial application compatibility with existing spray infrastructure.
- Granule:Polymer-coated controlled-release variants extend protection windows through variable rainfall patterns in Australia's cotton belt and Argentina's Pampas region. Soil moisture-triggered release architectures reduce reapplication frequency and total active ingredient load per hectare.
- Powder:Dust-exposure concerns constrain adoption in European markets under REACH occupational safety frameworks, though residual demand persists in manual application contexts across South Asian vegetable operations.
- Tablet:Precision-dosing format commands premium positioning in greenhouse ornamental production and high-value turf maintenance where calibration accuracy outweighs unit cost considerations.
Liquid dominates installed base. Granule is where expansion concentrates.
Application:
Cost tier separation runs deepest here, with agricultural crops optimizing for per-hectare input economics while horticultural and ornamental segments absorb substantial price premiums for residue-sensitive export compliance.
- Agricultural Crops:Corn and soybean seed treatment represents the volume anchor, with Brazil's Cerrado region sustaining systemic insecticide demand despite regulatory scrutiny. Large-scale operations exceeding 5,000 planted hectares prioritize total cost of ownership through consolidated procurement pools.
- Horticultural Crops:Chilean grape and Peruvian asparagus operations specify water dispersible granule formulations to satisfy EU and Japanese maximum residue limits. Per-hectare pricing runs substantially above field crop benchmarks due to analytical compliance burdens and export certification requirements.
- Turf:Golf course and sports field maintenance drives steady demand for liquid formulations compatible with broad-spectrum spray programs, with seasonal application windows concentrated in spring establishment periods.
- Ornamentals:Greenhouse and nursery operations favor tablet and granule formats for reduced operator exposure in enclosed environments, with procurement decisions heavily influenced by ECHA pollinator protection mandates.
Agricultural Crops anchors volume throughput. Horticultural Crops captures the steepest expansion trajectory.
Formulation:
Supply concentration shapes competitive dynamics, with suspension concentrate and water dispersible granule formats requiring more sophisticated manufacturing infrastructure than emulsifiable concentrate alternatives.
- Emulsifiable Concentrate:Traditional solvent-based delivery system faces environmental fate scrutiny under EPA FIFRA assessments. Persists in price-sensitive generic channels where manufacturing simplicity offsets performance limitations.
- Suspension Concentrate:Aqueous dispersion technology enables higher active ingredient loadings with reduced organic solvent content. Syngenta's proprietary Cruiser seed treatment platform leverages this format for extended systemic protection windows.
- Water Dispersible Granule:Reduced dust exposure and precise dosing compatibility with aerial and ground-based equipment drives fastest category expansion. Spanish citrus and Italian stone fruit operations accelerate adoption under EU export residue protocols.
- Others:Microencapsulation and controlled-release variants occupy emerging niche positions, with polymer-shell formulations piloting in Brazilian soybean regions for moisture-responsive release profiles.
Emulsifiable Concentrate retains legacy installed base. Water Dispersible Granule is where formulation innovation concentrates.
Distribution Channel:
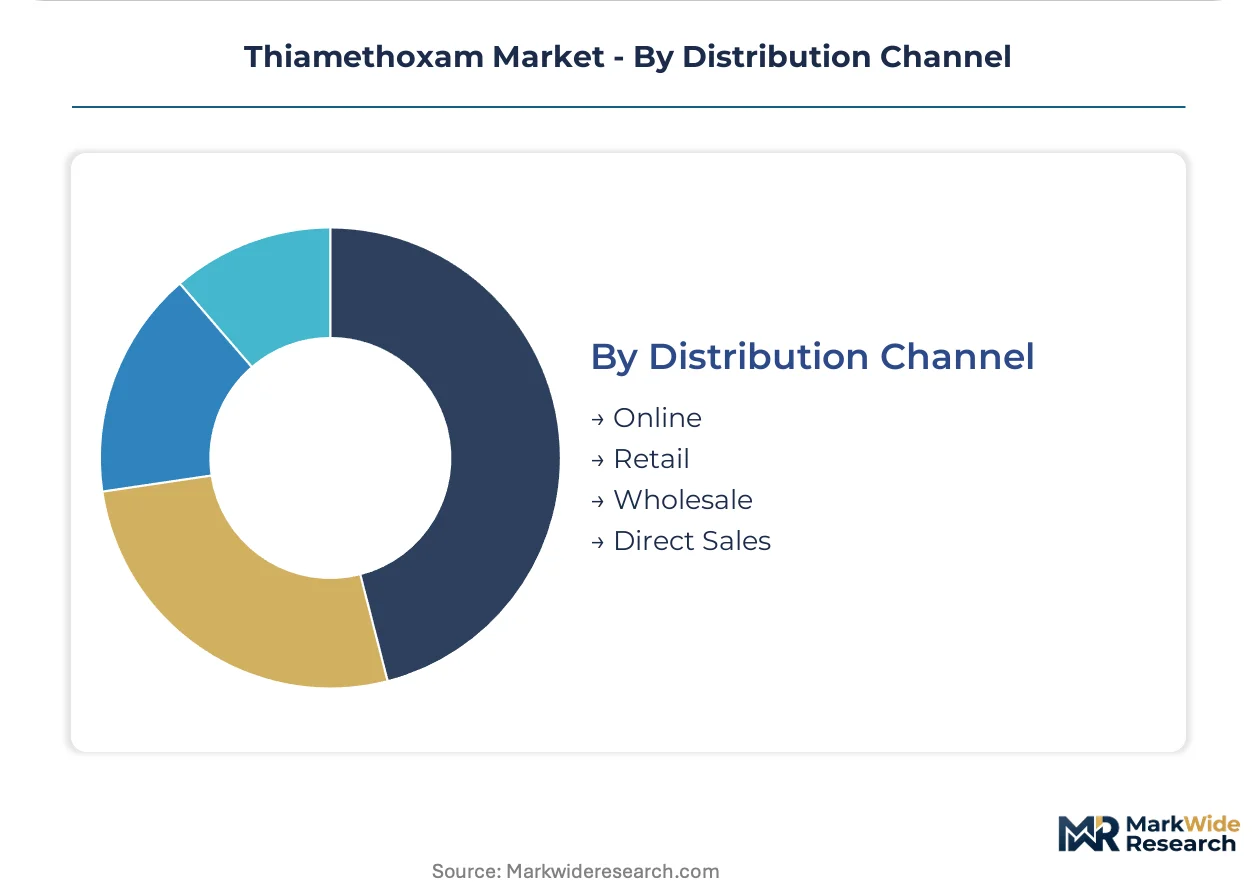
Customer scale and geographic concentration determine channel selection, with consolidated buying pools disintermediating traditional wholesale structures in mature agricultural markets while direct sales penetrate precision-dependent specialty segments.
- Online:Digital procurement platforms gain traction among mid-scale operators in India's CIBRC-regulated rice and vegetable markets, though seed treatment volume remains concentrated in physical channels due to application timing constraints.
- Retail:Farm supply cooperatives and independent dealers serve fragmented smallholder markets across Southeast Asian rice production systems, with technical support bundling differentiating service levels.
- Wholesale:Traditional distributor networks face margin compression as Iowa and Illinois buying pools representing 35-40 percent of seed treatment volume negotiate direct manufacturer agreements.
- Direct Sales:Technical-intensive horticultural and ornamental segments favor manufacturer-direct relationships for calibration support and residue compliance documentation, particularly in EU and Japanese export-oriented operations.
Wholesale retains largest installed base. Direct Sales is where channel restructuring concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil consumes thiamethoxam predominantly through seed treatment channels, while European markets fragment across residue-sensitive horticultural applications and biological substitution pathways. This consumption-mix differential shapes regulatory exposure and margin structures across geographies.
Brazil
Mato Grosso and Goiás states anchor demand through large-scale soybean operations requiring systemic protection against soil-dwelling pests. ANVISA maintains distinct maximum residue limits that shape export-oriented formulation standards for EU-bound shipments. The Cerrado region sustains neonicotinoid deployment despite tightening pollinator scrutiny, with consolidated buying pools now representing substantial procurement volume.
United States
Iowa and Illinois farm cooperatives prioritize total cost of ownership through direct manufacturer agreements, disintermediating traditional wholesale channels. EPA governs registration under FIFRA with ongoing pollinator risk assessments extending review cycles for specialty crop labels. The Corn Belt's consolidated buying pools now capture 35-40 percent of seed treatment volume, compressing branded product margins.
India
Rice and vegetable cultivation in Telangana and Andhra Pradesh drives uptake through CIBRC's streamlined registration pathway for combination chemistries. The central insecticide regulator imposes distinct maximum residue limits that align with export market requirements. Mid-scale operators increasingly adopt digital procurement platforms, though physical channels retain seed treatment dominance due to application timing constraints.
Germany
BASF SE anchors European manufacturing through backward integration into active ingredient synthesis, serving residue-sensitive export markets. ECHA's REACH framework and accompanying F-Gas Regulation constrain neonicotinoid deployment while accelerating substance evaluation timelines. The country's industrial base supplies combination chemistry dossiers that enable reduced application rates for compliant portfolios.
China
Technical-grade production concentrates among manufacturers supplying over 70 percent of global active ingredient, exposing formulators to quota-driven allocation disruptions. The Ministry of Ecology and Environment oversees environmental fate assessments under evolving dual carbon goals. Shandong and Jiangsu provinces host the primary synthesis clusters where capacity expansion responds to Brazilian and Indian formulation demand.
Thiamethoxam Market Vendor Landscape
Capability concentration sits with integrated active ingredient manufacturers; scale advantage sits with broad-portfolio agrochemical conglomerates. The market structures around three tiers: proprietary formulation specialists commanding premium seed treatment channels, generic manufacturers eroding margins through price-competitive supply, and regional distributors consolidating procurement volumes. Dominant competitive moves include backward integration into technical-grade synthesis and technical support bundling to defend positioning against procurement disintermediation.
Among the integrated formulation tier, Syngenta Crop Protection, BASF SE, and Bayer AG occupy positions defined by proprietary chemistry platforms and field trial databases. Syngenta leverages its Actara and Cruiser formulations to sustain premium positioning. BASF anchors competitiveness through captive supply of active ingredients. Bayer competes via extensive performance validation under variable pest pressure. These three represent distinct archetypes: the proprietary platform defender, the vertically integrated manufacturer, and the data-validated claim substantiator.
| Leading Market Players |
|---|
| Syngenta Crop Protection |
| BASF SE |
| Bayer AG |
| United Phosphorus Limited (UPL) |
| FMC Corporation |
| Sumitomo Chemical |
| Corteva |
| Nufarm |
| Adama Agricultural Solutions |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Chinese technical-grade manufacturers determines both the compression of generic pricing tiers and the elongated procurement timelines facing Brazilian and Indian formulators. This concentration risk feeds directly into three-tier pricing stratification across premium proprietary seed treatments, standard combination chemistries, and economy generic channels.
Pricing Analysis
Long-term offtake agreements between Brazilian buying pools and generic manufacturers anchor volume pricing, while spot procurement persists for urgent foliar application windows in Australian cotton regions. Price differentiation rests on formulation sophistication—water dispersible granules command substantial premiums over emulsifiable concentrates—and backward integration into active ingredient synthesis. Pricing pressure intensifies in standard-tier channels as Iowa and Illinois cooperatives consolidate procurement volumes. Smallholder vegetable operators in South Asia exhibit highest price sensitivity, while EU horticultural exporters absorb premium-tier costs to satisfy residue compliance mandates.
Supply Chain Analysis
Upstream feedstock synthesis concentrates in Shandong and Jiangsu provinces, where three manufacturers supply the majority of technical-grade thiamethoxam for global formulation. This geographic concentration draws from 2-chloro-5-chloromethylthiazole and 3-methyl-4-nitroimino-perhydro-1,3,5-oxadiazine feedstocks, both subject to environmental quota restrictions under China's dual carbon goals. Single-source vulnerability exposes formulators to allocation disruptions during peak planting seasons. Distribution runs through regional distributor networks in mature markets, with direct manufacturer agreements displacing wholesale channels in the US Corn Belt and Brazilian Cerrado.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The thiamethoxam market sits in early-cycle expansion as precision delivery systems and microencapsulation technologies penetrate Brazilian soybean operations, extending protection windows while reducing per-hectare active ingredient loads.
For Market Incumbents: Harden proprietary formulation positioning through accelerated dossier submissions for combination chemistries under ECHA's REACH framework, preempting regulatory compression windows. Deepen captive supply of active ingredients to insulate margin structures from Chinese quota volatility. Defend seed treatment channels against generic disintermediation by bundling technical calibration support with residue compliance documentation. For New Entrants and Emerging Players: India's CIBRC fast-track pathway for reduced-loading combination chemistries offers the most penetrable entry vector, particularly in rice and vegetable segments where digital procurement platforms are gaining traction. Target precision-dosing tablet formats for greenhouse ornamental operations under ECHA pollinator protection mandates. Pursue go-to-market partnerships with drone service providers in Australian cotton regions to establish micro-dosing service revenue streams. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors backward-integrated manufacturers with combination chemistry pipelines. Long-term viability hinges on regulatory adaptability across divergent EU and Brazilian frameworks. Acquisition targets should demonstrate REACH-compliant dossier portfolios and established field trial databases. Monitor EPA pollinator risk assessment timelines as the critical inflection signal for foliar application label expansions in specialty crops.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Ingredient Synthesis | BASF SE's captive supply model insulates margin structures from Chinese quota-driven allocation disruptions. |
| Combination Chemistry Dossier Submission | Preemptive REACH compliance investments create first-mover positioning as ECHA accelerates substance evaluation timelines. |
| Precision Delivery System Deployment | Drone-mounted micro-dosing in Australian cotton regions enables service revenue at reduced application rates. |
| Direct Procurement Pool Negotiation | Iowa and Illinois buying pools now capture substantial seed treatment volume, compressing traditional wholesale margins. |
| Microencapsulation Formulation Development | Moisture-triggered release architectures in Brazil's Goiás state extend protection windows through variable rainfall patterns. |
Methodological Framework
Initial hypotheses were tested against primary input from agrochemical R&D directors, Brazilian procurement committee members, EU regulatory affairs specialists, and Indian distributor network managers, then refined through secondary validation. Trade data from customs authorities, ECHA substance evaluation databases, EPA FIFRA registration filings, and ANVISA residue limit specifications provided cross-reference anchors. Bottom-up volume estimates from seed treatment application rates and top-down value reconstructions from manufacturer revenue disclosures were triangulated for consistency.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation modeled across formulation type, application crop category, and regional regulatory cluster. CAGRs were derived from trend extrapolation of planted acreage, treatment adoption rates, and per-hectare active ingredient loadings. Key forecast inputs included EPA pollinator risk assessment timelines and Brazilian Cerrado expansion projections for soybean cultivation.
Practitioners should monitor ECHA substance evaluation acceleration and Chinese environmental quota enforcement for early signals of supply constraint or regulatory compression. Forecasts reflect assumptions regarding continued neonicotinoid deployment in Brazil and gradual biological substitution in EU cereal markets. Cross-checking against customs trade flow data and manufacturer capacity announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Duty Free Retail Market
Others
Nuclear Power Cables Market
Others
Linseed Oil Market
Others
Middle East and Africa Cocoa Products Market
Others
Level Measuring Instrument Market
Others
Heavy Duty Traps Market
Others
Conditional Access System (CAS) Market
Others
One-Way Degassing Valve Market
Others
Bitcoin Mining Servers Market
Others
Air Separation Module Kit Market
Others
Asia-Pacific Agricultural Enzymes Market
Others
Biopharma Plastics Market
Others
Sports Events Market
Others
Textile Composites Market
Others
AI In Government And Public Services Market
Others
Lepidolite Market