
 5G Devices Market | 2026-2036
5G Devices Market Size, Share, and Industry Trends Forecast 2026-2036
5G Devices Market Outlook
3GPP Release 17 certification is bifurcating vendor access between established chipset suppliers and newer entrants struggling with conformance testing timelines. Samsung Electronics Co., Ltd. leverages its captive semiconductor fabrication to sustain modem supply security for premium smartphone tiers. Qualcomm Incorporated anchors the premium Android ecosystem through integrated RF front-end platforms that reduce OEM design complexity. Huawei Technologies Co., Ltd. competes primarily in domestic Chinese infrastructure despite export control limitations on advanced node silicon.
5G devices encompass subscriber equipment and network termination hardware operating across sub-6 GHz and millimeter-wave spectrum allocations, with modem architectures integrating baseband processors, RF transceivers, and antenna arrays to achieve theoretical peak downlink rates exceeding 10 Gbps in ideal channel conditions. Smartphones dominate absolute shipment volumes while mmWave-enabled enterprise routers command substantially higher average selling prices due to beamforming complexity and thermal management requirements. Sub-6 GHz deployment leads in geographic coverage breadth, though standalone 5G core migration is accelerating latency-sensitive industrial applications.
The FCC governs spectrum licensing and device authorization through its Equipment Authorization Program, while the EU AI Act and Radio Equipment Directive impose cybersecurity and interoperability mandates on connected hardware sold within member states. China's MIIT enforces domestic type approval and GB standards compliance that foreign manufacturers must satisfy through designated testing laboratories. Stakeholders should monitor spectrum reallocation proceedings and open RAN interface standardization as these forces will determine which silicon architectures retain pricing power in next-generation baseband procurement decisions.
Market Dynamics
Standalone 5G core migration is compressing latency thresholds for industrial automation, forcing modem vendors to prioritize real-time processing capabilities over peak throughput metrics in their silicon roadmaps.
Growth Catalysts
- Smart Manufacturing Adoption:Industrial IoT deployments in automotive and electronics assembly lines require sub-10 millisecond latency that only 5G standalone networks deliver, driving enterprise router procurement cycles.
- FCC Spectrum Auctions:Mid-band reallocation in the United States has expanded contiguous channel access for fixed wireless access equipment, accelerating rural broadband substitution for fiber-to-the-home.
- China Handset Replacement:Domestic base station density in tier-1 cities now supports consistent millimeter-wave coverage, triggering consumer upgrade waves for compatible smartphones.
Market Restraints
- Advanced Node Silicon Concentration:Sub-7 nanometer fabrication for premium modems relies on a concentrated foundry base in Taiwan, creating supply vulnerability from geopolitical friction or natural disaster.
- Millimeter-Wave Thermal Costs:Beamforming antenna arrays require gallium nitride power amplifiers and complex heat dissipation systems that inflate bill-of-materials costs by 40-60 percent versus sub-6 GHz equivalents.
- EU Cybersecurity Certification:The Radio Equipment Directive's delegated acts impose extended testing timelines for network termination hardware, delaying market entry by six to nine months for non-EU vendors.
Strategic Opportunities
- India Industrial Corridors:The country's PLI scheme for telecom equipment manufacturing creates localized assembly incentives for 5G private networks in Gujarat and Tamil Nadu industrial zones.
- Open RAN Interface Standardization:O-RAN Alliance specifications are fragmenting baseband procurement, creating entry points for specialized modem vendors to supply disaggregated radio units.
- Automotive V2X Convergence:Integration of 5G NR-V2X with edge computing platforms enables vehicle-to-infrastructure coordination for autonomous logistics fleets in German autobahn corridors.
Industry Challenges
- RF Engineering Talent Scarcity:Millimeter-wave antenna design and beam management algorithm development require specialized expertise concentrated among legacy base station vendors, constraining new entrant hiring.
- 3GPP Release 17 Conformance:Extended certification timelines at designated testing laboratories are creating backlog bottlenecks for modem vendors seeking multi-band interoperability approval.
- Legacy 4G Core Integration:Non-standalone deployment architectures demand backward compatibility testing across heterogeneous network equipment generations, complicating operator migration strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Devices Market |
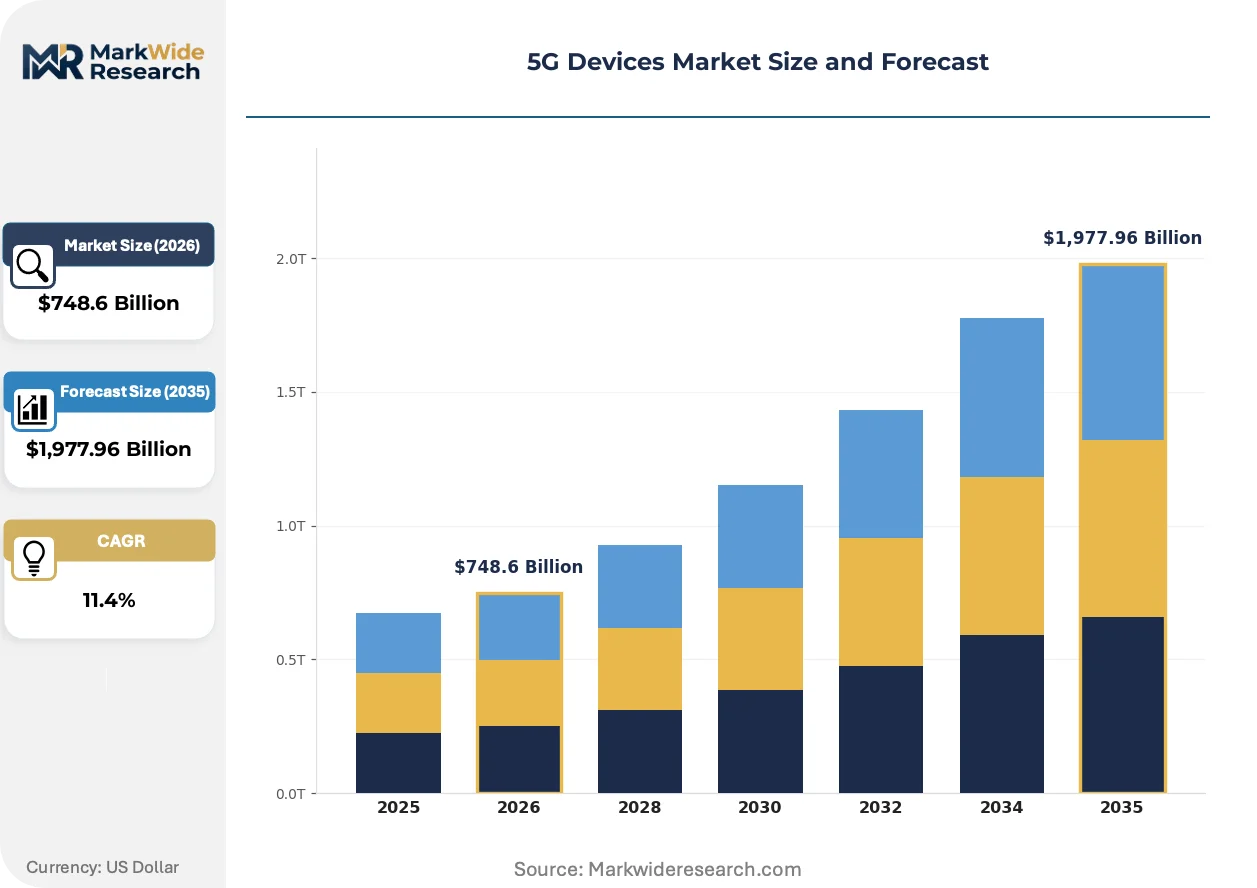
| Market Size in 2026 | $748.6 Billion |
| Market Size in 2035 | $1,977.96 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Routers, Mi-Fi Devices, Tablets Technology: Standalone 5G, Non-Standalone 5G, mmWave, Sub-6 GHz End User: Consumers, Enterprises, Government, Industrial Deployment: On-Premises, Cloud-Based, Edge Computing, Hybrid |
| Companies Covered | Samsung Electronics Co., Ltd., Apple Inc., Huawei Technologies Co., Ltd., Qualcomm Incorporated, MediaTek Inc., Intel Corporation, LG Electronics Inc., Motorola Solutions, Inc., ZTE Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Devices Market Strategic Shifts
Silicon integration density and regulatory fragmentation are simultaneously compressing device form factors and expanding compliance scope, reshaping how vendors architect modem platforms for divergent geographic requirements.
Integrated RF front-end modules are consolidating power amplifiers, filters, and switches into single-package solutions that reduce printed circuit board footprint for smartphone OEMs. Premium handset manufacturers in South Korea and China are adopting these modules at volume scale to enable larger battery cells within unchanged chassis dimensions. The structural consequence is that discrete component suppliers are losing socket share to platform-integrated solutions, and the technology is miniaturizing antenna clearance requirements to sub-3 millimeter tolerances.
The EU AI Act's risk classification framework now captures 5G network equipment with embedded machine learning for traffic optimization, imposing conformity assessment obligations previously limited to medical devices. Hardware vendors must document algorithmic transparency and data governance protocols to maintain CE marking eligibility. Network termination equipment with autonomous beam-steering capabilities faces the strictest scrutiny, prompting some suppliers to strip AI features from European SKUs rather than absorb compliance costs.
Enterprise buyers are consolidating procurement authority for private 5G networks from IT departments into operational technology leadership, reflecting convergence between factory automation and connectivity infrastructure. System integrators are displacing traditional value-added resellers in Germany and Japan as the primary channel for industrial router deployment. This shift is most visible in automotive manufacturing, where production line engineers now specify latency requirements directly in equipment tenders rather than delegating to telecommunications procurement teams.
5G Devices Market Segmentation
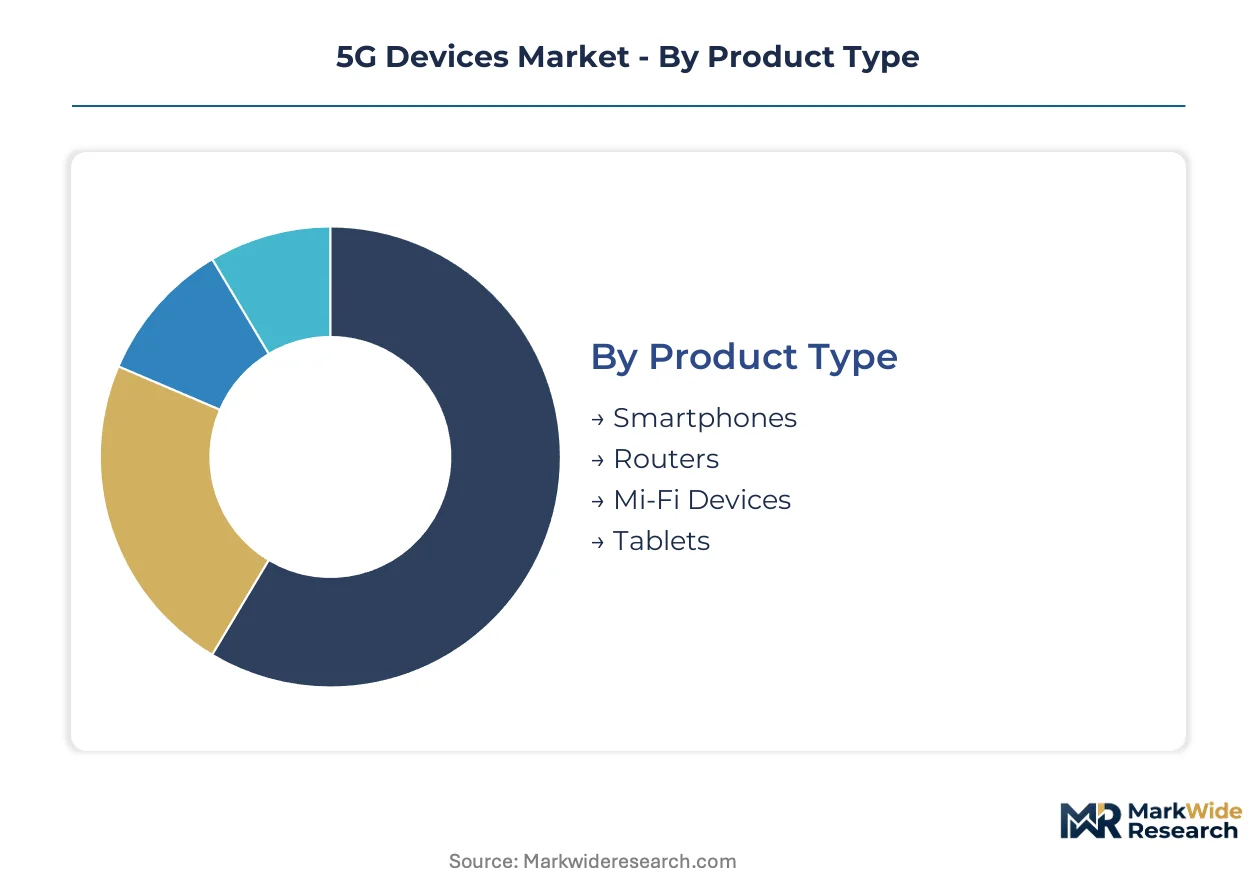
5G device segmentation reveals divergent growth trajectories across connectivity architectures and buyer categories. Procurement patterns in industrial automation differ fundamentally from consumer handset cycles, creating distinct margin profiles within each segment cluster.
Product Type:
Smartphones dominate absolute shipment volumes with concentrated production in Chinese and South Korean manufacturing clusters, while enterprise routers command premium pricing through specialized thermal engineering.
- Smartphones:Integrated modem-RF platforms power these devices with sub-6 GHz and mmWave variants differentiated by antenna complexity. Replacement cycles in Chinese tier-1 cities accelerate as domestic base station density enables consistent millimeter-wave coverage, triggering upgrade waves for compatible handsets.
- Routers:Enterprise-grade hardware incorporates beamforming antenna arrays and gallium nitride power amplifiers for industrial environments. German automotive manufacturers specify sub-10 millisecond latency requirements directly in equipment tenders, bypassing traditional telecommunications procurement teams.
- Mi-Fi Devices:Portable hotspots serve mobile broadband substitution in rural United States markets where FCC mid-band reallocation expanded fixed wireless access deployment.
- Tablets:Larger form factors accommodate higher-gain antenna configurations for field service applications in Japanese construction and logistics sectors.
Smartphones command the established base. The steepest expansion runs through routers.
Technology:
Silicon roadmaps prioritize real-time processing capabilities in standalone architectures while non-standalone deployments retain backward compatibility burdens.
- Standalone 5G:Core network independence enables network slicing and ultra-reliable low-latency communication for industrial automation. Automotive assembly lines in Stuttgart and Wolfsburg require these capabilities for robotic coordination, forcing modem vendors to compress processing thresholds.
- Non-Standalone 5G:LTE anchor dependency simplifies initial deployment but complicates operator migration strategies across heterogeneous equipment generations. Legacy 4G core integration demands extensive interoperability testing at designated certification laboratories.
- mmWave:Beamforming complexity and thermal management requirements inflate bill-of-materials costs substantially versus sub-6 GHz equivalents, constraining adoption to premium tiers and dense urban corridors.
- Sub-6 GHz:Broader geographic coverage and simpler RF engineering enable volume scaling across mid-market smartphone tiers and rural broadband equipment.
Non-Standalone 5G anchors current installed capacity. Standalone 5G climbs the fastest as industrial use cases mature.
End User:
Procurement authority consolidation from IT departments into operational technology leadership reshapes vendor engagement models across buyer categories.
- Consumers:Individual purchasers respond to carrier subsidy structures and handset replacement cycles, with Chinese domestic demand outpacing other national markets through accelerated base station rollout.
- Enterprises:Private 5G network deployments in Gujarat and Tamil Nadu industrial zones benefit from India's PLI scheme for telecom equipment manufacturing, creating localized assembly incentives.
- Government:Public sector tenders emphasize cybersecurity certification under EU Radio Equipment Directive delegated acts, extending testing timelines for non-EU vendors.
- Industrial:Factory automation buyers specify latency requirements directly in equipment procurement, displacing traditional value-added resellers with system integrators in German and Japanese markets.
Consumers anchor shipment volumes. Industrial buyers gain share fastest as operational technology convergence accelerates.
Deployment:
Edge computing architectures fragment infrastructure procurement between hyperscale cloud providers and specialized on-premises integrators.
- On-Premises:Dedicated hardware installations serve latency-sensitive manufacturing environments where data sovereignty requirements preclude cloud migration.
- Cloud-Based:Centralized network management platforms simplify multi-site enterprise deployments but introduce dependency on connectivity resilience.
- Edge Computing:Distributed processing nodes enable vehicle-to-infrastructure coordination for autonomous logistics fleets in German autobahn corridors, integrating 5G NR-V2X with localized computation.
- Hybrid:Mixed architectures balance real-time processing requirements with centralized analytics, common in smart manufacturing deployments with heterogeneous legacy systems.
On-premises deployment anchors industrial reliability requirements. Edge computing expands most quickly as automotive and logistics applications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial automation buyers concentrate procurement authority in operational technology leadership, creating divergent demand profiles across manufacturing corridors. Equipment tenders now specify latency thresholds directly, bypassing traditional telecommunications teams. This shift concentrates vendor engagement in automotive and electronics assembly zones.
United States
FCC mid-band reallocation expanded contiguous channel access for fixed wireless access equipment, accelerating rural broadband substitution. The Equipment Authorization Program governs device certification timelines. Manufacturing demand clusters in Detroit automotive corridors and Austin semiconductor fabrication zones.
China
Domestic base station density in tier-1 cities now supports consistent millimeter-wave coverage, triggering consumer upgrade cycles. MIIT enforces GB standards compliance through designated testing laboratories. Shenzhen and Dongguan electronics manufacturing clusters anchor global smartphone production volumes.
Germany
Automotive assembly lines in Stuttgart and Wolfsburg require sub-10 millisecond latency for robotic coordination, forcing standalone 5G procurement. The EU Radio Equipment Directive imposes cybersecurity mandates on network termination hardware. Bavarian industrial zones lead private network deployment for automotive tier-1 suppliers.
Japan
Construction and logistics sectors in Tokyo and Osaka drive tablet procurement for field service applications. METI standards shape domestic type approval requirements. Nagoya automotive corridors integrate 5G NR-V2X with edge computing for autonomous logistics coordination.
India
PLI scheme incentives for telecom equipment manufacturing attract localized assembly for private 5G networks. TRAI spectrum allocation policies shape deployment economics. Gujarat and Tamil Nadu industrial zones concentrate system integrator activity for factory automation buyers.
5G Devices Market Competitive Environment
Player mix skews toward integrated platform vendors with captive semiconductor fabrication capabilities. Market structure concentrates around three to five vertically integrated suppliers controlling premium modem silicon and RF front-end integration. Strategic archetypes include captive foundry operators, fabless chipset designers with RF platform dominance, and domestic infrastructure specialists serving restricted geographies. Competitive moves center on RF front-end module consolidation and geographic diversification of assembly capacity.
Within the integrated platform tier, Samsung Electronics Co., Ltd. and Qualcomm Incorporated exemplify divergent approaches to modem-RF integration. Samsung leverages captive fabrication for supply security in premium smartphone tiers. Qualcomm anchors the premium Android ecosystem through design complexity reduction for OEM partners. Huawei Technologies Co., Ltd. occupies a distinct position shaped by export control limitations on advanced node access.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| Apple Inc. |
| Huawei Technologies Co., Ltd. |
| Qualcomm Incorporated |
| MediaTek Inc. |
| Intel Corporation |
| LG Electronics Inc. |
| Motorola Solutions, Inc. |
| ZTE Corporation |
| Others |
Value Chain & Pricing Dynamics
Gallium nitride power amplifiers replacing silicon LDMOS in millimeter-wave beamforming arrays simultaneously shifts procurement geography toward Taiwanese and South Korean foundries while compressing gross margins through 40-60 percent bill-of-materials inflation versus sub-6 GHz equivalents. This substitution dynamic concentrates pricing power among captive-fabrication vendors while forcing sub-tier suppliers into cost-absorption strategies.
Pricing Analysis
Cost-plus contracts with gallium nitride wafer indexation dominate enterprise router procurement, insulating tier-1 vendors from spot price volatility while exposing mid-tier suppliers to margin compression. Three-tier pricing structure across premium, standard, and economy levels stratifies by thermal management complexity and certification grade, with EU Cybersecurity Act compliance adding six-to-nine-month delays that inflate European SKUs. Pricing pressure stems from Chinese domestic handset replacement saturation compressing Android ecosystem premiums. Industrial buyers in German automotive corridors exhibit lowest price sensitivity due to latency-specified tenders, while rural fixed wireless access purchasers in the United States face highest elasticity.
Supply Chain Analysis
Inventory cycles for RF front-end modules now stretch fourteen to twenty weeks as sub-7 nanometer modem silicon concentrates in Taiwanese and South Korean fabrication facilities. Raw material dependencies center on gallium nitride substrates, high-frequency laminates, and advanced packaging resins sourced from Japanese and German specialty chemical suppliers. Single-source vulnerability in extreme ultraviolet lithography equipment creates chokepoint exposure for advanced node migration. Distribution runs through consolidated electronics manufacturing service providers in Shenzhen and Dongguan for smartphone volumes, while enterprise routers deploy through system integrators in Stuttgart and Nagoya.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 5G devices market sits at a platform-economics inflection where O-RAN Alliance interface specifications fragment baseband procurement, creating interoperability arbitrage opportunities for specialized modem vendors against integrated incumbents.
For Market Incumbents: Shield premium modem socket share by accelerating captive fabrication capacity in South Korea and Vietnam ahead of potential Taiwan Strait disruption. Deepen backward integration into RF filter design to offset discrete component supplier erosion. Prioritize 3GPP Release 17 pre-certification investments to compress testing laboratory bottlenecks that currently delay market entry. For New Entrants and Emerging Players: Lead with disaggregated radio unit supply for Indian PLI scheme beneficiaries in Gujarat and Tamil Nadu industrial corridors, where localized assembly incentives reduce incumbent cost advantages. Target private 5G network deployments in Japanese construction and logistics sectors where tablet form factors accommodate higher-gain antenna configurations underserved by smartphone-centric platforms. Pursue direct operational technology engagement models that bypass traditional IT procurement channels. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized RF engineering boutiques with millimeter-wave beam management algorithm expertise. Long-term viability hinges on silicon architecture transitions toward standalone 5G core migration rather than non-standalone legacy compatibility burdens. Watch for inflection in FCC spectrum reallocation proceedings that would redirect fixed wireless access equipment demand toward mid-band rather than millimeter-wave deployment.| Strategic Initiative | Industry Significance |
|---|---|
| RF Front-End Module Consolidation | Single-package integration reduces PCB footprint for South Korean and Chinese premium handset OEMs. |
| Captive Fabrication Geographic Diversification | Vietnam and South Korea capacity additions mitigate Taiwan concentration risk for advanced node silicon. |
| O-RAN Alliance Certification Investment | Disaggregated radio unit interoperability opens procurement channels outside integrated platform vendors. |
| EU Cybersecurity Act Pre-Compliance | Early conformity assessment preserves CE marking eligibility for network termination hardware with embedded AI. |
| Operational Technology Channel Development | Direct factory automation engagement displaces traditional value-added resellers in German automotive corridors. |
Study Parameters
Operator-level perspectives from network equipment procurement officers, semiconductor fabrication planners, RF engineering directors, and private 5G system integrators anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through FCC Equipment Authorization Program filings, MIIT GB standards documentation, 3GPP release specifications, and SEC semiconductor capex disclosures. Bottom-up shipment modeling by device category triangulated against top-down spectrum allocation and base station deployment data.
Sensitivity analysis tested forecast robustness across standalone versus non-standalone 5G migration scenarios, gallium nitride cost trajectories, and regulatory timeline variations throughout the projection horizon. Segmentation dimensions modeled include product architecture, connectivity technology, end-user category, and deployment topology alongside regional regulatory cluster differentiation. CAGRs derived from install-base replacement cycles, industrial automation penetration curves, and carrier subsidy elasticity parameters.
The analysis sits within stated boundaries; outcomes outside sustained mid-band spectrum reallocation, stable Taiwan fabrication capacity, or accelerated EU cybersecurity certification timelines would require recalibration. Forecasts reflect documented assumptions regarding 3GPP conformance testing throughput and open RAN commercialization velocity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Africa Smart Card Market
Others
Mexico 3D Printing Construction Market
Others
Pet Care Packaging Market
Others
Couscous Market
Others
Smart Card Market
Others
Digital Thermal Plates Market
Others
High Frequency Vibrator Market
Others
Convertible Shipper Display Market
Others
North America Thermoformed Plastics Market
Others
Global Military Wearable Sensors Market
Others
Mobile Computer Market
Others
Communication Base Station Body Market
Others
Reduced-Risk Products (Rrps) Market
Others
Gas Holders Market
Others
Smart Electric Curtain Market
Others
Brazil Passenger Vehicles Lubricants Market