
 France 3D Printing Construction Market | 2026-2036
France 3D Printing Construction Market Size, Share, and Industry Trends Forecast 2026-2036
France 3D Printing Construction Market Insights
Modular prefabrication of printed wall assemblies is rebalancing procurement patterns among French construction buyers. XtreeE leverages its proprietary gantry systems to dominate large-scale concrete printing for social housing prototypes. COBOD International A/S anchors the equipment supply layer through distributor partnerships with regional contractors. Vinci sustains technology leadership by integrating printed elements into its own project pipelines rather than relying solely on external vendors.
France 3D printing construction encompasses additive manufacturing processes that deposit concrete, polymer, metal, or composite materials layer-by-layer to form structural or architectural components, typically using gantry or robotic arm systems with build volumes exceeding 10 cubic meters and layer heights of 10-50 millimeters. The primary purpose is to reduce formwork waste, accelerate on-site assembly, and enable complex geometries impractical with conventional cast-in-place methods. Concrete printing occupies the dominant share of current project value given its suitability for load-bearing walls and foundation elements, while polymer printing sustains faster growth in non-structural cladding and insulation modules where thermal performance requirements drive specification. Extrusion technology leads installed equipment counts due to lower capital barriers and mature material supply chains, though powder bed fusion competes in metal connector and reinforcement niche applications where geometric precision commands premium positioning.
France's national building regulator enforces structural safety verification through CSTB technical assessments, while the EU Green Deal's embodied carbon thresholds reshape material selection criteria for public procurement. ANSM and CNIL oversight extends to occupational health data collection on construction sites deploying automated printing equipment. Stakeholders must monitor evolving CSTB certification pathways for novel cementitious formulations and decide whether to build in-house printing capability or contract through specialized fabricators as project scales diversify.
Market Dynamics
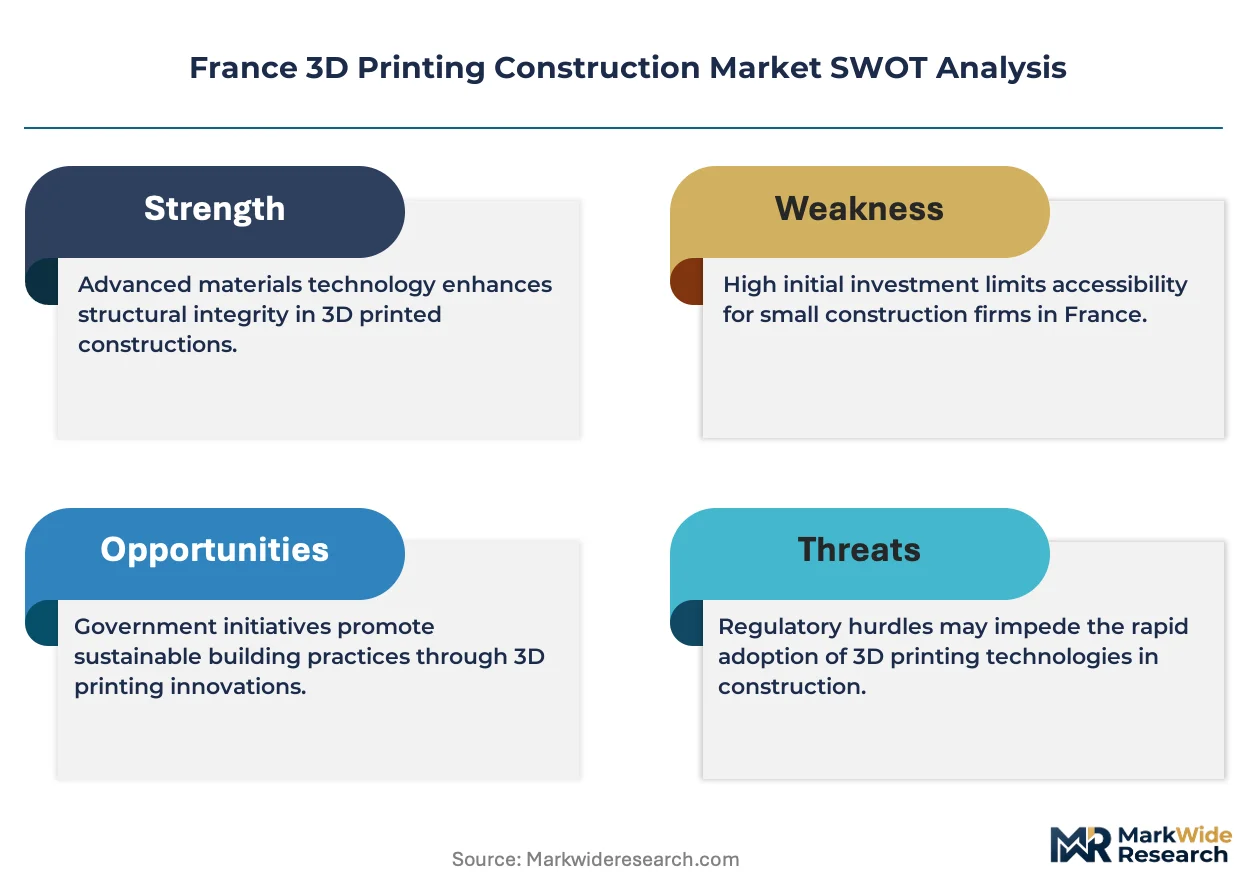
France's construction additive manufacturing sector is compressing project delivery timelines through the substitution of cast-in-place concrete with printed structural elements, a shift reinforced by CSTB certification pathways for novel cementitious formulations and EU Green Deal embodied carbon thresholds.
Growth Catalysts
- EU Green Deal embodied carbon thresholds:Public procurement mandates in Île-de-France and Auvergne-Rhône-Alpes accelerate specification of low-cement geopolymer mixes for load-bearing printed walls.
- Social housing prototypes:Municipalities in Lyon and Paris validate structural performance through public-private demonstration projects, reducing buyer risk perception among residential developers.
- Gantry system maturation:Extrusion equipment with build volumes exceeding 500 cubic meters now achieves layer-height precision of 10-20 millimeters, enabling foundation and wall-panel fabrication at commercial scale.
Market Restraints
- Cementitious input cost volatility:Geopolymer binder formulations depend on fly ash and slag supply concentrated in northern France industrial corridors, exposing fabricators to energy-intensive material price swings.
- CSTB certification timeline friction:Novel concrete admixtures require 18-24 month technical assessment cycles, delaying project commissioning for developers targeting public-sector contracts.
- Powder bed fusion equipment concentration:Metal reinforcement printing for structural connectors relies on imported laser sintering systems, creating spare parts and maintenance dependency on non-EU supply chains.
Strategic Opportunities
- Occitanie underpenetration:Toulouse and Montpellier metropolitan zones lack established 3D printing construction clusters, offering first-mover positioning for regional contractors before CSTB certification density increases.
- Retrofit application expansion:Printed facade cladding modules address thermal renovation mandates in 1970s housing stock, opening non-structural revenue streams with shorter sales cycles than ground-up construction.
- CNIL-compliant site data monetization:Automated printing equipment generates real-time material flow telemetry that construction firms can license to cement suppliers for mix optimization, pending occupational health data governance alignment.
Industry Challenges
- Robotic systems integration expertise scarcity:French construction labor pools lack technicians trained in gantry calibration and extrusion nozzle maintenance, forcing contractors to import specialized crews from Belgium and Germany at premium rates.
- Legacy BIM-to-print workflow incompatibility:Standard architectural software outputs require manual translation for slicer programs used by concrete extrusion systems, introducing errors and revision cycles that compress already-tight project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France 3D Printing Construction Market |
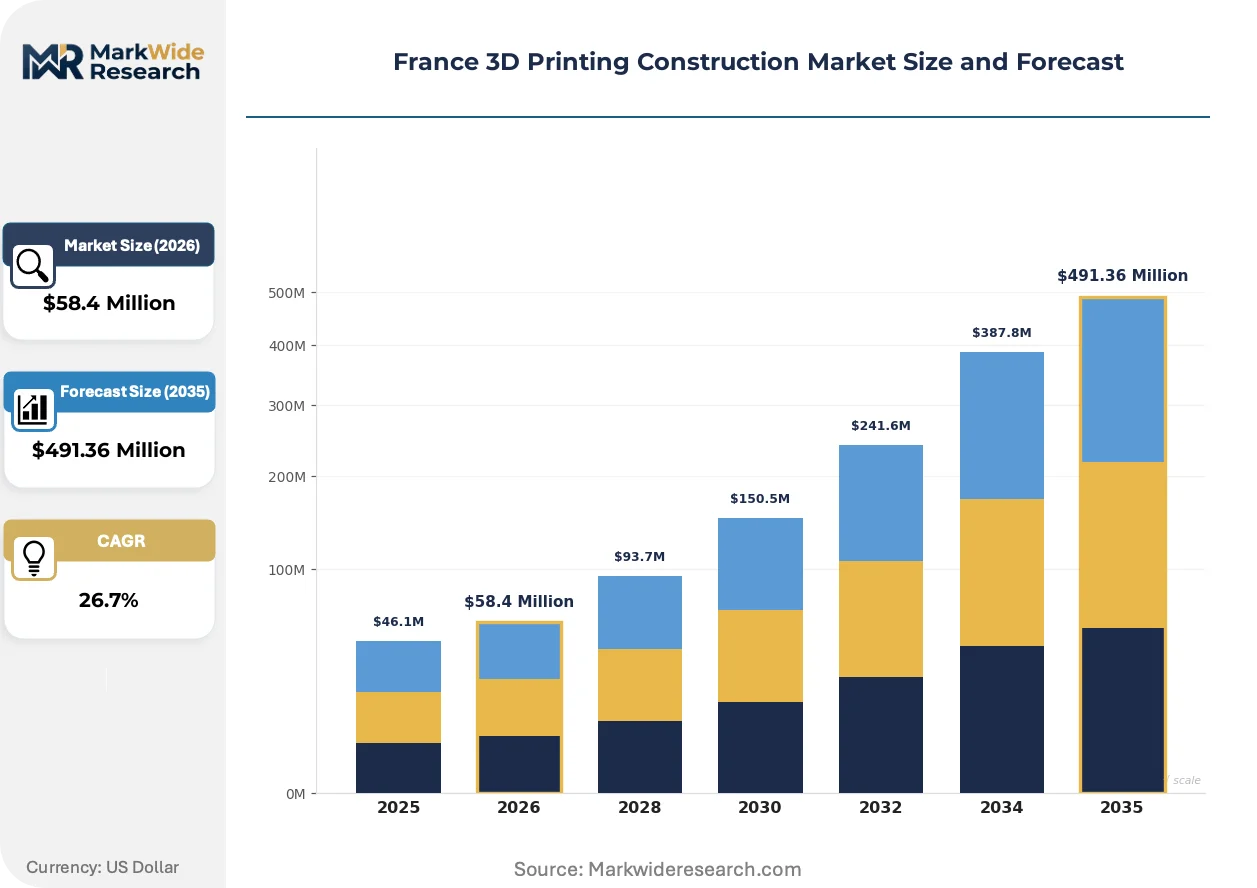
| Market Size in 2026 | $58.4 Million |
| Market Size in 2035 | $491.36 Million |
| CAGR (2026 – 2036) | 26.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concrete Printing, Polymer Printing, Metal Printing, Composite Printing Technology: Extrusion, Powder Bed Fusion, Binder Jetting, Material Jetting Application: Residential Buildings, Commercial Structures, Infrastructure Projects, Sculptures End User: Construction Firms, Architects, Government Agencies, Real Estate Developers |
| Companies Covered | XtreeE, COBOD International A/S, Vinci, Bouygues, Lafarge, Prodways, Sculpteo, 3DCeram, Lynxter, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France 3D Printing Construction Market Trends and Innovations
Material science breakthroughs and regulatory recalibration are redrawing competitive boundaries in French construction additive manufacturing. Three developments merit particular attention from stakeholders positioning for the 2026-2035 window.
Low-cement geopolymer concrete is decentralizing structural fabrication away from centralized ready-mix plants toward on-site or near-site production nodes. Social housing developers in Seine-Saint-Denis and Val-de-Marne are adopting these formulations to meet EU Green Deal carbon accounting requirements while eliminating transport emissions from conventional concrete delivery. This shift compresses the traditional supply chain radius from 50 kilometers to under 5 kilometers, reconfiguring logistics contracts and site labor deployment patterns.
CSTB is accelerating technical assessment protocols for printed structural elements under pressure from ANSM and the EU Construction Products Regulation harmonization timeline. The regulator's streamlined evaluation framework reduces certification cycles for repetitive wall-panel geometries, though complex architectural forms still face extended review. Prefabrication specialists targeting standardized social housing typologies gain first-mover advantage, while custom residential architects encounter persistent approval bottlenecks.
Buyers in Provence-Alpes-Côte d'Azur are consolidating vendor relationships around turnkey fabricators who retain ownership of printed elements through installation, displacing the traditional material-supplier-plus-general-contractor procurement model. This performance-risk transfer appeals to developers facing CSTB liability exposure and skilled labor shortages. The contractual shift concentrates volume with integrated providers capable of warranting structural performance across design, print, and assembly phases.
France 3D Printing Construction Market Segmentation
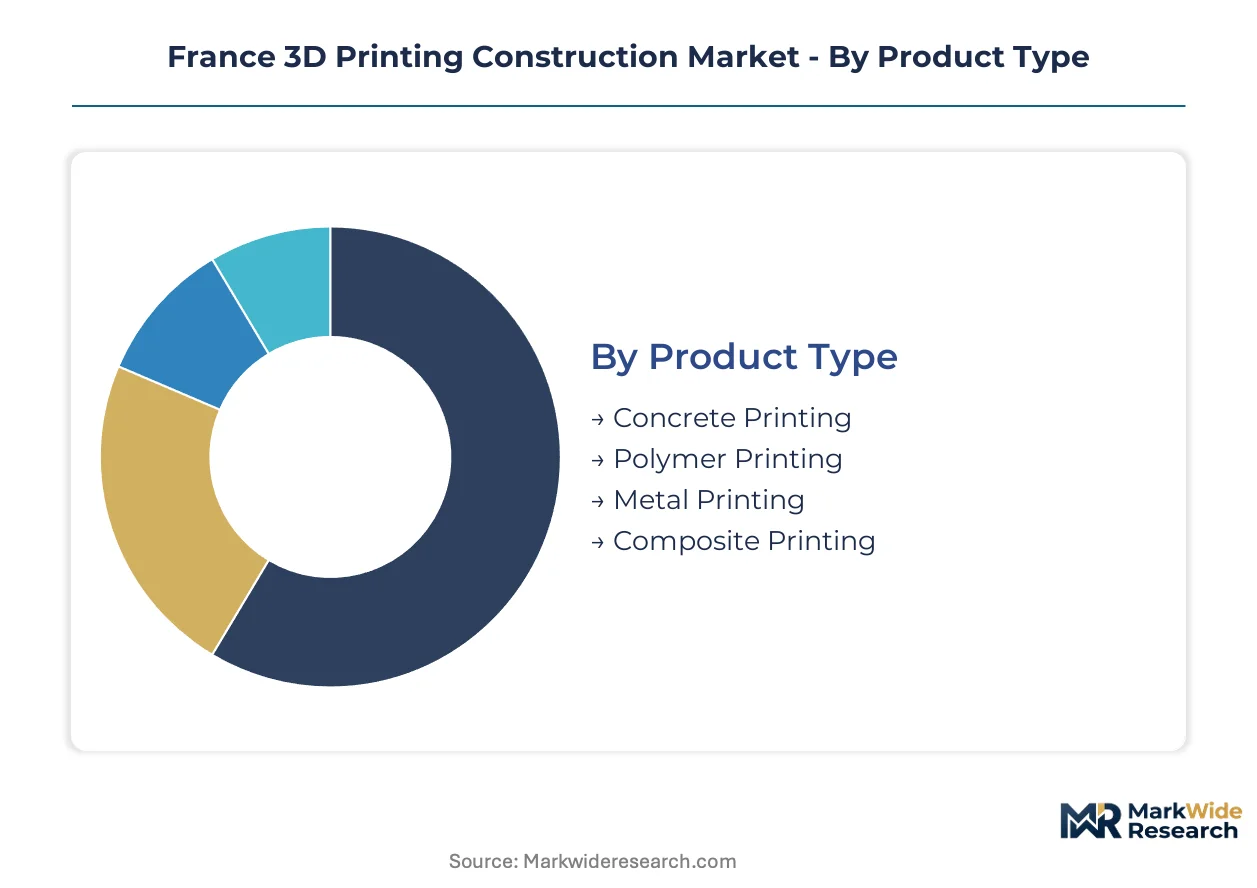
Segmentation in France's 3D printing construction market reveals where capital deployment concentrates and which technology-material combinations command premium positioning. Procurement patterns diverge sharply between structural load-bearing applications governed by CSTB certification and non-structural modules where thermal performance drives specification.
Product Type:
Concrete printing dominates standalone structural fabrication while polymer and metal systems embed into hybrid construction workflows requiring multi-material integration.
- Concrete Printing:Layer-deposited cementitious formulations with 10-50 millimeter layer heights form load-bearing walls and foundation elements. Demand clusters in Île-de-France social housing prototypes where EU Green Deal embodied carbon thresholds accelerate low-cement geopolymer adoption.
- Polymer Printing:Thermoplastic extrusion produces non-structural cladding modules and insulation elements with complex thermal bridging geometries. Auvergne-Rhône-Alpes municipalities specify these for 1970s housing stock retrofits, compressing sales cycles versus ground-up construction.
- Metal Printing:Laser-based powder bed fusion fabricates structural connectors and reinforcement nodes requiring geometric precision.
- Composite Printing:Fiber-reinforced polymer deposition combines tensile strength with design flexibility for architectural feature elements.
Volume placements concentrate in concrete printing; the faster expansion belongs to polymer printing.
Technology:
Capital intensity and material compatibility separate extrusion systems accessible to regional contractors from powder-based methods requiring specialized maintenance infrastructure.
- Extrusion:Gantry and robotic arm systems deposit viscous materials through precision nozzles with build volumes exceeding 500 cubic meters. French construction firms favor these for on-site wall panel fabrication given mature supply chains and lower technician training barriers.
- Powder Bed Fusion:Laser sintering of metal powders achieves dimensional tolerances critical for structural connectors. Equipment concentration in non-EU supply chains creates spare parts dependency that constrains adoption among mid-size contractors.
- Binder Jetting:Liquid binding agents fuse powder layers for sand molds and architectural models with reduced thermal distortion.
- Material Jetting:Photopolymer droplet deposition enables high-resolution facade prototypes and detailed scale models.
Equipment counts favor extrusion; steepest expansion trajectory belongs to powder bed fusion in metal connector niches.
Application:
Project scale and certification burden separate residential workflows standardized for CSTB approval from commercial and infrastructure segments requiring custom structural validation.
- Residential Buildings:Printed wall assemblies and foundation elements for single-family and multi-unit housing. Lyon and Paris public-private demonstration projects validate structural performance, reducing buyer risk perception among developers targeting social housing.
- Commercial Structures:Office and retail facade modules with complex geometries impractical in conventional formwork. Procurement concentrates with turnkey fabricators warranting performance across design through assembly.
- Infrastructure Projects:Bridge components and utility housing requiring extended CSTB technical assessment cycles.
- Sculptures:Non-structural architectural features and public art installations with minimal regulatory friction.
Project value concentrates in residential buildings; custom residential architects nonetheless encounter persistent approval bottlenecks.
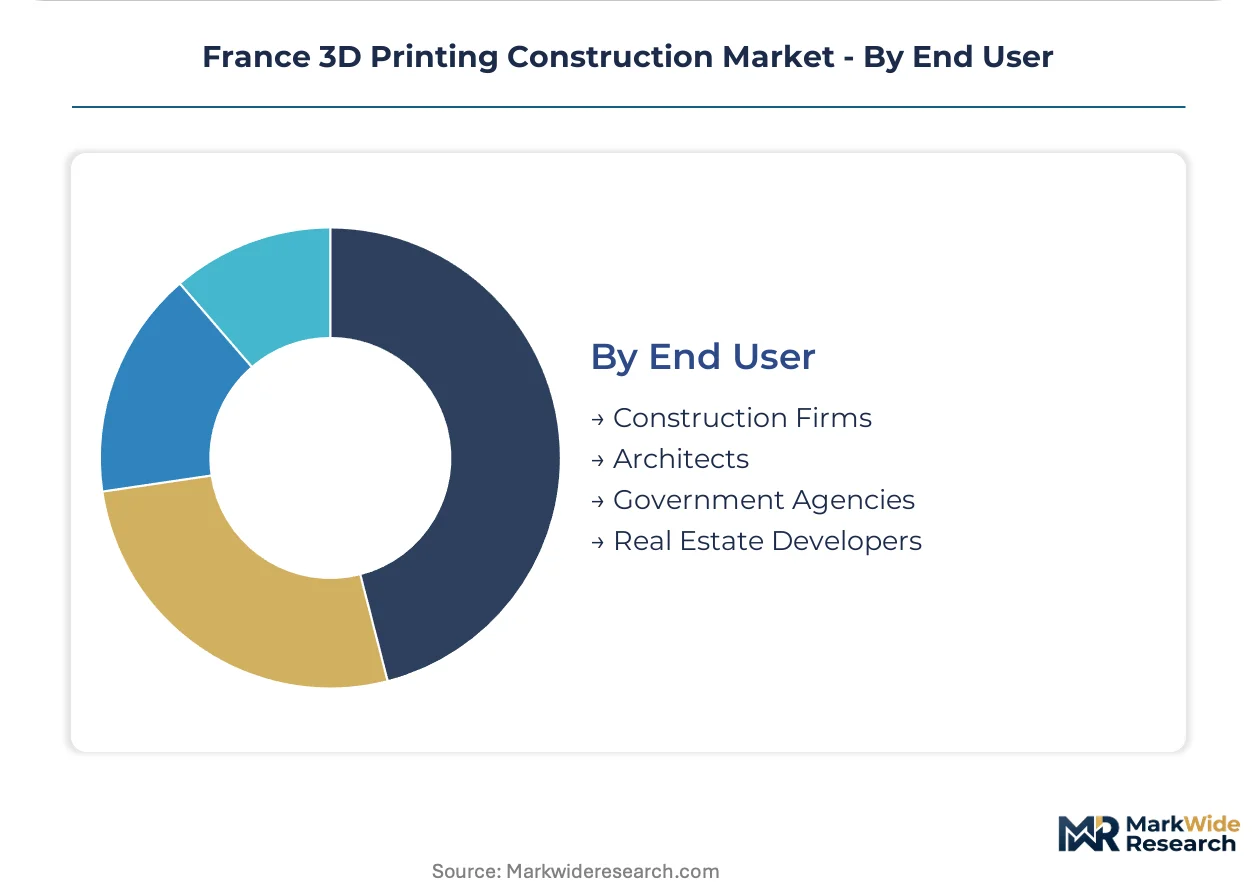
End User:
Technical capability depth distinguishes construction firms building in-house printing capacity from architects and developers outsourcing fabrication to specialized vendors.
- Construction Firms:General contractors and specialty trades integrating printed elements into project delivery. Vinci exemplifies vertical integration by retaining fabrication in-house rather than relying on external vendors.
- Architects:Design practices specifying printed components for geometric complexity or sustainability credentials. Legacy BIM-to-print workflow incompatibility forces manual translation for slicer programs, compressing project margins.
- Government Agencies:Public procurement bodies enforcing EU Green Deal embodied carbon thresholds in municipal housing contracts.
- Real Estate Developers:Private sponsors consolidating vendor relationships around performance-risk transfer to turnkey fabricators.
Procurement authority concentrates in construction firms; government agencies are gaining share fastest through public housing mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Île-de-France's status as a tax-advantaged innovation zone concentrates 3D printing construction demand through social housing mandates and CSTB certification density. Public procurement flows toward Paris and Lyon metropolitan clusters where demonstration projects validate structural performance.
Île-de-France
Social housing developers in Seine-Saint-Denis and Val-de-Marne scale procurement of printed wall assemblies for municipal projects. The EU Green Deal's embodied carbon thresholds accelerate low-cement geopolymer specification in public contracts. Paris anchors demonstration pipelines where XtreeE deploys gantry systems for multi-unit residential prototypes.
Auvergne-Rhône-Alpes
Lyon metropolitan authorities validate structural performance through public-private partnerships for printed foundation elements. CSTB technical assessments for novel cementitious formulations proceed faster here due to proximity to certification laboratories. Saint-Étienne and Grenoble industrial corridors supply fly ash and slag feedstocks for geopolymer binder production.
Provence-Alpes-Côte d'Azur
Turnkey fabricators consolidate vendor relationships around performance-risk transfer models for commercial facade modules. ANSM occupational health oversight extends to automated printing equipment deployed on Marseille and Nice construction sites. Thermal renovation mandates for 1970s housing stock drive polymer cladding demand with compressed sales cycles.
Occitanie
Toulouse and Montpellier metropolitan zones remain underpenetrated relative to northern clusters, offering first-mover positioning before CSTB certification density increases. Regional contractors lack established gantry system partnerships found in Île-de-France. The absence of demonstration projects elevates buyer risk perception among residential developers.
Hauts-de-France
Industrial corridors around Lille concentrate fly ash and slag supply for geopolymer binder formulations, exposing fabricators to energy-intensive material price volatility. Logistics contracts reconfigure around on-site production nodes that compress supply chain radius from 50 kilometers to under 5 kilometers. CNIL-compliant data governance frameworks govern telemetry collection from automated printing equipment.
France 3D Printing Construction Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across equipment supply, material formulation, and turnkey fabrication segments. Market structure tilts toward vertical integration as construction firms retain in-house printing capacity rather than relying on external vendors. Three archetypes dominate: equipment manufacturers licensing gantry systems, cement suppliers controlling geopolymer formulations, and integrated contractors warranting structural performance across design-through-assembly phases. Competitive moves concentrate on strategic partnerships for CSTB certification acceleration and geographic expansion into underpenetrated regional clusters.
Among France-based specialists, XtreeE exemplifies the equipment-to-fabrication archetype through proprietary gantry system deployment. COBOD International A/S anchors the equipment supply layer through distributor partnerships with regional contractors. Vinci occupies a position among diversified conglomerates integrating printed elements into captive project pipelines. These three represent distinct strategic postures: pure-play equipment licensing, hybrid equipment-distribution, and full-stack vertical integration.
| Leading Market Players |
|---|
| XtreeE |
| COBOD International A/S |
| Vinci |
| Bouygues |
| Lafarge |
| Prodways |
| Sculpteo |
| 3DCeram |
| Lynxter |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap contractors in Hauts-de-France anchor geopolymer binder supply through long-term slag procurement contracts, translating feedstock security into pricing discipline that resists volatility from energy-intensive material markets.
Pricing Analysis
Margin tightening in standard-grade printed wall assemblies reflects fly ash supply concentration in northern France industrial corridors. Project-based pricing dominates procurement, with differentiation tracking CSTB certification tier and volume scale. Cost-down pressure on mid-size contractors accelerates because municipal social housing tenders prioritize low-carbon compliance over brand premium. Public-sector buyers exhibit highest price sensitivity; turnkey fabricators warranting full performance risk command lowest elasticity.
Supply Chain Analysis
Direct-to-fabricator channels handle hyperscale demand from Île-de-France social housing developers, bypassing traditional ready-mix intermediaries. Equipment supply draws from Denmark and Belgium; geopolymer feedstocks rest on French and German industrial byproduct streams. Single-source vulnerability concentrates in laser sintering systems for metal connectors, creating spare parts dependency on non-EU maintenance networks. Distribution runs through specialized turnkey providers who retain ownership through installation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's 3D printing construction market reads as supply-constrained: gantry system deployment capacity limits project commissioning velocity, propping pricing power for certified fabricators.
For Market Incumbents: Deepen backward integration into geopolymer formulation by securing slag offtake from Saint-Étienne industrial corridors, insulating margin position against energy price volatility. Expand in-house technician training pipelines to reduce dependency on Belgian and German specialized crews. Prioritize CSTB certification investment for repetitive wall-panel geometries that unlock streamlined approval pathways. For New Entrants and Emerging Players: Capture Occitanie's underpenetrated Toulouse and Montpellier zones before demonstration projects elevate buyer confidence and certification density. Target retrofit facade cladding applications where thermal renovation mandates compress sales cycles versus ground-up construction. Lead with polymer printing specialization that sidesteps structural certification friction. For Investors and Strategic Acquirers: Distressed-cycle entries favor equipment-to-fabrication specialists with proven gantry deployment records in Île-de-France. Long-term viability hinges on vertical integration depth across design-print-install phases. Monitor CSTB protocol acceleration announcements as inflection signal for certification-timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| CSTB Certification Fast-Track | Streamlined approval for repetitive geometries accelerates social housing project commissioning in Seine-Saint-Denis. |
| Geopolymer Supply Integration | Slag offtake agreements with Hauts-de-France steel producers secure low-carbon binder feedstock against price volatility. |
| Gantry System Partnership | Distributor relationships with COBOD International A/S lower capital barriers for regional contractors in Auvergne-Rhône-Alpes. |
| Technician Training Academy | In-house calibration and maintenance programs reduce premium labor import costs from Belgium and Germany. |
| Retrofit Cladding Specialization | Polymer printing for 1970s housing thermal renovation opens non-structural revenue with shorter sales cycles. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with construction firm project directors, gantry system operators, CSTB certification specialists, and municipal housing procurement officers combined with bottom-up and top-down triangulation. Secondary sources included EU Construction Products Regulation harmonization documents, ANSM occupational health filings, CNIL data governance guidance, and cement industry production statistics.
Granularity-level modeling addressed product type, technology, application, and end user dimensions at the regional cluster level across the projection horizon. CAGRs derived from segment-level volume trajectories calibrated against equipment deployment rates and public procurement pipeline disclosures. Forecast inputs incorporated CSTB certification timeline assumptions and EU Green Deal embodied carbon threshold implementation schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolymer feedstock price volatility and CSTB protocol acceleration timing. Forecasts reflect documented assumptions about municipal social housing commitment levels and gantry system maturation curves. Practitioners should monitor ANSM guidance updates on automated equipment telemetry governance and fly ash supply contract renegotiation cycles for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Fibert Market
Others
Military Wearable Market
Others
North America 3D Printing Construction Market
Others
Space Power Supply Market
Others
Printed Leather Market
Others
Folding Mobile Phone Market
Others
Automatic Barriers and Bollards Market
Others
Security Bottles Market
Others
Asia-Pacific Battery E-Commerce Market
Others
Indoor LBS Market
Others
Middle East and Africa Induced Pluripotent Stem Cells (Ipscs) Market
Others
Durian Fruit Market
Others
Human Enhancement Technology Market
Others
Metaverse Market
Others
Asia-Pacific Laser Hair Removal Market
Others
Asia-Pacific Military 4D Printing Market