

Residential Electrical Conduit Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Electrical Conduit Market Insights
Polyvinyl chloride is rebalancing residential electrical conduit economics as copper price volatility pushes contractors toward non-metallic alternatives in low-voltage and communication wiring runs. Atkore leverages its integrated PVC resin-to-conduit manufacturing footprint to sustain margin stability across volatile feedstock cycles. Hubbell anchors its position through deep distribution relationships with electrical contractors in North American residential construction markets. Legrand differentiates via smart home integration-ready conduit systems that accommodate low-voltage cabling alongside traditional power circuits.
Residential electrical conduit comprises rigid or flexible tubing systems, typically manufactured from PVC, galvanized steel, or aluminum alloys in trade sizes from one-half to six inches diameter, designed to protect and route electrical wiring through walls, ceilings, and underground pathways in dwelling units. The primary purpose is to provide mechanical protection, moisture resistance, and fire containment for branch circuits and feeder cables serving lighting, appliances, and electronic systems. PVC dominates material type volume due to cost efficiency and corrosion immunity in buried and damp-location applications, while EMT and rigid metal segments command premium positioning in jurisdictions with stringent fire-resistance mandates. Concealed installation type generates the largest revenue pool as new residential construction prioritizes finished-wall aesthetics, though surface-mounted systems retain share in renovation and basement retrofit work where wall demolition proves prohibitive.
The US National Electrical Code, enforced by local authorities having jurisdiction under OSHA workplace safety frameworks, mandates conduit specifications based on circuit voltage, environmental exposure, and fire-rating requirements, directly shaping contractor material selection and inventory decisions. EMA's Construction Products Regulation and CE marking requirements govern metallic conduit sold in European residential markets, creating compliance barriers for non-certified imports while elevating quality benchmarks for domestic manufacturers. Stakeholders must monitor evolving smart home wiring standards and electrification load requirements that will redefine conduit sizing practices as residential circuits absorb EV charging, heat pump, and battery storage connections.
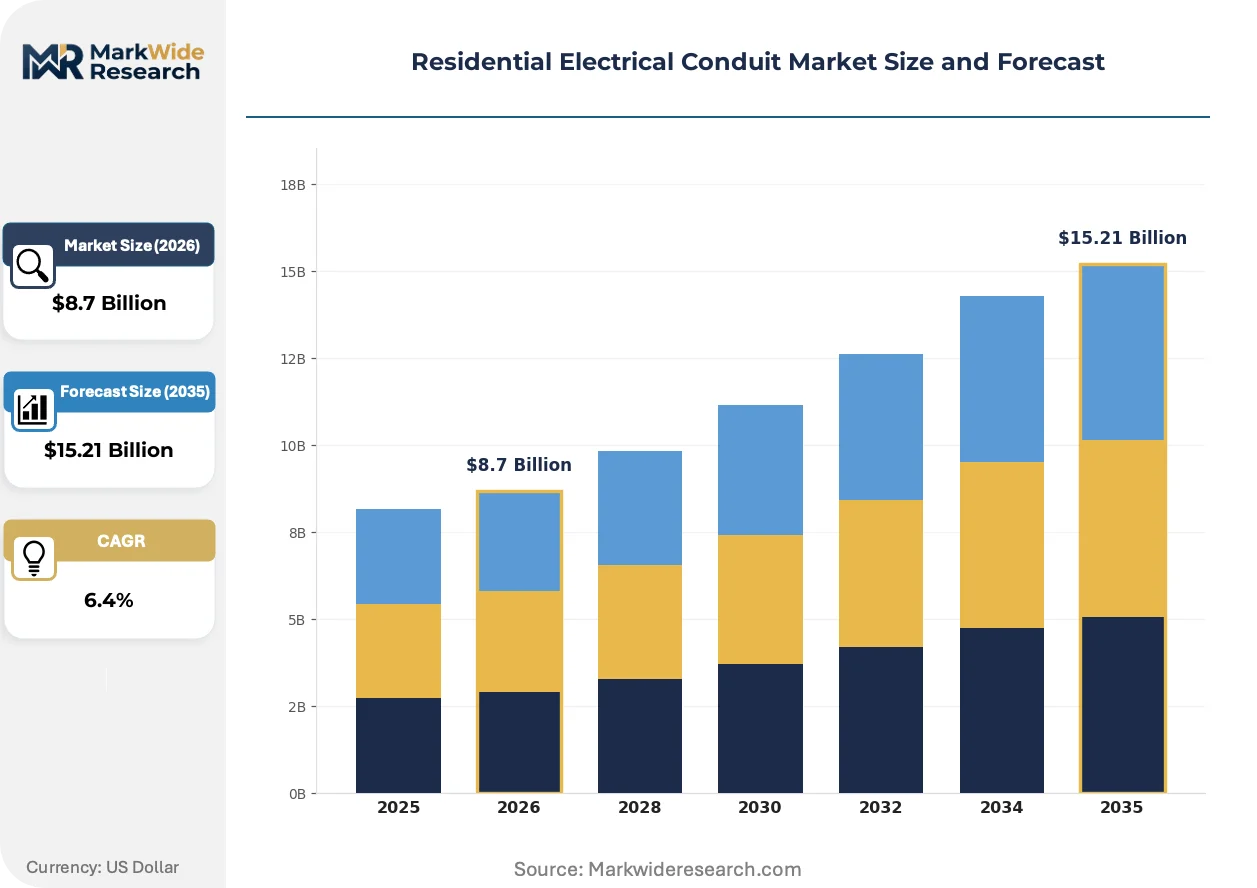
Market Dynamics
Single-family housing construction is accelerating demand for concealed installation systems across the US Sun Belt, while updated ampacity requirements in the US National Electrical Code are pushing contractors toward higher-grade metallic conduit solutions in new residential developments.
Growth Catalysts
- Electrification mandates:State-level building electrification policies in California and New York are mandating EV-ready rough-in requirements that expand conduit runs per dwelling unit.
- Smart home infrastructure:Low-voltage cabling density for integrated home automation systems is expanding conduit sizing specifications beyond traditional power-only configurations.
- Sun Belt migration:Population inflows into Texas, Florida, and Arizona are sustaining elevated residential permitting velocity that concentrates demand for PVC and EMT installations.
Market Restraints
- Copper price volatility:Fluctuations in copper futures markets transmit directly to EMT and rigid metal conduit pricing, compressing contractor bid margins on fixed-price residential projects.
- Resin supply concentration:Domestic PVC resin production clusters along the US Gulf Coast expose conduit manufacturers to hurricane-related production disruptions and force majeure events.
- Skilled labor scarcity:Licensed electrician shortages in high-growth metropolitan statistical areas are extending project timelines and deferring conduit procurement schedules.
Strategic Opportunities
- Prefabrication adoption:Off-site electrical panel and conduit assembly is reducing field installation hours for production homebuilders pursuing cycle-time compression.
- Heat pump retrofits:Federal IRA tax incentives for residential HVAC electrification are expanding branch circuit requirements in existing housing stock.
- Modular construction:Factory-built residential modules require standardized conduit specifications that favor suppliers with consistent dimensional tolerances and national distribution networks.
Industry Challenges
- Code cycle synchronization:Variability in local authority adoption timelines for NEC updates creates inventory complexity for distributors serving multiple jurisdictions.
- Material specification conflicts:General contractor value engineering pressures clash with electrical contractor preference for premium metallic conduit in fire-rated assemblies.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Electrical Conduit Market Trends and Innovations
Material substitution and installation method evolution are compressing traditional product lifecycle patterns. Regulatory load calculations and procurement centralization are simultaneously reshaping contractor-vendor relationships.
Flexible non-metallic conduit is decentralizing residential electrical distribution by enabling faster rough-in sequences in timber-framed construction. Production homebuilders in Texas and Florida are specifying liquid-tight flexible metal conduit for appliance circuits to reduce labor hours per unit. This technology is decentralizing the historical dominance of rigid PVC in branch circuit protection by accommodating complex routing through engineered wood products.
The US National Electrical Code's revised ampacity derating tables for bundled conductors are mandating larger conduit trade sizes for high-density residential panel feeds. Electrical contractors in jurisdictions with 2023 NEC adoption are upsizing EMT specifications to maintain compliance margins. Sun Belt metropolitan permit offices are experiencing elevated plan review cycles as inspectors verify conduit fill calculations against revised tabular values.
Homebuilder procurement consolidation is compressing vendor relationship structures toward national account frameworks. Regional electrical distributors are losing specification influence as national production builders centralize material sourcing through direct manufacturer agreements. This concentration is most visible in Arizona and Nevada markets where top-five homebuilders command majority market share and standardize conduit specifications across divisions.
Residential Electrical Conduit Market Segmentation
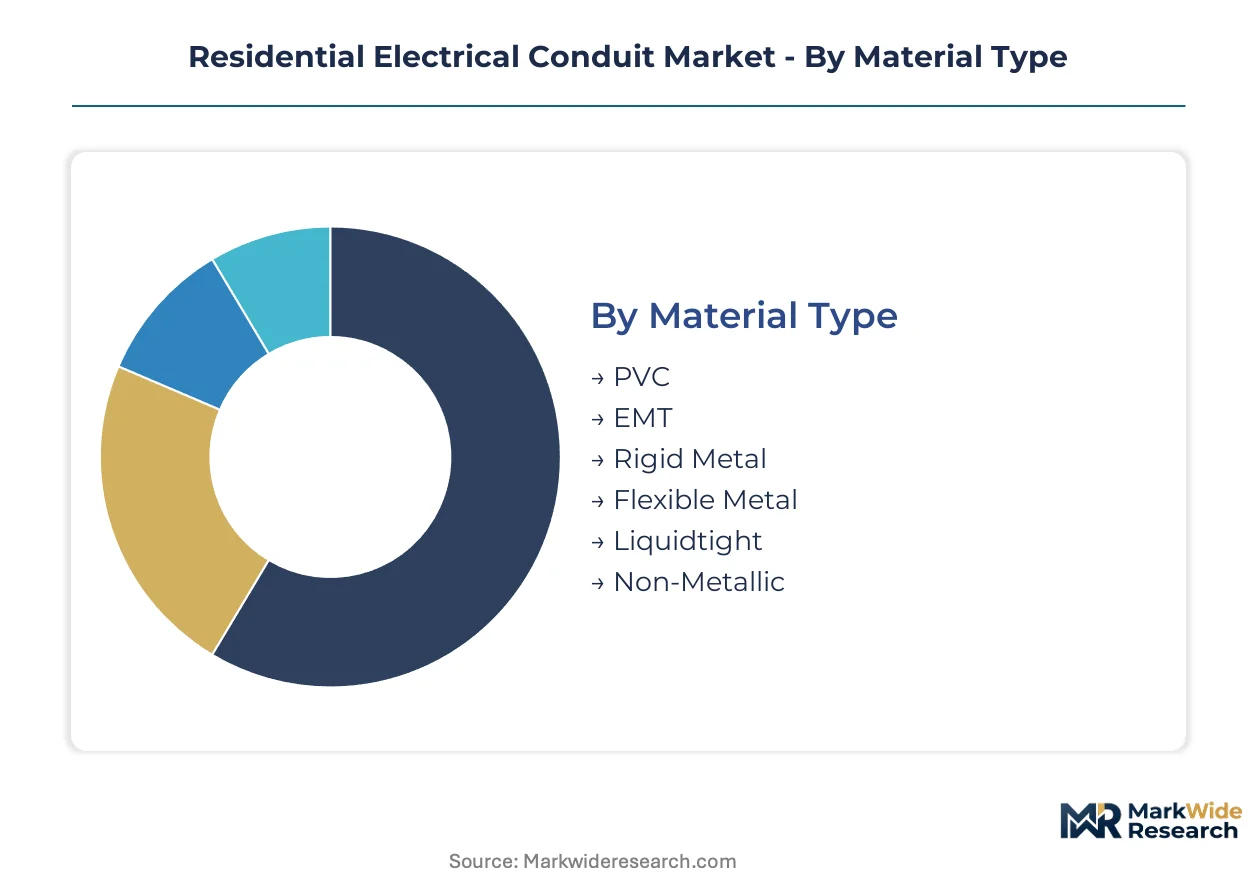
Material selection and installation method dictate capital deployment patterns across residential electrical conduit procurement. Contractors align inventory decisions with local code cycles and builder specification preferences.
Material Type:
PVC and metallic systems demand divergent capital commitments in resin handling versus metal forming and coating infrastructure.
- PVC:Extruded polyvinyl chloride compound delivers corrosion immunity and moisture resistance for buried and damp-location installations. Gulf Coast residential developments specify PVC for underground service entrances where soil chemistry degrades metallic alternatives. Resin supply concentration along the Texas-Louisiana corridor exposes procurement schedules to hurricane-related production disruptions.
- EMT:Thin-wall galvanized steel tubing offers field-bendable mechanical protection with lighter weight than rigid metal systems. Sun Belt electrical contractors favor EMT for exposed basement and utility room installations where fire-resistance ratings apply. Copper price volatility in futures markets transmits directly to EMT pricing, compressing bid margins on fixed-price projects.
- Rigid Metal:Threadable heavy-wall steel conduit satisfies NEC ampacity derating requirements in high-density panel feeds.
- Flexible Metal:Interlocked steel strip construction accommodates complex routing through engineered wood products in timber-framed construction.
- Liquidtight:PVC-jacketed flexible metal systems protect appliance circuits in outdoor and wet-location applications.
- Non-Metallic:Corrugated plastic tubing serves low-voltage communication and smart home cabling runs where electromagnetic shielding is unnecessary.
PVC absorbs the bulk of installed capacity; non-metallic flexible systems are expanding most quickly alongside smart home infrastructure deployment.
Installation Type:
Application method determines labor intensity and rough-in sequencing for production versus custom home construction.
- Concealed:In-wall and in-ceiling routing preserves finished aesthetics in new residential construction. Texas and Florida production homebuilders mandate concealed systems to meet buyer expectations and appraisal standards. Skilled electrician scarcity in high-growth metropolitan statistical areas extends rough-in timelines for concealed installations.
- Surface Mounted:Exposed conduit on walls and ceilings serves renovation and basement retrofit work where wall demolition proves cost-prohibitive. Northeast and Midwest markets retain surface-mounted share in aging housing stock upgrades. Faster installation cycles appeal to contractors facing compressed project schedules.
- Underground:Direct-buried PVC and liquidtight systems route service entrances and outbuilding feeders below grade.
- Overhead:Suspended conduit runs serve detached garages and accessory dwelling units in rural and suburban lot configurations.
Concealed installations command the dominant revenue share; surface-mounted systems retain stable demand in renovation-heavy markets.
End User:
Procurement authority and specification influence vary sharply between professional installers and owner-driven purchasing.
- Electrical Contractors:Licensed professionals specify material grade and trade size based on NEC compliance and local authority requirements. Deep distribution relationships with national suppliers anchor procurement patterns in high-volume markets. Inventory complexity from variable code adoption timelines across jurisdictions complicates stocking decisions.
- Real Estate Developers:Production homebuilders centralize material sourcing through direct manufacturer agreements to compress cycle times. Top-five builders in Arizona and Nevada standardize conduit specifications across divisions, marginalizing regional distributor influence.
- Homeowners:Retail purchasing for minor repairs and DIY projects concentrates in big-box channels.
- Property Managers:Maintenance and turnover-driven replacement demand flows through wholesale electrical supply houses.
Electrical contractors specify the majority of material volume; real estate developers are concentrating procurement authority fastest through national account frameworks.
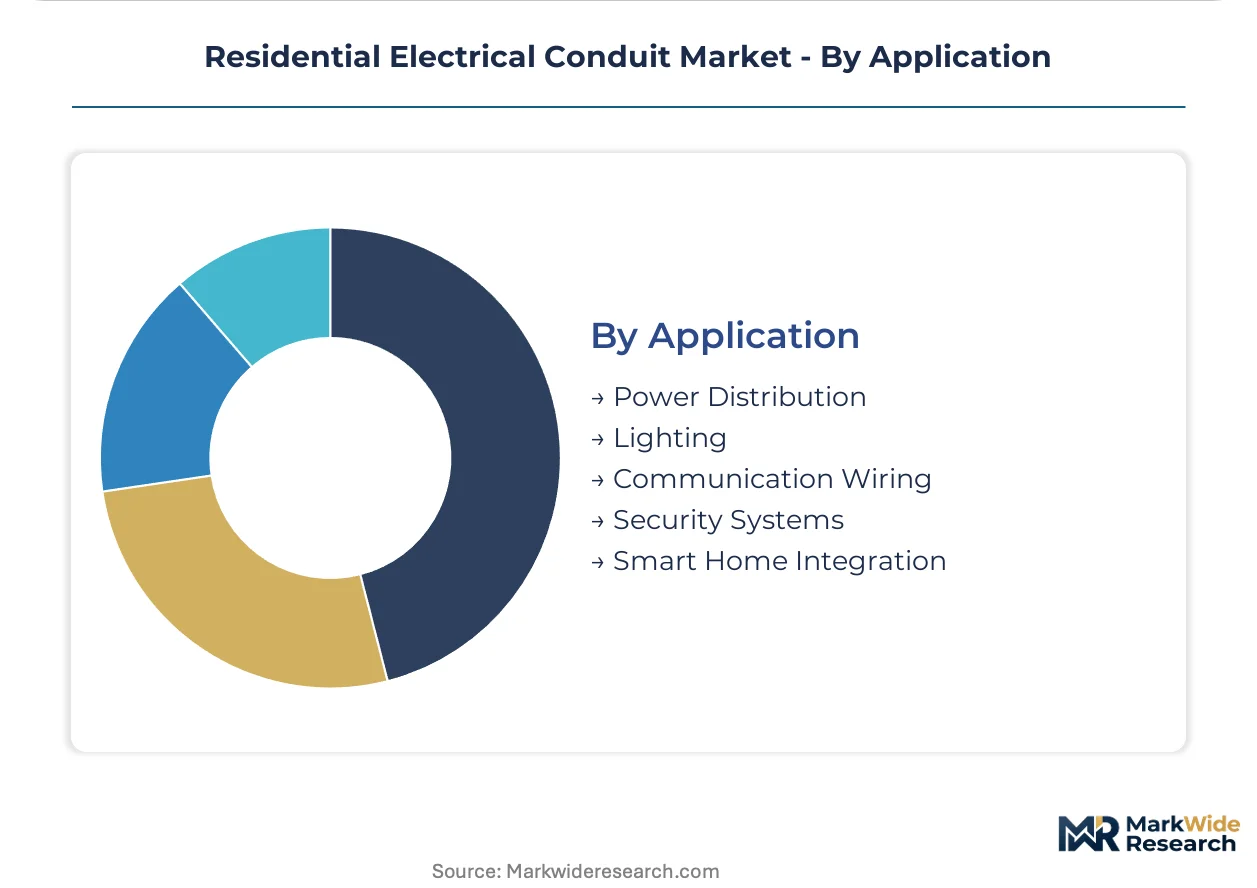
Application:
Circuit function dictates conduit sizing, fill calculations, and segregation requirements under NEC bundling rules.
- Power Distribution:Branch circuits and feeder cables serving panels, appliances, and HVAC equipment require fire-rated mechanical protection. Revised NEC ampacity derating tables for bundled conductors mandate larger trade sizes in high-density residential panel feeds. Sun Belt permit offices experience elevated plan review cycles as inspectors verify fill calculations.
- Smart Home Integration:Low-voltage cabling density for automation, security, and communication systems expands conduit sizing beyond traditional power-only configurations. California and New York electrification mandates require EV-ready rough-in that enlarges conduit runs per dwelling unit. Legrand and competitors engineer integration-ready systems accommodating mixed voltage levels.
- Lighting:General illumination circuits dominate installation count per residential unit.
- Communication Wiring:Data, voice, and video cabling runs favor non-metallic flexible conduit for cost efficiency.
- Security Systems:Sensor and camera wiring requires dedicated pathways separate from power circuits.
Power distribution consumes the greatest material tonnage; smart home integration is driving specification evolution fastest through mixed-voltage pathway requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Opportunity Zones program and state-level electrification incentives are concentrating residential electrical conduit demand in designated high-growth corridors where infrastructure investment accelerates permitting velocity.
United States
Texas and Florida single-family construction dominates volume as Sun Belt migration sustains elevated permitting. The US National Electrical Code's 2023 ampacity derating requirements are mandating larger conduit trade sizes in high-density panel feeds. Houston and Dallas-Fort Worth metropolitan areas concentrate demand for PVC and EMT installations in production homebuilder developments.
Germany
Building energy efficiency renovations under the federal subsidy program are expanding branch circuit requirements in existing housing stock. EMA's Construction Products Regulation and CE marking requirements govern metallic conduit specifications, elevating quality benchmarks for domestic manufacturers. The Rhine-Ruhr industrial corridor anchors distribution networks serving residential electrification projects across North Rhine-Westphalia.
China
Urban residential redevelopment and smart city infrastructure deployment are expanding low-voltage cabling density in new dwelling units. GB standards and MIIT regulations shape material specifications for electrical protection systems in residential construction. The Yangtze River Delta manufacturing cluster supplies extruded PVC and metal-forming capacity for domestic and export markets.
India
Affordable housing initiatives and urbanization are accelerating concealed installation adoption in multi-story residential developments. BIS certification requirements and state electrical inspectorates mandate compliance with IS standards for conduit materials. Maharashtra and Gujarat industrial zones concentrate PVC resin processing and conduit extrusion capacity serving western India construction markets.
Brazil
Middle-class housing expansion and electrification programs in informal settlements are expanding surface-mounted and concealed system deployment. ANVISA and national electrical safety regulations establish material specifications for residential wiring protection. São Paulo state's construction industrial belt anchors manufacturing and distribution for southeastern Brazil residential markets.
Residential Electrical Conduit Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated resin-to-conduit producers commanding margin stability while regional fabricators compete on logistics proximity. The vendor base clusters around three strategic archetypes: integrated chemical-industrial conglomerates with captive PVC supply, electrical infrastructure specialists with deep contractor distribution relationships, and regional extrusion houses serving localized construction markets. M&A activity concentrates on resin backward integration and distribution network consolidation.
Among North American electrical infrastructure specialists, Atkore, Hubbell, and Legrand occupy distinct positioning vectors. Atkore exemplifies the integrated manufacturing archetype with resin-to-conduit production control. Hubbell anchors contractor-centric distribution relationships across residential construction markets. Legrand represents the smart-home integration tier, engineering conduit systems for mixed-voltage residential applications.
| Leading Market Players |
|---|
| ABB |
| Anamet Electrical |
| Astral |
| Atkore |
| CANTEX |
| Champion Fiberglass |
| Electri-Flex |
| Hubbell |
| Legrand |
| Others |
Pricing and Supply Chain Analysis
Copper futures volatility propagates through galvanized steel tubing costs to compress contractor bid margins on fixed-price residential projects, while PVC resin pricing stability rewards integrated manufacturers with captive Gulf Coast supply. This input-cost divergence stratifies the market into premium metallic systems for fire-rated assemblies and economy non-metallic alternatives for standard branch circuits.
Pricing Analysis
Short lead-time premiums for EMT and rigid metal conduit widen during hurricane season when Gulf Coast resin disruptions accelerate contractor spot purchasing. Three-tier pricing structure across premium, standard, and economy levels separates UL-listed fire-rated metallic systems from commodity PVC and unbranded flexible alternatives. Pricing pressure stems from general contractor value engineering mandates that clash with electrical contractor preferences for premium specifications. Production homebuilders exhibit highest price sensitivity through centralized national account procurement, while custom residential developers absorb premiums for concealed installation aesthetics.
Supply Chain Analysis
Licensed electrician shortages in Houston, Dallas-Fort Worth, and Phoenix metropolitan areas extend project timelines and defer conduit procurement schedules for production homebuilders. Manufacturing concentrates in Texas, Louisiana, and Ohio where PVC resin processing, steel forming, and national distribution networks anchor supply. Raw material inputs draw from Gulf Coast petrochemical corridors, Midwest steel mills, and copper cathode imports through Port of Houston. Single-source vulnerability in resin supply exposes manufacturers to hurricane-related force majeure events. Distribution runs through national electrical distributors, regional supply houses, and direct manufacturer agreements with top-five homebuilders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
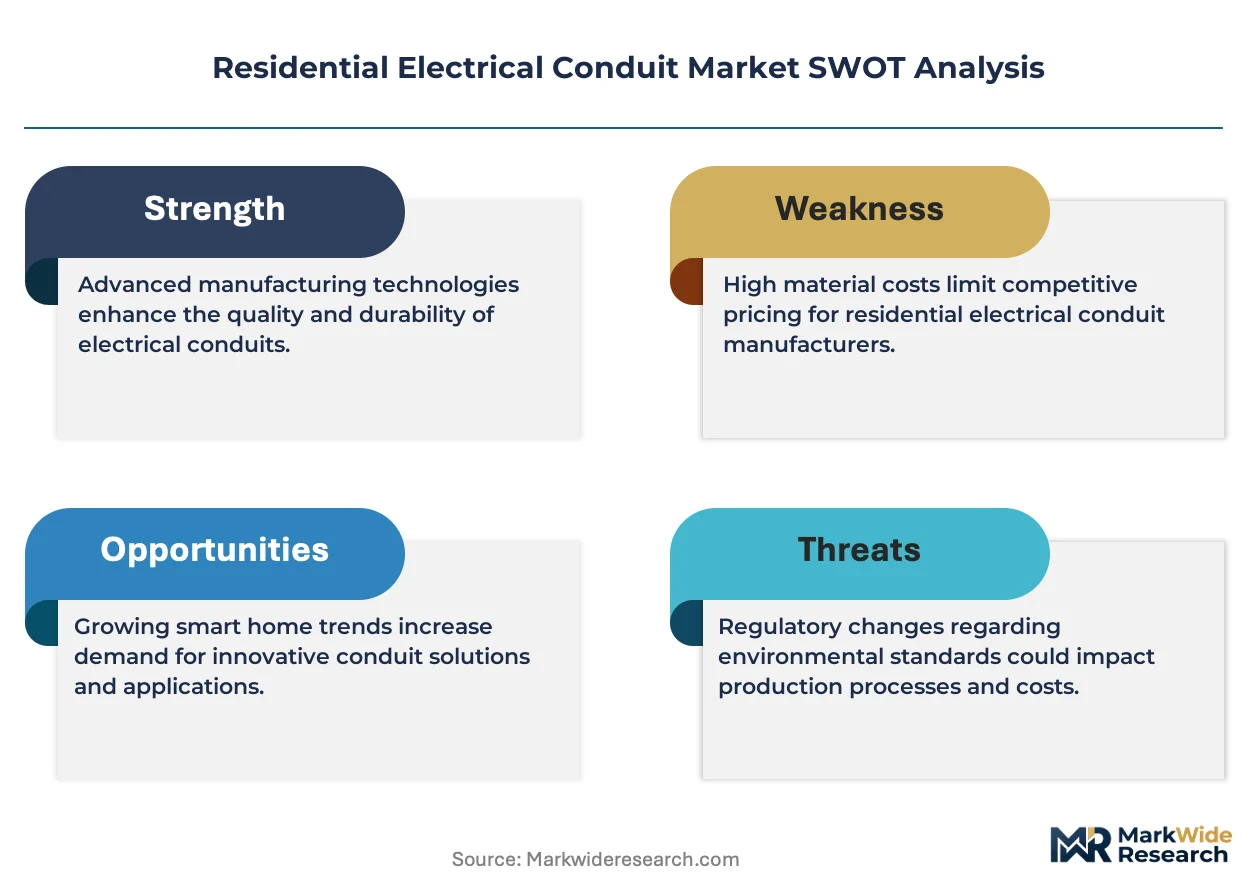
The residential electrical conduit sector is becoming a vertical-integration race as players pursue captive PVC resin supply to insulate margins from petrochemical volatility. Backward integration into resin production represents the decisive upstream lever separating integrated specialists from margin-compressed assemblers.
For Market Incumbents: Deploy captive resin supply to defend margin stability against Gulf Coast hurricane disruptions and copper price spikes. Consolidate distribution relationships with national production homebuilders before procurement centralization completes in Arizona and Nevada markets. Atkore's integrated manufacturing footprint demonstrates how upstream control insulates against feedstock cycles that compress regional fabricators. For New Entrants and Emerging Players: Enter via modular construction supplier certification programs where standardized dimensional tolerances create specification barriers for established distributors. Target liquidtight flexible metal conduit for outdoor appliance circuits in Texas and Florida production housing where labor-hour reduction drives specification shifts. Pursue direct relationships with factory-built residential module producers seeking national distribution coverage. For Investors and Strategic Acquirers: NEC code adoption timelines accelerating in Sun Belt jurisdictions is the leading indicator that specification influence is concentrating among distributors with multi-state inventory positioning. Over the projection horizon, vertically integrated manufacturers with resin-to-conduit control represent the optimal acquisition archetype. Watch for state-level building electrification mandates mandating EV-ready rough-in requirements as the signal that conduit runs per dwelling unit are structurally expanding.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PVC Resin | Captive Gulf Coast supply insulates margins from hurricane-related force majeure disruptions. |
| National Account Procurement Consolidation | Direct manufacturer agreements with top-five homebuilders marginalize regional distributor influence in Arizona. |
| Smart Home Integration Certification | Legrand's mixed-voltage pathway systems capture electrification-driven specification evolution in California. |
| Modular Construction Supplier Qualification | Factory-built residential modules require dimensional tolerances that favor consistent national producers. |
| Electrification-Ready Rough-In Positioning | State EV-ready mandates in New York expand conduit runs per dwelling unit beyond traditional power-only configurations. |
Research Methodology
SEC 10-K filings, NEC code adoption records, and residential permitting databases formed the secondary backbone, supplemented by primary interviews with electrical contractors, production homebuilder procurement directors, and national distribution channel managers. Bottom-up and top-down triangulation validated volume estimates across material type and installation method segments. Primary fieldwork captured contractor inventory decisions under variable local authority adoption timelines.
Bottom-up modeling built from metropolitan statistical area permitting velocity and conduit content per dwelling unit, while top-down analysis cross-checked against national construction spending flows. Segmentation dimensions included material type, installation method, end-user procurement authority, and application circuit function across the analysis window. CAGRs derived from slope-log regression on annualized permit data adjusted for code-driven upsizing effects. Key inputs encompassed copper futures pricing volatility and Gulf Coast resin production capacity utilization.
Forecast precision tightens around the base case; tail outcomes carry wider variance under hurricane-related resin supply disruptions or accelerated NEC adoption timelines. Forecasts reflect documented assumptions regarding Sun Belt migration patterns and electrification policy implementation. A small set of named triggers—state EV-ready mandate expansion, modular construction penetration rates, and licensed electrician supply constraints—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.