
 Film Capacitor Market | 2026-2036
Film Capacitor Market Size, Share, and Industry Trends Forecast 2026-2036
Film Capacitor Market Intelligence
East Asian polymer film suppliers is realigning capacitor-grade polypropylene output toward thicker biaxially oriented stocks. KEMET Corporation leverages vertical integration into metallized film production to secure dielectric consistency. Xiamen Faratronic anchors its position through captive supply of raw polyester film. TDK Corporation dominates high-frequency polypropylene segments for EV powertrains.
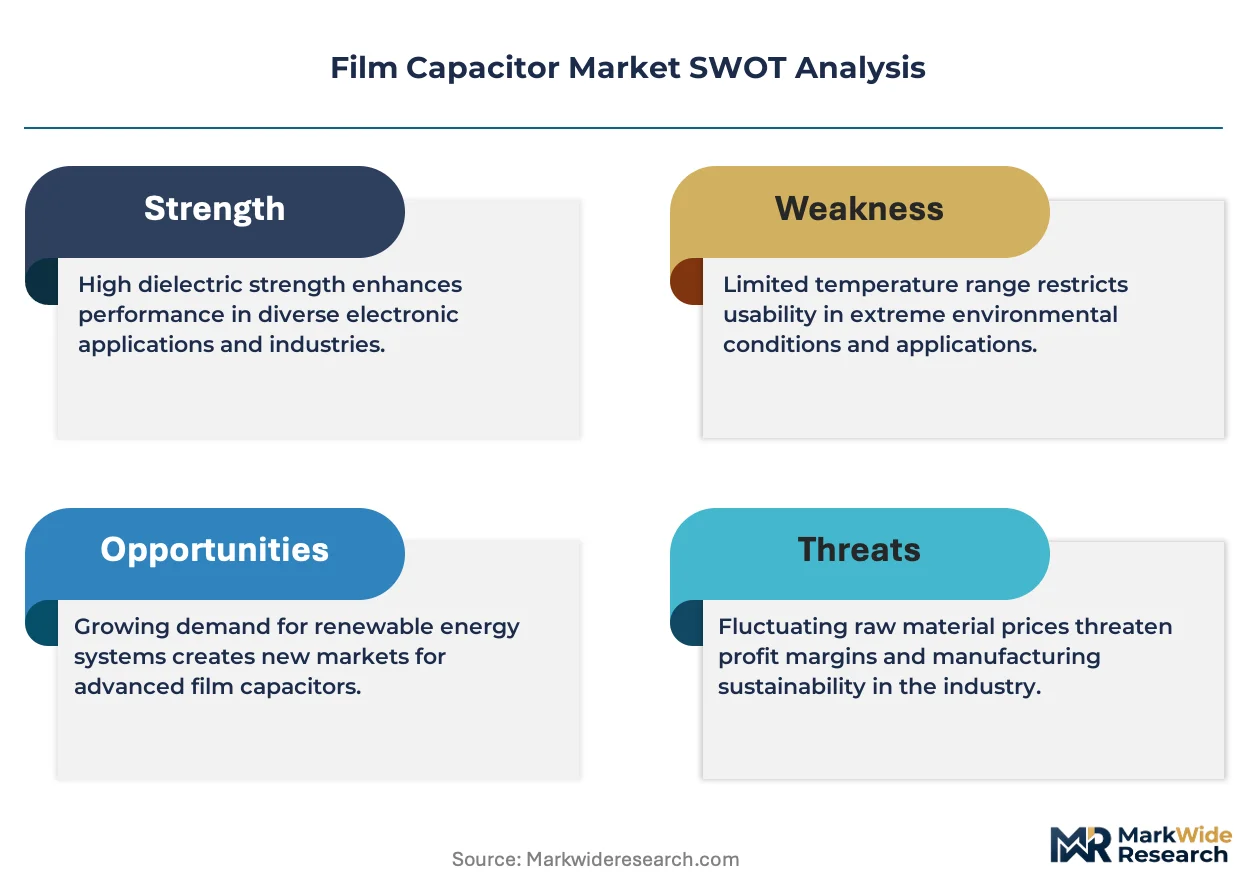
Film capacitors store electrical energy in a thin polymer dielectric layer sandwiched between metallized electrodes, with typical film thickness ranging from 2 to 12 micrometers depending on voltage rating and self-healing requirements. They primarily serve circuits requiring stable capacitance, low dissipation factor, and resilience against AC ripple current in power conversion systems. Polypropylene film types lead in renewable energy inverters due to superior thermal stability and low dielectric losses at elevated frequencies. Power electronics applications capture the deepest margin pools, particularly in EV onboard chargers and solar string inverters where volumetric efficiency commands premium pricing. Industrial equipment demand for polyester variants remains mature, with growth constrained by substitution from ceramic alternatives in low-voltage signal paths.
REACH compliance in Europe restricts certain phthalate plasticizers in capacitor encapsulants, compelling reformulation of polyester film coatings. China's GB standards for grid-connected inverters mandate specific film capacitor ripple current endurance, filtering non-compliant imports from smaller Southeast Asian suppliers. FDA electrical safety requirements for medical devices in the United States shape insulation ratings and failure-mode documentation for film capacitors deployed in diagnostic imaging equipment. Stakeholders must monitor polymer raw material allocation between packaging and capacitor-grade film as bioplastics capacity expands.
Market Dynamics
Power electronics manufacturers are consolidating procurement around polypropylene film capacitors for inverter systems, while the EU F-Gas Regulation accelerates substitution toward dry-type designs and China's Jiangsu province concentrates automotive tier-one supply.
Growth Catalysts
- EV Powertrain Electrification:Electric vehicle onboard chargers and traction inverters require film capacitors with superior thermal stability and low dielectric losses at elevated frequencies, pulling demand from conventional automotive passive components.
- REACH Compliance Reformulation:European restrictions on phthalate plasticizers in capacitor encapsulants compel manufacturers to develop compliant polyester film coatings, creating first-mover advantages for reformulated product lines.
- Renewable Energy Inverter Deployment:Solar string inverters and wind power converters utilize polypropylene film types for stable capacitance under AC ripple current, with grid-scale installations driving volume procurement.
Market Restraints
- Polypropylene Raw Material Concentration:East Asian polymer film suppliers dominate capacitor-grade biaxially oriented polypropylene output, creating supply vulnerability for European and North American capacitor manufacturers dependent on imported dielectric stock.
- Ceramic Substitution in Low-Voltage Paths:Multilayer ceramic capacitors displace polyester film variants in signal path applications below 50 volts, compressing addressable market for traditional film constructions in consumer electronics.
- Bioplastics Capacity Competition:Expanding bioplastics production for packaging applications diverts polymer raw material allocation, tightening feedstock availability for capacitor-grade film extrusion.
Strategic Opportunities
- Medical Device Insulation Standards:FDA electrical safety requirements for diagnostic imaging equipment create specialized demand for film capacitors with documented failure modes and enhanced insulation ratings in the United States.
- Grid-Connected Inverter Certification:China's GB standards for ripple current endurance filter non-compliant imports, opening procurement pathways for domestic Jiangsu province producers with certified metallized film capabilities.
- High-Frequency Polypropylene Convergence:Integration of wide-bandgap semiconductors with polypropylene film capacitors enables next-generation EV powertrain inverters operating at elevated switching frequencies.
Industry Challenges
- Metallization Process Expertise Gap:Self-healing electrode deposition requires specialized vacuum metallization operators, with talent scarcity constraining capacity expansion at mid-tier capacitor manufacturers.
- Dual Certification Timeline Compression:Simultaneous compliance with EU F-Gas Regulation and China GB standards extends product qualification cycles, delaying revenue recognition for new film capacitor platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Film Capacitor Market |
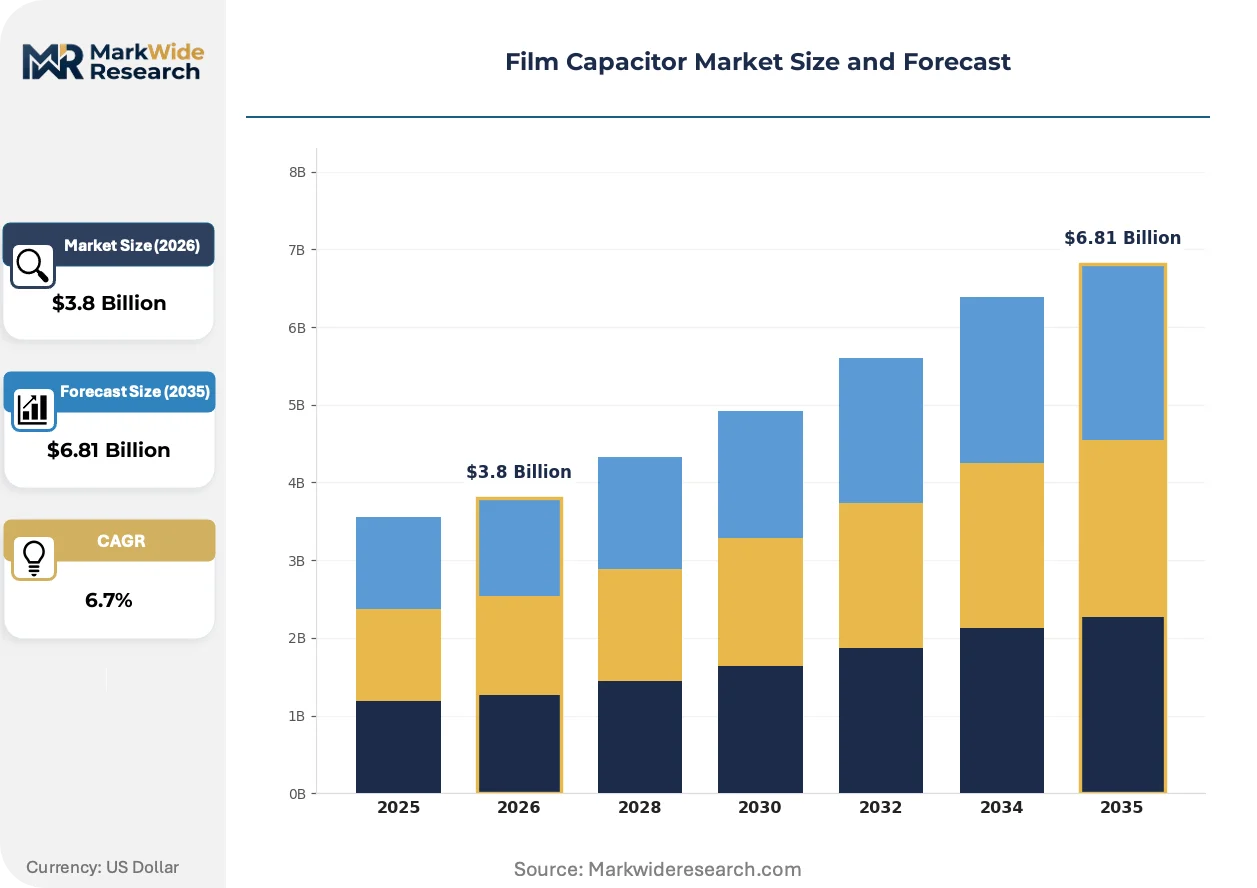
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Polyester, Polypropylene, Polycarbonate, Polyphenylene Sulfide Application: Power Electronics, Consumer Electronics, Industrial Equipment, Renewable Energy Installation: Through-Hole, Surface Mount, Snap-In, Radial End User: Automotive, Telecommunications, Aerospace, Medical Devices |
| Companies Covered | KEMET Corporation, Xiamen Faratronic Co. Ltd., TDK Corporation, Cornell Dubilier Electronics, Nichicon Corporation, Panasonic Corporation, Vishay Intertechnology, Murata Manufacturing, AVX Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Film Capacitor Market Strategic Shifts & Innovations
Dielectric material science and regulatory chemistry requirements are restructuring competitive positioning in film capacitor manufacturing, with metallization technology and encapsulant reformulation emerging as primary differentiation vectors.
Segmented electrode metallization is electrifying high-voltage DC-link applications in electric vehicle powertrains. Tier-one automotive suppliers are adopting patterned metallized polypropylene constructions at accelerated qualification cycles. This electrode architecture is electrifying market entry for capacitor manufacturers with captive metallization capabilities, compressing margins for commodity film suppliers.
The EU F-Gas Regulation mandates phase-down of fluorinated greenhouse gases in capacitor cooling systems, compelling dry-type film designs without liquid impregnants. Industrial equipment OEMs in Germany are redesigning inverter thermal management around air-cooled polypropylene constructions. Power conversion suppliers serving European renewable energy projects are prioritizing dry-type film capacitors to preempt compliance-driven procurement restrictions.
Automotive tier-one buyers are consolidating supplier panels around vertically integrated film capacitor manufacturers with in-house polymer extrusion and metallization. Direct procurement agreements with Jiangsu province producers are displacing distributor-mediated supply for high-volume EV programs. This concentration pattern is most visible in China's Yangtze River Delta manufacturing corridor, where captive raw film supply anchors long-term supply contracts.
Film Capacitor Market Segmentation
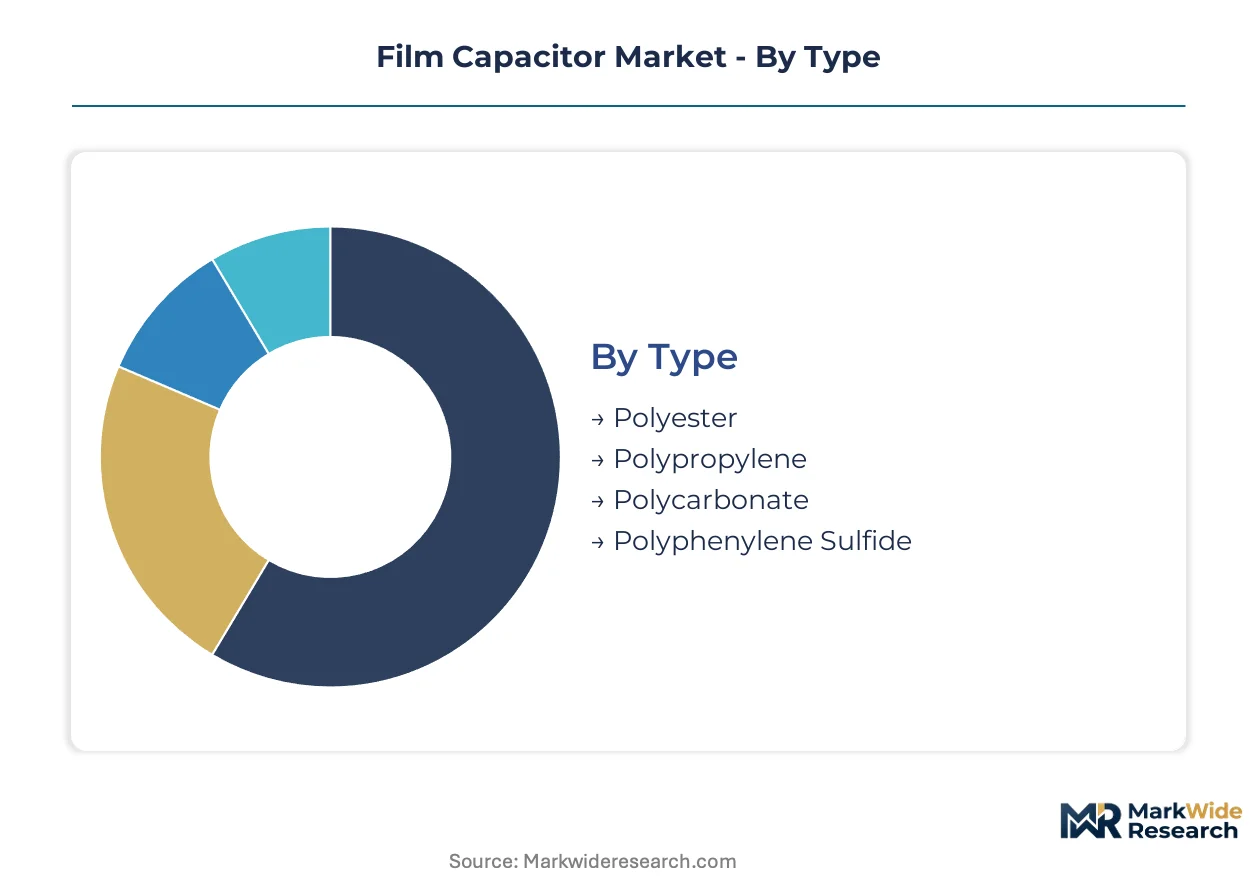
Film capacitor procurement patterns diverge sharply across dielectric chemistries and mounting configurations, with power electronics applications commanding premium specifications while consumer electronics segments face ceramic displacement pressures. Understanding these segment boundaries reveals where margin pools concentrate versus where commoditization accelerates.
Type:
Capacitor-grade polymer film supply concentrates among East Asian biaxial orientation specialists, creating divergent availability profiles for each dielectric chemistry.
- Polypropylene:Biaxially oriented polypropylene film delivers superior thermal stability and dielectric strength across temperatures exceeding 105°C. Demand concentrates in Germany's inverter manufacturing corridor and China's Jiangsu province automotive clusters, pulled by EV traction inverter qualification cycles and renewable energy converter deployments.
- Polyester:Polyethylene terephthalate film offers cost-efficient capacitance density for industrial signal conditioning and legacy power supplies. REACH compliance in Europe compels reformulation of phthalate-based encapsulant coatings, filtering non-compliant imports from Southeast Asian converters.
- Polycarbonate:High-precision capacitance stability across temperature extremes suits precision measurement instrumentation and military-grade timing circuits.
- Polyphenylene Sulfide:Aromatic polymer dielectric withstands surface mount reflow temperatures exceeding 260°C, enabling high-density automotive ECU integration.
Polypropylene absorbs the bulk of installed capacity; polyphenylene sulfide is expanding most quickly.
Application:
End-use requirements stratify film capacitor specifications across voltage handling, ripple current endurance, and volumetric efficiency thresholds.
- Power Electronics:DC-link capacitors in EV onboard chargers and solar string inverters demand metallized polypropylene constructions with self-healing electrode architectures. China's GB standards for grid-connected inverter ripple current endurance filter non-compliant imports, opening procurement pathways for certified domestic producers.
- Renewable Energy:Wind power converters and utility-scale solar installations utilize high-voltage polypropylene film banks for AC output filtering. EU F-Gas Regulation phase-down of fluorinated cooling gases accelerates dry-type film adoption in European renewable project tenders.
- Industrial Equipment:Motor drives and welding power supplies employ polyester film capacitors for EMI suppression and DC bus buffering, with growth constrained by ceramic substitution below 50 volts.
- Consumer Electronics:Power supply input filtering and audio crossover networks represent mature demand, with multilayer ceramic capacitors displacing film constructions in portable device miniaturization.
Power electronics commands the deepest margin pools; renewable energy is climbing the fastest.
Installation:
Mounting technology selection tracks assembly automation requirements and thermal management constraints across manufacturing geographies.
- Through-Hole:Radial leaded constructions dominate high-voltage industrial applications and repair-service aftermarket supply, with continued demand from legacy infrastructure maintenance in North American manufacturing bases.
- Surface Mount:Pick-and-place compatible film capacitors enable high-density automotive ECU and telecommunications equipment assembly, with polyphenylene sulfide dielectrics required for lead-free reflow compatibility.
- Snap-In:Quick-connect terminals accelerate inverter and UPS assembly line throughput, concentrating procurement among European power conversion OEMs redesigning thermal management around air-cooled constructions.
- Radial:Compact lead spacing variants serve consumer appliance motor run applications and lighting ballast designs, with specification convergence around IEC 60384 safety standards.
Through-hole retains the largest installed base; surface mount is gaining share fastest.
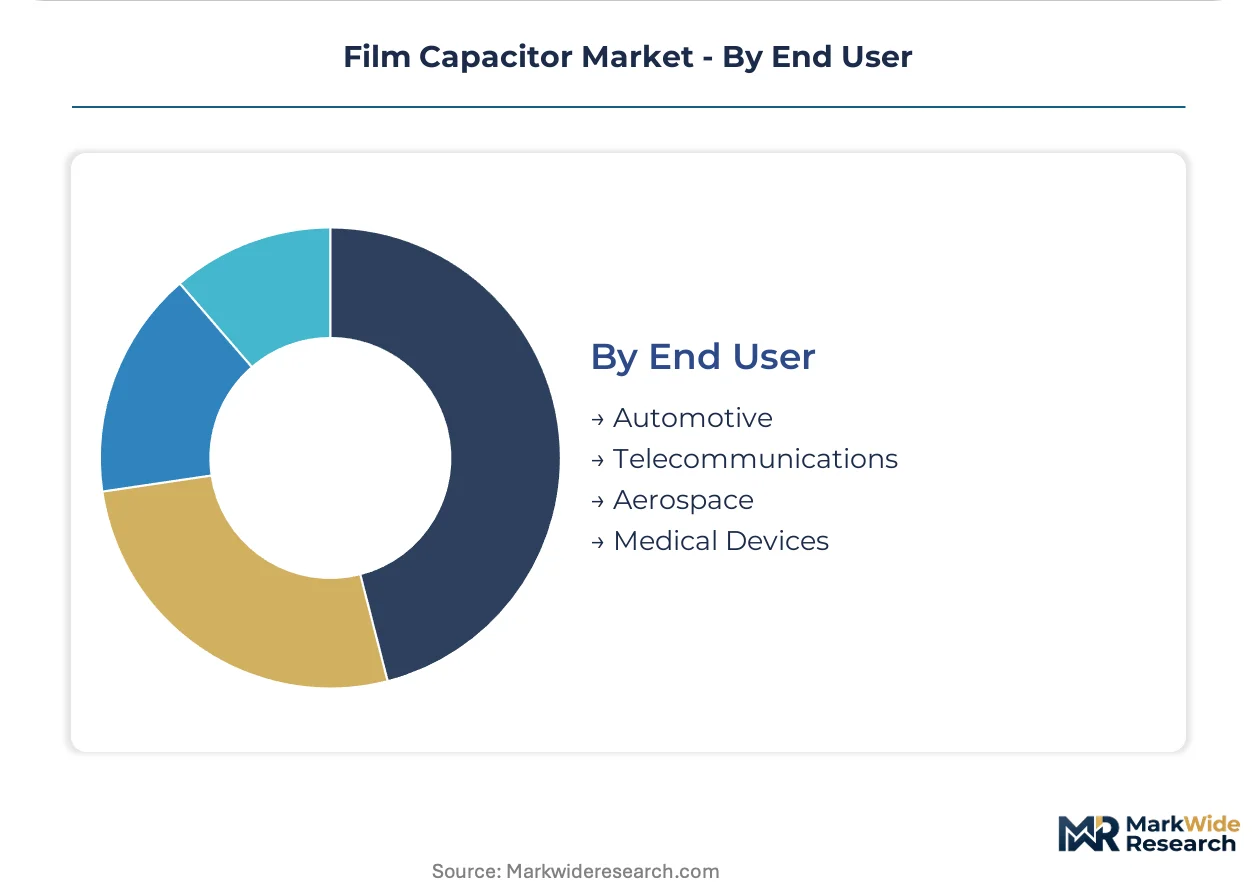
End User:
Customer certification requirements fragment film capacitor procurement around industry-specific insulation documentation and failure-mode analysis protocols.
- Automotive:Tier-one EV powertrain suppliers consolidate procurement around vertically integrated manufacturers with captive polypropylene film extrusion and in-house vacuum metallization. Jiangsu province producers anchor long-term supply contracts through direct procurement agreements displacing distributor mediation.
- Medical Devices:FDA electrical safety requirements for diagnostic imaging equipment mandate documented failure modes and enhanced insulation ratings, creating specialized demand for polyester film capacitors with traceable quality systems.
- Telecommunications:Base station power supplies and optical network equipment utilize surface mount film capacitors for EMI filtering, with 5G infrastructure deployment sustaining procurement volumes.
- Aerospace:DO-160 environmental qualification and outgassing restrictions limit qualified suppliers, with polyphenylene sulfide and polycarbonate constructions preferred for satellite and avionics applications.
Automotive absorbs the bulk of capacity expansion investment; medical devices commands the steepest premium tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capacitor-grade polypropylene film production clusters in East Asian biaxial orientation facilities, while European inverter manufacturers and Chinese automotive suppliers drive differentiated demand patterns across three continents.
Germany
Power electronics OEMs in Baden-Württemberg and Bavaria expand polypropylene film capacitor procurement for EV traction inverters and solar string converters. The EU F-Gas Regulation mandates dry-type film designs without liquid impregnants, compelling thermal management redesigns around air-cooled constructions. Industrial equipment manufacturers in the Stuttgart manufacturing corridor anchor inverter system assembly lines.
China
Jiangsu province automotive tier-one suppliers consolidate procurement around vertically integrated domestic producers with captive metallized film capabilities. GB standards for grid-connected inverter ripple current endurance filter non-compliant imports, opening certified procurement pathways for Yangtze River Delta manufacturers. Xiamen and Suzhou industrial clusters host concentrated polypropylene film extrusion and electrode deposition operations.
United States
FDA electrical safety requirements for diagnostic imaging equipment create specialized demand for polyester film capacitors with documented failure modes and enhanced insulation ratings. Medical device manufacturers in Massachusetts and Minnesota shape procurement specifications for precision instrumentation applications. Domestic capacitor fabricators serve aerospace and defense contractors with polyphenylene sulfide constructions for satellite avionics.
Japan
METI industrial policy supports high-frequency polypropylene development for wide-bandgap semiconductor integration in next-generation power electronics. Automotive ECU manufacturers in the Nagoya industrial corridor demand surface mount film capacitors with lead-free reflow compatibility. Kansai-region chemical producers supply aromatic polymer dielectrics for high-density electronic integration.
South Korea
Seoul Capital Area electronics conglomerates procure metallized film capacitors for telecommunications base station power supplies and 5G infrastructure deployment. Domestic polymer film suppliers realign biaxially oriented polypropylene output toward thicker capacitor-grade stocks. Busan-Ulsan manufacturing complexes support export-oriented passive component assembly for automotive and industrial customers.
Film Capacitor Market Key Industry Players
Global majors compete with regional champions across metallization technology and captive polymer supply, producing a tiered structure where vertically integrated Japanese and Korean conglomerates hold scale advantages while Chinese specialists capture automotive volume through direct procurement agreements. Three archetypes dominate: diversified electronics conglomerates with backward integration into dielectric film production, mid-cap regional specialists with concentrated metallization expertise, and captive suppliers serving single automotive OEM programs. Capacity expansion and strategic partnerships constitute the primary competitive vectors, with European manufacturers pursuing joint ventures to secure polypropylene film supply and East Asian players consolidating electrode deposition capabilities.
Within the diversified conglomerate tier, TDK Corporation exemplifies the vertically integrated model with upstream control over high-frequency polypropylene segments, while KEMET Corporation represents North American fabrication capabilities with in-house metallized film production. Xiamen Faratronic Co. Ltd. anchors the Chinese specialist archetype through captive raw polyester film supply and direct relationships with Jiangsu province automotive customers. These three occupy positions spanning premium EV powertrain specifications, industrial equipment reliability tiers, and high-volume standard product markets respectively.
| Leading Market Players |
|---|
| KEMET Corporation |
| Xiamen Faratronic Co. Ltd. |
| TDK Corporation |
| Cornell Dubilier Electronics |
| Nichicon Corporation |
| Panasonic Corporation |
| Vishay Intertechnology |
| Murata Manufacturing |
| AVX Corporation |
| Others |
Cost & Logistics Intelligence
Automotive tier-one procurement consolidation around vertically integrated suppliers is forcing smaller capacitor manufacturers to absorb metallization cost premiums or exit high-volume EV programs entirely. This buyer-driven concentration is compressing margins for non-integrated producers while rewarding captive film extrusion capabilities with pricing power in long-term supply agreements.
Pricing Analysis
Warranty and failure-mode documentation bundling separates medical-grade polyester film capacitors from standard industrial tiers, with FDA-compliant insulation ratings commanding substantial premiums over unbundled commodity constructions. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth, with automotive AEC-Q200 qualification and China GB ripple-current endurance filtering out economy-tier imports. Pricing pressure stems from ceramic substitution below 50 volts in consumer electronics signal paths. Industrial equipment OEMs exhibit highest price sensitivity due to mature demand and alternative sourcing options, while EV powertrain suppliers accept premium positioning for thermal stability guarantees.
Supply Chain Analysis
China's domestic-content requirements for grid-connected inverters under GB standards are redirecting procurement toward Jiangsu province producers with certified metallized film capabilities, displacing Southeast Asian imports. Capacitor-grade biaxially oriented polypropylene film concentrates in China, Japan, and South Korea, with European and North American manufacturers dependent on imported dielectric stock. Raw material dependencies center on polymer resin feedstocks, vacuum metallization equipment, and electrode deposition chemistry. Single-source vulnerability runs through East Asian polymer film suppliers following bioplastics capacity competition for packaging applications. Distribution runs through direct procurement agreements between automotive tier-ones and vertically integrated manufacturers, compressing distributor margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around metallization expertise and captive polymer supply, with dual certification timelines under EU F-Gas Regulation and China GB standards forcing weaker players into exit or acquisition.
For Market Incumbents: Anticipate ceramic substitution encroachment in low-voltage industrial segments by deepening backward integration into capacitor-grade polypropylene extrusion and securing long-term raw film offtake agreements with East Asian suppliers. Prioritize simultaneous EU F-Gas dry-type qualification and China GB ripple-current certification to compress competitor entry timelines. Channel control through direct automotive tier-one relationships in Jiangsu province anchors volume retention against emerging domestic competitors. For New Entrants and Emerging Players: Direct-to-autotive-platform digital procurement channels offer lower friction entry for certified metallized film suppliers without legacy distributor relationships. Target medical device insulation tiers in the United States where FDA documentation requirements filter established Asian competitors unfamiliar with traceable quality systems. Specialty renewable energy inverter servicing in Europe presents white-space opportunity as EU F-Gas Regulation accelerates dry-type redesign demand. Lead with rapid certification turnaround and localized technical support as primary go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors mid-cap metallization specialists with captive vacuum deposition capabilities and existing automotive qualification relationships. Long-term viability rests on polymer raw material security and switching-frequency convergence with wide-bandgap semiconductors. Target acquisition archetype: regional European or North American fabricators with certification infrastructure but lacking backward film integration. Watch China Jiangsu province capacity expansion rates as inflection indicator for pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polypropylene Extrusion | Captive dielectric supply secures margin retention against East Asian polymer price volatility. |
| Dual Certification Investment (EU F-Gas + China GB) | Simultaneous compliance opens procurement pathways in Germany's inverter corridor and Jiangsu automotive clusters. |
| Medical Device Quality System Development | FDA traceability requirements create defensible premium tier in diagnostic imaging equipment supply. |
| Wide-Bandgap Semiconductor Partnership | High-frequency polypropylene convergence enables next-generation EV traction inverter positioning. |
| Direct Procurement Agreement Expansion | Automotive tier-one panel consolidation rewards bypassing distributor intermediation in Yangtze River Delta. |
Research Approach
Multi-period observation of metallization capacity expansion, certification timeline compression, and automotive procurement panel consolidation anchored the trend analysis, supplemented by interviews with capacitor manufacturing executives, vacuum metallization equipment suppliers, automotive tier-one procurement directors, and polymer film extrusion specialists. Secondary validation drew from EU F-Gas Regulation implementation documents, China GB standard technical specifications, FDA electrical safety guidance for medical devices, SEC filings of passive component manufacturers, and trade flow data for capacitor-grade polymer film. Bottom-up segment sizing triangulated against top-down market envelope checks.
The input-output matrix framed demand drivers against supply constraints across dielectric chemistry, mounting technology, and end-user certification tiers. Segmentation dimensions modeled include polymer type, installation configuration, application voltage class, and regional regulatory cluster. CAGRs were derived from slope analysis of historical procurement volumes projected through technology adoption curves and regulatory compliance deadlines. Industry-specific forecast inputs incorporated EV powertrain inverter qualification cycles and renewable energy inverter deployment pipelines.
The model holds under stable polymer raw material allocation between packaging and capacitor-grade film; deviation in bioplastics capacity expansion rates or East Asian export restriction triggers would shift supply availability assumptions. Forecasts reflect documented certification timelines, buyer consolidation patterns, and substitution elasticity parameters. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Europe Water Cooled Capacitors Market
Electronic Components
Electronic Speed Controllers Market
Electronic Components
Gigabit Interface Converter Market
Electronic Components
Capacitor Kits Market
Electronic Components
Docking Station Market
Electronic Components
North America MLCC Market
Electronic Components
RAID Controller Card Market
Electronic Components
Wearable Display Device Materials Market
Electronic Components
Laser Direct Structuring (LDS) Antenna Market
Electronic Components
Ceramic Disc Capacitor Market
Electronic Components
Global Industrial Media Converters Market
Electronic Components
High Temperature Capacitor Market
Electronic Components
Cordless Phone Battery Market
Electronic Components
Speaker Membranes Market
Electronic Components
Metal Oxide Varistor (MOV) Market
Electronic Components
Electric Fuse Market