
 Electric Fuse Market | 2026-2036
Electric Fuse Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Fuse Market Analysis
Silver-copper composite metallization is expanding as the dominant arc-quenching architecture in medium-voltage fuse designs, displacing traditional pure-silver elements to reduce raw-material cost exposure. ABB leverages integrated fuse-switchgear portfolios to anchor European utility procurement cycles. Schneider Electric sustains R&D intensity in solid-state fuse alternatives for DC microgrid applications. Eaton dominates North American industrial channel access through distributor-exclusive product lines.
An electric fuse is a sacrificial overcurrent protection device comprising a metal wire or strip that melts when excessive current flows, permanently interrupting the circuit to prevent equipment damage or fire. Construction typically involves a fusible element housed in a ceramic or fiber body, with rated breaking capacities from tens of amperes to hundreds of kiloamperes depending on application voltage class. Cartridge-type fuses lead installed base volumes across heavy industrial equipment owing to standardized IEC dimensioning and field-proven reliability under short-circuit conditions. PCB-mount variants represent the fastest-expanding installation category as consumer electronics miniaturization demands surface-compatible protection footprints.
UL 248 standards in the United States and IEC 60269 frameworks in Europe mandate precise time-current characteristic bands, forcing manufacturers to maintain dual certification laboratories. China's GB 13539 national standard, administered by SAMR, imposes additional local testing protocols that condition market access for imported fuse assemblies. Stakeholders must monitor solid-state circuit protection displacement timelines and raw-material hedge positions against silver price cyclicality.
Market Dynamics
Data center power density escalation is compressing fuse replacement cycles from decade-long intervals to 3-5 year refresh schedules, forcing manufacturers to redesign thermal withstand curves for continuous overload tolerance.
Growth Catalysts
- IEC 60269-4 arc-fault coordination:Renewable inverter integration mandates in Germany and Spain are pulling medium-voltage fuse demand into utility-scale solar and wind interconnect substations.
- Silver-copper composite metallization:Raw-material substitution in fusible elements cuts noble metal exposure while maintaining interrupting ratings, expanding addressable cost bands for industrial buyers.
- China:Domestic renewable installations and State Grid modernization programs are concentrating procurement volumes for 12kV-36kV distribution fuse cutouts.
Market Restraints
- Silver price cyclicality:London Bullion Market Association spot volatility compresses gross margins on pure-silver fusible elements, exposing inventory valuation risk.
- Solid-state circuit breaker substitution:Silicon carbide power electronics in DC microgrids threaten conventional fuse displacement in 1500V solar string protection.
- Dual certification overhead:UL 248 and IEC 60269-1 testing divergence forces redundant laboratory investments, raising fixed cost barriers for entrants.
Strategic Opportunities
- India:Bureau of Indian Standards certification gaps in rural electrification create first-mover positioning for fuse-switchgear combinations in state distribution company tenders.
- DC fast-charging infrastructure:800V automotive platforms require specialized high-rupture-capacity fuses with arc-quenching ceramics, opening premium product tiers.
- RoHS recast exemption expirations:Lead-free fusible alloy development incentives align with EU Green Deal procurement preferences for sustainable supply chains.
Industry Challenges
- Short-circuit testing capacity scarcity:Megavolt-ampere fault simulation laboratories face 18-month booking queues, delaying new product qualification timelines.
- Legacy switchgear interoperability:Retrofit fuse coordination with 1980s-vintage air-insulated switchgear requires custom adapter engineering, fragmenting project economics.
- Field failure traceability:Distributed installation bases complicate root-cause analysis for nuisance fuse operations, straining warranty reserve calculations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Fuse Market |
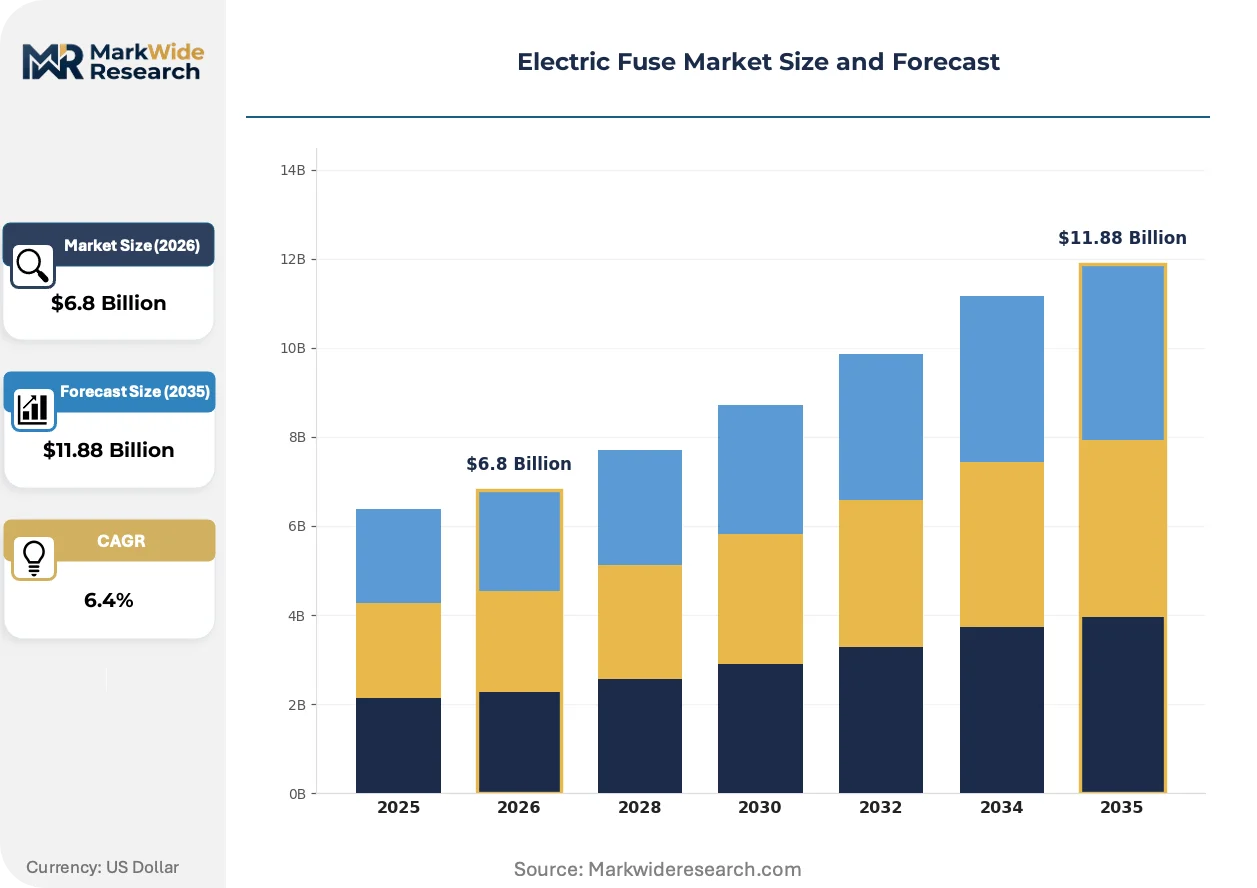
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Cartridge, Blade, Resettable, Glass Application: Industrial Equipment, Consumer Electronics, Automotive, Aerospace End User: Manufacturers, Electricians, DIY Users, Wholesalers Installation: Panel Mount, DIN Rail, PCB Mount, Surface Mount |
| Companies Covered | ABB, Schneider Electric, Eaton, Siemens, Mersen, Littelfuse, Bel Fuse, Fuji Electric, Schurter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Fuse Market Emerging Trajectories
Arc-quenching material science and digital protection coordination are redrawing competitive boundaries between electromechanical fuses and solid-state alternatives across voltage classes.
Self-healing polymer composite fuse bodies are decentralizing thermal management architecture in medium-voltage designs. Data center operators in Northern Virginia and Frankfurt are specifying these for 480V bus duct protection to eliminate ceramic fragmentation risks during high-fault interruptions. The shift is decentralizing supplier qualification criteria toward material traceability rather than pure metallurgical heritage.
EU F-Gas Regulation phase-down schedules are pressuring sulfur hexafluoride-dependent switchgear manufacturers to specify fuse-protected air-insulated alternatives. Industrial buyers in the Rhine-Ruhr manufacturing corridor are rewriting procurement specifications to exclude SF6-containing assemblies. Medium-voltage fuse producers with dry-air or vacuum interrupter portfolios are capturing these retrofit volumes.
Specifying engineers are consolidating vendor lists around integrated fuse-switchgear portfolios, collapsing the historical separation between protection component and enclosure procurement. European utilities are bundling 20-year service agreements with initial fuse purchases, transferring inventory risk to manufacturers. This concentration is most visible in German distribution network operator frameworks, where single-source contracts now cover both primary fuses and downstream coordination studies.
Electric Fuse Market Segmentation
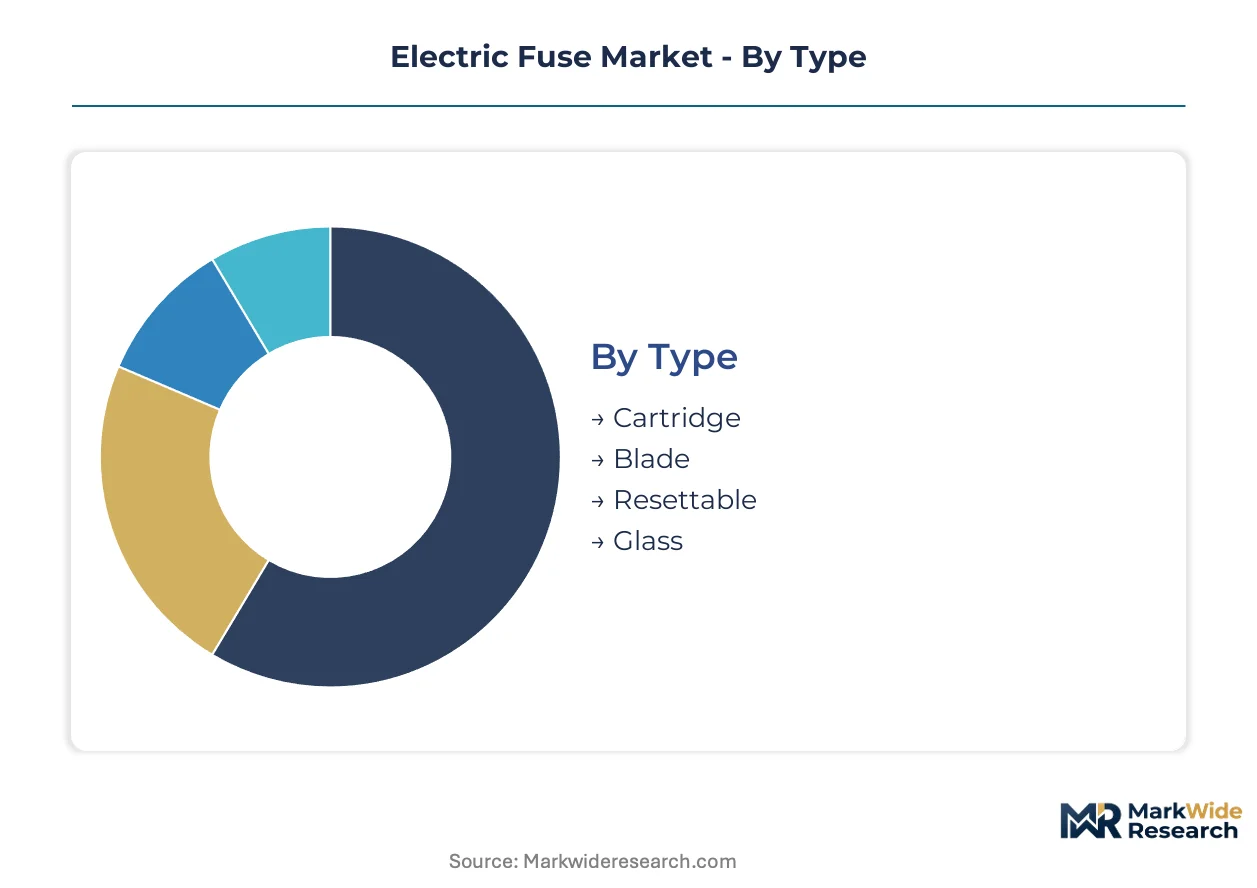
Fuse segmentation reflects divergent technical requirements across voltage classes and replacement-cycle economics. Equipment refresh timelines vary dramatically—from decade-long industrial intervals to sub-5-year data center schedules—creating distinct procurement behaviors by segment.
Type:
Upgrade cycles in industrial infrastructure are compressing demand patterns across fuse architectures, with thermal tolerance specifications tightening fastest in medium-voltage categories.
- Cartridge:Cylindrical ceramic or fiber-bodied fuses with standardized IEC dimensioning dominate heavy industrial motor protection and distribution feeder circuits. German utility-scale solar interconnect substations are pulling cartridge fuse demand through IEC 60269-4 arc-fault coordination mandates for renewable inverter integration.
- Blade:Flat metal strip elements housed in plastic bodies serve automotive auxiliary circuits and low-voltage industrial control panels. China's State Grid modernization programs are concentrating procurement volumes for blade-type distribution fuse cutouts in 12kV-36kV rural electrification projects.
- Resettable:Polymeric positive temperature coefficient devices self-restore after fault clearance, eliminating replacement labor in inaccessible installations.
- Glass:Sealed tubular designs with precise ampere ratings protect consumer electronics power entry modules and laboratory instrumentation.
Cartridge fuses sit at the top of the volume ranking, with blade fuses climbing the fastest on renewable infrastructure deployment.
Application:
Cost-tier stratification separates premium aerospace specifications from commoditized consumer electronics protection, with certification overhead driving 3-5x pricing spreads between tiers.
- Industrial Equipment:High-rupture-capacity cartridge fuses protect motor starters, transformers, and switchgear in manufacturing plants. Northern Virginia data center operators are specifying self-healing polymer composite fuse bodies for 480V bus duct protection to eliminate ceramic fragmentation risks during high-fault interruptions.
- Consumer Electronics:Miniature PCB-mount and surface-mount fuses safeguard smartphones, laptops, and appliance power supplies. Frankfurt data center clusters are driving demand for compact fuse footprints in power distribution unit miniaturization.
- Automotive:Blade and bolt-down fuses protect 12V/48V electrical systems in internal combustion and electric vehicle platforms.
- Aerospace:MIL-PRF-qualified fuses with extreme temperature tolerance protect avionics and flight-critical systems in commercial and defense aircraft.
Industrial Equipment commands the largest revenue pool, while Automotive is expanding most quickly on 800V platform proliferation.
End User:
Procurement authority concentration favors manufacturers and wholesalers, with electrician and DIY channels fragmenting on specification complexity and certification requirements.
- Manufacturers:Original equipment builders specify fuses at design stage, locking in multi-year supply agreements for production volumes. ABB leverages integrated fuse-switchgear portfolios to anchor European utility procurement cycles through manufacturer-direct contracting.
- Wholesalers:Electrical distributors stock broad SKU ranges for contractor fulfillment, carrying inventory risk on slow-moving specialty ratings. Eaton dominates North American industrial channel access through distributor-exclusive product lines that capture wholesaler shelf space.
- Electricians:Field service technicians specify replacement fuses based on existing panel labeling and local code requirements.
- DIY Users:Retail consumers purchase automotive and small-appliance fuses through hardware stores and e-commerce platforms.
Manufacturers retain the dominant procurement share, with Wholesalers gaining influence fastest on integrated fuse-switchgear bundling trends.
Installation:
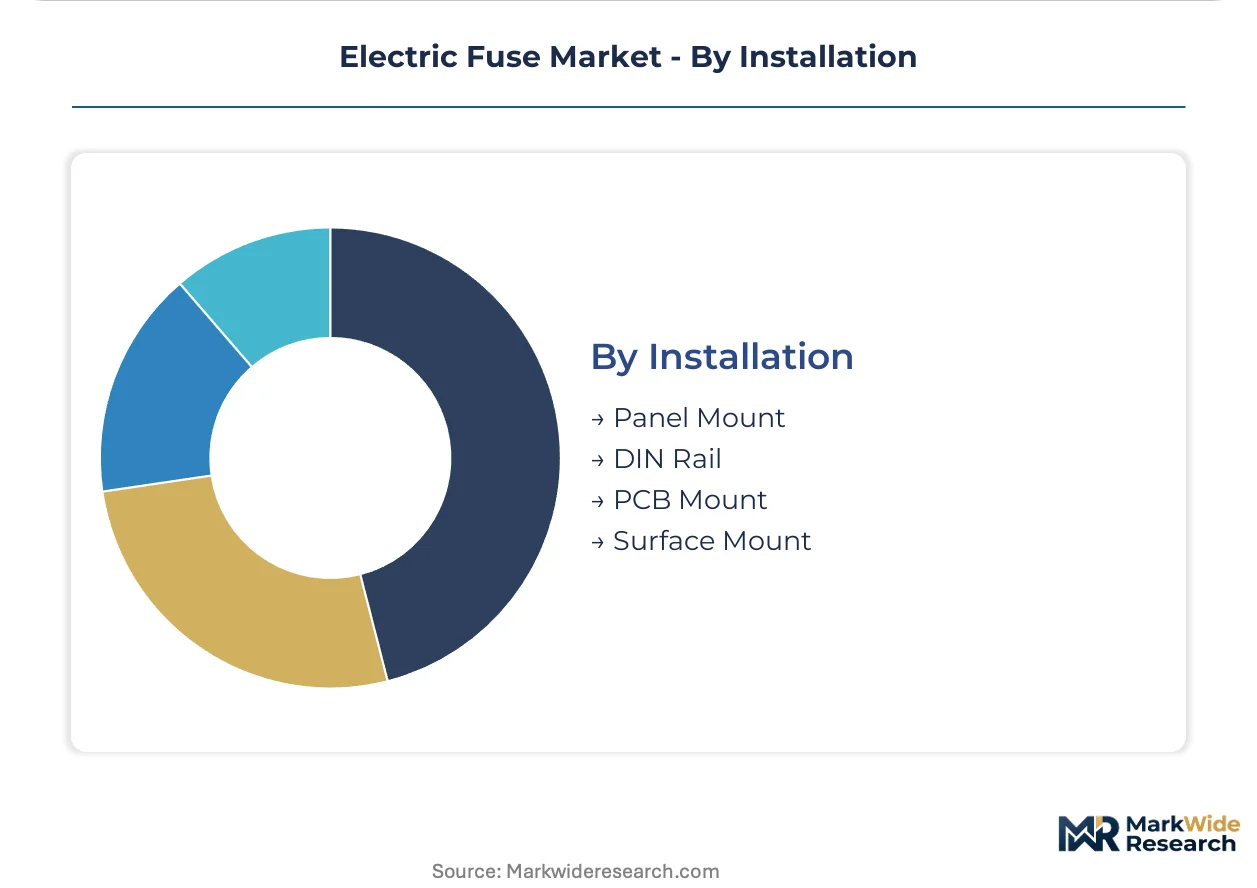
Mounting method selection traces directly to voltage class and accessibility requirements, with DIN Rail and PCB Mount formats capturing divergent growth vectors on industrial automation and electronics miniaturization respectively.
- DIN Rail:Snap-on modular fuses integrate with standardized industrial control panel architectures. Schneider Electric sustains R&D intensity in solid-state fuse alternatives for DC microgrid applications that mount on DIN Rail infrastructure.
- PCB Mount:Surface-compatible fuse footprints solder directly onto printed circuit boards in consumer electronics and automotive control modules. Silver-copper composite metallization in PCB-mount designs cuts noble metal exposure while maintaining interrupting ratings for industrial buyers.
- Panel Mount:Threaded or bracket-fixed fuses install through equipment enclosure walls for field-replaceable protection.
- Surface Mount:Tape-and-reel compatible chip fuses enable automated assembly in high-volume electronics manufacturing.
DIN Rail leads installed base volumes, with PCB Mount showing the steepest expansion trajectory on consumer electronics density trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr manufacturing corridor anchors procurement volumes for fuse-protected air-insulated switchgear as EU F-Gas Regulation phase-down schedules pressure sulfur hexafluoride-dependent alternatives. State Grid modernization programs and domestic renewable installations are redrawing procurement gravity across multiple voltage classes.
United States
Northern Virginia data center clusters specify self-healing polymer composite fuse bodies for 480V bus duct protection to eliminate ceramic fragmentation risks. FERC interconnection standards and OSHA electrical safety mandates tighten coordination requirements for utility-scale solar and storage projects. Texas and Arizona solar belt developments are pulling medium-voltage fuse demand into utility interconnect substations.
Germany
Distribution network operators bundle 20-year service agreements with fuse purchases under single-source frameworks covering primary protection and coordination studies. EU F-Gas Regulation and IEC 60269-4 arc-fault coordination mandates accelerate renewable inverter integration specifications. The Rhine-Ruhr corridor rewrites procurement specifications to exclude SF6-containing assemblies, favoring dry-air or vacuum interrupter portfolios.
China
State Grid modernization programs concentrate procurement volumes for 12kV-36kV distribution fuse cutouts across rural electrification corridors. SAMR-administered GB 13539 national standards impose additional local testing protocols conditioning market access for imported assemblies. Yangtze River Delta manufacturing hubs scale silver-copper composite metallization to reduce noble metal exposure in medium-voltage designs.
India
Bureau of Indian Standards certification gaps in rural electrification create positioning opportunities for fuse-switchgear combinations in state distribution company tenders. CEA grid codes and PLI scheme incentives for domestic manufacturing reshape supplier qualification criteria. Maharashtra and Gujarat industrial corridors drive demand for high-rupture-capacity cartridge fuses in manufacturing plant motor protection.
Japan
METI energy efficiency directives and JIS standards for industrial electrical equipment tighten thermal withstand specifications for continuous overload tolerance. Kanto and Kansai manufacturing belts specify PCB-mount fuse footprints for automotive electronics and industrial control module miniaturization. Solid-state fuse alternatives for DC microgrid applications attract sustained R&D intensity from domestic component suppliers.
Electric Fuse Market Vendor Landscape
Global majors compete with regional champions across certification laboratory access and integrated portfolio breadth. The vendor base stratifies into three tiers: multinational electrical conglomerates with dual UL-IEC certification infrastructure, mid-cap specialists with voltage-class focus, and commodity producers serving replacement markets. Consolidation pressure intensifies as specifying engineers collapse vendor lists around bundled fuse-switchgear offerings. Dominant competitive moves include M&A to acquire arc-quenching material science capabilities and capacity expansion in silver-copper composite metallization.
Within the multinational tier, ABB leverages integrated fuse-switchgear portfolios to anchor European utility procurement cycles, while Schneider Electric sustains R&D positioning in solid-state alternatives. Eaton exemplifies North American channel dominance through distributor-exclusive arrangements. These three conglomerates represent the archetype of certification-heavy, service-bundled market presence.
| Leading Market Players |
|---|
| ABB |
| Schneider Electric |
| Eaton |
| Siemens |
| Mersen |
| Littelfuse |
| Bel Fuse |
| Fuji Electric |
| Schurter |
| Others |
Supply Flow & Price Mechanics
Data center operator consolidation around 20-year service agreements is forcing fuse manufacturers to absorb inventory risk and recalibrate pricing models toward lifecycle value rather than transactional component sales. This procurement shift compresses margins on standardized cartridge products while opening premium tiers for integrated fuse-switchgear portfolios with embedded coordination engineering.
Pricing Analysis
Silver-copper composite metallization in fusible elements is transmitting London Bullion Market Association spot volatility directly into manufacturing cost structures. Three-tier pricing structure across premium, standard, and economy levels separates UL-IEC dual-certified industrial grades from single-standard commercial ratings and commodity replacement fuses. Cost compression in pure-silver element tiers is intensifying because raw-material hedge positions prove inadequate during price spikes. Electricians and field service technicians exhibit highest price sensitivity on replacement orders, while original equipment manufacturers lock in multi-year supply agreements with limited renegotiation flexibility.
Supply Chain Analysis
Silver and copper feedstock supply rests on Yangtze River Delta smelters, Peruvian mining operations, and Chilean concentrate exporters. Ceramic fuse body production draws from Japanese and German specialty refractory manufacturers, while arc-quenching filler compounds rely on Chinese and American chemical processors. Single-source vulnerability concentrates in megavolt-ampere fault simulation laboratory capacity, where 18-month booking queues delay new product qualifications. Distribution runs through electrical wholesalers carrying broad SKU ranges for contractor fulfillment, with manufacturer-direct contracting gaining share on utility-scale projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric fuse market functions as a stable compounder anchored by non-discretionary replacement demand from industrial infrastructure and data center power density escalation. Regulatory tightening on arc-fault coordination and SF6 phase-down schedules creates predictable specification upgrade cycles.
For Market Incumbents: Deploy integrated fuse-switchgear bundling to capture 20-year service agreement procurement frameworks and transfer inventory risk to balance sheets. Expand silver-copper composite metallization capacity in Yangtze River Delta manufacturing hubs to reduce noble metal exposure. Solid-state circuit breaker substitution in 1500V DC microgrids demands accelerated R&D positioning in self-restoring protection alternatives.
For New Entrants and Emerging Players: E-commerce platforms for automotive blade fuse replacement offer lowest barrier to initial revenue, bypassing wholesaler shelf-space competition dominated by established distributor-exclusive arrangements. India's Bureau of Indian Standards certification gaps in rural electrification present the most penetrable geography for fuse-switchgear combinations. Target state distribution company tenders with pre-engineered coordination studies to differentiate from component-only suppliers.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists possessing arc-quenching material science capabilities and dual UL-IEC certification infrastructure. Long-term viability over a 5-10 year horizon favors manufacturers with backward integration into silver-copper metallization and captive testing laboratory access. Monitor solid-state protection displacement timelines in solar string applications as the critical inflection signal for conventional fuse demand erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silver-Copper Metallization | Yangtze River Delta captive production reduces LBMA spot price exposure for industrial fuse tiers. |
| Dual Certification Laboratory Expansion | UL 248 and IEC 60269-1 parallel testing capacity shortens 18-month qualification queues for new product introductions. |
| Integrated Fuse-Switchgear Portfolio Development | German distribution network operator frameworks now bundle 20-year service agreements with primary protection procurement. |
| Self-Healing Polymer Composite Fuse Body Scale-Up | Northern Virginia data center specifications favor polymer bodies over ceramic to eliminate fragmentation risks during high-fault interruptions. |
| Solid-State Fuse Alternative R&D Investment | Silicon carbide power electronics in 1500V solar string protection threaten conventional fuse displacement without competitive response. |
Methodological Framework
Direct dialogue with plant engineers, electrical contractor procurement managers, utility protection engineers, and fuse manufacturer product directors grounded qualitative findings in operational reality. Secondary validation drew from IEC 60269 and UL 248 certification databases, State Grid and FERC interconnection filings, and London Bullion Market Association silver price series. Bottom-up demand modeling triangulated against top-down macroeconomic drivers to ensure segment-level consistency.
Bottom-up volume builds aggregated fuse replacement cycles by voltage class, installation method, and end-use sector across the analysis window. Top-down cross-checks applied industrial production indices and data center power capacity expansion to validate demand trajectories. Segmentation dimensions modeled include fuse architecture, application voltage class, mounting format, and procurement channel. CAGRs derived from fitted growth curves incorporating technology substitution elasticities and regulatory mandate implementation schedules.
The model assumes a particular technology adoption path for solid-state circuit protection; alternative pathways for silicon carbide power electronics would alter the outlook for conventional fuse demand erosion. Forecasts incorporate assumptions on silver price cyclicality, dual certification harmonization timelines, and data center refresh rate compression. A small set of triggers—solid-state protection cost parity, F-Gas Regulation enforcement intensity, and megavolt-ampere laboratory capacity expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Discrete Capacitors Market
Electronic Components
China Data Converter Market
Electronic Components
Aluminum Electrolytic Capacitor Market
Electronic Components
Display Port Adapters Market
Electronic Components
North America MLCC Market
Electronic Components
Video Surveillance Chip Market
Electronic Components
United States MLCC Market
Electronic Components
Encoder Market
Electronic Components
Flash Charger Adapter Market
Electronic Components
Impulse Relays Market
Electronic Components
Chip Shield Market
Electronic Components
Global Waveguide Components and Assemblies Market
Electronic Components
Tower Mounted Amplifier Market
Electronic Components
United States Radiation-Hardened Electronics Market
Electronic Components
Lead Zirconate Titanate (PZT) Market
Electronic Components
Single Layer Capacitors Market