
 Electronic Speed Controllers Market | 2026-2036
Electronic Speed Controllers Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Speed Controllers Market Insights
Drone end-use vertical is hardening as the fastest-expanding demand channel for electronic speed controllers, pulling procurement volumes away from traditional radio-controlled hobby applications. Hobbywing Technology Co., Ltd. leverages its Shenzhen manufacturing base to dominate consumer-grade brushless ESC supply chains. Castle Creations sustains premium positioning in high-performance racing and industrial segments through advanced firmware architectures. T-MOTOR anchors the commercial drone propulsion stack with integrated motor-controller systems that reduce wiring complexity.
An electronic speed controller modulates power delivery to electric motors through pulse-width modulation circuits, managing commutation timing in brushless three-phase systems with switching frequencies typically ranging from 8 kHz to 32 kHz. The device converts DC battery input into phased AC output while regulating RPM through throttle signal interpretation from flight controllers or receiver units. Brushless product type commands the largest revenue share due to superior efficiency and thermal performance in sustained-load applications. PID control technology leads algorithm deployment for stability-critical drone operations, while embedded installation formats gain traction as OEMs pursue weight reduction in airframe design.
FAA Part 107 rules and forthcoming Remote ID mandates in the United States impose operational constraints that elevate controller reliability requirements for commercial drone fleets. EASA's Specific Category framework in Europe demands fail-safe architectures and redundant signal pathways that increase ESC complexity and certification costs. IEC 60034-30-1 efficiency classes and REACH substance restrictions further constrain component selection and manufacturing processes. Stakeholders must monitor regulatory divergence between FAA trajectory-based operations and EASA's risk-based categories when designing platform-agnostic controller portfolios.
Market Dynamics
Drone delivery networks and urban air mobility platforms are compressing development cycles for high-efficiency brushless controllers, forcing suppliers to prioritize thermal performance and fail-safe architectures over cost optimization.
Growth Catalysts
- FAA Part 107 and Remote ID mandates:Commercial drone fleets in the United States face escalating reliability requirements that drive replacement cycles and premium ESC procurement.
- Urban air mobility infrastructure:Electric vertical take-off and landing platforms demand integrated motor-controller systems with redundant signal pathways.
- Shenzhen manufacturing ecosystem:Concentrated electronics supply chains enable rapid prototyping and cost-efficient scaling of brushless controller production.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings directly impact brushless motor and controller input costs.
- EASA certification complexity:The Specific Category framework imposes redundant architecture requirements that extend development timelines and inflate R&D expenditure.
- Silicon carbide MOSFET supply concentration:Advanced switching component production concentrates among limited foundry operators, creating procurement bottlenecks for high-frequency designs.
Strategic Opportunities
- India defense and agricultural drone programs:PLI scheme incentives and BIS standardization create entry pathways for certified ESC suppliers.
- GaN-SiC hybrid switching convergence:Gallium nitride and silicon carbide technology integration enables 48V-800V platform flexibility for next-generation electric aircraft.
- Embedded firmware-as-a-service models:Subscription-based algorithm updates offer recurring revenue streams beyond hardware sales to commercial fleet operators.
Industry Challenges
- Power electronics talent scarcity:Specialized firmware engineers with PID tuning and thermal management expertise command premium compensation and extended recruitment cycles.
- Dual certification burden:IEC 60034-30-1 efficiency validation alongside FAA airworthiness documentation creates parallel compliance tracks that strain smaller engineering teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Speed Controllers Market |
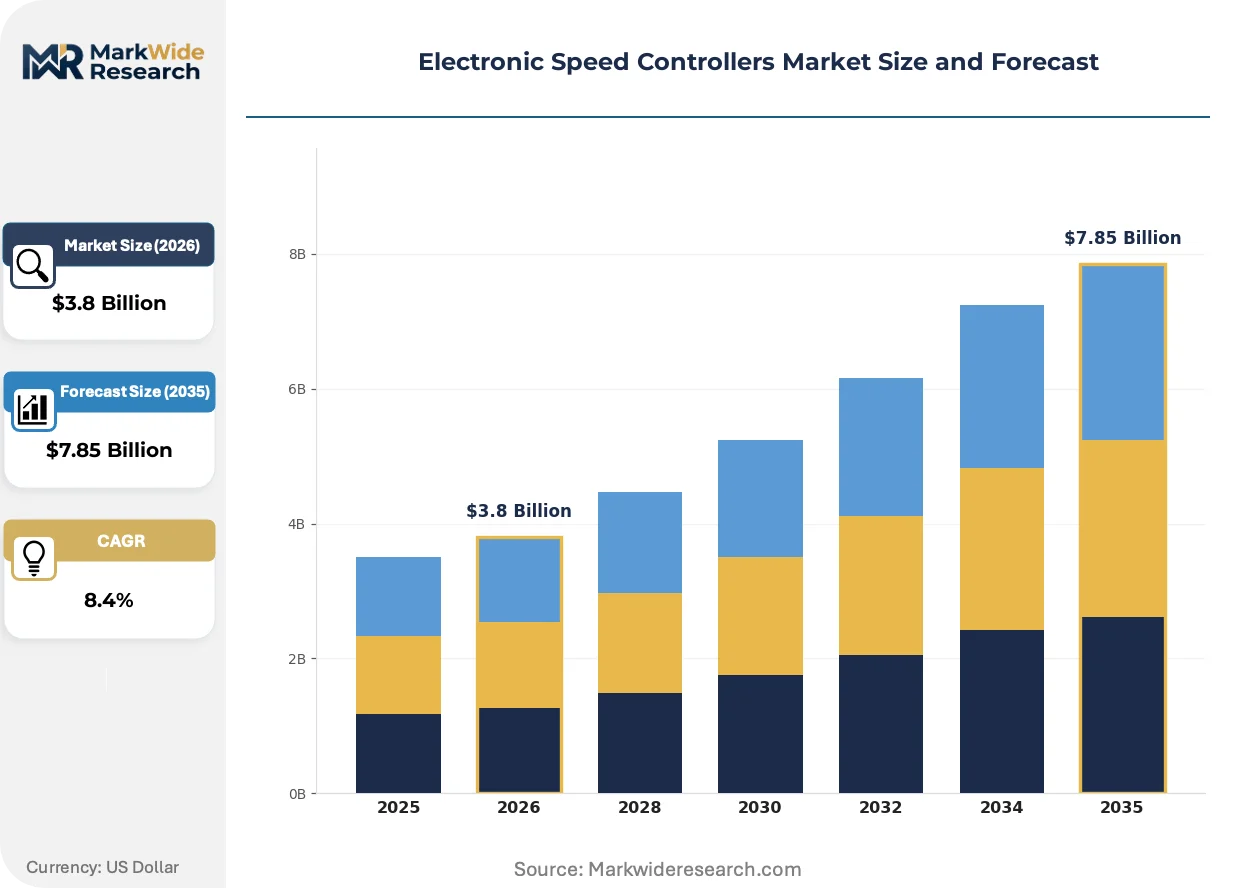
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brushed, Brushless, Digital, Analog Technology: PID Control, Fuzzy Logic, PWM, Linear Installation: Embedded, Standalone, Remote, Integrated End User: Consumer Electronics, Automotive, Industrial Automation, Drones |
| Companies Covered | Hobbywing Technology Co., Ltd., Align Corporation Limited, Thunder Tiger Corp., Castle Creations, Scorpion Power System, T-MOTOR, Embention S.L., Aikon Electronics, Graupner, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Speed Controllers Market Trends and Innovations
Distributed control architectures and wide-bandgap semiconductors are rewriting performance benchmarks, while regulatory fragmentation between aviation authorities forces modular design strategies.
GaN-based switching topology is decentralizing thermal management requirements in high-density ESC designs. Commercial drone manufacturers in Germany and Japan are adopting these systems for sustained-load applications. This shift is decentralizing the traditional dominance of silicon MOSFET suppliers and compressing form-factor constraints for integrated propulsion stacks.
EASA's Specific Category framework and forthcoming drone noise regulations are mandating active braking and harmonic reduction features. These requirements add firmware complexity and extend certification timelines. Racing and cinematography segments in Europe are absorbing these costs fastest, while hobby markets face margin compression.
Direct procurement from Shenzhen design houses is displacing traditional distributor channels for mid-volume commercial buyers. North American and European system integrators now bypass regional wholesalers to access firmware-customizable controllers. This pattern is most visible among agricultural spraying drone assemblers in Australia and Brazil seeking rapid iteration cycles.
Electronic Speed Controllers Market Segmentation
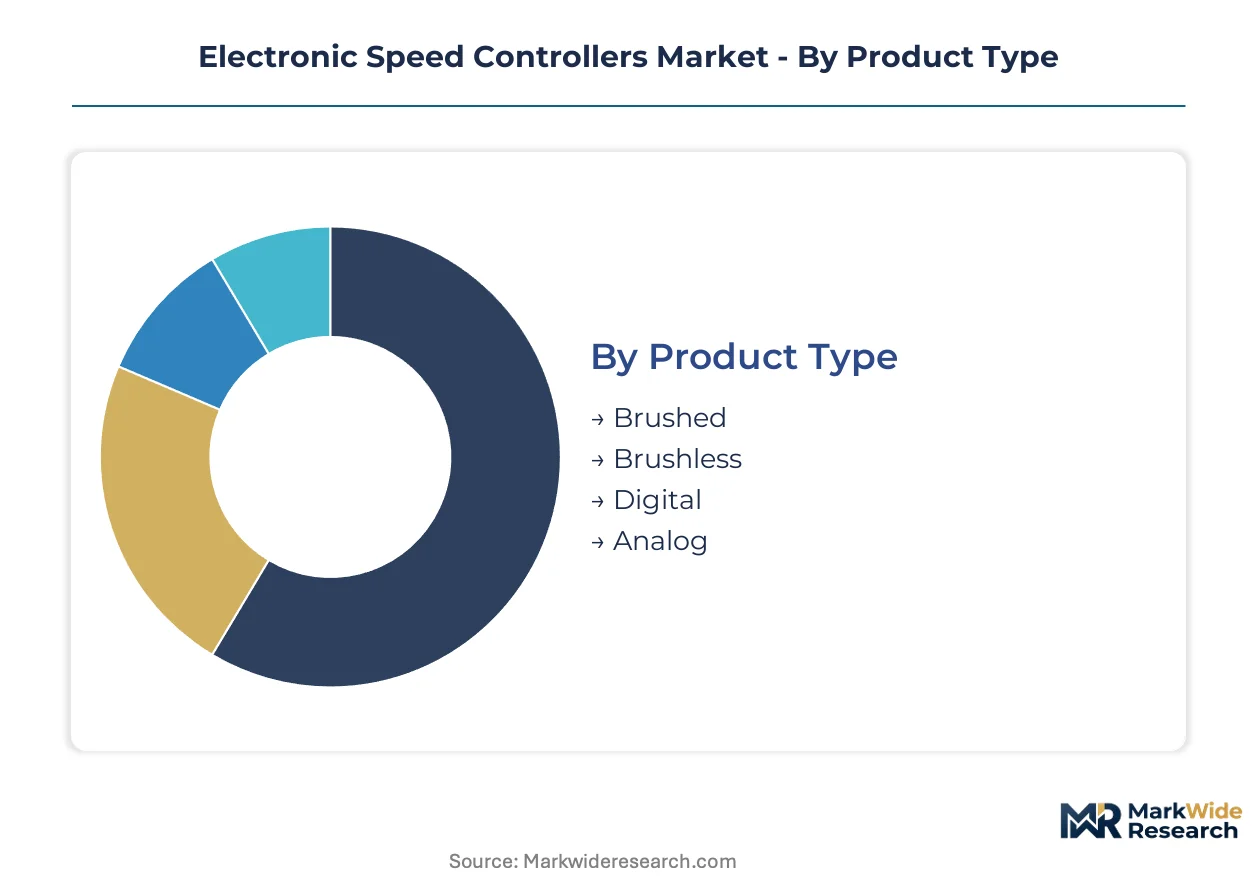
ESC segmentation reveals sharp divergences between commodity hobby-grade controllers and precision-engineered systems for commercial aviation. Procurement patterns cluster around thermal performance thresholds and certification requirements rather than price alone.
Product Type:
Brushless variants command premium positioning through superior efficiency metrics, while brushed units retain volume presence in cost-constrained applications.
- Brushless:Three-phase commutation architectures with switching frequencies between 8 kHz and 32 kHz deliver sustained-load thermal stability. Demand concentrates in Shenzhen-manufactured systems for commercial drone fleets operating under FAA Part 107 reliability mandates. Neodymium magnet cost volatility constrains margin expansion despite technology leadership.
- Brushed:DC motor control through mechanical commutation suits low-RPM, intermittent-duty cycles. Hobby applications in North America and Europe absorb the majority of procurement volumes as entry-level radio-controlled platforms. IEC 60034 efficiency standards threaten obsolescence in industrial settings.
- Digital:Microprocessor-based signal processing enables firmware-upgradable control algorithms.
- Analog:Discrete component architectures persist in electromagnetic interference-sensitive environments.
Mature deployment sits with Brushed controllers. Newer deployment is concentrated in Brushless systems.
Technology:
Algorithm sophistication separates stability-critical drone operations from basic motor control, with firmware architecture determining certification pathway complexity.
- PID Control:Proportional-integral-derivative feedback loops dominate commercial UAV stabilization through real-time error correction. Drone delivery networks in Germany and Japan specify PID-tuned controllers for payload oscillation suppression. EASA Specific Category fail-safe requirements extend firmware validation timelines.
- PWM:Pulse-width modulation circuits convert DC battery input to phased AC output across brushless three-phase windings. Consumer electronics manufacturing in China sources PWM controllers at scale for appliance motor drives. Silicon carbide MOSFET supply concentration creates procurement bottlenecks for high-frequency designs.
- Fuzzy Logic:Rule-based adaptive control suits nonlinear load conditions without precise system modeling.
- Linear:Continuous voltage regulation avoids switching noise for audio and precision instrumentation applications.
Established integration sits with PWM architectures. Accelerating adoption is visible in PID Control deployments.
Installation:
Physical integration depth reflects airframe weight constraints and maintenance accessibility tradeoffs across vehicle classes.
- Embedded:PCB-mounted controllers eliminate connector mass and wiring harness complexity. Urban air mobility platforms in the United States demand embedded formats for electric vertical take-off and landing propulsion stacks. Thermal management challenges intensify as power density increases.
- Integrated:Motor-controller unified housings reduce electromagnetic compatibility testing burden. Agricultural drone assemblers in Australia and Brazil source integrated systems from Shenzhen design houses for rapid iteration cycles. EASA noise regulation compliance adds firmware complexity for active braking features.
- Standalone:Modular enclosures permit field replacement without propulsion system disassembly.
- Remote:Distributed mounting separates power electronics from heat-generating motor assemblies.
Volume concentration rests with Standalone formats. Steepest expansion trajectory belongs to Embedded installations.
End User:
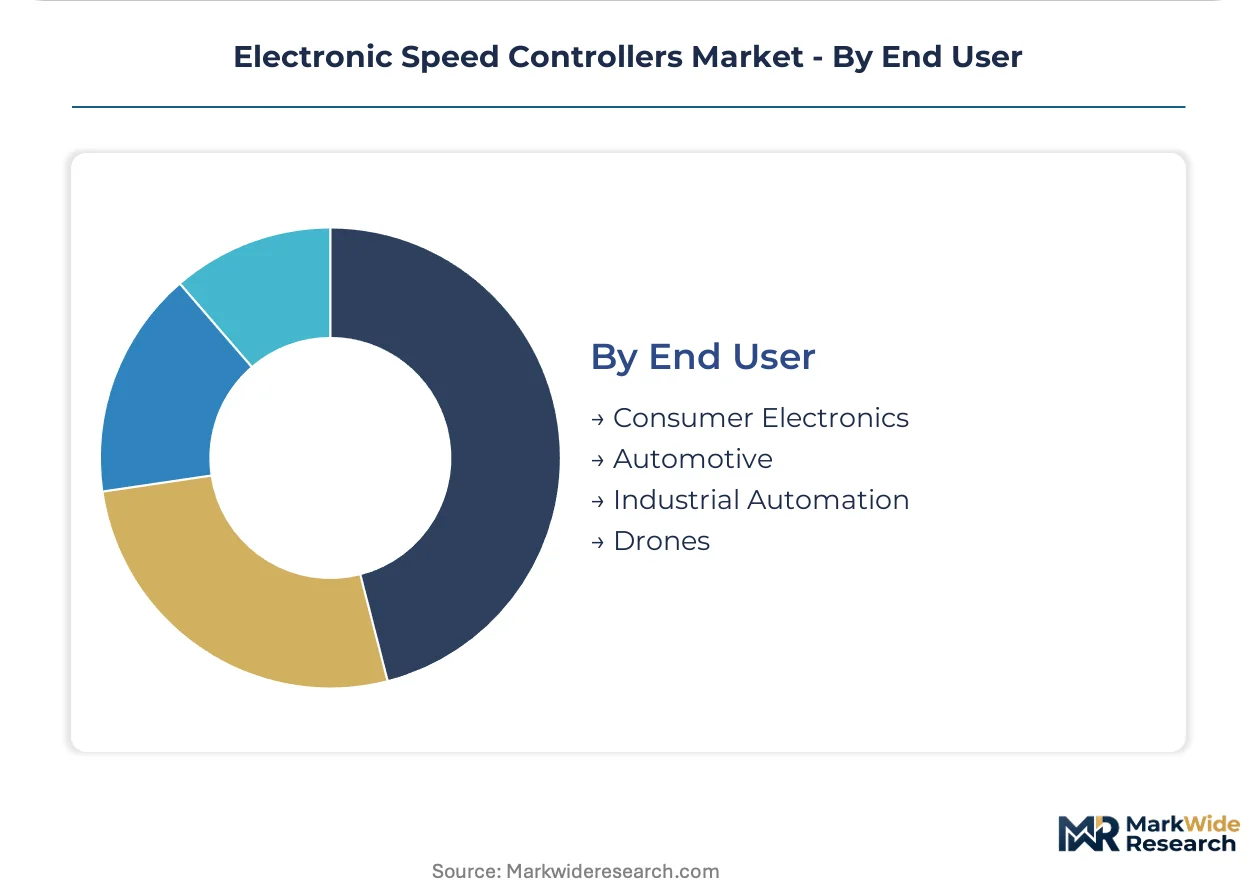
Application-specific reliability tiers create distinct procurement specifications, from consumer hobby budgets to airworthiness-certified industrial systems.
- Drones:Multi-rotor and fixed-wing platforms require redundant signal pathways and fail-safe throttle cutoffs. Commercial fleet operators in the United States face Remote ID mandate compliance costs that elevate controller replacement cycles. GaN-SiC hybrid switching convergence enables 48V-800V platform flexibility for next-generation electric aircraft.
- Industrial Automation:Servo motor precision positioning demands closed-loop feedback integration. Factory automation deployments in Japan specify IEC 60034-30-1 efficiency class compliance for motor-controller pairings. Power electronics talent scarcity extends recruitment cycles for specialized firmware engineers.
- Consumer Electronics:Appliance and personal device motor control prioritizes cost minimization over thermal performance.
- Automotive:Electric powertrain auxiliary systems require automotive-grade temperature and vibration specifications.
Margin stability aligns with Industrial Automation. Share gains are materializing fastest in Drones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of global ESC output through Shenzhen's concentrated electronics ecosystem, while the United States and Germany absorb premium volumes for commercial aviation and industrial automation applications.
United States
Commercial drone fleets and urban air mobility prototypes drive procurement of fail-safe brushless controllers. FAA Part 107 rules and forthcoming Remote ID mandates elevate reliability requirements for fleet operators. California-based system integrators source directly from Shenzhen design houses to compress iteration cycles for agricultural spraying platforms.
Germany
Industrial automation and precision racing segments demand IEC 60034-30-1 efficiency class compliance in motor-controller pairings. EASA's Specific Category framework imposes redundant signal pathway requirements that extend certification timelines. Bavarian drone manufacturers absorb these costs fastest for cinematography and surveying applications.
China
Shenzhen's vertically integrated electronics manufacturing base supplies consumer and industrial ESC volumes at scale. MIIT motor efficiency standards and dual carbon goals reshape product design requirements for export markets. Pearl River Delta fabricators dominate brushless controller prototyping for global drone assemblers.
Japan
Factory automation and servo motor precision positioning sustain demand for closed-loop feedback integration. METI efficiency regulations and JIS standards constrain component selection in industrial pairings. Nagoya-area industrial electronics clusters source high-frequency switching designs for sustained-load applications.
India
Defense and agricultural drone programs create entry pathways for certified ESC suppliers. PLI scheme incentives and BIS standardization accelerate localization requirements for government tenders. Karnataka and Telangana aerospace clusters trial integrated motor-controller systems for monsoon-resistant spraying operations.
Electronic Speed Controllers Market Competitive Landscape
Top-tier vendors anchor premium certification tiers, while mid-scale fabricators compete on Shenzhen-based cost structures and firmware customization velocity. The vendor base stratifies across three strategic archetypes: integrated propulsion stack specialists, firmware-differentiated premium providers, and commodity brushless controller manufacturers. Capacity expansion and direct procurement channel development represent the dominant competitive moves as traditional distributor relationships erode.
Within the Shenzhen manufacturing tier, Hobbywing Technology Co., Ltd. exemplifies scale-driven cost optimization for consumer-grade applications. Castle Creations occupies a position in firmware-architecture premium positioning for racing and industrial segments. T-MOTOR anchors the integrated motor-controller system archetype that reduces wiring complexity for commercial drone assemblers. These three vendors represent distinct competitive vectors rather than overlapping market positions.
| Leading Market Players |
|---|
| Hobbywing Technology Co., Ltd. |
| Align Corporation Limited |
| Thunder Tiger Corp. |
| Castle Creations |
| Scorpion Power System |
| T-MOTOR |
| Embention S.L. |
| Aikon Electronics |
| Graupner |
| Others |
Pricing and Supply Chain Analysis
Neodymium and dysprosium price indices cascade through brushless ESC manufacturing tiers, compressing margins in Shenzhen-sourced commodity controllers while amplifying pricing power for firmware-differentiated premium suppliers serving FAA-certified commercial fleets.
Pricing Analysis
Margin tightening in consumer-grade tiers reflects rare earth magnet cost volatility and silicon carbide MOSFET supply bottlenecks. Three-tier pricing structure across premium, standard, and economy levels separates EASA-certified redundant architectures from hobby-grade PWM units. Pricing pressure intensifies in brushed controller segments as IEC 60034 efficiency standards threaten obsolescence. Agricultural drone assemblers in Australia and Brazil exhibit highest price sensitivity, while urban air mobility developers in the United States absorb premium positioning for fail-safe embedded formats.
Supply Chain Analysis
Power electronics engineer scarcity in Shenzhen, Nagoya, and Bavaria constrains firmware development velocity for next-generation GaN-SiC designs. Manufacturing gravity centers on China's Pearl River Delta, South Korea's memory foundry corridor, and Germany's industrial automation belt. Controller production draws from neodymium magnet processors in Inner Mongolia, silicon carbide wafer fabricators in North Carolina, and PCB laminate suppliers in Taiwan. Single-source vulnerability concentrates in advanced MOSFET foundry capacity. Distribution runs through direct procurement channels displacing traditional wholesale relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic speed controller manufacturing is consolidating around firmware-architecture capabilities and certification infrastructure, with EASA's Specific Category framework and FAA Remote ID mandates forcing sub-scale competitors toward exit or acquisition.
For Market Incumbents: Deploy captive firmware development teams to defend against GaN-SiC hybrid switching disruption from semiconductor specialists. Deepen backward integration into neodymium magnet supply through offtake agreements with Inner Mongolia processors. Lock in EASA certification pipelines before 2025 noise regulation deadlines harden competitive moats. For New Entrants and Emerging Players: Launch via direct-to-assembler channels targeting India's PLI-subsidized defense and agricultural drone programs. White-space concentrates in BIS-certified embedded controllers for monsoon-resistant spraying operations. Avoid Shenzhen-saturated consumer tiers; instead, pursue firmware-as-a-service subscriptions for commercial fleet operators seeking algorithm update revenue streams. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale firmware houses with EASA pre-certification progress in Germany and Japan. Long-term viability hinges on PID control algorithm IP and thermal management patent portfolios. Watch silicon carbide MOSFET supply normalization as inflection signal for premium controller margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| GaN-SiC Hybrid Switching Integration | Enables 48V-800V platform flexibility for electric vertical take-off and landing aircraft. |
| EASA Specific Category Certification | Establishes redundant architecture compliance for European commercial drone fleet operators. |
| Firmware-as-a-Service Monetization | Converts hardware transactions into recurring algorithm update revenue from fleet managers. |
| Direct Shenzhen Procurement Channels | Bypasses distributor markups for agricultural drone assemblers in Brazil and Australia. |
| Neodymium Magnet Backward Integration | Secures rare earth supply against price volatility in brushless motor-controller pairings. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews of drone fleet operators, ESC firmware engineers, agricultural spraying platform assemblers, and power electronics procurement leads. FAA Part 107 compliance databases, EASA Specific Category certification registries, Shenzhen customs export manifests, and IEC 60034 efficiency test reports supplied quantitative benchmarks. Bottom-up volume aggregation across brushless, brushed, digital, and analog product types triangulated against top-down market sizing from motor drive semiconductor consumption data.
Data-stream reconciliation aligned shipment volumes from Pearl River Delta fabricators with end-use consumption patterns across drone, industrial automation, and consumer electronics verticals. Segmentation modeling spanned product type, control technology, installation format, and end-use application across the projection horizon. CAGRs derived from regression analysis of historical rare earth magnet pricing, silicon carbide MOSFET availability curves, and regulatory mandate implementation schedules. GaN switching adoption trajectories and urban air mobility prototype development pipelines fed scenario-weighted forecast outputs.
The model assumes a particular technology adoption path; alternative pathways for wide-bandgap semiconductor convergence would alter the outlook. Forecasts reflect assumptions regarding EASA certification timeline adherence, Shenzhen manufacturing cost trajectories, and neodymium supply chain stability. Material deviation in FAA Remote ID enforcement intensity, PLI scheme renewal in India, or silicon carbide foundry capacity expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Audio Power Amplifier Market
Electronic Components
USB Wall Charger Market
Electronic Components
Multi-Layer Ceramic Capacitor (MLCC) Market
Electronic Components
Fuel Pump Driver Module Market
Electronic Components
Class D Audio Amplifier Market
Electronic Components
China Crystal Oscillator Market
Electronic Components
Europe PCB Market
Electronic Components
Docking Station Market
Electronic Components
DVB/SAT Remote Controls Market
Electronic Components
Electronic Wipe Market
Electronic Components
Electric Vehicle (EV) Electronic Components Market
Electronic Components
Capacitor Aluminum Polymer Market
Electronic Components
Safety Relay Market
Electronic Components
Capacitor Kits Market
Electronic Components
Digital Electronic Detonator Market
Electronic Components
High Precision Mechanical Machine Components Market