
 Global Industrial Media Converters Market | 2026-2036
Global Industrial Media Converters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Media Converters Market Outlook
Equipment leasing and managed-network-service contracts is rewriting competitive dynamics in industrial connectivity, lowering capital barriers for mid-sized manufacturers. Moxa Inc. leverages its vertically integrated manufacturing in Taiwan to sustain price competitiveness across DIN-rail and rack-mount portfolios. Cisco Systems anchors enterprise-class security features into media converter lines, competing for critical infrastructure accounts. Advantech Co., Ltd. specializes in modular, edge-integrated platforms that occupy the factory-automation channel.
Industrial media converters are hardened network interface devices that translate signal types—typically between copper Ethernet, fiber optic, serial RS-232/485, and wireless protocols—while operating across extended temperature ranges from minus forty to plus seventy-five degrees Celsius and meeting IP30 or higher ingress protection ratings. Their primary purpose is extending network distance, isolating electrical noise, and bridging legacy industrial equipment into modern IP-based control architectures. DIN-rail converters lead unit shipments due to universal compatibility with industrial control panels, while fiber-to-Ethernet technology captures premium margins as power utilities and rail operators demand electromagnetic immunity. Rack-mount converters dominate data-intensive telecommunications central offices where density and hot-swap modularity offset higher installed costs.
IEC 62443 cybersecurity certification, IEEE 802.3 standards for power-over-Ethernet, and CE marking under the EU Machinery Directive collectively shape product development cycles and market access requirements for industrial media converter vendors. NHTSA and FERC guidelines in the United States further constrain device selection in transportation and energy applications, favoring suppliers with documented compliance traceability. Stakeholders must monitor evolving interoperability mandates between IT and OT networks as the decisive factor in procurement specifications.
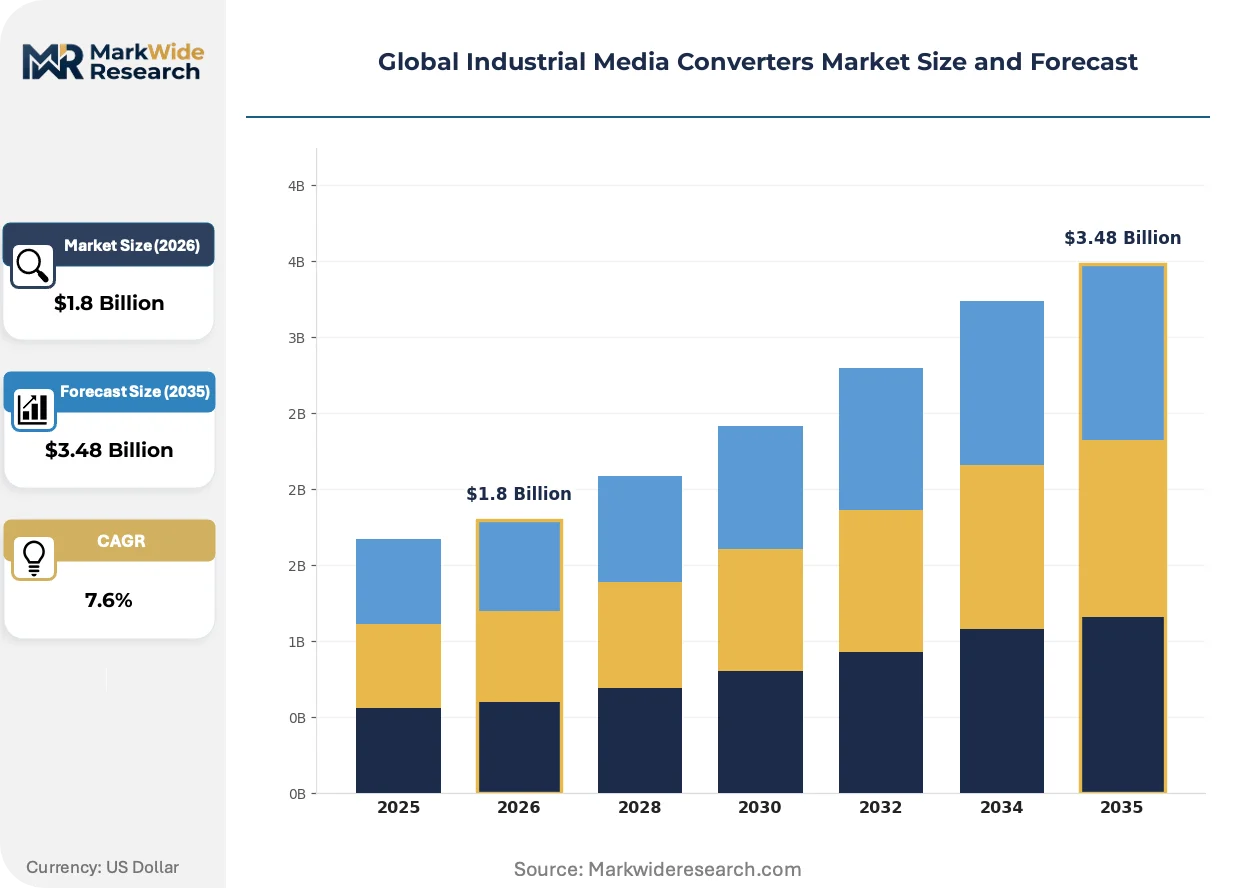
Market Dynamics
The migration from legacy serial protocols to Ethernet-fiber backbones in smart manufacturing facilities is compressing replacement cycles and forcing procurement teams to prioritize cybersecurity-certified units over commodity alternatives.
Growth Catalysts
- IEC 62443 Certification:Power utilities and rail operators now mandate industrial cybersecurity compliance in procurement specifications, filtering out uncertified suppliers from critical infrastructure tenders.
- Automotive Electrification:Battery assembly lines and EV powertrain test facilities require electromagnetic-immune fiber-to-Ethernet conversion to isolate high-voltage noise from control networks.
- IEEE 802.3bt Advancement:Ninety-watt power-over-Ethernet capability eliminates separate power cabling for IP cameras, access points, and edge sensors in plant-floor deployments.
Market Restraints
- Optical Component Concentration:Laser diode and transceiver supply concentrates among Taiwanese and Chinese contract manufacturers, exposing lead times to geopolitical friction and export control volatility.
- Copper Price Volatility:Ethernet port assemblies depend on copper alloy feedstock subject to commodity exchange fluctuations that compress margin predictability for DIN-rail volume producers.
- Legacy Protocol Persistence:RS-485 and Modbus RTU equipment installed across oil and gas upstream facilities creates technical debt that slows full IP migration and extends hybrid infrastructure maintenance costs.
Strategic Opportunities
- India Manufacturing Expansion:PLI scheme incentives for semiconductor and electronics assembly are attracting greenfield fab construction requiring hardened network infrastructure for cleanroom and process control environments.
- Edge-AI Convergence:Media converters integrating TSN time-sensitive networking with onboard inference accelerators enable deterministic data pre-processing for predictive maintenance applications.
- Managed Service Transition:Mid-sized German and Japanese manufacturers are outsourcing network lifecycle management to system integrators, creating recurring revenue attachment for converter-as-a-service models.
Industry Challenges
- IEC 62443 Certification Timeline:Multi-stage security assessment procedures extend product launch windows by twelve to eighteen months, delaying revenue recognition for new platform introductions.
- OT-IT Skill Bridging:Plant engineers proficient in ladder logic and SCADA configuration lack TCP/IP troubleshooting depth, forcing vendors to absorb training costs or risk deployment failures.
- Multi-Protocol Integration Complexity:Hybrid environments mixing Profinet, EtherNet/IP, and OPC UA require protocol-aware converters that increase firmware validation burden and defect surface area.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Media Converters Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Converters, Rack-Mount Converters, DIN-Rail Converters, Modular Converters Technology: Ethernet, Fiber, Serial, Wireless End User: Manufacturing, Energy, Transportation, Telecommunications Installation: On-site, Remote, Integrated, Cloud-Based |
| Companies Covered | Advantech Co., Ltd., Moxa Inc., Antaira Technologies, Allied Telesis, Perle Systems, Cisco Systems, Phoenix Contact, PLANET Technology, Belden Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Media Converters Market Strategic Shifts
Convergence between operational technology reliability requirements and information technology security architectures is redefining product roadmaps and procurement evaluation criteria across industrial connectivity.
Single-pair Ethernet SPE physical layer technology operating at 10 Mbps over 1000 meters on single twisted-pair cable is digitizing sensor-to-controller connectivity in process industries. Chemical and pharmaceutical manufacturers are piloting SPE media converters to replace analog 4-20mA loops in hazardous-area instrumentation. This compression of wiring infrastructure is eliminating marshalling cabinets and reducing installation labor by two-thirds in greenfield projects.
EU Cyber Resilience Act mandatory security-by-design requirements will impose conformity assessment obligations on network infrastructure suppliers serving European manufacturing. The regulation's vulnerability disclosure and update support mandates are forcing firmware architecture redesigns toward over-the-air patch capability. Machine builders in Germany and Italy are already screening suppliers for documented software bill of materials practices ahead of enforcement deadlines.
Buying committees at North American automotive tier-one suppliers have consolidated vendor qualification lists from twelve to four approved media converter sources, prioritizing documented mean-time-between-failure data and domestic technical support presence. This concentration is displacing price-driven spot purchasing with multi-year framework agreements bundling hardware, sparing, and on-site engineering support. Similar patterns are visible among Japanese semiconductor equipment OEMs qualifying suppliers for twenty-year service life commitments.
Global Industrial Media Converters Market Segmentation
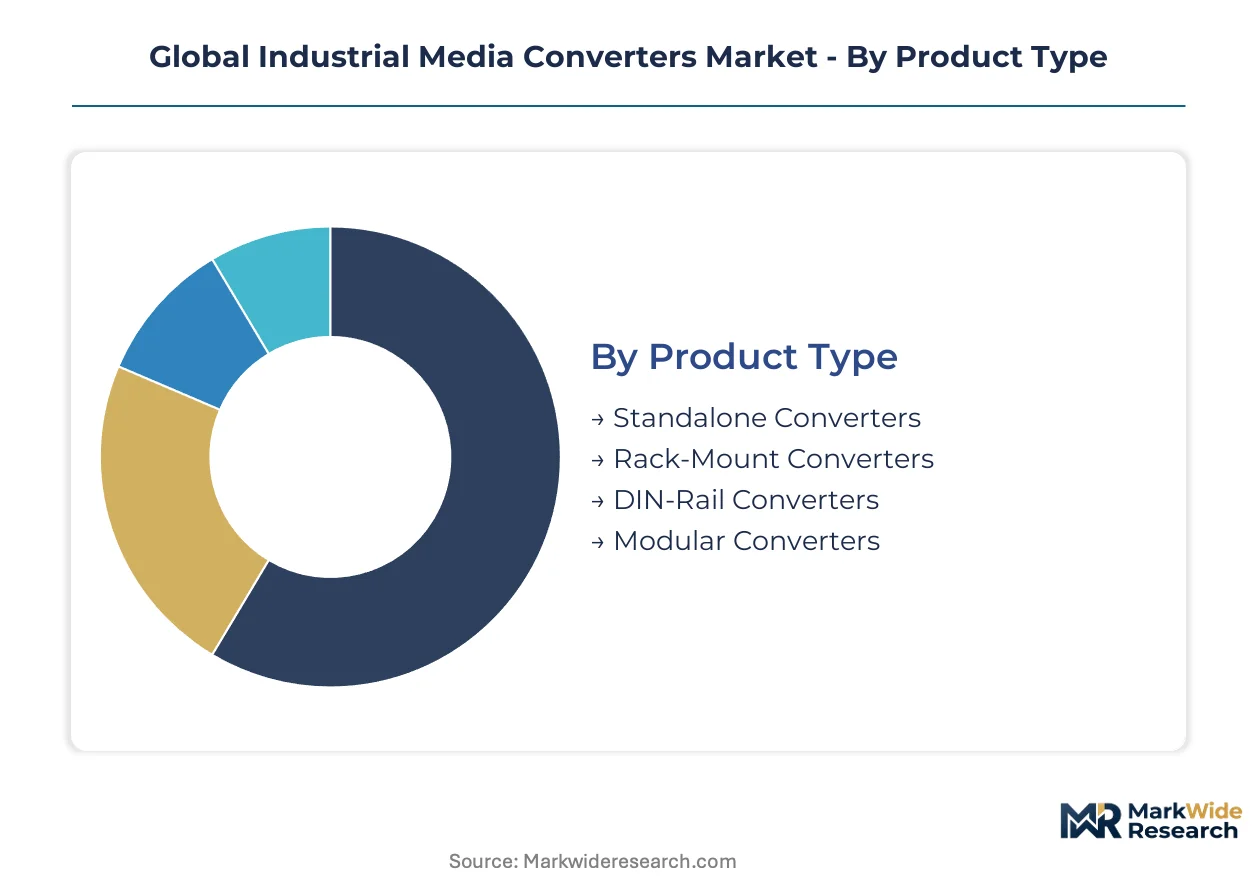
Industrial media converter procurement varies sharply by deployment environment, from harsh factory floors requiring DIN-rail mounting to data centers demanding hot-swap rack density. Segmentation reveals how form factor, protocol translation needs, and cybersecurity certification requirements shape vendor selection across automotive assembly, utility substations, and rail signaling networks.
Product Type:
Mature industrial form factors coexist with emerging modular architectures as plant operators balance legacy compatibility against edge-computing flexibility.
- DIN-Rail Converters:Compact units clip onto standard 35mm rails inside electrical enclosures, operating across minus forty to plus seventy-five degrees Celsius with IP30 ingress protection. Automotive battery plants in Germany and power utility substations in Texas specify these for vibration-resistant signal translation in space-constrained motor control centers.
- Rack-Mount Converters:Nineteen-inch chassis accommodate high-density fiber-to-Ethernet aggregation with redundant power supplies and hot-swappable blades. Telecommunications central offices in Japan and data halls operated by cloud providers in Virginia prioritize these for centralized network management and rapid field replacement.
- Standalone Converters:Desktop or wall-mounted units serve point-to-point links in small machine shops and building automation retrofits where DIN-rail infrastructure is absent.
- Modular Converters:Swappable interface cards allow field reconfiguration between copper, fiber, and serial protocols without hardware replacement.
DIN-Rail Converters retain volume leadership; Modular Converters hold the steepest expansion curve.
Technology:
Cost tier separation between commodity copper Ethernet and premium fiber optics reflects electromagnetic immunity requirements in high-voltage industrial environments.
- Fiber:Single-mode and multimode optical transceivers eliminate ground loops and lightning susceptibility across kilometer-scale distances. High-voltage EV test cells in South Korea and offshore oil platforms in the Gulf of Mexico mandate fiber-to-Ethernet conversion to isolate control networks from electromagnetic interference.
- Ethernet:Copper RJ45 ports dominate short-reach plant-floor connectivity where cost sensitivity outweighs noise immunity concerns.
- Serial:RS-232, RS-485, and Modbus protocol translation bridges decades-old SCADA equipment into modern IP architectures.
- Wireless:IEEE 802.11 industrial Wi-Fi and proprietary radio links serve mobile equipment and temporary construction sites where cabling is impractical.
Fiber commands premium pricing in critical infrastructure; Wireless is gaining share fastest among brownfield logistics facilities.
End User:
Application intensity separates process industries with twenty-year asset horizons from discrete manufacturing with compressed technology refresh cycles.
- Energy:Power generation, transmission, and distribution operators require IEC 62443-certified devices with documented mean-time-between-failure data spanning decades. FERC-mandated reliability standards in the United States and similar national regulations in China drive procurement toward hardened, security-validated converters for substation automation.
- Manufacturing:Smart factory deployments mix legacy fieldbus with TSN-enabled Ethernet, demanding protocol-aware gateways for predictive maintenance integration.
- Transportation:Rail signaling and intelligent traffic systems prioritize electromagnetic immunity and extended temperature operation.
- Telecommunications:Carrier-grade reliability and SNMP manageability dominate central office and cell tower backhaul specifications.
Energy retains the longest replacement cycles; Manufacturing shows the steepest expansion curve.
Installation:
Customer type stratification separates asset owners with in-house engineering capability from operators outsourcing network lifecycle management.
- On-site:Physical hardware deployment by plant maintenance teams remains dominant in regulated industries requiring air-gapped security and documented chain of custody.
- Remote:Zero-touch provisioning over cellular or satellite backhaul serves distributed pipelines, mining operations, and renewable generation sites with limited technical staff.
- Integrated:Pre-configured converter modules embedded within OEM equipment reduce field commissioning time for machine builders.
- Cloud-Based:Virtualized protocol translation and centralized policy management appeal to mid-sized manufacturers adopting managed network services.
On-site installation retains volume leadership; Cloud-Based deployment holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PLI scheme incentives in India and FERC reliability mandates in the United States are redirecting procurement toward certified, security-validated industrial media converters. National industrial policies across Germany, China, and Japan are accelerating Ethernet-fiber backbone modernization in automotive and utility automation.
United States
Power utility substation automation and EV battery plant construction drive procurement volumes. FERC-mandated reliability standards filter device selection toward IEC 62443-certified units with documented mean-time-between-failure data. Texas and California concentrate new installations across grid modernization and automotive electrification projects.
Germany
Automotive tier-one suppliers and semiconductor equipment OEMs demand twenty-year service life commitments from converter vendors. EU Cyber Resilience Act security-by-design requirements are forcing firmware architecture redesigns ahead of enforcement deadlines. Bavaria and Baden-Württemberg industrial clusters lead qualification list consolidation from twelve to four approved suppliers.
China
Smart manufacturing facility construction and dual carbon goals accelerate legacy serial network replacement. MIIT industrial internet standards shape domestic procurement specifications for hardened network infrastructure. Yangtze River Delta and Pearl River Delta manufacturing hubs concentrate bulk installations across automotive and electronics assembly.
Japan
Rail signaling modernization and semiconductor fab construction require electromagnetic-immune fiber-to-Ethernet conversion. METI industrial cybersecurity guidelines influence vendor qualification for critical infrastructure accounts. Kanto and Kansai metropolitan areas anchor demand from telecommunications central offices and intelligent traffic systems.
India
Greenfield semiconductor fab construction under PLI scheme incentives requires hardened network infrastructure for cleanroom environments. CEA grid reliability regulations extend to substation automation device selection. Gujarat and Karnataka emerging electronics manufacturing clusters drive first-wave installations.
Global Industrial Media Converters Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement channels. DIN-rail volume producers face margin pressure from copper price volatility while fiber-to-Ethernet specialists capture premium pricing in critical infrastructure. Three archetypes dominate: vertically integrated hardware manufacturers, enterprise-class security integrators, and modular edge-computing platforms. Consolidation through strategic partnerships and portfolio diversification into managed service offerings are reshaping competitive positioning.
Among Taiwan-based hardware manufacturers, Moxa Inc. exemplifies vertically integrated production control. Enterprise security integration is anchored by Cisco Systems. Modular platform specialization is represented by Advantech Co., Ltd. These three occupy distinct competitive vectors rather than direct substitution relationships.
| Leading Market Players |
|---|
| Advantech Co., Ltd. |
| Moxa Inc. |
| Antaira Technologies |
| Allied Telesis |
| Perle Systems |
| Cisco Systems |
| Phoenix Contact |
| PLANET Technology |
| Belden Inc. |
| Others |
Value Chain & Pricing Dynamics
Taiwanese optical component clusters in Hsinchu and Taichung anchor transceiver manufacturing capacity, concentrating supply-side leverage among contract manufacturers who dictate payment terms to downstream media converter assemblers. This geographic concentration cascades into pricing power asymmetries where fiber-to-Ethernet specialists capture premium margins while DIN-rail volume producers absorb copper feedstock volatility.
Pricing Analysis
Certification level creates the primary spread between IEC 62443-validated units and uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects cybersecurity grade, mean-time-between-failure documentation, and domestic technical support availability. Cost compression in economy-grade DIN-rail segments is intensifying because copper alloy feedstock fluctuates on commodity exchanges. Automotive tier-one suppliers show least price sensitivity, prioritizing documented reliability over unit cost.
Supply Chain Analysis
Extended payment terms from Taiwanese and Chinese contract manufacturers now stretch to ninety days, squeezing working capital for mid-sized converter vendors. Laser diodes and optical transceivers draw from Taiwan, China, and South Korea; copper alloy feedstock sources from Chile and Indonesia. Single-source vulnerability in specialized single-mode transceivers exposes lead times to export control friction. Distribution runs through industrial automation distributors, system integrators, and direct OEM supply contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The narrow pipeline of engineers proficient in both OT ladder logic and IT network security creates a binding constraint on deployment velocity, amplifying returns for vendors who internalize training and certification support.
For Market Incumbents: Insulate fiber-to-Ethernet premium positions by deepening backward integration into optical transceiver supply and accelerating IEC 62443-4-2 certification timelines ahead of EU Cyber Resilience Act enforcement. Threat substitution from modular edge-computing platforms with onboard inference accelerators demands preemptive TSN capability integration. For New Entrants and Emerging Players: India's greenfield semiconductor fab construction under PLI scheme incentives offers the most penetrable geographic entry point, with cleanroom network infrastructure specifications still fluid and vendor qualification lists unconsolidated. Target managed service provider channels rather than direct plant sales to bypass incumbent distributor lock-in. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because converter-as-a-service models are displacing transactional hardware procurement among mid-sized German and Japanese manufacturers. Acquisition target archetype: modular platform specialists with TSN firmware stacks and documented software bill of materials practices. Signal to watch: FERC or CEA regulatory expansions mandating cybersecurity certification for substation automation.| Strategic Initiative | Industry Significance |
|---|---|
| IEC 62443-4-2 Certification Acceleration | EU Cyber Resilience Act enforcement will filter uncertified suppliers from European tenders. |
| Backward Integration into Optical Transceivers | Taiwanese contract manufacturer concentration exposes margin predictability to geopolitical friction. |
| TSN-Enabled Firmware Development | Time-sensitive networking convergence with edge-AI enables predictive maintenance data pre-processing. |
| Managed Service Platform Launch | German and Japanese mid-sized manufacturers are outsourcing network lifecycle management to integrators. |
| India Market Channel Establishment | PLI scheme fab construction creates first-mover advantage in cleanroom infrastructure specification. |
Study Parameters
A standing panel of plant engineers, OEM procurement managers, system integration specialists, and aftermarket service directors provided ongoing calibration against operating reality. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, customs trade data, IEC certification registries, and FERC reliability documentation. Bottom-up unit shipment estimates by form factor and technology triangulated against top-down infrastructure investment flows from national industrial policies.
Scenario-bracketing around copper price volatility bands and IEC 62443 certification adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include form factor, protocol translation technology, end-use industry intensity, installation type, and regional regulatory cluster. CAGRs derived from installed base replacement cycles, greenfield automation project pipelines, and cybersecurity mandate phase-in schedules. Specific inputs included MIIT industrial internet standards deployment timelines and NHTSA transportation infrastructure specifications.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by optical component specialists or sudden export control expansions would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Robotic Flat Cable Market
Electronic Components
Europe PCB Market
Electronic Components
Film Capacitor Market
Electronic Components
Trackpad Market
Electronic Components
Global Capacitor Market
Electronic Components
Display Port Adapters Market
Electronic Components
Braking Resistors Market
Electronic Components
AC Adapter Market
Electronic Components
Flex-Rigid PCB Market
Electronic Components
Camera Battery Charger Market
Electronic Components
Class D Audio Amplifier Market
Electronic Components
Electronic Wipe Market
Electronic Components
PTC Resettable Device Market
Electronic Components
Microspeaker Market
Electronic Components
Cordless Phone Battery Market
Electronic Components
Electromechanical Relay Market