
 Wearable Display Device Materials Market | 2026-2036
Wearable Display Device Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Display Device Materials Market Outlook
A wide capital-intensity gap between microLED foundries and plastic substrate converters is reorganizing competitive tiers in wearable display materials. Samsung Electronics leverages in-house semiconductor fabrication to control gallium nitride epitaxy for AR waveguides. Porotech anchors its position through proprietary porous nitride architectures that sustain higher brightness per watt than conventional quantum-dot films.
Wearable display device materials encompass engineered substrates, encapsulation films, and optical coatings formulated for bend tolerance, moisture barrier performance, and pixel-density scalability beyond 3000 ppi. These materials enable see-through near-eye projection in headsets and low-power always-on surfaces in wrist-worn health monitors. OLED stack materials currently dominate value capture due to mature vapor-deposition supply chains, while MicroLED transfer films represent the fastest-expanding margin pool as pick-and-place yield rates improve. Plastic substrate grades are displacing glass in fitness bands where gram-weight reduction determines OEM selection criteria.
The EPA governs perfluorinated substance discharge from fluoropolymer barrier-film plants in the United States, forcing reformulation of multi-layer encapsulants. REACH restricts organometallic precursor use in EU-based MOCVD operations, extending qualification timelines for European MicroLED material entrants. Stakeholders must monitor how RoHS exemptions for cadmium-based quantum dots expire across multiple Asian manufacturing jurisdictions, as this will redirect phosphor procurement toward indium phosphide alternatives or narrow-band perovskite systems.
Market Dynamics
MicroLED transfer yield improvements are compressing the cost gap against mature OLED stacks, forcing material suppliers to recalibrate qualification timelines and foundry partnerships around pixel-density thresholds exceeding 3000 ppi.
Growth Catalysts
- REACH chemical disclosure mandates:European regulators accelerate substitution of legacy encapsulant chemistries, opening qualification windows for fluoropolymer alternatives with superior moisture barrier performance.
- AR headset optical waveguides:Consumer electronics OEMs scale gallium nitride epitaxy capacity for near-eye projection systems, pulling demand for engineered substrate architectures.
- South Korean cluster concentration:Domestic supply chain integration around Seoul-Incheon corridor reduces logistics friction for OLED stack precursor procurement.
Market Restraints
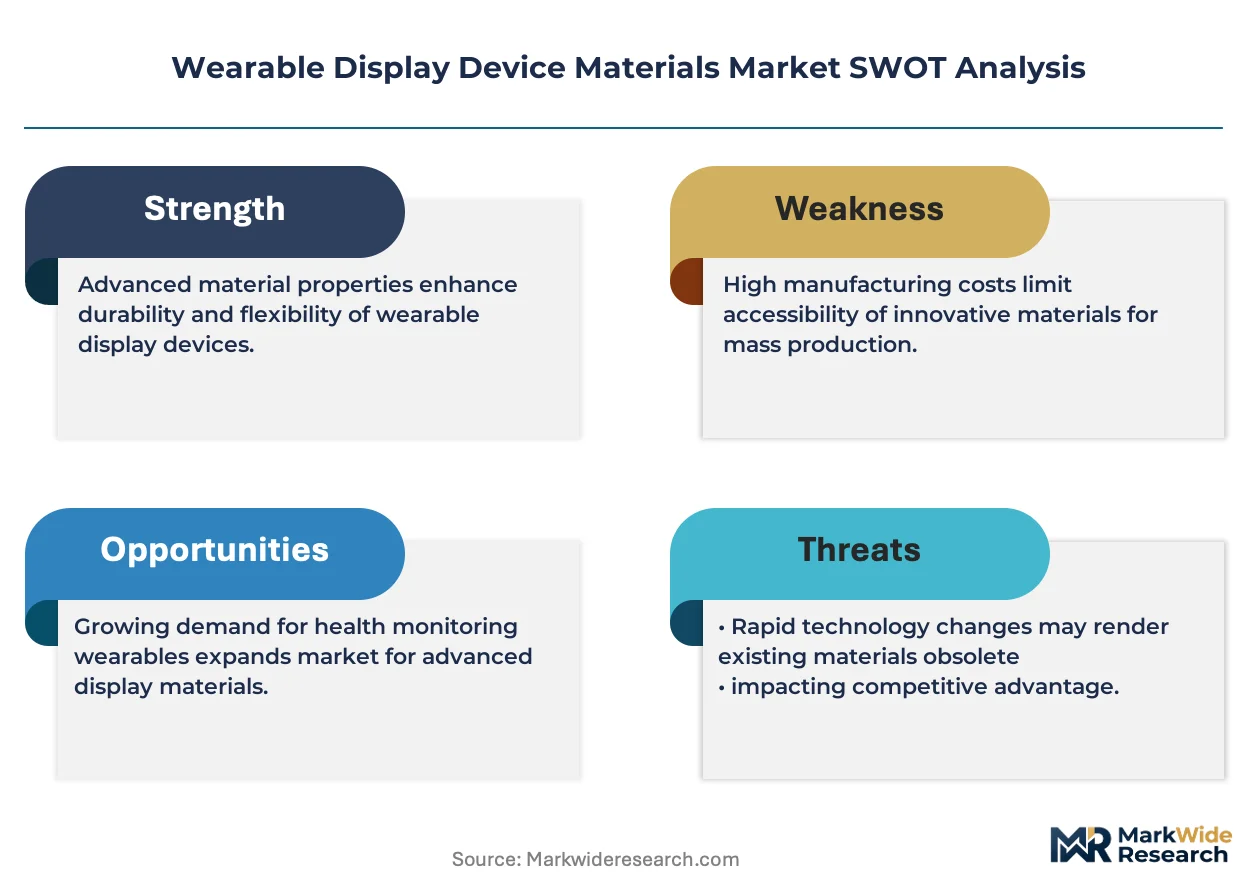
- Gallium spot price volatility:MicroLED epitaxy operations face input cost swings from semiconductor-grade metal markets, compressing margin buffers for tier-two foundries.
- Single-source MOCVD equipment:Veeco and AIXTRON anchor global reactor supply, creating concentration risk for European material entrants seeking independent qualification paths.
- Indium phosphide quantum dot yield:Cadmium-free phosphor alternatives suffer spectral purity gaps against narrow-band perovskite systems, limiting color gamut in premium AR displays.
Strategic Opportunities
- RoHS exemption expiration timelines:Asian manufacturing jurisdictions phase out cadmium quantum dot allowances, redirecting phosphor procurement toward indium phosphide or perovskite supply chains.
- Fitness band plastic substrates:Gram-weight reduction mandates from wrist-worn health monitor OEMs displace glass in sub-50-gram device categories.
- Dual carbon goals in China:MIIT efficiency standards for display fabs create pull for low-temperature processing materials that reduce vapor-deposition energy intensity.
Industry Challenges
- Pick-and-place technician scarcity:MicroLED mass transfer operations require specialized cleanroom skills that outpace vocational training pipeline output in key manufacturing hubs.
- Multi-jurisdiction certification lag:EPA discharge permits for fluoropolymer barrier-film plants run parallel to REACH precursor registrations, extending time-to-revenue for new encapsulant formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Display Device Materials Market |
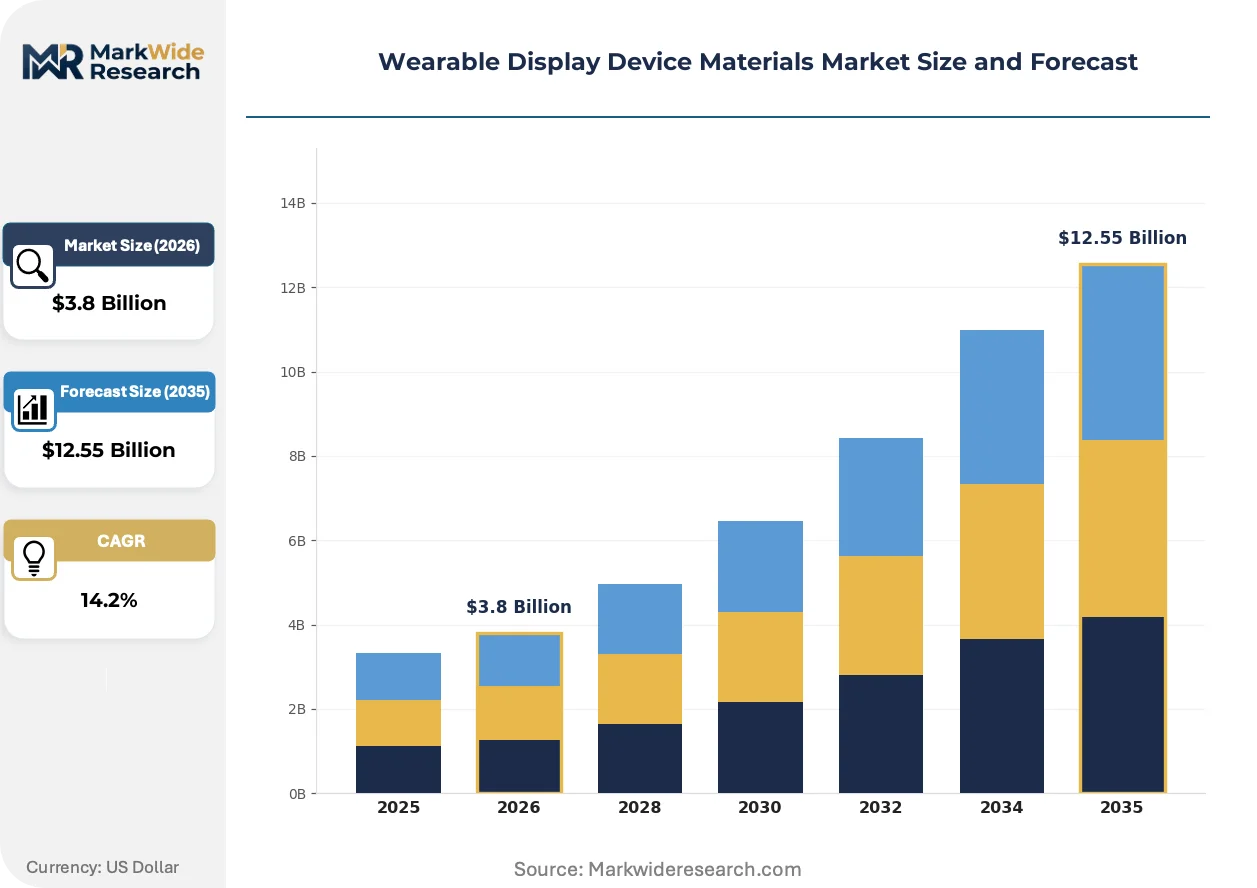
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Glass, Plastic, Metal, Crystal End User: Consumers, Healthcare, Education, Industrial Technology: OLED, LCD, E Ink, MicroLED Application: Fitness Tracking, Health Monitoring, Gaming, Augmented Reality |
| Companies Covered | Dispelix, Porotech, Samsung Electronics, KOPIN Corporation, Jade Bird Display, LG Display, MicroLED Devices, PlayNitride, BOE Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Display Device Materials Market Strategic Shifts
Material architectures for wearable displays are bifurcating between performance-maximizing microLED stacks and cost-optimized OLED derivatives, with regulatory chemistry constraints acting as the decisive selection filter across both paths.
Porous nitride architectures are miniaturizing active layer thicknesses while sustaining brightness-per-watt ratios critical for battery-constrained AR headsets. Military and enterprise training system integrators adopt these substrates fastest, compressing traditional qualification cycles from 18 months to under 9 months. The technology is miniaturizing optical engine volumes by 40 percent compared to conventional quantum-dot film stacks, enabling rimless eyewear form factors previously unattainable.
EPA perfluorinated substance discharge rules are forcing reformulation of multi-layer encapsulants used in fitness band displays. Barrier-film plants in the United States must retrofit wastewater treatment systems or relocate production to jurisdictions with less stringent fluoropolymer effluent standards. Consumer-grade wearable OEMs respond by qualifying alternative parylene-CVD hybrid coatings that trade marginal barrier performance for regulatory compliance certainty.
Specification sheets now prioritize gram-weight and bend-radius metrics over luminance benchmarks in fitness band procurement decisions. Direct substrate converters bypass traditional optical film distributors, selling calibrated plastic grades straight to Shenzhen and Dongguan assembly houses. This channel compression is most visible in China, where domestic substrate specialists capture volume previously held by Japanese and Korean intermediaries.
Wearable Display Device Materials Market Segmentation
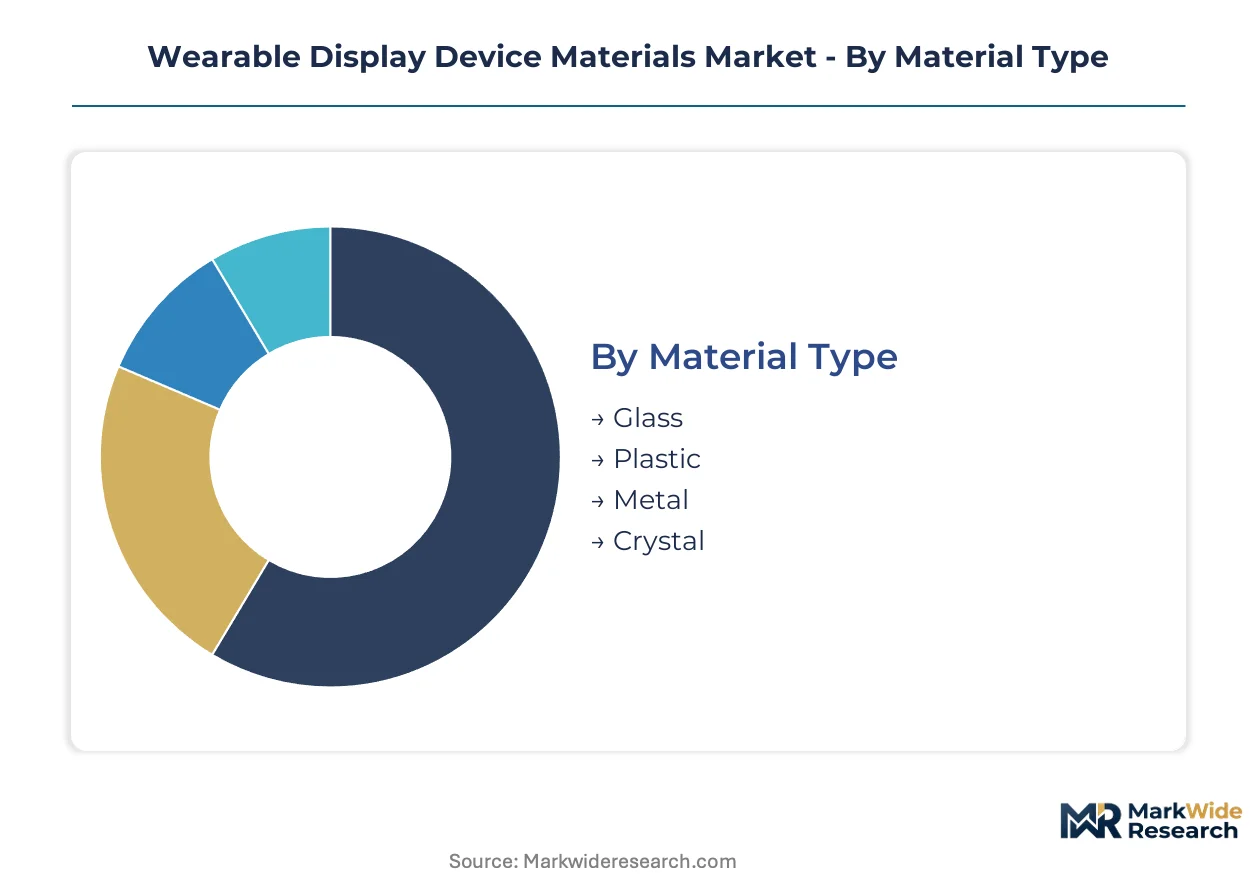
Material selection in wearable displays hinges on trade-offs between optical performance, mechanical durability, and regulatory compliance across divergent end-use environments. Segmentation reveals how substitution pressures from MicroLED architectures and plastic substrate adoption are fragmenting traditional supply hierarchies.
Material Type:
Substitution pressure runs strongest against glass substrates as gram-weight reduction mandates from wrist-worn OEMs accelerate plastic qualification timelines.
- Plastic:Polycarbonate and polyimide grades formulated for sub-50-gram fitness bands displace glass through direct sales to Shenzhen assembly houses. South Korean substrate converters anchor supply for OLED stacks requiring bend radii below 3mm.
- Glass:Borosilicate and chemically strengthened variants retain dominance in premium AR headsets where surface hardness exceeds 9H. Corning and AGC control thinning capacity for sub-0.3mm substrates used in near-eye waveguides.
- Metal:Aluminum and magnesium alloys form thermal spreaders in high-brightness MicroLED engines where passive cooling constraints dictate material selection.
- Crystal:Sapphire and lithium niobate substrates serve niche military AR applications requiring scratch resistance beyond aluminosilicate limits.
Plastic anchors the volume base while glass retains premium positioning; crystal gains share at the steepest rate in defense procurement channels.
End User:
Customer-type segmentation exposes divergent procurement rhythms between consumer electronics OEMs and regulated medical device manufacturers.
- Consumers:Fitness band and smartwatch OEMs prioritize gram-weight and bend-radius metrics over luminance, sourcing plastic substrates through compressed distributor channels. Shenzhen and Dongguan assembly houses now purchase calibrated grades directly from substrate converters.
- Healthcare:FDA and EMA device pathways impose biocompatibility testing on encapsulant chemistries, extending qualification cycles for continuous glucose monitor displays. Parylene-CVD hybrid coatings displace fluoropolymer barriers where perfluorinated discharge rules tighten.
- Education:Enterprise training system integrators compress traditional 18-month qualification cycles to under 9 months for porous nitride architectures in AR headsets.
- Industrial:Ruggedized wearable displays for field service applications specify metal-reinforced housings and glass substrates with impact resistance above 1.5-meter drop thresholds.
Consumer procurement anchors volume concentration while healthcare represents the most tightly regulated qualification pathway.
Technology:
Maturity gradients across display technologies determine where material suppliers can extract margin versus facing commoditization pressure.
- MicroLED:Porous nitride architectures and gallium nitride epitaxy substrates enable 3000+ ppi densities critical for rimless AR eyewear. Mass transfer yield improvements compress cost gaps against OLED, pulling demand for specialized transfer films and pick-and-place compatible substrates.
- OLED:Mature vapor-deposition supply chains dominate current value capture, with South Korean foundries anchoring global precursor procurement through Seoul-Incheon corridor integration.
- LCD:Backlight unit materials face displacement in wrist-worn applications where power efficiency and thickness constraints favor emissive alternatives.
- E Ink:Bistable display materials serve extended battery-life applications in retail and logistics wearables where refresh rate requirements remain minimal.
OLED retains the broadest installed base while MicroLED climbs the fastest in premium AR procurement specifications.
Application:
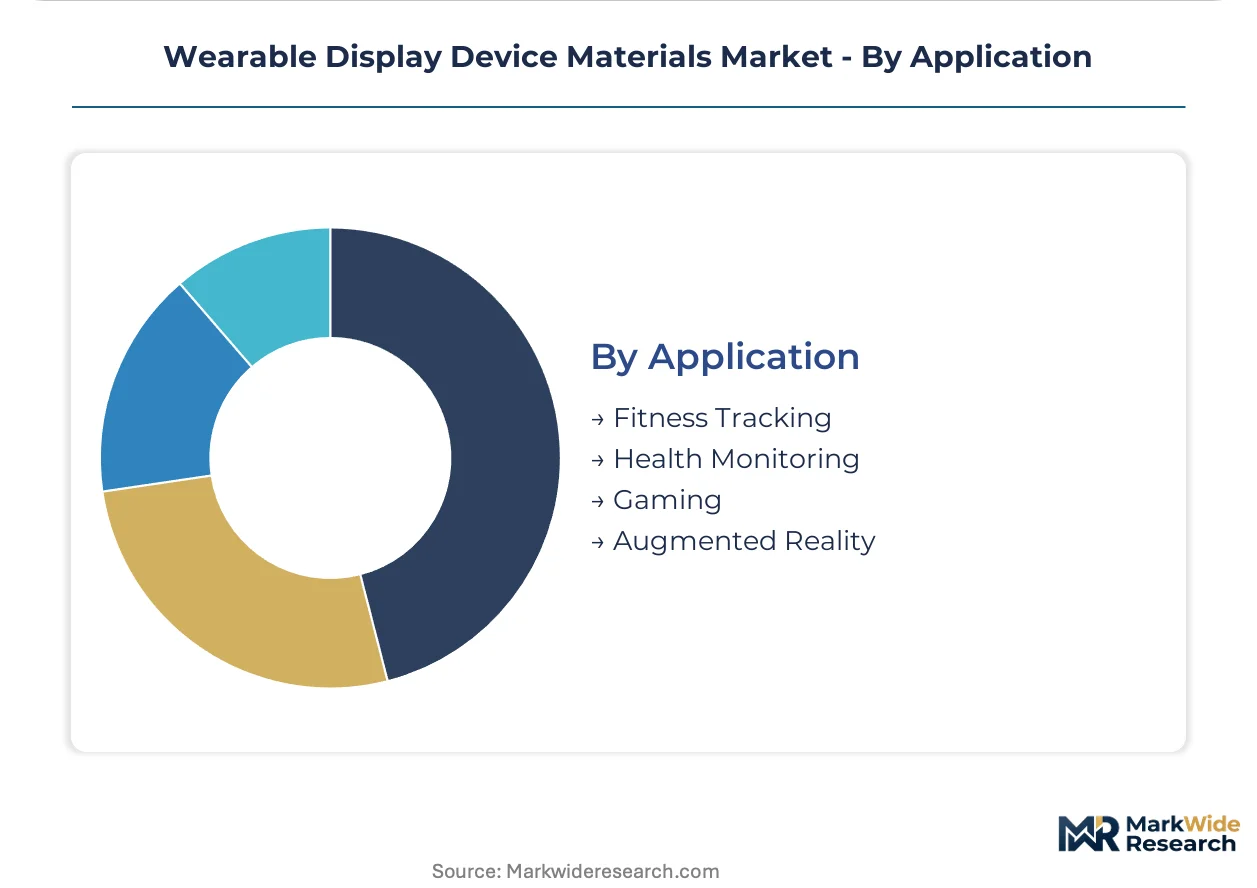
Application segmentation tracks how display performance requirements scale from ambient-readable health monitors to sunlight-visible augmented reality.
- Augmented Reality:Near-eye waveguides demand gallium nitride epitaxy and engineered substrates with optical transparency above 90% at 450-650nm wavelengths. Military and enterprise training integrators drive fastest adoption of porous nitride architectures.
- Health Monitoring:Continuous glucose monitors and cardiac wearables specify low-temperature processing materials that reduce vapor-deposition energy intensity under MIIT efficiency standards.
- Fitness Tracking:Sub-50-gram device categories mandate plastic substrate displacement of glass, with procurement decisions driven by gram-weight benchmarks over luminance specifications.
- Gaming:High-refresh-rate VR headsets prioritize OLED and MicroLED stacks with response times below 1ms, pulling demand for thermal management materials in tethered and standalone form factors.
Fitness tracking anchors unit volume while augmented reality commands the steepest material specification escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in wrist-worn fitness applications exhibit extreme gram-weight price sensitivity, while AR headset procurement tolerates 3-5x material cost premiums for optical performance. South Korea and China concentrate volume-scale production, whereas Germany and the United States anchor qualification-intensive premium supply.
South Korea
Seoul-Incheon corridor integration pulls OLED stack precursor procurement into domestic supply chains. Samsung Electronics and LG Display anchor captive demand for vapor-deposition materials. MFDS biocompatibility pathways extend timelines for healthcare wearable encapsulants.
China
MIIT dual carbon standards redirect display fab energy intensity toward low-temperature processing materials. Shenzhen and Dongguan assembly houses source plastic substrates directly from domestic converters. NMPA device registrations impose extended pathways for continuous glucose monitor displays.
United States
EPA perfluorinated discharge rules force reformulation of multi-layer encapsulants for fitness bands. Military and enterprise AR integrators compress porous nitride qualification cycles to under nine months. Greater Boston and Pacific Northwest clusters concentrate waveguide substrate development.
Germany
ECHA REACH restrictions on organometallic precursors extend MOCVD qualification timelines for MicroLED material entrants. Bavaria and Baden-Württemberg host precision optics fabricators supplying AR near-eye projection systems. KBA-adjacent industrial standards influence automotive wearable display specifications.
Japan
METI efficiency standards accelerate adoption of low-power emissive materials in wrist-worn health monitors. Kanto and Kansai corridors concentrate thinning capacity for sub-0.3mm glass substrates. PMDA device pathways impose biocompatibility testing on encapsulant chemistries for clinical wearables.
Wearable Display Device Materials Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with semiconductor-grade substrate control separating the two. Samsung Electronics exemplifies the integrated archetype through in-house gallium nitride epitaxy, while Porotech occupies a specialist position through proprietary porous nitride architectures. Competitive moves concentrate on backward integration into precursor supply and geographic co-location with Seoul-Incheon and Shenzhen-Dongguan assembly corridors.
Within the integrated tier, Samsung Electronics and LG Display represent scale-driven anchors with captive demand structures. Porotech exemplifies the technology-specialist archetype, occupying a position defined by brightness-per-watt differentiation rather than volume scale. Dispelix sits within the optical component specialist tier, its positioning tied to waveguide substrate qualification for near-eye projection systems.
| Leading Market Players |
|---|
| Dispelix |
| Porotech |
| Samsung Electronics |
| KOPIN Corporation |
| Jade Bird Display |
| LG Display |
| MicroLED Devices |
| PlayNitride |
| BOE Technology |
| Others |
Value Chain & Pricing Dynamics
Plastic substrate displacement of glass in sub-50-gram fitness bands simultaneously redraws procurement geography toward Shenzhen-Dongguan assembly corridors and compresses margin structures for legacy optical film intermediaries. This substitution dynamic pulls volume away from Japanese and Korean distributors while rewarding direct substrate converters with pricing power rooted in gram-weight compliance rather than luminance performance.
Pricing Analysis
After-sales encapsulant reformulation services now drive lifetime value as EPA perfluorinated discharge rules force ongoing barrier-film plant retrofits. Pricing stratifies across premium AR waveguide substrates, standard OLED stack materials, and economy plastic grades for fitness bands, with differentiation resting on MIIT efficiency certification and REACH precursor registration status. Cost compression in economy tiers intensifies as Chinese domestic converters bypass traditional distribution layers. Healthcare OEMs exhibit lowest price sensitivity due to FDA and EMA biocompatibility pathway requirements, while consumer fitness band manufacturers demand sub-dollar substrate solutions.
Supply Chain Analysis
Inbound logistics costs from Busan and Shanghai ports to Shenzhen assembly houses fluctuate with container availability across the East Asian trade lane, compressing just-in-time substrate delivery windows. Supply concentrates in South Korea for OLED precursors, China for plastic substrate conversion, and Japan for sub-0.3mm glass thinning capacity. Raw material dependencies include semiconductor-grade gallium for MicroLED epitaxy, organometallic precursors for MOCVD operations, and fluoropolymer resins for barrier films. Single-source vulnerability runs through Veeco and AIXTRON reactor supply for European material entrants. Distribution runs through direct substrate converter relationships with Dongguan assembly houses, displacing traditional optical film distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized cleanroom technician scarcity for MicroLED mass transfer operations now constrains foundry expansion plans more than capital availability, creating durable advantage for incumbents with established vocational training pipelines.
For Market Incumbents: Fortify captive precursor supply through backward integration into gallium nitride epitaxy or porous nitride architecture licensing, defending against Porotech's brightness-per-watt differentiation and emerging Chinese substrate converters. Prioritize Seoul-Incheon corridor capacity expansion to maintain logistics friction advantages over European entrants facing REACH-extended qualification timelines. Deepen relationships with Shenzhen assembly houses through direct sales channel control. For New Entrants and Emerging Players: Lead with parylene-CVD hybrid coating formulations for healthcare wearable encapsulants, where FDA and EMA biocompatibility pathways create defensible qualification moats against fluoropolymer incumbents. Target German precision optics fabricators in Bavaria and Baden-Württemberg as the most penetrable geography for AR waveguide substrate partnerships. Establish go-to-market presence through KBA-adjacent automotive wearable specifications. For Investors and Strategic Acquirers: Capital is best deployed toward technology-specialist archetypes with proprietary material architectures rather than volume-scale commodity substrate converters, as MicroLED transfer yield improvements concentrate value capture in specialized transfer films and pick-and-place compatible substrates. Monitor RoHS exemption expiration timelines across Asian manufacturing jurisdictions as the critical inflection signal for cadmium-free phosphor supply chain redirection toward indium phosphide or perovskite alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Samsung Electronics controls gallium nitride epitaxy for AR waveguide captive demand. |
| Direct Channel Expansion | Substrate converters bypass Japanese intermediaries to capture Shenzhen assembly house volume. |
| Regulatory Compliance Repositioning | Parylene-CVD hybrid coatings displace fluoropolymers under EPA perfluorinated discharge rules. |
| Specialized Workforce Development | MicroLED mass transfer operations require cleanroom skills outpacing vocational training output. |
| Geographic Co-location Investment | Seoul-Incheon corridor integration reduces logistics friction for OLED stack precursor procurement. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with display material procurement leads, MOCVD operations managers, and AR headset optical engineers; and secondary validation through customs trade data, SEC semiconductor equipment filings, and ECHA REACH registration databases. Bottom-up triangulation across substrate converter shipment records and top-down reconciliation against foundry capacity announcements anchored volume estimates.
Across the analysis window, the analytical framework modeled segmentation dimensions including material type substitution trajectories, technology maturity gradients, and end-user regulatory pathway intensity. CAGRs were derived from installation base expansion rates and replacement cycle dynamics in wrist-worn and near-eye display categories. Forecast inputs incorporated MIIT dual carbon efficiency standards and RoHS exemption phase-out schedules.
Forecasts assume regulatory continuity in EPA discharge permitting, REACH precursor registration, and RoHS cadmium quantum dot exemptions; material policy shifts would require re-modeling of encapsulant reformulation timelines and phosphor procurement redirection. Practitioners should keep alternative scenarios live as gallium spot price volatility and single-source MOCVD equipment concentration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Speaker Cone Material Market
Electronic Components
Audio Capacitor Market
Electronic Components
SAW Filters Market
Electronic Components
Trackpad Market
Electronic Components
Global Capacitor Market
Electronic Components
Capacitor Kits Market
Electronic Components
Efuse Market
Electronic Components
Industrial Relays Market
Electronic Components
United States MLCC Market
Electronic Components
Global Microfluidic Components Market
Electronic Components
Gas Discharge Tube Market
Electronic Components
Metal Composite Power Inductor Market
Electronic Components
Special Function Data Convertors Market
Electronic Components
High-Voltage Capacitor Market
Electronic Components
Silicon Capacitors Market
Electronic Components
Global Multilayer Varistors Market