
 Cordless Phone Battery Market | 2026-2036
Cordless Phone Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Cordless Phone Battery Market Analysis
Lithium-ion chemistry is repositioning cordless phone battery economics as manufacturers phase out heavier nickel-cadmium formulations. Panasonic Corporation leverages its vertical integration in cell production to sustain cost advantages across Asian supply chains. Samsung SDI Co. Ltd. anchors its position through R&D intensity in energy-dense cylindrical formats. Energizer Holdings Inc. competes on brand strength and retail channel control in North American replacement markets.
Cordless phone batteries are rechargeable electrochemical cells, typically cylindrical or prismatic packs rated between 2.4V and 3.6V, designed to deliver sustained milliamp-hour discharge cycles for DECT and analog handset operation. NiMH variants dominate current replacement volumes due to compatibility with legacy charging cradles and intermediate cost positioning. Li-ion configurations represent the fastest-growing chemistry segment as handset OEMs redesign around higher voltage platforms and lighter pack weights. Residential end users constitute the largest demand pool, though business telecommunications accounts for disproportionate margin capture through bulk procurement contracts and longer service-life requirements.
The EPA governs cadmium disposal thresholds in the United States, while REACH and RoHS constrain hazardous substance content across European supply chains, collectively elevating compliance costs for NiCd-containing products. Japan's METI promotes battery recycling infrastructure that shapes collection obligations for manufacturers selling into domestic channels. Stakeholders must monitor chemistry-transition timelines against charger-compatibility constraints and regional substance bans to optimize portfolio allocation across legacy and next-generation platforms.
Market Dynamics
The cordless phone battery market faces a forced chemistry transition as REACH cadmium restrictions and EPA disposal thresholds render nickel-cadmium packs structurally obsolete, compelling manufacturers to redesign around lithium-ion voltage platforms while managing charger-backward compatibility constraints.
Growth Catalysts
- EU REACH Regulation:The cadmium content ban accelerates replacement demand as residential users discard non-compliant NiCd inventory ahead of enforcement deadlines.
- Li-ion Voltage Platforms:Handset OEMs redesign charging cradles around 3.6V architectures, creating pull-through for higher-capacity replacement packs.
- Japan METI Recycling Infrastructure:Manufacturer collection obligations sustain domestic replacement cycles by ensuring proper disposal channels for end-of-life batteries.
Market Restraints
- Cobalt Price Volatility:Li-ion cathode input costs fluctuate with Democratic Republic of Congo supply disruptions, compressing margin stability for pack assemblers.
- Charger Compatibility Lock-in:Legacy 2.4V charging cradles constrain chemistry migration for installed bases exceeding fifteen years in German and Japanese households.
- Smartphone Substitution:Fixed-line cordless penetration erodes as mobile-only households expand in urban United States markets, shrinking addressable replacement volume.
Strategic Opportunities
- India Telecom Expansion:Rural landline infrastructure buildouts create first-time cordless handset demand requiring compatible battery supply.
- Business Telecommunications Contracts:Bulk procurement agreements for office DECT systems offer margin capture through multi-year service-life guarantees.
- Cross-Chemistry Retail Bundling:Electronics retailers pair replacement batteries with universal charging cradles, unlocking compatibility-constrained upgrade paths.
Industry Challenges
- Cell Balancing Expertise Gap:Pack assemblers lack firmware engineering capacity for Li-ion protection circuit integration, requiring outsourced electronics design.
- UN 38.3 Certification Timelines:Lithium battery transport safety testing delays product launches by four to six months for new cylindrical formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cordless Phone Battery Market |
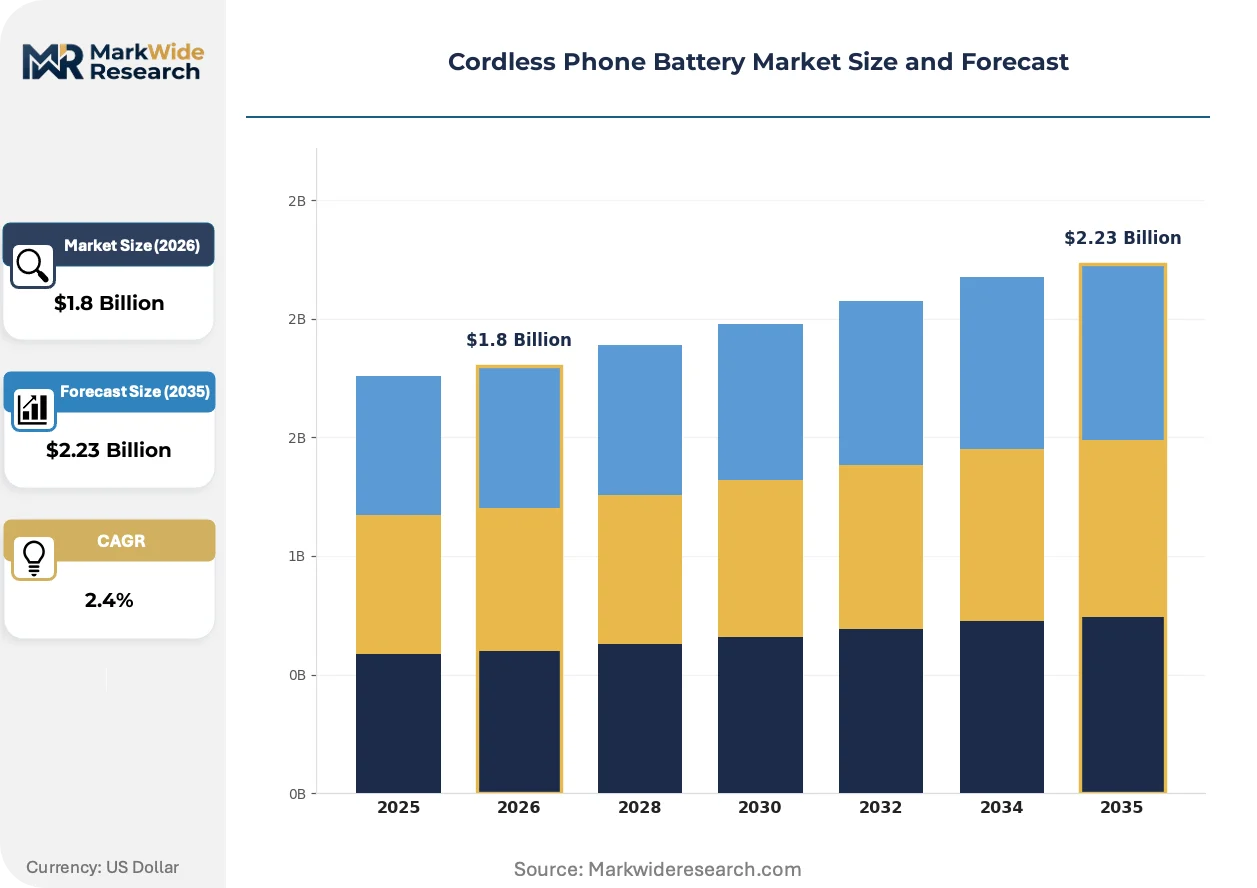
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.23 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: NiMH, Li-ion, NiCd, Li-Po End User: Residential, Business, Telecommunications, Retail Charging Method: Corded Dock, Wireless Charging, USB Charging, Fast Charging Capacity: 300mAh, 600mAh, 1200mAh, 2200mAh |
| Companies Covered | Panasonic Corporation, Samsung SDI Co. Ltd., GS Yuasa Corporation, Ultrlife Corporation, Energizer Holdings Inc., E-One Moli Energy Corp., GP Batteries International Limited, BYD Company Ltd., LG Chem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cordless Phone Battery Market Emerging Trajectories
Battery chemistry is actively reshaping competitive positioning as manufacturers abandon legacy formulations. Three developments dominate the transition window: voltage architecture migration, regulatory compliance automation, and channel consolidation around specialized distributors.
Lithium-ion cylindrical cells is overtaking nickel-metal hydride in residential replacement volumes. Home users in Germany and Japan now prioritize lighter pack weights over cradle compatibility. This chemistry migration compresses NiMH margin structures while rewarding suppliers with captive cell production.
REACH and RoHS substance tracking requirements force pack assemblers to implement automated compliance documentation systems. European distributors now reject shipments lacking full material disclosure. Small-format battery specialists in South Korea and Taiwan are investing in blockchain-traceable supply chains to maintain market access.
Aftermarket buyers increasingly bypass retail electronics chains in favor of direct-from-manufacturer online portals. This channel compression eliminates distributor markups for technically sophisticated residential users. The shift is most visible in United States replacement markets where warranty registration data enables targeted battery replenishment campaigns.
Cordless Phone Battery Market Segmentation
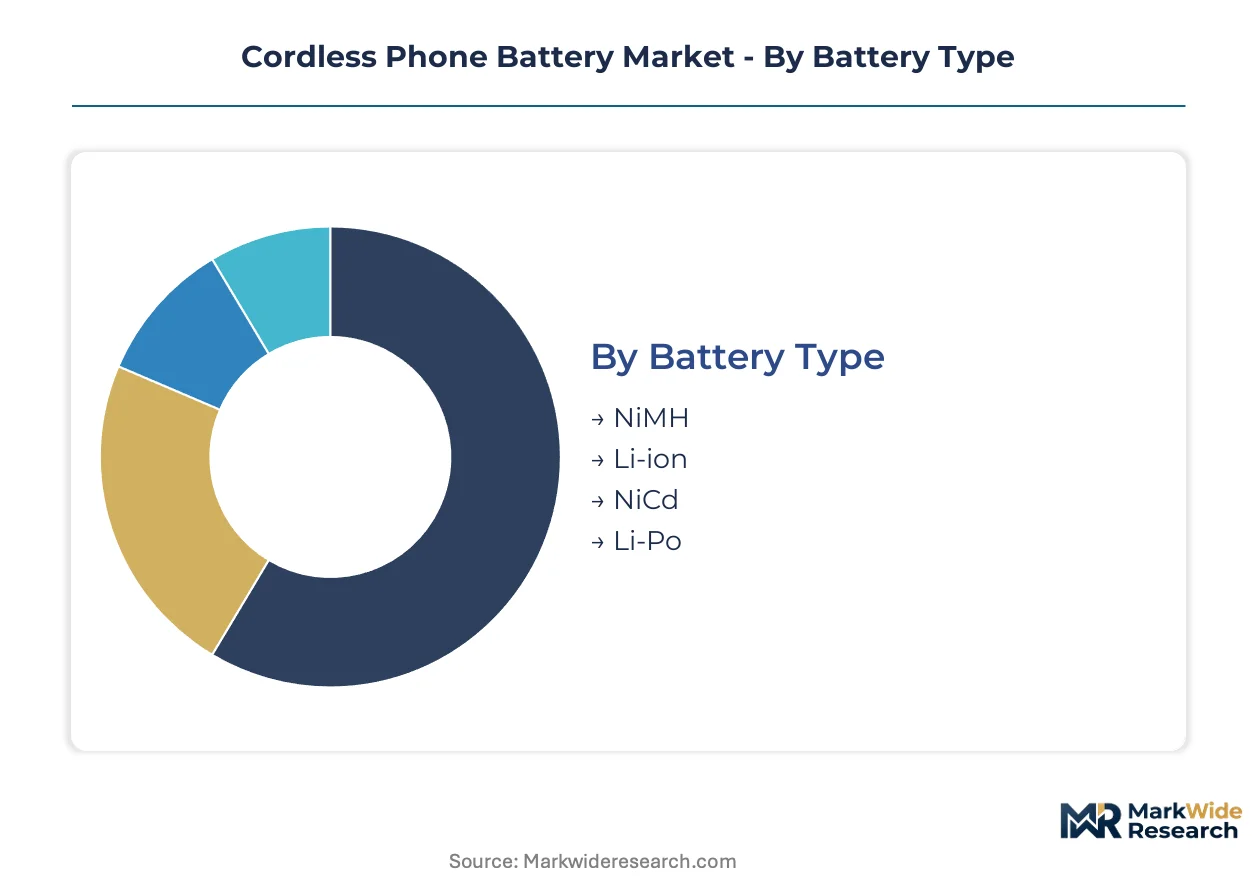
Cordless phone battery segmentation reveals how chemistry transitions and charging infrastructure constraints reshape procurement patterns. Each dimension captures distinct trade-offs between backward compatibility, energy density, and regulatory compliance that manufacturers must navigate.
Battery Type:
Standalone replacement packs dominate aftermarket volumes, while embedded cell configurations concentrate in OEM handset production.
- NiMH:Nickel-metal hydride cells deliver 2.4V nominal output with intermediate energy density suited to legacy charging cradles. Residential replacement demand concentrates in Germany and Japan where fifteen-plus-year installed bases resist voltage platform migration.
- Li-ion:Lithium-ion cylindrical formats enable 3.6V architectures with 40% weight reduction versus nickel formulations. Handset redesigns in South Korea and Taiwan are pulling OEM procurement toward higher-voltage platforms despite cradle incompatibility.
- NiCd:Nickel-cadmium packs face structural obsolescence under EU REACH cadmium restrictions and EPA disposal thresholds.
- Li-Po:Lithium-polymer prismatic configurations suit ultra-compact handset designs with irregular form factors.
Volume placements concentrate in NiMH; the faster expansion belongs to Li-ion.
End User:
Cost tier stratification separates price-sensitive mass replacement from premium service-life contracting.
- Residential:Home users prioritize cradle compatibility and cost efficiency in aftermarket replacement cycles. German and Japanese households sustain demand for 2.4V NiMH packs compatible with aging charging infrastructure.
- Business:Enterprise DECT deployments demand multi-year service-life guarantees and bulk procurement terms. Office telecommunications contracts in the United States capture disproportionate margin through performance warranties.
- Telecommunications:Carrier-managed landline infrastructure requires standardized battery specifications across handset fleets.
- Retail:Electronics chains stock universal replacement packs targeting compatibility breadth over chemistry optimization.
Procurement scale favors Business; the steepest volume climb belongs to Residential replacement cycles.
Charging Method:
Application context determines whether users prioritize convenience, speed, or infrastructure reuse.
- Corded Dock:Traditional cradle charging dominates installed-base compatibility requirements. German and Japanese households retain legacy 2.4V dock infrastructure that constrains chemistry migration.
- Wireless Charging:Inductive pad systems enable sealed handset designs eliminating contact corrosion. Premium DECT handset lines in South Korea incorporate Qi-compatible coils.
- USB Charging:Universal serial bus inputs support travel handsets and secondary charging locations.
- Fast Charging:Accelerated charge protocols demand battery management firmware and thermal protection circuits.
Installed-base dominance secures Corded Dock; the technology transition favors Wireless Charging.
Capacity:
Customer type and usage intensity segment mAh requirements across talk-time expectations.
- 300mAh:Entry-level cylindrical packs serve occasional-use residential handsets with minimal standby demands. Budget cordless phones in Indian retail channels specify this tier for cost minimization.
- 600mAh:Mid-range capacities balance physical pack size against multi-day standby performance. Standard DECT handsets in European business deployments specify this tier for eight-hour talk-time compliance.
- 1200mAh:Extended-capacity NiMH and Li-ion configurations support heavy residential use patterns.
- 2200mAh:Maximum-capacity Li-ion packs enable all-day talk time in professional DECT headsets and multi-handset base stations.
Shipments cluster at 600mAh; the specification trend moves toward 1200mAh.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Replacement cycles concentrate in Germany, Japan, and the United States where aging cordless phone installed bases sustain aftermarket demand. These mature markets exhibit divergent chemistry adoption timelines shaped by charging infrastructure legacy and regulatory pressure. Regional variation in substance restrictions and recycling obligations creates distinct competitive environments for pack assemblers.
Germany
Legacy NiMH demand persists among households retaining fifteen-year-old charging cradles. ECHA REACH cadmium restrictions accelerate NiCd phase-out while creating compliance documentation burdens for distributors. Industrial battery specialists in North Rhine-Westphalia supply replacement packs to electronics retailers across the DACH region.
Japan
METI recycling infrastructure mandates manufacturer collection obligations that sustain domestic replacement cycles. Home users prioritize lighter Li-ion packs despite cradle incompatibility with aging base stations. Osaka-based pack assemblers serve both residential aftermarket and business telecommunications contracts.
United States
EPA disposal thresholds elevate compliance costs for NiCd-containing inventory while smartphone substitution erodes fixed-line cordless penetration. Business DECT deployments in Texas and California generate bulk procurement demand with multi-year service guarantees. Retail channel consolidation favors direct-from-manufacturer online portals.
South Korea
Handset OEMs in Seoul redesign charging architectures around 3.6V Li-ion platforms. Domestic cell producers supply cylindrical formats to regional DECT manufacturers. Government efficiency standards accelerate voltage platform migration across consumer electronics categories.
India
Rural landline infrastructure expansion creates first-time cordless handset demand requiring compatible battery supply. BIS certification requirements shape import compliance for replacement pack distributors. Maharashtra-based electronics assemblers source entry-level NiMH configurations for cost-sensitive retail channels.
Cordless Phone Battery Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with consumer-facing names dominating retail replacement channels while OEM-integrated cell producers capture handset original equipment supply. The market exhibits moderate concentration at the cell production tier and fragmentation among downstream pack assemblers. Three archetypes define competitive positioning: captive cell producers with backward integration into cathode materials, branded pack specialists leveraging retail distribution control, and regional contract manufacturers serving cost-optimized aftermarket demand. Capacity expansion and chemistry-transition portfolio diversification constitute the dominant competitive moves as players navigate NiCd obsolescence and Li-ion certification requirements.
Among Asia-Pacific cell producers, Panasonic Corporation and Samsung SDI Co. Ltd. exemplify the vertically integrated archetype with captive production of energy-dense cylindrical formats. Energizer Holdings Inc. occupies a distinct position as a branded specialist anchoring North American retail replacement markets through channel presence and warranty recognition. These three companies represent divergent strategic approaches to chemistry transition timing and geographic market prioritization.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Samsung SDI Co. Ltd. |
| GS Yuasa Corporation |
| Ultrlife Corporation |
| Energizer Holdings Inc. |
| E-One Moli Energy Corp. |
| GP Batteries International Limited |
| BYD Company Ltd. |
| LG Chem |
| Others |
Supply Flow & Price Mechanics
Cell-balancing firmware engineers cluster in South Korea and Taiwan, creating labor-cost differentials that widen spreads between premium Li-ion packs and economy NiMH replacements. German pack assemblers absorb higher European labor rates while competing against Asian contract manufacturers on entry-level 2.4V configurations.
Pricing Analysis
Volume shipments concentrate in 600mAh NiMH tiers where margin compression runs deepest; premium capture concentrates in 2200mAh Li-ion configurations for business DECT contracts. Price differentiation hinges on UN 38.3 certification status and cradle-backward compatibility guarantees. Cost compression in standard-tier NiMH intensifies as REACH compliance documentation burdens small assemblers. Residential replacement buyers in Germany and Japan exhibit highest price sensitivity; enterprise telecommunications procurement in the United States shows lowest sensitivity due to multi-year service-life contracting.
Supply Chain Analysis
Reverse-logistics flows for end-of-life NiCd packs concentrate through Japan's METI-mandated collection infrastructure and Germany's ECHA-compliant recycler networks. Cathode active material production concentrates in China, South Korea, and Japan. Pack assembly draws from cylindrical cell supply anchored in Osaka and Seoul manufacturing clusters. Single-source vulnerability sits with cobalt hydroxide feedstock from Democratic Republic of Congo. Distribution runs through electronics retail chains in North America and specialized industrial distributors across the DACH region.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cordless phone battery markets sit in a forced chemistry-transition phase as lithium-ion voltage platforms displace legacy nickel-cadmium and nickel-metal hydride formulations. Li-ion cylindrical formats are capturing replacement volume from aging 2.4V installed bases.
For Market Incumbents: Acquire cell-balancing firmware engineering capabilities to reduce outsourced electronics design dependencies. Secure backward-compatible charging cradle partnerships to ease residential migration from 2.4V NiMH infrastructure. Smartphone substitution threatens fixed-line cordless penetration; defend margin position through bulk enterprise DECT contracting with multi-year performance warranties. For New Entrants and Emerging Players: The 40-50% price-point gap between premium Li-ion business packs and economy NiMH residential replacements opens white-space targeting. Focus initial penetration on India's rural landline infrastructure expansion requiring entry-level 300mAh NiMH supply. Leverage direct-from-manufacturer online portals to bypass retail distributor markups in United States replacement markets. For Investors and Strategic Acquirers: Re-rating potential sits with captive cell producers given cobalt price volatility and chemistry-transition timing advantages. Long-term viability favors upstream-integrated assemblers with in-house cathode material production. Monitor UN 38.3 certification backlog durations as early signal for Li-ion supply constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Li-ion Voltage Platform Migration | Handset OEMs in Seoul redesign charging architectures around 3.6V cylindrical formats. |
| REACH Compliance Automation Investment | European distributors now reject shipments lacking blockchain-traceable material disclosure. |
| Direct-to-Consumer Portal Launch | Warranty registration data enables targeted battery replenishment campaigns in United States markets. |
| Enterprise DECT Contract Expansion | Multi-year service-life guarantees capture disproportionate margin in business telecommunications. |
| India Distribution Partnership | BIS certification requirements shape import compliance for Maharashtra-based electronics assemblers. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this cordless phone battery market assessment. Primary interviews with pack assembly plant managers, electronics retailer category buyers, OEM handset procurement leads, and industrial battery distribution channel partners combined with secondary validation. Secondary sources included ECHA REACH substance databases, METI recycling infrastructure reports, EPA disposal threshold guidance, UN 38.3 transport safety documentation, and regional customs import records. Bottom-up unit shipment estimates triangulated against top-down chemistry-transition demand projections.
Data-stream reconciliation across replacement volume tracking, OEM procurement surveys, and retail sell-through audit channels shaped the analytical framework. Segmentation dimensions modeled encompassed battery chemistry type, end-user category, charging method, and capacity tier alongside regional regulatory cluster variations. CAGRs were derived through installed-base aging curve analysis and chemistry substitution rate modeling. Forecast inputs incorporated cradle-backward compatibility constraints and REACH enforcement timeline assumptions.
Inputs from Japanese METI collection statistics and German ECHA compliance registries were available through the study window; gaps in real-time cobalt price volatility data introduce uncertainty bands around Li-ion pack margin projections. Forecasts reflect documented assumptions regarding charger infrastructure replacement cycles and smartphone substitution rates. Practitioners should monitor UN 38.3 certification queue lengths and REACH cadmium restriction enforcement deadlines for early signals of supply-side constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Data Acquisition Card Market
Electronic Components
Multi-Layer Ceramic Capacitor (MLCC) Market
Electronic Components
Coaxial Attenuators Market
Electronic Components
Gigabit Interface Converter Market
Electronic Components
Radiation Hardened Electronics Market
Electronic Components
Bonding Wires and Ribbons Market
Electronic Components
Tower Mounted Amplifier Market
Electronic Components
Audio Power Amplifier Market
Electronic Components
RAID Controller Card Market
Electronic Components
Special Function Data Convertors Market
Electronic Components
Bluetooth Adapter Market
Electronic Components
Speaker Membranes Market
Electronic Components
Electromechanical Timers Market
Electronic Components
Dual Relay Board Market
Electronic Components
Low-Dropout (LDO) Regulator Market
Electronic Components
Fuel Pump Driver Module Market