
 Silicon Capacitors Market | 2026-2036
Silicon Capacitors Market Size, Share, and Industry Trends Forecast 2026-2036
Silicon Capacitors Market Outlook
Modular die-stacking configurations is decoupling silicon capacitor procurement from traditional passive component bundles, letting buyers specify integrated deep-trench capacitors at the wafer level rather than sourcing discrete parts. KYOCERA AVX Components Corporation leverages its ceramic-to-silicon hybrid expertise to anchor high-reliability defense and aerospace contracts. Murata Manufacturing Co Ltd sustains manufacturing scale across multi-layer ceramic and silicon capacitor portfolios, competing on total cost of ownership for automotive module suppliers. TSMC dominates advanced packaging roadmaps where silicon capacitors embed directly into interposer substrates.
Silicon capacitors employ deep-trench etching in monocrystalline silicon wafers, achieving capacitance densities above 200 nF per square millimeter with breakdown voltages tailored to sub-1V processor cores, and serve primarily to stabilize power delivery in high-current, fast-switching integrated circuits. Ceramic capacitors within the product type taxonomy remain the volume baseline for consumer electronics filtering, while film capacitors occupy margin-rich niches in renewable energy inverter stages where thermal cycling endurance commands price premiums. Surface mount technology leads assembly methodology, though high-frequency technology segments gain share as 5G baseband and radar modules push operating bandwidths past 77 GHz.
RoHS and REACH compliance in Europe constrain lead-bearing termination materials and mandate full material disclosure, while the EU Chips Act directs subsidy eligibility toward domestic silicon capacitor fabrication capacity. In the United States, the FDA regulates silicon capacitors incorporated into implantable medical devices through biocompatibility and reliability testing protocols, and the IRA's domestic content bonuses for clean energy hardware indirectly stimulate film and ceramic capacitor demand in inverter supply chains. Stakeholders must track how export control expansions on advanced semiconductor manufacturing equipment affect silicon capacitor process tool availability outside East Asia.
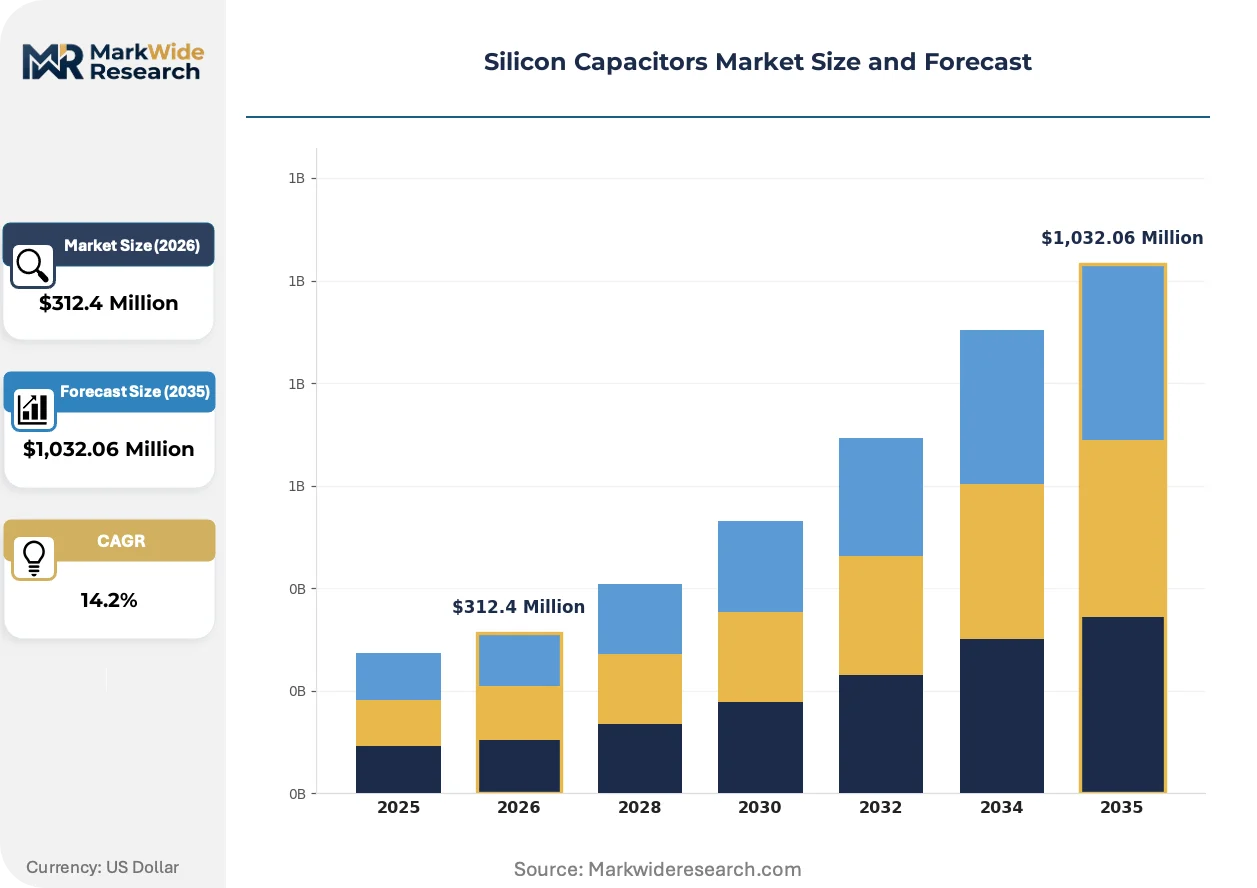
Market Dynamics
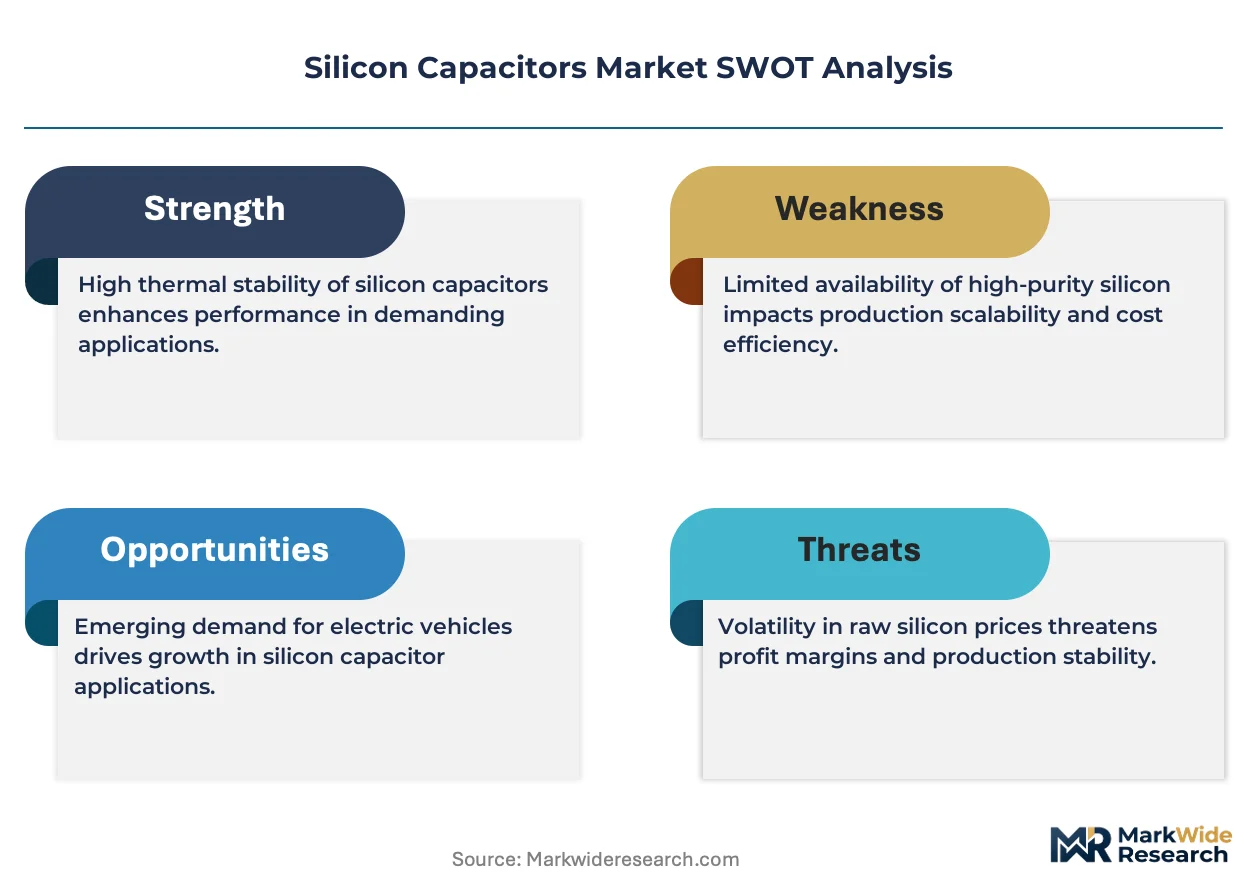
Deep-trench silicon capacitor fabrication is concentrating advanced packaging capacity among East Asian foundries, decoupling passive component procurement from traditional discrete supply chains and embedding capacitance directly at the wafer level.
Growth Catalysts
- AI Accelerator Packaging:Advanced interposer substrates in Taiwan and South Korea are absorbing silicon capacitors as standard die-stacking elements, replacing surface-mount discrete banks with integrated deep-trench structures.
- EU Chips Act Subsidies:Captive silicon capacitor fabrication capacity now qualifies for foundry investment incentives, redirecting European semiconductor investment toward domestic deep-trench etching lines.
- Sub-1V Core Stabilization:Processor power delivery networks below one volt require capacitance densities exceeding 200 nF per square millimeter, a threshold only monocrystalline silicon architectures achieve.
Market Restraints
- Equipment Concentration:Deep reactive-ion etching tools for high-aspect-ratio trenching concentrate among Japanese and German equipment suppliers, creating single-source vulnerability for new market entrants.
- High-Purity Silicon Wafer Costs:Monocrystalline substrate prices fluctuate with solar photovoltaic demand cycles, compressing gross margins for capacitor manufacturers without long-term polysilicon contracts.
- Multi-Layer Ceramic Substitution:Automotive module suppliers continue specifying X7R and C0G ceramic dielectrics for cost-sensitive filtering below 100 MHz, limiting silicon capacitor penetration in volume consumer applications.
Strategic Opportunities
- Defense and Aerospace Contracts:KYOCERA AVX's ceramic-to-silicon hybrid expertise anchors high-reliability programs requiring MIL-STD-883 qualification, a segment commanding price premiums over commercial equivalents.
- 5G Millimeter-Wave Modules:Baseband and radar applications past 77 GHz operating bandwidths favor silicon capacitor thermal stability over ceramic temperature coefficient drift, opening new frequency domains.
- Renewable Energy Inverters:Film capacitor thermal cycling limitations in solar and wind inverter stages create upgrade pathways for silicon alternatives with superior endurance under temperature swing stress.
Industry Challenges
- Deep-Trench Etching Talent Scarcity:Process engineers with high-aspect-ratio plasma etching expertise concentrate among incumbent foundries, constraining capacity expansion timelines for new fabrication facilities.
- Biocompatibility Certification Timelines:FDA implantable medical device qualification protocols extend silicon capacitor validation cycles to 24-36 months, delaying revenue recognition for healthcare-targeted product lines.
- Interposer Design Integration Complexity:System-in-package architects must retime power delivery network simulations to account for embedded capacitor parasitics, extending customer qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicon Capacitors Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,032.06 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrolytic Capacitors, Ceramic Capacitors, Film Capacitors, Tantalum Capacitors Application: Consumer Electronics, Automotive Systems, Telecommunications, Renewable Energy Systems End User: Manufacturers, OEMs, Distributors, Aftermarket Providers Technology: Surface Mount Technology, Through-Hole Technology, High-Frequency Technology, Power Electronics |
| Companies Covered | KYOCERA AVX Components Corporation, MACOM Technology Solutions Holdings Inc, Murata Manufacturing Co Ltd, TSMC, Empower Semiconductor, Vishay Intertechnology Inc, Microchip Technology Inc, ROHM Semiconductor Co Ltd, Skyworks Solutions Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicon Capacitors Market Strategic Shifts
Silicon capacitor technology is converging with advanced packaging roadmaps, embedding passive functionality directly into active die stacks rather than treating capacitance as a board-level afterthought. Three developments are compressing traditional supply chain configurations.
Deep-trench etching in monocrystalline silicon wafers is integrating capacitance formation with front-end semiconductor processing, eliminating separate passive component mounting steps. Hyperscale data center customers in East Asian manufacturing clusters are specifying these integrated structures for AI training accelerators. The structural consequence is compressing bill-of-materials line counts while shifting procurement decisions from component distributors to foundry tape-out teams.
REACH and RoHS compliance mandates in Europe are constraining lead-bearing termination materials and mandating full material disclosure across capacitor supply chains. Subsidy eligibility under the EU Chips Act now predicates foundry investment on demonstrated domestic silicon capacitor fabrication capacity. Automotive module suppliers serving European OEMs are responding by dual-sourcing ceramic and silicon portfolios to hedge against regulatory friction in cross-border component flows.
Buyers are consolidating specification authority within semiconductor packaging design teams rather than delegating passive component selection to commodity procurement functions. Distributor relationships with traditional MLCC suppliers face disintermediation pressure as foundries absorb capacitor sourcing into captive interposer supply chains. This concentration is most visible in Taiwan and South Korea, where TSMC and Samsung Foundry customers now specify silicon capacitor integration at the wafer level during initial floorplanning stages.
Silicon Capacitors Market Segmentation
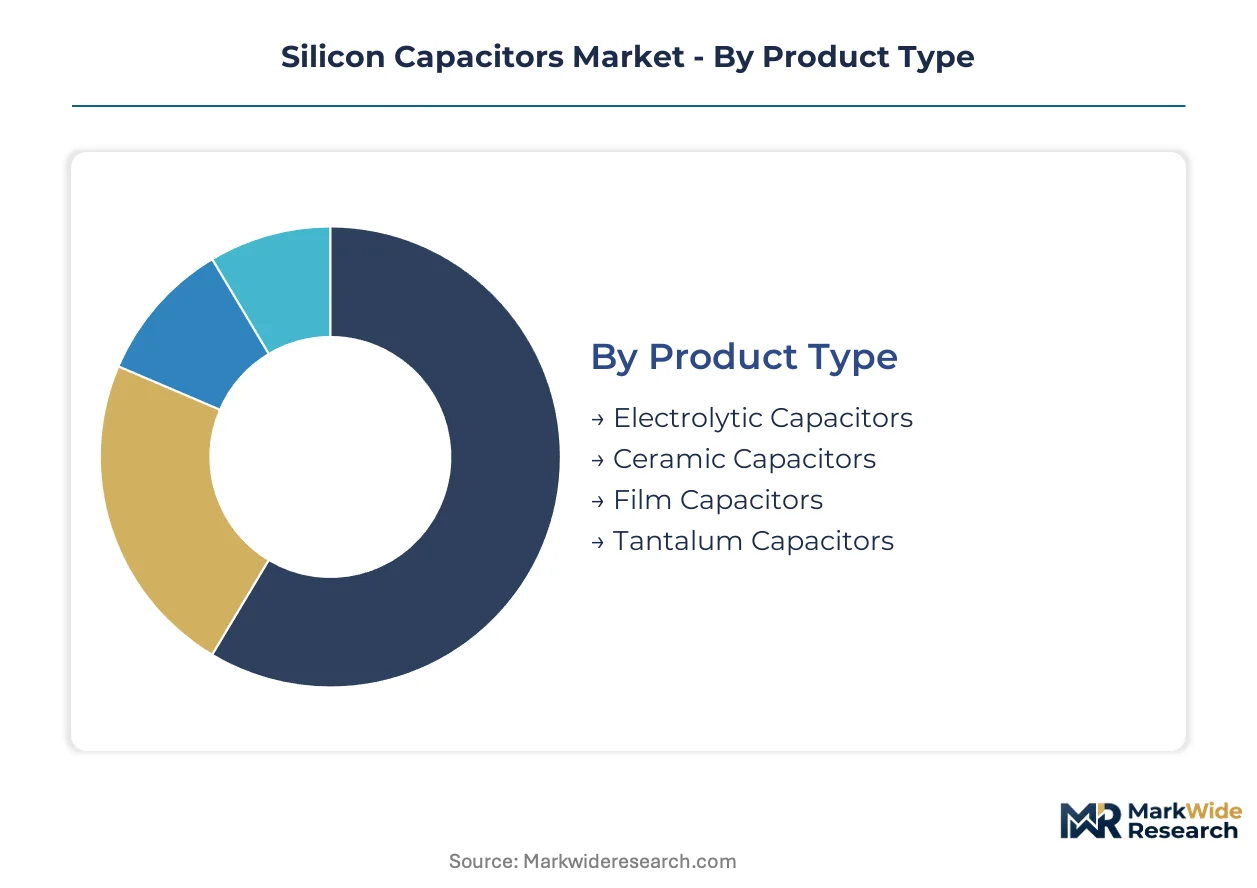
Segmentation in silicon capacitors reveals how capital deployment and technical requirements fragment procurement authority across foundries, module suppliers, and distribution channels. Understanding these divisions exposes where specification power concentrates and where margin pools shift.
Product Type:
Electrolytic and ceramic variants demand the heaviest upfront tooling investment, while film and tantalum architectures require specialized material purification infrastructure.
- Ceramic Capacitors:Multi-layer dielectric stacks of barium titanate achieve the highest volume shipment positions across consumer electronics filtering. Automotive module suppliers in Germany and Japan specify X7R and C0G formulations for cost-sensitive applications below 100 MHz operating frequencies.
- Film Capacitors:Polypropylene and polyester dielectrics deliver thermal cycling endurance for renewable energy inverter stages. Wind and solar installations in Denmark and Texas favor these structures where temperature swing stress exceeds ceramic tolerance limits.
- Electrolytic Capacitors:Aluminum oxide dielectrics with liquid or polymer electrolytes dominate bulk capacitance requirements in power supply stages.
- Tantalum Capacitors:Manganese dioxide or conductive polymer cathodes serve military and aerospace programs requiring volumetric efficiency under severe mechanical stress.
Ceramic capacitors absorb the bulk of installed capacity; film capacitors are expanding most quickly in renewable energy applications.
Application:
Automotive and telecommunications segments concentrate the most demanding reliability specifications, while consumer electronics and renewable energy systems fragment across cost-performance tradeoffs.
- Automotive Systems:Powertrain electrification and advanced driver-assistance systems impose AEC-Q200 qualification requirements on all passive components. Battery management systems in South Korean and German vehicle platforms specify capacitors with operating temperature ranges from minus 55 to 150 degrees Celsius.
- Telecommunications:5G baseband and millimeter-wave radar modules push operating bandwidths past 77 GHz, demanding thermal stability that silicon architectures provide over ceramic temperature coefficient drift. Base station deployments in Taiwan and Finland specify these components for phased-array antenna calibration circuits.
- Consumer Electronics:Smartphones, laptops, and wearables drive volume consumption of compact surface-mount components with relaxed reliability requirements.
- Renewable Energy Systems:Solar inverters and wind turbine power converters require extended operational lifetimes under thermal cycling stress.
Automotive systems absorb the bulk of qualification engineering resources; telecommunications is climbing the fastest as 5G infrastructure deployment accelerates.
End User:
Manufacturers and OEMs capture specification authority in advanced packaging integration, while distributors and aftermarket providers retain influence in replacement and repair channels.
- Manufacturers:Semiconductor foundries and contract assembly houses specify capacitor integration at the wafer or substrate level. TSMC and Samsung Foundry customers in Hsinchu and Pyeongtaek now embed silicon capacitors directly into interposer designs during initial floorplanning stages.
- OEMs:Original equipment manufacturers in medical devices and industrial automation retain component selection authority for systems requiring FDA or IEC certification. Implantable device makers in Minnesota and Massachusetts extend validation cycles to 24-36 months for biocompatibility clearance.
- Distributors:Arrow Electronics and Avnet maintain inventory positions for standard ceramic and electrolytic lines serving mid-volume contract manufacturers.
- Aftermarket Providers:Repair and refurbishment specialists source replacement capacitors for legacy industrial equipment and consumer product warranty service.
Manufacturers absorb the bulk of design-in activity; OEMs are gaining share fastest as system-level integration requirements intensify.
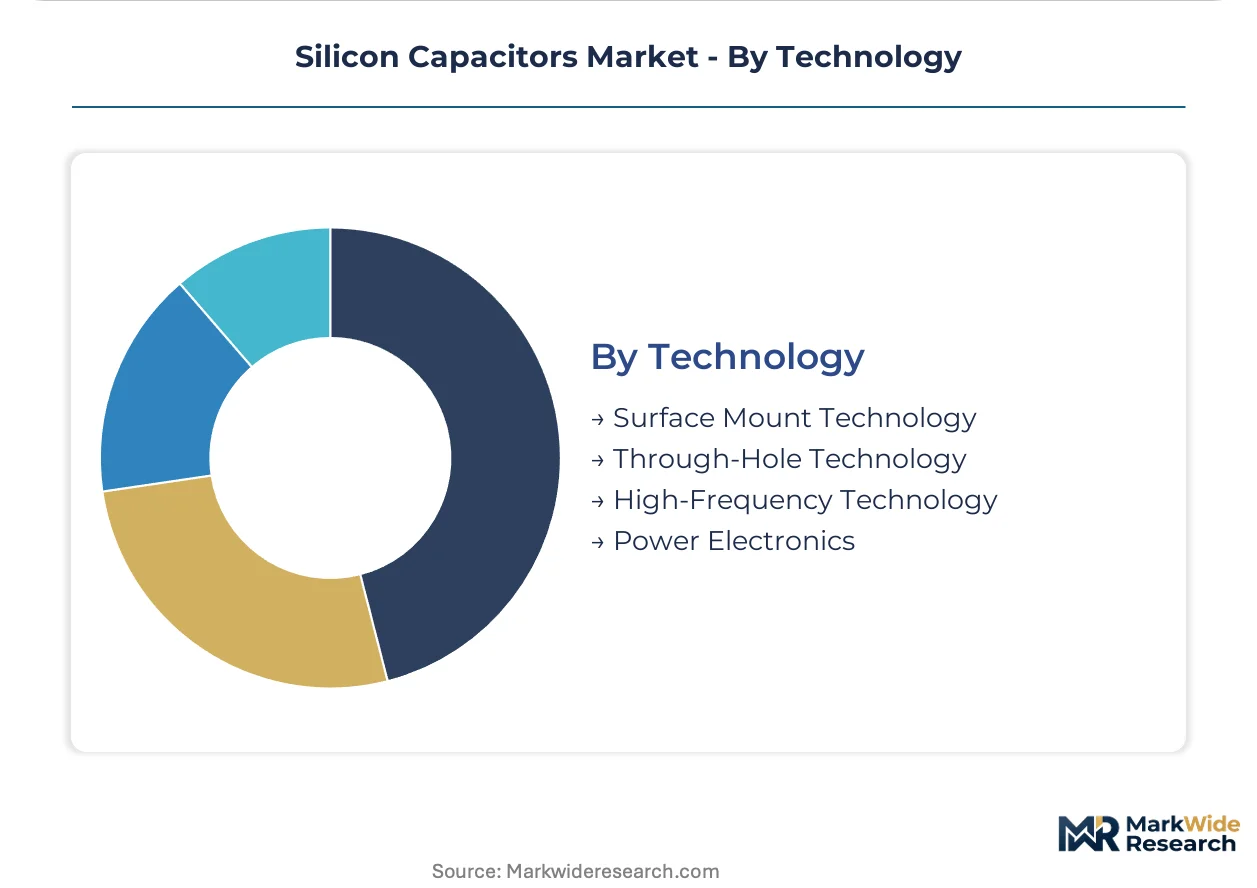
Technology:
Surface mount and high-frequency technologies concentrate the most advanced process tooling, while through-hole and power electronics segments rely on mature equipment bases.
- Surface Mount Technology:Pick-and-place assembly of compact chip capacitors dominates consumer electronics and automotive module production. Assembly lines in Shenzhen and Guadalajara process billions of units monthly with placement accuracies below 50 microns.
- High-Frequency Technology:Specialized dielectric formulations and electrode geometries address millimeter-wave and radar applications. 5G baseband processors in Ericsson and Nokia supply chains specify these components for signal integrity preservation above 6 GHz.
- Through-Hole Technology:Leaded component mounting persists in industrial power supplies and military hardware requiring mechanical strain relief.
- Power Electronics:High-voltage and high-current capacitor designs serve motor drives, grid-tied inverters, and electric vehicle charging infrastructure.
Surface mount technology absorbs the bulk of production volume; high-frequency technology is expanding most quickly in telecommunications infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park tax incentives concentrate advanced packaging capacity for silicon capacitors serving AI accelerator supply chains. South Korean government subsidies under the K-Semiconductor Belt program redirect foundry investment toward captive deep-trench fabrication lines. European subsidy eligibility under the EU Chips Act predicates foundry investment on demonstrated domestic silicon capacitor fabrication capacity.
United States
Implantable medical device manufacturers in Minnesota and Massachusetts drive demand for biocompatible silicon capacitors with extended validation cycles. FDA regulates these components through reliability testing protocols under 21 CFR Part 820 quality system regulations. Greater Boston anchors defense and aerospace contracting where KYOCERA AVX secures MIL-STD-883 qualified programs.
Taiwan
TSMC dominates advanced packaging roadmaps where silicon capacitors embed directly into interposer substrates for hyperscale data center customers. The National Development Council coordinates semiconductor investment incentives that qualify deep-trench etching capacity expansion. Hsinchu and Tainan Science Parks concentrate die-stacking configurations that decouple capacitor procurement from discrete component bundles.
South Korea
Samsung Foundry customers specify silicon capacitor integration at the wafer level during initial floorplanning for AI training accelerators. The Ministry of Trade, Industry and Energy administers K-Chips Act subsidies redirecting investment toward captive silicon capacitor supply chains. Pyeongtaek and Yongin clusters absorb the bulk of advanced interposer substrate production for sub-1V core stabilization applications.
Germany
Automotive module suppliers specify X7R and C0G ceramic dielectrics for cost-sensitive filtering below 100 MHz operating frequencies in battery management systems. REACH and RoHS compliance constrains lead-bearing termination materials and mandates full material disclosure across capacitor supply chains. Bavaria and Baden-Württemberg anchor powertrain electrification programs imposing AEC-Q200 qualification requirements on passive components.
Japan
Deep reactive-ion etching tools for high-aspect-ratio trenching concentrate among Japanese equipment suppliers creating single-source vulnerability for new market entrants. METI coordinates supply chain resilience initiatives targeting domestic silicon capacitor fabrication capacity. Kyoto and Osaka prefectures sustain manufacturing scale across multi-layer ceramic and silicon capacitor portfolios competing on total cost of ownership.
Silicon Capacitors Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across silicon capacitor procurement channels. The market structure concentrates specification authority within semiconductor packaging design teams rather than commodity procurement functions. Three archetypes dominate: foundry-integrated captive suppliers, ceramic-to-silicon hybrid specialists, and discrete component distributors facing disintermediation pressure. Competitive moves center on backward integration into deep-trench etching capacity and strategic partnerships with advanced packaging roadmaps.
Among Japanese diversified electronics manufacturers, Murata Manufacturing Co Ltd and KYOCERA AVX Components Corporation exemplify hybrid portfolio strategies spanning multi-layer ceramic and silicon architectures. TSMC represents the foundry-integrated archetype where capacitor sourcing absorbs into captive interposer supply chains. These three anchors illustrate how specification power shifts from component distributors to semiconductor packaging design teams in Taiwan and South Korea manufacturing clusters.
| Leading Market Players |
|---|
| KYOCERA AVX Components Corporation |
| MACOM Technology Solutions Holdings Inc |
| Murata Manufacturing Co Ltd |
| TSMC |
| Empower Semiconductor |
| Vishay Intertechnology Inc |
| Microchip Technology Inc |
| ROHM Semiconductor Co Ltd |
| Skyworks Solutions Inc |
| Others |
Value Chain & Pricing Dynamics
Captive foundry integration anchors both supply position and pricing power in silicon capacitors, as TSMC and Samsung Foundry customers embed deep-trench structures directly into interposer substrates during initial floorplanning rather than sourcing discrete components through distribution channels. This structural shift concentrates procurement authority within semiconductor packaging design teams and decouples capacitor sourcing from traditional passive component spot markets.
Pricing Analysis
Lead-time-driven pricing stratification separates expedited wafer-level integration from standard discrete component procurement, with premium tiers commanding substantial markups for die-stacking configurations under tight tape-out schedules. Price differentiation rests on certification grade—MIL-STD-883 qualified products for defense programs versus commercial-grade offerings—and volume scale, with hyperscale data center contracts securing preferential allocation. Cost compression in ceramic substitution tiers is intensifying because automotive module suppliers continue specifying X7R and C0G dielectrics for cost-sensitive filtering below 100 MHz. Contract manufacturers in East Asian clusters exhibit the highest price sensitivity, while defense and aerospace programs demonstrate the least.
Supply Chain Analysis
Dual-sourcing requirements from automotive and medical device OEMs mandate multi-supplier qualification for deep-trench etching capacity, forcing foundries to maintain redundant tool sets across Japanese and German equipment suppliers. Geographic supply concentration centers on Taiwan, South Korea, and Japan, where Hsinchu and Pyeongtaek clusters absorb the bulk of advanced interposer production. Raw material dependencies draw from high-purity monocrystalline silicon wafers, photoresist chemistries, and specialized plasma etching gases. Single-source vulnerability in deep reactive-ion etching tools creates acute supply chain risk. Distribution runs through foundry-direct channels for integrated capacitors and traditional electronics distributors for discrete alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Deep-trench etching talent scarcity props pricing power by constraining capacity expansion timelines, creating a supply-constrained market structure where qualified process engineers concentrate among incumbent foundries. This bottleneck limits rapid supply response even as AI accelerator demand accelerates.
For Market Incumbents: To counter disintermediation pressure from foundry-integrated captive supply chains, Murata Manufacturing and KYOCERA AVX should anchor backward integration into deep-trench etching capacity in Japan and expand ceramic-to-silicon hybrid portfolios for defense qualification. Certification investment in MIL-STD-883 and AEC-Q200 tiers secures margin-protected segments against commodity ceramic substitution.
For New Entrants and Emerging Players: Millimeter-wave thermal stability expertise offers a technology-first wedge into 5G baseband and radar modules past 77 GHz, where silicon architectures outperform ceramic temperature coefficient drift. White-space targets include renewable energy inverter stages requiring thermal cycling endurance beyond film capacitor limits, and implantable medical devices where FDA validation cycles deter rapid incumbent response. A go-to-market angle partnering with European automotive module suppliers on REACH-compliant material disclosure accelerates qualification.
For Investors and Strategic Acquirers: Exit pathways concentrate in foundry-integrated acquisitions by TSMC and Samsung Foundry seeking captive deep-trench capacity, or defense-aerospace platform rollups by diversified industrials. Long-term viability favors specialists with demonstrated interposer design integration and biocompatibility certification timelines. The signal to watch is EU Chips Act subsidy disbursement velocity for domestic European fabrication capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Deep-Trench Etching Capacity Expansion | Captive fabrication lines in Taiwan and South Korea secure allocation priority for AI accelerator interposers. |
| Ceramic-to-Silicon Hybrid Portfolio Development | MIL-STD-883 qualification opens defense programs commanding price premiums over commercial equivalents. |
| 5G Millimeter-Wave Module Partnership | Ericsson and Nokia supply chains specify thermal-stable components for phased-array antenna calibration. |
| Biocompatibility Certification Investment | FDA 21 CFR Part 820 compliance enables implantable medical device revenue recognition in Minnesota clusters. |
| EU Chips Act Subsidy Alignment | Domestic European fabrication capacity qualifies for foundry investment incentives under REACH and RoHS mandates. |
Study Parameters
Document review covered SEC filings from capacitor and semiconductor manufacturers, EU Chips Act subsidy disclosures, and FDA 21 CFR Part 820 quality system regulations, complemented by interviews with foundry packaging engineers, automotive module procurement leads, and defense program qualification officers. Secondary validation drew from customs trade data for monocrystalline silicon wafer flows, METI supply chain resilience reports, and AEC-Q200 reliability databases. Bottom-up unit demand estimates from interposer substrate production combined with top-down foundry capex allocations to triangulate market sizing.
Segmented outputs across product type, application, end user, and technology dimensions reflect penetration modeling for AI accelerator packaging, automotive electrification, and 5G infrastructure deployment over the projection horizon. CAGRs derived from foundry capacity expansion schedules, polysilicon contract pricing trajectories, and hyperscale data center buildout trajectories in East Asian manufacturing clusters. The analytical framework incorporated deep-trench etching tool installation rates and process engineer labor pool constraints as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under export control expansions on advanced semiconductor manufacturing equipment or photovoltaic demand spikes compressing high-purity silicon wafer availability. A model refresh is warranted upon material change in EU Chips Act subsidy eligibility criteria or K-Semiconductor Belt program disbursement velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Wireless Charging Stand Market
Electronic Components
Flexible Heater Market
Electronic Components
US Frequency Control and Timing Devices Market
Electronic Components
Global Multilayer Varistors Market
Electronic Components
Gigabit Interface Converter Market
Electronic Components
Pulse Width Modulation Controllers Market
Electronic Components
Bluetooth Adapter Market
Electronic Components
Printed Circuit Board Market
Electronic Components
Touch Screen Controllers Market
Electronic Components
Bonding Wires and Ribbons Market
Electronic Components
Stretchable Conductors in Electronics Market
Electronic Components
Hydrogen Thyratron Market
Electronic Components
AC Adapter Market
Electronic Components
Camera Battery Charger Market
Electronic Components
Battery Shunt Resistor Market
Electronic Components
Structural Electronics Market