
 Metal Oxide Varistor (MOV) Market | 2026-2036
Metal Oxide Varistor (MOV) Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Oxide Varistor (MOV) Market Foresight
Automotive OEMs are bifurcating from traditional appliance and telecom buyers as the fastest-growing demand archetype for MOVs. TDK Corporation leverages its ceramics expertise to anchor high-voltage disc supply for EV inverters. Vishay Intertechnology competes through broad radial and surface-mount portfolios that sustain design wins across industrial and consumer segments.
A metal oxide varistor is a nonlinear resistive device fabricated from zinc oxide grains interspersed with bismuth, cobalt, and manganese oxide boundary layers, exhibiting a sharp transition from insulating to conducting state when clamp voltage is exceeded. Its primary purpose is transient voltage suppression in AC and DC circuits, protecting semiconductors and insulation systems from lightning-induced surges and switching transients. Disc-type MOVs dominate margin pools in renewable energy and medium-voltage distribution due to higher energy absorption requirements, while surface-mount variants are capturing the fastest growth in compact consumer electronics and automotive control modules where PCB density constraints intensify. Low-voltage ratings still occupy the largest volume share across power supplies and electrical appliances, though ultra-high-voltage segments are deepening as offshore wind and utility-scale solar installations expand.
IEC 61000-4-5, AEC-Q200, and UL 1449 collectively define surge immunity benchmarks, automotive qualification protocols, and safety listing requirements that determine market access and product differentiation. China's GB/T 18802 and SAMR certification processes add further compliance layers for suppliers targeting domestic EV and grid infrastructure procurement. Stakeholders must monitor how next-generation wide-bandgap semiconductor adoption in inverters and chargers alters clamp energy specifications and MOV redundancy architectures.
Market Dynamics
Automotive electrification is compressing qualification timelines for surge protection components as OEMs demand AEC-Q200 certification alongside higher energy density specifications for 800V architectures.
Growth Catalysts
- EV Inverter Protection Mandates:IEC 61000-4-5 surge immunity requirements are hardening across European and North American automotive supply chains, forcing tier-one suppliers to double MOV inventory coverage for onboard chargers and DC-DC converters.
- China Grid Modernization:SAMR certification processes for GB/T 18802 standards are accelerating procurement of high-voltage disc varistors for utility-scale solar and offshore wind installations along the eastern seaboard.
- Silicon Carbide Adoption:Wide-bandgap semiconductor deployment in traction inverters is demanding faster-clamping, lower-capacitance MOV architectures to protect sensitive gate drivers from switching transients.
Market Restraints
- Zinc Oxide Price Volatility:Raw material concentration in Chinese smelting operations exposes margin structures to commodity swings and export quota uncertainties.
- Technical Performance Ceiling:Energy absorption density in conventional sintered discs faces physical limits that constrain single-device protection for multi-megawatt renewable installations.
- Substitution by TVS Diodes:Transient voltage suppression arrays are capturing low-energy protection slots in consumer electronics where clamping speed outweighs energy handling.
Strategic Opportunities
- India Manufacturing Localization:BIS certification mandates and PLI scheme incentives for electronics components are opening captive supply opportunities for disc and axial MOV production serving domestic appliance and automotive markets.
- Module-Integrated Protection:Convergence of MOV functionality with fuse and disconnect architectures is enabling single-subsystem surge protection for compact EV battery management systems.
- Direct OEM Procurement Channels:Automotive tier-one bypass strategies are creating volume contracts that displace traditional distributor intermediaries in high-reliability segments.
Industry Challenges
- AEC-Q200 Qualification Timelines:Extended thermal cycling and humidity bias testing protocols are stretching product validation cycles to 18-24 months, freezing design wins for emerging platforms.
- Legacy System Integration Friction:Retrofitting MOV protection into existing industrial motor drives requires thermal and clearance recalculation that stalls upgrade decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Oxide Varistor (MOV) Market |
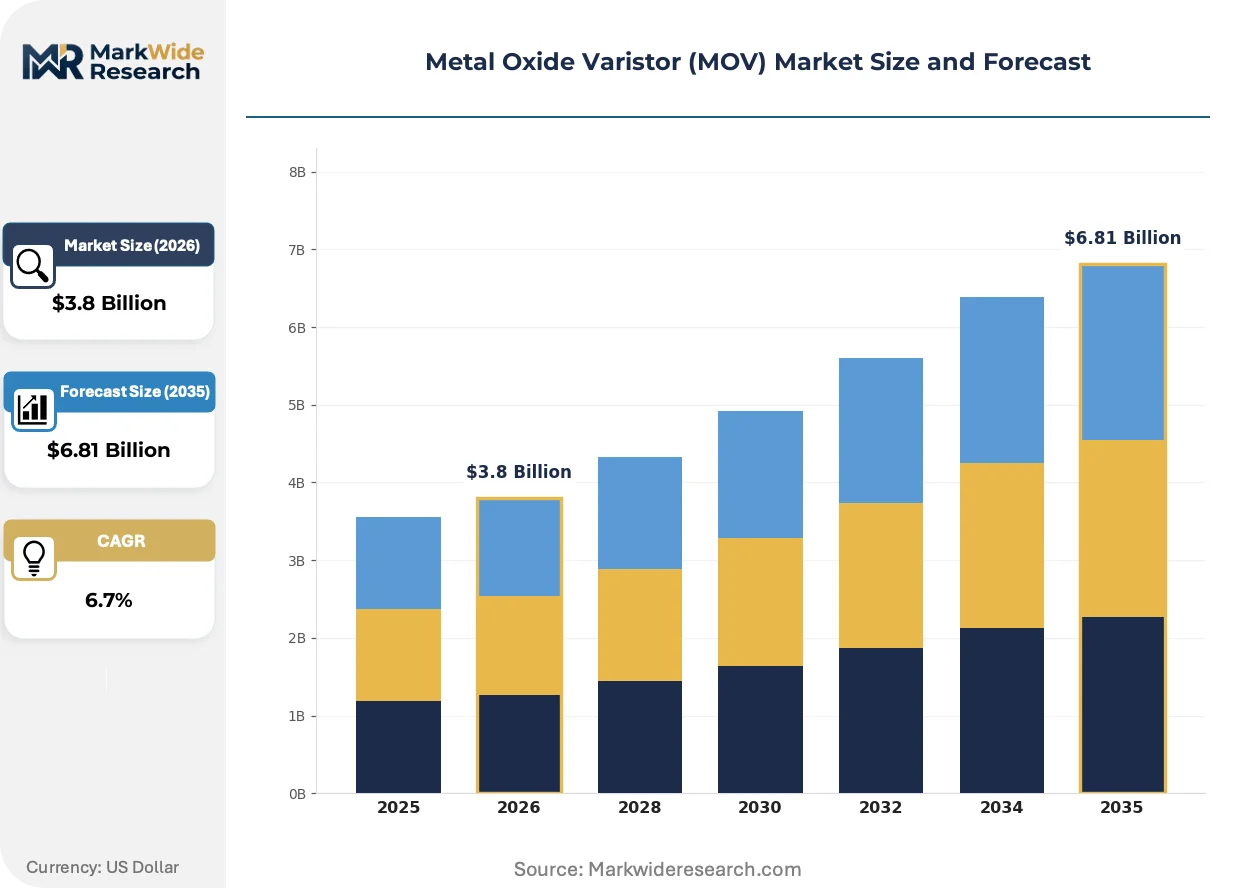
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radial, Axial, Disc, Surface Mount Application: Power Supplies, Consumer Electronics, Automotive, Industrial Equipment Voltage Rating: Low Voltage, Medium Voltage, High Voltage, Ultra High Voltage End User: Telecommunications, Renewable Energy, Electrical Appliances, Military |
| Companies Covered | TDK Corporation, Vishay Intertechnology, Panasonic Corporation, Littelfuse, Inc., Bourns, Inc., Eaton Corporation PLC, KYOCERA AVX, KEMET Corporation, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Oxide Varistor (MOV) Market Shifts & Advancements
Material science advances and qualification protocol evolution are redefining performance benchmarks across voltage classes, with sintering techniques and boundary-layer engineering commanding differentiated positioning.
Multilayer ceramic varistor technology is decomposing the traditional trade-off between energy absorption and response speed. EV powertrain engineers at tier-one suppliers are specifying these devices for 800V bus protection where nanosecond clamping prevents silicon carbide MOSFET avalanche failure. The structural consequence is compression of radial leaded disc margins in automotive applications above 400V.
REACH substance restrictions on bismuth oxide formulations are forcing reformulation of boundary-layer chemistries in European-sourced components. Industrial consequence includes qualification retesting costs and supply chain bifurcation between REACH-compliant and legacy formulations. High-voltage renewable energy projects in Germany and Scandinavia are absorbing premium pricing for certified materials to maintain installation timelines.
Consolidated procurement by automotive OEMs is compressing supplier bases and demanding bonded inventory programs with 52-week horizon commitments. Tier-one power module manufacturers are displacing fragmented distributor networks with direct vendor-managed inventory agreements. This concentration is most visible in China, where BYD and CATL procurement desks are qualifying single-source MOV suppliers for 10-year platform life cycles.
Metal Oxide Varistor (MOV) Market Segmentation
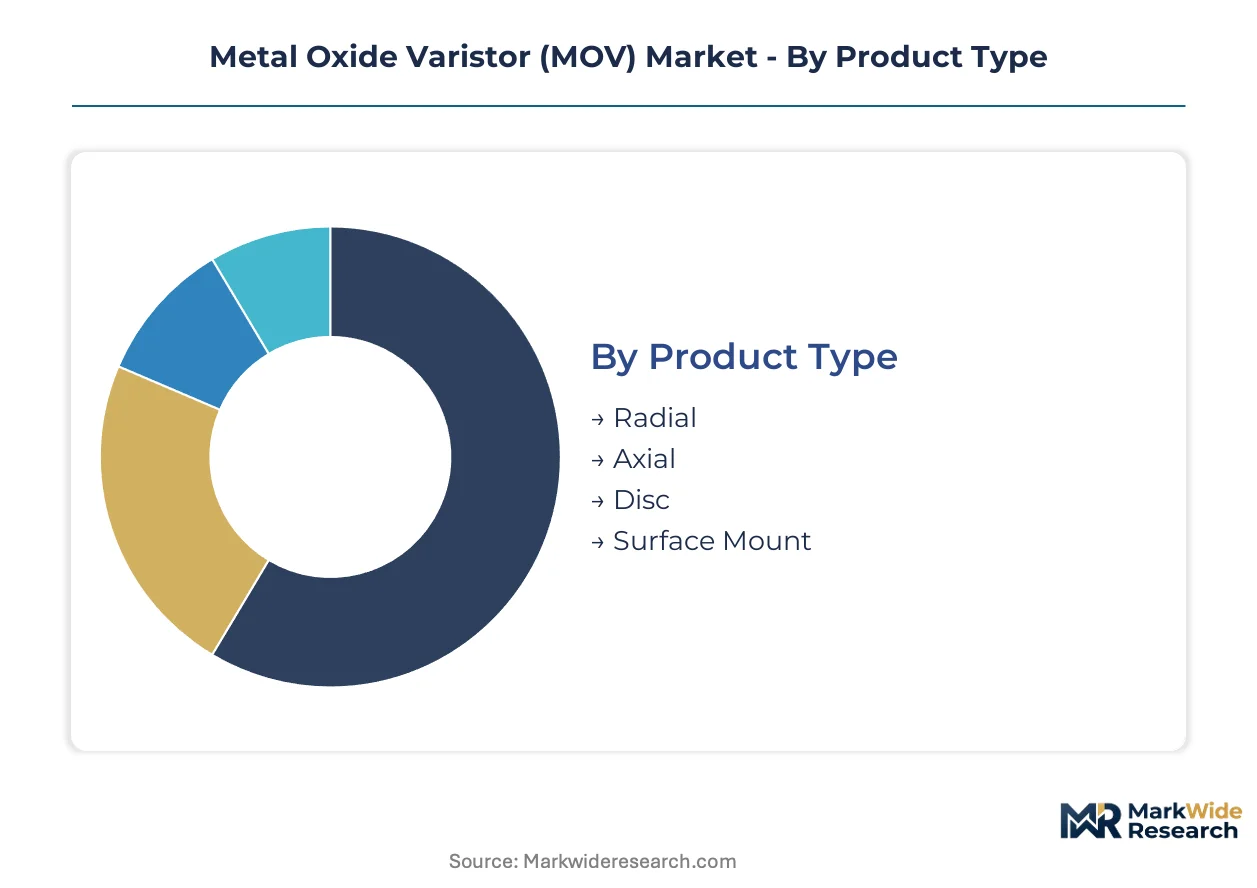
MOV segmentation reveals divergent qualification burdens across voltage classes and mounting formats. Product architecture choices directly determine which certification regimes—AEC-Q200, IEC 61000-4-5, UL 1449—dominate procurement decisions and margin capture.
Product Type:
Regulatory differentiation separates radial and axial formats bound by UL 1449 safety listings from automotive-qualified surface-mount variants. Disc types face the most stringent energy absorption testing under GB/T 18802 for Chinese grid infrastructure.
- Disc:Sintered zinc oxide ceramic construction delivers the highest energy absorption density among standard formats. Utility-scale solar installations in China and offshore wind projects along Germany's North Sea coast are driving bulk procurement of 40mm and 60mm diameter variants. SAMR certification timelines for GB/T 18802 compliance now exceed 14 months.
- Surface Mount:Multilayer ceramic construction achieves nanosecond response times critical for silicon carbide gate driver protection. Tier-one EV power module suppliers specify these for 800V battery bus architectures where PCB density constraints rule out leaded alternatives. AEC-Q200 thermal cycling requirements now mandate 1000-hour qualification runs.
- Radial:Through-hole leaded construction dominates legacy industrial motor drives and appliance surge protection. IEC 61000-4-5 surge immunity testing remains the primary qualification threshold.
- Axial:Cylindrical leaded format occupies intermediate energy handling between radial and disc types. Telecom base station power distribution units represent the anchor demand segment.
Disc handles the majority of throughput; surface mount is the fastest mover on share.
Application:
Cost tier stratification places automotive protection modules at premium pricing multiples above commodity appliance applications. Industrial equipment demands intermediate reliability grades with extended temperature specifications.
- Automotive:Onboard chargers, DC-DC converters, and traction inverters require AEC-Q200 certification plus 150°C continuous operation ratings. 800V platform proliferation is compressing design-in windows to 12-month cycles.
- Power Supplies:Server rack and datacenter uninterruptible power systems specify UL 1449 listed components with 20kA surge current ratings. Hyperscale procurement desks in Virginia and Frankfurt are consolidating supplier bases.
- Consumer Electronics:Compact surge protectors and USB charging adapters prioritize surface-mount formats. TVS diode substitution is eroding MOV share in sub-100J protection slots.
- Industrial Equipment:Variable frequency drives and motor control centers demand 85°C ambient operation with 20-year service life guarantees. Retrofit installation friction stalls upgrade decisions.
Automotive commands the steepest pricing tier; industrial equipment shows the most volume expansion.
Voltage Rating:
Volume concentration in low-voltage ratings masks the technology shift toward ultra-high-voltage segments where energy density specifications are tightening fastest.
- Low Voltage:5V to 60V ratings dominate power supply and consumer electronics protection. IEC 61000-4-5 Class 2 surge immunity remains the baseline qualification.
- High Voltage:300V to 1000V ratings anchor renewable energy inverter protection. Offshore wind installations in the North Sea and utility-scale solar in China's Gobi Desert are deepening procurement.
- Medium Voltage:100V to 300V ratings serve industrial automation and telecom infrastructure. Margin pressure from TVS diode competition is intensifying.
- Ultra High Voltage:Above 1000V ratings for grid-scale transmission protection face physical energy absorption limits in single-device configurations. Multi-disc series architectures are emerging.
Low voltage handles the majority of throughput; ultra high voltage is expanding most quickly.
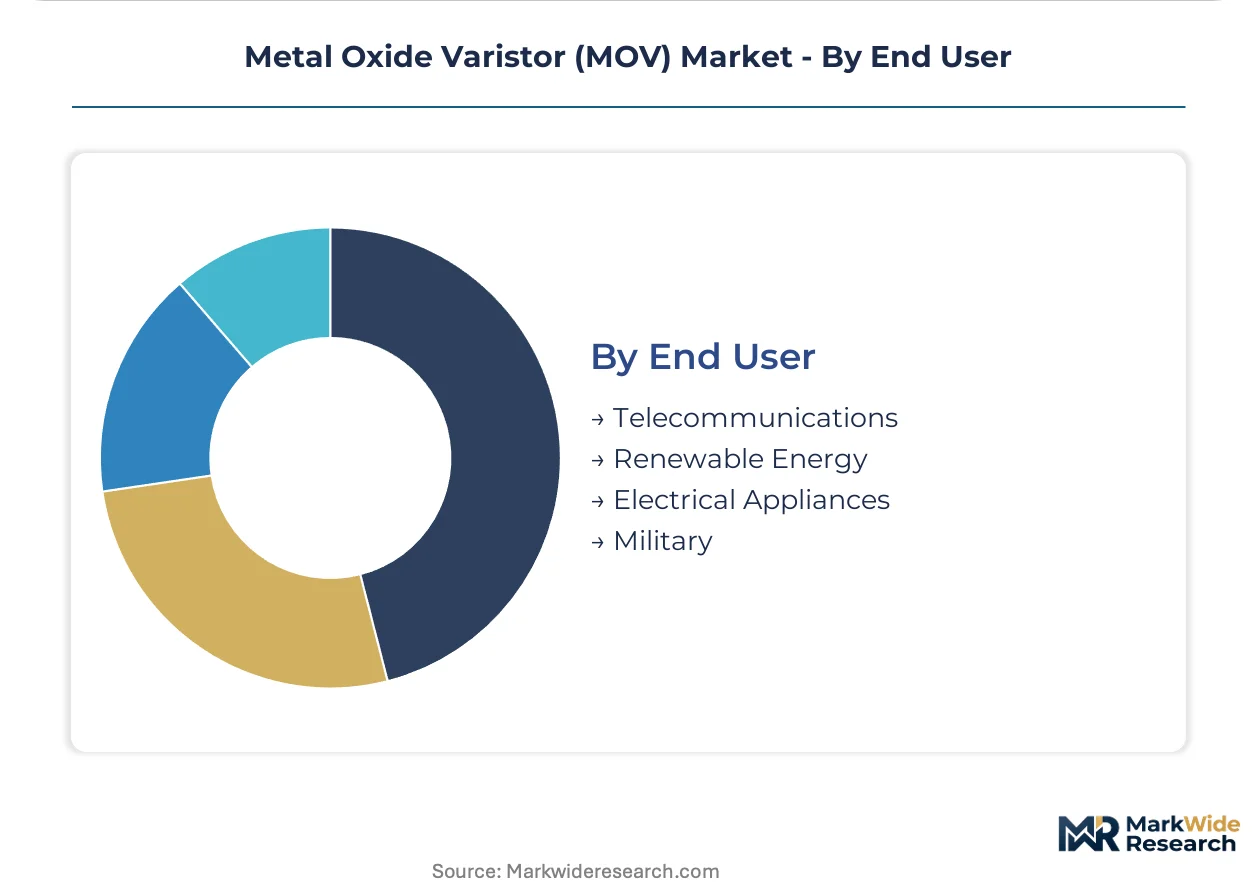
End User:
Customer type determines procurement channel structure, with renewable energy developers demanding direct vendor relationships while electrical appliance manufacturers route through distributor networks.
- Renewable Energy:Utility-scale solar and wind developers specify 40kA surge current ratings with 25-year service life guarantees. GB/T 18802 certification is mandatory for Chinese project financing.
- Telecommunications:5G base station power distribution requires compact axial formats with -40°C cold start capability. India's BSNL and Bharti Airtel procurement desks are qualifying domestic suppliers.
- Electrical Appliances:White goods manufacturers specify radial MOVs for surge protection modules. REACH substance restrictions on bismuth oxide are forcing European supply chain bifurcation.
- Military:MIL-STD-202 qualification requirements for shock and vibration resistance create captive supply relationships. US defense primes maintain approved vendor lists with 10-year platform commitments.
Renewable energy handles the majority of throughput; telecommunications is climbing the fastest on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Qinghai-Tibet ultra-high-voltage DC transmission corridor anchors China's dominance in grid-scale MOV procurement, channeling renewable output from western provinces to eastern load centers. This infrastructure backbone underwrites bulk demand for 60mm disc varistors rated above 1000V.
China
Utility-scale solar installations in the Gobi Desert and offshore wind clusters along Jiangsu province drive SAMR-certified GB/T 18802 procurement. BYD and CATL procurement desks in Shenzhen and Ningde are qualifying single-source MOV suppliers for decade-long platform commitments. Yangtze River Delta manufacturing hubs in Suzhou and Wuxi concentrate sintering capacity for automotive-grade surface-mount variants.
Germany
North Sea offshore wind interconnectors and Bavarian solar farms demand REACH-compliant bismuth oxide formulations. ECHA substance restrictions are forcing supply chain bifurcation between legacy and reformulated boundary-layer chemistries. Industrial clusters in Baden-Württemberg around Stuttgart host tier-one automotive suppliers specifying AEC-Q200 components for 800V traction inverters.
United States
Texas ERCOT grid hardening and California solar-plus-storage deployments require UL 1449 listed components with 25-year service guarantees. NHTSA safety mandates for EV onboard chargers are compressing qualification timelines to 12-month design-in cycles. Southeast manufacturing corridors in Tennessee and South Carolina are attracting MOV module assembly for Detroit Three automotive programs.
India
BIS certification mandates and PLI scheme incentives for electronics components are opening captive supply opportunities. Tamil Nadu and Karnataka automotive belts near Chennai and Bengaluru are qualifying domestic MOV sources for two-wheeler and passenger EV platforms. Telecom infrastructure rollout by BSNL and Bharti Airtel is driving axial format demand for 5G base station power distribution.
Japan
Silicon carbide traction inverter adoption by Tokyo-based automotive OEMs is demanding nanosecond-clamping MOV architectures. METI energy efficiency standards for industrial motor drives are triggering retrofit protection upgrades. Kyushu semiconductor foundries and Nagoya automotive supplier networks are co-developing multilayer ceramic varistor specifications for next-generation power modules.
Metal Oxide Varistor (MOV) Market Competitive Landscape
Concentration sits with diversified passive component conglomerates and specialized surge protection fabricators. Japanese and European electronics groups anchor high-reliability supply for automotive and industrial segments, while North American distributors maintain broad radial and axial portfolios. Three archetypes dominate: ceramics-focused material science specialists, integrated circuit protection platform vendors, and contract manufacturers serving cost-optimized appliance tiers. Competitive dynamics center on AEC-Q200 qualification speed and bonded inventory programs with 52-week horizon commitments.
Among Japan-based electronics conglomerates, TDK Corporation and Panasonic Corporation occupy positions exemplifying ceramics-to-systems vertical integration. Vishay Intertechnology represents the diversified passive component archetype with broad format coverage. These three anchors illustrate how qualification protocol mastery and automotive direct procurement channel access are separating margin capture tiers in surge protection component supply.
| Leading Market Players |
|---|
| TDK Corporation |
| Vishay Intertechnology |
| Panasonic Corporation |
| Littelfuse, Inc. |
| Bourns, Inc. |
| Eaton Corporation PLC |
| KYOCERA AVX |
| KEMET Corporation |
| ABB |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts with 52-week bonded inventory commitments lock in supply access for automotive OEMs while anchoring price visibility against zinc oxide commodity swings. Chinese sintering capacity concentration and SAMR certification timelines force tier-one suppliers to pre-position disc varistor stockpiles before GB/T 18802 qualification gates.
Pricing Analysis
Volume-discount tiering separates AEC-Q200 automotive-qualified surface-mount devices from commodity radial formats serving appliance manufacturers. Three-tier pricing structure across premium, standard, and economy levels tracks certification burden, with automotive protection modules commanding multiples above industrial grades. Cost compression in consumer electronics radial segments is intensifying because TVS diode substitution erodes MOV share below 100J protection thresholds. Appliance OEMs exhibit highest price sensitivity, while renewable energy developers absorb premium pricing for 25-year service life guarantees.
Supply Chain Analysis
Strategic stockpile preferences dominate automotive and renewable energy procurement desks, with tier-one suppliers maintaining 6-month zinc oxide ceramic powder reserves. Sintering capacity concentrates in China, Japan, and Germany, with Yangtze River Delta hubs feeding automotive-grade surface-mount production. Raw material supply draws from Chinese zinc smelting operations, Japanese bismuth oxide refiners, and German cobalt oxide processors. Single-source vulnerability intensifies as BYD and CATL procurement desks qualify sole-supplier relationships for decade-long platform commitments. Distribution runs through direct vendor-managed inventory agreements displacing fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified AEC-Q200 sintering capacity sits scarce relative to 800V platform proliferation, compressing design-in windows and freezing margin capture for suppliers lacking thermal cycling protocol mastery.
For Market Incumbents: Compound certification speed advantages by expanding Suzhou and Stuttgart surface-mount capacity ahead of silicon carbide inverter ramp schedules. Deepen backward integration into zinc oxide ceramic powder processing to defend margin structures against Chinese smelter export quota volatility. Lock 10-year bonded inventory programs with CATL and BYD procurement desks before secondary suppliers clear GB/T 18802 timelines. For New Entrants and Emerging Players: Lead with BIS-certified disc varistor production in Tamil Nadu automotive corridors, exploiting PLI scheme incentives and captive two-wheeler EV demand. Target India's 5G base station power distribution segment where BSNL and Bharti Airtel procurement desks seek domestic axial format alternatives. Secure SAMR fast-track partnerships with Yangtze River Delta contract manufacturers to bypass 14-month GB/T 18802 qualification bottlenecks. For Investors and Strategic Acquirers: Ceramic-to-systems specialists with AEC-Q200 protocol mastery and automotive direct channel access represent the priority acquisition archetype. Long-term viability hinges on positioning before wide-bandgap semiconductor adoption redefines clamp energy specifications. Watch silicon carbide MOSFET avalanche failure rates as the signal indicating MOV redundancy architecture shifts.| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q200 Certification Acceleration | Shrinks 18-24 month thermal cycling timelines to capture 800V platform design-ins at tier-one suppliers. |
| Backward Integration into Zinc Oxide | Captures smelter margin and insulates against Chinese export quota volatility affecting disc production. |
| Direct OEM Procurement Channel Development | Bypasses distributor intermediaries to secure 52-week bonded inventory commitments with automotive procurement desks. |
| Multilayer Ceramic Varistor Scale-Up | Addresses nanosecond-clamping demand from silicon carbide gate driver protection in 800V EV architectures. |
| REACH-Compliant Boundary Layer Reformulation | Maintains European renewable energy project access as ECHA restrictions force bismuth oxide chemistry shifts. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with tier-one automotive procurement managers, EV powertrain engineers, and renewable energy EPC contractors; and secondary validation against IEC 61000-4-5 surge immunity test reports, SAMR GB/T 18802 certification databases, and AEC-Q200 qualification filings. Bottom-up segment sizing triangulated against top-down macro indicators including EV platform production schedules and utility-scale solar installation permits.
Across the analysis window, forecasting employed discrete modeling by voltage rating, mounting format, and end-user application, with automotive electrification penetration curves and silicon carbide adoption rates as key demand drivers. CAGRs derived from segment-level volume trajectories weighted by pricing tier concentration. Modeled outputs incorporate raw material cost pass-through assumptions and certification timeline compression scenarios.
The analysis sits within stated boundaries; outcomes outside sustained 800V platform proliferation or accelerated wide-bandgap semiconductor deployment would require recalibration. Forecasts reflect documented assumptions regarding zinc oxide supply stability and automotive qualification protocol evolution. Revision becomes warranted when TVS diode substitution thresholds cross below 100J protection slots or when REACH substance restrictions expand beyond bismuth oxide formulations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Pulse Width Modulation Controllers Market
Electronic Components
Tower Mounted Amplifier Market
Electronic Components
Aluminum Electrolytic Capacitor Market
Electronic Components
Primary Charge Roller Market
Electronic Components
Motherboard Battery Market
Electronic Components
Digital Potentiometer Market
Electronic Components
SAW Filters Market
Electronic Components
Laser Direct Structuring (LDS) Antenna Market
Electronic Components
Digital Isolator Market
Electronic Components
Battery Shunt Resistor Market
Electronic Components
Display Port Adapters Market
Electronic Components
High Precision Mechanical Machine Components Market
Electronic Components
Data Acquisition Hardware Market
Electronic Components
Audio Capacitor Market
Electronic Components
Motherboard Market
Electronic Components
Coin Battery Holder Market