
 Europe Water Cooled Capacitors Market | 2026-2036
Europe Water Cooled Capacitors Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Water Cooled Capacitors Market Analytics
Modular capacitor rack configurations is shifting buyer preference across European power infrastructure procurement. ZEZ SILKO Ltd. leverages its Czech manufacturing base to compete on delivery speed for customized cooling manifolds. Vishay Intertechnology Inc. anchors its position through film dielectric expertise that extends into water-cooled variants for traction converters. Celem Power Capacitors specializes in mica-based assemblies that sustain thermal cycling in induction heating installations.
Water cooled capacitors employ dielectric films or mica paper impregnated with insulating oil, housed in aluminum casings with integrated cooling channels that maintain operating temperatures below thermal runaway thresholds. These components manage reactive power compensation and harmonic filtering in megawatt-scale converter systems where air cooling proves insufficient. AC Capacitors dominate installed base volumes across European steel mills and rolling stock depots, while Pulse Capacitors capture margin pools in medical imaging and laser applications demanding microsecond discharge precision. Film Capacitors compete aggressively in renewable energy inverter strings where manufacturers prioritize energy density and predictable failure modes.
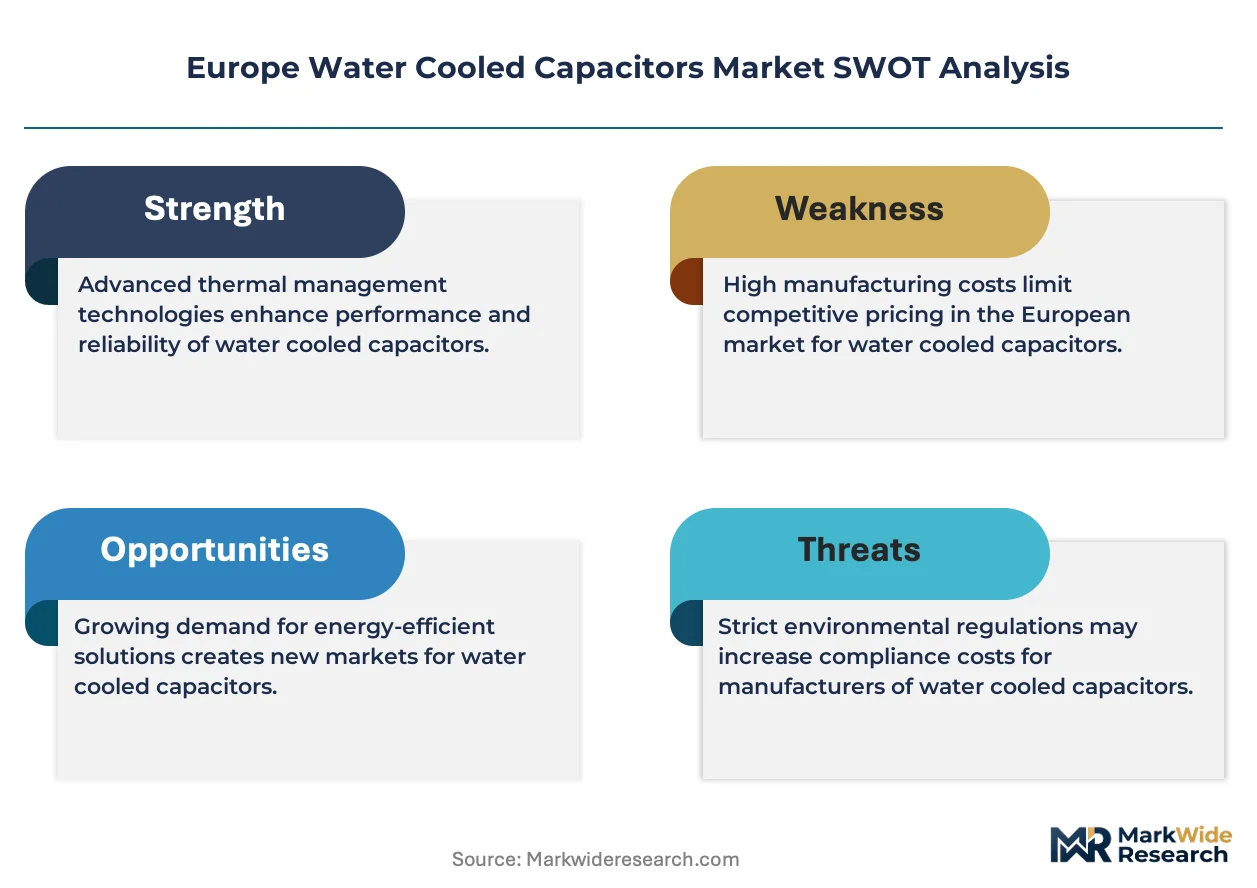
CE marking under the EU's Low Voltage Directive and ECHA REACH compliance on insulating oil formulations constrain material choices and supplier qualification timelines. Germany's KBA and France's ANSM enforce equipment safety standards that ripple through capacitor specifications for rail traction and medical equipment respectively. Buyers must monitor evolving F-Gas Regulation thresholds that could restrict certain synthetic coolants, forcing earlier-than-planned thermal management redesigns.
Market Dynamics
The EU Green Deal's electrification mandates are compressing replacement cycles for air-cooled capacitor systems across European heavy industry, forcing liquid-cooled retrofits at steel mills and automotive plants before natural end-of-life.
Growth Catalysts
- Grid Stabilization Mandates:Power generation utilities in Germany and France are expanding procurement of water cooled capacitor banks to manage reactive power compensation in megawatt-scale converter systems. This demand concentrates in the Rhine-Ruhr industrial corridor where aging infrastructure requires thermal management upgrades.
- F-Gas Regulation Thresholds:The EU's tightening restrictions on synthetic coolants are accelerating thermal management redesigns, pushing manufacturers toward water-cooled alternatives with integrated aluminum cooling channels that eliminate fluorinated gas dependencies.
- Induction Heating Expansion:European steel producers are retrofitting rolling mills with mica-based capacitor assemblies capable of sustaining thermal cycling, driven by energy efficiency targets in the EU Steel Action Plan.
Market Restraints
- Aluminum Casing Supply Concentration:Specialized extruded aluminum housing production clusters in Central European foundries, creating vulnerability to energy price shocks and capacity constraints for integrated cooling channel fabrication.
- REACH Compliance Friction:ECHA's evolving restrictions on insulating oil formulations extend supplier qualification timelines by 12-18 months, freezing material choices and delaying product certifications for dielectric film impregnation processes.
- Air-Cooled System Persistence:Lower upfront capital requirements and established maintenance protocols for conventional air-cooled capacitors continue to dominate procurement in smaller industrial facilities and non-critical power conditioning applications.
Strategic Opportunities
- Medical Imaging Pulse Capacitors:Microsecond discharge precision requirements in MRI and laser systems represent an underpenetrated margin pool, with ANSM safety standards creating qualified supplier moats for mica-paper assemblies.
- Renewable Energy Inverter Integration:Film capacitor manufacturers are converging water-cooled thermal management with high energy density designs for offshore wind converter strings in the North Sea and Baltic installations.
- Modular Rack Standardization:Buyer preference is shifting toward configurable capacitor bank architectures that reduce field installation complexity, creating channel opportunities for system integrators serving distributed industrial power conditioning.
Industry Challenges
- Dielectric Film Thermal Engineering Talent:Specialized expertise in oil-impregnated polypropylene film behavior under liquid cooling regimes remains scarce across European capacitor engineering pools, constraining product development velocity.
- CE Marking Documentation Burden:The EU Low Voltage Directive's technical file requirements and Notified Body engagement timelines create 6-9 month certification gaps that mismatch with compressed utility procurement schedules.
- Legacy System Integration Complexity:Retrofitting water-cooled capacitor banks into existing air-cooled infrastructure requires custom cooling manifold fabrication and control system recalibration, extending project timelines and technical risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Water Cooled Capacitors Market |
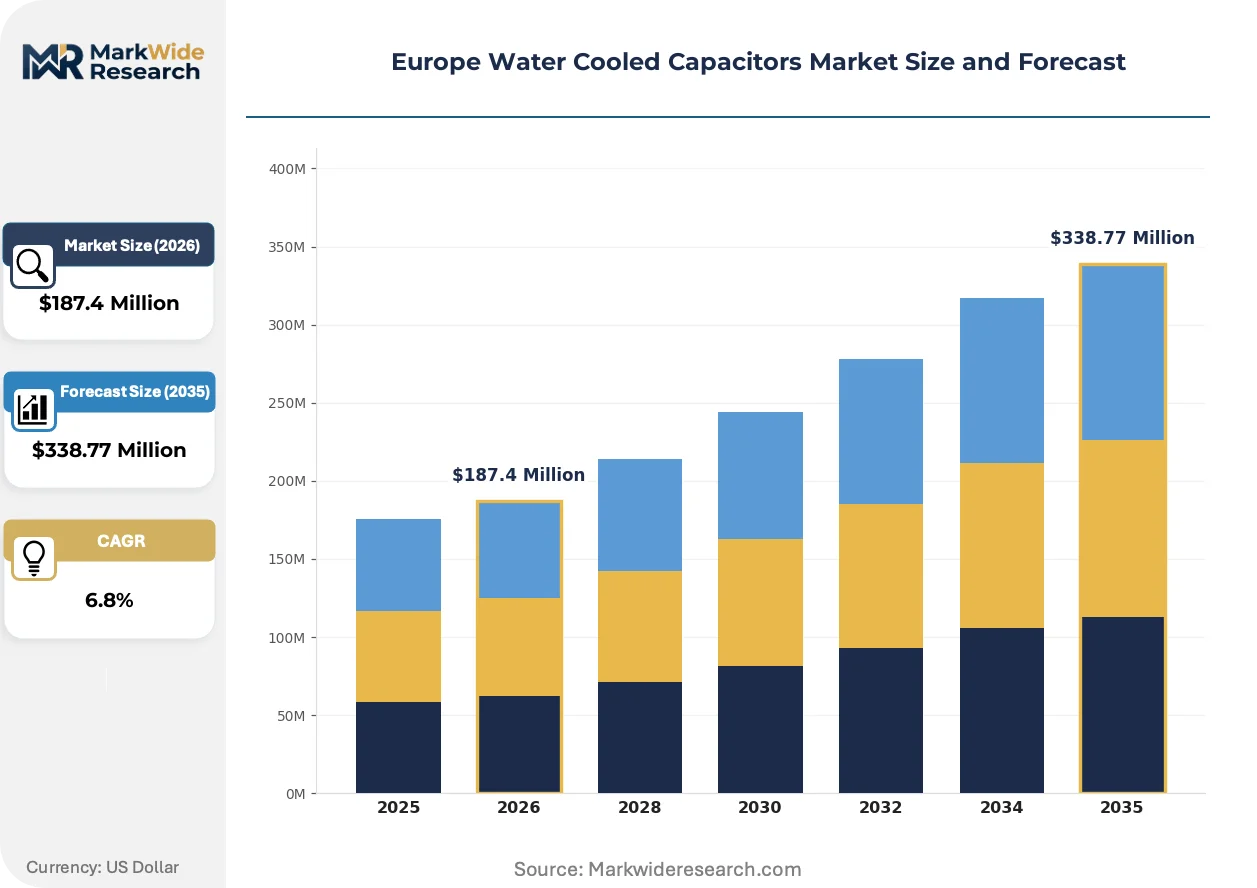
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Capacitors, DC Capacitors, Pulse Capacitors, Film Capacitors Installation: Outdoor, Indoor, Centralized, Distributed End User: Telecommunications, Manufacturing, Power Generation, Renewable Energy Capacity: Low Voltage, Medium Voltage, High Voltage, Ultra High Voltage |
| Companies Covered | ZEZ SILKO Ltd., Celem Power Capacitors, Cornell Dubilier Electronics, Vishay Intertechnology Inc., Clariant Power System Ltd., GE Grid Solutions, High Energy Corp., MAGNEWIN ENERGY PVT.LTD., SAILING TECH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Water Cooled Capacitors Market Evolving Landscape
Dielectric material science and thermal interface engineering are converging to redefine performance benchmarks for liquid-cooled power conditioning components across European heavy industry applications.
Polypropylene film dielectrics with nanocomposite surface treatments are rewriting thermal endurance expectations in water-cooled capacitor designs. Steel mills in Germany's industrial corridor are adopting these formulations at accelerated replacement cycles to meet EU Green Deal efficiency targets. The technology is compressing the performance gap between oil-impregnated film and traditional mica-paper assemblies in high-frequency inverter applications.
REACH restrictions on perfluorinated compounds are forcing insulating oil reformulation across European manufacturing. The regulation's industrial consequence is a supply chain scramble for bio-based and synthetic ester alternatives that maintain dielectric strength under thermal cycling. Medical equipment manufacturers serving the French market face the most acute compliance pressure, with ANSM safety standards layering additional qualification requirements on capacitor assemblies for imaging systems.
Buyer preference is consolidating around integrated thermal-electric subsystems rather than discrete component procurement. European rail traction OEMs are displacing traditional capacitor-only vendors with suppliers offering complete liquid cooling loops and control electronics. This pattern is most visible in rolling stock depots across Germany and Austria, where KBA safety certifications now favor vertically integrated subsystem providers over standalone capacitor specialists.
Europe Water Cooled Capacitors Market Segmentation
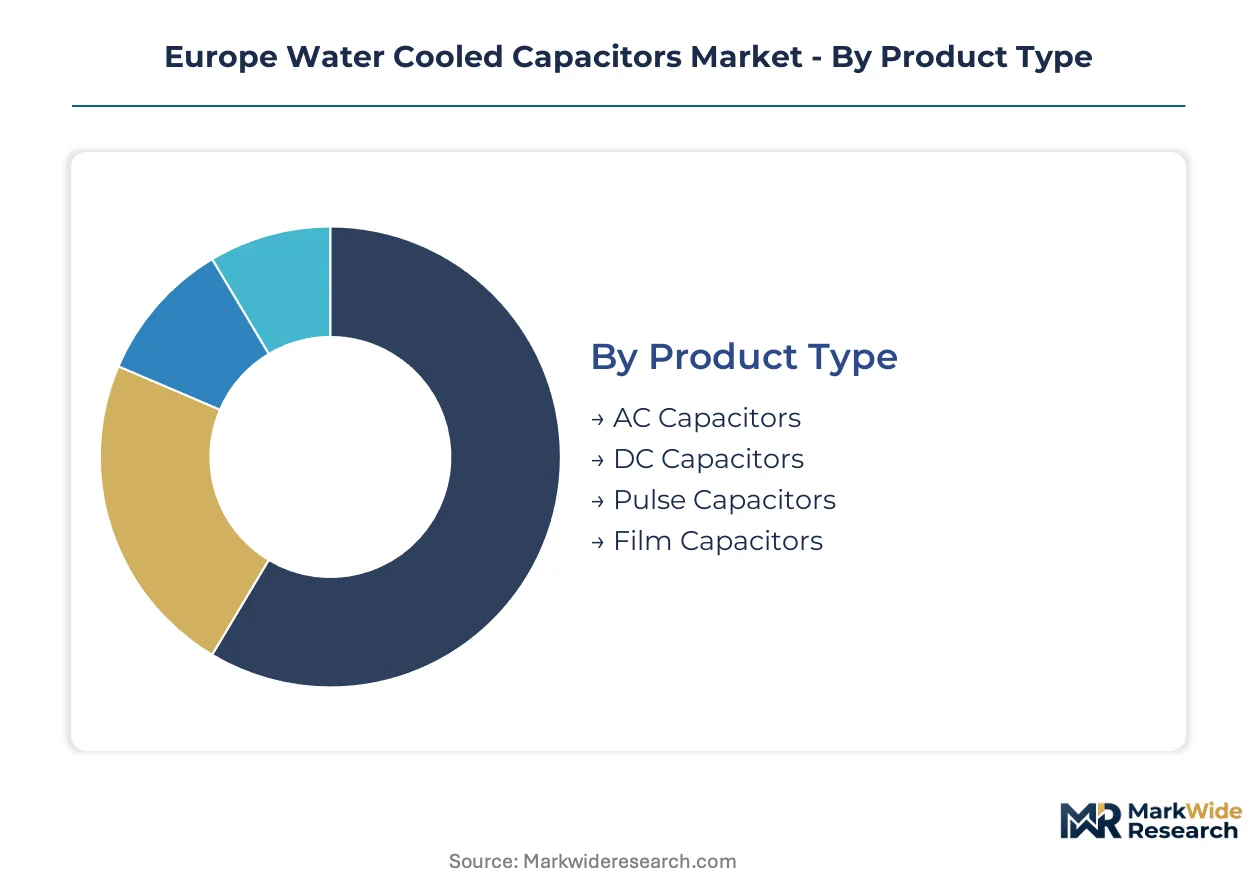
Water cooled capacitors serve heterogeneous thermal management requirements across European heavy industry, from megawatt-scale grid stabilization to precision medical discharge systems. Segmentation reveals how dielectric material choices and cooling architectures align with specific voltage regimes and installation constraints.
Product Type:
Standardized film dielectric platforms compete against application-specific mica-paper assemblies across this category, with customization depth varying by thermal cycling intensity and discharge precision requirements.
- AC Capacitors:Oil-impregnated polypropylene film dielectrics housed in aluminum casings with integrated cooling channels. Demand concentrates in Germany's steel mills and rolling stock depots, where reactive power compensation requirements under EU Green Deal electrification mandates are forcing thermal management upgrades ahead of natural replacement cycles.
- Film Capacitors:High energy density designs with predictable failure modes prioritized by renewable energy inverter manufacturers. These components are capturing share fastest in offshore wind converter strings across North Sea and Baltic installations, where energy density and thermal stability outweigh upfront cost considerations.
- DC Capacitors:Electrolytic and film-based assemblies for DC-link applications in traction converters and industrial drives.
- Pulse Capacitors:Mica-paper dielectrics engineered for microsecond discharge precision in medical imaging and laser systems.
Leading the category by volume: AC Capacitors. Expanding most quickly: Film Capacitors.
Installation:
Site constraints and cooling infrastructure availability determine whether capacitor banks deploy as integrated subsystems or discrete field-assembled units.
- Centralized:Rack-mounted configurations with shared cooling manifolds and control electronics. European rail traction OEMs in Germany and Austria are consolidating procurement around these integrated thermal-electric subsystems, with KBA safety certifications now favoring vertically integrated providers over standalone component vendors.
- Distributed:Modular architectures reducing field installation complexity for industrial power conditioning retrofits. Steel producers across the Rhine-Ruhr corridor are adopting these configurations to minimize downtime during air-to-liquid cooling conversions mandated by compressed replacement cycles.
- Indoor:Climate-controlled environments with managed coolant quality and filtration systems.
- Outdoor:Hardened enclosures with weatherproof sealing and extended temperature range specifications for substation and renewable generation sites.
Highest deployment share: Centralized installations in rail and heavy industry. Fastest adoption trajectory: Distributed architectures for retrofit applications.
End User:
Regulatory pressure intensity and capital equipment refresh cycles create divergent procurement timelines across vertical applications.
- Power Generation:Grid stabilization capacitor banks for reactive power compensation in megawatt-scale converter systems. Utilities in Germany and France are expanding procurement most aggressively, driven by transmission system operator requirements for inertia provision and voltage support.
- Renewable Energy:Inverter-integrated capacitor strings for offshore wind and utility-scale solar. North Sea and Baltic developers are prioritizing film capacitor technologies with water-cooled thermal management to maximize energy density within platform weight constraints.
- Manufacturing:Induction heating and power conditioning for steel, automotive, and industrial process applications.
- Telecommunications:Backup power and harmonic filtering for data center and network infrastructure.
Dominant demand source: Power Generation. Steepest expansion trajectory: Renewable Energy.
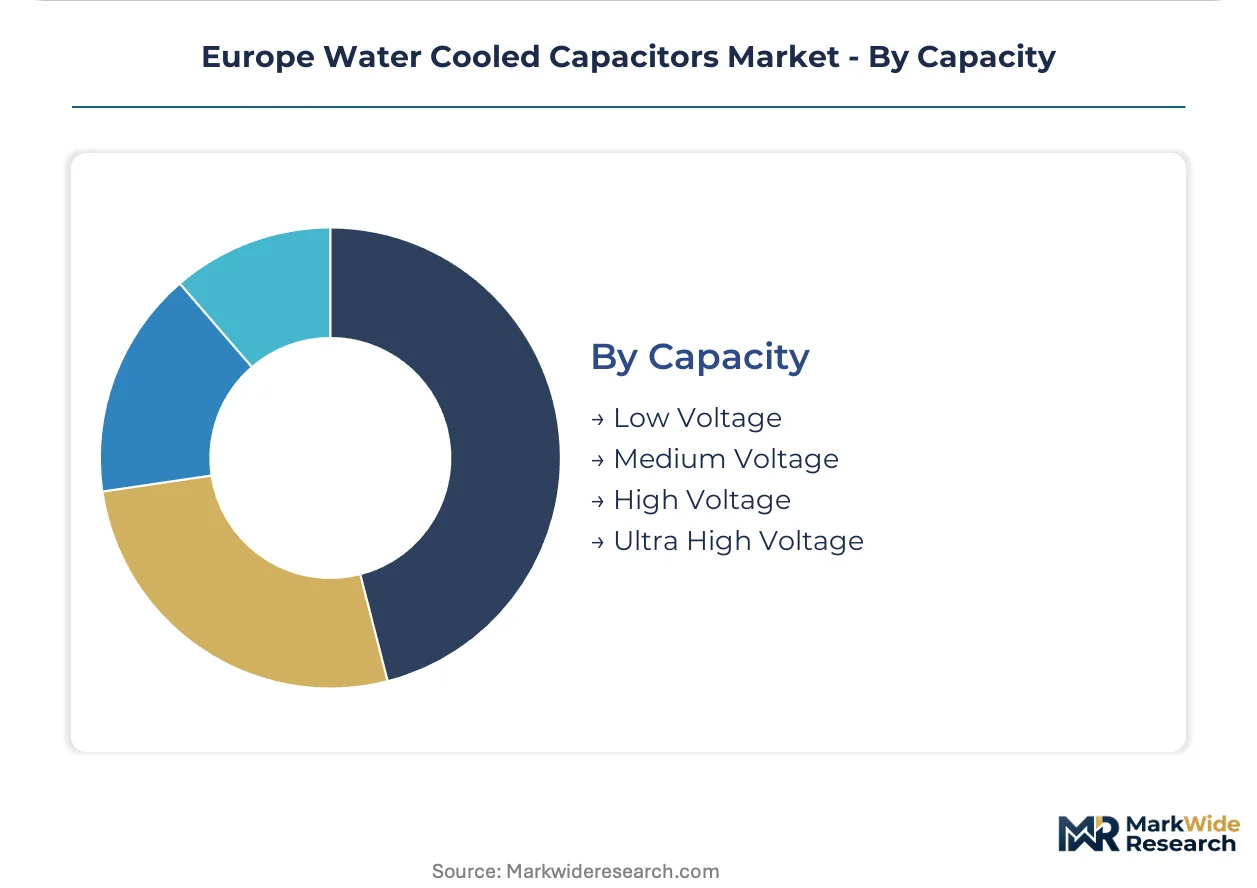
Capacity:
Voltage tier selection correlates directly with cooling system complexity and dielectric material sophistication requirements.
- Medium Voltage:Systems operating between 1kV and 52kV serving industrial drives and distribution networks. This tier captures the largest installed base across European steel mills and automotive plants, where F-Gas Regulation thresholds are accelerating water-cooled retrofits of previously air-cooled infrastructure.
- High Voltage:Transmission-grade capacitor banks above 52kV for grid stabilization and reactive compensation. German and French utilities are concentrating procurement here, with CE marking under the EU Low Voltage Directive and specialized Notified Body engagement extending qualification timelines.
- Low Voltage:Sub-1kV applications in smaller industrial facilities and commercial power conditioning.
- Ultra High Voltage:Specialized assemblies for research facilities and extreme grid interconnection projects.
Widest deployment: Medium Voltage systems. Gaining share fastest: High Voltage configurations for transmission infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration for water cooled capacitors clusters in Central European foundries, while demand spreads across industrial corridors from the Rhine-Ruhr to the French automotive belt. This production-consumption divide shapes procurement lead times and cooling manifold customization capabilities.
Germany
Grid stabilization mandates from transmission system operators are expanding procurement of megawatt-scale capacitor banks across the Rhine-Ruhr industrial corridor. KBA safety certifications for rail traction equipment favor vertically integrated thermal-electric subsystem providers over standalone component vendors. Steel mills in North Rhine-Westphalia are retrofitting induction heating infrastructure with mica-based assemblies to meet EU Steel Action Plan efficiency targets.
France
Power generation utilities are accelerating reactive power compensation deployments to manage voltage support requirements in the national transmission network. ANSM safety standards for medical imaging equipment create qualified supplier moats for capacitor assemblies serving MRI and laser system manufacturers. The Auvergne-Rhône-Alpes industrial cluster hosts concentrated demand from automotive plants undergoing electrification retrofits.
Italy
Steel producers in Lombardy and Piedmont are replacing air-cooled systems with liquid-cooled alternatives ahead of compressed replacement cycles driven by EU Green Deal mandates. CE marking under the EU Low Voltage Directive extends qualification timelines for medium-voltage industrial drive applications. The Emilia-Romagna manufacturing belt exhibits growing procurement of modular capacitor rack configurations for distributed power conditioning.
United Kingdom
Offshore wind developers in the North Sea are prioritizing film capacitor technologies with integrated water-cooled thermal management for converter platform weight constraints. The Midlands industrial corridor shows accelerating demand from automotive battery manufacturing facilities requiring harmonic filtering infrastructure. REACH compliance on insulating oil formulations is freezing material choices for dielectric film impregnation processes across British manufacturing.
Spain
Renewable energy inverter integration is driving procurement of high energy density capacitor strings for utility-scale solar installations in Andalusia and Extremadura. The Basque Country maintains specialized demand from machine tool manufacturers requiring precision power conditioning for induction heating applications. F-Gas Regulation thresholds are accelerating thermal management redesigns away from synthetic coolants toward aluminum-cooled water systems.
Europe Water Cooled Capacitors Market Competitive Landscape
The competitive structure tilts toward specialized dielectric material experts and integrated thermal subsystem providers rather than generalist component fabricators. European capacitor engineering pools remain scarce in specialized expertise for oil-impregnated polypropylene film behavior under liquid cooling regimes, constraining product development velocity for new entrants. Three archetypes dominate: vertically integrated rail traction specialists, film dielectric technology anchors, and regional fabrication houses competing on delivery speed for customized cooling manifolds. Competitive moves concentrate on strategic partnerships for thermal interface engineering and geographic expansion into Baltic offshore wind installation corridors.
Among Czech-based fabricators, ZEZ SILKO Ltd. occupies a position emphasizing delivery speed for customized cooling manifold configurations. Vishay Intertechnology Inc. represents the film dielectric technology anchor archetype, with expertise extending into water-cooled variants. Celem Power Capacitors exemplifies the specialized mica-assembly segment, serving thermal cycling requirements in industrial heating installations. These three anchors illustrate how material science specialization and geographic proximity to Central European foundries determine competitive positioning in procurement decisions.
| Leading Market Players |
|---|
| ZEZ SILKO Ltd. |
| Celem Power Capacitors |
| Cornell Dubilier Electronics |
| Vishay Intertechnology Inc. |
| Clariant Power System Ltd. |
| GE Grid Solutions |
| High Energy Corp. |
| MAGNEWIN ENERGY PVT.LTD. |
| SAILING TECH |
| Others |
Value Network & Pricing Analysis
Captive production of extruded aluminum housings with integrated cooling channels anchors supply positioning for tier-one suppliers serving German rail traction and French power generation utilities. This backward integration into thermal management hardware insulates incumbents from Central European foundry energy price volatility while preserving margin pools on customized manifold configurations.
Pricing Analysis
Margin tightening in standard-grade AC capacitor tiers reflects REACH compliance friction extending supplier qualification timelines by 12-18 months. Three-tier pricing structure across premium CE-certified, standard industrial-grade, and economy non-critical tiers separates buyers by certification burden and thermal cycling intensity. Cost-down pressure accelerates in renewable energy inverter segments as offshore wind developers prioritize energy density over upfront capital. Steel mills and automotive plants show lowest price sensitivity due to compressed replacement cycles under EU Green Deal mandates.
Supply Chain Analysis
Direct-to-OEM channels handle demand from German rail traction manufacturers and French power utilities requiring integrated thermal-electric subsystems. Manufacturing gravity centers on Czech Republic, Germany, and Austria for specialized aluminum extrusion and dielectric film impregnation. Raw material flows draw from polypropylene film suppliers in Belgium, insulating oil blenders in Netherlands, and mica paper sources in Spain. Single-source vulnerability concentrates in Central European foundries capable of precision cooling channel fabrication. Distribution runs through system integrators serving distributed industrial retrofits across the Rhine-Ruhr corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized dielectric engineering talent scarcity props pricing power for qualified suppliers, constraining new entrant velocity and extending incumbent margin durability.
For Market Incumbents: Cement market position through captive supply of customized cooling manifold fabrication and accelerated CE marking investment under EU Low Voltage Directive. Film dielectric expertise extension into water-cooled traction variants creates defensive moats against mica-assembly specialists. Capacity addition in Czech manufacturing corridors addresses delivery speed competition from regional fabricators. For New Entrants and Emerging Players: Nanocomposite surface treatment technology for polypropylene films offers entry into high-frequency inverter applications where thermal endurance gaps persist. Medical imaging pulse capacitor segments remain underpenetrated due to ANSM qualification barriers protecting established mica-paper suppliers. Partner with German rolling stock depots seeking modular rack standardization for field installation simplicity. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by vertically integrated rail traction OEMs seeking thermal-electric subsystem control. Long-term viability favors dielectric material specialists with REACH-compliant oil formulation capabilities and KBA certification track records. Monitor F-Gas Regulation threshold revisions as inflection signal for accelerated air-to-liquid cooling conversion timelines.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Oil Reformulation | ECHA restrictions on perfluorinated compounds force insulating oil alternatives maintaining dielectric strength under thermal cycling. |
| Modular Rack Standardization | Configurable capacitor bank architectures reduce field installation complexity for steel mill retrofit applications. |
| Integrated Thermal-Electric Subsystems | German KBA certifications now favor vertically integrated providers over standalone capacitor specialists. |
| Offshore Wind Converter Integration | North Sea developers prioritize film capacitor energy density within platform weight constraints. |
| CE Marking Acceleration | Notified Body engagement timelines create 6-9 month certification gaps mismatched with utility procurement schedules. |
Research Methodology
Document review covered EU regulatory filings, ECHA REACH substance restrictions, and transmission system operator procurement disclosures, complemented by interviews with capacitor engineering directors, power utility procurement leads, rail traction OEM platform engineers, and industrial plant maintenance managers. Secondary validation drew from KBA safety certification databases, CE marking technical files, and EU Steel Action Plan implementation reports. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Cross-referencing historical replacement cycle data with expert panel input on EU Green Deal compliance timelines shaped the projection framework. Segmentation dimensions modeled include product type, installation architecture, end-user vertical, and voltage capacity tier. CAGRs derived from elasticity analysis of regulatory mandate intensity against natural equipment refresh patterns. Industry-specific inputs incorporated F-Gas Regulation threshold trajectories and offshore wind installation pipeline disclosures.
Several conditions sit outside the modeled scope, including unannounced revisions to ECHA substance restrictions, abrupt aluminum alloy price shocks, and geopolitical disruptions to Central European foundry operations. Forecasts reflect documented assumptions on regulatory implementation pacing and technology substitution rates. Periodic stress-testing of base assumptions is recommended given compressed replacement cycle uncertainty and evolving CE marking documentation burdens.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Frequency Control and Timing Devices Market
Electronic Components
Power Resistor Market
Electronic Components
Audio DSP Market
Electronic Components
Structural Electronics Market
Electronic Components
Audio and Visual Public Address System Market
Electronic Components
Automation Component Market
Electronic Components
Global Circuit Protection Market
Electronic Components
Asia Pacific Safety Relays and Timers Market
Electronic Components
Circuit Protection Kits Market
Electronic Components
Switch Diode Market
Electronic Components
Crystal Oscillators Market
Electronic Components
Chip Ferrite Beads Market
Electronic Components
Microspeaker Market
Electronic Components
Audio Power Amplifier Market
Electronic Components
Asia-Pacific USB Retimer Market
Electronic Components
Metal Composite Power Inductor Market