
 Speaker Membranes Market | 2026-2036
Speaker Membranes Market Size, Share, and Industry Trends Forecast 2026-2036
Speaker Membranes Market Insights
Capital-intensity divergence between thin-film deposition specialists and conventional injection molders is unwinding competitive hierarchies in speaker membrane supply. Sony Corporation leverages captive materials science laboratories to sustain proprietary polymer formulations across consumer electronics verticals. Samsung Electronics anchors high-volume production through in-house diaphragm fabrication for smartphone and television speaker arrays. Bose Corporation differentiates through specialized acoustic engineering that commands premium positioning in professional monitoring applications.
Speaker membranes are thin, semi-rigid diaphragms typically engineered from polymers, paper composites, or aramid fibers, manufactured through calendering, thermoforming, or vapor-deposited coating processes to achieve precise mass and stiffness targets for controlled acoustic radiation. Polypropylene formulations dominate cost-sensitive consumer electronics due to moisture resistance and batch consistency, while Kevlar-reinforced variants capture margin pools in professional audio where rigidity-to-mass ratios determine transient response fidelity. Component and subwoofer designs represent the fastest-expanding product design categories as automotive OEMs specify multi-way systems for cabin acoustic zoning.
FCC equipment authorization requirements govern electromagnetic and acoustic device compliance in the United States, while REACH and RoHS frameworks in Europe restrict hazardous substances in polymer formulations and mandate recyclability disclosures for electronics components. Japan's METI energy efficiency guidelines indirectly shape membrane material selection through downstream product power-consumption targets. Stakeholders must monitor evolving chemical substance restrictions and automotive safety harmonization standards to preempt supply chain requalification costs.
Market Dynamics
Automotive cabin acoustic zoning requirements are compressing development cycles for multi-way speaker systems, forcing membrane suppliers to synchronize material qualification timelines with platform engineering gates. Tier-1 audio integrators now specify diaphragm stiffness tolerances at the concept phase rather than the component phase.
Growth Catalysts
- EU Green Deal material mandates:Bio-based polymer feedstocks gain procurement preference across German precision manufacturing clusters, accelerating supplier requalification programs for aramid fiber alternatives.
- Automotive OEM specification intensity:Multi-way cabin audio systems in electric vehicle platforms drive membrane volume for tweeter, midrange, and subwoofer channels simultaneously.
- Vapor-deposited coating advances:Thin-film deposition techniques enable mass-customization of stiffness gradients without retooling, compressing prototype-to-production lead times for specialty audio applications.
Market Restraints
- Aramid fiber supply concentration:Kevlar and Nomex precursor availability clusters with two North American chemical conglomerates, exposing membrane fabricators to force majeure pricing volatility.
- REACH substance restriction expansion:ECHA candidate list updates for polymer plasticizers trigger reformulation costs and six-month requalification freezes for European electronics suppliers.
- Polypropylene substitution ceiling:Moisture-resistant commodity formulations hit performance limits in high-temperature automotive underhood placements, constraining addressable application scope.
Strategic Opportunities
- India automotive localization:PLI scheme incentives for advanced cell manufacturing create downstream demand for acoustic component indigenization in Pune and Chennai assembly corridors.
- Professional monitoring resurgence:Studio rebuilds and broadcast facility upgrades in South Korea and Japan specify Kevlar-reinforced membranes for transient response fidelity in nearfield monitors.
- Recyclability disclosure premiums:CSRD-aligned sustainability reporting creates tiered supplier preference for membrane vendors with verified closed-loop polymer recovery programs.
Industry Challenges
- Thin-film deposition talent scarcity:Process engineers with vapor-phase coating expertise command compensation premiums that mid-cap membrane specialists struggle to match against semiconductor industry recruiters.
- FCC equipment authorization synchronization:Acoustic device electromagnetic compliance testing queues extend to fourteen weeks, delaying product launches for consumer electronics brands with fixed retail windows.
- Legacy injection molding asset stranding:Conventional diaphragm fabricators face write-down pressure as calendering and thermoforming capacity requirements shift toward hybrid manufacturing architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Speaker Membranes Market |
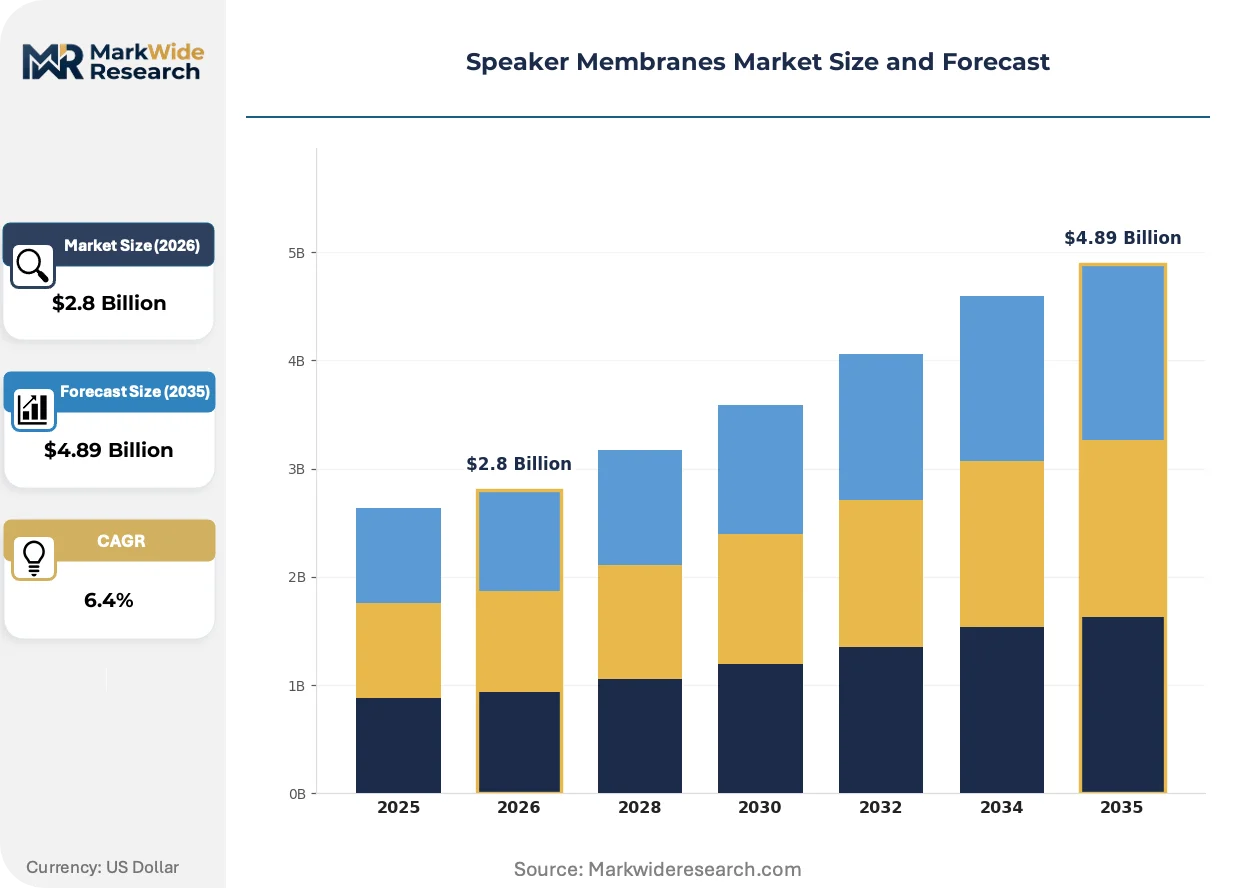
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polypropylene, Paper, Kevlar, Foam Product Design: Coaxial, Component, Full-Range, Subwoofer Application Type: Home Audio, Professional Audio, Automotive, Musical Instruments End User: Consumer Electronics, Automotive Manufacturers, Music Producers, Audio Engineers |
| Companies Covered | Sony Corporation, Samsung Electronics, Bose Corporation, Harman International, Panasonic Corporation, JBL, Sennheiser Electronic GmbH, Pioneer Corporation, Murata Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Speaker Membranes Market Trends and Innovations
Material science convergence with acoustic simulation software is collapsing the traditional separation between membrane design and system tuning. Suppliers now co-develop diaphragm geometries with OEM acoustic engineers rather than delivering to static specifications.
Electroactive polymer actuation is fragmenting the conventional voice-coil-and-suspension architecture. Dielectric elastomer membranes enable variable stiffness without mechanical crossover networks. Automotive infotainment divisions at Hyundai and Stellantis pilot these configurations for software-defined cabin equalization. The technology is fragmenting supplier roles between materials specialists and embedded firmware developers.
Japan's METI energy efficiency guidelines indirectly constrain membrane material selection through downstream product power consumption targets. Television and smart speaker manufacturers must demonstrate standby and active-mode efficiency improvements that favor lighter diaphragm constructions. Korean consumer electronics brands respond by specifying biaxially oriented polypropylene formulations with reduced moving mass.
Direct sourcing from membrane specialists is displacing tier-1 audio integrator intermediation in high-volume smartphone programs. Chinese handset manufacturers now contract diaphragm fabrication separately from final acoustic module assembly, compressing margin pools for traditional subsystem vendors. This pattern concentrates most visibly in Shenzhen and Dongguan electronics manufacturing corridors where vertical specialization dominates supplier selection.
Speaker Membranes Market Segmentation
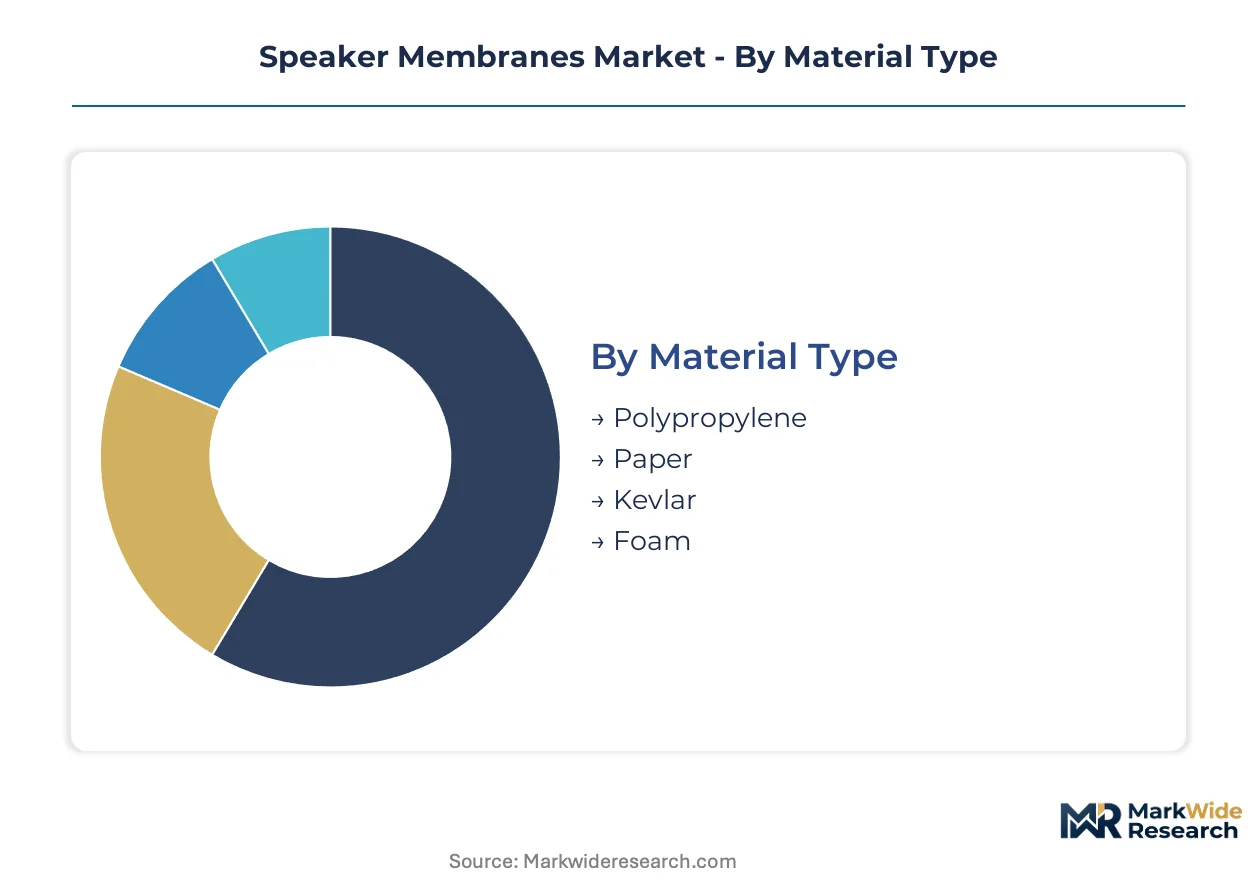
Material specifications cascade through product design choices and ultimately determine which channel—OEM direct, tier-1 integrator, or aftermarket distributor—carries volume for each membrane category. Segmentation clarity enables suppliers to align qualification timelines with the divergent technical gates of automotive platform engineering versus consumer electronics retail windows.
Material Type:
Polypropylene and Kevlar formulations flow through distinct procurement channels, with commodity polymers reaching consumer electronics via high-volume distributors while aramid-reinforced variants move through specialized acoustic engineering consultancies serving professional monitoring studios.
- Polypropylene:Biaxially oriented thermoplastic formulations deliver moisture resistance and batch consistency for cost-sensitive applications. Demand concentrates in Korean television and smart speaker manufacturing corridors where METI energy efficiency guidelines favor reduced moving mass.
- Kevlar:Aramid fiber reinforcement achieves superior rigidity-to-mass ratios for transient response fidelity. Professional monitoring rebuilds in South Korea and Japan specify these membranes, though supply concentrates with North American chemical conglomerates exposing fabricators to pricing volatility.
- Paper:Traditional pulp-based composites retain niche positioning in high-end audiophile segments where acoustic damping characteristics outweigh environmental durability concerns.
- Foam:Lightweight cellular structures serve specialized midrange applications requiring controlled breakup behavior in compact enclosure designs.
Polypropylene dominates installed base across consumer electronics. Kevlar is where expansion concentrates for premium professional audio applications.
Product Design:
Design complexity stratifies manufacturing investment requirements, with coaxial and full-range configurations favoring conventional injection molding assets while component systems and subwoofers demand hybrid calendering-thermoforming architectures.
- Component:Separated tweeter, midrange, and woofer elements enable cabin acoustic zoning in electric vehicle platforms. Automotive OEMs in Germany's precision manufacturing corridor now specify diaphragm stiffness tolerances at concept phase rather than component phase.
- Subwoofer:Large-diameter low-frequency drivers require enhanced excursion capability and thermal management. Multi-way cabin audio systems in EV platforms drive simultaneous membrane volume across all frequency channels.
- Coaxial:Concentric driver arrangements reduce enclosure complexity for space-constrained automotive door and dash placements.
- Full-Range:Single-point radiation sources simplify crossover design for entry-level home audio and portable speaker applications.
Component designs command the steepest expansion trajectory as automotive specification intensity accelerates. Full-range retains volume leadership in cost-optimized consumer segments.
Application Type:
Application focus determines regulatory exposure, with automotive placements subject to REACH substance restrictions and FCC equipment authorization while professional audio faces fewer chemical compliance burdens but demands superior acoustic performance verification.
- Automotive:Cabin acoustic zoning requirements compress development cycles for multi-way systems. EU Green Deal material mandates push German precision manufacturing clusters toward bio-based polymer feedstocks.
- Professional Audio:Studio and broadcast facility upgrades specify Kevlar-reinforced membranes for nearfield monitoring accuracy. South Korean and Japanese facility rebuilds anchor this segment's resilience.
- Home Audio:Smart speaker and soundbar proliferation drives volume for compact full-range configurations in residential installations.
- Musical Instruments:Instrument amplification and stage monitoring applications favor robust cone constructions withstand touring abuse.
Automotive applications are gaining share fastest as EV platform audio specification intensifies. Home audio maintains the broadest installed base across consumer segments.
End User:
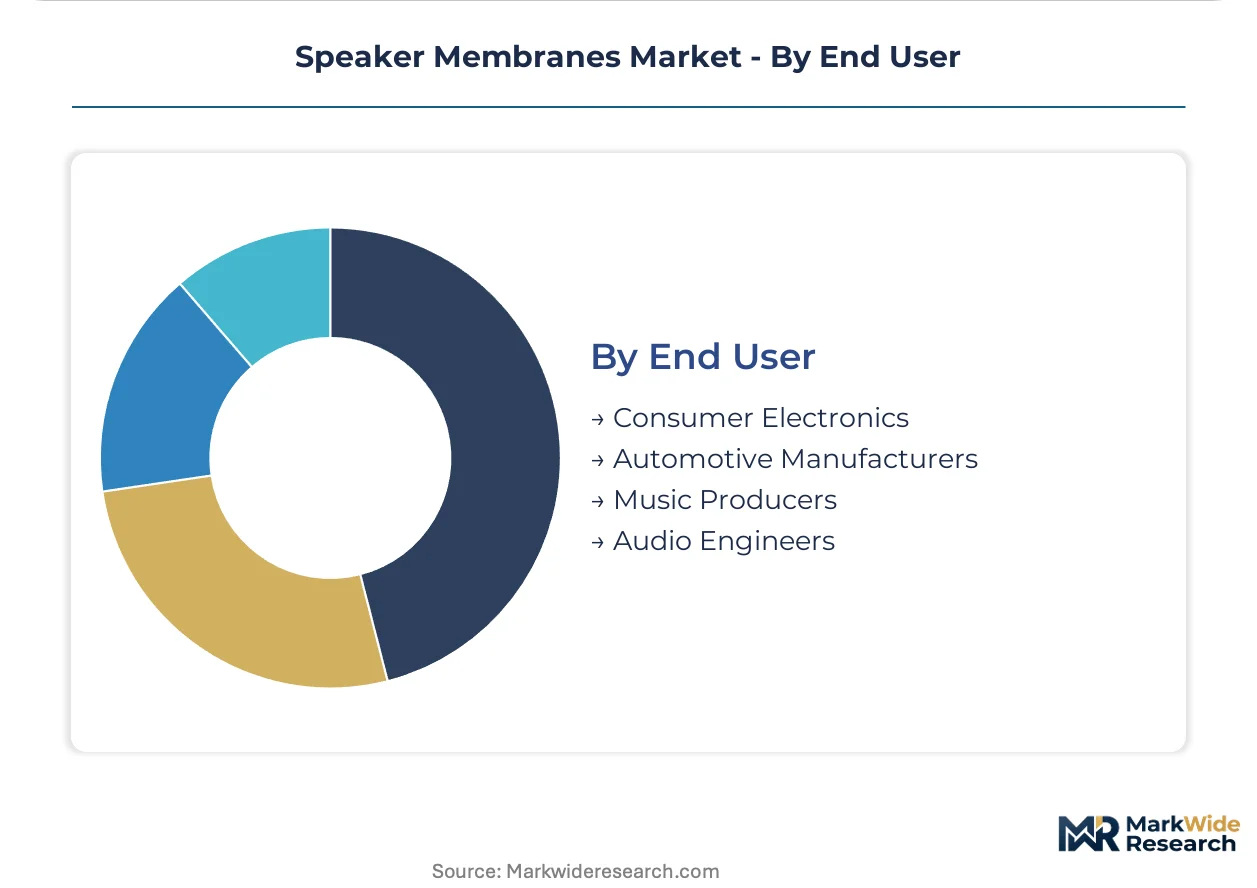
End-user category shapes contracting structures, with automotive manufacturers and consumer electronics brands increasingly sourcing membranes directly from specialists rather than through tier-1 audio integrators.
- Automotive Manufacturers:OEMs specify multi-way systems for cabin acoustic zoning with synchronized material qualification timelines. Direct sourcing patterns concentrate in Pune and Chennai assembly corridors under India's PLI scheme incentives.
- Consumer Electronics:Chinese handset manufacturers in Shenzhen and Dongguan corridors now contract diaphragm fabrication separately from final acoustic module assembly.
- Music Producers:Studio facility operators prioritize transient response fidelity in nearfield monitor specifications for mixing and mastering applications.
- Audio Engineers:Broadcast and live sound professionals demand consistent unit-to-unit performance for critical listening environments.
Consumer electronics represents the deepest installed base by unit volume. Automotive manufacturers concentrate expansion investment as cabin audio becomes a platform differentiation vector.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany's precision manufacturing corridor demonstrate the lowest price elasticity, absorbing premium membrane costs for acoustic performance verification, while Chinese consumer electronics manufacturers operate at the highest sensitivity, driving polypropylene volume through aggressive procurement consolidation.
Germany
Automotive OEMs specify multi-way cabin audio systems with synchronized material qualification timelines for electric vehicle platforms. EU Green Deal mandates through ECHA accelerate supplier requalification for bio-based polymer feedstocks in diaphragm fabrication. Stuttgart and Munich precision manufacturing clusters concentrate specification authority for stiffness tolerance standards.
China
Handset manufacturers in Shenzhen and Dongguan electronics corridors contract diaphragm fabrication separately from acoustic module assembly, compressing traditional subsystem margins. MIIT equipment certification governs electromagnetic compliance for domestic smart speaker and television production. Pearl River Delta manufacturing agglomerations dominate high-volume polypropylene membrane procurement.
United States
FCC equipment authorization requirements extend testing queues to fourteen weeks, delaying retail-window-dependent product launches for consumer electronics brands. Professional monitoring studios in Los Angeles and Nashville specify Kevlar-reinforced membranes for transient response fidelity. REACH-aligned substance restrictions propagate through multinational electronics supply chains with US assembly operations.
Japan
METI energy efficiency guidelines constrain membrane material selection through downstream television and smart speaker power consumption targets. Kanto and Kansai manufacturing belts favor biaxially oriented polypropylene formulations with reduced moving mass. Broadcast facility rebuilds in Tokyo and Osaka anchor demand for nearfield monitor accuracy specifications.
India
PLI scheme incentives for advanced cell manufacturing create downstream demand for acoustic component indigenization in automotive assembly corridors. BIS certification requirements govern electronics component quality standards for domestic and export markets. Pune and Chennai manufacturing clusters concentrate direct sourcing patterns from membrane specialists to OEMs.
Speaker Membranes Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure rather than consolidated dominance. Captive materials science laboratories at vertically integrated electronics conglomerates sustain proprietary polymer formulations, while independent membrane specialists compete on vapor-deposited coating customization and prototype-to-production compression. Three archetypes define competitive positioning: conglomerate-affiliated fabrication divisions, independent precision acoustic component specialists, and diversified polymer materials suppliers extending into diaphragm applications. Dominant competitive moves include backward integration into polymer feedstock production and strategic partnerships with automotive tier-1 integrators for platform engineering gate synchronization.
Among diversified electronics conglomerates with captive membrane operations, Sony Corporation and Samsung Electronics exemplify the scale-driven archetype, leveraging in-house fabrication for smartphone and television speaker arrays. Bose Corporation occupies a position within the premium-tier specialization vector, anchoring professional monitoring applications through differentiated acoustic engineering capabilities. These three players represent the spectrum from high-volume consumer electronics integration to margin-focused professional audio positioning.
| Leading Market Players |
|---|
| Sony Corporation |
| Samsung Electronics |
| Bose Corporation |
| Harman International |
| Panasonic Corporation |
| JBL |
| Sennheiser Electronic GmbH |
| Pioneer Corporation |
| Murata Manufacturing |
| Others |
Pricing and Supply Chain Analysis
Fourteen-week FCC equipment authorization queues compress procurement calendars for membrane suppliers serving retail-window-dependent consumer electronics brands, concentrating pricing power with fabricators holding pre-qualified material libraries while forcing spot-market buyers into premium expediting fees. This lead-time asymmetry stratifies the supplier base between integrated conglomerates with captive qualification pipelines and independent specialists exposed to requalification cost volatility.
Pricing Analysis
After-sales service bundling and extended warranty contracts drive lifetime value capture for membrane suppliers serving automotive OEMs with decade-long platform support obligations. Three-tier pricing structure across premium, standard, and economy levels separates Kevlar-reinforced professional monitoring specifications from biaxially oriented polypropylene consumer electronics volumes and commodity paper-composite aftermarket replacements. Price differentiation hinges on REACH compliance certification tier and volume scale commitment, with German precision manufacturers absorbing stiffness-tolerance premiums while Chinese handset makers drive polypropylene spot-market compression. Margins are tightening in commodity thermoplastic grades due to polypropylene feedstock volatility and aggressive procurement consolidation among Shenzhen corridor assemblers.
Supply Chain Analysis
Port congestion on transpacific trade lanes elevates inbound logistics costs for aramid fiber precursors sourced from North American chemical conglomerates, compressing margin buffers for European membrane fabricators without long-term offtake agreements. Manufacturing concentrates in China, Germany, and South Korea, with Pearl River Delta agglomerations dominating high-volume polypropylene diaphragm output and Stuttgart precision clusters anchoring automotive qualification authority. Raw material dependencies center on Kevlar and Nomex precursor availability, biaxially oriented polypropylene resin, and vapor-deposition coating chemicals. Single-source vulnerability in aramid fiber supply exposes mid-cap specialists to force majeure pricing spikes. Distribution runs through tier-1 audio integrators for automotive programs and direct OEM contracting for smartphone and television applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electroactive polymer actuation threatens conventional voice-coil-and-suspension architectures, forcing incumbent membrane suppliers to defend material science positioning against software-defined acoustic competitors. Substitution pressure from dielectric elastomer configurations at Hyundai and Stellantis pilot programs signals capability migration toward embedded firmware development.
For Market Incumbents: Shield proprietary polymer formulation libraries through accelerated bio-based requalification under EU Green Deal mandates, locking automotive OEMs into synchronized platform engineering gates. Capture backward integration into aramid fiber precursor production to neutralize North American supply concentration risk. Deepen captive materials science laboratory investment to outpace electroactive polymer displacement in professional monitoring segments.
For New Entrants and Emerging Players: Anchor in India's Pune and Chennai automotive assembly corridors where PLI scheme incentives and BIS certification requirements create procurement preference for indigenized acoustic component suppliers. Target vapor-deposited coating customization for specialty audio applications where thin-film deposition talent scarcity constrains incumbent response speed. Pursue direct sourcing relationships with Chinese handset manufacturers displacing traditional tier-1 integrator intermediation.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified polymer materials suppliers extending into diaphragm applications with underutilized calendering capacity and automotive tier-1 integrator relationships. Long-term viability favors membrane specialists with verified closed-loop polymer recovery programs aligned to CSRD sustainability reporting requirements. Monitor ECHA candidate list expansion for polymer plasticizer restrictions as an inflection signal triggering reformulation investment cycles and requalification freeze windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Bio-based Polymer Feedstock Requalification | EU Green Deal mandates through ECHA accelerate supplier transition away from petroleum-based formulations in German manufacturing clusters. |
| Vapor-Deposited Coating Capacity Expansion | Thin-film deposition expertise commands compensation premiums against semiconductor industry recruiters in specialty audio applications. |
| Direct OEM Sourcing Relationship Development | Chinese handset manufacturers in Shenzhen and Dongguan corridors now contract diaphragm fabrication separately from acoustic module assembly. |
| Automotive Platform Engineering Gate Synchronization | Tier-1 audio integrators specify diaphragm stiffness tolerances at concept phase rather than component phase for EV cabin zoning. |
| Closed-Loop Polymer Recovery Program Certification | CSRD-aligned sustainability reporting creates tiered supplier preference for verified circular economy membrane vendors. |
Research Methodology
A standing panel of acoustic engineering directors at automotive OEMs, polymer procurement leads at tier-1 audio integrators, and thin-film deposition process engineers provided ongoing calibration across primary interview rounds. Secondary validation drew from MIIT equipment certification filings, ECHA substance restriction updates, METI energy efficiency guideline releases, and customs trade data for biaxially oriented polypropylene resin flows. Bottom-up membrane volume modeling triangulated against top-down automotive platform audio specification intensity assessments.
Consistency checks against external benchmarks validated value outputs across the projection horizon, with segmentation dimensions spanning material type, product design complexity, application regulatory exposure, and end-user contracting structure. CAGRs derived from platform engineering gate timelines and retail window synchronization requirements incorporated vapor-deposited coating adoption curves and electroactive polymer pilot program expansion rates as industry-specific forecast inputs.
Material uncertainties — aramid fiber supply disruption, REACH substance list expansion, and electroactive polymer technology maturation — sit outside the modeled envelope. Forecasts reflect assumptions regarding automotive OEM specification intensity and consumer electronics direct sourcing pattern persistence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Audio and Visual Public Address System Market
Electronic Components
Coaxial Attenuators Market
Electronic Components
Efuse Market
Electronic Components
US Supercapacitor Market
Electronic Components
Stretchable Conductors in Electronics Market
Electronic Components
Gas Discharge Tube Market
Electronic Components
Flexible Heater Market
Electronic Components
Industrial Relays Market
Electronic Components
Flash Charger Adapter Market
Electronic Components
Electric Capacitor Market
Electronic Components
Global Industrial Media Converters Market
Electronic Components
Americas MPU Market
Electronic Components
Fuse Bases Market
Electronic Components
TWS and Noise-Cancelling Headphone with MEMS Chip Market
Electronic Components
Audio Capacitor Market
Electronic Components
Plastics in Consumer Electronics Market