
 Laser Direct Structuring (LDS) Antenna Market | 2026-2036
Laser Direct Structuring (LDS) Antenna Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Direct Structuring (LDS) Antenna Market Foresight
Market Context with Strategic Players
The capital-intensity divergence between laser-system owners and contract assemblers is redrawing competitive boundaries across the LDS antenna supply base. LPKF Laser & Electronics leverages its captive laser-source technology to dominate equipment supply and anchor premium pricing for high-precision 5G antenna substrates. Amphenol Corporation sustains manufacturing scale across multiple continents, while Shenzhen Sunway Communication Co. Ltd specializes in cost-optimized LDS production for mid-tier consumer electronics brands.
Technical Definition and Structural Segments
Laser Direct Structuring (LDS) antenna refers to a three-dimensional molded interconnect device manufactured by laser-activating a thermoplastic substrate doped with metal-organic compounds, followed by electroless copper plating to create conductive traces with typical line/space resolution of 150 micrometers. The process enables antenna integration directly onto complex plastic housings, eliminating separate flex circuits and solder joints in smartphones, automotive radar modules, and medical wearables. Passive antennas occupy the largest volume share as legacy 4G and basic IoT applications retain substantial installed bases, while smart antennas represent the fastest-expanding margin pool as beamforming requirements intensify under 5G and Wi-Fi 6 technology deployments. Automotive systems applications within the application dimension show accelerated structural growth as OEMs consolidate multiple RF functions into single LDS-enabled housings for advanced driver-assistance systems.
Regulatory Frame and Forward-Looking Close
The Federal Communications Commission in the United States enforces stringent specific absorption rate limits that directly shape LDS antenna efficiency requirements and test protocols for devices entering the North American market. China's Ministry of Industry and Information Technology mandates GB-standard electromagnetic compatibility certification, while the European Union's Radio Equipment Directive governs market access across member states through harmonized frequency allocation and safety testing. Stakeholders must monitor evolving spectrum reallocation decisions in major economies, as mid-band and millimeter-wave assignments will determine which antenna architectures and plating specifications become technically mandatory for next-generation device certification.
Market Dynamics
5G beamforming requirements are compressing antenna architectures into increasingly compact geometries, forcing manufacturers to abandon planar flex circuits in favor of three-dimensional molded interconnect devices that integrate RF functionality directly onto structural plastic housings.
Growth Catalysts
- MIIT electromagnetic compatibility mandates:China's Ministry of Industry and Information Technology enforces stricter GB-standard certification for wireless devices, compelling smartphone OEMs to adopt LDS substrates that guarantee signal integrity under tighter testing protocols.
- Automotive radar consolidation:Advanced driver-assistance system suppliers integrate multiple RF functions into single LDS-enabled housings, reducing component count and assembly complexity for 77 GHz and 79 GHz radar modules.
- South Korean consumer electronics cluster:Seoul and Suwon host concentrated smartphone manufacturing operations where LDS antenna adoption accelerates as domestic brands push 5G handset refresh cycles.
Market Restraints
- Laser system supply concentration:Captive laser-source technology concentrates among a handful of equipment vendors, creating procurement bottlenecks for contract assemblers seeking to expand LDS capacity.
- Copper plating chemistry volatility:Electroless copper bath formulations depend on palladium activator compounds whose spot prices fluctuate with precious metals markets, compressing plating shop margins unpredictably.
- Thermoplastic substrate limitations:Laser-activated resins require precise metal-organic doping concentrations that restrict substrate suppliers to qualified compounders, limiting material sourcing flexibility.
Strategic Opportunities
- Medical wearable expansion:Hearable and continuous glucose monitor manufacturers seek antenna integration into curved plastic enclosures where LDS eliminates solder joint fatigue in body-worn devices.
- Wi-Fi 6E and Wi-Fi 7 transition:New spectrum allocations in the 6 GHz band demand antenna architectures with tighter phase coherence, favoring LDS precision over stamped metal alternatives.
- India PLI scheme localization:Production-linked incentive schemes for electronics manufacturing attract LDS equipment investment to serve emerging smartphone assembly operations in Tamil Nadu and Uttar Pradesh.
Industry Challenges
- Electroplating process engineering talent:Qualified technicians capable of maintaining electroless copper bath chemistry within tight pH and temperature windows remain scarce relative to LDS line expansion plans.
- Multi-band antenna integration complexity:Handset designers struggle to isolate sub-6 GHz, millimeter-wave, and ultra-wideband antenna elements within shared LDS-enabled housings without mutual coupling degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Direct Structuring (LDS) Antenna Market |
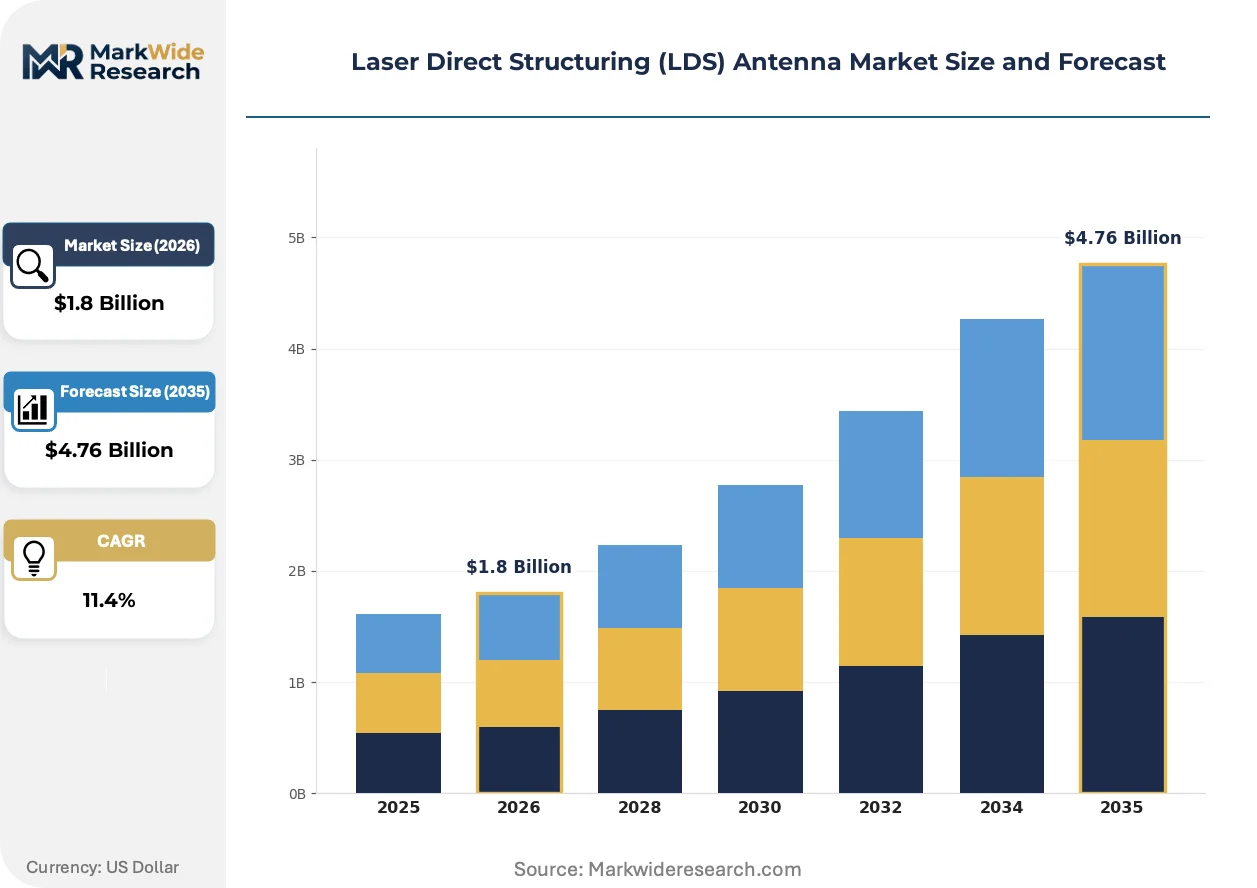
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Antennas, Active Antennas, Hybrid Antennas, Smart Antennas Technology: 5G, Wi-Fi 6, Bluetooth, RFID Application: IOT Devices, Communication Equipment, Automotive Systems, Wearable Technology End User: Telecommunications, Consumer Electronics, Automotive, Aerospace |
| Companies Covered | Luxshare Precision Industry Co. Ltd, Taoglas Group Holdings Limited, Amphenol Corporation, Pulse Electronics Corporation, Galtronics Corporation Ltd, TE Connectivity, Shenzhen Sunway Communication Co. Ltd, Molex, LPKF Laser & Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Direct Structuring (LDS) Antenna Market Shifts & Advancements
Antenna-in-package architectures are collapsing traditional boundaries between semiconductor packaging and RF subsystem assembly, compressing development cycles and forcing equipment vendors to retool for finer feature resolution.
Multi-layer LDS processing is miniaturizing antenna feed networks by stacking laser-activated substrates with interlayer via metallization, enabling smartphone manufacturers to embed 5G mmWave arrays within device frames without sacrificing battery volume. Korean OEMs have adopted this capability fastest, pressuring plating shops to qualify new resin systems that withstand repeated thermal cycling during assembly.
The European Union's Radio Equipment Directive harmonization is tightening electromagnetic compatibility documentation requirements for devices claiming multi-band operation, forcing LDS antenna suppliers to invest in enhanced test chamber capacity and third-party certification partnerships. Medical device manufacturers exporting into EU member states now face extended validation timelines that compress product launch windows.
Consolidated procurement contracts are displacing fragmented supplier relationships as smartphone OEMs reduce their antenna vendor bases from six to two qualified sources per handset platform. This concentration is most visible in China's Pearl River Delta, where tier-one brands now mandate direct equipment audits and process certification before awarding LDS substrate volume.
Laser Direct Structuring (LDS) Antenna Market Segmentation
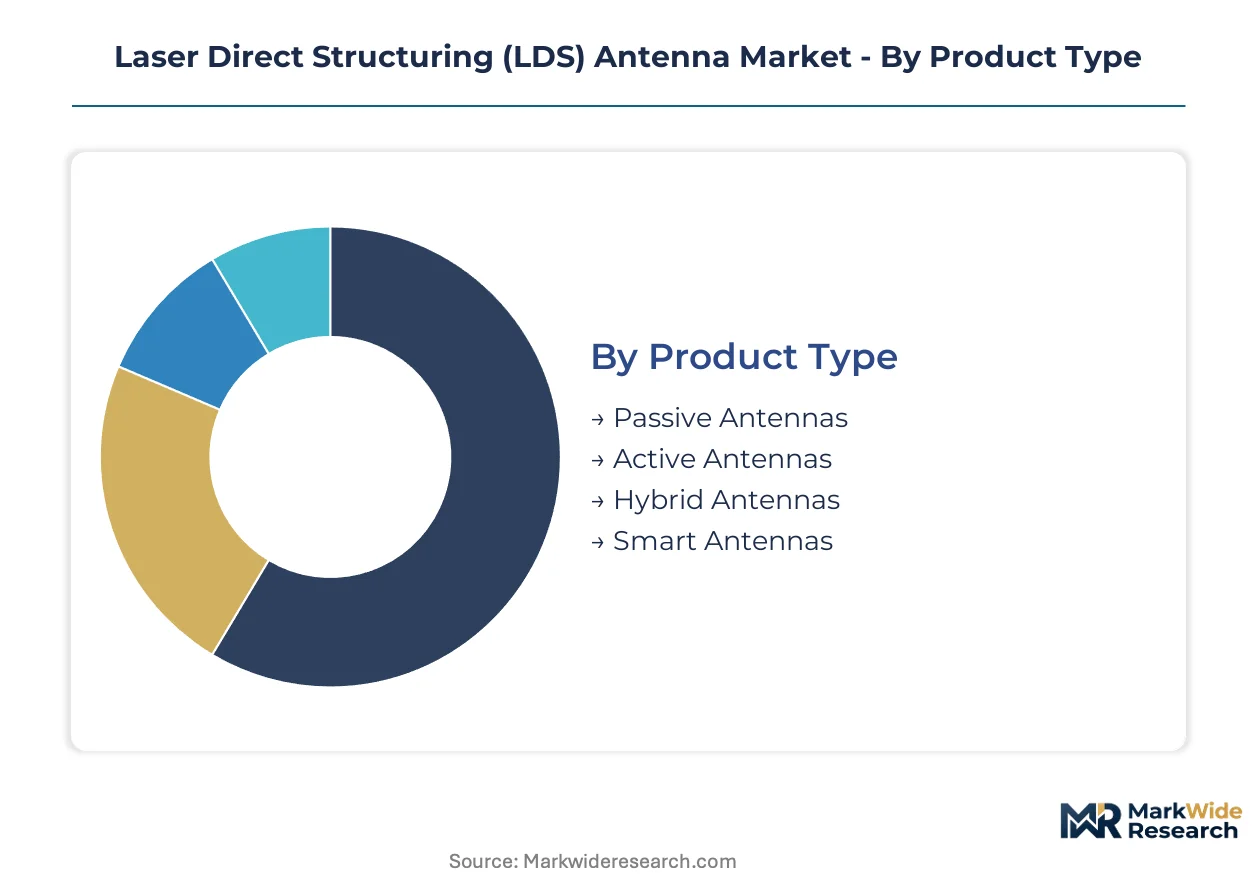
Segmentation in the LDS antenna market reveals how manufacturing complexity and certification requirements fragment procurement channels. Equipment vendors, contract assemblers, and OEM captive shops each dominate distinct product tiers, shaping margin structures and technical specifications across the value chain.
Product Type:
Channel distribution varies sharply by antenna complexity, with passive variants flowing through high-volume contract manufacturers while smart antennas concentrate in vertically integrated OEM facilities.
- Passive Antennas:Single-function radiating elements manufactured through standard laser activation and electroless copper plating on doped thermoplastic substrates. China's Pearl River Delta contract assemblers process the bulk of volume for mid-tier smartphone brands where basic 4G connectivity suffices. By volume, passive antennas lead. By growth pace, smart antennas are climbing the fastest.
- Smart Antennas:Beamforming-capable arrays with integrated RF front-end components requiring multi-layer LDS processing and precision phase-matched feed networks. Seoul-based OEMs deploy these in flagship 5G handsets where MIIT electromagnetic compatibility certification demands guaranteed signal integrity under tighter testing protocols.
- Active Antennas:Modules incorporating power amplifiers and low-noise amplifiers directly on the LDS substrate, reducing interconnect losses in automotive radar housings.
- Hybrid Antennas:Designs combining stamped metal radiators with LDS feed structures for cost optimization in Wi-Fi 6E access points.
Passive antennas dominate unit shipments. Smart antennas command the steepest expansion trajectory as beamforming requirements intensify.
Technology:
Cost tiers stratify cleanly across wireless standards, with 5G commanding premium plating specifications and Wi-Fi 6E driving mid-tier investment while Bluetooth and RFID anchor economy production.
- 5G:Sub-6 GHz and millimeter-wave architectures demanding 150-micrometer line/space resolution and multi-band isolation within shared LDS-enabled housings. South Korean consumer electronics manufacturers around Seoul and Suwon push refresh cycles fastest, pressuring plating shops to qualify new resin systems that withstand repeated thermal cycling during assembly.
- Wi-Fi 6:6 GHz spectrum allocations requiring tighter phase coherence than stamped metal alternatives can deliver, favoring LDS precision for enterprise access point manufacturers.
- Bluetooth:Low-complexity single-band designs concentrated in hearable and medical wearable production where antenna integration into curved plastic enclosures eliminates solder joint fatigue.
- RFID:Ultra-high-frequency and near-field communication tags produced through simplified single-layer LDS for logistics and retail applications.
Bluetooth ships the highest unit volumes. 5G generates the fastest value expansion as handset OEMs consolidate vendor bases.
Application:
Customer type determines specification stringency, with automotive systems demanding full traceability and medical wearables requiring biocompatible substrate formulations absent in consumer electronics.
- Automotive Systems:77 GHz and 79 GHz radar modules where advanced driver-assistance system suppliers consolidate multiple RF functions into single LDS-enabled housings. Germany's KBA type-approval requirements shape plating thickness specifications for radar substrates entering European vehicle platforms.
- Communication Equipment:Base station and small-cell antennas where FCC specific absorption rate limits directly shape efficiency requirements for North American market entry.
- IOT Devices:Industrial sensors and smart home controllers prioritizing cost over performance in high-volume production.
- Wearable Technology:Continuous glucose monitors and fitness trackers where curved enclosure geometries make flex circuit alternatives mechanically unreliable.
Communication equipment leads by installed base. Automotive systems are expanding most quickly as OEMs consolidate RF functionality.
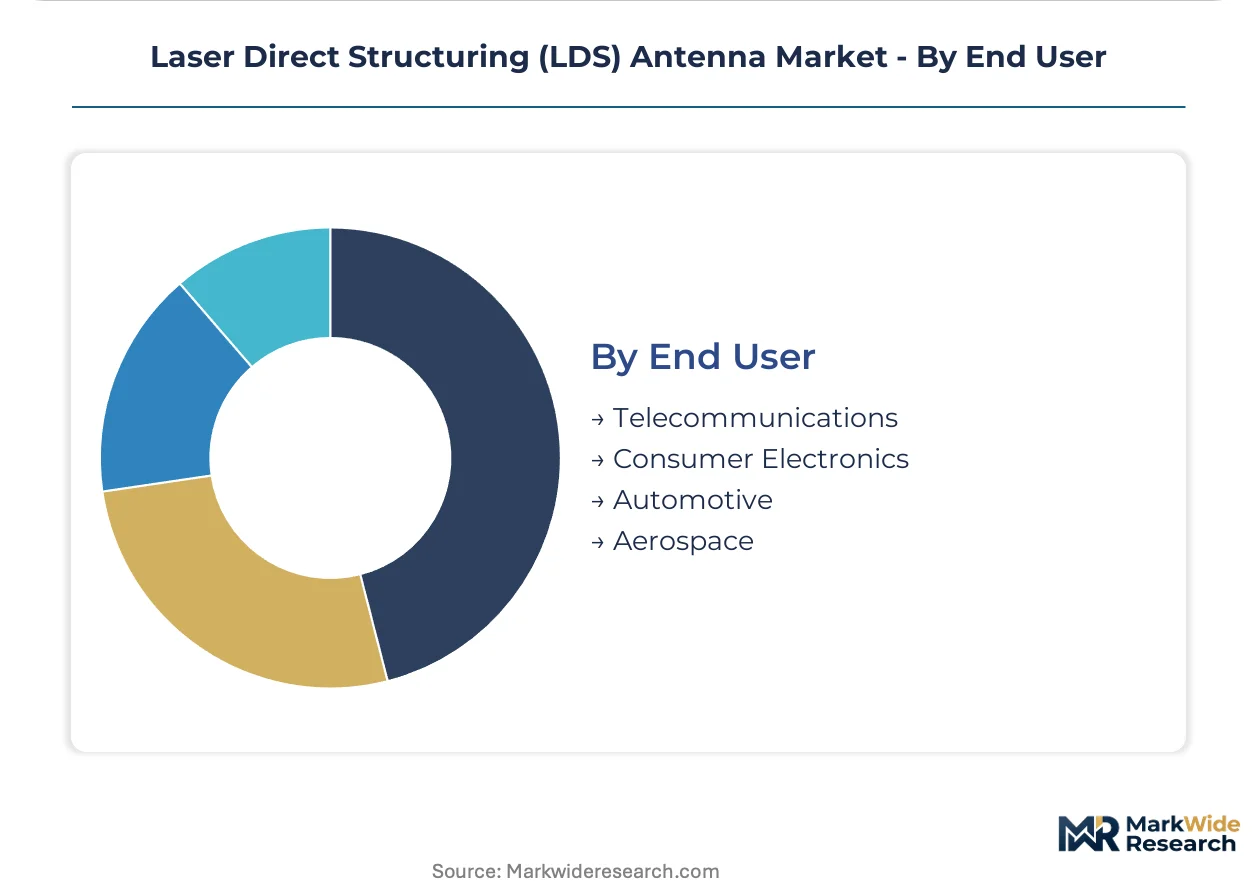
End User:
Supply concentration aligns with end-user procurement power, with telecommunications carriers dictating test protocols and aerospace primes enforcing captive supplier qualification.
- Consumer Electronics:Smartphone and tablet manufacturers in Asia-Pacific driving adoption as 5G deployment accelerates, with China's MIIT mandates compelling OEMs to adopt LDS substrates that guarantee signal integrity.
- Automotive:Tier-1 radar module suppliers qualifying LDS plating shops through direct equipment audits before awarding substrate volume.
- Telecommunications:Carrier certification requirements for network infrastructure equipment spanning multiple national regulatory regimes.
- Aerospace:Satellite and unmanned aerial vehicle manufacturers where weight reduction justifies premium LDS processing despite low volumes.
Consumer electronics dominates unit demand. Aerospace shows the steepest value-per-unit premium despite limited shipment scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in South Korea's Seoul-Suwon corridor where domestic OEMs command premium specifications, while China's Pearl River Delta contract assemblers compete on volume at compressed margins. This asymmetry shapes procurement patterns across the LDS antenna supply base.
China
Smartphone OEMs in Shenzhen and Dongguan drive LDS substrate demand as 5G handset refresh cycles accelerate. MIIT enforces stricter GB-standard electromagnetic compatibility certification that compels adoption of signal-integrity-guaranteed LDS architectures. The Pearl River Delta hosts concentrated contract assembly operations where tier-one brands mandate direct equipment audits before awarding volume.
South Korea
Seoul-based consumer electronics manufacturers push multi-layer LDS processing for flagship 5G devices with integrated millimeter-wave arrays. The MFDS maintains device certification protocols that shape antenna efficiency testing requirements for domestic market entry. The Seoul-Suwon corridor concentrates smartphone manufacturing where domestic brands accelerate 5G deployment fastest.
United States
Telecommunications infrastructure and aerospace applications sustain demand for high-reliability LDS-enabled housings. The FCC enforces specific absorption rate limits that directly shape antenna efficiency requirements and test protocols for devices entering North American markets. California's technology corridor hosts RF subsystem designers integrating antenna-in-package architectures for next-generation wireless devices.
Germany
Automotive radar module suppliers consolidate multiple RF functions into single LDS-enabled housings for advanced driver-assistance systems. The KBA type-approval requirements shape plating thickness specifications for radar substrates entering European vehicle platforms. Bavaria's automotive electronics cluster hosts tier-1 suppliers qualifying plating shops through rigorous process certification.
India
Production-linked incentive schemes for electronics manufacturing attract LDS equipment investment to serve emerging smartphone assembly operations. The BIS certification framework governs electromagnetic compatibility standards for wireless devices entering the domestic market. Tamil Nadu and Uttar Pradesh host expanding electronics manufacturing zones where contract assemblers establish LDS capacity to serve export-oriented production.
Laser Direct Structuring (LDS) Antenna Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the LDS antenna supply base. Equipment vendors with captive laser-source technology anchor premium pricing for high-precision applications, while contract assemblers compete on scale and geographic proximity to OEM manufacturing clusters. Three archetypes dominate: laser-system specialists, multi-continent contract manufacturers, and regionally focused cost-optimized producers. Consolidation pressures intensify as smartphone OEMs reduce qualified antenna vendor bases, while plating chemistry volatility forces margin compression across contract assembly tiers.
Among equipment-centric players, LPKF Laser & Electronics exemplifies technology leadership through its integrated laser-source capabilities. Amphenol Corporation and Shenzhen Sunway Communication Co. Ltd represent contrasting scale archetypes—one spanning multi-continent manufacturing footprints, the other concentrating cost-optimized production for mid-tier consumer electronics brands. These three anchors illustrate how competitive positioning stratifies across technology ownership, manufacturing scale, and regional specialization vectors.
| Leading Market Players |
|---|
| Luxshare Precision Industry Co. Ltd |
| Taoglas Group Holdings Limited |
| Amphenol Corporation |
| Pulse Electronics Corporation |
| Galtronics Corporation Ltd |
| TE Connectivity |
| Shenzhen Sunway Communication Co. Ltd |
| Molex |
| LPKF Laser & Electronics |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation contracts lock in laser-system access and plating chemistry supply for tier-one smartphone OEMs, insulating them from palladium price volatility while compressing margin visibility for uncommitted contract assemblers in China's Pearl River Delta.
Pricing Analysis
Configured-to-order pricing for multi-layer 5G mmWave substrates commands substantial premiums over standard single-layer passive antenna configurations. Pricing stratifies across automotive-grade, consumer electronics-grade, and basic IoT tiers, with certification to China's GB-standard electromagnetic compatibility protocols acting as a gatekeeper to premium tiers. Cost compression in mid-tier consumer electronics production is intensifying because contract assemblers compete for consolidated procurement contracts from reducing vendor bases. Smartphone OEMs exhibit the sharpest price sensitivity, while automotive radar module suppliers accept premium positioning for traceability-assured supply.
Supply Chain Analysis
Inventory buffers for palladium activator compounds and laser-activated thermoplastic resins extend lead times when spot markets tighten. Manufacturing concentrates in China, South Korea, and Germany, with the Seoul-Suwon corridor and Shenzhen-Dongguan cluster anchoring distinct premium and volume tiers respectively. The supply chain draws from specialized metal-organic compound suppliers and captive laser-source equipment vendors, creating single-source vulnerability for contract assemblers lacking backward integration. Distribution runs through consolidated procurement channels where tier-one brands mandate direct equipment audits before volume allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment—manifest in GB-standard, FCC, and EU Radio Equipment Directive certification requirements—creates switching costs that protect qualified suppliers from displacement.
For Market Incumbents: Consolidate plating shop capacity in South Korea's Seoul-Suwon corridor to capture premium 5G mmWave substrate demand, while deepening backward integration into laser-activated resin compounding to offset palladium chemistry volatility. Threat of emerging multi-layer LDS specialists in India's Tamil Nadu electronics zones demands preemptive certification investment to maintain vendor-base position. For New Entrants and Emerging Players: GB-standard electromagnetic compatibility fast-track certification unlocks access to China's Pearl River Delta contract assembly tier, the most penetrable entry point for unqualified suppliers. Medical wearable applications in curved enclosure geometries offer white-space opportunity where flex circuit alternatives fail mechanically. A plating-shop partnership model with established laser-system owners accelerates technical qualification without capital-intensive equipment acquisition. For Investors and Strategic Acquirers: Capital is best deployed toward plating shops with demonstrated multi-layer processing capability and existing automotive radar qualification, as OEM consolidation trends favor suppliers spanning both consumer electronics and automotive end-use. Long-term viability hinges on process engineering talent retention and resin system qualification breadth. The signal to watch is spectrum reallocation decisions in major economies, which will determine which antenna architectures become technically mandatory for next-generation device certification.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Layer LDS Processing Qualification | Enables 5G mmWave antenna integration for Korean OEM flagship devices. |
| Backward Integration into Resin Compounding | Secures supply of laser-activated thermoplastics against qualified compounder concentration. |
| GB-Standard Certification Investment | Unlocks volume allocation from Shenzhen-based smartphone OEMs under MIIT mandates. |
| Automotive Radar Plating Shop Qualification | Captures ADAS substrate demand as tier-1 suppliers consolidate RF functions. |
| India PLI Scheme Manufacturing Footprint | Positions capacity to serve Tamil Nadu and Uttar Pradesh electronics assembly expansion. |
Research Methodology
Initial hypotheses were tested against primary input from laser-system equipment vendors, electroless plating shop operations managers, smartphone OEM antenna procurement leads, and automotive radar module tier-1 supplier quality directors, then refined against secondary validation from MIIT GB-standard documentation, FCC equipment authorization databases, EU Radio Equipment Directive harmonized standards, and SEC filings of listed RF component manufacturers. Bottom-up plating shop capacity modeling and top-down smartphone antenna content-per-unit estimates were triangulated to constrain variance.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects within each segmentation dimension: product type complexity tier, wireless standard generation, application-specific certification grade, and end-user procurement concentration. CAGRs were derived from fitted adoption curves for 5G handset refresh cycles and automotive radar module consolidation trends, with cross-reference to laser-system installation data and palladium spot price sensitivity scenarios.
Decision-makers should treat outputs as directional under assumptions of continued MIIT electromagnetic compatibility enforcement and stable laser-source equipment vendor concentration; material deviation in spectrum allocation timelines or trade policy affecting palladium supply chains would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Capacitor Kits Market
Electronic Components
Video Surveillance Chip Market
Electronic Components
Semiconductor Micro Components Market
Electronic Components
Film Capacitor Market
Electronic Components
Crystal Oscillators Market
Electronic Components
Ceramic Capacitors Market
Electronic Components
Wireless Charging Stand Market
Electronic Components
Robotic Flat Cable Market
Electronic Components
Electrolytic Capacitor Market
Electronic Components
Operational Amplifier Market
Electronic Components
Capacitive Stylus Pen Market
Electronic Components
Global Waveguide Components and Assemblies Market
Electronic Components
Timing Relay Market
Electronic Components
United States Radiation-Hardened Electronics Market
Electronic Components
Handheld Devices Battery Market
Electronic Components
Motherboard Battery Market