
 Ceramic Disc Capacitor Market | 2026-2036
Ceramic Disc Capacitor Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramic Disc Capacitor Market Outlook
Component refurbishment and lifecycle extension services is rewriting margin capture in passive component supply chains. Murata Manufacturing Co., Ltd. anchors high-frequency ceramic formulations for 5G base stations and radar modules. TDK Corporation leverages its ferrite and dielectric material science heritage to sustain pricing power in automotive-grade X7R and C0G lines. Vishay Intertechnology, Inc. competes through broad catalog breadth and distributor channel control across industrial and military-aerospace verticals.
Ceramic disc capacitors are passive electronic components constructed from ceramic dielectric wafers with silver-palladium electrode layers, typically rated from picofarads to microfarads with voltage tolerances spanning tens to thousands of volts; they stabilize voltage, filter noise, and manage transient currents in power electronics and signal processing circuits. High voltage and X7R product types dominate industrial and automotive procurement due to temperature stability requirements under harsh operating conditions. C0G formulations command premium positioning in precision timing and RF applications where capacitance drift must remain negligible across temperature extremes.
REACH in Europe and RoHS directives constrain lead content and hazardous substance thresholds in ceramic dielectric and electrode compositions, forcing reformulation investments that filter smaller fabricators from qualified supplier lists. China's GB standards and SAMR quality certification protocols impose parallel conformity requirements for capacitors sold into domestic telecommunications and renewable energy infrastructure. Japan's METI energy efficiency frameworks indirectly shape capacitor specification through downstream power electronics efficiency mandates. Stakeholders must monitor evolving dual-use export controls and raw material sourcing constraints for palladium and rare earth dielectric additives.
Market Dynamics
EV powertrain electrification is multiplying ceramic disc capacitor counts per vehicle, while REACH and RoHS compliance in Europe is forcing dielectric reformulations that filter smaller fabricators from qualified supplier lists.
Growth Catalysts
- EV Onboard Charger Expansion:Electric vehicle manufacturers are specifying high-voltage X7R capacitors for DC-link filtering and snubber circuits, driving procurement volumes across automotive tier-one suppliers.
- REACH Material Purity Mandates:European ECHA enforcement of restricted substance thresholds is accelerating qualified supplier consolidation, benefiting incumbent dielectric formulators with in-house testing laboratories.
- 5G Base Station Buildout:Telecommunications infrastructure deployment in China and South Korea requires C0G-class precision capacitors for RF signal conditioning in massive MIMO antenna arrays.
Market Restraints
- Palladium Electrode Cost Volatility:Silver-palladium inner electrode formulations face price pressure from precious metal commodity swings, compressing margins for mid-tier capacitor fabricators without hedging programs.
- China Supply Concentration:Domestic Chinese manufacturers control approximately 60% of global ceramic powder supply, creating geographic single-source risk for dielectric raw material procurement.
- MLCC Substitution Pressure:Multilayer ceramic chip capacitors are displacing disc formats in space-constrained consumer electronics, narrowing the addressable market for traditional radial-lead designs.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor and component production are attracting dielectric formulation investments to serve domestic appliance and automotive assembly networks.
- Renewable Energy Inverters:Grid-tied solar and wind power conversion systems require high-voltage snubber capacitors with extended temperature ratings, opening industrial-grade procurement channels.
- Medical Device Reshoring:FDA quality system regulations are prompting North American OEMs to dual-source C0G capacitors for implantable and diagnostic equipment from qualified regional suppliers.
Industry Challenges
- Dielectric Chemistry Talent Scarcity:Formulation expertise for temperature-stable barium titanate modifications is concentrated among retiring Japanese and European specialists, constraining R&D pipeline velocity.
- AEC-Q200 Certification Timelines:Automotive reliability qualification protocols require 12-18 month validation cycles, delaying revenue recognition for new high-voltage product introductions.
- Legacy Equipment Integration:Industrial power electronics retrofits demand pin-compatible disc capacitor replacements with obsolete case sizes, forcing manufacturers to maintain uneconomic legacy production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramic Disc Capacitor Market |
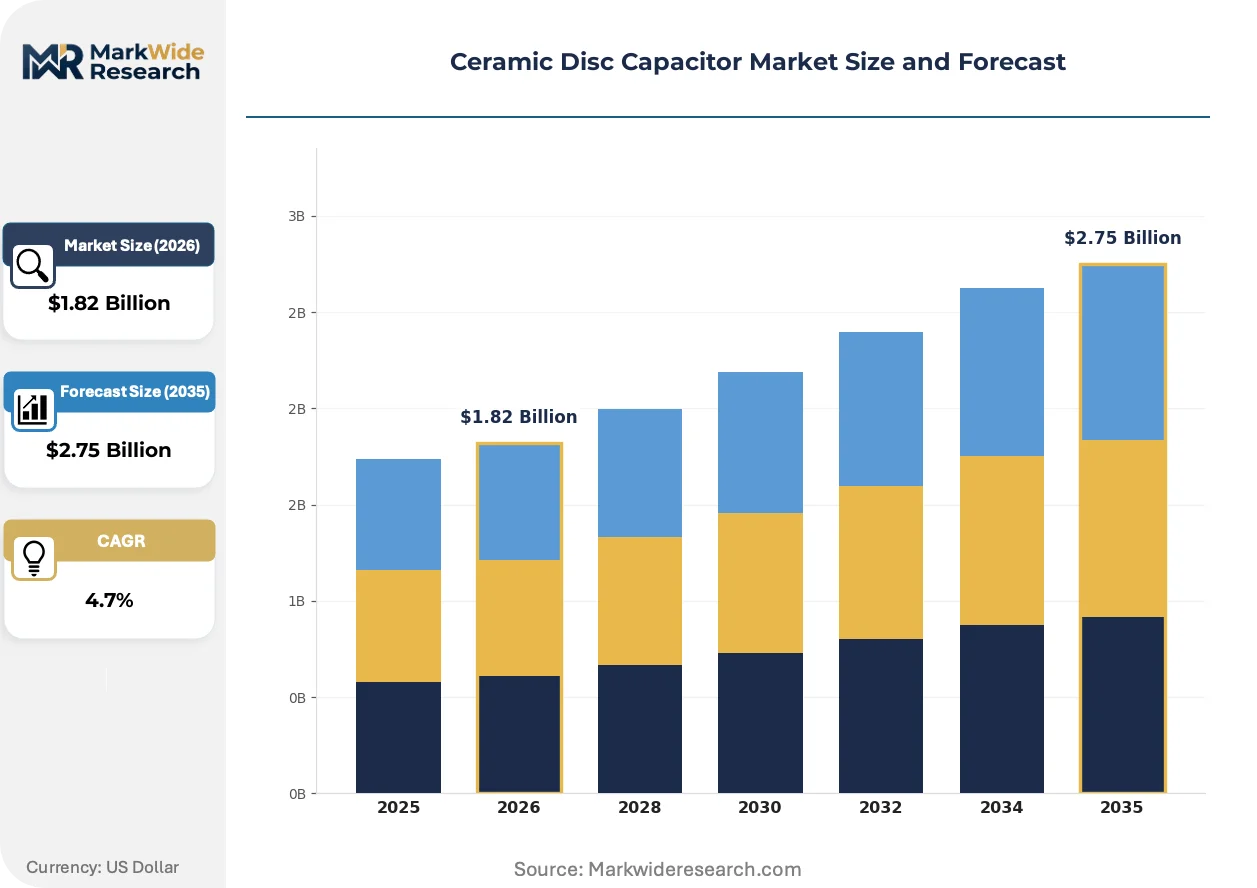
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $2.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, High Voltage, X7R, C0G Application: Consumer Electronics, Automotive Electronics, Industrial Equipment, Communication Devices End User: OEMs, Aftermarket Consumers, Distributors, Retailers Dielectric Constant: Low, Medium, High, Ultra-High |
| Companies Covered | TAIYO YUDEN CO., LTD., YAGEO Group, Murata Manufacturing Co., Ltd., Walsin Technology Corporation, Vishay Intertechnology, Inc., TDK Corporation, SAMSUNG ELECTRO-MECHANICS, Johanson Dielectrics, Inc., KYOCERA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramic Disc Capacitor Market Strategic Shifts
Dielectric material science is converging with automotive electrification requirements, while regulatory frameworks in Europe and Asia are rewriting qualification protocols for high-reliability applications.
Lead-free BME (base metal electrode) formulations are hybridizing traditional precious metal architectures to reduce palladium dependency while maintaining X7R temperature characteristics. Tier-one automotive suppliers in Germany and Japan are qualifying these formulations for 150°C under-hood applications. The technology is hybridizing cost structures across premium and standard product tiers, enabling margin expansion for qualified manufacturers.
EU REACH Annex XVII restrictions on lead content in dielectric ceramics are forcing reformulation of Class 1 and Class 2 ceramic compositions for European-market capacitors. ECHA enforcement actions against non-compliant imports are accelerating laboratory testing investments among Asian exporters. Medical and automotive verticals are responding by mandating full material disclosure documentation from qualified suppliers.
Consolidated procurement through authorized distributor networks is replacing fragmented spot-market purchasing for high-reliability capacitor categories. Industrial and military-aerospace buyers are demanding lot traceability and counterfeit avoidance protocols that only franchised channels can provide. This behavioral shift is most visible in North American defense electronics and European railway signaling equipment supply chains.
Ceramic Disc Capacitor Market Segmentation
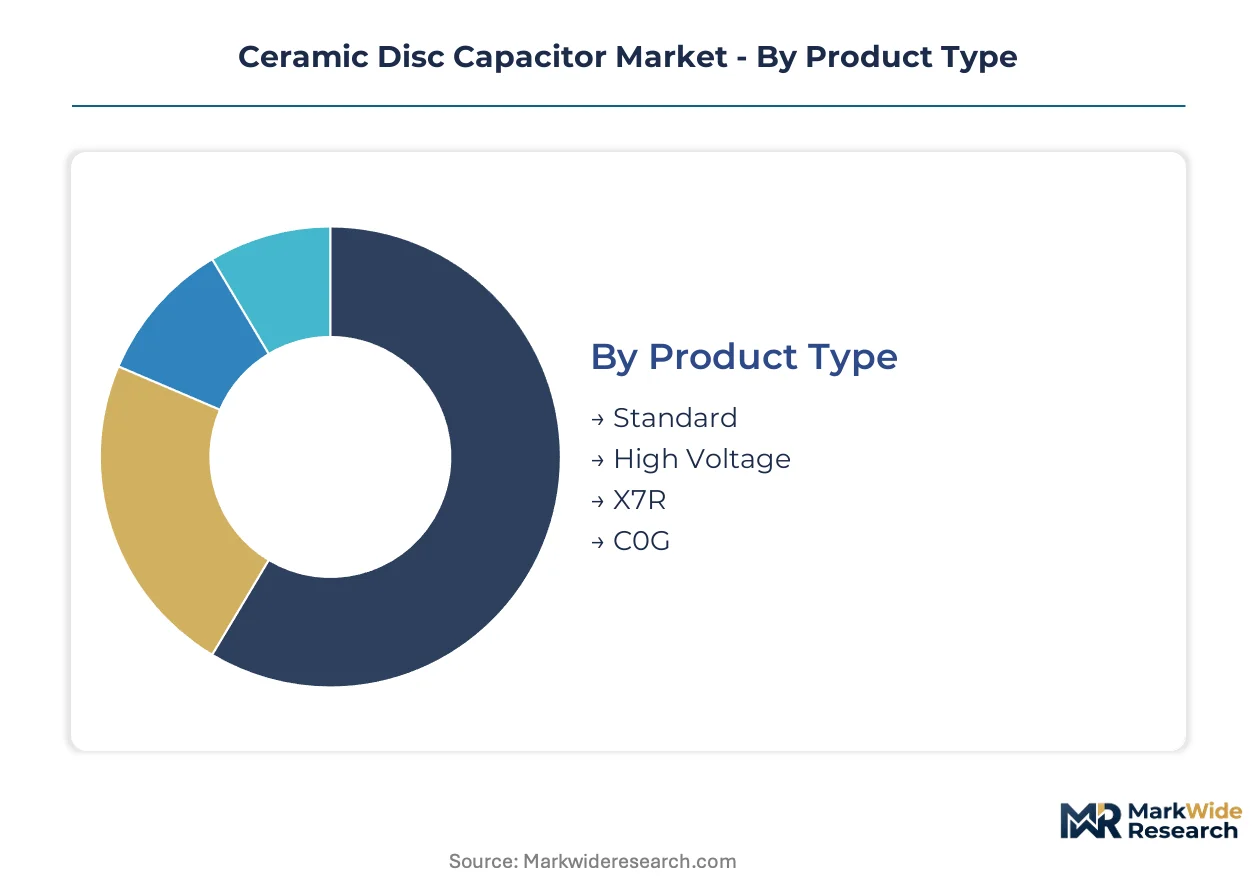
Dielectric formulation chemistry and voltage tolerance specifications fragment procurement patterns across automotive, industrial, and consumer verticals. Segment boundaries align with reliability certification tiers rather than simple price brackets, forcing suppliers to maintain parallel qualification tracks for AEC-Q200 automotive grades versus standard commercial ratings.
Product Type:
Cost tier separation in ceramic disc capacitors correlates with temperature stability specifications and electrode material costs.
- Standard:General-purpose formulations using barium titanate dielectrics with silver electrodes serve appliance power supplies and lighting ballasts. Procurement concentrates in China for domestic white goods manufacturing and Southeast Asian export assembly, with price pressure from high-volume contract manufacturers.
- High Voltage:Thick ceramic wafers with optimized grain structure withstand kilovolt-level transients in industrial motor drives and grid infrastructure. German and Japanese automotive tier-ones specify these for onboard charger DC-link filtering as EV platforms multiply component counts.
- X7R:Temperature-compensated Class 2 dielectrics maintain capacitance stability across -55°C to +125°C ranges for under-hood automotive modules.
- C0G:Ultra-stable Class 1 formulations with near-zero capacitance drift serve precision RF timing and medical diagnostic equipment.
High Voltage holds installed capacity. X7R is rotating up the share rankings.
Application:
End-use diversity spans from commodity consumer goods to mission-critical infrastructure, with qualification protocols determining supplier eligibility.
- Consumer Electronics:Radial-lead disc formats face displacement pressure from surface-mount MLCCs in smartphones and wearables. Remaining demand concentrates in power supply filtering for desktop PCs and gaming consoles where through-hole assembly persists.
- Automotive Electronics:EV powertrain electrification multiplies capacitor counts per vehicle for DC-link stabilization, snubber circuits, and battery management systems. TDK and Murata anchor qualified supplier positions for 150°C under-hood specifications.
- Industrial Equipment:Motor drives, welding equipment, and uninterruptible power supplies demand high-voltage ratings with extended temperature endurance.
- Communication Devices:Base station RF conditioning and radar modules require C0G-class precision for signal integrity.
Automotive Electronics commands qualification investment. Communication Devices is climbing the fastest on 5G infrastructure deployment.
End User:
Channel structure shapes margin capture, with authorized distribution gaining share in high-reliability categories.
- OEMs:Direct procurement contracts with automotive and industrial equipment manufacturers specify lot traceability and counterfeit avoidance protocols. Tier-one suppliers in Germany and Japan mandate full material disclosure documentation under REACH and RoHS compliance frameworks.
- Aftermarket Consumers:Repair and replacement demand for legacy industrial equipment sustains obsolete case size production. North American distributors maintain inventory for equipment refurbishment services.
- Distributors:Arrow Electronics and Avnet control franchised channels for military-aerospace and medical verticals requiring qualified supplier status.
- Retailers:Electronics hobbyist and repair shop sales represent fragmented, price-sensitive volume with minimal specification requirements.
OEMs anchor volume commitments. Distributors is gaining share fastest on consolidated procurement trends.
Dielectric Constant:
Material science sophistication separates premium precision grades from commodity high-capacitance formulations.
- Low:C0G/NP0 formulations with εr below 100 deliver temperature stability for RF circuits and crystal oscillator loading. Demand clusters in South Korean telecommunications equipment and Japanese precision instrumentation.
- Medium:X5R and X7R Class 2 dielectrics balance capacitance density with moderate temperature drift for general industrial applications.
- High:Y5V and Z5U formulations maximize volumetric efficiency in cost-constrained consumer power supplies. Chinese domestic manufacturers dominate this tier for appliance and lighting applications.
- Ultra-High:Specialty relaxor ferroelectric compositions achieve εr above 10,000 for compact energy storage in pulsed power applications.
Medium dielectric constant holds installed capacity. Low is rotating up the share rankings on RF and timing precision demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys ceramic disc capacitors predominantly for domestic appliance manufacturing and export assembly networks, whereas Germany and Japan concentrate procurement on automotive-grade X7R and C0G formulations for EV powertrains and precision RF modules.
China
Domestic white goods manufacturing and telecommunications infrastructure buildout absorb high volumes of standard and Y5V dielectric grades. SAMR quality certification protocols and GB standards enforce conformity for capacitors entering renewable energy and 5G base station supply chains. Yangtze River Delta fabricators supply both local appliance OEMs and Southeast Asian export assembly operations.
Germany
Automotive tier-one suppliers specify AEC-Q200 qualified X7R capacitors for onboard chargers and DC-link filtering in EV platforms. ECHA enforcement of REACH Annex XVII restrictions accelerates laboratory testing investments and filters non-compliant Asian imports. Bavarian industrial electronics clusters anchor procurement for motor drives and grid-tied inverter applications.
Japan
Precision instrumentation and telecommunications equipment manufacturers demand C0G-class capacitors with near-zero temperature drift. METI energy efficiency frameworks indirectly shape capacitor specifications through downstream power electronics mandates. Kanto region specialists concentrate formulation expertise for temperature-stable barium titanate modifications.
United States
North American defense electronics and medical device OEMs mandate lot traceability and counterfeit avoidance protocols through franchised distributor channels. FDA quality system regulations prompt dual-sourcing strategies for implantable equipment capacitors. Midwest industrial equipment refurbishment services sustain demand for obsolete case size legacy replacements.
South Korea
Telecommunications infrastructure deployment for massive MIMO antenna arrays requires C0G-class precision capacitors for RF signal conditioning. MFDS medical device regulations align with international standards for diagnostic equipment components. Seoul Capital Area electronics clusters integrate capacitor procurement into smartphone and base station export manufacturing.
Ceramic Disc Capacitor Market Competitive Environment
Capability concentration sits with Japanese and German dielectric formulators possessing in-house material science laboratories; scale advantage sits with Chinese manufacturers leveraging domestic ceramic powder supply and high-volume contract manufacturing. The vendor base stratifies across three tiers: premium specialists with automotive qualification tracks, broad-catalog distributors serving military-aerospace verticals, and commodity fabricators competing on price for appliance applications. Dominant competitive moves include backward integration into ceramic powder production and strategic partnerships with automotive tier-one suppliers for AEC-Q200 certification support.
Within the premium formulation tier, Murata Manufacturing Co., Ltd. and TDK Corporation exemplify Japanese specialists with heritage dielectric material science capabilities. Vishay Intertechnology, Inc. occupies a position among broad-catalog competitors with distributor channel control across industrial and military-aerospace segments. These three anchors illustrate how qualification depth and geographic origin stratify competitive positioning in high-reliability capacitor procurement.
| Leading Market Players |
|---|
| TAIYO YUDEN CO., LTD. |
| YAGEO Group |
| Murata Manufacturing Co., Ltd. |
| Walsin Technology Corporation |
| Vishay Intertechnology, Inc. |
| TDK Corporation |
| SAMSUNG ELECTRO-MECHANICS |
| Johanson Dielectrics, Inc. |
| KYOCERA Corporation |
| Others |
Value Chain & Pricing Dynamics
Shanghai-Rotterdam container freight corridors transmit cost volatility from Yangtze River Delta ceramic powder mills to European automotive tier-ones, compressing margins for distributors caught between fixed long-term contracts and spot-market palladium swings. This logistics tension amplifies price stratification across AEC-Q200 qualified suppliers and commodity fabricators serving appliance OEMs.
Pricing Analysis
Long-term offtake agreements dominate procurement for automotive-grade X7R and C0G formulations, while spot-market purchasing persists for standard dielectric grades in consumer appliance applications. Price differentiation rests on REACH compliance certification and AEC-Q200 qualification depth, with German and Japanese incumbents commanding premiums against Chinese commodity suppliers. Pricing pressure stems from silver-palladium electrode cost volatility, squeezing mid-tier fabricators lacking precious metal hedging programs. Contract manufacturers represent the most price-sensitive buyer segment; medical device OEMs exhibit the least sensitivity due to FDA-mandated dual-sourcing requirements.
Supply Chain Analysis
Contract manufacturing concentration sits with Foxconn, Jabil, and Flex holding assembly capacity for telecommunications and automotive electronics verticals. Raw material supply draws from Chinese ceramic powder production, Japanese palladium refining, and German dielectric formulation expertise. Supply chain risk centers on geographic single-source vulnerability for barium titanate precursors, with approximately 60% of global ceramic powder originating from domestic Chinese manufacturers. Distribution runs through Arrow Electronics and Avnet franchised channels for military-aerospace and medical verticals requiring lot traceability protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Component lifecycle extension and refurbishment services are expanding faster than hardware unit sales, creating recurring-revenue attach opportunities for qualified suppliers with testing laboratory infrastructure. This service layer transforms transactional capacitor procurement into multi-year technical support relationships.
For Market Incumbents: Entrench AEC-Q200 qualification advantages by accelerating lead-free BME formulation deployment for 150°C automotive specifications. Deepen backward integration into ceramic powder production to offset palladium cost volatility. Defend against MLCC substitution in consumer electronics by emphasizing high-voltage disc formats for industrial motor drives where through-hole assembly persists.
For New Entrants and Emerging Players: Establish a beachhead in India's PLI-supported electronics manufacturing clusters, where domestic appliance and automotive assembly networks lack qualified local capacitor suppliers. Target renewable energy inverter manufacturers requiring high-voltage snubber capacitors with extended temperature ratings. Pursue direct technical partnership models with industrial equipment OEMs rather than distributor channel competition.
For Investors and Strategic Acquirers: Japanese dielectric formulation specialists with retiring technical talent and established METI compliance track records represent the most compelling acquisition archetype. Long-term viability hinges on material science IP retention and automotive certification pipeline depth. Watch for ECHA enforcement acceleration against non-compliant Asian imports as an inflection signal for qualified supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Powder Production | Captive supply of barium titanate precursors insulates margin from Chinese export concentration. |
| AEC-Q200 Certification Acceleration | Automotive reliability qualification opens procurement channels with German and Japanese tier-ones. |
| Lead-Free BME Formulation Deployment | ECHA REACH compliance enables continued European market access amid tightening restrictions. |
| Lifecycle Extension Service Launch | Refurbishment capabilities capture recurring revenue from industrial equipment aftermarket demand. |
| India Manufacturing Footprint Establishment | PLI scheme incentives align with domestic appliance and automotive assembly network growth. |
Study Parameters
A standing panel of dielectric formulation chemists, automotive tier-one procurement directors, and distributor channel managers provided ongoing calibration across primary interview rounds. Secondary validation drew from ECHA REACH enforcement databases, SAMR quality certification registries, SEC 10-K filings from listed component manufacturers, and customs trade data for ceramic powder imports. Bottom-up demand modeling from end-use application counts was triangulated against top-down market sizing from manufacturer revenue disclosures.
Scenario bracketing around EV powertrain electrification rates and REACH enforcement intensity shaped the analytical framework across the projection horizon. Segmentation dimensions included dielectric formulation class, voltage tolerance tier, end-use vertical, and regional regulatory cluster. CAGRs were derived from installed base growth and content-per-vehicle expansion in automotive electronics, cross-referenced with telecommunications infrastructure deployment schedules for 5G massive MIMO arrays.
Stress conditions across palladium price volatility, Chinese export restriction scenarios, and MLCC substitution acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding AEC-Q200 certification timelines and dielectric chemistry talent availability. Quarterly review of ECHA enforcement actions and automotive platform electrification announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Semiconductor Micro Components Market
Electronic Components
Battery Holders Market
Electronic Components
Audio and Visual Public Address System Market
Electronic Components
Dual Relay Board Market
Electronic Components
Special Function Data Convertors Market
Electronic Components
Multi-Layer Ceramic Capacitor (MLCC) Market
Electronic Components
Efuse Market
Electronic Components
Pulse Width Modulation Controllers Market
Electronic Components
Flex-Rigid PCB Market
Electronic Components
Capacitor Aluminum Polymer Market
Electronic Components
Global Tantalum Capacitors Market
Electronic Components
Circuit Protection Kits Market
Electronic Components
Europe PCB Market
Electronic Components
Coaxial Attenuators Market
Electronic Components
USB Wall Charger Market
Electronic Components
Audio Capacitor Market