
 RAID Controller Card Market | 2026-2036
RAID Controller Card Market Size, Share, and Industry Trends Forecast 2026-2036
RAID Controller Card Market Intelligence
Hyperscale cloud buyer concentration is expanding as Amazon Web Services, Microsoft Azure, and Google Cloud consolidate server procurement into fewer, larger contracts. Broadcom leverages its merchant silicon portfolio to supply PCIe switch and RAID controller dies to multiple OEMs. Intel sustains relevance through Optane-adjacent memory controller IP integrated into platform chipsets. Dell Technologies anchors enterprise channel volume through direct-attach storage configurations bundled with PowerEdge servers.
A RAID controller card is a dedicated expansion board that manages multiple disk drives as a unified logical unit, typically employing cache memory modules between 512 MB and 8 GB and battery or capacitor-backed write caches to ensure data integrity during power events. Its primary purpose is to provide redundancy, striping, or mirroring across drive arrays while offloading parity calculations from the host CPU in hardware RAID implementations. PCIe form factor cards now dominate performance-sensitive deployments, while SATA interfaces retain volume in cost-optimized SMB server builds. Hardware RAID technology commands premium positioning in enterprise settings, whereas software RAID gains traction in cloud-native environments where host CPU cycles are abundant and cost minimization prevails.
FCC equipment authorization requirements govern electromagnetic emissions for RAID controllers sold into US infrastructure, while the EU RoHS directive restricts hazardous substances in printed circuit board assemblies, affecting solder and capacitor chemistry choices. China's GB standards mandate energy efficiency reporting for server components entering government and state-owned enterprise tenders. Stakeholders must monitor how NMPA-aligned cybersecurity review processes for critical information infrastructure may extend to storage subsystem components, reshaping supplier qualification timelines and localization requirements.
Market Dynamics
AI training clusters are compressing storage refresh cycles and forcing RAID controller vendors to prioritize throughput density over legacy parity optimization, fundamentally restructuring how enterprise buyers evaluate controller specifications.
Growth Catalysts
- GB Standards Compliance:China's energy efficiency mandates for server components are accelerating replacement of legacy controllers in state-owned data centers, creating procurement volume for certified suppliers.
- Hyperscale Cloud Expansion:Northern Virginia and Oregon campus buildouts are consolidating demand for high-throughput PCIe Gen5 RAID solutions capable of saturating NVMe drive arrays.
- AI Workload Proliferation:Training pipeline checkpointing requirements are mandating battery-backed write cache configurations that ensure data integrity during power events.
Market Restraints
- Flash Memory Cost Volatility:NAND pricing swings directly compress controller card margins, as cache module costs represent 15-25% of bill-of-materials.
- Merchant Silicon Concentration:PCIe switch die supply concentrates among three foundry sources, exposing OEMs to allocation risk during semiconductor upcycles.
- Software RAID Substitution:Cloud-native environments with abundant host CPU cycles are displacing hardware RAID in tier-two and tier-three deployments.
Strategic Opportunities
- India Data Center Buildout:The country's PLI scheme for electronics manufacturing is attracting modular server assembly, creating localized demand for SATA-optimized controller cards.
- CE Marking Acceleration:EU CSRD-aligned sustainability reporting is favoring suppliers with documented circular economy credentials for printed circuit board assemblies.
- NVMe-oF Convergence:Controller vendors integrating RDMA offload capabilities are capturing socket space in disaggregated storage architectures.
Industry Challenges
- FCC Authorization Timelines:Electromagnetic compliance testing for new PCIe form factors extends product launch windows by 8-14 weeks.
- Firmware Talent Scarcity:Specialized engineers capable of optimizing parity calculation pipelines command premium compensation, constraining R&D scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RAID Controller Card Market |
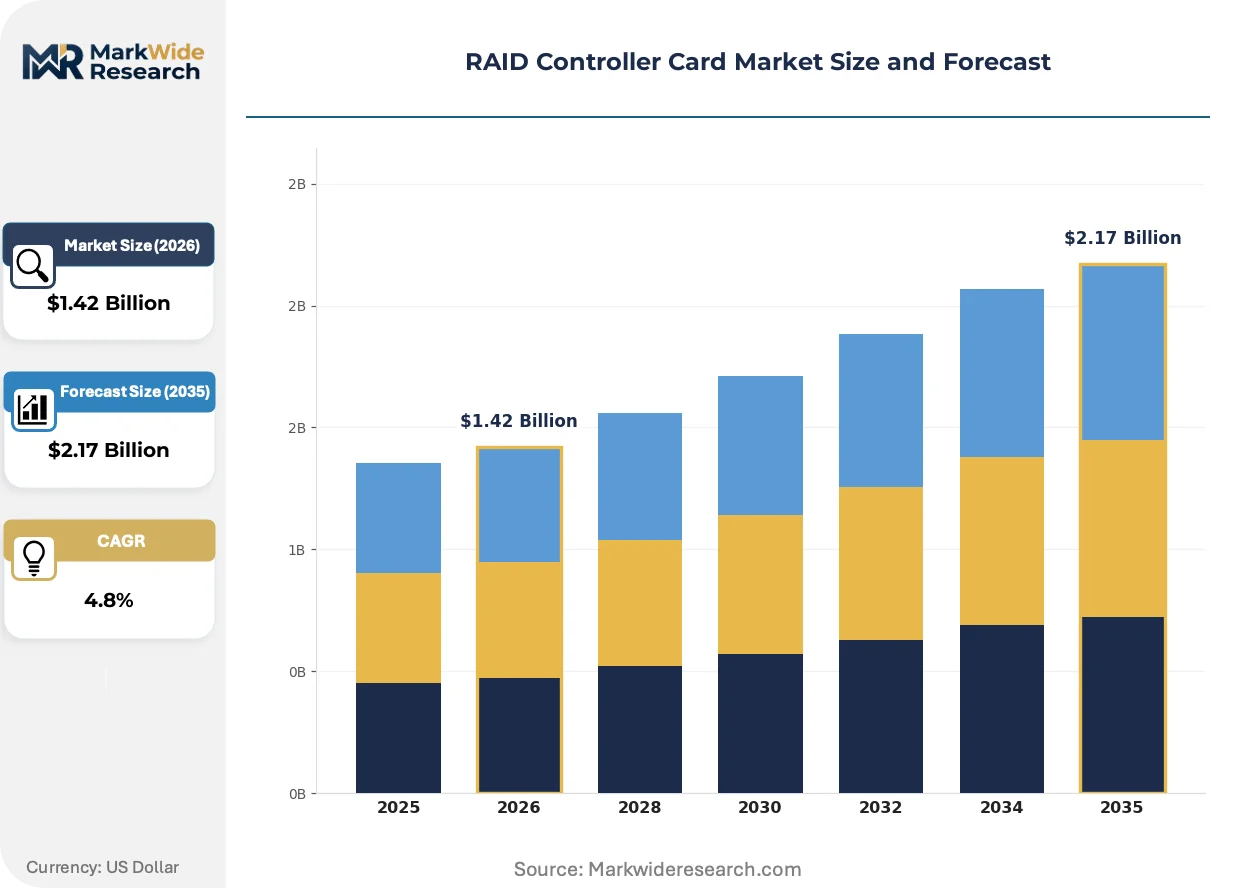
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SATA, SAS, SCSI, PCIe Technology: Hardware RAID, Software RAID, Hybrid RAID, Virtual RAID End User: Data Centers, Enterprises, SMBs, Individual Users Form Factor: Internal, External, Modular, Embedded |
| Companies Covered | Microchip Technology, Lenovo, Broadcom, HighPoint Technologies, Areca Technology, Intel, Fujitsu, Hewlett Packard Enterprise, Dell Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RAID Controller Card Market Strategic Shifts & Innovations
Storage controller architectures are bifurcating between maximum-performance hardware acceleration and software-defined flexibility, with the boundary shifting as host processor core counts expand and AI training infrastructure demands deterministic latency.
PCIe Gen5 interface technology is electrifying throughput capabilities for NVMe backplane connectivity. Hyperscale operators in United States cloud campuses are deploying these controllers at replacement velocity exceeding traditional three-year cycles. The technology is electrifying competitive positioning around queue depth handling and thermal design power specifications.
EU RoHS substance restrictions are tightening solder alloy and capacitor chemistry specifications for printed circuit board assemblies. Manufacturers serving European enterprise channels are reformulating component bills to eliminate restricted hazardous substances ahead of 2024 enforcement windows. RAID controller cards with full material disclosure documentation are capturing preferential placement in Dell Technologies and HPE supply agreements.
Hyperscale buyers are consolidating direct procurement contracts and disintermediating traditional distribution channels. Amazon Web Services and Microsoft Azure now negotiate controller die supply directly with merchant silicon vendors, bypassing branded card OEMs for custom mezzanine designs. This pattern concentrates most visibly in United States cloud infrastructure buildouts where volume thresholds justify non-standard form factors.
RAID Controller Card Market Segmentation
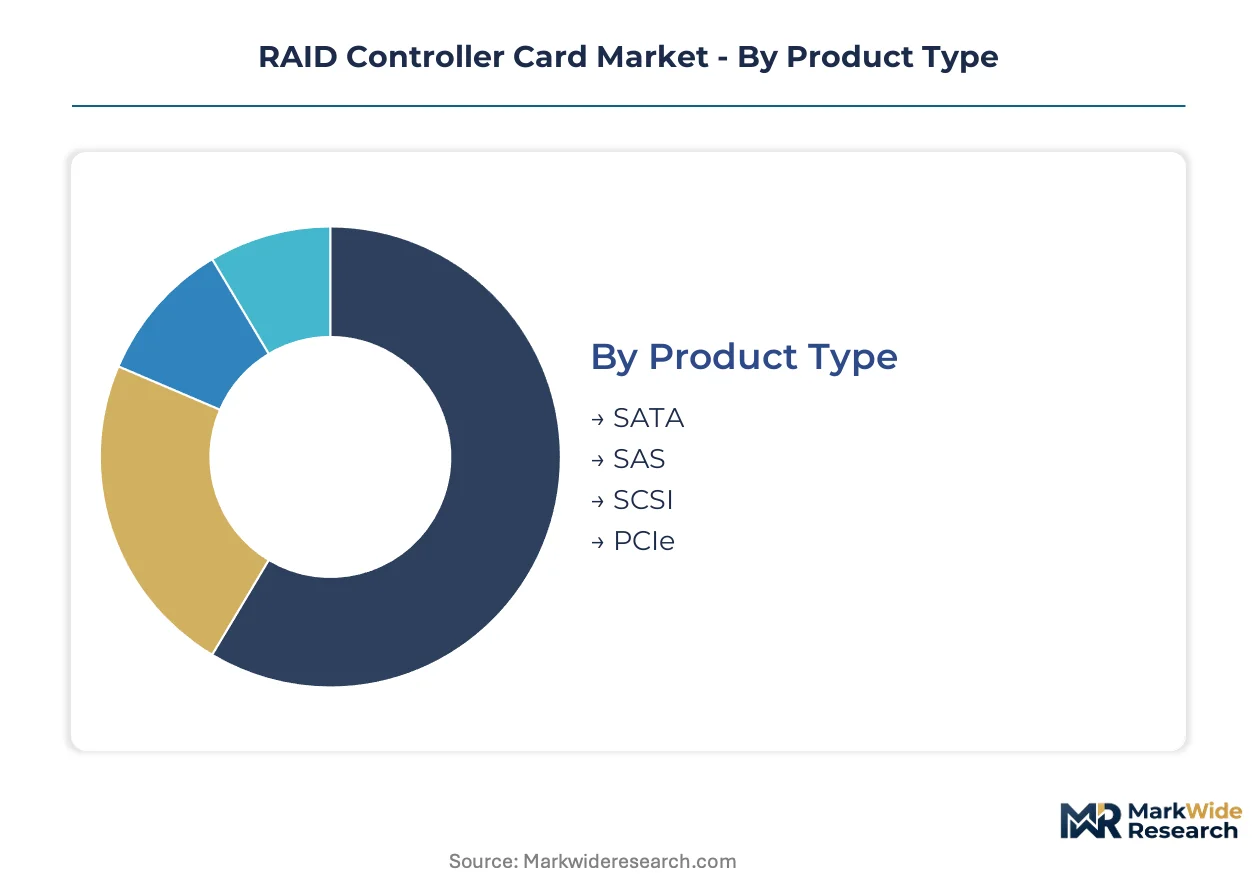
RAID controller segmentation reveals how procurement priorities diverge between hyperscale operators optimizing for throughput density and cost-conscious buyers prioritizing interoperability. Understanding these fault lines exposes where vendor R&D investments concentrate and which specifications command pricing premiums.
Product Type:
Interface selection traces the customization-standardization spectrum from legacy compatibility requirements to bleeding-edge throughput demands.
- PCIe:Gen5 interface technology saturates NVMe backplane connectivity with lane speeds reaching 32 GT/s. United States hyperscale campuses in Northern Virginia and Oregon deploy these controllers at replacement velocities exceeding traditional refresh cycles, driven by AI training checkpointing requirements.
- SAS:Serial Attached SCSI maintains enterprise relevance through dual-port drive support and established ecosystem compatibility. Data center operators in Germany and Japan specify SAS controllers for tiered storage hierarchies where reliability documentation outweighs raw bandwidth specifications.
- SATA:Cost-optimized interface retains volume in SMB server builds and legacy infrastructure refresh cycles.
- SCSI:Parallel SCSI persists in specialized industrial and medical imaging equipment requiring deterministic legacy bus timing.
Leading the category by volume: SATA. Growing fastest: PCIe.
Technology:
Architecture choice splits between deterministic hardware acceleration and flexible software abstraction, with deployment context dictating optimal configuration.
- Hardware RAID:Dedicated ASICs offload parity calculations from host CPUs, employing cache modules between 512 MB and 8 GB with battery or capacitor-backed write protection. Enterprise data centers specify hardware RAID for mission-critical workloads where deterministic latency and power-loss data integrity are non-negotiable.
- Software RAID:Host-processor execution eliminates controller card cost while consuming CPU cycles abundant in cloud-native environments. Hyperscale operators in United States cloud campuses increasingly deploy software RAID in tier-two storage tiers where cost minimization prevails over performance guarantees.
- Hybrid RAID:Combines hardware acceleration for critical operations with software flexibility for routine tasks.
- Virtual RAID:Hypervisor-abstracted storage pooling enables dynamic array reconfiguration without physical hardware changes.
Hardware RAID dominates enterprise procurement by revenue. Software RAID is expanding most quickly in cloud-native deployments.
End User:
Buyer sophistication and procurement scale create distinct specification requirements across organizational tiers.
- Data Centers:Hyperscale and colocation facilities specify high-throughput PCIe Gen5 controllers with NVMe-oF offload capabilities. China's state-owned enterprises under GB standards compliance mandates are accelerating replacement of legacy controllers, creating certified supplier procurement volume.
- Enterprises:Direct-attach storage configurations bundled with server platforms dominate procurement, with Dell Technologies and HPE supply agreements favoring vendors with full EU RoHS material disclosure documentation.
- SMBs:Cost-optimized SATA controllers satisfy limited storage expansion requirements.
- Individual Users:Prosumer workstation builds represent minimal volume with high specification sensitivity.
Data centers command the highest average selling prices. SMBs represent the largest unit volume.
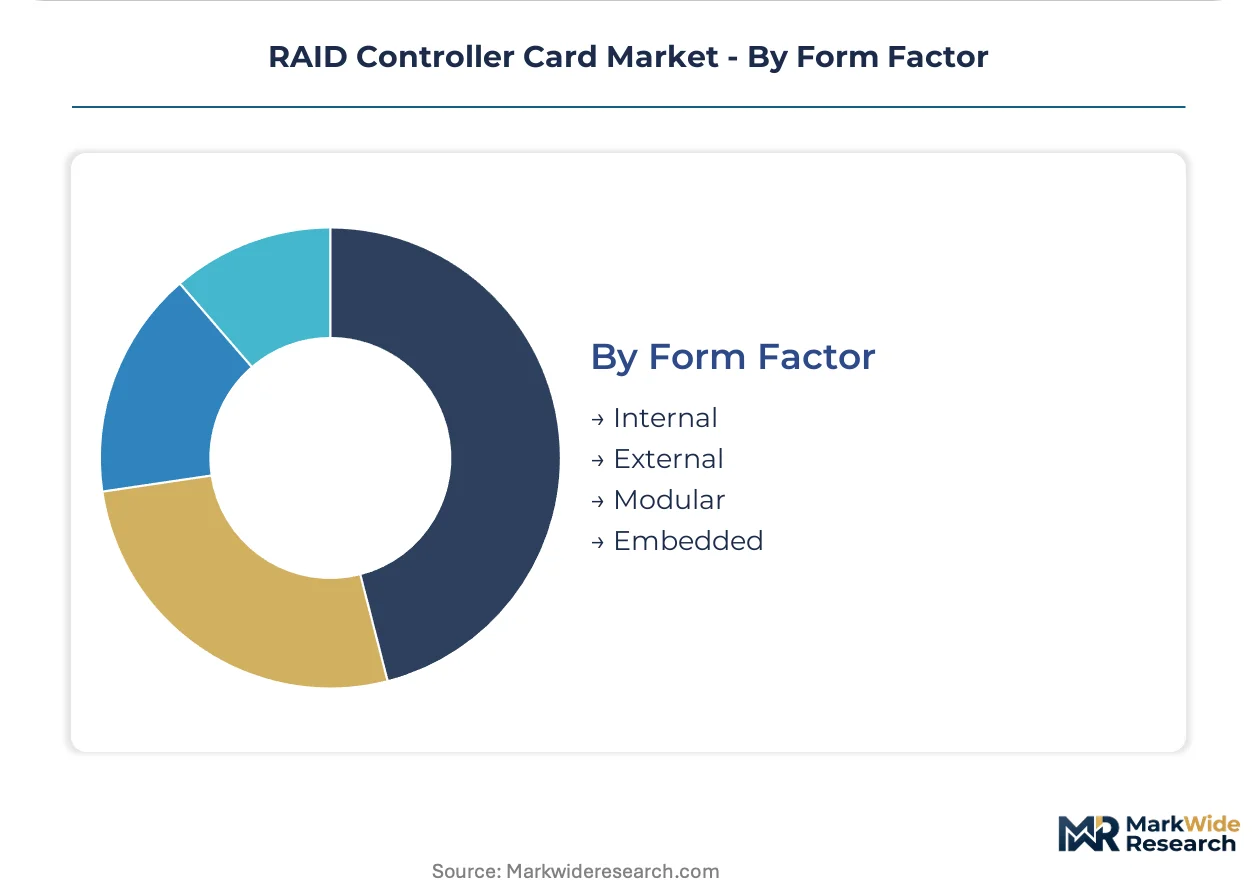
Form Factor:
Physical integration method determines thermal design constraints and serviceability profiles across deployment scenarios.
- Internal:PCIe slot-mounted cards dominate performance-sensitive deployments with standardized thermal envelopes and field-replaceable cache modules.
- External:JBOD connectivity via SAS expanders serves high-density storage enclosures requiring separate controller accessibility.
- Modular:Hot-swappable mezzanine designs enable controller replacement without server downtime.
- Embedded:Chipset-integrated controllers on server motherboards eliminate expansion slot consumption for base storage requirements.
Internal cards lead by revenue concentration. Modular designs are climbing the fastest as disaggregated storage architectures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale cloud operators in Northern Virginia and Oregon drive bulk purchasing of high-throughput RAID solutions, concentrating procurement volume in the United States while China's GB standards reshape state-owned enterprise tenders.
United States
Amazon Web Services and Microsoft Azure negotiate controller die supply directly with merchant silicon vendors for custom mezzanine designs. FCC equipment authorization requirements govern electromagnetic emissions for RAID controllers sold into US infrastructure. Northern Virginia and Oregon hyperscale campuses deploy PCIe Gen5 controllers at replacement velocities exceeding traditional refresh cycles.
China
State-owned data centers are accelerating replacement of legacy controllers under dual carbon goals and GB standards for energy-efficient electronics. NMPA-aligned cybersecurity review processes for critical information infrastructure may extend qualification timelines for storage subsystem components. Beijing and Shanghai data center clusters prioritize certified suppliers meeting localization requirements.
Germany
Data center operators specify SAS controllers for tiered storage hierarchies where reliability documentation outweighs raw bandwidth specifications. EU RoHS directive restrictions on hazardous substances in printed circuit board assemblies affect solder and capacitor chemistry choices. Frankfurt and Munich colocation facilities favor vendors with full material disclosure documentation.
Japan
Enterprise buyers prioritize deterministic latency and power-loss data integrity for mission-critical workloads. METI oversight shapes procurement standards for data center infrastructure components. Tokyo and Osaka industrial clusters maintain demand for hardware RAID configurations with battery-backed write cache protection.
India
The PLI scheme for electronics manufacturing attracts modular server assembly, creating localized demand for SATA-optimized controller cards. BIS certification requirements govern server component quality standards for government tenders. Maharashtra and Karnataka data center buildouts concentrate procurement for cost-sensitive deployments.
RAID Controller Card Market Key Industry Players
United States-based semiconductor giants anchor the premium controller tier; Taiwan and China specialists hold volume positions in cost-optimized SATA implementations. Merchant silicon vendors supply PCIe switch and RAID controller dies to multiple OEMs, creating a tiered structure where branded card manufacturers compete on firmware differentiation and thermal design. Three archetypes dominate: merchant silicon suppliers, branded controller OEMs, and server platform integrators. Competitive moves concentrate on direct procurement contract consolidation and custom mezzanine form factor development.
Within the merchant silicon tier, Broadcom and Intel occupy positions supplying core controller technology to downstream OEMs. Microchip Technology exemplifies the branded controller specialist archetype, while Dell Technologies and Hewlett Packard Enterprise anchor enterprise channel volume through direct-attach storage configurations bundled with server platforms. Lenovo and Fujitsu represent Asia-Pacific platform integrators competing on supply chain proximity to regional data center buildouts.
| Leading Market Players |
|---|
| Microchip Technology |
| Lenovo |
| Broadcom |
| HighPoint Technologies |
| Areca Technology |
| Intel |
| Fujitsu |
| Hewlett Packard Enterprise |
| Dell Technologies |
| Others |
Cost & Logistics Intelligence
Merchant silicon sourcing from Taiwan and South Korea anchors supply positioning for PCIe switch dies, while GB standards compliance in China and FCC authorization in the United States create tiered certification costs that stratify pricing power across branded controller OEMs and direct-procurement hyperscale buyers.
Pricing Analysis
Volume concentration in SATA controllers serving India's PLI-driven modular assembly competes against margin capture in PCIe Gen5 solutions for United States hyperscale campuses. Three-tier pricing structure across premium hardware RAID, standard SAS configurations, and economy SATA cards reflects cache module capacity and battery-backup certification levels. Cost compression in the SATA tier intensifies because NAND flash volatility squeezes controller card margins where cache represents substantial bill-of-materials exposure. SMB buyers in India and legacy enterprise refresh cycles exhibit highest price sensitivity, while United States cloud operators negotiating direct die supply sacrifice margin for throughput density guarantees.
Supply Chain Analysis
Refurbishment flows for cache modules and capacitor-backed write buffers extend component lifecycles in European enterprise channels where EU RoHS documentation requirements favor circular-economy-certified suppliers. Controller die fabrication concentrates in Taiwan, South Korea, and the United States, while PCB assembly for cost-optimized SATA cards draws from China and Vietnam. Raw material dependencies span NAND flash from Samsung and SK Hynix facilities, specialty capacitors from Japanese suppliers, and RoHS-compliant solder alloys reformulated for European enforcement windows. Single-source vulnerability in PCIe switch die allocation during semiconductor upcycles exposes OEMs to foundry rationing. Distribution runs through direct-procurement contracts with hyperscale operators and tiered channel partnerships for enterprise server bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's GB standards for energy-efficient server components erect a compliance moat that filters out uncertified suppliers from state-owned data center tenders, transforming energy reporting from a cost center into a barrier-to-entry mechanism for qualified players.
For Market Incumbents: Extend firmware optimization pipelines for PCIe Gen5 queue depth handling to defend socket space against software RAID substitution in tier-two cloud deployments. Deepen backward integration into cache module sourcing to buffer NAND pricing volatility compressing hardware RAID margins. Prioritize thermal design power reduction to meet China's dual carbon procurement criteria ahead of localization mandates tightening supplier qualification timelines. For New Entrants and Emerging Players: NVMe-oF RDMA offload capabilities offer a technology-first wedge into disaggregated storage architectures where incumbent controller vendors lack mature software-defined integration. Target India's Maharashtra and Karnataka data center buildouts with SATA-optimized cards certified under BIS quality standards for government tenders. Pursue white-label partnerships with modular server assemblers benefiting from PLI scheme incentives rather than competing directly for hyperscale direct-procurement contracts. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by merchant silicon suppliers seeking branded controller firmware differentiation or server platform integrators filling direct-attach storage gaps. Long-term viability hinges on positioning within AI training infrastructure refresh cycles where checkpointing requirements sustain battery-backed write cache demand. Watch for NMPA-aligned cybersecurity review processes extending to storage subsystems as the signal indicating qualification timeline inflection and localization premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| GB Standards Certification Investment | Unlocks state-owned data center procurement volume under China's dual carbon mandates. |
| PCIe Gen5 Thermal Design Optimization | Captures hyperscale replacement velocity exceeding traditional refresh cycles in United States campuses. |
| Firmware Talent Acquisition Pipeline | Addresses parity calculation engineer scarcity constraining R&D scaling for hardware RAID vendors. |
| EU RoHS Material Disclosure Documentation | Secures preferential placement in Dell Technologies and HPE supply agreements for European channels. |
| NVMe-oF RDMA Offload Integration | Captures socket space in disaggregated storage architectures displacing traditional controller form factors. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with data center procurement officers, server platform engineers, RAID controller firmware architects, and semiconductor distribution channel managers. SEC 10-K disclosures from merchant silicon suppliers, FCC equipment authorization databases, China's GB standards certification registries, and EU RoHS compliance documentation provided demand-side validation. Bottom-up triangulation across controller card shipment volumes and top-down reconciliation against hyperscale capex disclosures ensured cross-verification of market sizing.
Segment-level granularity modeled product type across PCIe, SAS, SATA, and SCSI interfaces; technology split between hardware, software, hybrid, and virtual RAID architectures; end user tiers spanning hyperscale data centers, enterprises, SMBs, and individual users; and form factor categories including internal, external, modular, and embedded configurations. CAGR derivation incorporated NAND flash pricing cycle impacts, AI training workload proliferation rates, and regulatory compliance timeline shifts across the projection horizon. Industry-specific inputs included PCIe Gen5 adoption velocity in United States cloud campuses and GB standards replacement acceleration in China's state-owned infrastructure.
Several conditions sit outside the modeled scope, including unforeseen semiconductor foundry allocation shocks, abrupt shifts in hyperscale software RAID deployment preferences, and geopolitical disruptions to Taiwan-based controller die supply. Forecasts reflect assumptions regarding sustained AI training infrastructure investment, stable NAND pricing recovery trajectories, and continued enforcement of China's dual carbon procurement criteria. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Aluminum Electrolytic Capacitor Market
Electronic Components
Printed Circuit Board Market
Electronic Components
Capacitor Aluminum Polymer Market
Electronic Components
Microcontroller Socket Market
Electronic Components
Plastics in Consumer Electronics Market
Electronic Components
Loudspeaker Market
Electronic Components
US Supercapacitor Market
Electronic Components
Global DC Motor Control Devices Market
Electronic Components
Single Layer Capacitors Market
Electronic Components
Handheld Devices Battery Market
Electronic Components
North America Safety Relay and Timers Market
Electronic Components
Chip Shield Market
Electronic Components
Digital Potentiometer Market
Electronic Components
Data Acquisition Hardware Market
Electronic Components
Power Resistor Market
Electronic Components
Asia-Pacific USB Retimer Market