
 Graphene Lighting Market | 2026-2036
Graphene Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Graphene Lighting Market Insights
EU RoHS recast is restructuring material compliance costs for entrants without in-house toxicology testing. Graphenea sustains European supply chain credibility through its Barcelona-based CVD graphene production. Samsung Electronics dominates downstream integration by leveraging its captive semiconductor foundries for LED driver co-packaging. First Graphene anchors raw material security through its Sri Lankan vein graphite reserves and Australian processing assets.
Graphene lighting denotes luminaire systems incorporating graphene or graphene oxide as thermal spreaders, transparent conductive electrodes, or phosphor hosts, typically achieving thermal conductivity exceeding 1000 W/mK in spreader applications and sheet resistance below 100 ohms/sq in electrode configurations. The primary purpose is to extract heat from high-power LED junctions or enable flexible OLED form factors inaccessible to indium tin oxide. LED product lines currently occupy the largest revenue share due to retrofit infrastructure compatibility, while OLED segments are capturing premium positioning in automotive interior contour lighting where conformal shapes outweigh cost sensitivity. Flexible lighting technology leads patent filing velocity, though solid-state lighting retains the broadest installed base across commercial retrofit projects.
The US EPA Energy Star program and California Title 20 appliance efficiency regulations jointly shape product certification requirements for North American market access, while EU REACH governs graphene nanoparticle registration obligations for importers. China's GB standards for solid-state lighting safety, administered by SAMR, create additional testing burdens for exporters without domestic certification partnerships. Stakeholders must monitor how evolving graphene substance classifications under ECHA's nanoform reporting requirements will alter documentation costs relative to conventional carbon additive baselines.
Market Dynamics
The EU Ecodesign Directive's tightening luminous efficacy minimums are restructuring import compliance costs while automotive exterior lighting programs at BMW and Volkswagen accelerate graphene-enhanced LED prototyping cycles.
Growth Catalysts
- Thermal Performance Mandates:The EU Ecodesign Directive's escalating minimums for luminous efficacy are disqualifying conventional aluminum heat-sink designs, forcing luminaire importers toward graphene thermal spreaders exceeding 1000 W/mK conductivity.
- Automotive Form Factor Requirements:Conformal interior contour lighting specifications from German OEMs are absorbing graphene transparent conductive electrodes as ITO alternatives for flexible OLED substrates in curved dashboard applications.
- Co-Located Production Clusters:South Korea's Gwangju corridor concentration of Samsung Electronics and Seoul Semiconductor pilot lines is compressing graphene-LED driver co-packaging development timelines through shared metrology infrastructure.
Market Restraints
- Vein Graphite Supply Concentration:Sri Lankan vein graphite reserves anchor raw material security for First Graphene and similar processors, creating geographic single-point vulnerability for European CVD graphene production dependent on imported flake precursors.
- REACH Nanoform Documentation Burden:ECHA's evolving graphene substance classifications under nanoform reporting requirements are inflating registration costs by 40-60% relative to conventional carbon additive baselines for importers lacking in-house toxicology testing.
- Indium Tin Oxide Price Volatility:ITO spot market fluctuations are compressing graphene electrode cost competitiveness windows, particularly for flexible lighting segments where sheet resistance below 100 ohms/sq must match ITO's 10-30 ohms/sq performance at scale.
Strategic Opportunities
- Retrofit Infrastructure Compatibility:Solid-state LED product lines retain the broadest installed base across commercial retrofit projects, creating white space for graphene thermal spreader retrofits in existing high-bay and street lighting fixtures without luminaire replacement.
- Flexible OLED Premium Positioning:Automotive interior contour lighting applications where conformal shapes outweigh cost sensitivity are absorbing graphene transparent conductive electrodes at 3-5x material cost premiums versus rigid alternatives.
- US EPA Energy Star Certification Pathway:The joint shaping of product certification requirements by Energy Star and California Title 20 regulations is creating regulatory tailwinds for graphene-enhanced luminaires meeting efficacy thresholds that conventional designs cannot sustain.
Industry Challenges
- CVD Process Technician Scarcity:Barcelona-based production at Graphenea and similar European CVD facilities faces talent gaps in plasma-enhanced chemical vapor deposition operation and defect metrology, constraining yield ramp rates.
- Multi-Standard Certification Timelines:Luminaire exporters must sequentially satisfy China's GB standards administered by SAMR, EU REACH nanoform obligations, and US EPA Energy Star requirements, extending time-to-revenue by 8-14 months.
- Legacy Driver Integration Complexity:Graphene-LED junction thermal management improvements require recalibration of existing driver electronics designed for aluminum heat-sink thermal profiles, creating retrofit friction in installed base upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Graphene Lighting Market |
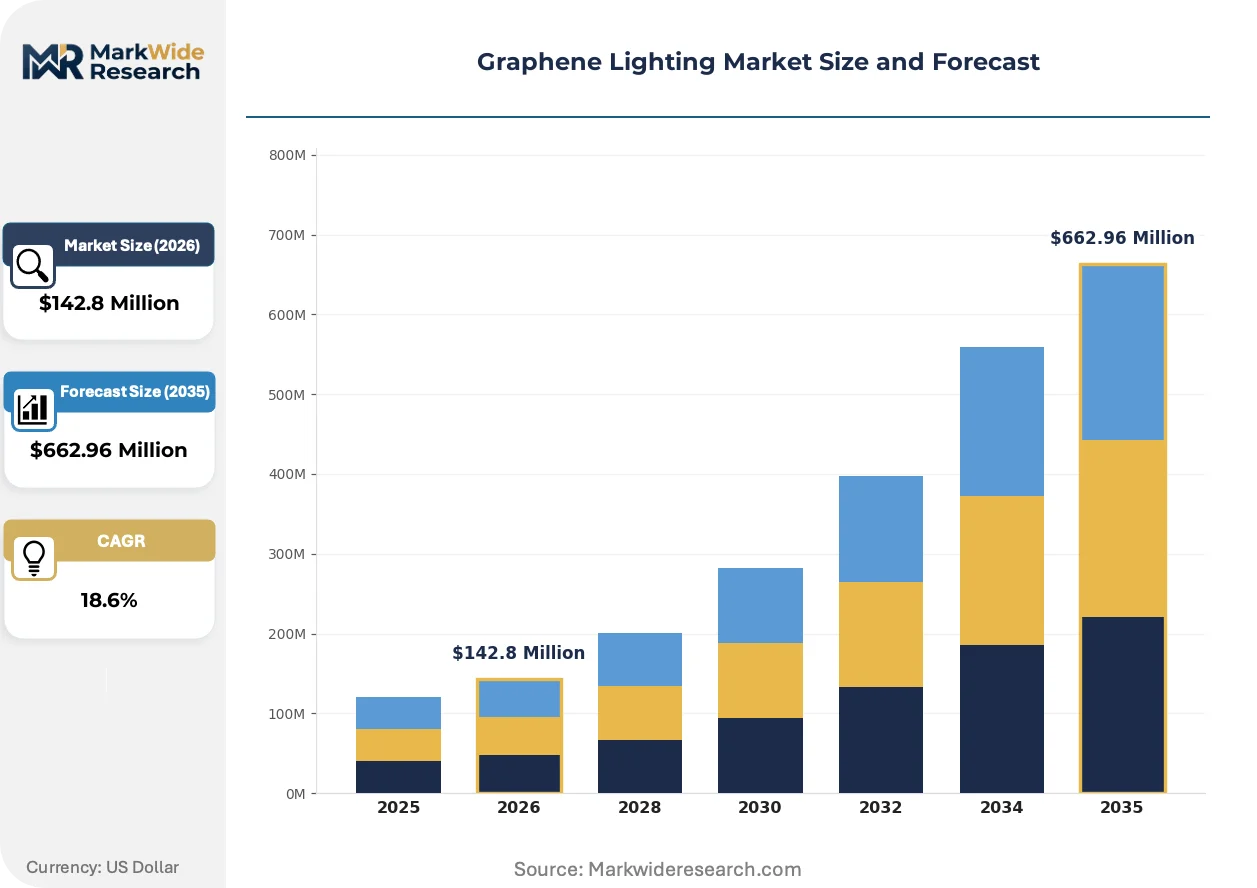
| Market Size in 2026 | $142.8 Million |
| Market Size in 2035 | $662.96 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, OLED, Light Panels, Light Bulbs Application: Commercial, Residential, Automotive, Industrial Technology: Flexible Lighting, Smart Lighting, Solid-State Lighting, Energy-Efficient End User: Homeowners, Businesses, Manufacturers, Retailers |
| Companies Covered | Applied Graphene Materials, Graphenea, AIXTRON SE, First Graphene, Samsung Electronics, Graphene Lighting PLC, CHARMGRAPHENE Co., Ltd, G6 Materials Corp., Versarien, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Graphene Lighting Market Trends and Innovations
Graphene oxide phosphor hosts are absorbing thermal management functions previously handled by discrete heat-sink assemblies, while regulatory frameworks across the EU, US, and China are hardening material compliance requirements simultaneously.
Chemical vapor deposition graphene is absorbing transparent conductive electrode functions in flexible OLED form factors previously inaccessible to indium tin oxide. Automotive tier-one suppliers are adopting CVD graphene at pilot scale for interior contour lighting where conformal curvature requirements exceed ITO's fracture limits. The technology is absorbing premium positioning in automotive segments while compressing cost reduction timelines for commercial lighting through shared CVD reactor utilization across display and illumination applications.
The EU RoHS recast is restructuring material compliance costs for luminaire entrants without in-house toxicology testing capabilities. Industrial consequence includes mandatory substance restriction documentation for graphene nanoparticle imports that previously flowed under general carbon additive classifications. LED retrofit product lines face the most acute documentation burden as they target price-sensitive commercial segments where compliance cost absorption is least feasible.
Buyer certification-driven preference shifts are displacing specification-by-specification procurement in municipal and commercial retrofit channels. Lighting contractors are consolidating vendor relationships around pre-certified graphene-enhanced luminaire suppliers who carry Energy Star, CE marking, and GB standard documentation. This consolidation is most visible in California's Title 20 enforcement zone where non-compliant inventory carries distributor liability exposure.
Graphene Lighting Market Segmentation
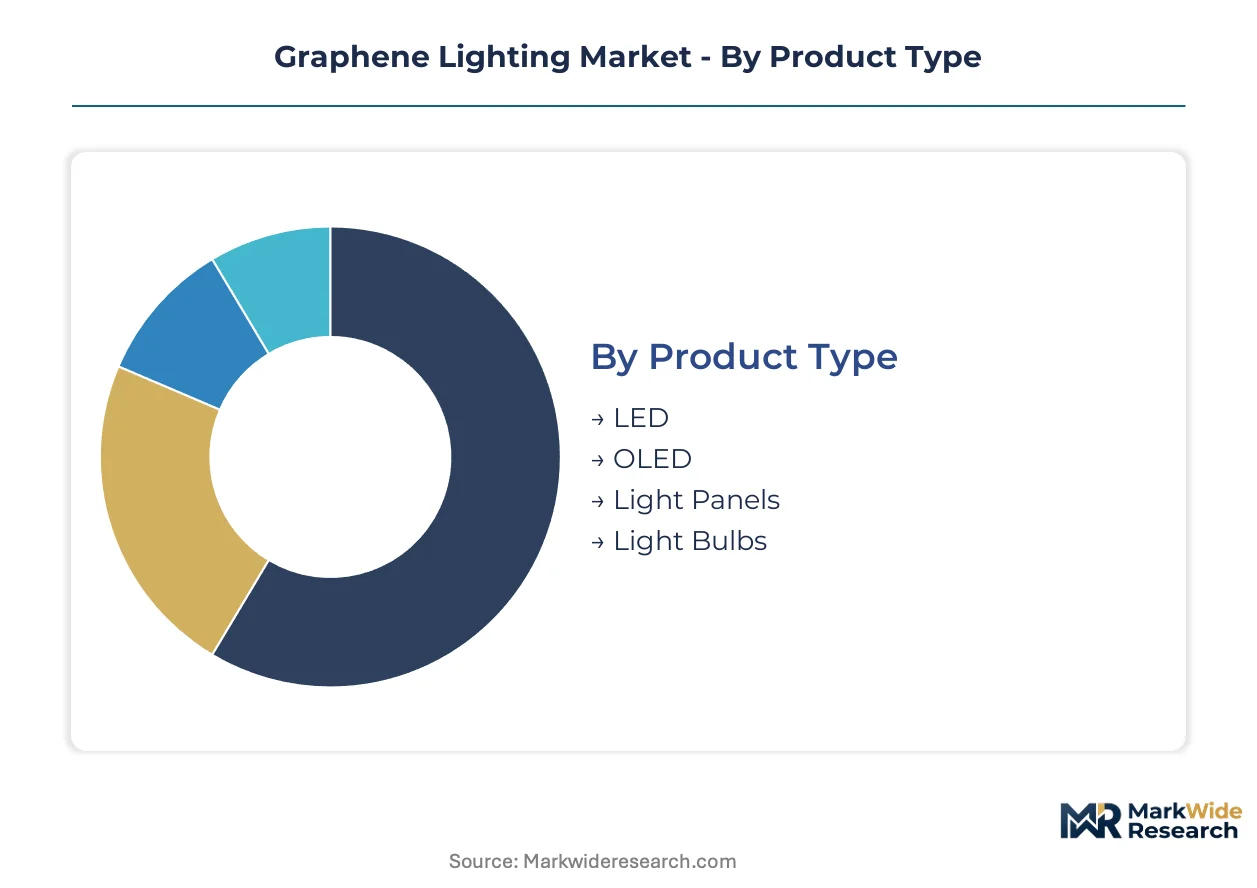
Graphene lighting architectures diverge sharply across thermal management intensity, form factor flexibility requirements, and certification complexity. Product type selection dictates whether graphene functions as a passive thermal spreader or an active transparent electrode, while application context determines the balance between material cost premiums and performance mandates.
Product Type:
Buyers differentiate primarily by retrofit compatibility versus form factor innovation potential, with thermal conductivity specifications and driver integration complexity as secondary filters.
- LED:Graphene thermal spreaders exceeding 1000 W/mK conductivity extract heat from high-power junctions in retrofit street and high-bay fixtures. Demand concentrates in South Korea's Gwangju corridor, where Samsung Electronics and Seoul Semiconductor compress co-packaging timelines through shared metrology infrastructure.
- OLED:Graphene transparent conductive electrodes enable curved dashboard contour lighting for German automotive OEMs, with sheet resistance below 100 ohms/sq replacing ITO where conformal shapes outweigh cost sensitivity. BMW and Volkswagen exterior lighting programs are accelerating pilot production cycles.
- Light Panels:Large-area graphene deposition enables uniform thermal distribution across architectural surface illumination systems.
- Light Bulbs:Standardized form factors limit graphene integration to thermal management retrofits in existing Edison-base infrastructure.
Volume sits with LED; growth tilts toward OLED.
Application:
Margin capture potential separates specification-driven procurement from price-sensitive retrofit markets, with regulatory enforcement intensity as the decisive variable.
- Commercial:Retrofit infrastructure dominates installed base across office and retail environments, creating white space for graphene thermal spreader upgrades without full luminaire replacement. California Title 20 enforcement drives distributor consolidation around pre-certified suppliers.
- Automotive:Interior contour lighting specifications from German OEMs absorb graphene transparent conductive electrodes at 3-5x material cost premiums, with conformal curvature requirements exceeding ITO fracture limits.
- Residential:Price sensitivity constrains graphene adoption to premium fixture tiers with Energy Star certification differentiation.
- Industrial:High-bay applications prioritize thermal performance over form factor, favoring solid-state LED configurations with graphene-enhanced heat extraction.
Revenue concentrates in automotive; expansion velocity is steepest in commercial retrofit channels.
Technology:
Patent filing velocity and manufacturing maturity create divergent investment horizons across flexible substrate development and established solid-state platforms.
- Solid-State Lighting:Broadest installed base across commercial retrofit projects retains infrastructure compatibility advantages, with graphene thermal spreaders slotting into existing aluminum heat-sink geometries.
- Flexible Lighting:CVD graphene deposition enables OLED form factors inaccessible to indium tin oxide, with automotive tier-one suppliers adopting pilot-scale production for curved dashboard applications.
- Smart Lighting:Driver electronics integration requires recalibration for graphene-LED junction thermal profiles, creating retrofit friction in installed base upgrades.
- Energy-Efficient:EU Ecodesign Directive luminous efficacy minimums disqualify conventional designs, forcing importers toward graphene thermal solutions exceeding regulatory thresholds.
Deployment scale favors solid-state lighting; patent momentum clusters in flexible substrate technologies.
End User:
Technical specification authority and compliance documentation access determine graphene adoption feasibility across fragmented procurement channels.
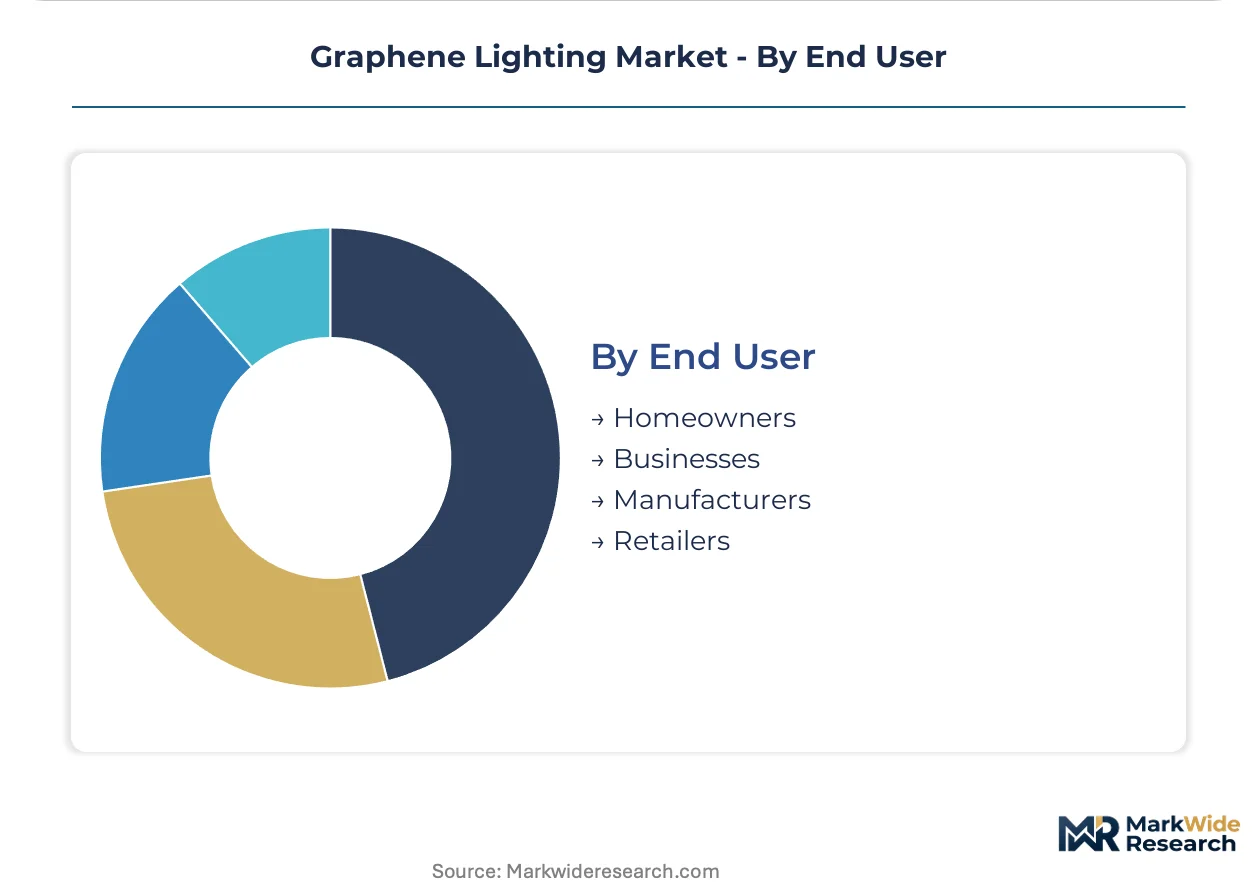
- Businesses:Municipal and commercial retrofit contractors consolidate vendor relationships around pre-certified suppliers carrying Energy Star, CE marking, and GB standard documentation.
- Manufacturers:Automotive tier-one suppliers and luminaire OEMs control graphene integration specifications, with co-located production clusters compressing development timelines.
- Homeowners:Retail channel access limits exposure to premium-tier certified products with visible graphene thermal performance claims.
- Retailers:Distributor liability exposure under California Title 20 drives inventory preference for pre-documented compliant SKUs.
Specification authority rests with manufacturers; procurement consolidation runs through business channel intermediaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gwangju's free economic zone designation accelerates graphene-LED pilot line concentration through tax incentives and shared metrology infrastructure. South Korea anchors production gravity through Samsung Electronics and Seoul Semiconductor co-location. Regulatory divergence across the EU, US, and China fragments certification pathways for luminaire exporters.
United States
California Title 20 appliance efficiency regulations and EPA Energy Star certification jointly reshape distributor inventory preferences. The US EPA program mandates luminous efficacy thresholds that conventional aluminum heat-sink designs cannot sustain. Procurement consolidation runs through pre-certified suppliers in the California enforcement zone where non-compliant inventory carries liability exposure.
Germany
BMW and Volkswagen exterior lighting programs absorb graphene-enhanced LED prototypes for conformal automotive applications. The EU Ecodesign Directive's escalating minimums disqualify conventional luminaire designs for import. Automotive tier-one suppliers in Bavaria and Baden-Württemberg pilot CVD graphene deposition for curved dashboard OLED substrates.
South Korea
Samsung Electronics dominates downstream integration through captive semiconductor foundries for LED driver co-packaging. The country's national industrial regulator enforces GB-standard-aligned safety protocols for solid-state lighting exports. Gwangju corridor concentration compresses development timelines through shared metrology infrastructure between Samsung Electronics and Seoul Semiconductor.
Spain
Graphenea sustains European supply chain credibility through Barcelona-based CVD graphene production. The EU REACH nanoform reporting requirements inflate registration costs for graphene nanoparticle imports relative to conventional carbon additive baselines. Catalonia-based production faces talent gaps in plasma-enhanced chemical vapor deposition operation and defect metrology.
China
SAMR-administered GB standards for solid-state lighting safety create testing burdens for exporters without domestic certification partnerships. The country's dual carbon goals accelerate energy-efficient luminaire procurement in municipal retrofit channels. Yangtze River Delta manufacturing clusters absorb graphene thermal spreader production for high-bay industrial LED fixtures.
Graphene Lighting Market Competitive Landscape
European producers anchor one tier through CVD graphene specialization; East Asian fabricators hold downstream integration advantages through captive LED foundries. The vendor base stratifies across raw material security holders, deposition equipment suppliers, and luminaire OEMs with in-house thermal management design. Three archetypes dominate: vein graphite reserve holders, CVD reactor operators, and semiconductor-integrated lighting manufacturers. Capacity expansion and strategic partnerships constitute the primary competitive vectors as firms seek to compress multi-standard certification timelines.
Among European CVD specialists, Graphenea exemplifies the reactor-operator archetype through its Barcelona-based production positioning. First Graphene anchors the raw-material-security tier through Sri Lankan vein graphite reserves and Australian processing assets. Samsung Electronics occupies the semiconductor-integrated manufacturer position, leveraging captive foundry capacity for LED driver co-packaging in the Gwangju corridor.
| Leading Market Players |
|---|
| Applied Graphene Materials |
| Graphenea |
| AIXTRON SE |
| First Graphene |
| Samsung Electronics |
| Graphene Lighting PLC |
| CHARMGRAPHENE Co., Ltd |
| G6 Materials Corp. |
| Versarien |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between Energy Star-compliant graphene luminaires and uncertified commodity alternatives manifests in dual pricing regimes and geographically fragmented supply configurations. Premium-tier suppliers command material cost absorption capacity through pre-certified documentation bundles, while commodity importers face margin compression from sequential multi-standard testing timelines.
Pricing Analysis
Expedited lead-time premiums dominate contract negotiations for automotive tier-one suppliers facing BMW and Volkswagen prototype deadlines, while spot inventory of CVD graphene feedstock trades at discounts to long-term offtake agreements. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden differentiation, with EU REACH nanoform documentation inflating registration costs for importers lacking in-house toxicology testing. Cost compression in economy-tier LED retrofits intensifies because aluminum heat-sink alternatives face disqualification under tightening Ecodesign Directive minimums. Municipal procurement contractors exhibit highest price sensitivity, while German automotive OEMs absorb 3-5x material premiums for conformal OLED specifications.
Supply Chain Analysis
Freight cost volatility from Sri Lankan vein graphite exports to European CVD processing hubs compounds raw material security concerns for Barcelona-based production facilities. Supply concentrates in South Korea's Gwangju corridor for downstream LED driver co-packaging, Spain's Catalonia region for CVD graphene deposition, and China's Yangtze River Delta for high-bay industrial fixture assembly. Raw material dependencies span Sri Lankan vein graphite reserves, copper interconnect substrates, and specialty gas precursors for plasma-enhanced deposition. Single-source vulnerability from geographic concentration of vein graphite extraction threatens European production continuity. Distribution runs through consolidated lighting contractor channels in California's Title 20 enforcement zone, where distributor liability exposure drives pre-certified inventory preference.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into raw material reserves and captive semiconductor foundry capacity constitutes the decisive competitive race, with First Graphene's vein graphite holdings and Samsung Electronics' LED driver co-packaging exemplifying divergent upstream and downstream leverage strategies.
For Market Incumbents: Cement supply chain credibility through Barcelona-based CVD production positioning and REACH nanoform registration pre-clearance, defending against emerging Asian entrants with faster certification timelines. Prioritize talent acquisition in plasma-enhanced chemical vapor deposition operation to address yield ramp constraints. Lock in long-term vein graphite offtake agreements before Sri Lankan reserve access tightens.
For New Entrants and Emerging Players: Lighting contractors in California's Title 20 enforcement zone represent the most penetrable channel partner type, given distributor liability exposure and pre-certified supplier consolidation. Target commercial retrofit segments where graphene thermal spreader retrofits slot into existing aluminum heat-sink geometries without full luminaire replacement. Pursue co-development partnerships with municipal procurement offices seeking Energy Star-compliant high-bay fixtures.
For Investors and Strategic Acquirers: Re-rating potential sits with CVD reactor operators possessing in-house toxicology testing capabilities given ECHA's evolving nanoform documentation requirements. Long-term viability over a multi-year horizon hinges on regulatory compliance infrastructure rather than pure deposition scale. Watch for inflection signals in automotive interior contour lighting adoption rates at German OEMs, where conformal OLED specifications currently absorb 3-5x material premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vein Graphite Reserves | First Graphene's Sri Lankan holdings anchor raw material security against supply concentration risk. |
| CVD Reactor Capacity Expansion | Graphenea's Barcelona facility addresses talent gaps in plasma-enhanced deposition and defect metrology. |
| Multi-Standard Certification Pre-Clearance | Pre-certified documentation bundles compress 8-14 month sequential testing timelines for luminaire exporters. |
| Automotive Tier-One Supplier Partnership | BMW and Volkswagen exterior lighting programs accelerate graphene-enhanced LED prototyping cycles. |
| Shared Metrology Infrastructure Investment | Samsung Electronics and Seoul Semiconductor's Gwangju co-location compresses development timelines. |
Research Methodology
Document review covered regulatory filings with EPA Energy Star, EU ECHA REACH nanoform registrations, and SAMR GB standards documentation, complemented by interviews with thermal management engineers at luminaire OEMs, procurement leads at automotive tier-one suppliers, graphene deposition technicians at CVD facilities, and lighting contractors in California's Title 20 enforcement zone. Secondary validation drew from customs trade data for vein graphite and CVD equipment imports, SEC filings from publicly traded graphene producers, and patent filing databases tracking flexible OLED electrode applications. Bottom-up unit economics for LED thermal spreader retrofits were triangulated against top-down market sizing from automotive lighting program announcements.
Segmented outputs across product type, application, technology, and end user dimensions were generated through the projection horizon, with CAGRs derived from regression analysis of historical efficacy mandate tightening patterns and automotive adoption curve analogs. Key inputs included EU Ecodesign Directive implementation schedules, ITO spot price volatility indices, and LED junction thermal profile specifications from driver electronics manufacturers.
Several conditions sit outside the modeled scope, including potential reclassification of graphene substance definitions under ECHA nanoform reporting, abrupt indium tin oxide supply disruptions from mining jurisdiction instability, and accelerated OLED cost reduction timelines from display industry technology spillover. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Dimmers Market
Lighting
COB Photo Light Market
Lighting
Indicator Lights Market
Lighting
North America Outdoor Lighting Market
Lighting
Xenon Flashlamps Market
Lighting
Solar Rope Light Market
Lighting
High-End Lighting Market
Lighting
Programmable Stage Lighting Market
Lighting
Hazardous Lighting Market
Lighting
Intelligent Lighting Market
Lighting
High Bay Lighting Market
Lighting
Art and Museum Lighting Market
Lighting
Photography Light Box Market
Lighting
Bulb Market
Lighting
Industrial Lighting Market
Lighting
LED Eye Protection Desk Lamp Market