
 Electronic Sentry Market | 2026-2036
Electronic Sentry Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Sentry Market Insights
AI/ML engineering talent scarcity is bifurcating vendor capabilities between algorithm-native platforms and hardware-legacy suppliers. Hikvision sustains manufacturing scale across integrated camera-sensor production. SenseTime differentiates through computer vision R&D intensity concentrated in facial recognition analytics. Dahua anchors geographic dominance through channel control in Asia-Pacific distribution networks.
Electronic sentry systems encompass networked surveillance infrastructure combining optical sensors, edge processors, and centralized management software for real-time threat detection and automated response coordination, typically operating across IP-based architectures with latency thresholds under 150 milliseconds for live analytics. Surveillance cameras occupy the largest product category while AI-driven analytics represents the fastest-expanding technology segment as on-device inference chips displace cloud-dependent processing. Perimeter protection applications command premium pricing due to environmental hardening requirements and false-positive sensitivity standards.
FCC certification mandates govern wireless transmission protocols for US-deployed systems while GDPR data-processing restrictions shape European cloud-based solution architectures. China's MIIT enforces GB standards on encryption modules within domestic installations. Stakeholders must weigh regulatory fragmentation against platform standardization when selecting multi-territory deployment partners.
Market Dynamics
Edge inference chip deployment is compressing latency thresholds below 50 milliseconds, forcing hardware-legacy vendors to rebuild architectures around on-device AI processing or surrender high-value perimeter contracts to algorithm-native competitors.
Growth Catalysts
- Smart city infrastructure mandates:Germany's federal digital sovereignty framework requires encrypted local processing for public surveillance networks, accelerating procurement of edge-native sentry systems across municipal transit and critical infrastructure.
- Retail loss prevention automation:Computer vision analytics integrated with point-of-sale systems enables real-time shrinkage detection, driving replacement cycles for analog CCTV installations in US big-box and grocery chains.
- Logistics hub perimeter hardening:E-commerce fulfillment centers in China's Yangtze River Delta are deploying multi-sensor fusion arrays combining thermal, optical, and radar inputs to secure automated sorting facilities.
Market Restraints
- GPU and NPU supply concentration:Taiwan-based foundry capacity constraints for advanced node semiconductors create 12-18 month lead times for edge inference chip procurement, freezing deployment schedules for mid-tier integrators.
- GDPR Article 35 impact assessments:European cloud-based video management platforms face mandatory data protection impact reviews for biometric analytics, extending sales cycles by 6-9 months in France and Germany.
- Silicon carbide substrate costs:Thermal imaging sensor production depends on SiC wafer supply where 6-inch substrate prices have tripled since 2022, compressing margins for perimeter protection hardware vendors.
Strategic Opportunities
- India smart city mission Phase II:100 additional cities receive centralized funding for integrated command centers, creating entry points for vendors offering GB-compliant encryption modules and localized data residency.
- EU AI Act high-risk system classification:Biometric identification systems face strict conformity requirements from 2025, favoring vendors with pre-certified algorithmic audit trails over retrofit-dependent competitors.
- 5G private network convergence:Manufacturing campuses in Japan and South Korea are deploying standalone 5G cores with sub-10 millisecond slicing for mobile sentry robotics, opening greenfield deployment models.
Industry Challenges
- Embedded systems firmware engineering:Scarce talent capable of optimizing neural network kernels for ARM Cortex-M and RISC-V microcontrollers delays product roadmaps for camera OEMs transitioning from generic SoCs.
- FCC Part 15 unintentional radiator certification:Wireless video transmission modules require 4-6 month approval timelines for new frequency bands, blocking simultaneous multi-territory launches.
- ONVIF Profile T interoperability gaps:Inconsistent implementation of advanced video streaming features across VMS platforms forces costly integration testing for each deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Sentry Market |
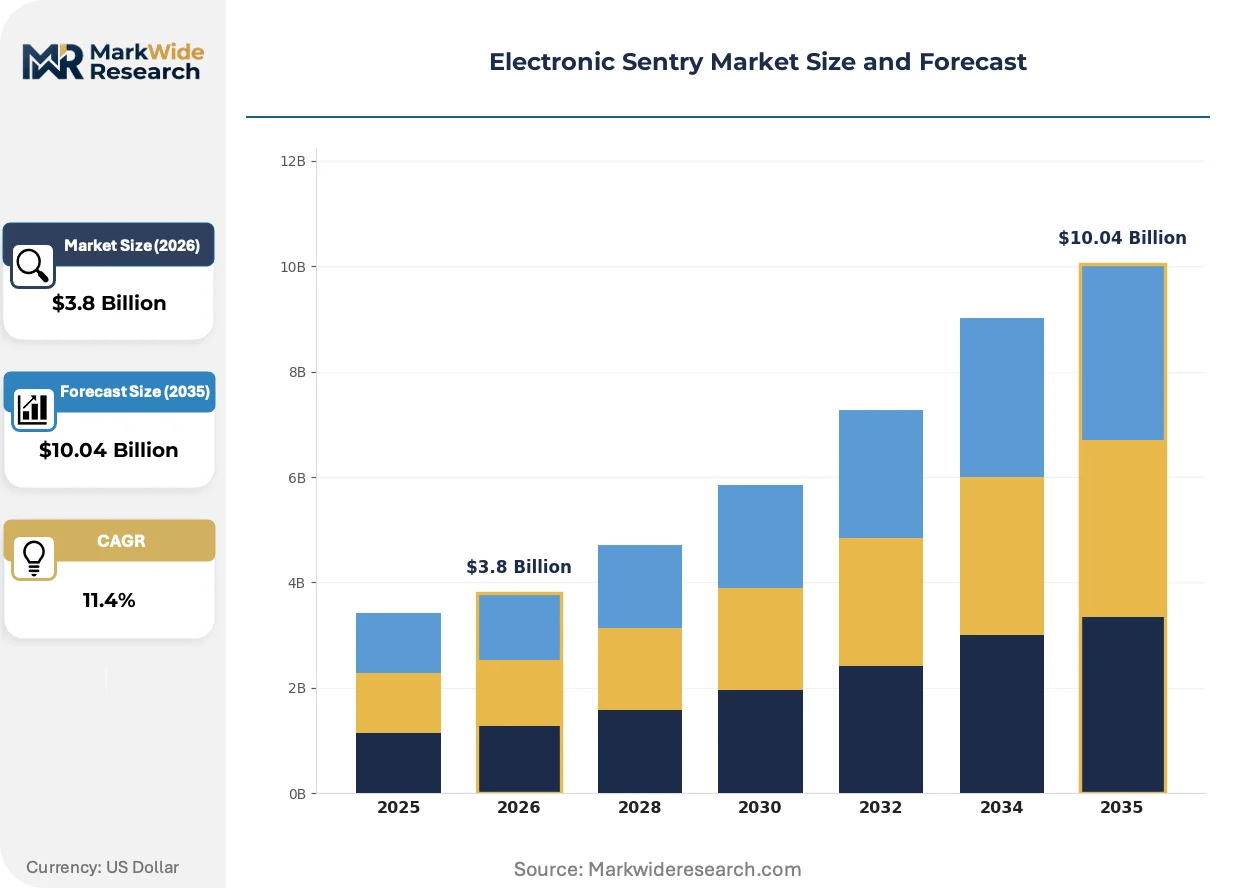
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surveillance Cameras, Alarm Systems, Access Control, Detection Sensors Application: Residential Security, Commercial Surveillance, Industrial Monitoring, Perimeter Protection End User: Homeowners, Businesses, Government Agencies, Security Installers Technology: Wireless Systems, Cloud-Based Solutions, AI-Driven Analytics, IoT Integration |
| Companies Covered | Hikvision, Dahua, SenseTime, Maxvision, Pelco, Sensormatic Solutions, Nedap, Avery Dennison, Checkpoint Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Sentry Market Trends and Innovations
Silicon architecture decisions now determine competitive tiering faster than brand recognition, with inference performance per watt becoming the decisive procurement metric across government and enterprise accounts.
On-device transformer-based vision models are supplanting convolutional neural networks for multi-object tracking in crowded scenes. Large retail operators in the United Kingdom and Netherlands are piloting these architectures for behavioral analytics, compressing cloud inference costs by 60-70 percent while eliminating data residency exposure. The shift is enabling smaller integrators to bid against cloud-native incumbents on total cost of ownership.
GDPR's automated decision-making restrictions are reshaping European cloud-based video analytics architectures. Providers must now implement human-in-the-loop review interfaces for facial recognition alerts, adding UI development burden but creating differentiation for vendors with pre-built audit workflows. German critical infrastructure operators are prioritizing these compliance-ready platforms for Q3 2025 procurement cycles.
Buying committees are unbundling hardware procurement from software licensing and managed services. US university campus security departments now issue separate RFPs for camera hardware, VMS platforms, and analytics subscriptions, fragmenting vendor relationships that previously ran through single-source integrators. This pattern is most pronounced in California and Texas public higher education systems with decentralized IT governance.
Electronic Sentry Market Segmentation
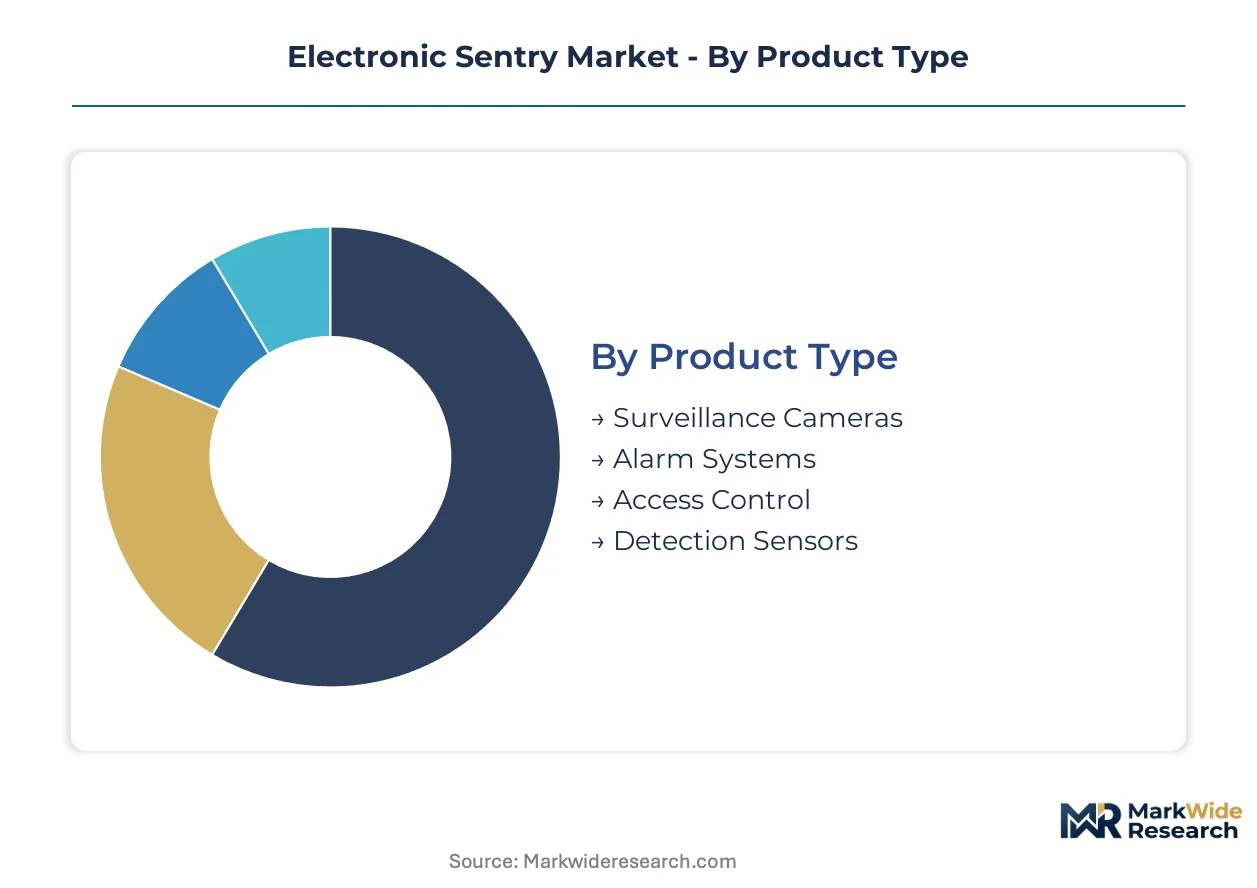
Procurement patterns in electronic sentry systems diverge sharply across product categories, with enterprise buyers favoring integrated platforms while residential segments drive volume through retail channels. Channel economics determine which segments absorb R&D investment and which compete on price.
Product Type:
Surveillance cameras flow primarily through security integrators and direct enterprise sales, while alarm systems and detection sensors distribute heavily through electrical wholesalers and e-commerce marketplaces.
- Surveillance Cameras:Fixed and PTZ camera units incorporating CMOS sensors, varifocal lenses, and IP66+ environmental sealing. Demand concentrates in US retail chains and Chinese logistics hubs where AI-enabled video analytics mandates are replacing analog infrastructure. Edge inference chip integration is driving premium tier differentiation.
- Alarm Systems:Intrusion detection panels combining PIR sensors, glass-break detectors, and central station connectivity protocols. German critical infrastructure operators and US university campuses are upgrading legacy hardwired installations to encrypted wireless architectures, accelerating replacement cycles.
- Access Control:Biometric readers, card credential systems, and electromechanical locks for entry management.
- Detection Sensors:Thermal, radar, and acoustic perimeter sensors for environmental threat identification.
By volume, surveillance cameras lead. By growth pace, detection sensors are expanding most quickly through multi-sensor fusion deployments.
Application:
Cost tiering separates these segments, with perimeter protection commanding 3-4x hardware premiums over residential due to environmental hardening and certification requirements.
- Commercial Surveillance:Retail loss prevention, office building security, and hospitality monitoring with centralized VMS management. US big-box chains and Netherlands grocery operators are piloting transformer-based vision models for behavioral analytics, compressing cloud inference costs while eliminating data residency exposure.
- Perimeter Protection:Critical infrastructure, transportation corridors, and energy facility boundary security with multi-sensor fusion arrays. China's Yangtze River Delta fulfillment centers are deploying thermal-optical-radar combinations to secure automated sorting facilities against intrusion.
- Residential Security:Single-family and multi-unit dwelling protection with DIY installation options.
- Industrial Monitoring:Manufacturing floor safety, process control, and hazard detection in production environments.
Commercial surveillance generates the largest revenue pool. Perimeter protection shows the steepest margin expansion as environmental certification requirements tighten.
End User:
Customer type determines purchasing modality, with government agencies running formal RFP processes and security installers acting as channel aggregators for fragmented small-business demand.
- Government Agencies:Federal, state, and municipal procurement for public safety, transit, and critical infrastructure networks. Germany's federal digital sovereignty framework mandates encrypted local processing, accelerating edge-native sentry adoption across municipal transit authorities.
- Businesses:Corporate security departments with centralized IT governance and decentralized facility management. California and Texas public university systems now unbundle hardware, VMS, and analytics into separate RFPs, fragmenting vendor relationships.
- Homeowners:Individual consumers purchasing through retail and direct-to-consumer channels.
- Security Installers:Regional integration firms serving SMB customers with bundled installation and monitoring services.
Businesses account for the dominant transaction volume. Government agencies are gaining share fastest through smart city infrastructure mandates.
Technology:
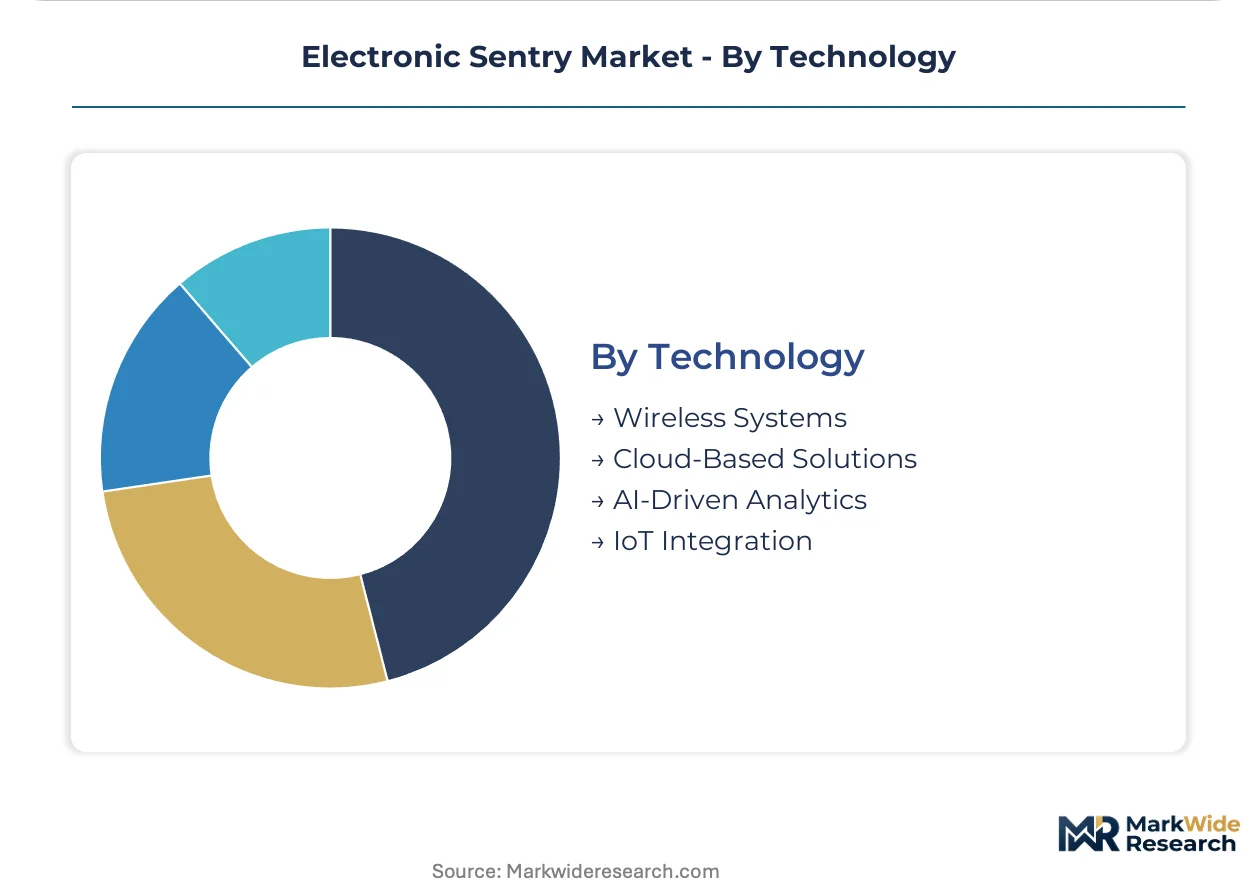
Supply concentration in semiconductor foundries creates divergent availability, with wireless and IoT components facing shorter lead times than AI inference chips.
- AI-Driven Analytics:On-device neural network inference for object detection, facial recognition, and behavioral classification. Large UK retailers are deploying transformer-based vision models for multi-object tracking, cutting cloud inference expenditure by 60-70 percent while satisfying GDPR data residency constraints.
- Cloud-Based Solutions:Centralized video management with remote storage, multi-site federation, and software-defined analytics. French and German deployments now require human-in-the-loop review interfaces for biometric alerts under GDPR automated decision-making restrictions, adding UI development burden.
- Wireless Systems:Wi-Fi, cellular, and proprietary RF transmission protocols for flexible deployment.
- IoT Integration:Sensor fusion platforms connecting cameras, access control, and environmental monitors through unified data layers.
Wireless systems ship the highest unit volumes. AI-driven analytics is climbing the fastest as on-device inference displaces cloud-dependent processing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Germany and China prioritize encrypted edge processing for data sovereignty, while US buyers emphasize unbundled procurement and cloud flexibility. India and Japan represent emerging deployment models shaped by infrastructure funding and private network convergence.
United States
Retail chains and university campuses drive replacement cycles for legacy analog infrastructure. FCC Part 15 certification governs wireless transmission protocols for new frequency bands. California and Texas public higher education systems unbundle hardware, VMS, and analytics into separate procurement streams.
Germany
Federal digital sovereignty mandates accelerate edge-native sentry adoption across municipal transit authorities. GDPR Article 35 impact assessments extend sales cycles for biometric analytics deployments. Critical infrastructure operators in North Rhine-Westphalia prioritize compliance-ready platforms with human-in-the-loop review interfaces.
China
Logistics hubs in the Yangtze River Delta deploy multi-sensor fusion arrays for automated fulfillment center security. MIIT enforces GB standards on encryption modules within domestic installations. Shenzhen-based manufacturers sustain integrated camera-sensor production at manufacturing scale.
India
Smart city mission Phase II funding creates entry points for vendors offering localized data residency solutions. BIS certification requirements shape product specifications for domestic procurement. Command center deployments concentrate in Maharashtra and Gujarat where municipal infrastructure investment accelerates.
Japan
Manufacturing campuses deploy standalone 5G cores with sub-10 millisecond slicing for mobile sentry robotics. METI industrial policy supports private network convergence for factory automation. Kanto region industrial clusters pilot greenfield deployment models for sensor fusion platforms.
Electronic Sentry Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with algorithm-native platforms separating from hardware-legacy suppliers on inference performance metrics. The vendor base stratifies across three archetypes: vertically integrated manufacturers controlling sensor-to-software stacks, pure-play analytics specialists licensing computer vision IP, and regional channel aggregators bundling installation services. Competitive moves concentrate on edge chip architecture transitions and multi-territory certification pre-positioning ahead of regulatory deadlines.
Within the integrated manufacturing tier, Hikvision and Dahua represent scale-driven positions anchored in Asia-Pacific production ecosystems. SenseTime occupies a specialist position exemplifying algorithm-native competitive logic. These three entities collectively illustrate the capability bifurcation between hardware-legacy and software-first market approaches.
| Leading Market Players |
|---|
| Hikvision |
| Dahua |
| SenseTime |
| Maxvision |
| Pelco |
| Sensormatic Solutions |
| Nedap |
| Avery Dennison |
| Checkpoint Systems |
| Others |
Pricing and Supply Chain Analysis
Twelve-to-eighteen month lead times for edge inference chip procurement compress pricing power toward algorithm-native vendors while freezing deployment schedules for mid-tier integrators dependent on Taiwan-based foundry capacity. This supply bottleneck concentrates margin capture among vertically integrated manufacturers with captive semiconductor allocation, fragmenting competitive tiers across hardware-legacy and software-first archetypes.
Pricing Analysis
Long-term offtake agreements dominate enterprise procurement for perimeter protection systems, while project-based contracting governs commercial surveillance deployments and spot purchasing persists in residential channels. Three-tier pricing structure across premium, standard, and economy levels separates edge-native AI platforms from cloud-dependent VMS bundles and analog replacement hardware. Cost compression in standard-tier camera OEMs is intensifying because silicon carbide substrate prices have tripled since 2022, eroding thermal imaging margins. Government agencies exhibit lowest price sensitivity due to certification mandates, while security installers serving SMB customers face acute margin pressure from unbundled procurement trends.
Supply Chain Analysis
Port congestion on Asia-Pacific trade lanes elevates inbound logistics costs for CMOS sensor modules and varifocal lens assemblies sourced from Shenzhen and Taipei manufacturing clusters. Supply concentrates in China for integrated camera-sensor production, Taiwan for advanced node semiconductor fabrication, and Germany for precision optical components. Raw material dependencies include silicon carbide wafers for thermal sensors, rare earth elements for lens coatings, and copper alloys for RF shielding. Single-source vulnerability in NPU foundry capacity creates procurement freezes during capacity crunches. Distribution runs through security integrators for enterprise accounts, electrical wholesalers for alarm systems, and direct e-commerce for residential DIY segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflection is restructuring vendor relationships as ONVIF interoperability gaps and unbundled RFP processes fragment historically integrated procurement channels. The shift from single-source integrators to separated hardware, VMS, and analytics contracts rewards modular architecture investments.
For Market Incumbents: Fortify algorithm-native capabilities through edge inference chip design partnerships or risk surrendering high-value perimeter contracts to computer vision specialists. Secure manufacturing scale advantages by deepening backward integration into sensor production. Prioritize multi-territory certification pre-positioning ahead of EU AI Act high-risk system deadlines to defend against retrofit-dependent competitors. For New Entrants and Emerging Players: Compliance-ready audit workflows for GDPR human-in-the-loop requirements represent a service-layer gap where incumbents under-serve European critical infrastructure operators. Target India's Smart City Mission Phase II command center deployments with localized data residency solutions and GB-compliant encryption modules. Pursue white-label analytics licensing to regional channel aggregators as a capital-efficient go-to-market path. For Investors and Strategic Acquirers: Long-term, this sits as a semiconductor-tethered infrastructure play because inference performance per watt is displacing brand recognition as the decisive procurement metric. Acquisition targets should display pre-certified algorithmic audit trails and ARM Cortex-M optimization capabilities for transformer-based vision models. Monitor Taiwan foundry capacity allocation announcements as the primary inflection signal for deployment velocity across mid-tier integrators.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Inference Chip Partnership | Secures NPU supply allocation from Taiwan foundries ahead of mid-tier competitors. |
| GDPR Compliance Platform Development | Captures German critical infrastructure procurement with human-in-the-loop audit workflows. |
| India Smart City Localization | Positions for Phase II command center funding with BIS-certified data residency. |
| ONVIF Profile T Certification Investment | Eliminates costly integration testing for each VMS deployment across fragmented platforms. |
| 5G Private Network Convergence Pilot | Opens greenfield mobile sentry robotics opportunities in Japanese manufacturing campuses. |
Research Methodology
A standing panel of security integrators, municipal procurement officers, semiconductor supply planners, and edge AI engineering leads provided ongoing calibration against deployment timelines and certification bottlenecks. Primary fieldwork combined structured interviews with channel partners and enterprise security directors alongside secondary validation through FCC equipment authorization databases, MIIT GB standard filings, and EU AI Act implementation guidance documents. Bottom-up unit economics for camera hardware, VMS licensing, and analytics subscriptions were triangulated against top-down smart city infrastructure budget allocations.
Consistency checks validated volume and value outputs against hyperscaler capex disclosures for edge computing infrastructure, customs records for CMOS sensor trade flows, and municipal RFP publication rates across Germany, the United States, and India. Segmentation modeling spanned product type, application tier, end-user governance structure, and technology deployment architecture across the projection horizon. CAGRs were derived from installed base replacement cycles, AI analytics attach rate trajectories, and foundry capacity expansion schedules for advanced node semiconductors.
Underlying assumptions cover sustained Taiwan semiconductor foundry utilization rates, stable GDPR enforcement intensity across EU member states, and continued MIIT domestic encryption mandates, with deviation risk concentrated in geopolitical trade restrictions affecting sensor component flows. Practitioners should keep alternative scenarios live as edge inference chip supply allocation protocols and EU AI Act conformity assessment timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Active Sensor Market
Sensors and Controls
Connected Sensors Market
Sensors and Controls
Absolute Pressure Sensor Market
Sensors and Controls
Brazil Electric Power Steering (EPS) Sensor Market
Sensors and Controls
RTD Temperature Sensors Market
Sensors and Controls
United States Sensor Market
Sensors and Controls
Middle East and Africa Occupancy Sensors Market
Sensors and Controls
Distributed Acoustic Sensing (DAS) Market
Sensors and Controls
Middle East and Africa Pressure Sensors Market
Sensors and Controls
High-End Accelerometer Market
Sensors and Controls
Microsensor Market
Sensors and Controls
Water Quality Sensor Market
Sensors and Controls
Fork Sensor Market
Sensors and Controls
Torque Transducer Market
Sensors and Controls
Middle East and Africa Touch Sensor Market
Sensors and Controls
North America Water Detection Sensors Market