

Residential Heat Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Heat Pump Market Insights
European heat pump manufacturing is consolidating around specialized producers with cold-climate engineering capabilities. Daikin Industries leverages its inverter-driven compressor R&D to dominate premium air-source installations across Nordic markets. Mitsubishi Electric sustains technology leadership in ductless mini-split architectures for dense urban housing. Carrier anchors North American market presence through extensive contractor channel relationships and residential HVAC service networks.
A residential heat pump extracts ambient thermal energy from air, ground, or water sources and transfers it indoors via vapor-compression refrigeration cycles operating at coefficient of performance ratings typically between three and five. These systems serve as primary heating and cooling equipment in electrified buildings seeking to displace fossil-fuel combustion. Air-source products occupy the largest installed base due to lower upfront costs and minimal site preparation requirements. Ground-source configurations command superior efficiency metrics but face constrained addressable markets where drilling access and geology permit loop field installation. Inverter technology leads unit shipments as variable-speed compressor modulation improves seasonal performance factors and reduces electrical demand peaks.
The US Department of Energy appliance efficiency standards and ENERGY STAR certification thresholds shape minimum viable product specifications for manufacturers accessing American households. The European Union F-Gas Regulation and Ecodesign Directive progressively restrict refrigerant global warming potential and mandate seasonal space heating energy efficiency labels that influence consumer procurement decisions. Stakeholders must monitor refrigerant transition timelines and regional electrification subsidy durability to align capacity investments with policy-supported demand corridors.
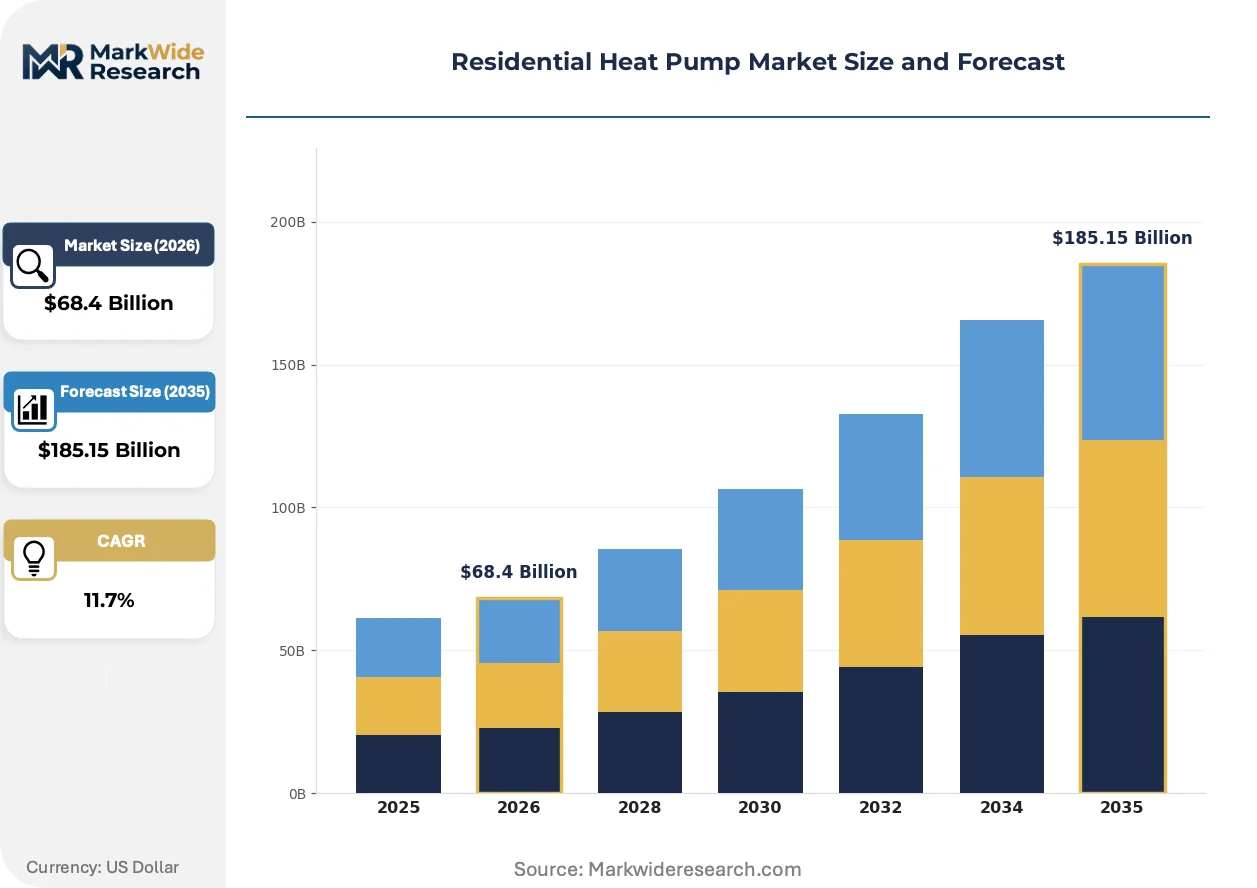
Market Dynamics
The US Inflation Reduction Act's heat pump tax credits and rebates are accelerating equipment turnover across single-family housing stock. This subsidy durability question now governs manufacturer capacity planning and distributor inventory positioning.
Growth Catalysts
- Cold-climate engineering advances:Inverter-driven compressor modulation now delivers rated capacity at sub-zero ambient temperatures. Single-family homeowners in Nordic zones are upgrading from fossil-fuel furnaces.
- EU F-Gas Regulation phase-down:Refrigerant global warming potential restrictions are forcing equipment replacement cycles. Building retrofit mandates in Germany intensify demand for low-GWP systems.
- Natural gas phase-out policies:Municipal heating bans in Dutch cities are compressing replacement timelines. Existing housing stock retrofits dominate addressable demand.
Market Restraints
- Copper and aluminum input volatility:Compressor and coil raw material costs swing with commodity markets. OEMs face margin compression without pricing power.
- Drilling access constraints:Ground-source loop field installation requires suitable geology and property footprint. Urban density limits addressable market for geothermal configurations.
- Contractor channel concentration:North American distribution runs through consolidated HVAC service networks. Installer capacity bottlenecks throttle equipment shipment velocity.
Strategic Opportunities
- Ductless mini-split penetration:Dense urban housing in Japanese and Korean markets favors compact outdoor units. Multi-zone architectures serve apartment retrofits.
- Electrification subsidy stacking:State-level rebates layered atop federal IRA credits expand effective demand. Utility demand-response programs add recurring revenue streams.
- R-290 propane refrigerant transition:Hydrocarbon-based systems bypass F-Gas quota limitations. European OEMs are engineering charge-size compliant architectures.
Industry Challenges
- Refrigerant handling certification gaps:A2L mildly flammable refrigerants require technician retraining. Workforce pipeline constraints delay installation capacity expansion.
- Legacy thermostat integration friction:Smart home protocols fragment across proprietary ecosystems. Compatibility testing burdens product development timelines.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Heat Pump Market Trends and Innovations
Heat pump technology is converging with building energy management systems and grid-interactive controls. This convergence is compressing the traditional separation between HVAC hardware and software layers.
Variable-speed inverter technology is integrating with vapor-injection compressor architectures to extend operating envelopes into extreme cold. Nordic utilities are deploying these systems for peak demand reduction. The technology is integrating residential heating with district energy networks through thermal storage coupling.
The EU Ecodesign Directive's seasonal space heating energy efficiency labels are reshaping procurement criteria across member states. Manufacturers must redesign heat exchangers and fan assemblies to hit A+++ ratings. Cold-climate air-source units face the steepest engineering hurdles under these thresholds.
Single-family homeowners are compressing replacement cycles from fifteen-year intervals to ten-year intervals. Financing products tied to energy savings performance are displacing upfront cash purchases. This pattern concentrates in German and Dutch markets where building energy certificates affect property valuations.
Residential Heat Pump Market Segmentation
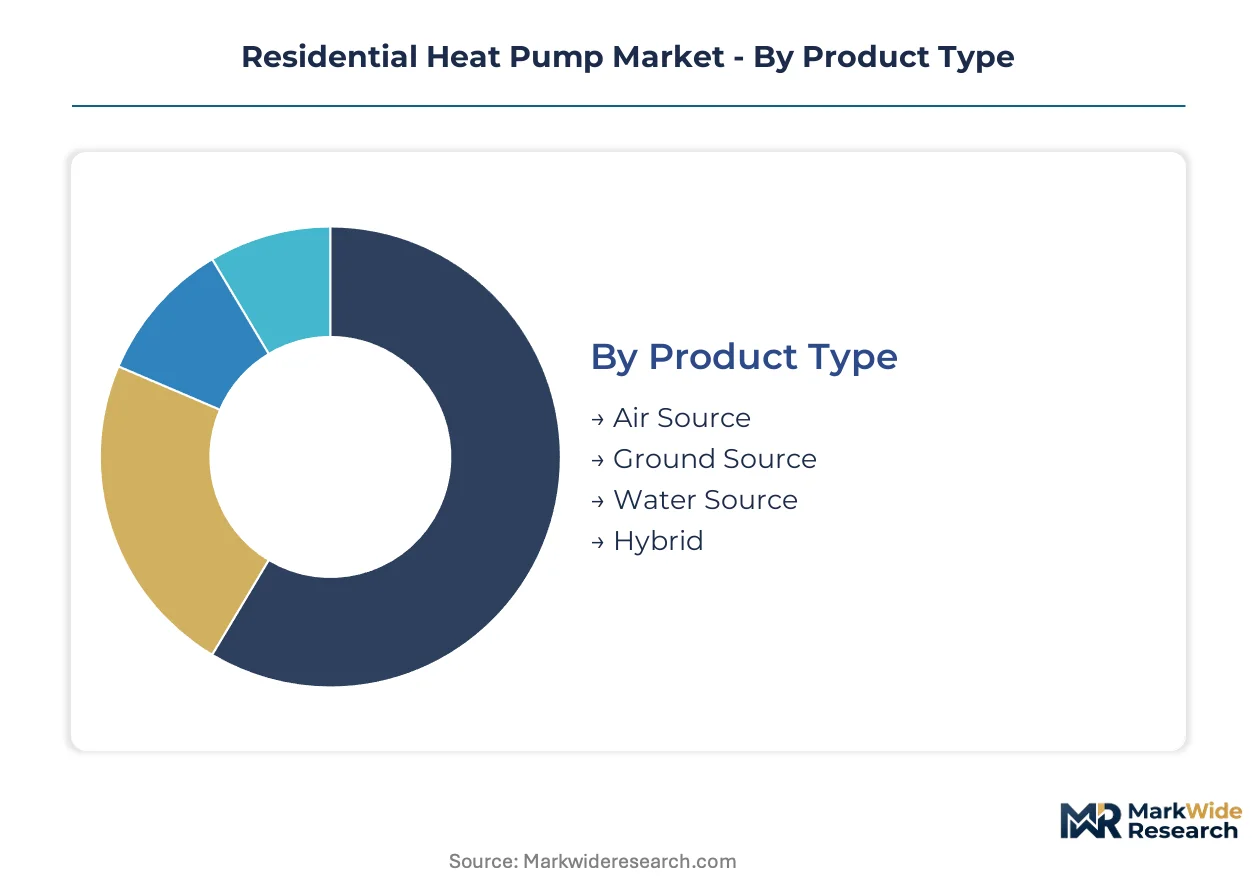
Product configuration, compressor architecture, and housing typology determine equipment specifications, installation complexity, and regulatory compliance pathways. Segmentation reveals where certification burdens concentrate and which buyer categories drive replacement velocity.
Product Type:
Air-source units face ENERGY STAR certification and DOE appliance standards in the US, while ground-source configurations trigger additional geological survey requirements and drilling permits.
- Air Source:Vapor-compression systems extract thermal energy from ambient air through refrigerant cycles. Single-family homeowners in cold-climate zones drive replacement demand as inverter technology extends rated capacity to sub-zero conditions.
- Ground Source:Geothermal loop fields exchange heat with subsurface soil or rock formations. Drilling access constraints and property footprint requirements limit addressable markets to suburban and rural housing with suitable geology.
- Water Source:Open-loop or closed-loop configurations draw from lakes, rivers, or aquifers. Waterfront properties and coastal housing clusters in the Netherlands and Denmark favor these systems where water table access permits.
- Hybrid:Dual-fuel architectures pair electric heat pumps with fossil-fuel backup furnaces. Transitional installations dominate in regions with severe cold snaps or unreliable grid infrastructure.
Air Source sits at the top of the volume ranking, with Hybrid climbing the fastest as utilities promote dual-fuel demand-response programs.
Technology:
Cost tiers separate premium inverter-driven modulation from standard fixed-speed alternatives, with margin structures varying sharply across compressor architectures.
- Inverter:Variable-speed compressor modulation matches thermal output to building load profiles. Nordic utilities deploy these systems for peak demand reduction and seasonal performance optimization.
- Scroll Compressor:Orbiting scroll mechanisms deliver quieter operation and higher efficiency than reciprocating alternatives. Mid-market single-family retrofits in Germany favor this technology for balance of upfront cost and operating economics.
- Reciprocating:Piston-driven compression remains prevalent in entry-level equipment and replacement part markets. Technician familiarity and service infrastructure sustain residual demand.
- Absorption:Thermal-activated cycles using ammonia-water or lithium bromide pairs suit waste-heat recovery applications. Limited residential penetration outside solar-thermal hybrid installations.
Inverter captures the premium tier by installed value, with Scroll Compressor expanding most quickly through mid-market channel penetration.
Application:
Customer type stratification shows single-family detached housing concentrating space heating demand, while multi-family dwellings drive water heating and combined system configurations.
- Space Heating:Primary heating function displaces fossil-fuel furnaces and boilers. German building retrofit mandates and natural gas phase-out policies compress replacement timelines across existing housing stock.
- Space Cooling:Reversible operation provides air conditioning in summer months. Mediterranean climates and warming Nordic summers expand addressable cooling demand beyond traditional markets.
- Water Heating:Dedicated heat pump water heaters extract ambient heat for domestic hot water. Japanese and Korean markets favor compact units for apartment installations.
- Combined Heating & Cooling:Integrated systems deliver year-round climate control through single outdoor units. Vacation homes and retirement communities prioritize simplified maintenance and unified control interfaces.
Space Heating dominates installed base, with Combined Heating & Cooling gaining share fastest as electrification subsidies stack across weatherization programs.
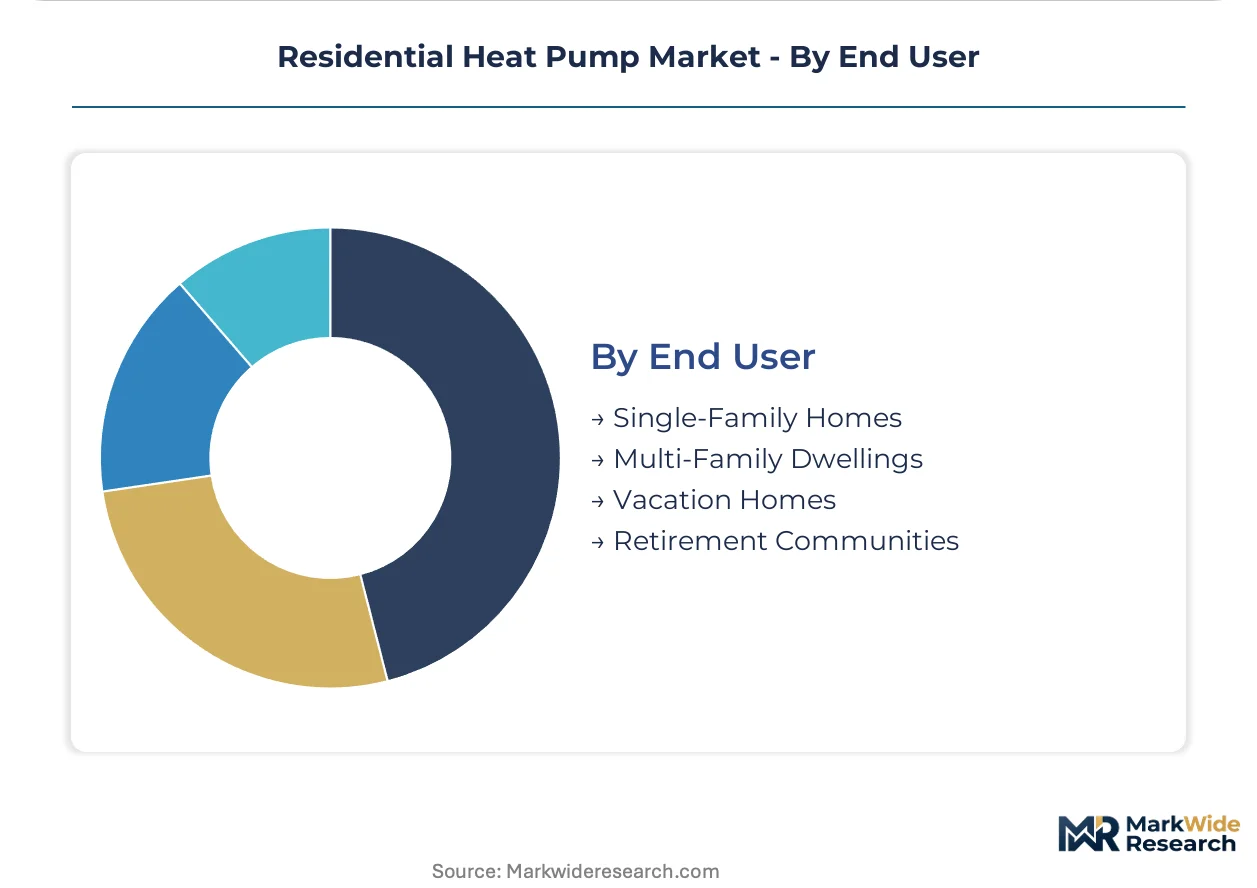
End User:
Geography determines installation constraints, with urban density favoring compact ductless architectures and suburban expansion accommodating larger split systems.
- Single-Family Homes:Detached residential structures with dedicated mechanical rooms and outdoor pad space. US IRA tax credits and state-level rebates accelerate equipment turnover across this segment.
- Multi-Family Dwellings:Apartment buildings and condominiums require compact outdoor units and multi-zone distribution. Dutch municipal heating bans compress replacement timelines in dense urban housing.
- Vacation Homes:Seasonal-use properties prioritize low-maintenance operation and freeze-protection reliability. Coastal and mountain markets favor corrosion-resistant coastal-grade enclosures.
- Retirement Communities:Age-restricted housing developments demand quiet operation and simplified controls. Centralized maintenance contracts favor standardized equipment platforms.
Single-Family Homes anchor volume, with Multi-Family Dwellings showing the steepest expansion trajectory as European building codes tighten energy performance standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing investment is migrating toward jurisdictions with durable electrification subsidies and permissive refrigerant transition timelines. Regulatory arbitrage between EU F-Gas quotas and US IRA credit durability is reshaping capacity placement decisions for cold-climate equipment.
United States
Single-family retrofits dominate equipment shipments as IRA tax credits stack with state-level rebates. The Department of Energy appliance efficiency standards and ENERGY STAR thresholds set minimum viable specifications for accessing American households. Contractor channel concentration in the Southeast and Midwest creates installation bottlenecks that throttle shipment velocity.
Germany
Building retrofit mandates and natural gas phase-out policies compress replacement cycles across existing housing stock. The Ecodesign Directive's seasonal space heating energy efficiency labels reshape procurement criteria toward A+++ rated systems. Industrial clusters in Bavaria and North Rhine-Westphalia concentrate inverter manufacturing for Nordic export markets.
Netherlands
Municipal heating bans in Amsterdam and Rotterdam accelerate fossil-fuel displacement in dense urban housing. The F-Gas Regulation phase-down forces equipment replacement toward low-GWP refrigerant architectures. Waterfront properties in coastal provinces favor water-source configurations where aquifer access permits.
Japan
Ductless mini-split penetration reaches saturation in Tokyo and Osaka metropolitan housing. METI efficiency standards and refrigerant transition timelines shape manufacturer R&D allocation toward hydrocarbon-based systems. Dense urban apartments drive demand for compact multi-zone outdoor units with simplified controls.
Sweden
Nordic utilities deploy inverter-driven systems for peak demand reduction in sub-zero operating conditions. District energy network integration creates thermal storage coupling opportunities in Stockholm and Gothenburg. Cold-climate engineering capabilities concentrate manufacturing expertise for Baltic and Finnish export markets.
Residential Heat Pump Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue refrigerant-transition niches and subsidy-stacking service models. The vendor base stratifies across three tiers: integrated HVAC conglomerates with contractor channel control, specialized cold-climate engineering houses, and Asian-scale manufacturers competing on inverter cost curves. Two strategic archetypes dominate: technology licensors monetizing compressor architectures through OEM partnerships, and vertically integrated assemblers capturing margin through captive component production. Competitive moves concentrate on capacity expansion in tariff-advantaged jurisdictions and technology licensing for A2L refrigerant handling.
Among Japanese diversified industrials, Daikin Industries and Mitsubishi Electric exemplify the technology-licensor archetype with deep cold-climate engineering legacies. Panasonic Holdings occupies a position within the scale-driven tier, leveraging component manufacturing breadth across consumer and commercial product lines. Carrier anchors the North American service-network tier through extensive contractor relationships and residential HVAC distribution infrastructure.
| Leading Market Players |
|---|
| Daikin Industries |
| Mitsubishi Electric |
| Panasonic Holdings |
| Carrier |
| Johnson Controls |
| Midea Group |
| Robert Bosch |
| Rheem Manufacturing Company |
| Lennox International |
| Others |
Pricing and Supply Chain Analysis
Captive inverter compressor production anchors supply positions for Japanese and Korean OEMs while insulating premium-tier pricing power against commodity coil volatility. This integration choice lets Daikin and Mitsubishi Electric defend margin structures even as copper and aluminum input costs swing through commodity cycles.
Pricing Analysis
Distributor margins in North American HVAC channels absorb installation complexity premiums before equipment reaches single-family homeowners. Three-tier pricing structure across premium inverter, standard scroll, and economy reciprocating compressor tiers separates cold-climate-certified systems from baseline replacements. Cost compression in entry-level equipment intensifies because Asian-scale manufacturers feed volume into price-sensitive retrofit markets. Multi-family developers in Dutch cities show least price sensitivity where municipal heating bans compress replacement timelines.
Supply Chain Analysis
Freight costs from East Asian component hubs to European assembly plants have reshored some inverter manufacturing toward Germany and Sweden. Compressor production concentrates in Japan, China, and South Korea while coil fabrication draws from Vietnamese and Mexican metalworking centers. Single-source vulnerability in rare-earth magnet supply for high-efficiency motors creates exposure to export licensing shifts. Distribution runs through consolidated HVAC service networks in North America and specialized heating contractors in Nordic markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder where building electrification mandates in Germany and the Netherlands drive replacement velocity through regulatory obligation rather than discretionary demand.
For Market Incumbents: Anticipate refrigerant transition timelines compressing product development cycles as EU F-Gas quotas force R-290 propane architectures. Defend channel position by certifying installer networks for A2L mildly flammable refrigerant handling before workforce pipeline constraints widen. Backward integration into compressor manufacturing insulates margin pressure from raw material volatility. For New Entrants and Emerging Players: The US Inflation Reduction Act in American states opens a window for subsidy-stacking service models that layer utility demand-response revenue atop federal tax credits. Target hybrid dual-fuel retrofits in regions with severe cold snaps where incumbent coverage remains thin. Lead with financing products tied to energy savings performance to bypass upfront cash purchase friction. For Investors and Strategic Acquirers: Roll-up economics work for regional HVAC service networks because contractor channel concentration in North America creates scarcity value for installation capacity. Five-to-ten-year viability hinges on subsidy durability rather than technology risk. Watch for F-Gas quota allocation decisions as the inflection signal for European manufacturing capacity placement.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Climate Certification Investment | A+++ Ecodesign ratings unlock German retrofit mandates and Nordic utility procurement. |
| R-290 Propane System Engineering | Low-GWP refrigerant architectures bypass EU F-Gas quota limitations on legacy HFCs. |
| Installer Network Certification | A2L handling credentials remove workforce bottlenecks throttling shipment velocity. |
| Demand-Response Program Integration | Utility partnerships add recurring revenue streams atop equipment sales in US markets. |
| Geographic Manufacturing Footprint | Tariff-advantaged assembly in Mexico or Eastern Europe reduces landed cost exposure. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged HVAC contractor network managers, OEM procurement directors, utility demand-response program officers, and building energy retrofit consultants across Germany, the Netherlands, and the United States. Secondary validation drew from DOE appliance efficiency filings, ENERGY STAR certification databases, EU Ecodesign compliance registries, and customs trade records for compressor and coil imports. Bottom-up equipment shipment data triangulated against top-down building stock electrification targets.
Segment-weighting distributed volume and value estimates across product configuration, compressor architecture, housing typology, and regional regulatory cluster dimensions. CAGRs derived from policy-supported replacement cycle compression and technology cost curve trajectories. Cold-climate performance thresholds and refrigerant transition timelines served as scenario inputs across the projection horizon.
Revisions become necessary when subsidy durability shifts, F-Gas quota allocations change, or raw material cost spikes alter manufacturer pricing power. Forecasts reflect documented assumptions about regulatory enforcement and installer capacity expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.