
 Concrete Formwork System Market | 2026-2036
Concrete Formwork System Market Size, Share, and Industry Trends Forecast 2026-2036
Concrete Formwork System Market Outlook
High-strength aluminum specification tiers is collapsing the cost-per-pour economics for mid-rise contractors. PERI Group leverages its German engineering base to dominate engineered modular systems for complex geometries. Doka Group sustains R&D intensity across digital formwork planning tools that reduce on-site labor hours. MEVA Formwork Systems anchors its position through captive supply of high-grade aluminum extrusions and precision welding capacity.
A concrete formwork system comprises temporary molds—fabricated from steel, aluminum, timber, or engineered polymer composites—designed to hold fluid concrete in place until it achieves specified compressive strength, typically measured at 28 days for standard Portland cement blends. These structures enable architects to execute cantilevered slabs, curved facades, and variable cross-sections that permanent shuttering cannot accommodate. Aluminum formwork commands premium positioning in residential high-rise segments where rapid cycle times and fifty-plus reuse thresholds justify first-cost outlays against timber alternatives. Infrastructure projects represent the deepest margin pool for steel systems, driven by load-bearing requirements on bridge piers and tunnel linings that exceed aluminum capacity. Plastic formwork occupies a narrow but expanding niche in emerging markets where corrosion resistance and lightweight handling offset lower durability metrics.
OSHA fall-protection mandates in the United States and the EU's Construction Products Regulation, enforced through CE marking and harmonized EN 12812 standards, compel manufacturers to certify load-bearing capacity and dismantling safety protocols before market entry. China's SAMR and MEE jointly enforce GB 50666 concrete structure codes that specify formwork deflection limits and tie-rod spacing for seismic zones. Stakeholders must monitor how India's BIS adoption of Eurocode-aligned design standards reshapes procurement criteria for public infrastructure tenders and whether modular-reusable installation methods gain specification share against traditional timber-intensive practices.
Market Dynamics
Reusable aluminum formwork systems are compressing project timelines for mid-rise residential towers across Southeast Asia, where building code convergence with Eurocode standards is mandating higher load-bearing specifications and accelerating displacement of timber-intensive traditional methods.
Growth Catalysts
- GB 50666 Seismic Provisions:China's SAMR and MEE enforcement of deflection limits and tie-rod spacing specifications is compelling contractors to upgrade from timber to engineered modular platforms in high seismic zones.
- Residential High-Rise Density:Vietnam's urban corridor is concentrating foreign contractor deployment of European-engineered systems for commercial tower projects demanding fifty-plus reuse cycles.
- BIS Eurocode Alignment:India's adoption of harmonized design standards for structural materials is reshaping procurement criteria in public infrastructure tenders toward certified reusable systems.
Market Restraints
- Aluminum Input Volatility:Primary aluminum price swings and energy-intensive smelting costs in China and the Gulf states compress margin predictability for extrusion-dependent formwork fabricators.
- Technical Load Ceiling:Aluminum capacity limits on bridge piers and tunnel linings exceeding specified compressive thresholds lock steel systems into infrastructure margins despite longer cycle times.
- CE Marking Compliance Burden:EU Construction Products Regulation harmonized EN 12812 certification timelines and dismantling safety protocol documentation create friction for non-European manufacturers seeking market entry.
Strategic Opportunities
- Plastic Composite Niche Expansion:Corrosion-resistant engineered polymer formwork is capturing specification share in coastal and chemical-exposure environments where aluminum fatigue accelerates.
- Digital Planning Convergence:BIM-integrated formwork design software is compressing on-site labor hours and reducing material waste for contractors adopting parametric layout tools.
- Modular-Reusable Mandates:India's BIS certification trajectory and state-level green building incentives are creating procurement preference for systems demonstrating documented reuse thresholds above traditional timber.
Industry Challenges
- Welding Certification Pipeline:Precision aluminum welding capacity scarcity and qualified technician training gaps constrain output scaling for manufacturers expanding high-grade extrusion supply.
- Legacy Timber Integration:Hybrid project specifications requiring mixed formwork systems create logistical complexity and cycle-time mismatches for contractors managing dual material workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concrete Formwork System Market |
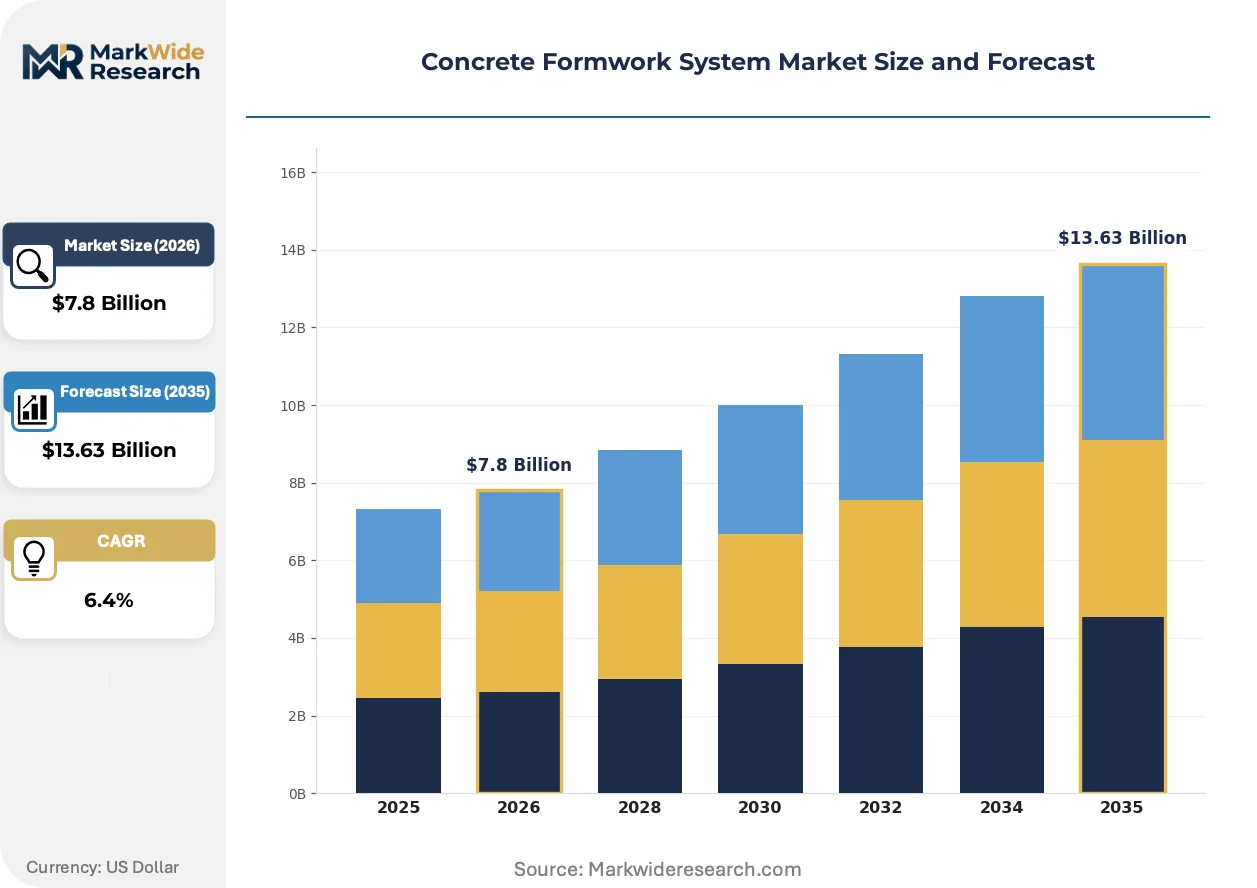
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Formwork, Plastic Formwork, Wood Formwork, Aluminum Formwork Application: Residential Construction, Commercial Construction, Industrial Construction, Infrastructure Projects End User: Contractors, Developers, Architects, Engineers Installation Method: Pre-assembled, Modular, Traditional, Reusable |
| Companies Covered | MEVA Formwork Systems, Acrow, PERI Group, Alsina, EFCO, Doka Group, RMD Kwikform, PASCHAL Group, ULMA Construction, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concrete Formwork System Market Strategic Shifts
Digital fabrication and connected jobsite technologies are compressing the gap between engineering design and field execution, enabling real-time formwork adjustment and predictive maintenance scheduling that reduces pour-cycle variability.
Self-climbing formwork platforms with integrated safety cages and hydraulic lifting mechanisms are miniaturizing crew requirements for high-rise core construction. General contractors in Singapore and Dubai are specifying these systems for towers exceeding forty stories. The technology is miniaturizing traditional crane-dependent erection sequences into continuous automated ascent cycles that shave weeks from structural schedules.
OSHA fall-protection mandates in the United States and the EU's Construction Products Regulation are hardening liability frameworks around dismantling-phase accidents. Manufacturers now embed RFID-tracked component serialization and digital inspection logs to demonstrate compliance. Steel system suppliers serving bridge and tunnel infrastructure face the steepest documentation burden given permanent-structure liability exposure.
Equipment-as-a-service leasing models are displacing capital purchase for mid-tier contractors in India's tier-two cities. Rental platforms bundle transport, assembly supervision, and technical support into per-pour pricing. Maharashtra and Karnataka urban clusters show the fastest contract structure migration as liquidity-constrained developers prioritize balance-sheet flexibility over ownership.
Concrete Formwork System Market Segmentation
Segmentation in concrete formwork systems reveals how material specifications, project scale, and procurement authority reshape margin capture across construction workflows. Understanding these divides exposes where aluminum commands premium positioning against timber displacement and where steel retains infrastructure dominance.
Product Type:
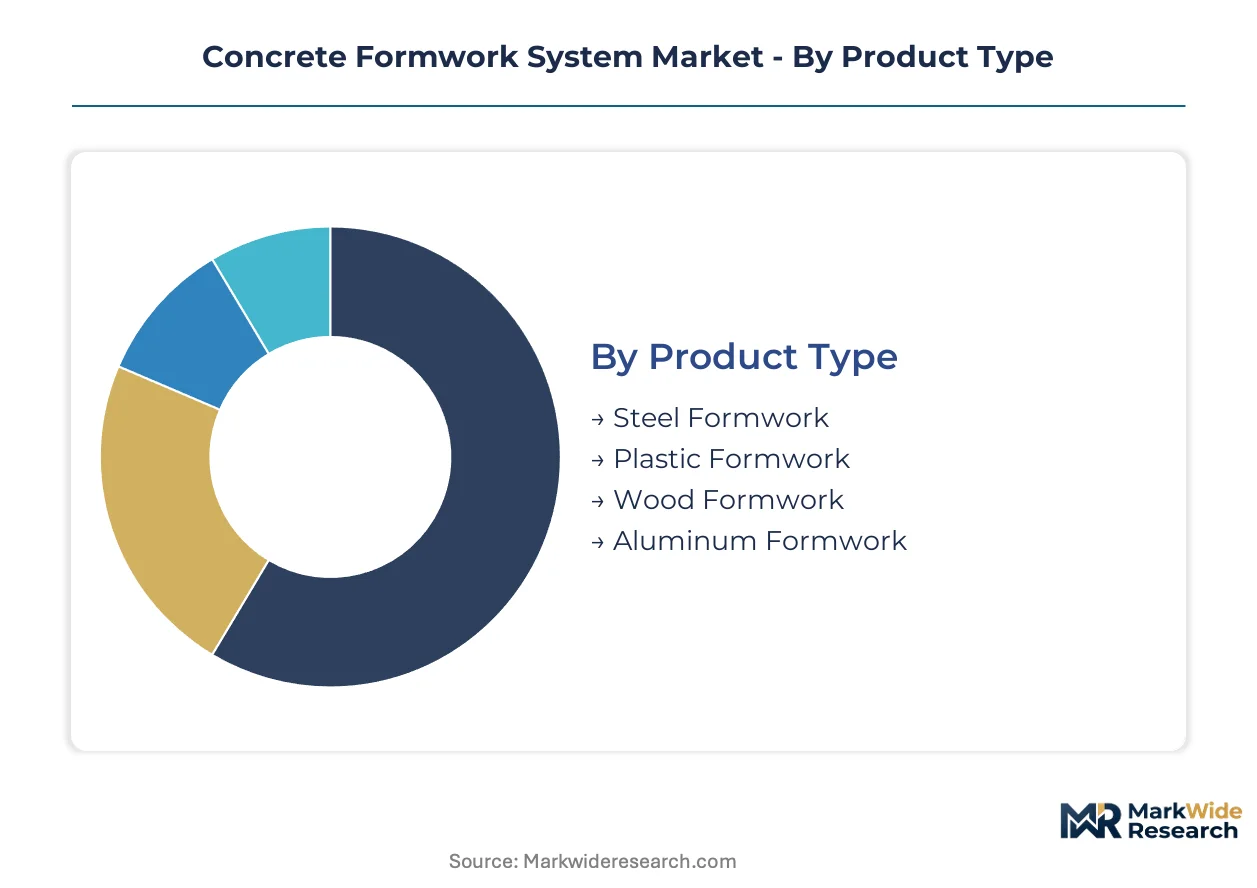
Margin pools concentrate in aluminum systems where fifty-plus reuse cycles justify first-cost premiums in high-rise residential, while steel captures infrastructure's deepest margins through load-bearing capacity that aluminum cannot match.
- Steel Formwork:Fabricated from high-tensile steel plates with welded reinforcement frames, engineered to withstand hydrostatic concrete pressures exceeding 100 kN/m² on bridge piers and tunnel linings. Infrastructure contractors in China's seismic zones specify GB 50666-compliant steel systems where aluminum deflection limits fail. Demand clusters on transportation megaprojects where permanent-structure liability exposure mandates documented load-bearing certification.
- Aluminum Formwork:Extruded 6061-T6 aluminum alloy panels with precision-machined connection nodes, achieving 4-5 day floor cycles in residential towers. Vietnam's urban corridor and India's Maharashtra cluster drive specification as foreign contractors deploy European-engineered modular platforms for commercial towers demanding rapid turnaround. BIS certification alignment accelerates displacement of traditional timber in public tenders.
- Plastic Formwork:Engineered polymer composites from polypropylene or fiberglass-reinforced resins, offering corrosion immunity in coastal chemical environments.
- Wood Formwork:Timber and plywood systems with limited reuse thresholds, retaining share in low-rise residential and temporary works where capital constraints block aluminum adoption.
The dominant share belongs to Steel Formwork, while Aluminum Formwork is closing the gap fastest.
Application:
Volume concentration tilts toward residential construction where repeatable floor plates reward systematized formwork investment, yet infrastructure projects sustain the longest contract tenures and deepest technical integration with engineering firms.
- Residential Construction:High-rise apartment towers and mass housing schemes requiring standardized slab and wall configurations that aluminum systems execute with minimal variation. India's tier-two cities and Vietnam's Ho Chi Minh City corridor concentrate demand as state-level green building incentives favor documented reuse thresholds above timber-intensive practices.
- Infrastructure Projects:Bridge piers, tunnel linings, and dam construction where hydrostatic loads and seismic forces exceed aluminum capacity. China's MEE enforcement of GB 50666 deflection limits locks steel specifications into transportation and water management tenders.
- Commercial Construction:Office towers and retail complexes with variable floor plates and accelerated schedules.
- Industrial Construction:Manufacturing facilities and power plants with specialized containment requirements.
Residential Construction holds the largest volume position, though Infrastructure Projects expand most quickly as India's BIS Eurocode alignment reshapes public procurement.
End User:
Procurement authority concentrates with contractors who control formwork selection through direct labor deployment and cycle-time accountability, while architects influence specification only where design complexity demands early technical integration.
- Contractors:General and specialty contractors with direct workforce deployment and pour-cycle accountability, selecting systems based on labor-hour economics and reuse depreciation models. Equipment-as-a-service leasing platforms in India's Karnataka and Maharashtra clusters target this segment with per-pour pricing that preserves balance-sheet flexibility.
- Developers:Project sponsors with capital allocation authority, increasingly mandating modular-reusable systems in sustainability-linked financing structures.
- Architects:Design professionals specifying formwork only where complex geometries require early technical coordination.
- Engineers:Structural consultants validating load-bearing calculations and seismic compliance documentation.
Contractors dominate specification authority, while Developers are gaining influence fastest through green building mandates and financing covenants.
Installation Method:
Technology maturity spreads unevenly across method types, with reusable and modular systems capturing specification share where labor scarcity and code convergence accelerate displacement of traditional timber-intensive approaches.
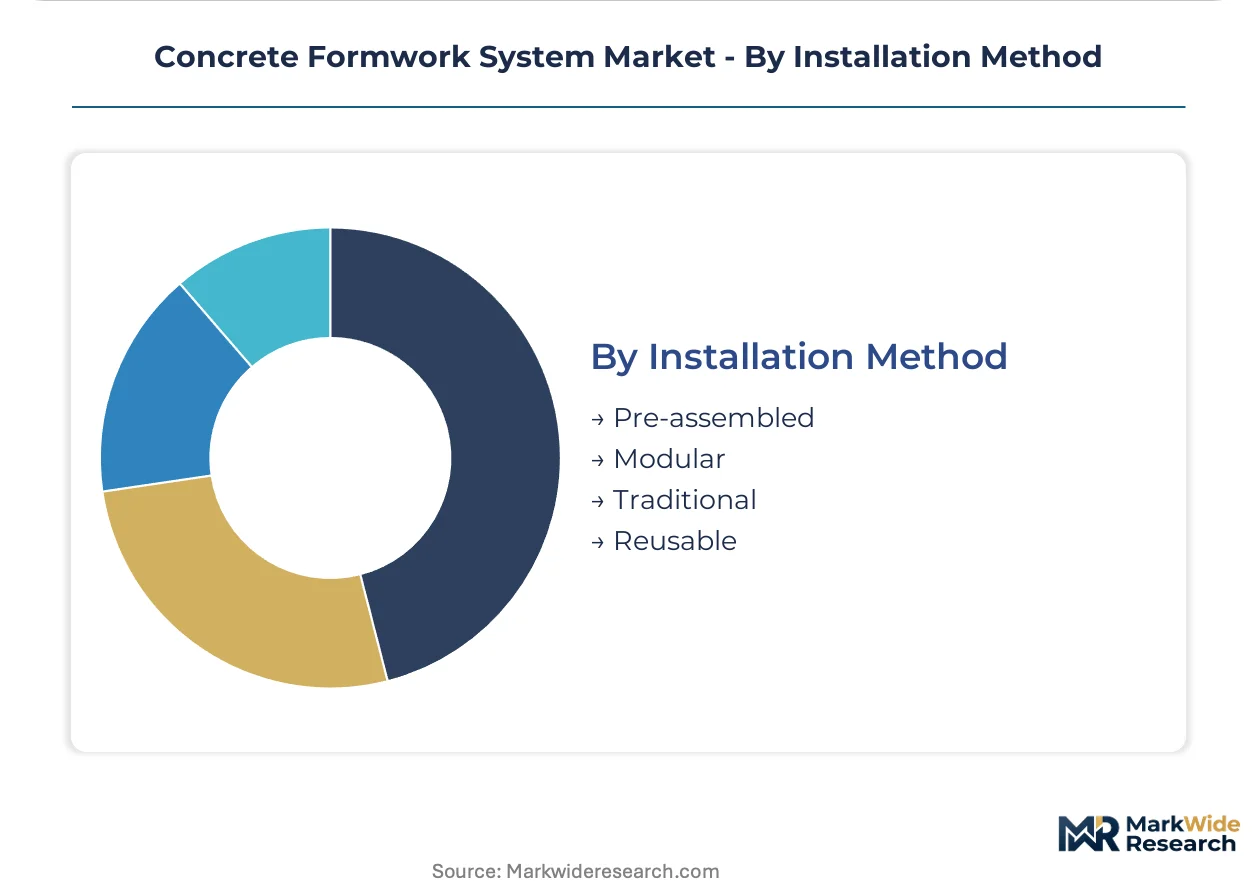
- Reusable:Systems designed for fifty-plus pour cycles with standardized panel inventories and documented inspection protocols, compressing cost-per-pour economics for mid-rise contractors. Singapore and Dubai contractors specify these for towers exceeding forty stories where self-climbing platforms integrate hydraulic ascent mechanisms.
- Modular:Pre-engineered panel configurations with parametric adaptability to varying floor plates, reducing on-site cutting and waste. European-engineered platforms dominate Vietnam's commercial tower segment.
- Pre-assembled:Factory-configured formwork units delivered to site for crane placement.
- Traditional:Timber-intensive site-built methods with high labor input and limited reuse.
Reusable systems command the leading specification share, with Modular methods climbing fastest as digital planning tools compress layout times.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for high-grade aluminum extrusions tilts trade balances toward Gulf state smelters and Chinese rolling mills, while finished system exports concentrate in German and Austrian engineering corridors serving Asian high-rise demand.
China
Domestic aluminum smelting capacity in Shandong and Xinjiang feeds captive extrusion supply for PERI Group and Doka Group manufacturing facilities. SAMR and MEE enforcement of GB 50666 seismic deflection limits accelerates displacement of timber-intensive methods in Sichuan-Chongqing high-rise zones. Yangtze River Delta contractors specify European-engineered modular platforms for commercial towers exceeding fifty stories.
India
BIS Eurocode alignment for structural materials reshapes procurement criteria in Maharashtra and Karnataka public infrastructure tenders. State-level green building incentives in Mumbai and Bangalore urban clusters favor documented reuse thresholds above traditional timber. Equipment-as-a-service leasing platforms target tier-two city contractors with per-pour pricing structures.
Vietnam
Ho Chi Minh City corridor concentrates foreign contractor deployment of aluminum systems for residential high-rises demanding rapid floor cycles. Building code convergence with Eurocode standards mandates higher load-bearing specifications than legacy timber methods accommodate. European-engineered modular platforms capture specification share in commercial tower segments.
Germany
Engineering-intensive formwork design anchors export competitiveness for PERI Group and Doka Group serving Asian and Middle Eastern markets. CE marking compliance under EN 12812 standards creates documentation advantages for EU-origin manufacturers. Bavaria-based R&D facilities drive digital planning tool integration that reduces on-site labor hours.
United Arab Emirates
Dubai and Abu Dhabi high-rise construction specifies self-climbing formwork platforms for towers exceeding forty stories. MOHAP building safety regulations align with EU Construction Products Regulation standards for dismantling-phase liability documentation. European system suppliers leverage regional logistics hubs for Gulf state project deployment.
Concrete Formwork System Market Competitive Environment
Concentration sits with German-engineered specialists commanding premium positioning through digital planning integration and aluminum extrusion supply control. The vendor base organizes across three tiers: integrated engineering houses with captive manufacturing, regional fabricators serving domestic infrastructure, and rental-platform operators aggregating asset-light service models. Strategic moves center on backward integration into aluminum extrusion capacity and BIM-software acquisition to compress layout-to-pour timelines.
Among German-origin engineering houses, PERI Group and Doka Group exemplify the integrated archetype combining R&D intensity with manufacturing scale. MEVA Formwork Systems occupies a position within the precision-fabrication tier through captive supply of high-grade aluminum extrusions. These three anchors demonstrate how European engineering heritage translates into specification authority for seismic-zone high-rise projects across Southeast Asia and the Middle East.
| Leading Market Players |
|---|
| MEVA Formwork Systems |
| Acrow |
| PERI Group |
| Alsina |
| EFCO |
| Doka Group |
| RMD Kwikform |
| PASCHAL Group |
| ULMA Construction |
| Others |
Value Chain & Pricing Dynamics
Project-based procurement contracts with multi-year offtake clauses dominate high-rise construction in Vietnam and India, locking contractors into aluminum extrusion supply from Chinese and Gulf state smelters while buffering against primary metal price swings through indexed pricing mechanisms. These structures bundle logistics, technical supervision, and reuse certification into per-pour economics that displace spot-market timber purchasing.
Pricing Analysis
General contractors anchor pricing structures around equipment-as-a-service leasing models with per-pour pricing that preserves balance-sheet flexibility. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked European-engineered systems from BIS-certified regional fabricators and unbranded timber alternatives. Cost compression in mid-tier aluminum systems is intensifying because energy-intensive smelting costs in Shandong and Xinjiang feed through to extrusion margins. Price sensitivity concentrates among liquidity-constrained developers in India's tier-two cities, while foreign contractors in Singapore and Dubai absorb premiums for self-climbing platforms with integrated safety systems.
Supply Chain Analysis
Inventory cycles stretch across six-to-eight week lead times for precision-machined connection nodes and tie-rod assemblies sourced from German and Austrian engineering corridors. Primary aluminum supply concentrates in China's Shandong and Xinjiang provinces, with secondary rolling capacity in the UAE and South Korea feeding regional fabrication hubs. Raw material dependencies center on 6061-T6 aluminum alloy billets, high-tensile steel plate for hybrid infrastructure projects, and engineered polymer resins for coastal corrosion-resistant applications. Single-source vulnerability sits with precision welding capacity scarcity constraining output scaling for manufacturers expanding high-grade extrusion supply. Distribution runs through regional logistics hubs in Dubai and Singapore serving Gulf state and Southeast Asian project deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GB 50666 seismic deflection mandates and India's BIS Eurocode alignment are compressing displacement timelines for timber-intensive methods, creating a high-growth disruption as modular-reusable systems capture specification share across Asian high-rise corridors.
For Market Incumbents: Secure captive supply of high-grade aluminum extrusions through backward integration into Shandong and Xinjiang smelter relationships, insulating margin predictability against primary metal price volatility. Invest in precision welding certification pipelines to overcome qualified technician scarcity constraining output scaling. Defend specification authority against emerging rental-platform operators by embedding BIM-integrated digital planning tools that compress layout-to-pour timelines for contractor clients. For New Entrants and Emerging Players: Anchor in India's Maharashtra and Karnataka equipment-as-a-service leasing markets where liquidity-constrained tier-two city contractors prioritize per-pour pricing over capital ownership. Target plastic composite formwork specifications in Vietnam's coastal chemical-exposure environments where aluminum fatigue accelerates and corrosion resistance commands premium positioning. Pursue go-to-market partnerships with European engineering houses seeking regional fabrication capacity for BIS-certified public tender compliance. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated specialists combining captive aluminum extrusion supply with digital planning software assets, positioned to capture margin pools as code convergence accelerates timber displacement. Long-term viability hinges on exposure to seismic-zone high-rise density in Vietnam and India rather than mature European replacement markets. Monitor India's state-level green building incentive adoption as the signal indicating procurement preference inflection toward documented reuse thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Captive supply from Shandong smelters insulates PERI and Doka against primary metal price volatility. |
| BIM-Integrated Digital Planning Acquisition | Software assets compress on-site labor hours for contractors adopting parametric layout tools. |
| Equipment-as-a-Service Platform Launch | Per-pour pricing structures penetrate India's tier-two cities where capital constraints block ownership. |
| Precision Welding Certification Pipeline | Qualified technician training gaps constrain output scaling for high-grade aluminum fabricators. |
| Plastic Composite Product Line Expansion | Corrosion-resistant engineered polymers capture coastal specifications where aluminum fatigue accelerates. |
Study Parameters
Desk research of customs trade data, SEC filings from construction equipment manufacturers, and GB/BIS regulatory documentation preceded structured interviews with general contractor procurement directors, aluminum extrusion plant managers, and formwork engineering specialists. Primary fieldwork across Vietnam's Ho Chi Minh City corridor and India's Maharashtra cluster validated secondary estimates of equipment-as-a-service contract structures. Bottom-up project pipeline analysis triangulated against top-down construction spending forecasts from national statistics offices.
Variance decomposition across material type, installation method, and end-user procurement authority shaped the analytical framework over the projection horizon. Modeled dimensions span steel-aluminum-plastic-wood product tiers, reusable-modular-traditional installation methods, and contractor-developer-architect procurement roles. CAGRs derived from historical displacement patterns of timber by aluminum in high-rise residential segments, calibrated against seismic code enforcement intensity in China and India. Forecast inputs incorporated primary aluminum price elasticity and qualified welding technician supply constraints.
Decision-makers should treat outputs as directional under assumptions of continued BIS Eurocode alignment and sustained GB 50666 enforcement intensity; material deviation in regulatory timelines or primary metal price trajectories would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Indonesia Ceramic Tiles Market
Building & Construction Materials
Softwood Lumber Market
Building & Construction Materials
Acoustical Ceiling Market
Building & Construction Materials
Concrete Conditioner Market
Building & Construction Materials
Japan Cross Laminated Timber (CLT) Market
Building & Construction Materials
US Commercial Windows Market
Building & Construction Materials
Sawn Timber Market
Building & Construction Materials
Building and Construction Plastic Fasteners Market
Building & Construction Materials
France Ceramic Tiles Market
Building & Construction Materials
Railing Market
Building & Construction Materials
Reclaimed Lumber Market
Building & Construction Materials
China UPVC Doors and Windows Market
Building & Construction Materials
Hollow Concrete Block Market
Building & Construction Materials
East Africa Gypsum Plaster Market
Building & Construction Materials
UPVC Doors and Windows Market
Building & Construction Materials
India Luxury Vinyl Tile (LVT) Market