
 Compact Fan Coils Market | 2026-2036
Compact Fan Coils Market Size, Share, and Industry Trends Forecast 2026-2036
Compact Fan Coils Market Insights
EU F-Gas Regulation is decoupling low-GWP refrigerant requirements from traditional compact fan coil architectures, forcing manufacturers to redesign heat exchanger geometries and coil circuitry. Johnson Controls International plc leverages its building automation integration to sustain specification capture in premium commercial projects. Carrier Global Corporation anchors its position through extensive contractor channel relationships across North American metropolitan construction corridors. Daikin Industries Ltd differentiates via inverter-driven fan coil platforms that navigate stringent seasonal efficiency thresholds.
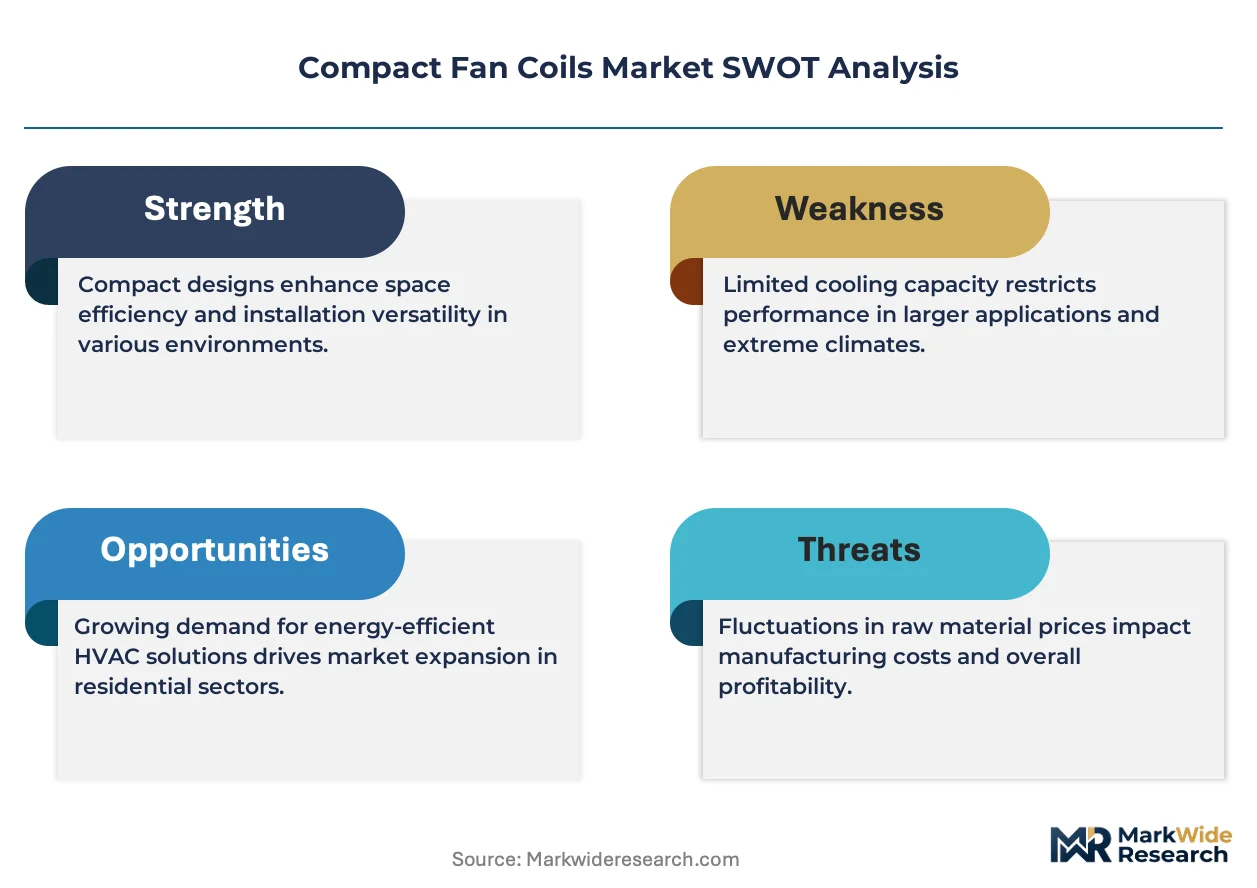
Compact fan coils are terminal HVAC units combining a finned-tube heat exchanger with a centrifugal or tangential fan, typically rated between 200 and 2,000 cubic feet per minute, designed for localized temperature control without ductwork distribution. These units serve primary comfort conditioning in multi-zone buildings where central air handling proves economically or spatially impractical. Horizontal configurations dominate existing stock in European commercial retrofits where ceiling void depth restricts vertical alternatives. Smart control mechanisms represent the fastest-expanding segment as BACnet and Modbus integration displace manual thermostatic valves in institutional and Class A office specifications. Digital programmable units occupy the densest margin pool by bridging first-cost sensitivity with energy code compliance in mid-tier commercial applications.
REACH restrictions on copper alloy compositions and EPA SNAP program rulings on refrigerant transitions are tightening material and working-fluid specifications for coil manufacturers serving transatlantic markets. CE marking under the EU Construction Products Regulation and ASHRAE 90.1 efficiency baselines collectively shape product development roadmaps and factory certification investments. Stakeholders must monitor evolving refrigerant phase-down schedules and building electrification mandates to align R&D allocation with emerging specification gatekeepers.
Market Dynamics
The EU F-Gas Regulation is forcing wholesale redesign of heat exchanger geometries as manufacturers decouple legacy coil architectures from high-GWP refrigerant dependencies. This regulatory pressure cascades through material specifications, factory certification investments, and contractor retraining requirements.
Growth Catalysts
- Building electrification mandates:German commercial refurbishment codes now prioritize electric heating solutions over fossil-fuel alternatives, accelerating specification of inverter-driven fan coil units in existing building stock.
- Smart control integration:BACnet and Modbus protocols are displacing manual thermostatic valves in Class A office and institutional projects, creating upgrade cycles across installed bases.
- Ceiling void constraints:Shallow plenum depths in European commercial retrofits favor horizontal compact configurations over vertical alternatives, locking in product form factors.
Market Restraints
- Copper alloy input volatility:REACH restrictions on specific copper alloy compositions constrain supplier pools and compress margins for coil manufacturers serving transatlantic markets.
- Refrigerant transition timelines:EPA SNAP program rulings create asynchronous phase-down schedules between North American and European jurisdictions, complicating inventory and SKU management.
- Technical ceiling on miniaturization:Heat transfer coefficients plateau as coil face areas shrink below 0.05 square meters, limiting performance gains in ultra-compact footprints.
Strategic Opportunities
- Underpenetrated Nordic markets:Sweden and Finland commercial HVAC refurbishment rates lag German benchmarks by approximately four years, presenting first-mover specification advantages.
- Data center precision cooling:Edge computing facilities require localized temperature control without ductwork distribution, matching compact fan coil core competencies.
- CSRD disclosure requirements:EU corporate sustainability reporting mandates are elevating embodied carbon metrics in procurement scoring, favoring manufacturers with verified low-carbon coil production.
Industry Challenges
- Refrigerant handling certification gaps:Field technician pools with low-GWP refrigerant credentials remain thin across contractor networks, slowing deployment velocity.
- ASHRAE 90.1 compliance testing:Seasonal efficiency verification protocols extend product development cycles and strain R&D resource allocation.
- Legacy BMS integration friction:Proprietary control protocols in existing building automation systems resist seamless smart fan coil retrofit, requiring custom gateway development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compact Fan Coils Market |
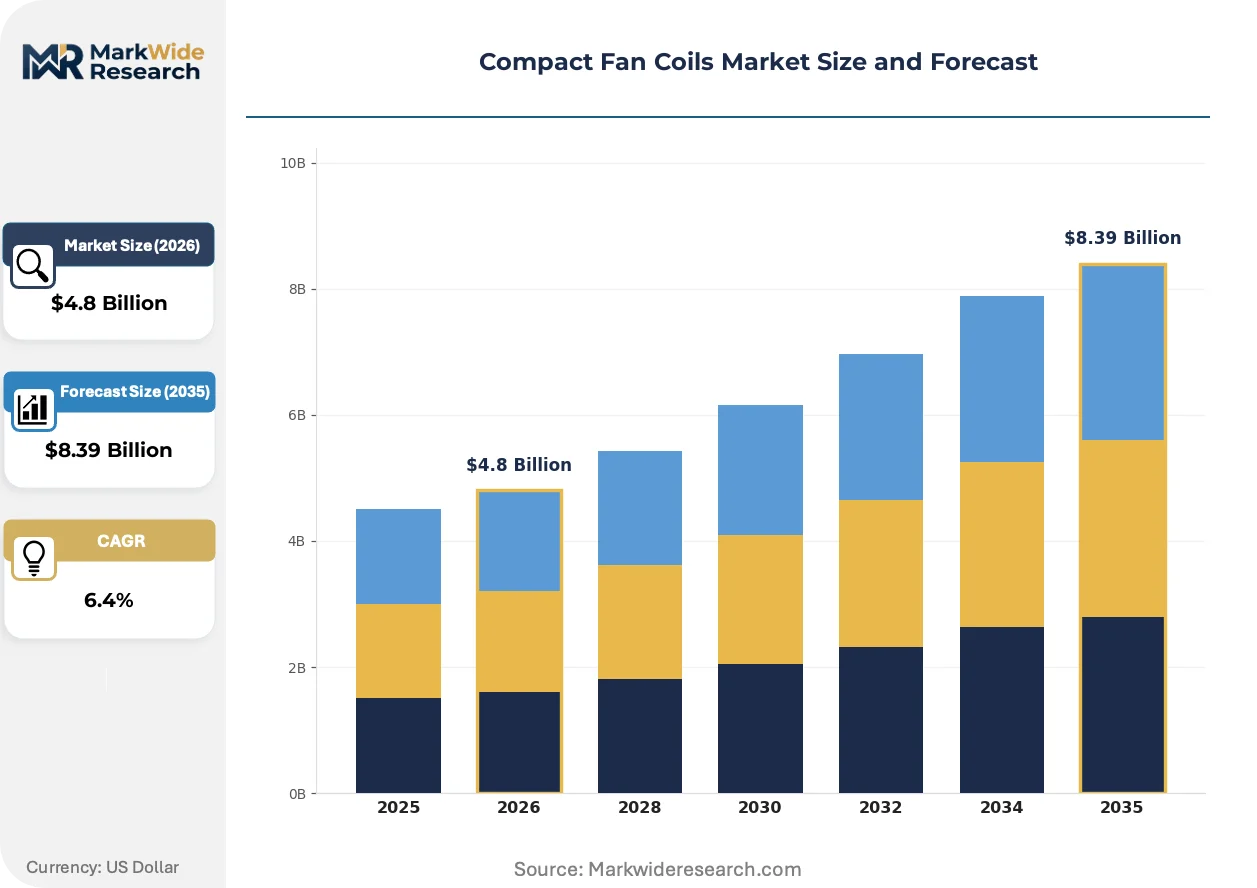
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal, Vertical, Ceiling Mounted, Universal Application: Commercial Buildings, Residential Spaces, Industrial Facilities, Institutional Structures Control Mechanism: Manual, Digital, Programmable, Smart End User: Architects, Contractors, Facility Managers, Homeowners |
| Companies Covered | Johnson Controls International plc, Carrier Global Corporation, Daikin Industries Ltd, Trane Technologies plc, Lennox International Inc, Mitsubishi Electric Corporation, TROX GmbH, Zehnder Group AG, Systemair AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compact Fan Coils Market Trends and Innovations
Digitalization of terminal HVAC units is compressing specification cycles and elevating software integration above hardware differentiation in procurement decisions. Three convergent developments are reshaping competitive positioning.
Microchannel aluminum heat exchangers are overtaking traditional copper-aluminum fin-tube constructions in compact fan coil designs. Data center operators and Nordic commercial developers specify these units for weight reduction and refrigerant charge minimization. The technology is overtaking conventional coil architectures in premium segments where lifecycle cost models dominate first-cost evaluation.
EU F-Gas Regulation amendments are tightening GWP thresholds for refrigerants in stationary HVAC equipment on accelerated timelines. Coil circuitry redesigns now prioritize compatibility with R-32 and R-454B blends ahead of hardware longevity tests. German and French specification engineers are pre-emptively excluding non-compliant units from tender documents eighteen months ahead of enforcement dates.
Outcome-based energy performance contracting is displacing traditional equipment-only procurement in institutional and multi-tenant commercial verticals. Energy service companies assume operational risk and specify fan coils with embedded metering and predictive maintenance capabilities. This model concentrates in Netherlands and Denmark markets where ESCO regulatory frameworks mature fastest.
Compact Fan Coils Market Segmentation
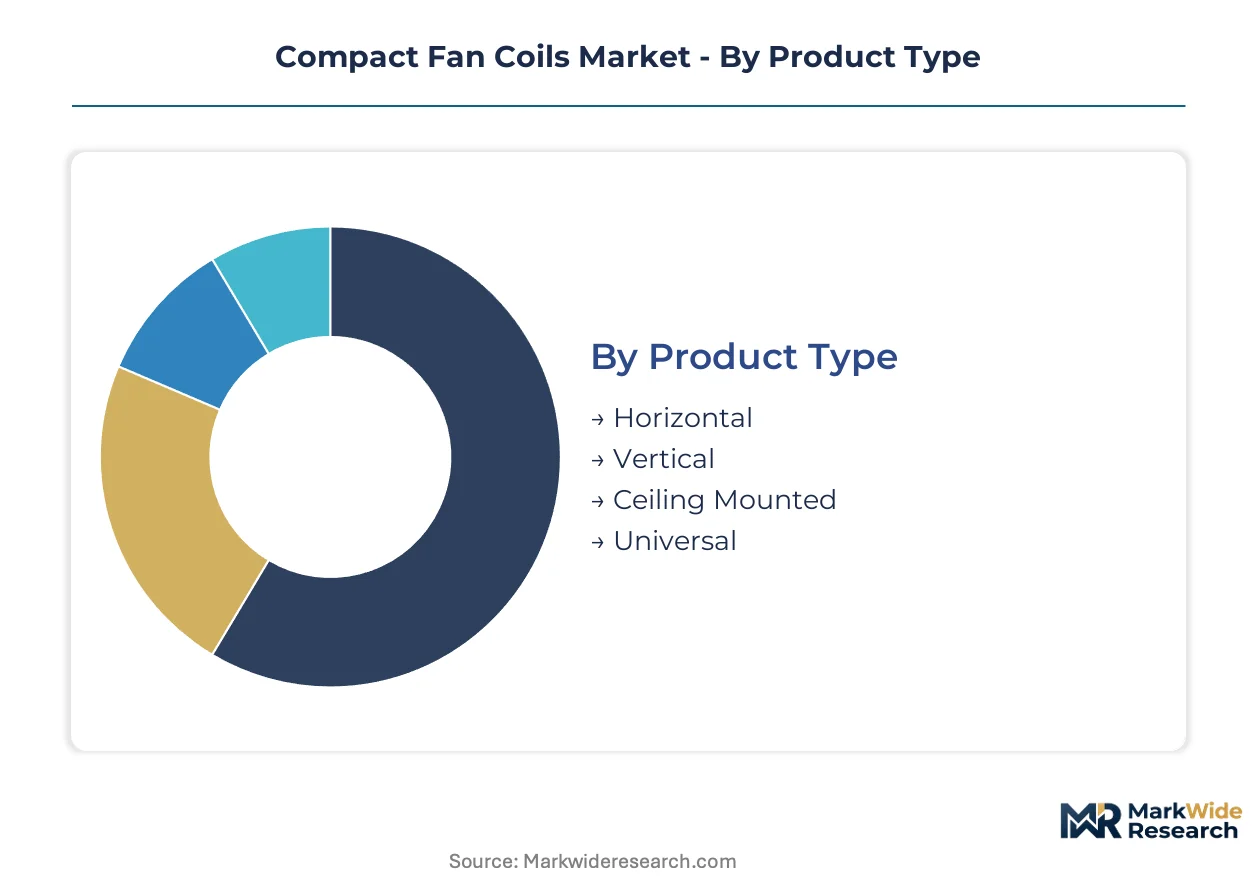
Compact fan coil specification diverges sharply across building typologies and control sophistication tiers. Procurement patterns cluster around installation constraints in retrofits versus performance optimization in new construction.
Product Type:
Heat exchanger orientation and mounting geometry determine spatial compatibility with existing building envelopes.
- Horizontal:Low-profile configurations fit shallow ceiling plenums common in European commercial refurbishments. German and French specification engineers prioritize these units where floor-to-floor heights restrict ducted alternatives.
- Vertical:Floor-standing or wall-mounted architectures serve perimeter zones in buildings lacking overhead service space. Demand concentrates in Nordic residential conversions and North American mixed-use developments.
- Ceiling Mounted:Cassette-style units integrate with suspended ceiling grids for discreet distribution. Preferred in Class A office fit-outs where aesthetic continuity matters.
- Universal:Convertible mounting hardware adapts to multiple orientations without field modification. Contractors specify these for phased renovation projects with uncertain final configurations.
Mature deployment sits with Horizontal configurations. Newer deployment is concentrated in Universal units.
Application:
Load profiles and occupancy patterns dictate coil sizing, fan selection, and control architecture.
- Commercial Buildings:Multi-zone offices and retail require zoned temperature control without centralized air handling. BACnet integration is displacing standalone thermostats in premium specifications.
- Residential Spaces:Individual apartment conditioning favors compact footprints and low acoustic signatures. European multifamily retrofits drive specification of inverter-driven platforms.
- Industrial Facilities:Process cooling and spot conditioning demand higher static pressure capabilities and corrosion-resistant coil coatings.
- Institutional Structures:Healthcare and education procurement prioritizes predictive maintenance integration and energy performance contracting compliance.
Commercial Buildings anchor current installed base. Institutional Structures are climbing the fastest as outcome-based procurement models expand.
Control Mechanism:
Automation integration depth separates commodity replacement from premium specification capture.
- Manual:Basic thermostatic valves serve cost-sensitive replacement cycles and residential owner-occupied stock.
- Digital:Electronic temperature setpoint control bridges first-cost constraints with baseline energy code compliance. Dominates mid-tier commercial applications.
- Programmable:Time-scheduled operation reduces runtime hours in intermittently occupied spaces. Facility managers specify these for tenant improvement projects.
- Smart:Embedded BACnet or Modbus communication enables centralized optimization and demand response participation. These units are gaining share fastest in Class A office and institutional verticals.
Digital controls dominate replacement volume. Smart mechanisms concentrate in new construction and deep energy retrofit specifications.
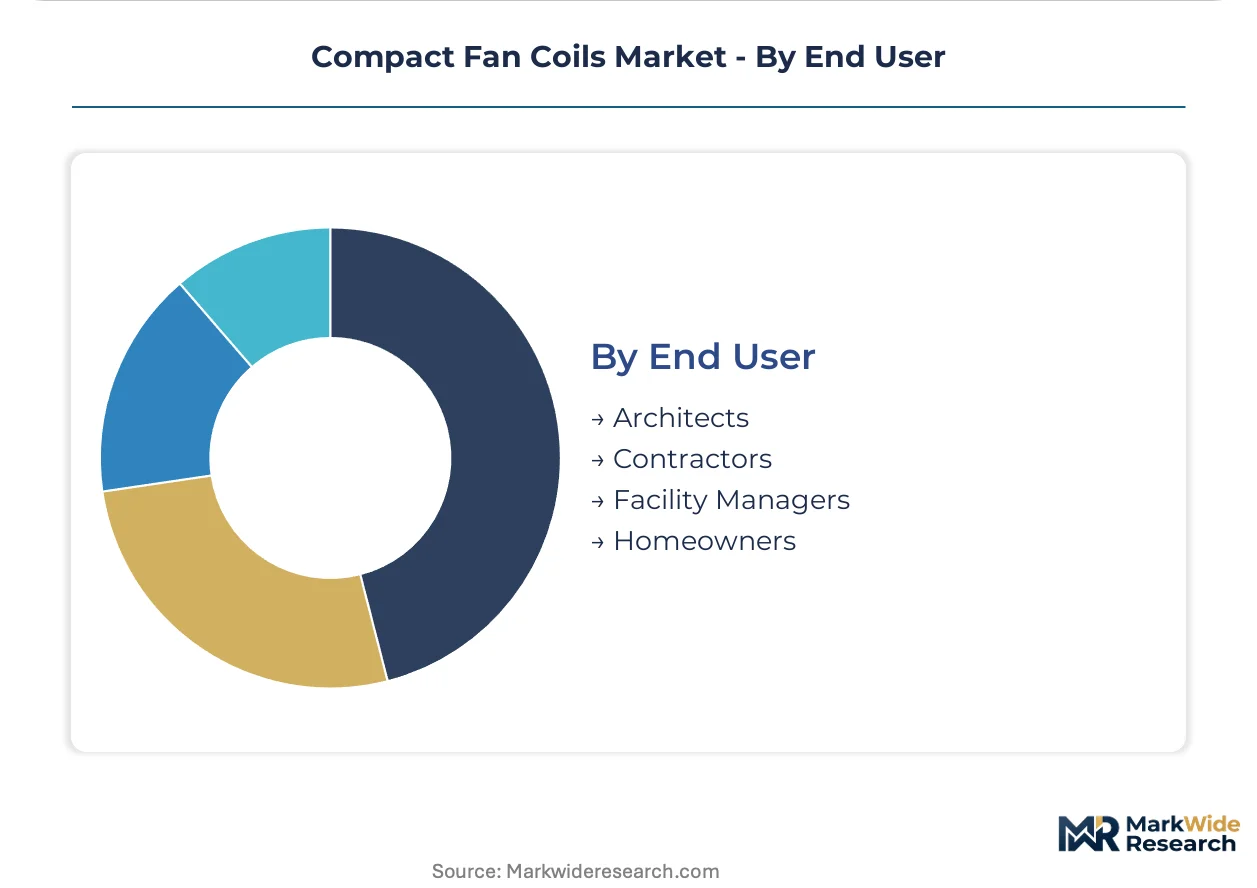
End User:
Specification authority and procurement criteria vary across project delivery roles.
- Architects:Early design-phase influence prioritizes spatial integration and aesthetic compatibility with ceiling systems.
- Contractors:Installation efficiency and inventory flexibility drive selection of standardized product families with broad application range.
- Facility Managers:Operational cost accountability elevates predictive maintenance capability and submetering integration in procurement scoring.
- Homeowners:First-cost sensitivity and acoustic comfort dominate residential self-directed purchases.
Contractors control replacement market volume. Facility Managers are expanding specification authority as performance contracting models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free economic zones in the UAE and Saudi Arabia are concentrating HVAC manufacturing capacity to serve Middle East commercial construction. German refurbishment codes and Nordic electrification mandates are pulling European specification patterns in divergent directions. Asian production clusters in Japan and South Korea are prioritizing inverter efficiency exports over domestic volume.
Germany
Commercial building refurbishment drives specification of horizontal compact fan coils in shallow ceiling plenums. The EU F-Gas Regulation accelerates coil redesigns for R-32 compatibility ahead of 2027 enforcement. The Rhine-Ruhr metropolitan corridor concentrates contractor networks trained in low-GWP refrigerant handling.
United States
Metropolitan construction corridors in Texas and Florida sustain replacement demand for digital-programmable units. EPA SNAP program rulings create asynchronous phase-down schedules complicating manufacturer SKU planning. The Southeast manufacturing belt anchors production of copper-aluminum fin-tube constructions for domestic and export markets.
United Arab Emirates
Data center precision cooling requirements match compact fan coil competencies for edge computing facilities. The country's national construction regulator mandates escalating efficiency baselines for commercial fit-outs. Dubai's free zones host assembly operations serving Gulf Cooperation Council specification flows.
Japan
Inverter-driven fan coil platforms navigate stringent seasonal efficiency thresholds in premium commercial segments. METI efficiency standards compress development cycles for heat exchanger miniaturization. The Kanto industrial corridor concentrates R&D investment in microchannel aluminum coil architectures.
Sweden
Commercial HVAC refurbishment rates lag German benchmarks, presenting first-mover specification advantages for compliant suppliers. The EU Green Deal accelerates building electrification mandates favoring electric heating solutions. Stockholm's district heating transition creates hybrid system opportunities integrating fan coils with low-temperature networks.
Compact Fan Coils Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered specification channels. The market structure consolidates around three strategic archetypes: building automation integrators capturing premium commercial projects, contractor-channel anchors dominating replacement volume, and inverter technology specialists differentiating on seasonal efficiency metrics. Dominant competitive moves include backward integration into coil manufacturing and strategic partnerships with energy service companies for outcome-based contracting models.
Within the building automation integrator tier, Johnson Controls International plc and Carrier Global Corporation exemplify specification capture through control system bundling. Daikin Industries Ltd anchors the inverter technology specialist position, while Trane Technologies plc and Mitsubishi Electric Corporation occupy scale-driven manufacturing positions. TROX GmbH and Zehnder Group AG represent European-focused engineering specialists, with Systemair AB exemplifying Nordic efficiency-led export positioning.
| Leading Market Players |
|---|
| Johnson Controls International plc |
| Carrier Global Corporation |
| Daikin Industries Ltd |
| Trane Technologies plc |
| Lennox International Inc |
| Mitsubishi Electric Corporation |
| TROX GmbH |
| Zehnder Group AG |
| Systemair AB |
| Others |
Pricing and Supply Chain Analysis
Copper alloy feedstock volatility cascades through coil manufacturing tiers, compressing margins at mid-market suppliers while premium manufacturers with captive metal sourcing maintain pricing power across project-based and spot procurement channels.
Pricing Analysis
Lead-time premiums separate procurement tiers, with contractors paying markups for sub-four-week delivery windows while stock inventory trades at spot discounts. Project-based contract pricing dominates institutional and data center verticals, locking in volume commitments against raw material escalators. Price differentiation hinges on CE marking tier and BACnet integration depth, with smart-enabled units commanding substantial premiums over digital-programmable baselines. Pricing pressure intensifies in the replacement segment as REACH-compliant copper sourcing constrains supplier pools. Residential homeowners exhibit the highest price sensitivity, while facility managers under performance contracting models prioritize lifecycle metrics over first cost.
Supply Chain Analysis
CE marking and EPA SNAP compliance certifications gate supplier participation, filtering out uncertified coil manufacturers from transatlantic specification flows. Manufacturing concentrates in Germany, the United States, and Japan, with each hub serving distinct regional regulatory clusters. Raw material dependencies center on copper tube stock, aluminum fin stock, and low-GWP refrigerant formulations. Single-source vulnerability runs through specialized microchannel aluminum extrusion capacity serving premium segment demand. Distribution runs through contractor-channel anchors in replacement markets and specification-engineer relationships in new construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-side constraints around REACH-compliant copper alloy sourcing prop pricing power for certified manufacturers, creating durable margin structures for incumbents with upstream metal relationships.
For Market Incumbents: Lock in specification capture by deepening backward integration into coil manufacturing and securing captive copper alloy supply arrangements. Counter refrigerant transition risk by accelerating R&D allocation to R-32 and R-454B compatible architectures ahead of EU F-Gas enforcement timelines. Channel control through energy service company partnerships anchors outcome-based contracting participation. For New Entrants and Emerging Players: Inverter-driven efficiency platforms offer a technology-first wedge into Nordic commercial refurbishment markets lagging German adoption curves. Target Sweden and Finland where specification engineer relationships remain less entrenched and electrification mandates favor electric heating solutions. Pursue data center precision cooling verticals where edge computing facility growth outpaces incumbent response capacity. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier European engineering specialists with established CE marking pathways and underutilized production capacity in the Rhine-Ruhr corridor. Long-term viability hinges on refrigerant transition readiness and smart control integration depth. Monitor EU F-Gas amendment enforcement dates as inflection indicators for specification exclusion risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coil Manufacturing | Captive heat exchanger production secures margin control against copper alloy volatility. |
| Low-GWP Refrigerant Platform Transition | R-32 and R-454B compatibility ensures EU F-Gas Regulation compliance ahead of enforcement. |
| Smart Control Protocol Certification | BACnet and Modbus integration unlocks Class A office and institutional specification capture. |
| ESCO Partnership Development | Outcome-based energy performance contracting concentrates procurement authority in Netherlands and Denmark markets. |
| Nordic Market Specification Engineering | First-mover positioning in Sweden and Finland commercial refurbishment lags German benchmarks. |
Research Methodology
Trade association filings, customs import records, and SEC 10-K disclosures formed the secondary backbone, supplemented by technical documentation from EU F-Gas Regulation implementation guidance. Primary interviews with HVAC specification engineers, contractor procurement managers, facility operations directors, and refrigerant handling certification bodies validated demand-side assumptions. Bottom-up unit shipment estimates triangulated against top-down construction spend allocation models across commercial building verticals.
Historical trendline analysis of compact fan coil shipments tracked product type evolution, control mechanism adoption curves, and application mix shifts across the analysis window. Segmentation modeling incorporated heat exchanger orientation, mounting geometry, automation integration depth, and end-user specification authority. CAGRs derived from regression against construction output indices, electrification mandate timelines, and refrigerant phase-down schedules. Forecast inputs weighted German refurbishment code stringency and Nordic electrification policy divergence.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU F-Gas enforcement or copper alloy supply disruption scenarios. Model outputs reflect assumptions regarding contractor retraining velocity and low-GWP refrigerant credential expansion. A model refresh is warranted upon material change in building electrification mandate timelines or REACH restriction amendments affecting copper alloy compositions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
HVAC Pumps Market
HVAC Equipment
United Kingdom Commercial HVAC Market
HVAC Equipment
Germany Commercial HVAC Market
HVAC Equipment
India Residential Heat Pump Market
HVAC Equipment
US HVAC Systems Market
HVAC Equipment
Canada Commercial HVAC Market
HVAC Equipment
GCC Kitchen Hood Market
HVAC Equipment
Industrial Boiler Market
HVAC Equipment
Desert Air Cooler Market
HVAC Equipment
Helical Screw Blowers Market
HVAC Equipment
South America Compressor Market
HVAC Equipment
Air-Conditioning Natural Convection Refrigerator Market
HVAC Equipment
Industrial Air Heaters Market
HVAC Equipment
United Kingdom District Heating Market
HVAC Equipment
Global Radiant Floor Heating Market
HVAC Equipment
Global Submerged Coil Heat Exchanger Market