
 Wall Fan Coil Market | 2026-2036
Wall Fan Coil Market Size, Share, and Industry Trends Forecast 2026-2036
Wall Fan Coil Market Analytics
EU Green Deal compliance is pivoting the cost-of-entry calculus for wall fan coil manufacturers serving European commercial buildings. Daikin Industries leverages its hydronic technology leadership to anchor premium positioning across Japanese and Southeast Asian projects. Carrier Global Corporation competes through captive supply of compressors and heat exchangers, sustaining margin control in North American hospitality retrofits. Johnson Controls specializes in building automation integration, differentiating its wall fan coil offerings through native BACnet connectivity that facility managers prioritize.
A wall fan coil is a terminal HVAC unit that houses a finned-tube heat exchanger and centrifugal blower within a compact cabinet, typically rated between 200 and 2,000 CFM and designed for zone-level temperature modulation without ductwork distribution. The unit draws return air through a filter, passes it across the coil where circulating hot or chilled water modulates temperature, then discharges conditioned air directly into the occupied space. Wall mounted configurations occupy the largest installed base across European residential towers, though mini fan coil units represent the fastest-growing category as Asian developers squeeze HVAC equipment into shrinking apartment footprints. Hydronic technology leads absolute volume given superior efficiency at part-load conditions, while VRF-linked fan coils capture expanding margin pools in Middle Eastern commercial towers seeking centralized refrigerant distribution with zonal fan coil terminals.
EPA energy conservation standards and the EU F-Gas Regulation together constrain refrigerant selection and minimum efficiency thresholds for equipment sold into their respective jurisdictions, effectively filtering out low-efficiency imports from unbranded Chinese assemblers. BIS certification requirements in India and GB standards enforcement by SAMR in China impose additional testing burdens that favor manufacturers with established in-country laboratories. Stakeholders must monitor how refrigerant phase-down schedules and embodied carbon disclosure rules reshape supplier qualification criteria before committing to long-term procurement contracts.
Market Dynamics
The EU Green Deal's building energy performance mandates are compressing replacement cycles across European commercial real estate, forcing facility managers to retire legacy HVAC terminals ahead of depreciation schedules.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of high-GWP refrigerants accelerates hydronic system retrofits in German and French office towers, creating replacement demand for water-based fan coil terminals.
- India's PLI scheme:Domestic manufacturing incentives for HVAC components reduce landed costs for hydronic coil assemblies, expanding addressable volume in Mumbai and Delhi NCR residential developments.
- Chilled beam substitution limits:Technical constraints in ceiling height and structural load capacity preserve wall-mounted fan coils as the only viable zonal solution in retrofit scenarios across aging European housing stock.
Market Restraints
- Copper price volatility:Coil manufacturing absorbs 40-60% raw material exposure to London Metal Exchange copper futures, compressing margins when commodity cycles spike.
- Chinese component concentration:Centrifugal blower motors and EC motor drives cluster in Zhejiang and Guangdong provinces, creating single-source vulnerability for European and North American assemblers.
- VRF system substitution:Refrigerant-based variable refrigerant flow terminals capture margin in new-build Middle Eastern commercial towers, constraining hydronic fan coil penetration in greenfield projects.
Strategic Opportunities
- US Inflation Reduction Act:Commercial building energy efficiency tax credits lower net installed cost for qualifying hydronic systems, expanding retrofit feasibility in Class B office inventory.
- Mini fan coil emergence:Shrinking residential footprints in Tokyo and Seoul drive demand for sub-400 CFM units that integrate with compact hydronic distribution loops.
- Building automation convergence:Native BACnet and Modbus integration creates premium positioning for fan coils specified in smart building tenders across Singapore and Sydney.
Industry Challenges
- Certification timeline compression:BIS testing queues in India and SAMR approval cycles in China extend product launch lead times by 8-14 months for new coil configurations.
- EC motor skill scarcity:Field commissioning of electronically commutated blower motors requires controls expertise that HVAC contractor networks in secondary US markets lack.
- Legacy hydronic integration:Mismatched flow rates and delta-T requirements between new fan coils and aging European two-pipe systems generate callback rates above category norms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wall Fan Coil Market |
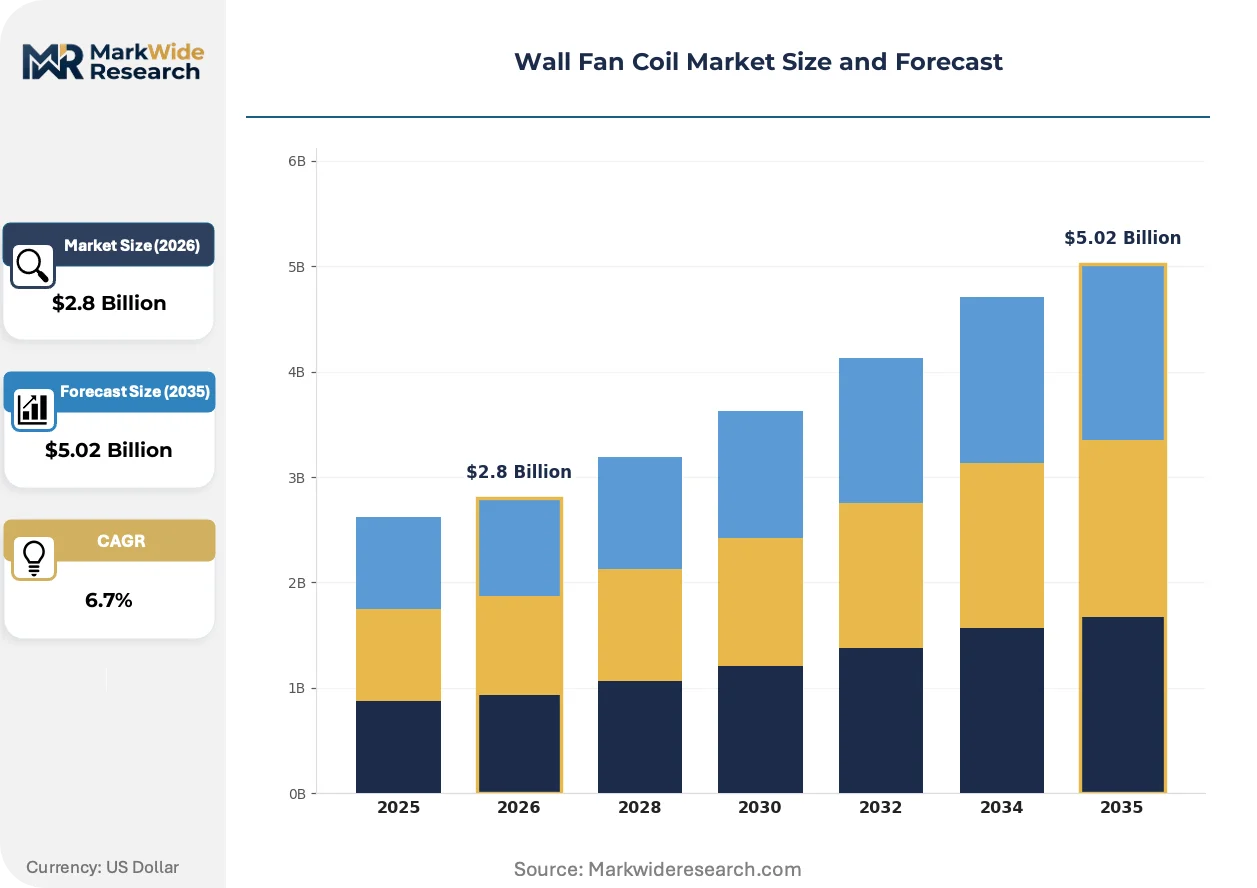
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceiling Mounted, Wall Mounted, Floor Mounted, Mini Fan Coil Technology: Hydronic, Electric, Hybrid, VRF Application: Residential, Commercial, Hospitality, Industrial End User: Property Developers, HVAC Contractors, Building Owners, Facility Managers |
| Companies Covered | Daikin Industries, Carrier Global Corporation, Johnson Controls, Trane Technologies, Mitsubishi Electric, LG Electronics, Panasonic Corporation, Hitachi, Systemair, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wall Fan Coil Market Evolving Landscape
Product development priorities are pivoting from thermal capacity benchmarks to connectivity and embodied carbon metrics, reshaping R&D allocation across the supplier base.
Brushless DC motor technology is overtaking shaded-pole and AC induction alternatives in premium wall fan coil specifications. European facility managers specify EC motors for part-load efficiency gains in variable-flow hydronic systems. The technology is overtaking legacy motor architectures by enabling 30-50% fan energy reduction at reduced coil loads, compressing total cost-of-ownership calculations in lifecycle procurement.
REACH and RoHS substance restrictions are tightening coil coating and insulation material specifications across EU member states. Manufacturers reformulate fin treatments and cabinet linings to eliminate restricted phthalates and heavy metal pigments. Hydronic units with certified low-embodied-carbon heat exchangers capture specification preference in Netherlands and Denmark public sector tenders.
Lifecycle service contracts are displacing transactional equipment sales in UK and German commercial property portfolios. Institutional landlords bundle fan coil maintenance with building automation subscriptions, unbundling capital expenditure from operational budgets. This procurement evolution concentrates buyer power with facilities management integrators and compresses direct OEM relationships.
Wall Fan Coil Market Segmentation
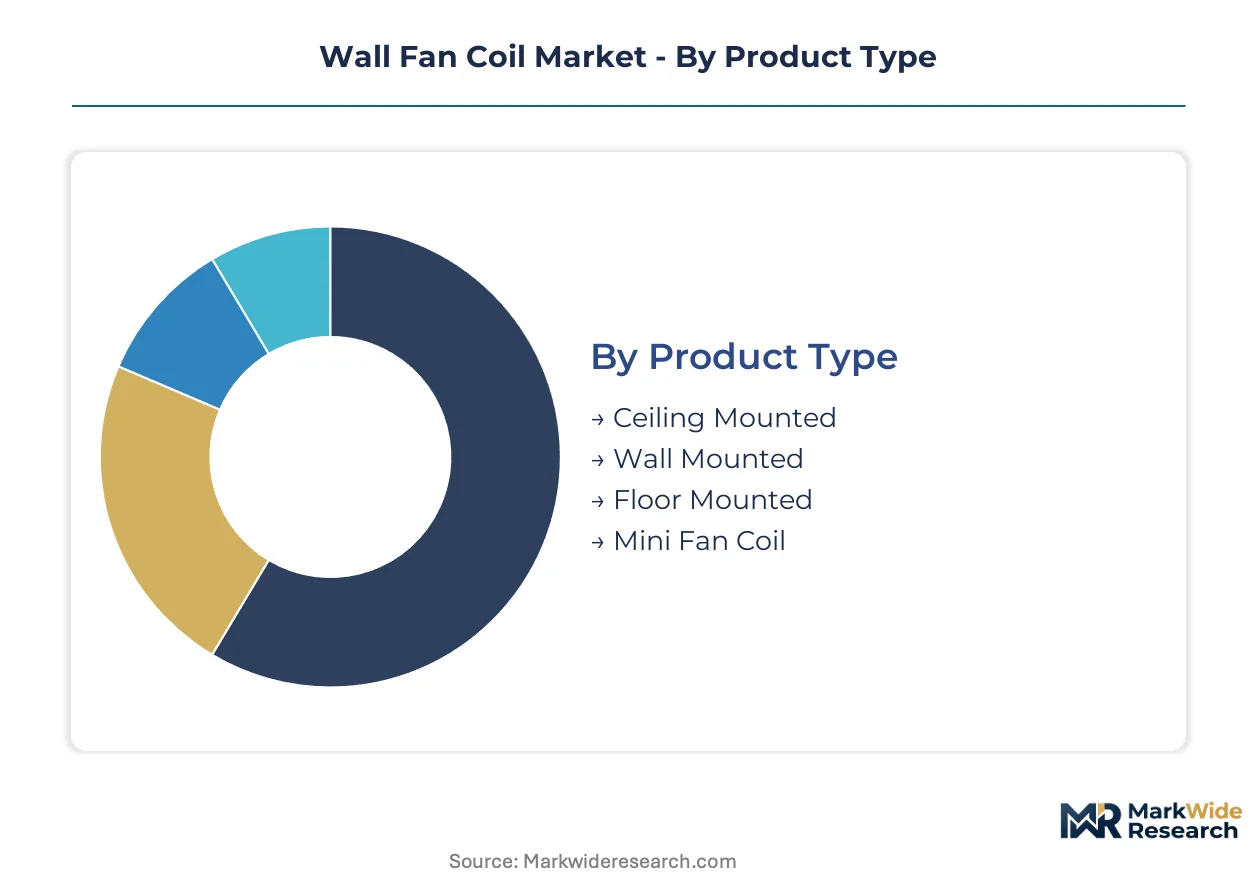
Wall fan coil procurement varies sharply by mounting configuration and thermal transfer method, with integration depth determining whether units operate as standalone terminals or as embedded nodes within centralized plant networks. Specification patterns diverge across residential retrofit, commercial new-build, and hospitality refurbishment contexts, each imposing distinct constraints on airflow capacity, control protocol, and physical envelope.
Product Type:
Standalone wall-mounted units dominate replacement cycles in aging European housing stock, while embedded mini configurations integrate into compact hydronic loops that developers favor for shrinking apartment footprints.
- Wall Mounted:These units house finned-tube coils and centrifugal blowers in cabinets rated 400-1,200 CFM, designed for perimeter zone conditioning without ductwork. Demand concentrates in German and French office retrofits where EU Green Deal mandates force premature retirement of legacy terminals, with facility managers prioritizing units that slip into existing architectural envelopes.
- Mini Fan Coil:Sub-400 CFM terminals squeeze into ceiling voids and utility closets that standard cabinets cannot occupy. Tokyo and Seoul residential developers specify these for micro-apartments where every square meter commands premium valuation, driving the steepest expansion trajectory across the product matrix.
- Ceiling Mounted:Recessed configurations serve hotel guest rooms and hospital wards requiring unobtrusive air distribution.
- Floor Mounted:Low-level discharge units address perimeter heating loads in Nordic residential towers with large glazing fractions.
Volume placements concentrate in Wall Mounted configurations; the faster expansion belongs to Mini Fan Coil terminals.
Technology:
Cost tier stratification separates premium hydronic systems from entry-level electric resistance alternatives, with hybrid and VRF-linked variants capturing margin in specialized applications.
- Hydronic:Water-based heat exchange delivers superior part-load efficiency through variable-speed pumps and modulating valves. Facility managers across China, India, and the United States specify these for lifecycle cost optimization, with coil assemblies absorbing 40-60% copper exposure that manufacturers hedge through London Metal Exchange positions.
- VRF:Refrigerant-linked fan coils connect to centralized variable refrigerant flow plants, enabling individual zone control without hydronic distribution infrastructure. Middle Eastern commercial towers in Dubai and Riyadh deploy these for centralized plant efficiency, though EU F-Gas Regulation phasedown schedules constrain refrigerant selection in European applications.
- Electric:Resistance-heated units serve retrofit scenarios where hydronic infrastructure proves cost-prohibitive to extend.
- Hybrid:Dual-source configurations combine hydronic cooling with electric backup heating for transitional climates.
Commercial procurement favors Hydronic technology for operating cost control; VRF-linked systems gain share fastest in greenfield Middle Eastern developments.
Application:
Customer maturity divides segments between price-sensitive residential volume and specification-intensive commercial performance tiers.
- Commercial:Office towers, retail podiums, and institutional buildings demand native BACnet connectivity and EC motor drives for building automation integration. Class B office inventory in the United States accesses Inflation Reduction Act tax credits that lower net installed cost for qualifying hydronic retrofits.
- Hospitality:Hotels and serviced apartments prioritize acoustic performance and rapid commissioning to minimize revenue disruption during refurbishment. Johnson Controls and Carrier Global Corporation compete through lifecycle service contracts that bundle maintenance with automation subscriptions.
- Residential:Property developers in Mumbai and Delhi NCR specify cost-optimized units under India's PLI scheme for HVAC components.
- Industrial:Manufacturing facilities and warehouses accept higher noise thresholds for thermal capacity.
Commercial applications absorb the largest equipment value; Hospitality retrofits climb fastest as institutional landlords consolidate procurement through facilities management integrators.
End User:
Supply channel configuration shapes how specifications flow from design intent to installed equipment, with direct OEM relationships compressing as service bundling concentrates buyer power.
- Facility Managers:Institutional landlords and corporate real estate operators prioritize total cost-of-ownership metrics and native protocol integration. These stakeholders specify EC motors and certified low-embodied-carbon heat exchangers for Netherlands and Denmark public sector tenders.
- HVAC Contractors:Installation networks in secondary US markets face skill scarcity in EC motor commissioning, generating callback rates above category norms when field crews lack controls expertise.
- Property Developers:Volume purchasers in Asian residential markets drive mini fan coil adoption through footprint constraints.
- Building Owners:Single-asset proprietors balance capital constraints against operating cost exposure.
Procurement volume aggregates through Facility Managers; HVAC Contractors represent the fastest-expanding specification channel as service contracts displace transactional sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones across the UAE and China's coastal provinces concentrate manufacturing capacity for wall fan coil exports, while India's PLI scheme for HVAC components redirects investment toward domestic coil assembly plants.
Germany
Commercial office retrofits in Frankfurt and Munich accelerate as the EU Green Deal tightens building energy performance standards. The EU F-Gas Regulation phases down high-GWP refrigerants, forcing facility managers toward hydronic terminals. Bavaria's industrial corridor hosts precision coil fabricators supplying premium units for Netherlands and Denmark public sector tenders.
United States
Class B office inventory in Chicago and Atlanta accesses Inflation Reduction Act tax credits that lower net installed cost for qualifying hydronic retrofits. EPA energy conservation standards filter out low-efficiency imports from unbranded assemblers. The Southeast contractor network faces EC motor commissioning skill gaps that generate callback rates above category norms.
China
GB standards enforcement by SAMR imposes testing burdens that favor manufacturers with established in-country laboratories in the Yangtze River Delta. Hydronic technology dominates procurement among facility managers across Shanghai and Beijing developments. Zhejiang and Guangdong provinces cluster centrifugal blower motor and EC motor drive production, creating single-source vulnerability for European assemblers.
India
Mumbai and Delhi NCR residential developments drive volume demand under the PLI scheme for HVAC components that reduces landed costs for hydronic coil assemblies. BIS certification requirements extend product launch lead times by 8-14 months for new configurations. Gujarat's manufacturing belt attracts coil assembly investment seeking export access to Middle Eastern commercial towers.
United Arab Emirates
Dubai and Riyadh commercial towers specify VRF-linked fan coils for centralized refrigerant distribution with zonal terminals. Free Trade Zone incentives concentrate re-export assembly capacity serving African and South Asian markets. The country's building automation convergence creates specification preference for native BACnet connectivity in smart building tenders.
Wall Fan Coil Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The supplier base stratifies between integrated HVAC majors controlling captive component supply and regional fabricators competing on landed cost. Three archetypes dominate: full-system integrators with automation platforms, component-scale manufacturers with coil expertise, and service-bundle providers capturing lifecycle contracts. Capacity expansion and strategic partnerships represent the dominant competitive vectors as players secure blower motor supply and certification laboratory access.
Among diversified Japanese industrials, Daikin Industries and Mitsubishi Electric occupy positions anchoring premium hydronic technology leadership across Southeast Asian projects. Carrier Global Corporation exemplifies the North American full-system archetype with compressor and heat exchanger supply integration. Johnson Controls sits within the building automation convergence tier, representing native protocol connectivity specialization that facility managers prioritize in smart building specifications.
| Leading Market Players |
|---|
| Daikin Industries |
| Carrier Global Corporation |
| Johnson Controls |
| Trane Technologies |
| Mitsubishi Electric |
| LG Electronics |
| Panasonic Corporation |
| Hitachi |
| Systemair |
| Others |
Value Network & Pricing Analysis
EC motor commissioning expertise clusters in Germany's Bavarian industrial corridor and China's Yangtze River Delta, creating labor-cost differentials that translate into 15-20% pricing spreads between premium certified units and standard-grade alternatives. Facility managers in Netherlands and Denmark public sector tenders absorb these premiums for lifecycle-optimized hydronic terminals, while Mumbai residential developers under India's PLI scheme prioritize landed-cost minimization.
Pricing Analysis
Short lead-time premiums command 8-12% markups over standard 12-16 week delivery cycles, with spot inventory from Zhejiang assemblers trading at discounts for buyers accepting unbranded EC motor drives. Three-tier pricing structure across premium, standard, and economy levels separates BACnet-native building automation units from basic hydronic terminals and electric resistance retrofit alternatives. Cost compression in the economy tier is intensifying because BIS certification queues extend product launch timelines, forcing inventory carry costs onto distributors. Property developers in Asian residential markets exhibit highest price sensitivity; facility managers in EU Green Deal compliance scenarios prioritize total cost-of-ownership metrics over upfront capital expenditure.
Supply Chain Analysis
India's PLI scheme for HVAC components and China's GB standards enforcement by SAMR are reshaping sourcing patterns, redirecting coil assembly investment toward Gujarat's manufacturing belt and Yangtze River Delta laboratory clusters. Centrifugal blower motors and EC motor drives concentrate in Zhejiang and Guangdong provinces; copper coil assemblies feed from Chilean and Indonesian smelter networks. Single-source vulnerability in Chinese motor production creates tariff exposure for European and North American assemblers seeking alternative qualified suppliers. Distribution runs through facilities management integrators in UK and German commercial property portfolios, compressing direct OEM relationships as lifecycle service contracts displace transactional equipment sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around manufacturers controlling captive component supply and certification laboratory access, with EU F-Gas Regulation compliance timelines forcing sub-scale fabricators toward exit or acquisition.
For Market Incumbents: Hedge copper price exposure through London Metal Exchange positions and backward integration into coil manufacturing. Secure blower motor supply agreements with Zhejiang producers before certification timeline compression extends lead times further. Prioritize in-house EC motor commissioning training networks to address skill scarcity generating callback rates above category norms in secondary US markets. For New Entrants and Emerging Players: The US Inflation Reduction Act opens a window for Class B office retrofit specialists capturing tax credit-enabled demand in Chicago and Atlanta. Target mini fan coil white space in Tokyo and Seoul micro-apartment developments where footprint constraints outpace incumbent R&D cycles. Enter through native BACnet integration partnerships with building automation platforms rather than competing on thermal capacity benchmarks alone. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier hydronic specialists possessing SAMR-approved laboratories and established Middle Eastern VRF project references, given chilled beam substitution limits preserving wall-mounted fan coils as the only viable zonal solution in European retrofit scenarios. Monitor copper futures backwardation as inflection indicator for margin compression severity across coil-dependent assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Laboratory Investment | SAMR and BIS approval cycles favor manufacturers with in-country testing capacity, compressing launch timelines by 8-14 months. |
| EC Motor Supply Agreement | Long-term contracts with Zhejiang motor producers lock in blower drive availability before single-source vulnerability intensifies. |
| Lifecycle Service Contract Bundling | UK and German facilities management integrators concentrate procurement power through maintenance-automation subscription packages. |
| Copper Hedging Program | London Metal Exchange positions protect margin on coil assemblies absorbing 40-60% raw material cost exposure. |
| Native BACnet Integration | Singapore and Sydney smart building tenders specify protocol-native fan coils, creating premium positioning for controls-capable suppliers. |
Research Methodology
Document review covered regulatory filings with EPA and EU F-Gas Regulation databases, SAMR GB standards documentation, and BIS certification records, complemented by interviews with facility managers at institutional landlords, HVAC contractor network heads in secondary US markets, and procurement leads at Mumbai and Delhi NCR residential developers. Secondary validation drew from customs data on centrifugal blower motor trade flows, London Metal Exchange copper futures positioning reports, and building automation tender specifications from Singapore and Sydney. Bottom-up unit economics triangulated against top-down addressable market sizing across the analysis window.
The modeling framework produced volume and value trajectories segmented by mounting configuration, thermal transfer technology, application context, and end-user procurement channel. CAGRs derived from regression analysis against EU Green Deal implementation timelines, India's PLI scheme capacity buildout curves, and US Inflation Reduction Act tax credit uptake patterns. Hydronic distribution loop penetration rates and VRF system substitution thresholds served as industry-specific demand elasticity inputs throughout the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for refrigerant-based variable refrigerant flow terminals in Middle Eastern greenfield developments would alter the outlook for hydronic fan coil penetration. Forecasts reflect assumptions on copper price stability, certification queue durations, and EC motor skill diffusion rates that supply-side disruptions or regulatory acceleration could revise. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
North America Gas Water Heater Market
HVAC Equipment
Ventilation Equipment Market
HVAC Equipment
Thermocompressors Market
HVAC Equipment
Heating Radiator Market
HVAC Equipment
Commercial RAC PD Compressor Market
HVAC Equipment
Brazed Plate Heat Exchangers Market
HVAC Equipment
Asia-Pacific Heating Equipment Market
HVAC Equipment
Cooling Tower Market
HVAC Equipment
Industrial Heating Equipment Market
HVAC Equipment
Industrial Dehumidifiers Market
HVAC Equipment
Global VRF System Market
HVAC Equipment
Heavy Duty Heat Pump Market
HVAC Equipment
HVAC Air Handling Units Market
HVAC Equipment
HVAC Systems Market
HVAC Equipment
Heating and Cooling Market
HVAC Equipment
Compressor Controllers Market