
 Heating and Cooling Market | 2026-2036
Heating and Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Heating and Cooling Market Analysis
Buyer concentration across the commercial building sector is rebalancing toward large-scale property management groups and institutional real estate portfolios. Daikin Industries leverages its captive compressor manufacturing to control cost structures across VRF product lines. Carrier Global Corporation anchors North American service infrastructure through its extensive dealer network. Trane Technologies plc differentiates on building automation integration, competing for premium retrofit contracts in aging urban cores.
Heating and cooling encompasses engineered thermal management systems that regulate indoor air temperature, humidity, and quality through vapor-compression cycles, combustion processes, or heat transfer fluids operating across specified COP and EER performance bands. HVAC Systems occupy the largest installed base but face margin compression from commoditized maintenance services; Heat Pumps capture the fastest expansion trajectory as electrification mandates displace fossil-fuel furnaces in residential and light-commercial settings. Smart Thermostats within the technology dimension concentrate software margin pools, while Geothermal applications remain niche due to high upfront drilling and loop-field costs.
US EPA refrigerant phase-down rules under the AIM Act and F-Gas Regulation in Europe are forcing manufacturers to redesign equipment around lower-GWP working fluids such as R-32 and R-454B. Japan's METI energy-efficiency standards and China's GB national standards for unitary air conditioners collectively shape export compliance burdens for multinational suppliers. Stakeholders must monitor refrigerant transition timelines against manufacturing retooling cycles to avoid stranded inventory in channels.
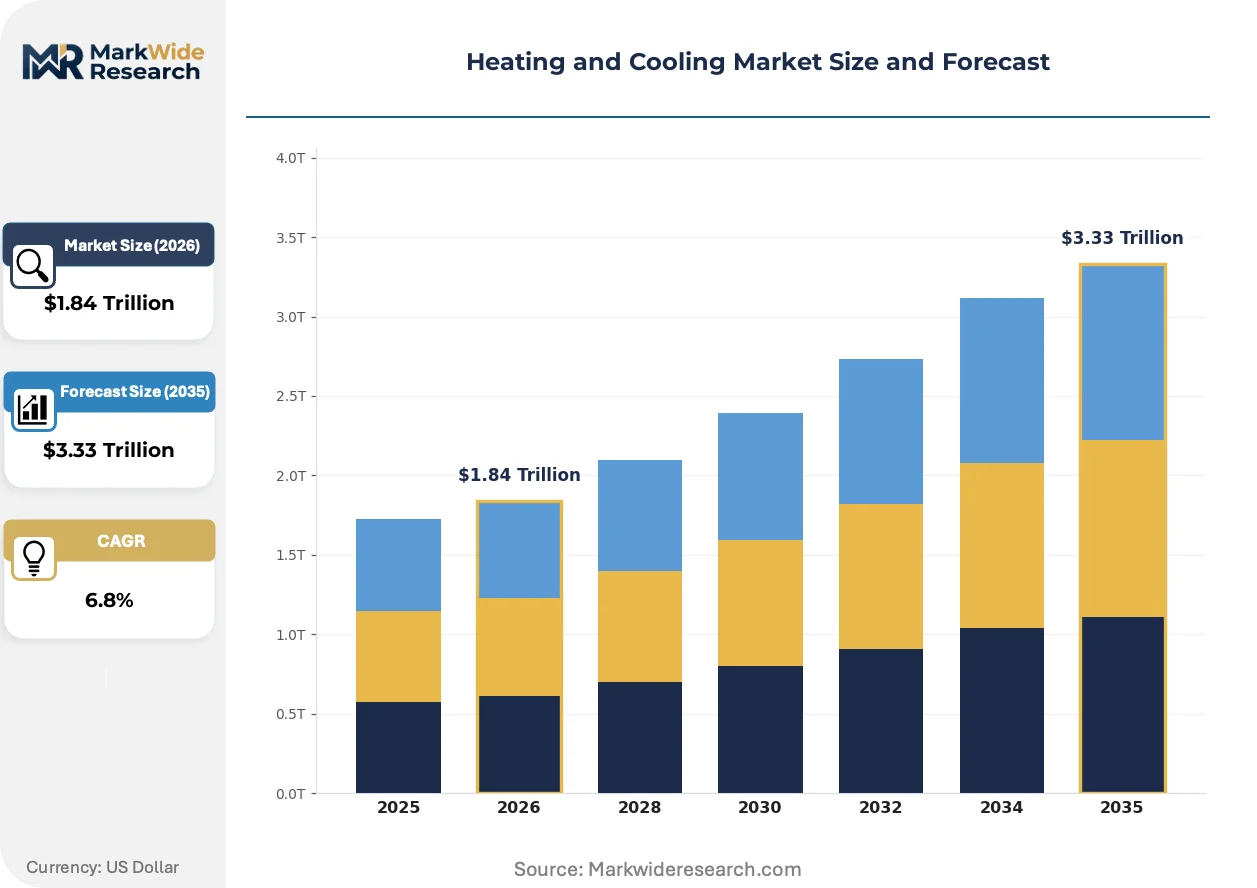
Market Dynamics
The refrigerant transition under the US AIM Act and EU F-Gas Regulation is forcing simultaneous equipment redesign and manufacturing retooling across compressor, heat exchanger, and system assembly tiers.
Growth Catalysts
- Electrification Mandates:Jurisdictions across Germany, France, and the Netherlands now prohibit fossil-fuel heating in new construction, accelerating heat pump deployment in residential retrofits.
- Data Center Expansion:Hyperscale cloud operators in Northern Virginia, Frankfurt, and Singapore are deploying liquid cooling and precision air handling at scale to manage AI workload thermal densities.
- Tax Credit Architecture:The US Inflation Reduction Act's Section 25C and 25D provisions reduce installed cost barriers for cold-climate heat pumps in Midwest and Northeast housing stock.
Market Restraints
- Copper and Aluminum Volatility:Coil and tubing raw material costs swing with commodity markets, compressing margins on unitary equipment during procurement cycles.
- Compressor Supply Concentration:Rotating machinery production clusters in China and Japan create single-source vulnerability for OEMs lacking captive manufacturing.
- Refrigerant Patent Thickets:Proprietary blends and lubricant formulations under Honeywell and Chemours licensing structures inflate working fluid costs versus legacy R-410A.
Strategic Opportunities
- Service Contract Penetration:Predictive maintenance subscriptions using IoT sensor networks remain underdeveloped in light-commercial and multi-family residential installed bases.
- R-32 Conversion Window:Equipment lines redesigned for mildly flammable A2L refrigerants capture efficiency premiums in Japan, Australia, and Southeast Asian export markets.
- Geothermal District Loops:Campus and master-planned community thermal energy networks in Denmark, Sweden, and the Netherlands demonstrate scalable fifth-generation district heating models.
Industry Challenges
- Refrigerant Handling Certification:Technician licensing for A2L and A3 flammable working fluids lags equipment availability in North American and European service channels.
- Controls Integration Complexity:Legacy pneumatic and early digital building automation systems resist seamless integration with modern BACnet and Modbus heat pump controllers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heating and Cooling Market |
| Market Size in 2026 | $1.84 Trillion |
| Market Size in 2035 | $3.33 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HVAC Systems, Heat Pumps, Air Conditioners, Furnaces Technology: Smart Thermostats, Variable Refrigerant Flow, Geothermal, Radiant Heating End User: Residential Sector, Commercial Buildings, Industrial Facilities, Construction Application: Heating, Cooling, Ventilation, Indoor Air Quality |
| Companies Covered | Carrier Global Corporation, Daikin Industries Ltd., Trane Technologies plc, Lennox International Inc., LG Electronics, Mitsubishi Electric Corporation, Johnson Controls, Honeywell International Inc., Midea, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heating and Cooling Market Emerging Trajectories
Equipment architecture is fragmenting into configurable subsystems as manufacturers seek to decouple refrigerant circuits from air handling and control intelligence for faster regional customization.
Variable refrigerant flow technology is modularizing around self-contained outdoor units with swappable compressor modules and field-expandable piping networks. Multi-tenant commercial developers in Japan and South Korea specify these configurations to phase HVAC capital deployment across lease-up timelines. This modularity compresses lead times for mid-rise residential and mixed-use projects while reducing stranded capacity risk.
The EU F-Gas Regulation's phase-down schedule and the US EPA's Technology Transitions program under the AIM Act are synchronizing refrigerant transitions across major export markets. Equipment OEMs must maintain parallel R-454B and R-32 product lines to serve divergent regional compliance timelines. Cold-climate heat pump categories face the steepest redesign burden as they balance low-GWP requirements with heating capacity retention at ambient temperatures below minus 15 degrees Celsius.
Building owners are unbundling equipment procurement from installation and long-term service, creating disaggregated vendor relationships. Institutional real estate portfolios in London, New York, and Sydney now separately contract engineering firms for design, mechanical contractors for installation, and third-party asset managers for lifecycle performance guarantees. This fragmentation pressures traditional manufacturer-dealer channels to defend attachment rates for controls, monitoring, and preventive maintenance contracts.
Heating and Cooling Market Segmentation
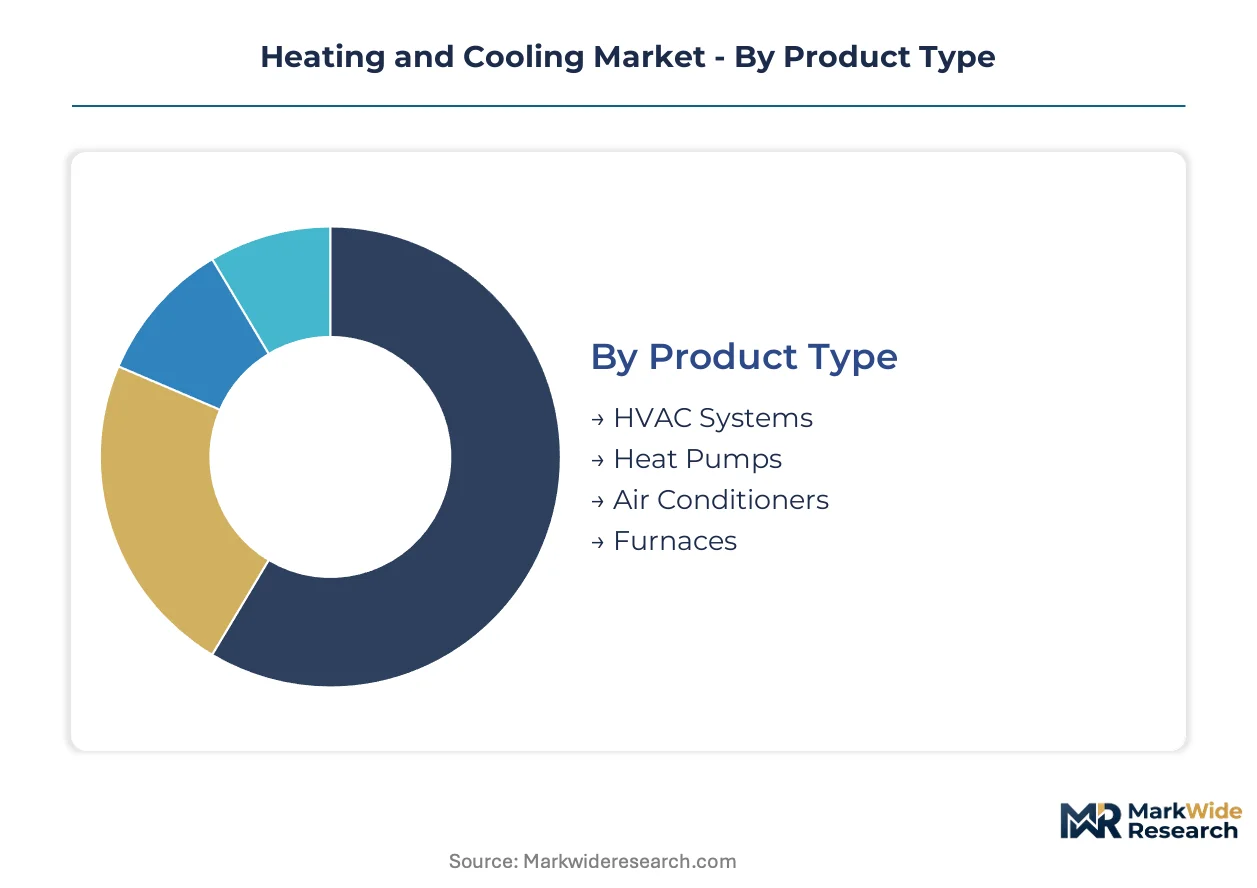
Segmentation in heating and cooling reveals how equipment specifications, control intelligence, and thermal delivery methods map to distinct procurement budgets and regulatory compliance tiers. Buyers optimize across capital cost, operating efficiency, and electrification mandates when selecting system architectures.
Product Type:
Equipment categories diverge by thermodynamic cycle, fuel source, and integration complexity with building envelopes.
- HVAC Systems:Integrated assemblies combining vapor-compression cooling, gas or electric heating, and air distribution through duct networks. Demand concentrates in US commercial retrofits where ASHRAE efficiency standards and local building codes drive full-system replacements rather than component upgrades.
- Heat Pumps:Refrigeration-based systems that reverse thermodynamic cycles to extract ambient heat for space conditioning. Deployment is accelerating in Germany, France, and the Netherlands where fossil-fuel heating bans in new construction create captive demand for air-source and ground-source variants.
- Air Conditioners:Dedicated cooling units spanning window-mounted, split-system, and packaged rooftop configurations. Southeast Asian urbanization and Middle Eastern construction activity sustain volume concentration despite efficiency regulations tightening across ASEAN markets.
- Furnaces:Combustion-based heating equipment utilizing natural gas, propane, or fuel oil. Replacement cycles dominate in existing US Midwest and Northeast housing stock where gas distribution infrastructure and cold-climate heating loads resist immediate electrification.
Mature deployment sits with HVAC Systems. Newer deployment is concentrated in Heat Pumps.
Technology:
Control and thermal delivery innovations reshape margin distribution between hardware manufacturers and software platforms.
- Smart Thermostats:Networked environmental controllers with occupancy sensing, weather forecasting, and demand-response integration. North American residential adoption is climbing fastest where utility rebate programs and time-of-use electricity pricing create payback visibility for homeowners.
- Variable Refrigerant Flow:Refrigerant-based zoning systems modulating compressor speed and refrigerant distribution to match real-time thermal loads. Japanese and South Korean multi-tenant developers specify VRF for phased lease-up flexibility in mid-rise residential and mixed-use assets.
- Geothermal:Ground-coupled heat pumps utilizing subsurface thermal stability for heating and cooling. High upfront drilling and loop-field costs restrict adoption to institutional campuses and master-planned communities in Denmark, Sweden, and the Netherlands with district-scale thermal infrastructure.
- Radiant Heating:Surface-based thermal distribution through hydronic tubing or electric elements embedded in floors, walls, or ceilings. Premium residential construction in Germany and Austria favors radiant systems for thermal comfort and compatibility with low-temperature heat pump supply.
Software margin pools concentrate in Smart Thermostats. Hardware differentiation centers on Variable Refrigerant Flow.
End User:
Customer archetypes separate by procurement sophistication, lifecycle cost horizons, and regulatory exposure.
- Residential Sector:Single-family and multi-family households purchasing equipment through contractor channels or retail distribution. US Inflation Reduction Act tax credits are restructuring substitution economics for cold-climate heat pumps in Midwest and Northeast states.
- Commercial Buildings:Office, retail, hospitality, and healthcare facilities with professional facility management. Large-scale property management groups and institutional real estate portfolios in London, New York, and Sydney are unbundling procurement from installation and long-term service contracts.
- Industrial Facilities:Manufacturing, warehousing, and process environments with specialized ventilation and process cooling requirements. Data center operators in Northern Virginia, Frankfurt, and Singapore deploy precision air handling and liquid cooling for AI workload thermal densities.
- Construction:New-build developers and general contractors specifying equipment during design and pre-construction phases. Electrification mandates in Germany, France, and the Netherlands are eliminating fossil-fuel options from new residential specifications.
Service contract penetration is deepest in Commercial Buildings. Equipment specification authority is shifting toward Construction channels.
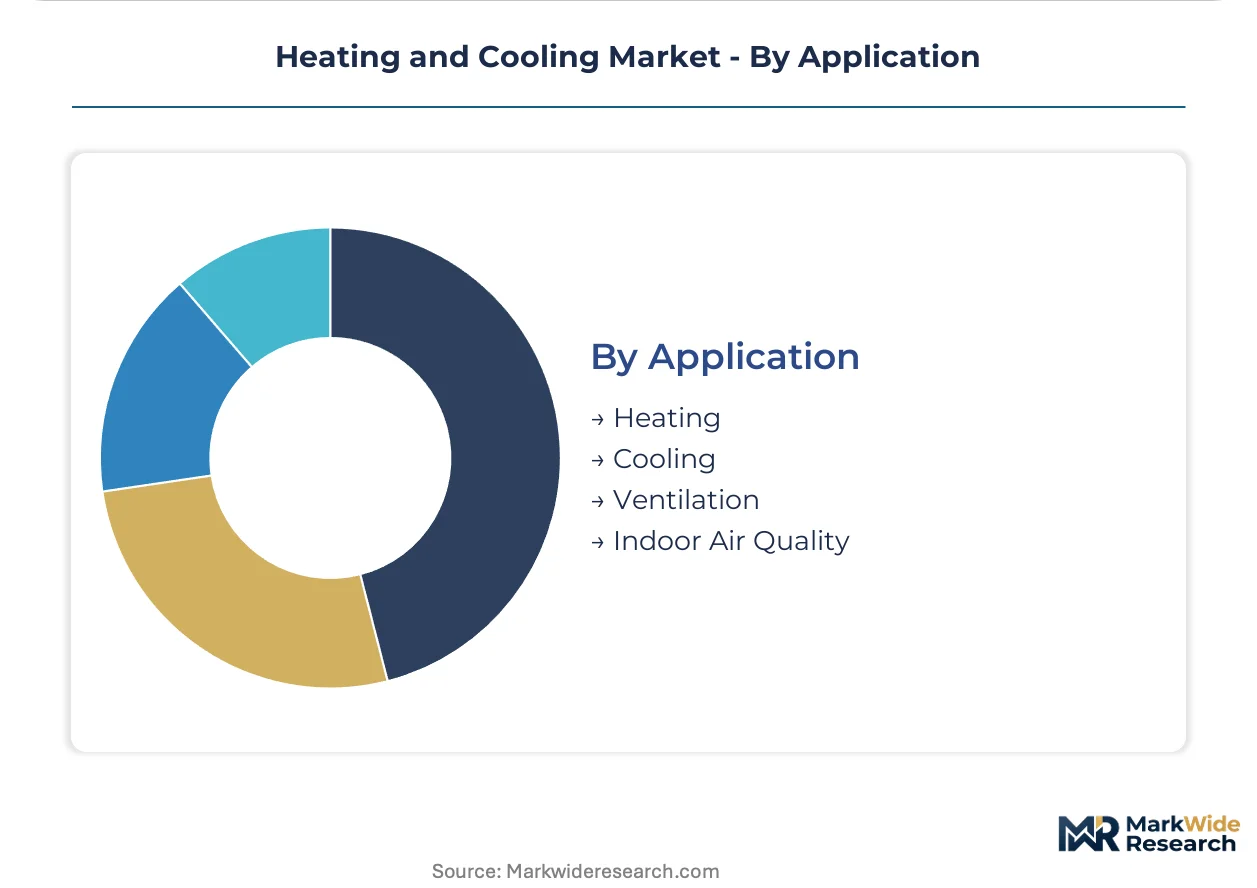
Application:
Functional use cases determine performance metrics, regulatory compliance thresholds, and integration with building automation.
- Heating:Space warming through combustion, electric resistance, or heat pump thermodynamic cycles. Electrification mandates are displacing fossil-fuel furnaces in residential and light-commercial settings across European jurisdictions.
- Cooling:Temperature reduction and humidity control through vapor-compression or absorption refrigeration. Data center cooling systems represent the fastest-expanding end-use segment as digital infrastructure scales.
- Ventilation:Outdoor air introduction and exhaust for indoor air quality and contaminant dilution. Post-pandemic building code revisions in California and New York are tightening minimum ventilation rate requirements.
- Indoor Air Quality:Filtration, purification, and humidity management beyond basic thermal conditioning. Healthcare and education facilities in Japan and South Korea specify advanced IAQ packages as differentiated amenities.
Regulatory pressure is most intense on Heating applications. Technology innovation is concentrating in Cooling systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper mining clusters in Chile and Zambia supply coil and tubing raw materials that anchor equipment manufacturing economics across major demand centers. Regional markets diverge sharply by electrification policy intensity, refrigerant regulation timelines, and data center construction velocity.
United States
Midwest and Northeast housing stock drives cold-climate heat pump deployment as IRA tax credits reduce installed cost barriers. EPA's AIM Act Technology Transitions program mandates R-454B and R-32 equipment redesigns by 2025-2028. Northern Virginia's hyperscale data center corridor consumes precision air handling and liquid cooling systems at unprecedented density.
China
GB national standards for unitary air conditioners shape export compliance burdens for multinational suppliers seeking market access. MIIT energy-efficiency mandates accelerate domestic heat pump manufacturing scale-up in Shandong and Guangdong provinces. Yangtze River Delta industrial clusters concentrate compressor and heat exchanger component production for regional OEM supply.
Germany
Fossil-fuel heating bans in new construction create captive demand for air-source and ground-source heat pump variants across residential retrofits. EU F-Gas Regulation phase-down schedules force simultaneous equipment redesign and manufacturing retooling. Bavaria's manufacturing belt hosts captive compressor production facilities serving Central European distribution networks.
Japan
METI energy-efficiency standards drive premium VRF system development for multi-tenant commercial developers in Tokyo and Osaka. Domestic OEMs leverage captive compressor manufacturing to control cost structures across product lines. Kanto region engineering centers specialize in low-GWP refrigerant integration for Southeast Asian export markets.
India
Rapid urbanization in Maharashtra and Karnataka sustains volume concentration for split-system and packaged rooftop air conditioners despite tightening ASEAN efficiency regulations. BIS certification requirements for cooling equipment create compliance differentiation between organized and unorganized manufacturing tiers. Gujarat industrial corridors attract component assembly investments serving Middle East and African export demand.
Heating and Cooling Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue smart controls and predictive maintenance software layers. The vendor base stratifies across three tiers: integrated multinationals with captive compressor manufacturing, regional assemblers dependent on imported rotating machinery, and software platforms unbundling controls from hardware. Three strategic archetypes dominate: cost-structure defenders leveraging backward integration, specification influencers capturing premium retrofit contracts, and service aggregators consolidating fragmented maintenance channels. Competitive intensity concentrates on M&A activity targeting controls capabilities and capacity expansion in lower-GWP refrigerant-compatible production lines.
Within the integrated multinational tier, Carrier Global Corporation, Daikin Industries Ltd., and Trane Technologies plc exemplify divergent strategic positioning. Carrier anchors North American service infrastructure through extensive dealer networks. Daikin leverages captive compressor manufacturing to control cost structures across VRF product lines. Trane occupies a position differentiated on building automation integration, competing for premium retrofit contracts in aging urban cores. These three represent how geographic origin and structural choices produce distinct competitive vectors without requiring identical capability investments.
| Leading Market Players |
|---|
| Carrier Global Corporation |
| Daikin Industries Ltd. |
| Trane Technologies plc |
| Lennox International Inc. |
| LG Electronics |
| Mitsubishi Electric Corporation |
| Johnson Controls |
| Honeywell International Inc. |
| Midea |
| Others |
Supply Flow & Price Mechanics
Large-scale property management groups and institutional real estate portfolios command project-based procurement with lifecycle cost guarantees, compressing margins for equipment-only vendors while rewarding integrated service providers. This buyer concentration forces manufacturers to unbundle hardware from installation and long-term maintenance contracts.
Pricing Analysis
Volume concentrates in unitary air conditioners and furnaces sold through contractor channels at thin margins, while premium accrues to VRF systems and smart building automation sold through specification engineering. Price differentiation rests on certification tier—EPA Section 608 compliance for refrigerant handling and ISO 9001 manufacturing standards—and geographic delivery cost to remote job sites. Pricing pressure stems from copper and aluminum commodity volatility compressing coil and tubing input costs. Residential retrofit buyers exhibit highest price sensitivity, while data center operators prioritize thermal density performance over capital outlay.
Supply Chain Analysis
Freight costs from Yangtze River Delta and Shandong province compressor clusters to North American distribution centers absorb margin on mid-tier equipment. Manufacturing concentrates in China, Japan, and Germany for rotating machinery and precision heat exchangers. Raw material dependencies span Chilean copper mining, Australian aluminum smelting, and Saudi petrochemical feedstocks for refrigerant precursors. Single-source vulnerability in Japanese and Chinese compressor production creates supply chain risk. Distribution runs through authorized dealer networks in North America and direct-to-contractor channels in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US EPA's AIM Act Technology Transitions program erects a compliance moat around lower-GWP refrigerant equipment lines, advantaging OEMs with capitalized retooling capacity against underfunded assemblers. This regulatory barrier-to-entry concentrates margin capture among compliant multinationals.
For Market Incumbents: To counter refrigerant patent thickets from Honeywell and Chemours licensing structures, accelerate captive compressor manufacturing expansion in Shandong and Bavaria. Prioritize R-32 and R-454B-compatible production line conversion ahead of regional compliance deadlines. Deepen backward integration into heat exchanger coil fabrication to offset copper commodity volatility. For New Entrants and Emerging Players: Direct-to-contractor digital platforms offer the lowest friction route into predictive maintenance subscriptions for light-commercial and multi-family residential installed bases. Target underpenetrated service contract penetration in US Midwest and Northeast housing stock with IoT-enabled diagnostic tools. White-space exists in geothermal district loop engineering for campus-scale thermal networks in Denmark and the Netherlands. For Investors and Strategic Acquirers: The window for entry favors controls software specialists with BACnet integration capabilities over pure hardware assemblers. Long-term viability hinges on acquisition targets possessing EPA refrigerant handling certification infrastructure and established dealer service networks. Monitor A2L technician licensing lag in North American channels as inflection indicator for service-capability scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant-Compatible Capacity Expansion | Retooling for R-32 and R-454B equipment lines secures EPA AIM Act compliance in US markets. |
| Predictive Maintenance Platform Launch | IoT sensor networks capture recurring revenue from institutional real estate portfolios in London and New York. |
| Captive Compressor Manufacturing Investment | In-house rotating machinery production insulates Daikin and Mitsubishi from single-source supply risk. |
| Building Automation Integration Partnership | BACnet-compatible controllers differentiate Trane Technologies for premium urban retrofit contracts. |
| Cold-Climate Heat Pump Certification Program | IRA Section 25C eligibility unlocks Midwest and Northeast residential substitution economics. |
Methodological Framework
Independent corroboration across OEM product managers, mechanical contractor procurement leads, and refrigerant supply specialists underwrites the qualitative findings. Primary interviews with facility directors at hyperscale data center operators and regulatory affairs officers at compressor manufacturers informed technology transition timelines. Secondary validation drew from EPA AIM Act rulemaking dockets, EU F-Gas Regulation implementation reports, and MIIT energy-efficiency standard filings. Bottom-up equipment shipment data triangulated against top-down construction spending forecasts.
Comparable historical reference periods anchored the projection horizon to post-pandemic supply chain normalization and pre-electrification mandate baselines. The analytical framework modeled demand across product type, technology tier, end-user vertical, and application function. CAGRs derived from regression against housing starts, commercial construction permits, and data center power capacity additions. Industry-specific inputs included refrigerant phase-down schedules and IRA tax credit uptake curves.
The model holds under stable commodity price regimes and scheduled regulatory implementation; deviation in copper tariff exposure or A2L technician certification delays would shift equipment availability and substitution economics. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
United States HVAC Equipment Market
HVAC Equipment
Europe Ventilation Equipment Market
HVAC Equipment
HVAC Centrifugal Compressors Market
HVAC Equipment
Global Home Ventilation System Market
HVAC Equipment
Refrigerant Compressors Market
HVAC Equipment
Air Humidifier and Dehumidifier Market
HVAC Equipment
Global Air-To-Air Heat Pumps Market
HVAC Equipment
Mexico Compressed Air Treatment Equipment Market
HVAC Equipment
Europe Heat Pump Market
HVAC Equipment
Industrial Air Heaters Market
HVAC Equipment
Global Split Systems Market
HVAC Equipment
Global Snow Making System Market
HVAC Equipment
Europe Air to Water Heat Pump Market
HVAC Equipment
Industrial Air Blower Market
HVAC Equipment
Underfloor Air Distribution Systems Market
HVAC Equipment
Germany Heat Pump Market