
 North America Gas Water Heater Market | 2026-2036
North America Gas Water Heater Market Size, Share, and Industry Trends Forecast 2026-2036
North America Gas Water Heater Market Insights
Market Context with Strategic Players
The North America gas water heater market is pivoting around a widening split between premium condensing units and standard atmospheric models. A. O. Smith Corporation leverages its vertically integrated manufacturing footprint across Tennessee and Ohio to dominate the replacement channel for conventional tank units. Rheem Manufacturing anchors the high-efficiency segment through advanced condensing technology and broad distribution through plumbing wholesalers. Bradford White competes aggressively in the commercial and light-industrial tier, sustaining margin strength through specification-grade products and restricted dealer networks.
Technical Definition and Structural Segments
A gas water heater is a thermal appliance that burns natural gas or propane to heat potable water, typically achieving energy factors between 0.59 and 0.95 depending on whether the design uses atmospheric, power-vented, or condensing combustion architecture. The primary purpose spans residential domestic hot water delivery, commercial food service operations, and institutional building services where gas infrastructure offers operating cost advantages over electric resistance heating. Storage water heaters still occupy the majority of installed base across North America, though tankless systems represent the fastest-growing product category as homeowners prioritize space savings and endless hot water capacity. The commercial end-user segment concentrates margin pools in specification-driven projects where engineering consultants mandate ASME-certified vessels and advanced venting compatibility.
Regulatory Framework and Outlook
The US Department of Energy enforces minimum energy factor standards under the National Appliance Energy Conservation Act, while Canada's Natural Resources Canada administers the EnerGuide rating system that shapes cross-border product eligibility. EPA regulations on NOx emissions from stationary combustion equipment push manufacturers toward ultra-low-NOx burner designs, particularly in California's South Coast Air Quality Management District where local rules exceed federal baselines. ANSI Z21.10.1 certification remains the gatekeeping standard for residential gas water heater safety and market access across both countries. Stakeholders must monitor whether electrification mandates in progressive municipalities erode gas hookup permissions before the current installed base reaches natural replacement cycles.
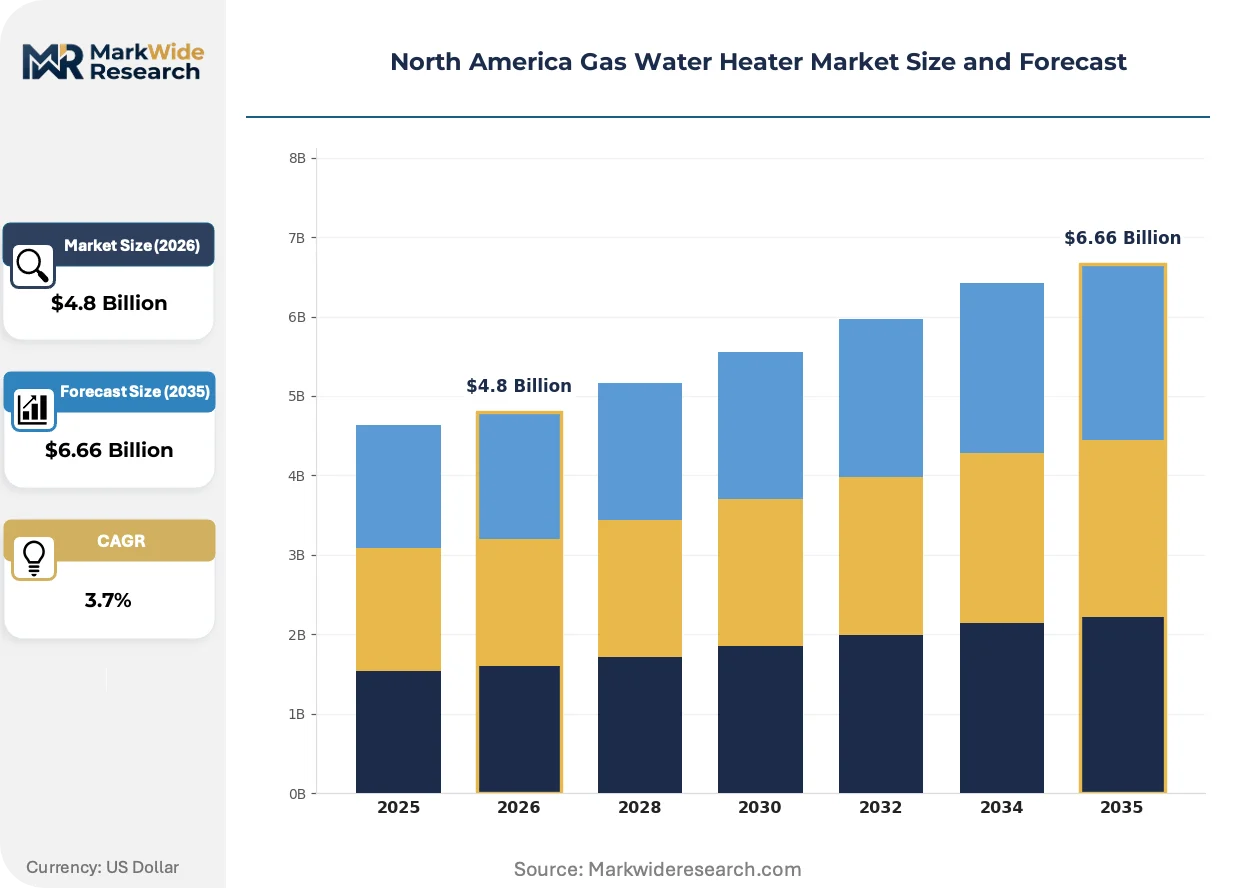
Market Dynamics
The US Department of Energy's appliance efficiency standards are compressing the atmospheric water heater segment while elevating condensing technology from premium niche to baseline compliance requirement across new construction and replacement channels.
Growth Catalysts
- Natural gas infrastructure entrenchment:Suburban developments in Texas and Florida continue embedding gas distribution networks, locking in water heating fuel choice for decades. Residential builders in these states specify gas units as standard.
- EnerGuide rating alignment:Canada's Natural Resources Canada harmonization with US efficiency metrics simplifies cross-border product portfolios for manufacturers. This regulatory convergence reduces SKU complexity.
- Condensing burner maturation:Secondary heat exchanger technology has achieved cost parity with power-vented systems at scale. Manufacturing learning curves passed the inflection point.
Market Restraints
- Copper and stainless steel input volatility:Heat exchanger material costs swing with commodity markets, compressing margins on already thin mid-efficiency product lines.
- Municipal electrification mandates:Progressive jurisdictions in California and Washington are restricting new gas hookups, foreclosing addressable market in high-growth metropolitan areas.
- Heat pump water heater substitution:Electric alternatives achieve comparable operating economics in regions with low electricity rates and moderate climates, eroding gas value proposition.
Strategic Opportunities
- Ultra-low-NOx burner retrofit demand:California's South Coast Air Quality Management District rules exceed federal NOx baselines, creating replacement cycle acceleration in Los Angeles and Orange County metro areas.
- Tankless distribution channel expansion:Plumbing wholesalers are building dedicated tankless showrooms and training programs, opening space for premium product penetration.
- Propane rural electrification gaps:Off-grid residential construction in northern Canada and remote US mountain states lacks electric infrastructure density, preserving gas as sole viable water heating option.
Industry Challenges
- Condensing technician certification gaps:Installation complexity for sealed combustion systems exceeds legacy atmospheric skill sets, creating service bottlenecks and callback risk.
- ANSI Z21.10.1 testing timeline compression:Certification cycles for new burner designs stretch 18-24 months, delaying product launches behind regulatory deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Gas Water Heater Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Storage Water Heaters, Tankless Water Heaters, Heat Pump Water Heaters, Solar Water Heaters End User: Residential, Commercial, Industrial, Institutional Installation Type: Indoor Installation, Outdoor Installation, Retrofits, New Construction Sales Channel: Direct Sales, Retail, Online Marketplaces, Distributors |
| Companies Covered | A. O. Smith Corporation, Rheem Manufacturing, Bradford White, Rinnai Corp., Navien Inc., Noritz Corporation, Bosch Thermotechnology, State Water Heaters, GE Appliances, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Gas Water Heater Market Trends and Innovations
Condensing technology is migrating from premium positioning to volume standard as regulatory baselines ratchet upward, while digital connectivity and predictive maintenance capabilities reshape how water heaters are specified, sold, and serviced.
Condensing secondary heat exchangers are integrating polymer and stainless-steel composite materials to reduce weight and corrosion susceptibility. Multi-family developers in Florida and Arizona specify these units for central plant applications where space constraints and venting complexity favor compact designs. The technology is integrating with building management systems through embedded sensors, enabling remote diagnostics that compress service response times.
The EPA's stationary combustion NOx regulations are tightening emission budgets for residential equipment. Manufacturers are responding with premixed burner architectures and flue gas recirculation that cut NOx formation at the flame front. California's local air districts are accelerating this transition, with South Coast rules pushing sub-14 ng/J specifications that exceed federal baselines and force product portfolio bifurcation.
Builders are consolidating procurement around specification-grade product tiers that bundle extended warranties and preventive maintenance contracts. Plumbing wholesalers capture margin from this shift by unbundling installation from equipment supply and capturing recurring service revenue. This pattern concentrates in Texas and Florida suburban developments where production homebuilders standardize across hundreds of units annually.
North America Gas Water Heater Market Segmentation
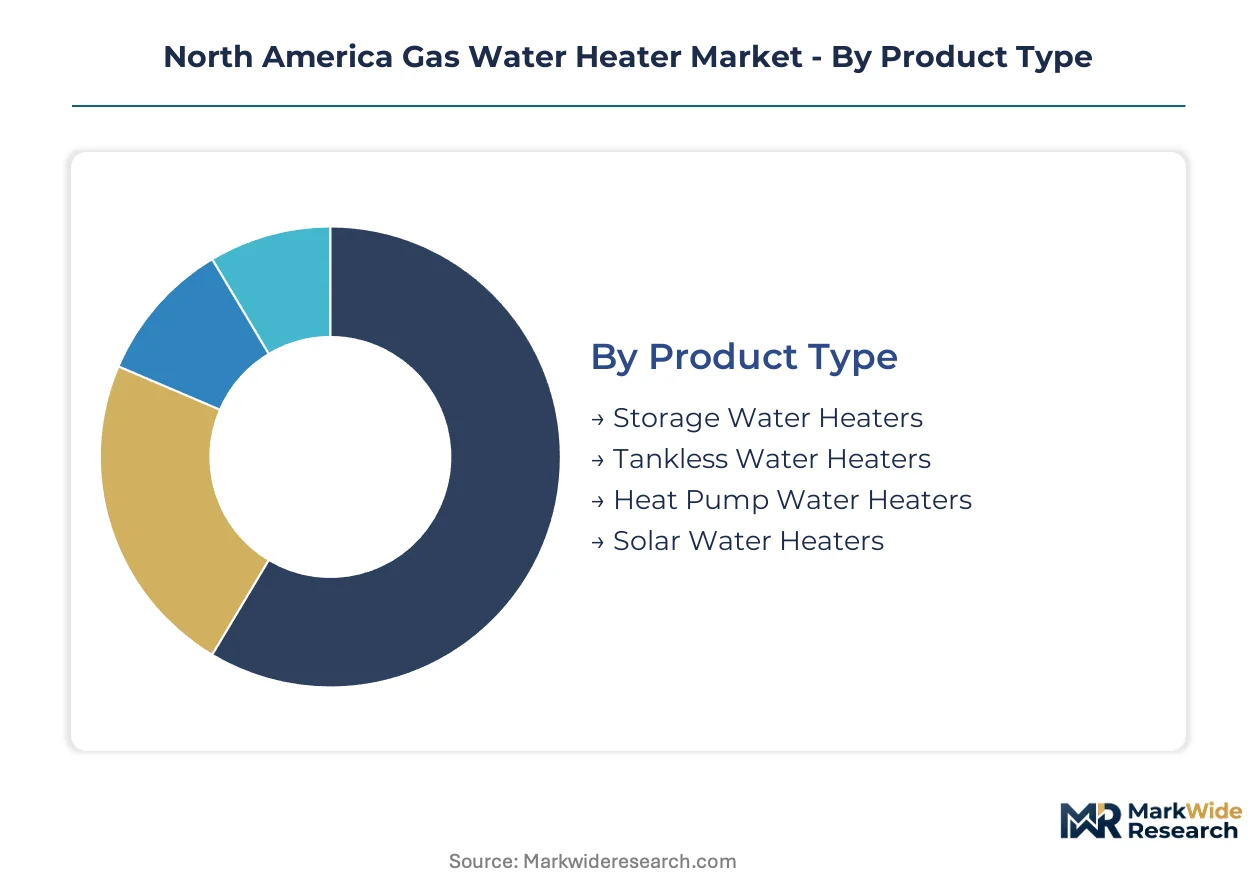
Gas water heater segmentation reveals divergent margin structures across product architectures and procurement channels. Installation type and sales channel choices increasingly determine manufacturer profitability as condensing technology reshapes specification requirements.
Product Type:
Buyers differentiate primarily by footprint constraints and venting flexibility rather than first-cost alone.
- Storage Water Heaters:Atmospheric and power-vented tank designs dominate replacement cycles in existing homes across Texas and Florida. Builders specify these units for production housing where gas infrastructure is pre-installed and space allowances accommodate 40-50 gallon vessels.
- Tankless Water Heaters:Compact wall-mounted units with sealed combustion achieve endless hot water delivery in high-end renovations and multi-family central plants. California's South Coast Air Quality Management District rules accelerate adoption where ultra-low-NOx certification is mandatory.
- Heat Pump Water Heaters:Hybrid electric-gas systems capture demand in moderate climates where electricity rates undercut pure gas operating economics.
- Solar Water Heaters:Gas-fired backup configurations serve off-grid installations in rural Arizona and New Mexico where solar thermal pre-heating reduces propane consumption.
Volume sits with Storage Water Heaters; growth tilts toward Tankless Water Heaters.
End User:
Specification authority varies sharply—homeowners prioritize replacement speed while engineers mandate certified vessels.
- Residential:Single-family replacement demand concentrates in Sun Belt states where warm climates reduce standby losses and gas utility rates stay competitive. Production homebuilders in Houston and Orlando standardize atmospheric units across hundreds of annual starts.
- Commercial:Food service operations, hotels, and multi-family housing drive specification-grade procurement with ASME certification requirements. Engineering consultants in Los Angeles and Chicago mandate condensing technology for central plant retrofits.
- Industrial:Process hot water applications in light manufacturing favor high-recovery rate designs with redundant burner configurations.
- Institutional:Schools and healthcare facilities specify preventive maintenance contracts bundled with extended warranty coverage.
Residential commands absolute unit volume; Commercial captures margin concentration through specification-driven procurement.
Installation Type:
Regulatory timing and labor availability split demand between new construction and replacement channels.
- Indoor Installation:Sealed combustion and power-vented designs dominate where mechanical room space permits venting through sidewalls or roofs. Chicago and Detroit codes require specific clearance zones that favor compact condensing footprints.
- Outdoor Installation:Freeze-protected tankless units serve southern California and Arizona markets where climate permits exterior mounting without weatherization costs.
- Retrofits:Replacement cycles accelerate in California air districts where ultra-low-NOx mandates force early retirement of atmospheric units.
- New Construction:Suburban developments in Dallas-Fort Worth and Tampa embed gas infrastructure that locks in water heating fuel choice for decades.
New Construction secures forward volume; Retrofits deliver immediate replacement acceleration where local NOx rules tighten.
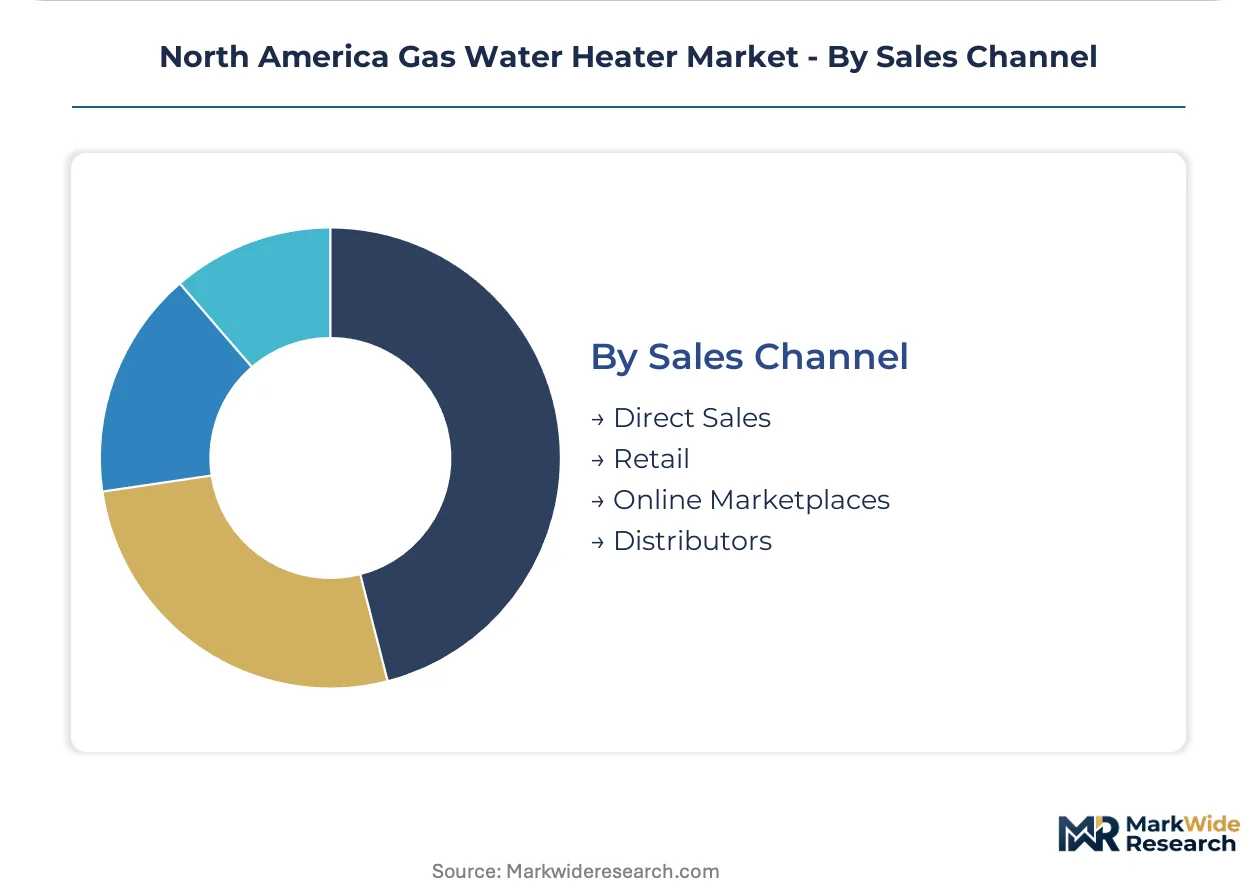
Sales Channel:
Channel selection determines warranty handling complexity and technician training investment requirements.
- Direct Sales:Manufacturers engage national production homebuilders and multi-family developers through specification programs. Volume commitments in Texas and Florida suburban projects secure multi-year supply agreements.
- Retail:Big-box home improvement chains serve emergency replacement demand with same-day pickup availability. Stocking depth favors atmospheric units with standardized venting packages.
- Online Marketplaces:E-commerce platforms capture tankless research-phase traffic where homeowners compare efficiency ratings and venting specifications before contractor consultation.
- Distributors:Plumbing wholesalers dominate commercial and institutional procurement through specification relationships with engineering consultants. Technical training programs and inventory financing differentiate channel value.
Distributors anchor commercial specification authority; Retail and Online split residential replacement urgency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors North American gas water heater demand through sprawling suburban developments that embed natural gas infrastructure across hundreds of annual housing starts. The Sun Belt corridor from Texas through Florida concentrates replacement cycles and new construction specifications where warm climates preserve gas operating economics against electric alternatives.
United States
Texas and Florida residential builders specify atmospheric units as standard equipment in production housing developments. The EPA enforces stationary combustion NOx regulations that push manufacturers toward ultra-low-NOx burner designs. Los Angeles and Orange County metro areas accelerate replacement cycles under South Coast Air Quality Management District rules that exceed federal baselines.
Canada
Natural Resources Canada administers the EnerGuide rating system that harmonizes efficiency metrics with US standards, simplifying cross-border product portfolios. Off-grid construction in northern provinces and remote mountain states preserves propane as the sole viable water heating option. Ontario and Quebec distribution networks concentrate specification-grade procurement for multi-family central plants.
California
Progressive municipalities restrict new gas hookups, foreclosing addressable market in high-growth metropolitan areas while accelerating retrofit demand for compliant replacements. The California Energy Commission updates building efficiency codes that favor condensing technology in remaining gas-permitted construction. San Diego and Phoenix markets specify freeze-protected outdoor tankless installations where climate permits exterior mounting.
Illinois and Michigan
Chicago and Detroit mechanical room codes require specific clearance zones that favor compact condensing footprints over legacy atmospheric designs. State energy offices administer rebate programs for high-efficiency gas equipment that narrow first-cost gaps with standard units. Cleveland and Milwaukee wholesale channels dominate commercial specification authority through engineering consultant relationships.
Arizona and New Mexico
Solar thermal pre-heating configurations with gas-fired backup serve rural off-grid installations where solar thermal reduces propane consumption. Tucson and Albuquerque building departments streamline permitting for sealed combustion systems that eliminate atmospheric venting requirements. Phoenix production homebuilders standardize power-vented units across desert suburban developments where electricity rates challenge pure gas economics.
North America Gas Water Heater Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a market that consolidates around vertically integrated manufacturing footprints and specification-driven distribution relationships. Three to five manufacturers capture the majority of installed base through replacement channel dominance and production builder supply agreements. The competitive structure separates atmospheric tank specialists, condensing technology leaders, and tankless innovators. Capacity expansion and strategic partnerships represent the dominant competitive moves as manufacturers align product portfolios with regulatory efficiency trajectories.
Within the vertically integrated tier, A. O. Smith Corporation and Rheem Manufacturing anchor distinct competitive positions through manufacturing footprint scale and distribution breadth. Bradford White occupies a specification-grade position serving commercial and institutional procurement channels. Rinnai Corp. and Navien Inc. exemplify the tankless specialization archetype, with Navien Inc. representing Korean-origin engineering focused on condensing combustion architectures. These five entities collectively illustrate how geographic manufacturing concentration and channel specialization stratify competitive positioning across residential replacement, new construction, and commercial specification segments.
| Leading Market Players |
|---|
| A. O. Smith Corporation |
| Rheem Manufacturing |
| Bradford White |
| Rinnai Corp. |
| Navien Inc. |
| Noritz Corporation |
| Bosch Thermotechnology |
| State Water Heaters |
| GE Appliances |
| Others |
Pricing and Supply Chain Analysis
London Metal Exchange copper pricing volatility cascades through heat exchanger fabrication costs, compressing margins on atmospheric tank units while condensing technology commands premium positioning through stainless-steel and polymer composite material differentiation. Input cost swings force manufacturers to tier pricing across certification grades, with EPA NOx compliance tiers separating value pools from commodity replacement cycles.
Pricing Analysis
Energy-factor performance anchors value-based pricing, with condensing units achieving 0.95 EF ratings commanding substantial premiums over 0.59 EF atmospheric baselines. Price differentiation rests on ANSI Z21.10.1 certification tier and ultra-low-NOx burner specification, particularly in California air districts. Cost compression in mid-efficiency power-vented segments is intensifying because copper heat exchanger material volatility erodes already thin margins. Production homebuilders in Texas and Florida exhibit highest price sensitivity through volume procurement, while commercial engineering consultants in Los Angeles and Chicago demonstrate lowest sensitivity due to specification-grade ASME certification requirements.
Supply Chain Analysis
Single-source vulnerability sits with Chinese stainless-steel coil suppliers serving secondary heat exchanger fabrication, while Mexican assembly plants and US Midwest burner component manufacturers complete the regional footprint. Raw material dependencies draw from Chilean copper cathode, Canadian nickel alloys, and domestic polymer resin feedstocks. Tariff exposure on Chinese stainless steel creates margin risk for condensing unit production. Distribution runs through plumbing wholesalers capturing commercial specification authority, with big-box retail serving emergency residential replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
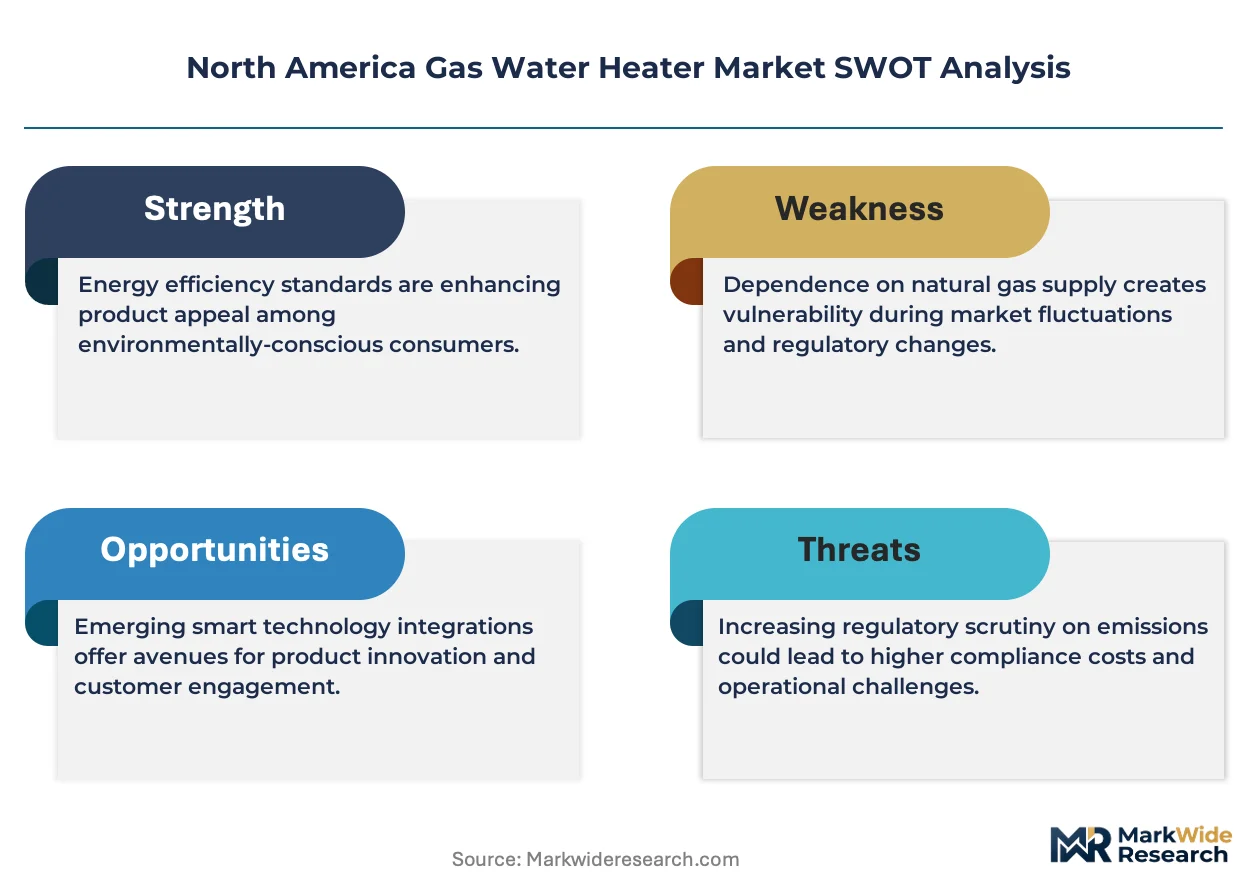
The North America gas water heater market functions as a cost-of-compliance arena where EPA stationary combustion NOx regulations erect certification barriers that favor incumbent manufacturers with established testing infrastructure and ANSI Z21.10.1 validation capabilities.
For Market Incumbents: To counter heat pump water heater substitution in moderate-climate markets, prioritize backward integration into stainless-steel heat exchanger production and expand condensing technology capacity in Tennessee and Ohio manufacturing clusters. Secure specification-grade positioning through extended warranty bundling with plumbing wholesalers serving commercial central plant retrofits. For New Entrants and Emerging Players: Begin with propane-powered tankless systems targeting off-grid residential construction in northern Canada and remote US mountain states where electric infrastructure gaps preserve gas as the sole viable water heating option. Pursue ultra-low-NOx burner certification for California South Coast Air Quality Management District compliance as the fastest-regulatory pathway to specification credibility. For Investors and Strategic Acquirers: Distressed-cycle entries favor tankless technology specialists with condensing combustion architectures in Korean and Japanese engineering hubs, where manufacturing learning curves have achieved cost parity with power-vented systems. Monitor municipal electrification mandate adoption rates in progressive jurisdictions as the critical signal for gas hookup permission erosion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Ultra-Low-NOx Burner Certification Investment | EPA and California South Coast rules force portfolio bifurcation between compliant and non-compliant product tiers. |
| Condensing Technology Capacity Expansion | US Department of Energy efficiency standards compress atmospheric segment while elevating secondary heat exchanger architectures to baseline. |
| Plumbing Wholesaler Channel Partnership | Specification relationships with engineering consultants in Los Angeles and Chicago capture commercial margin concentration. |
| Polymer-Stainless Composite Heat Exchanger Development | Weight reduction and corrosion resistance address multi-family central plant space constraints in Florida and Arizona. |
| Technician Certification Program Deployment | Sealed combustion installation complexity exceeds legacy atmospheric skill sets, creating service bottleneck mitigation opportunity. |
Research Methodology
Multi-period observation of gas utility rate spreads, housing start permits, and regulatory filing timelines anchored the trend analysis, supplemented by interviews with water heater manufacturing executives, plumbing wholesale distribution managers, HVAC contractor service heads, and municipal building code officials. Secondary validation drew from US Department of Energy appliance standards filings, EPA stationary combustion rulemaking dockets, Natural Resources Canada EnerGuide databases, and South Coast Air Quality Management District regulatory notices. Bottom-up unit shipment modeling triangulated against top-down construction spending allocations across the analysis window.
Segment-weighting applied product architecture splits between storage and tankless systems, installation type differentiation across new construction and replacement channels, and end-user stratification between residential production builders and commercial engineering-specified procurement. CAGRs were derived through logistic diffusion modeling of condensing technology adoption curves against regulatory deadline schedules. Forecast inputs incorporated natural gas infrastructure entrenchment patterns in Texas and Florida suburban developments and heat pump water heater substitution elasticity in moderate-climate electricity markets.
Underlying measurement precision varies by segment; new construction permitting data and replacement channel shipment reports carry tighter precision than long-run technology substitution assumptions. Forecasts reflect documented assumptions regarding regulatory implementation timing, commodity price stability, and electrification policy diffusion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Germany HVAC Market
HVAC Equipment
Air-Cooled Heat Exchangers Market
HVAC Equipment
Global Air-To-Air Heat Pumps Market
HVAC Equipment
HVAC Air Quality Monitoring Market
HVAC Equipment
Radiant Heating and Cooling Systems Market
HVAC Equipment
Asia Pacific Commercial HVAC Market
HVAC Equipment
Steam Heat Exchanger Market
HVAC Equipment
India Residential Heat Pump Market
HVAC Equipment
Foamer Pump Market
HVAC Equipment
Underfloor Air Distribution Systems Market
HVAC Equipment
Dedicated Outdoor Air System Market
HVAC Equipment
Japan HVAC Market
HVAC Equipment
Europe Heat Exchanger Market
HVAC Equipment
Linear Slot Diffuser Market
HVAC Equipment
Global Snow Making System Market
HVAC Equipment
Air Conditioning Systems Market