
 Shell and Tube Heat Exchangers Market | 2026-2036
Shell and Tube Heat Exchangers Market Size, Share, and Industry Trends Forecast 2026-2036
Shell and Tube Heat Exchangers Market Intelligence
Project engineering channels for large-capacity shell and tube heat exchangers are rewriting procurement patterns across heavy process industries. Kelvion Holding GmbH leverages its European fabrication footprint to anchor long-term service contracts with chemical complexes. ALFA LAVAL competes through specialized marine-grade titanium bundles that sustain premium positioning in offshore platforms. GEA Group dominates food-grade sanitary designs, extending its reach into dairy pasteurization systems worldwide.
A shell and tube heat exchanger consists of a pressure vessel enclosing a bundle of tubes, where one fluid circulates through the tubes and a second fluid flows across the shell side, with thermal transfer governed by tube diameter, wall thickness, baffle spacing, and fouling resistance coefficients. Manufacturers weld tube sheets to channel covers and route fluids through single-pass, double-pass, or multi-pass configurations to achieve target logarithmic mean temperature differences. Stainless steel and titanium materials command expanding share in corrosive chemical processing applications where carbon steel fails prematurely. Multi-pass designs lead in power generation feedwater heating, while U-tube configurations absorb thermal expansion stresses in oil and gas startup cycles.
ASME Boiler and Pressure Vessel Code Section VIII governs design and fabrication standards in the United States, while TEMA standards classify mechanical construction classes for shell and tube units globally. The EPA's New Source Performance Standards for petroleum refineries shape demand for low-emission channel designs with enhanced gasket sealing. India's BIS certification requirements for pressure equipment create compliance barriers for imported assemblies. Stakeholders must monitor evolving material substitution patterns as copper nickel faces displacement from seawater cooling circuits.
Market Dynamics
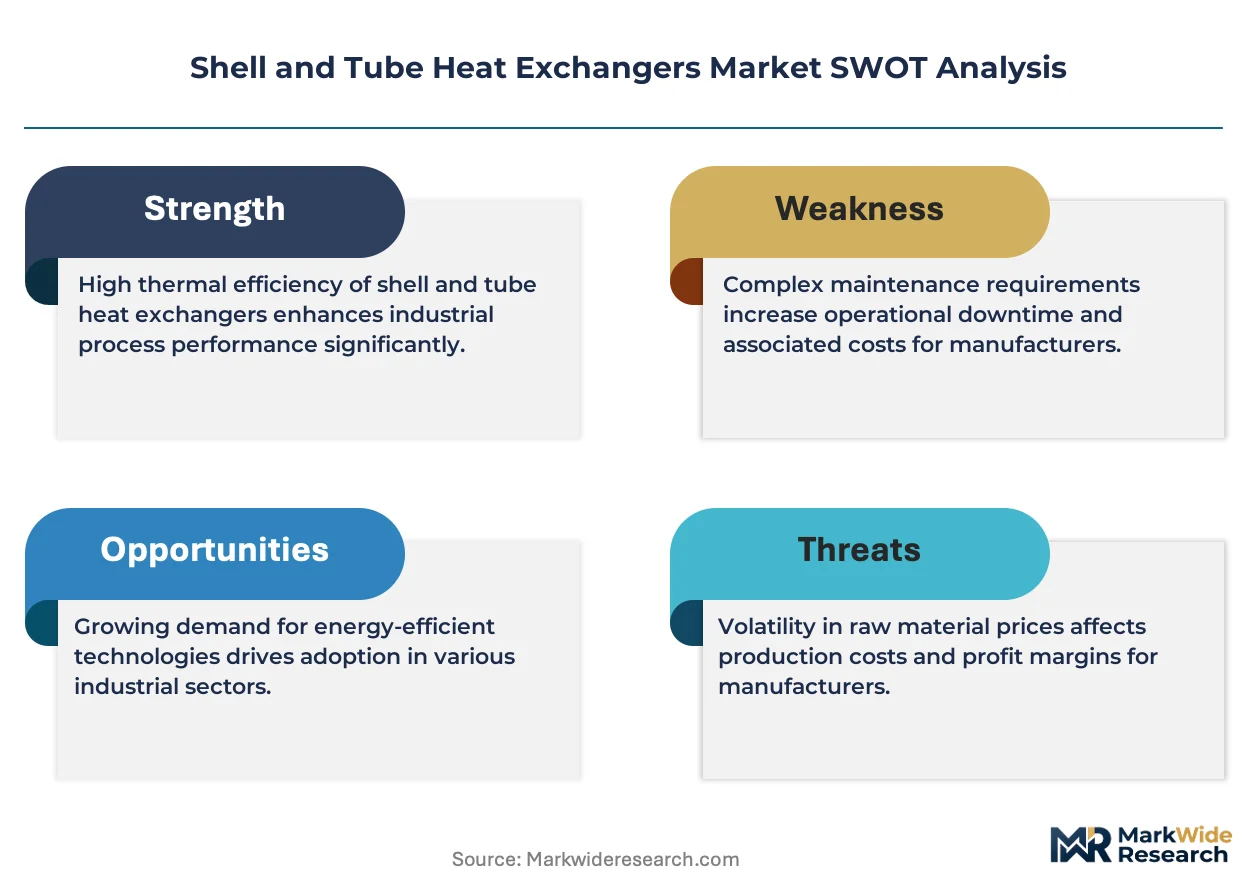
Refinery operators across the Gulf Coast are compressing replacement cycles for corrosion-prone carbon steel units, forcing procurement channels to prioritize titanium-clad and duplex stainless steel configurations ahead of traditional maintenance schedules.
Growth Catalysts
- EPA Methane Rules:Leak-tight channel designs with enhanced gasket sealing now dominate refinery procurement specifications across Texas and Louisiana facilities.
- India Petrochemical Buildout:Titanium-clad exchanger demand concentrates in Gujarat and Maharashtra where Reliance Industries and Indian Oil are expanding ethylene cracker complexes.
- Fouling-Resistant Coatings:Electroless nickel plating and polytetrafluoroethylene linings extend run lengths between cleaning cycles in heavy crude processing units.
Market Restraints
- Titanium Plate Volatility:Sponge titanium supply concentrates in Chinese and Russian smelters, exposing fabricators to alloy surcharge swings exceeding 30 percent quarter-to-quarter.
- ASME Certification Bottlenecks:Third-party inspection backlogs for Section VIII stamp approvals extend lead times by 8-14 weeks for non-standard pressure vessel designs.
- Compact Heat Exchanger Substitution:Plate-and-frame and welded plate units capture sub-50 MW thermal duty applications in chemical processing where footprint constraints dominate.
Strategic Opportunities
- India BIS Compliance Services:Foreign fabricators can capture aftermarket service contracts by establishing local calibration and recertification partnerships for pressure equipment.
- Hydrogen Preheating Applications:High-pressure shell and tube designs for green ammonia synthesis loops represent uncontracted demand from electrolyzer OEMs.
- Digital Twin Integration:Convergence of computational fluid dynamics modeling with IoT sensor networks enables predictive fouling management for offshore platform operators.
Industry Challenges
- Certified Welder Scarcity:ASME Section IX-qualified TIG welders for titanium tube-to-tubesheet joints command premium wages exceeding $85 hourly in Houston fabrication yards.
- Legacy Control System Integration:New heat exchanger skids require protocol translation layers to interface with 1980s-era DCS architectures still operating in Midwest refineries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shell and Tube Heat Exchangers Market |
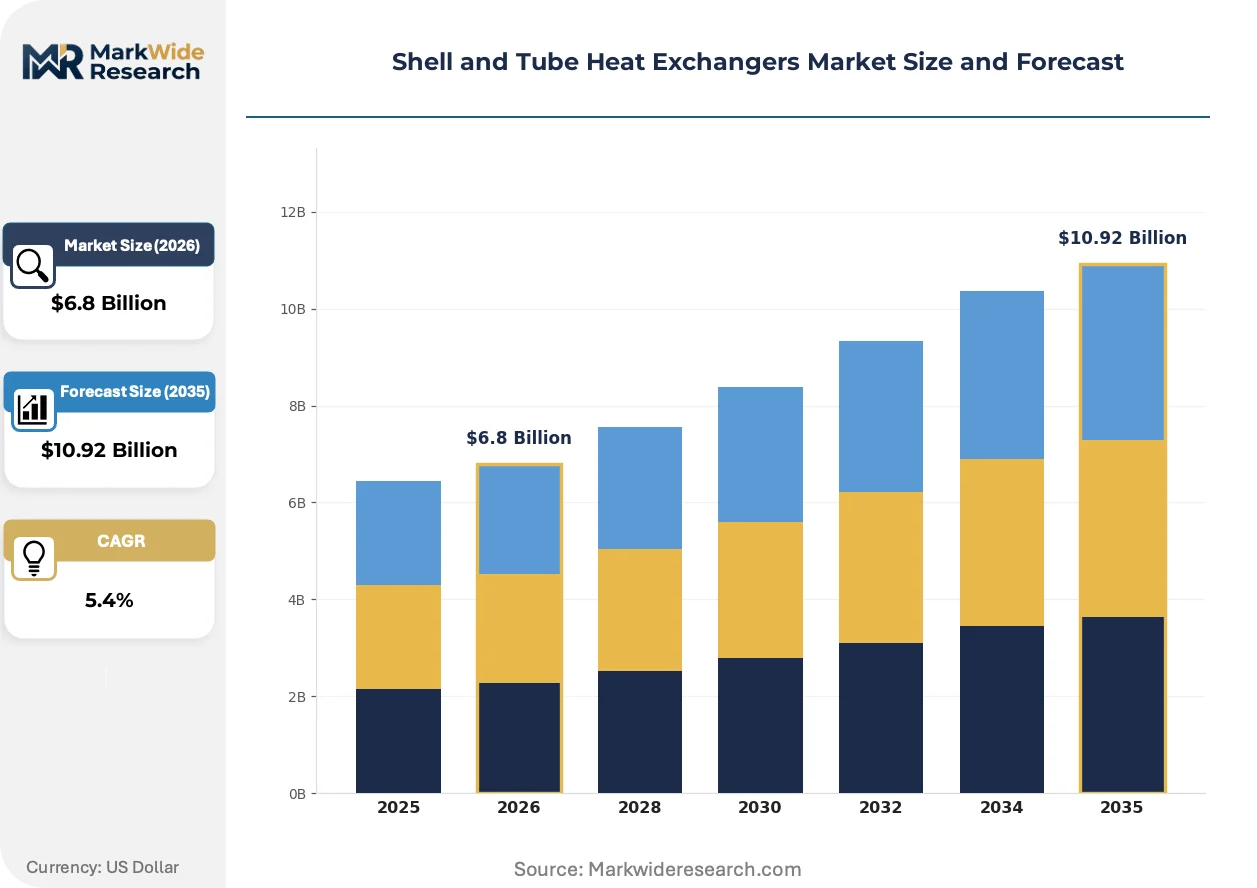
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Pass, Double-Pass, Multi-Pass, U-Tube Material: Carbon Steel, Stainless Steel, Copper Nickel, Titanium Application: Power Generation, Chemical Processing, Oil & Gas, HVAC End User: Industrial, Marine, Power Plants, Food & Beverage |
| Companies Covered | Kelvion Holding GmbH, API Heat Transfer, ALFA LAVAL, Danfoss, HRS Process Systems Ltd., Xylem, GEA Group, Exchanger Industries Limited, Mersen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shell and Tube Heat Exchangers Market Strategic Shifts & Innovations
Computational methods and sensor networks are compressing the traditional design-certify-fabricate cycle, enabling real-time performance optimization that static TEMA calculations cannot match.
Twisted-tube heat transfer technology replaces conventional segmental baffles with helically coiled tube supports that eliminate flow-induced vibration failures. Offshore platform operators in the North Sea and Gulf of Mexico adopt these configurations for high-pressure gas compression intercoolers where reliability premiums justify 40 percent fabrication cost uplifts. Kelvion and Alfa Laval are digitizing their engineering workflows to deliver twisted-tube thermal designs in 72-hour turnaround versus six-week conventional cycles.
The EPA's New Source Performance Standards for petroleum refineries mandate continuous monitoring of volatile organic compound emissions from process equipment. Channel cover designs now incorporate double-gasketed flanges with leak detection ports that trigger maintenance alerts before atmospheric release thresholds. Refinery operators in Texas and California are retrofitting existing shell and tube units with these low-emission configurations during scheduled turnarounds.
Engineering-procurement-construction firms are unbundling heat exchanger specification from bundled process unit contracts, creating direct manufacturer relationships for critical thermal equipment. Fluor and Bechtel now maintain approved vendor lists for titanium-clad bundles that bypass traditional distributor markups. This channel compression is most visible in Middle Eastern petrochemical projects where Saudi Aramco and ADNOC specify single-source accountability for corrosion-resistant designs.
Shell and Tube Heat Exchangers Market Segmentation
Shell and tube heat exchanger procurement cycles vary dramatically by segment, with replacement-driven industrial applications turning over in 8-12 years while marine installations extend to 20-plus years. Understanding these velocity differences allows manufacturers to align fabrication capacity with predictable demand windows.
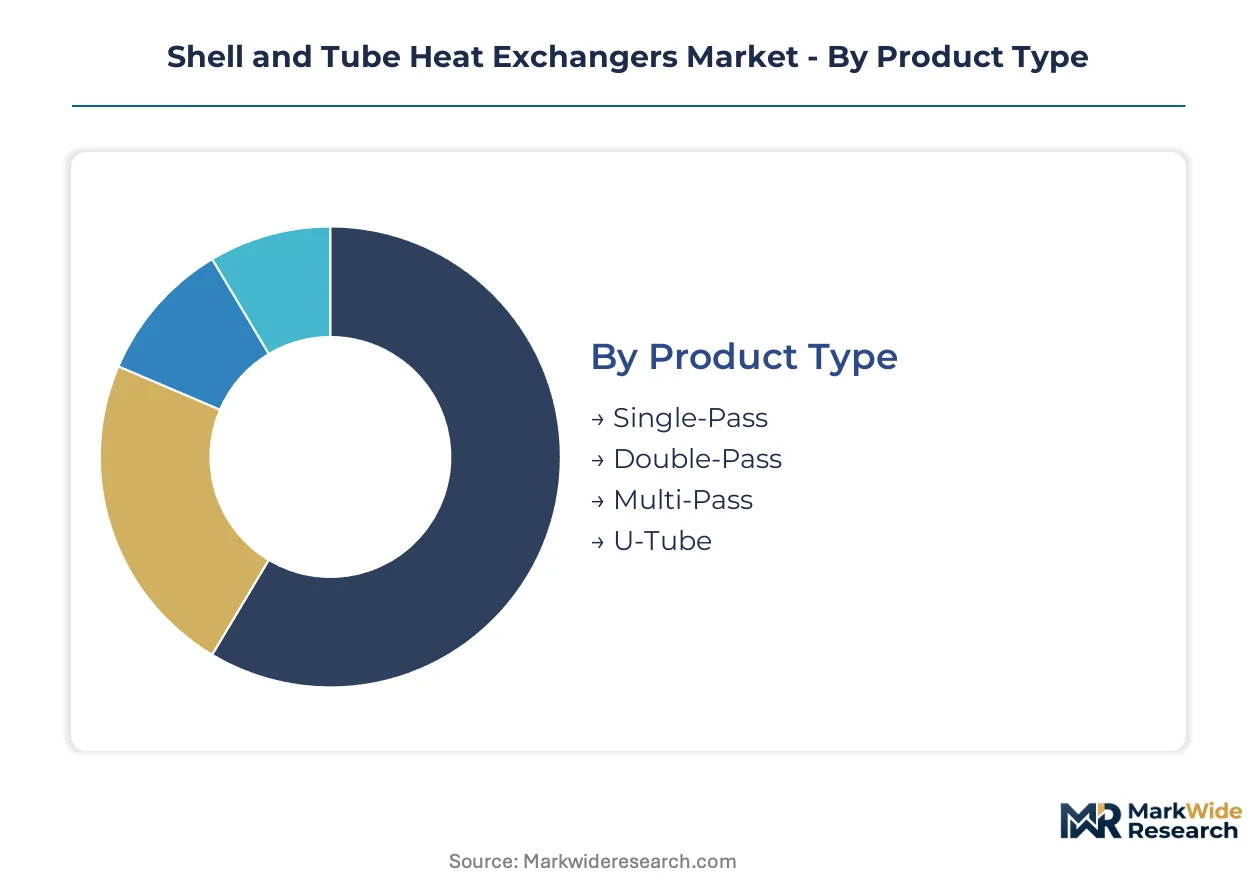
Product Type:
Replacement cycles stretch from 5-year intervals for fouling-prone single-pass units to 25-year lifespans for thermally stressed U-tube configurations, creating distinct revenue timing patterns across the installed base.
- Single-Pass:Fluid traverses tubes once from inlet to outlet without directional reversal, minimizing pressure drop for high-flow cooling water applications. Gulf Coast refineries specify these for crude preheat trains where ASME Section VIII compliance and rapid turnaround availability override thermal efficiency concerns.
- Multi-Pass:Internal baffles redirect flow through sequential tube passes, maximizing logarithmic mean temperature difference for feedwater heating in combined-cycle power plants. India's NTPC and Adani Power procure these for supercritical coal units where thermal performance guarantees drive vendor selection.
- Double-Pass:Two-directional flow configuration balances pressure drop against heat transfer area, common in chemical processing where moderate duty requirements dominate.
- U-Tube:Hairpin tube bends accommodate differential thermal expansion between shell and bundle, essential for oil and gas startup cycles where rapid temperature swings occur.
Single-pass units dominate installed base volume in North American refineries. Multi-pass configurations are where expansion concentrates as Asian power utilities upgrade thermal efficiency.
Material:
Cost tiers separate commodity carbon steel from premium corrosion-resistant alloys, with titanium commanding 8-12x per-kilogram premiums that reshape project economics for seawater and acid service.
- Titanium:Exceptional resistance to chloride-induced pitting and crevice corrosion enables seawater cooling circuits where copper nickel fails. Reliance Industries specifies titanium-clad tube sheets for Gujarat refinery expansion projects where 30-year service life justifies first-cost premiums.
- Stainless Steel:Austenitic and duplex grades resist sulfuric acid and amine corrosion in chemical processing and gas sweetening loops. BASF and Dow Chemical specify 316L and 2205 duplex for Louisiana and Texas Gulf Coast petrochemical complexes where EPA methane rules demand leak-tight, corrosion-resistant channel designs.
- Carbon Steel:Standard material for non-corrosive hydrocarbon service where cost minimization dominates specification.
- Copper Nickel:Traditional seawater alloy facing displacement as titanium costs moderate and biofouling resistance improves.
Carbon steel dominates installed base tonnage across legacy refining. Titanium is where expansion concentrates as Indian and Middle Eastern petrochemical buildouts prioritize corrosion immunity.
Application:
End-use concentration determines specification complexity, with oil and gas demanding highest pressure ratings and HVAC accepting standardized catalog designs.
- Oil & Gas:High-pressure sour service applications require NACE MR0175-compliant materials and double-gasketed channel covers for hydrogen sulfide containment. Permian Basin operators specify these for gas processing trains where EPA New Source Performance Standards mandate continuous emission monitoring integration.
- Chemical Processing:Aggressive acid and solvent exposure drives material selection toward nickel alloys and fluoropolymer linings. Bayer and Covestro specify multi-pass stainless units for German and Belgian chlorine-alkali plants where TEMA Class R construction ensures mechanical reliability.
- Power Generation:Feedwater heating and condensing applications prioritize thermal efficiency and low-pressure drop.
- HVAC:Building services applications accept standardized designs with reduced pressure vessel complexity.
HVAC applications dominate installed base count across commercial building stock. Oil and gas is where expansion concentrates as North American shale infrastructure matures.
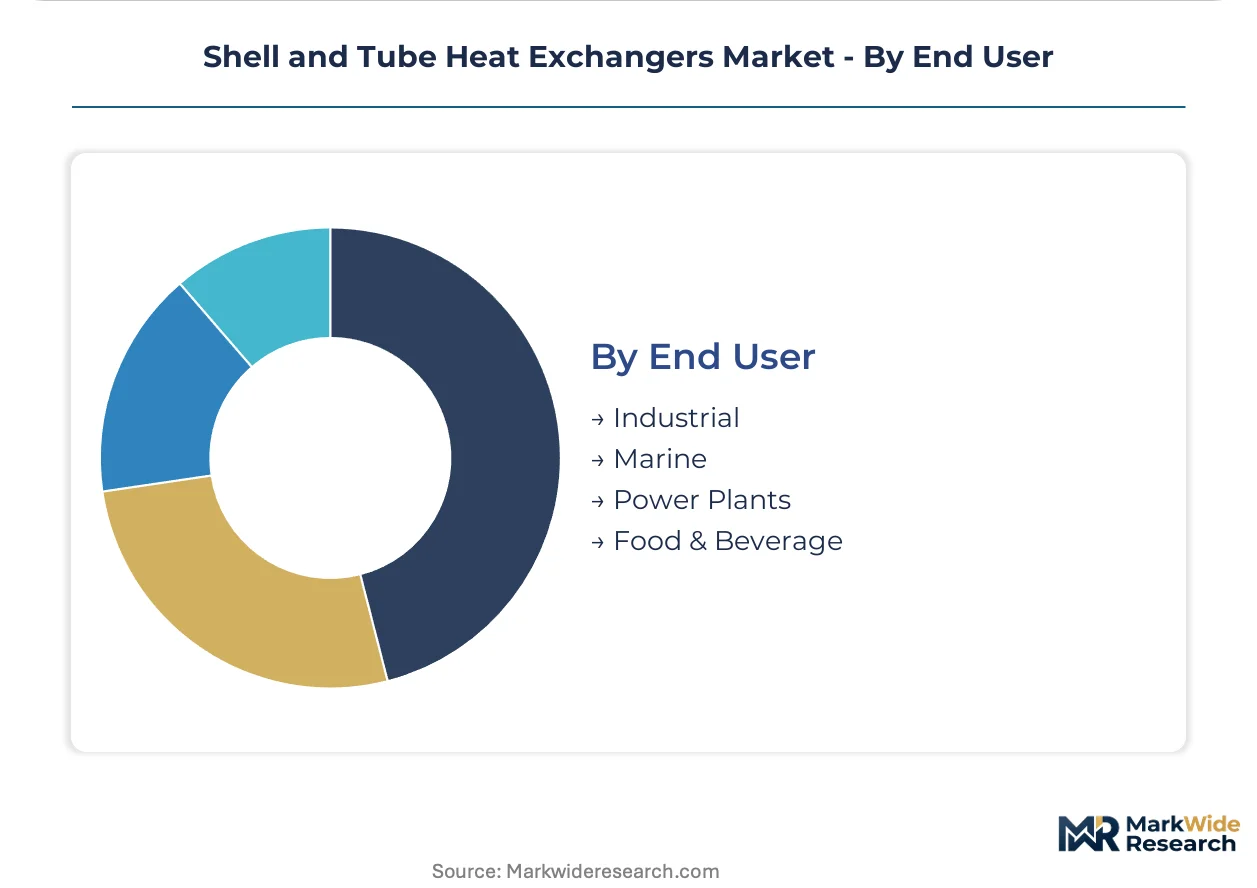
End User:
Customer type shapes procurement channel structure, with industrial buyers demanding engineered-to-order specifications and marine operators accepting classification society-certified standard designs.
- Industrial:Integrated petrochemical and refining companies specify custom pressure vessel designs with project-specific thermal guarantees. Saudi Aramco and ADNOC require single-source accountability for corrosion-resistant bundles in Jubail and Ruwais expansion projects.
- Marine:Classification society rules from DNV, ABS, and Lloyd's Register govern material selection and fabrication quality for shipboard lube oil coolers and central cooling systems. Korean shipyards Daewoo and Hyundai specify titanium bundles for LNG carrier cargo conditioning where seawater exposure is continuous.
- Power Plants:Utility procurement emphasizes lifecycle cost and guaranteed availability over first cost.
- Food & Beverage:Sanitary designs with polished surfaces and crevice-free construction meet 3-A sanitary standards for dairy pasteurization.
Industrial end users dominate installed base value across heavy process industries. Marine is where expansion concentrates as LNG carrier and offshore platform construction accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Titanium-clad fabricators in India command 15-20% cost advantages over Gulf Coast counterparts, while Houston-area yards extract premium pricing for ASME-certified turnaround speed. This asymmetry is reshaping procurement routing for Middle Eastern petrochemical investors.
United States
Gulf Coast refineries in Texas and Louisiana are compressing replacement cycles for corrosion-prone carbon steel units. The EPA's New Source Performance Standards mandate continuous monitoring of volatile organic compound emissions from process equipment. Houston fabrication yards specialize in leak-tight channel designs with double-gasketed flanges for Permian Basin gas processing trains.
India
Reliance Industries and Indian Oil are expanding ethylene cracker complexes in Gujarat and Maharashtra, driving procurement of titanium-clad exchangers. The BIS certification requirements for pressure equipment create compliance barriers for imported assemblies. Dahej and Hazira industrial corridors concentrate demand for 30-year service life designs in seawater cooling circuits.
Germany
BASF and Covestro specify multi-pass stainless units for chlorine-alkali plants in Ludwigshafen and Leverkusen. The EU Green Deal's industrial decarbonization targets accelerate demand for high-efficiency feedwater heating configurations. The BASF Verbund site anchors fabrication partnerships with TEMA Class R construction specialists.
Saudi Arabia
Saudi Aramco requires single-source accountability for corrosion-resistant bundles in Jubail and Ruwais expansion projects. The SFDA and SASO quality frameworks align with international pressure vessel standards for petrochemical exports. The King Salman Energy Park is attracting European fabricators for localized service contract fulfillment.
Japan
Kansai Electric and JERA procure multi-pass configurations for supercritical coal unit upgrades in Osaka and Nagoya bays. The METI's GX League decarbonization initiative prioritizes thermal efficiency guarantees in vendor selection. The Chubu region's integrated chemical complexes sustain demand for electroless nickel-plated units in heavy crude service.
Shell and Tube Heat Exchangers Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the fabrication hierarchy. The market structures around three tiers: European fabrication houses with long-term service contracts, Asian scale producers serving standardized replacement demand, and regional specialists capturing turnaround-driven procurement. Two strategic archetypes dominate: corrosion-resistant alloy specialists and digital-integrated predictive maintenance providers. Capacity expansion in Indian fabrication corridors and backward integration into titanium sponge sourcing represent the dominant competitive moves.
Among European-based platform integrators, Kelvion Holding GmbH and ALFA LAVAL occupy positions anchored to marine-grade and chemical-processing archetypes respectively. Kelvion exemplifies the fabrication-footprint-driven service contract model, while ALFA Laval represents premium positioning through specialized material configurations. GEA Group sits within the sanitary-design tier, extending archetype reach into food-grade applications. These three names illustrate how geographic origin and company structure suffixes map to competitive positioning without requiring specific product or financial claims.
| Leading Market Players |
|---|
| Kelvion Holding GmbH |
| API Heat Transfer |
| ALFA LAVAL |
| Danfoss |
| HRS Process Systems Ltd. |
| Xylem |
| GEA Group |
| Exchanger Industries Limited |
| Mersen |
| Others |
Cost & Logistics Intelligence
Houston-Singapore freight corridors absorb titanium sponge surcharges that compress margins for Gulf Coast fabricators while amplifying price premiums for configured-to-order bundles. This logistics tension concentrates procurement power among Middle Eastern petrochemical investors who route orders toward Indian fabrication corridors with 15-20% cost advantages.
Pricing Analysis
The customization-premium spread separates standard carbon steel replacement units from titanium-clad engineered-to-order configurations. Three-tier pricing structure across premium, standard, and economy levels stratifies by ASME certification grade and alloy specification, with EPA methane compliance requirements driving price differentiation toward leak-tight channel designs. Pricing pressure stems from compact heat exchanger substitution in sub-50 MW thermal duty applications. Industrial end users exhibit lowest price sensitivity due to lifecycle cost framing, while HVAC contractors face acute margin compression.
Supply Chain Analysis
Sponge titanium feedstock draws from Chinese and Russian smelters, exposing fabricators to alloy surcharge volatility. Raw material dependencies center on titanium sponge, duplex stainless steel plate, and electroless nickel plating chemicals. Single-source vulnerability concentrates in titanium sponge supply, with logistics chokepoints at Rotterdam and Singapore transshipment hubs. Distribution runs through engineering-procurement-construction approved vendor lists that bypass traditional distributor markups for critical thermal equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward integrated petrochemical operators who compress procurement channels through single-source accountability requirements. EPC unbundling of heat exchanger specification accelerates this consolidation.
For Market Incumbents: Build certification moats around ASME Section VIII and TEMA Class R stamping capacity. Anchor long-term service contracts with chemical complexes through localized calibration partnerships. Defend against compact heat exchanger substitution by emphasizing high-pressure sour service capabilities. Prioritize backward integration into titanium sponge sourcing to buffer alloy surcharge volatility. For New Entrants and Emerging Players: Build out India BIS compliance service capabilities to capture aftermarket recertification contracts for imported pressure equipment. Target hydrogen preheating applications for green ammonia synthesis loops where electrolyzer OEMs seek uncontracted high-pressure designs. Penetrate through digital twin integration partnerships with offshore platform operators seeking predictive fouling management. For Investors and Strategic Acquirers: Corrosion-resistant alloy specialists with captive titanium sourcing capabilities present acquisition targets with defensible margin structures. Long-term viability hinges on positioning for India's petrochemical buildout and Middle Eastern localization requirements. Watch for ASME certification bottleneck resolution as inflection signal for fabrication capacity utilization recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Sponge | Captive supply from Chinese and Russian smelters buffers alloy surcharge volatility for Gulf Coast fabricators. |
| India BIS Compliance Partnership | Local calibration capabilities unlock aftermarket service contracts for Reliance Industries and Indian Oil expansions. |
| Digital Twin Integration | CFD-IoT convergence enables predictive fouling management for North Sea and Gulf of Mexico platform operators. |
| Twisted-Tube Technology Adoption | Helical coil configurations command 40% fabrication premiums from offshore gas compression intercooler procurement. |
| Low-Emission Channel Retrofit | EPA New Source Performance Standards mandate double-gasketed flange upgrades during Texas and California refinery turnarounds. |
Research Approach
Desk research of TEMA construction standards, ASME Boiler and Pressure Vessel Code filings, and customs trade data preceded structured interviews with refinery maintenance directors, EPC procurement leads, titanium alloy distributors, and aftermarket service heads. Primary fieldwork with plant engineers at Gulf Coast and Gujarat facilities combined with secondary validation through SEC filings from listed fabricators and import-export databases. Bottom-up unit economics triangulated against top-down petrochemical capacity expansion announcements.
Assumptions held titanium sponge pricing volatility and ASME certification lead times within observed ranges while varying India petrochemical buildout pace and EPA enforcement intensity. Segmentation modeling spanned product type, material grade, application, and end user across the projection horizon. CAGRs derived from replacement cycle analysis and capacity addition pipelines, with thermal duty requirements and fouling resistance coefficients as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by European fabrication houses or rapid compact heat exchanger technology maturation would shift outcomes. Cross-checking against BIS certification queue lengths and titanium sponge spot market indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Hot Water Circulator Pump Market
HVAC Equipment
Europe Dehumidifier Market
HVAC Equipment
Germany HVAC Market
HVAC Equipment
Blowers Market
HVAC Equipment
Combustion Controls, Equipments and Systems Market
HVAC Equipment
Europe HVAC Field Device Market
HVAC Equipment
Brazed Plate Heat Exchangers Market
HVAC Equipment
Japan Commercial HVAC Market
HVAC Equipment
North America Gas Water Heater Market
HVAC Equipment
HVAC Louvers Market
HVAC Equipment
Equipment for HVAC Market
HVAC Equipment
France Commercial HVAC Market
HVAC Equipment
Welded Spiral Heat Exchangers Market
HVAC Equipment
Asia-Pacific Heat Exchanger Market
HVAC Equipment
Ceiling Cassettes Market
HVAC Equipment
North America Heat Exchanger Market