
 Brazed Plate Heat Exchangers Market | 2026-2036
Brazed Plate Heat Exchangers Market Size, Share, and Industry Trends Forecast 2026-2036
Brazed Plate Heat Exchangers Market Intelligence
The EU F-Gas Regulation is hardening demand for low-charge refrigeration systems across European food processing facilities. Alfa Laval leverages its copper-brazing expertise to dominate industrial refrigeration retrofits in Northern Europe. Danfoss sustains channel control through captive distribution networks serving HVAC contractors. Kelvion Holding GmbH anchors its position with specialized nickel-brazed units for aggressive chemical environments.
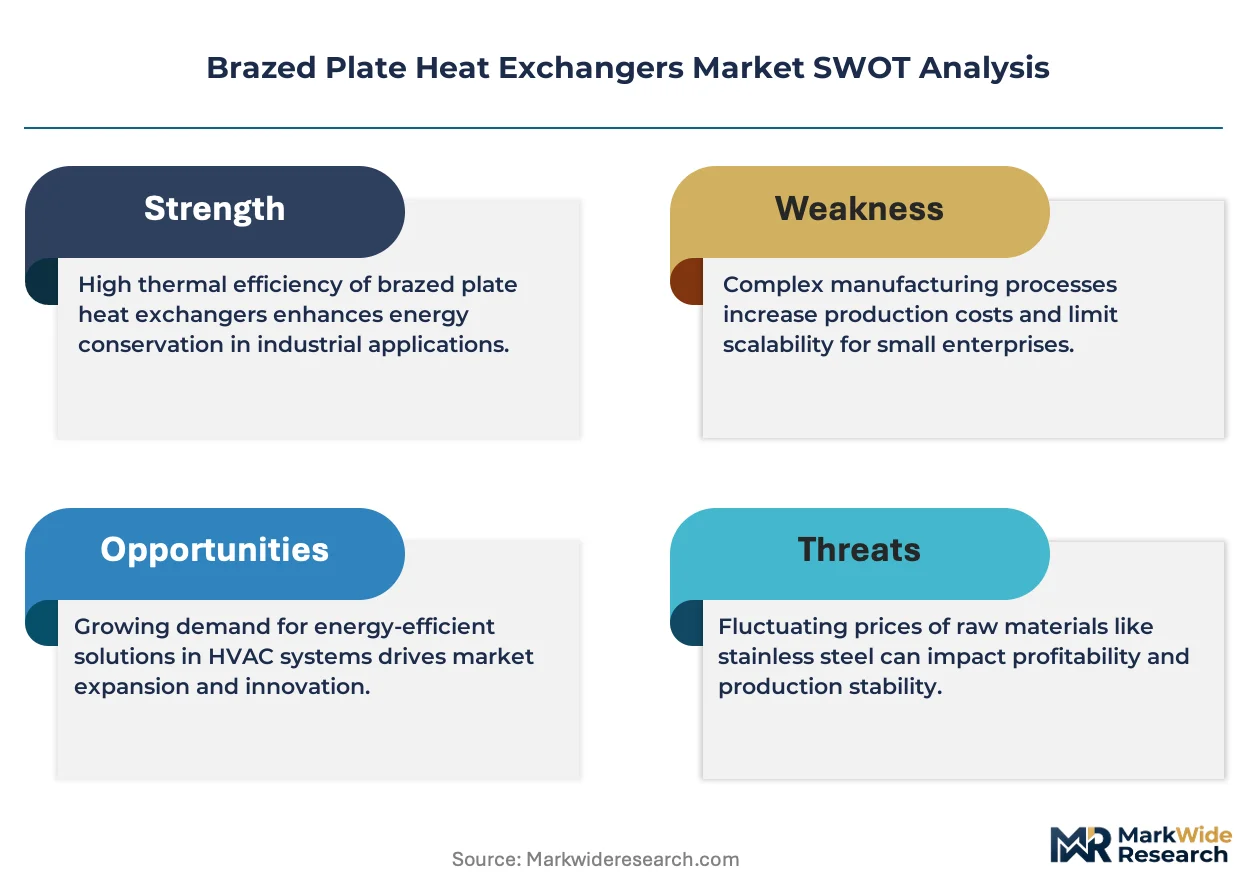
Brazed plate heat exchangers consist of corrugated stainless steel plates joined by brazing filler metals, typically copper or nickel, creating alternating hot and cold flow channels with heat transfer coefficients exceeding 3,000 W/m²K. These devices enable compact thermal energy transfer between fluids without gaskets, serving critical roles in refrigeration cycles, hydronic heating, and industrial process temperature control. HVAC applications lead volume due to widespread deployment in heat pumps and chiller systems, while chemical processing represents the fastest-growing segment as corrosive-resistant nickel-brazed designs displace traditional shell-and-tube units. Copper brazing technology occupies the mature core of the market, though silver-brazed variants command premium positioning for ultra-high-pressure hydrogen applications.
EPA SNAP program rules in the United States restrict high-GWP refrigerants, directly shaping replacement demand for compatible heat exchanger designs. EMA and REACH frameworks in Europe enforce material traceability and substance restrictions on brazing alloys, raising compliance costs for imported components. China's GB standards and MIIT efficiency mandates are tightening performance thresholds for heating equipment sold domestically. Stakeholders must monitor refrigerant chemistry transitions and alloy supply security as dual forces reshaping procurement criteria and supplier qualification timelines.
Market Dynamics
The EU F-Gas Regulation's phase-down mandates are compressing replacement cycles across European food processing refrigeration, forcing rapid adoption of low-charge brazed plate designs that minimize refrigerant volume while maintaining thermal performance.
Growth Catalysts
- US DOE Efficiency Standards:Commercial heating equipment mandates in the United States are accelerating replacement cycles for legacy shell-and-tube systems with compact brazed alternatives.
- Heat Pump Retrofit Momentum:Residential HVAC contractors across North America are expanding specification of brazed plate units for residential heat pump installations due to footprint constraints.
- Copper-Brazing Maturity:Established copper brazing processes enable cost-competitive manufacturing at scale, supporting volume deployment across standard HVAC applications.
Market Restraints
- Alloy Supply Concentration:Nickel and silver brazing filler metal supply chains concentrate in limited smelter geographies, exposing specialized unit producers to input volatility.
- REACH Compliance Burden:ECHA substance restrictions on brazing alloys raise qualification costs and extend procurement timelines for components imported into European markets.
- Shell-and-Tube Incumbency:Traditional shell-and-tube heat exchangers retain specification inertia in heavy industrial process applications with extreme pressure requirements.
Strategic Opportunities
- Hydrogen Energy Infrastructure:Ultra-high-pressure hydrogen applications are creating specification demand for silver-brazed variants with specialized pressure ratings.
- China Domestic Efficiency Mandates:MIIT performance thresholds for heating equipment are tightening, opening replacement demand for high-efficiency brazed designs in domestic Chinese markets.
- Industrial Process Corrosion Resistance:Chemical processors are specifying nickel-brazed units for aggressive media, displacing gasketed alternatives in sulfuric acid and chloride environments.
Industry Challenges
- Refrigerant Chemistry Transition:EPA SNAP program restrictions on high-GWP refrigerants force rapid redesign cycles to ensure material compatibility with emerging low-GWP alternatives.
- Certification Timeline Compression:Multiple concurrent regulatory frameworks across North America, Europe, and Asia-Pacific extend product qualification durations and strain engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazed Plate Heat Exchangers Market |
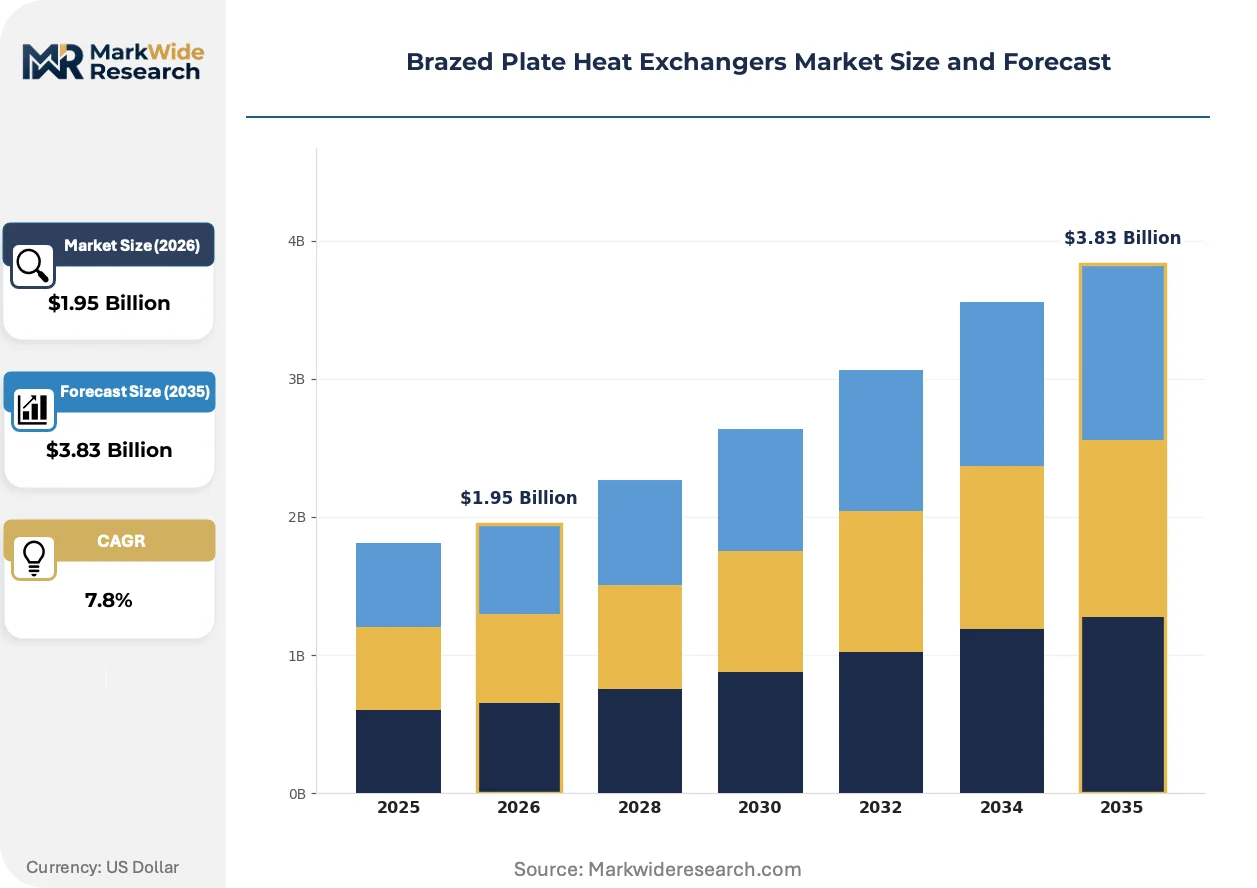
| Market Size in 2026 | $1.95 Billion |
| Market Size in 2035 | $3.83 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact, Semi-Welded, Fully Welded, Unitized Technology: Nickel Brazing, Copper Brazing, Aluminum Brazing, Silver Brazing Application: HVAC, Refrigeration, Food & Beverage Processing, Chemical Processing End User: Renewable Energy Developers, Marine Equipment Manufacturers, Semiconductor Fabricators, Power Generation Plants |
| Companies Covered | Alfa Laval, Danfoss, Kelvion Holding GmbH, SWEP International AB, API Heat Transfer, Xylem Inc., Hisaka Works Ltd., Chart Industries Inc., GEA Group Aktiengesellschaft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazed Plate Heat Exchangers Market Strategic Shifts & Innovations
Refrigerant chemistry transitions and brazing alloy material science are jointly reshaping product development priorities, with manufacturers racing to qualify designs for low-GWP working fluids while securing supply chain resilience for specialized filler metals.
Micro-channel brazed plate architectures are decentralizing thermal management system design by enabling distributed heat pump configurations that eliminate centralized chiller plants. Commercial building operators in Northern Europe are specifying these compact arrays for zoned climate control. The technology is decentralizing mechanical room footprints and reducing refrigerant charge volumes by over sixty percent compared to conventional centralized systems.
EPA SNAP program rules restricting high-GWP refrigerants are mandating material compatibility reassessments across the installed base. Equipment owners face accelerated replacement timelines as R-410A and R-134a face phasedown schedules. Food retail chains in the United States are responding by pre-qualifying brazed plate designs rated for R-454B and R-513A alternatives.
Specification authority is migrating from mechanical contractors to energy service companies with performance contracting capabilities. These ESCOs bundle heat exchanger selection into guaranteed savings agreements, displacing traditional component procurement. Germany's industrial refrigeration sector exhibits this pattern most acutely, where facility energy managers now dictate supplier qualification rather than maintenance departments.
Brazed Plate Heat Exchangers Market Segmentation
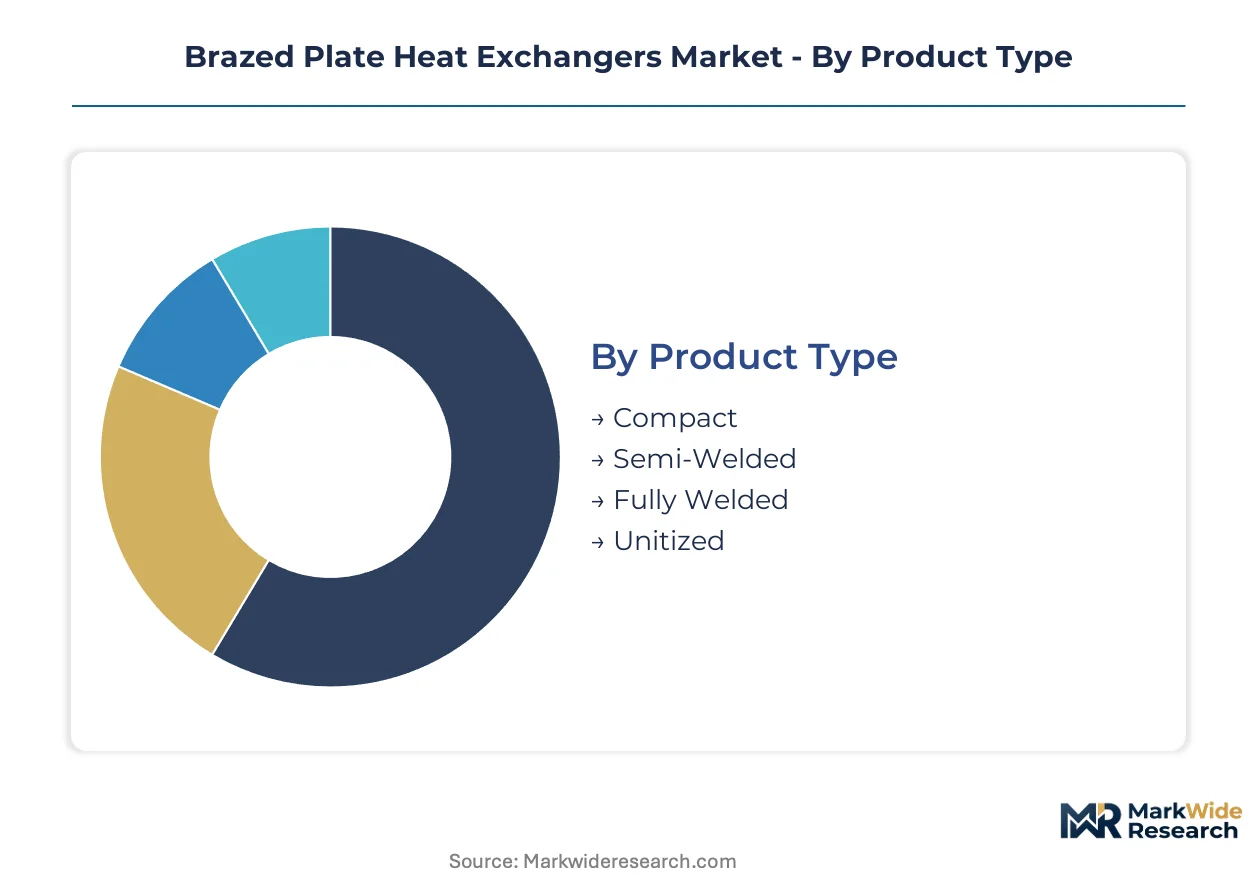
Segmentation in brazed plate heat exchangers reveals how manufacturing specialization and end-use requirements fragment supplier capabilities. Each dimension exposes distinct margin structures and qualification barriers that shape competitive positioning.
Product Type:
Supply concentration clusters around standardized compact designs where copper-brazing economies of scale dominate production capacity.
- Compact:Corrugated stainless steel plates bonded with copper filler metal deliver heat transfer coefficients above 3,000 W/m²K in minimal footprints. HVAC contractors across the United States specify these units for residential heat pump retrofits where mechanical room space constraints rule out shell-and-tube alternatives.
- Fully Welded:Laser-welded plate packs eliminate brazing filler metals entirely, enabling pressure ratings exceeding 100 bar for aggressive chemical service. German chemical processors facing ECHA substance restrictions on brazing alloys are migrating specification toward fully welded architectures for sulfuric acid heat recovery.
- Semi-Welded:Hybrid designs pair laser-welded channel pairs with gasketed plate assemblies for serviceability in food processing pasteurization loops.
- Unitized:Pre-assembled skid-mounted systems integrate pumps, controls, and heat exchanger cores for rapid deployment in distributed energy projects.
Compact units absorb the bulk of installed capacity; fully welded designs are expanding most quickly.
Technology:
Cost tier stratification separates mature copper processes from premium nickel and silver variants where raw material volatility compresses margins.
- Copper Brazing:Established furnace brazing processes using Cu-Sn-P alloys enable high-volume production at the lowest unit cost. Standard HVAC applications in China leverage this maturity as MIIT efficiency mandates drive equipment replacement without requiring exotic materials.
- Nickel Brazing:Ni-Cr-B-Si filler metals resist chloride corrosion and ammonia attack in industrial refrigeration. EU F-Gas Regulation phase-down mandates in Germany are accelerating specification of nickel-brazed low-charge systems for food processing facilities.
- Silver Brazing:Ag-Cu-Zn-Cd alloys withstand ultra-high pressures exceeding 700 bar for hydrogen fueling infrastructure. Japanese hydrogen station developers specify these variants under METI safety protocols for 70 MPa dispensing systems.
- Aluminum Brazing:Controlled atmosphere brazing of aluminum-silicon filler metals serves cost-sensitive automotive thermal management where weight reduction outweighs corrosion resistance requirements.
Copper brazing commands the greatest production volume; silver brazing exhibits the steepest expansion trajectory.
Application:
Customer type fragmentation separates specification authority between mechanical contractors, energy service companies, and facility engineering departments.
- HVAC:Heat pump and chiller systems deploy compact brazed units for hydronic heat transfer between refrigerant and water-glycol loops. US DOE commercial heating equipment standards are compressing replacement cycles for legacy systems in office buildings.
- Refrigeration:Supermarket display cases and industrial cold storage rely on low-charge brazed designs to minimize refrigerant inventory. EPA SNAP program restrictions on high-GWP refrigerants are forcing US food retailers to pre-qualify designs compatible with R-454B and R-513A.
- Chemical Processing:Nickel-brazed and fully welded units displace gasketed plate heat exchangers in sulfuric acid and caustic soda service.
- Food & Beverage Processing:Pasteurization and sterilization duties demand sanitary-grade surfaces with clean-in-place compatibility.
HVAC applications anchor current demand; chemical processing is climbing the fastest.
End User:
Geography and margin maturity concentrate procurement patterns across distinct industrial clusters with divergent qualification timelines.
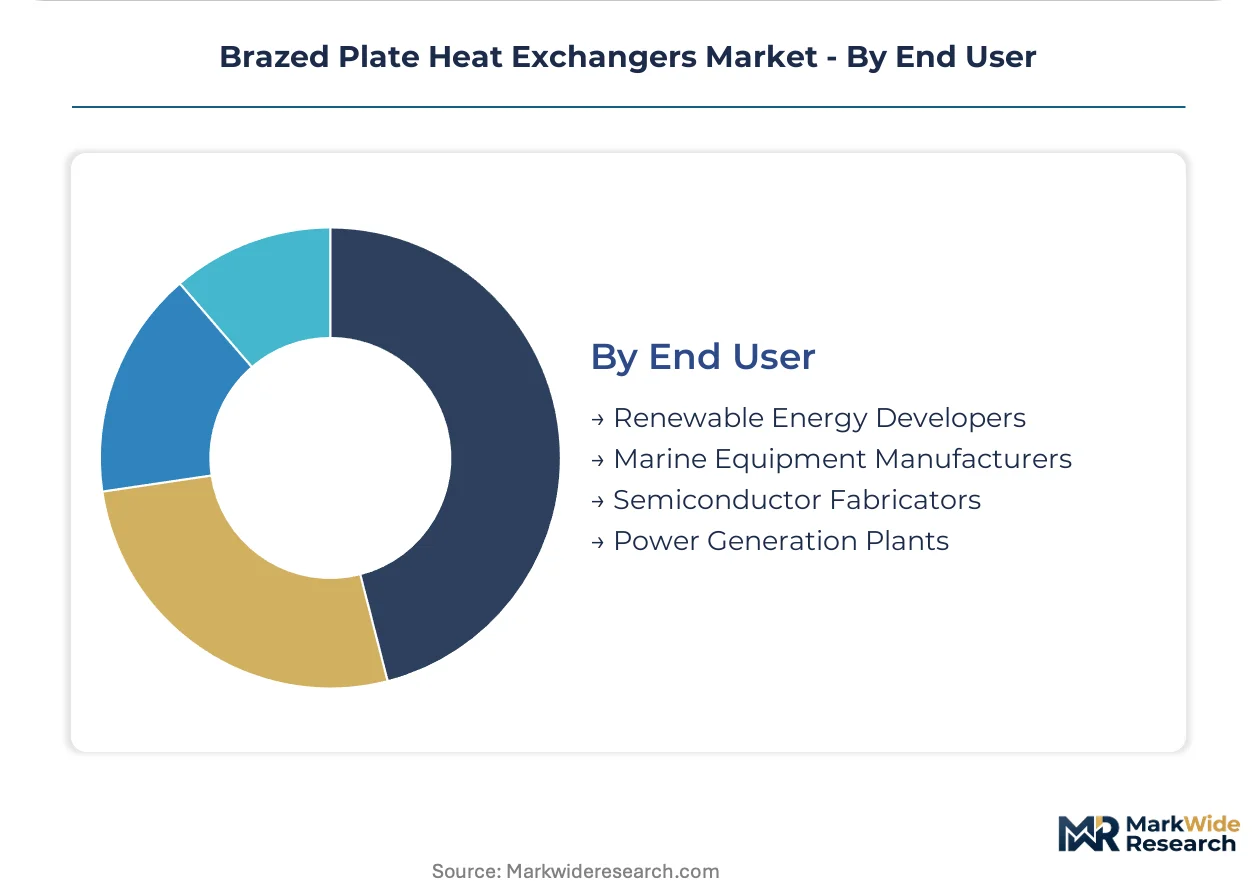
- Renewable Energy Developers:Geothermal and solar thermal projects specify large-format brazed units for heat collection fluid management. German district heating operators are deploying these in fourth-generation low-temperature networks.
- Semiconductor Fabricators:Ultra-pure water and process cooling loops demand nickel-brazed designs with electropolished surfaces to prevent ionic contamination. South Korean fab expansion under government semiconductor subsidies is driving specification volume.
- Power Generation Plants:Combined cycle gas turbine plants use brazed plate economizers for feedwater preheating.
- Marine Equipment Manufacturers:Space-constrained engine cooling and HVAC systems on vessels require corrosion-resistant titanium-clad variants.
Renewable energy developers represent the largest addressable base; semiconductor fabricators are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ruhr industrial corridor in Germany anchors European demand for nickel-brazed industrial refrigeration units, while Chinese manufacturing clusters along the Yangtze River Delta supply copper-brazed HVAC components at scale.
United States
HVAC contractors in Texas and Florida are retrofitting residential heat pumps with compact brazed units to meet footprint constraints. EPA SNAP program restrictions on high-GWP refrigerants are compressing replacement cycles for supermarket refrigeration systems. Food retail chains in California are pre-qualifying designs compatible with R-454B alternatives.
Germany
Industrial food processors in Bavaria face accelerated equipment replacement under EU F-Gas Regulation phase-down mandates. ECHA substance restrictions on brazing alloys are raising qualification costs for imported components. Chemical manufacturers in North Rhine-Westphalia are migrating specification toward fully welded architectures for sulfuric acid service.
China
MIIT efficiency mandates for domestic heating equipment are tightening performance thresholds across Shandong Peninsula manufacturing zones. GB standards enforcement is disqualifying legacy shell-and-tube designs from government procurement. District heating operators in Beijing-Tianjin-Hebei are deploying large-format brazed units for fourth-generation low-temperature networks.
Japan
Hydrogen station developers under METI safety protocols are specifying silver-brazed variants for 70 MPa dispensing infrastructure. Semiconductor fabricators in Kyushu are driving demand for nickel-brazed designs with electropolished surfaces. Automotive thermal management suppliers in Nagoya are adopting aluminum-brazed architectures for weight-sensitive electric vehicle cooling loops.
South Korea
Government semiconductor subsidies are accelerating fab expansion around Seoul Capital Area, driving specification volume for ultra-pure process cooling. MFDS pharmaceutical manufacturing standards are mandating sanitary-grade heat exchanger surfaces for biologics production. Shipbuilders in Busan-Ulsan are specifying titanium-clad variants for space-constrained marine engine cooling systems.
Brazed Plate Heat Exchangers Market Key Industry Players
The competitive structure tilts toward diversified thermal engineering conglomerates with captive brazing expertise and established furnace infrastructure. Three archetypes dominate: European industrial refrigeration specialists with nickel-brazing capabilities, Scandinavian HVAC-focused fabricators leveraging copper-brazing scale economies, and diversified process equipment multinationals serving chemical and energy verticals. Capacity expansion in Asian manufacturing zones and strategic partnerships for hydrogen infrastructure qualification represent the dominant competitive vectors.
Among European-based specialists, Alfa Laval, Danfoss, and Kelvion Holding GmbH exemplify the diversified thermal engineering archetype with established positions across refrigeration and process cooling verticals. These entities anchor the premium tier through specialized alloy expertise and captive distribution networks, while maintaining scale positions in standardized HVAC applications through furnace infrastructure deployed across multiple manufacturing geographies.
| Leading Market Players |
|---|
| Alfa Laval |
| Danfoss |
| Kelvion Holding GmbH |
| SWEP International AB |
| API Heat Transfer |
| Xylem Inc. |
| Hisaka Works Ltd. |
| Chart Industries Inc. |
| GEA Group Aktiengesellschaft |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap specialists across Northern Europe anchor supply discipline through multi-generational furnace infrastructure ownership, translating captive brazing expertise into pricing power that resists commoditization pressure from Asian volume producers. Their control over nickel-brazing qualification timelines creates natural price floors for industrial refrigeration applications where EU F-Gas Regulation compliance cannot tolerate supply disruption.
Pricing Analysis
Value-based pricing anchored to thermal performance guarantees dominates project contracting for industrial process applications. Three-tier pricing structure across premium, standard, and economy levels separates silver-brazed hydrogen infrastructure units from copper-brazed HVAC commodities. Cost compression in standard HVAC tiers is intensifying because Chinese manufacturers leverage MIIT efficiency mandate-driven volume to absorb alloy volatility. Food processors facing EPA SNAP program refrigerant transitions exhibit lowest price sensitivity due to compliance-driven replacement urgency, while residential contractors in Texas and Florida remain most sensitive to unit cost differentials.
Supply Chain Analysis
Copper filler metal supply rests on Chilean and Peruvian mining concentration, while nickel-brazing alloys draw from Russian and Canadian smelter geography. Stainless steel plate feedstock sources from Chinese and Indonesian integrated mills, with corrugated forming equipment concentrated in German and Italian machine tool builders. Single-source vulnerability runs through silver supply for hydrogen-rated units, where Mexican and Polish refiners dominate Ag-Cu-Zn-Cd alloy production. Distribution runs through captive HVAC wholesaler networks in North America and specialized industrial refrigeration distributors in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized brazing furnace capacity constitutes the binding constraint propping pricing discipline, as multi-year qualification timelines for nickel and silver alloys prevent rapid supply response to demand surges in hydrogen and industrial refrigeration verticals.
For Market Incumbents: Cement alloy supply security through backward integration into captive filler metal production or long-term offtake agreements with Russian and Canadian smelters. Expand furnace capacity in Poland and Mexico to serve hydrogen infrastructure demand without exposing qualification timelines to Asian logistics chokepoints. Threat substitution from fully welded laser architectures in German chemical processing demands accelerated R&D in hybrid brazed-welded designs. For New Entrants and Emerging Players: HVAC contractors in Florida and Texas represent the most penetrable channel partner type for compact copper-brazed units, as heat pump retrofit momentum outpaces established supplier response capacity. Target food retail chains in California pre-qualifying R-454B compatible designs ahead of EPA SNAP enforcement windows. Go-to-market angle should bundle installation training with unit supply to capture specification authority migrating from mechanical contractors to energy service companies. For Investors and Strategic Acquirers: Distressed-cycle entries favor nickel-brazing specialists with captive ECHA REACH compliance documentation in Germany and Poland, as regulatory qualification costs create moats against Asian volume competition. Long-term viability hinges on hydrogen infrastructure certification positioning over a decade horizon. Watch METI safety protocol revisions for 70 MPa hydrogen dispensing as the inflection signal for silver-brazed unit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Furnace Capacity Expansion | Polish and Mexican greenfield sites shorten lead times for hydrogen-rated silver-brazed units under METI protocols. |
| Backward Integration into Alloys | Captive nickel filler metal production insulates German refrigeration specialists from Russian supply volatility. |
| Low-GWP Refrigerant Qualification | Pre-certified R-454B and R-513A designs capture California food retail replacement cycles ahead of EPA SNAP enforcement. |
| Micro-Channel Architecture Deployment | Distributed heat pump arrays reduce refrigerant charge volumes sixty percent for Northern European commercial building operators. |
| Channel Partner Training Programs | Installation certification bundles capture specification authority migrating to Texas and Florida HVAC contractors. |
Research Approach
Document review covered SEC 10-K filings from thermal engineering conglomerates, ECHA substance restriction updates, and EPA SNAP program rulemaking dockets, complemented by interviews with HVAC contractor procurement managers, industrial refrigeration system integrators in Bavaria, and nickel alloy smelter sales directors. Secondary validation drew from customs trade data for brazing filler metal flows, MIIT equipment efficiency bulletins, and German district heating association technical specifications. Bottom-up unit demand modeling triangulated against top-down spending estimates from energy service company contract disclosures.
Cross-referencing historical copper and nickel price elasticity patterns against expert panel input on qualification timeline rigidity shaped the projection framework across the analysis window. Segmentation dimensions modeled include brazing technology tier, application vertical, end-user industry cluster, and regional regulatory framework cluster. CAGRs derived from installed base replacement cycle analysis, refrigerant phase-down schedule enforcement probability, and hydrogen infrastructure deployment curves under METI and EU Green Deal funding programs.
Caveats apply where ECHA substance restriction scope expansion or Russian nickel supply disruption could materially shift the outlook for European industrial refrigeration demand. Forecasts reflect assumptions on refrigerant chemistry transition pace and alloy smelter capacity utilization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Europe Hydronic Radiators Market
HVAC Equipment
Equipment Fan Filter Unit (EFU) Market
HVAC Equipment
Kitchen Hood Market
HVAC Equipment
US Heating Equipment Market
HVAC Equipment
Global Air Handling Units (AHU) Market
HVAC Equipment
North America Commercial HVAC Market
HVAC Equipment
Global Heat Exchangers Market
HVAC Equipment
Industrial Dehumidifiers Market
HVAC Equipment
US HVAC Field Device Market
HVAC Equipment
United States Air Conditioning Equipment Market
HVAC Equipment
Latin America Heat Exchanger Market
HVAC Equipment
Combustion Controls, Equipments and Systems Market
HVAC Equipment
South America Compressor Market
HVAC Equipment
Global Split Systems Market
HVAC Equipment
Compact Fan Coils Market
HVAC Equipment
Centrifugal Chillers Market