
 United Kingdom Heating Equipment Market | 2026-2036
United Kingdom Heating Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Heating Equipment Market Analytics
Modular heat pump packages bundled with smart controls and cylinder integration is realigning how installers specify residential systems. Worcester Bosch leverages its domestic manufacturing footprint to sustain next-day parts availability across Britain. Vaillant anchors its position through extensive installer training networks that lock in specification loyalty. Daikin Industries Ltd competes on variable refrigerant flow expertise carried over from its commercial air conditioning base.
United Kingdom heating equipment encompasses boilers, heat pumps, radiators, and underfloor heating systems engineered to deliver space heating and domestic hot water across residential, commercial, and industrial premises, with heat pumps typically achieving coefficient of performance ratings between three and five depending on source temperature and emitter design. Gas-fired condensing boilers remain the installed base majority but face phase-down pressure under carbon budgets, while air-source heat pumps represent the fastest-growing product category as electrification incentives deepen and cold-climate compressor technology improves. The residential end user segment carries the largest absolute volume, though commercial retrofits command stronger margins due to complexity and bespoke engineering requirements.
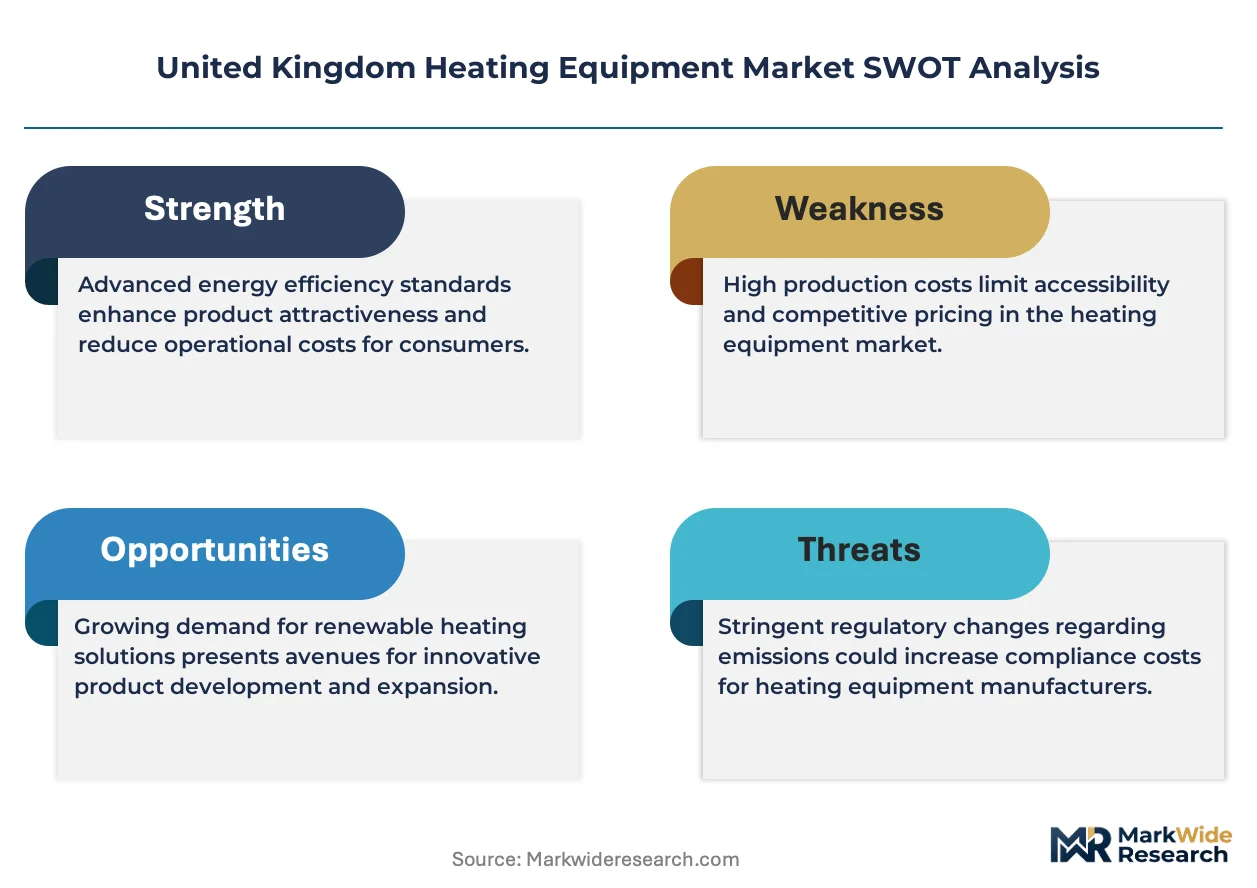
The Boiler Upgrade Scheme administered by Ofgem shapes near-term demand through grant-supported heat pump adoption, while the Future Homes Standard from the Ministry of Housing, Communities and Local Government will prohibit fossil fuel heating in new English homes. Building Regulations Part L and the corresponding compliance frameworks in Wales and Scotland enforce efficiency minimums that filter available product ranges. Stakeholders must track how the Clean Heat Market Mechanism alters manufacturer obligations and whether grid capacity constraints in rural sub-regions delay electrification timelines.
Market Dynamics
The electrification pivot from gas boilers to heat pumps is compressing replacement cycles and rewiring installer-specifier relationships across Britain's residential base.
Growth Catalysts
- Boiler Upgrade Scheme:Ofgem-administered grants reduce upfront capital barriers for households replacing aging gas systems with air-source heat pumps, accelerating retrofit momentum in England's southeast corridor.
- Future Homes Standard:The Ministry of Housing, Communities and Local Government mandate prohibits fossil fuel heating in new English dwellings from 2025, forcing developers toward low-carbon specifications.
- Cold-climate compressor advances:Improved variable-speed scroll and rotary technology extends heat pump operating range to sub-zero temperatures, unlocking rural northern installations previously deemed non-viable.
Market Restraints
- Copper and rare-earth input costs:Compressor windings and refrigerant piping expose manufacturers to London Metal Exchange volatility and Chinese export quotas on neodymium magnets.
- Grid capacity saturation:Distribution network operators in rural Scotland and Wales sub-regions lack headroom for mass electrification, delaying connection timelines for clustered heat pump deployments.
- Gas boiler residual stock:Twenty million installed condensing units with 15-year lifespans create a sunk-cost drag on household switching economics outside grant-eligible zones.
Strategic Opportunities
- Hybrid heat pump-gas systems:Bivalent configurations blending air-source compressors with hydrogen-ready boilers capture risk-averse retrofitters in transitional zones.
- Installer certification networks:Microgeneration Certification Scheme accreditation creates lock-in effects that manufacturers can monetize through exclusive parts and warranty channels.
- Social housing decarbonization:Local authority retrofit programs aggregate fragmented demand into volume tenders, favoring suppliers with modular package capabilities and maintenance bundling.
Industry Challenges
- Heat pump engineer scarcity:F-gas certification and MCS accreditation requirements outstrip training pipeline capacity, constraining installation throughput.
- Legacy emitter incompatibility:Existing radiator sizing and distribution pipework often underserve heat pump flow temperatures, forcing disruptive civil works that erode project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Heating Equipment Market |
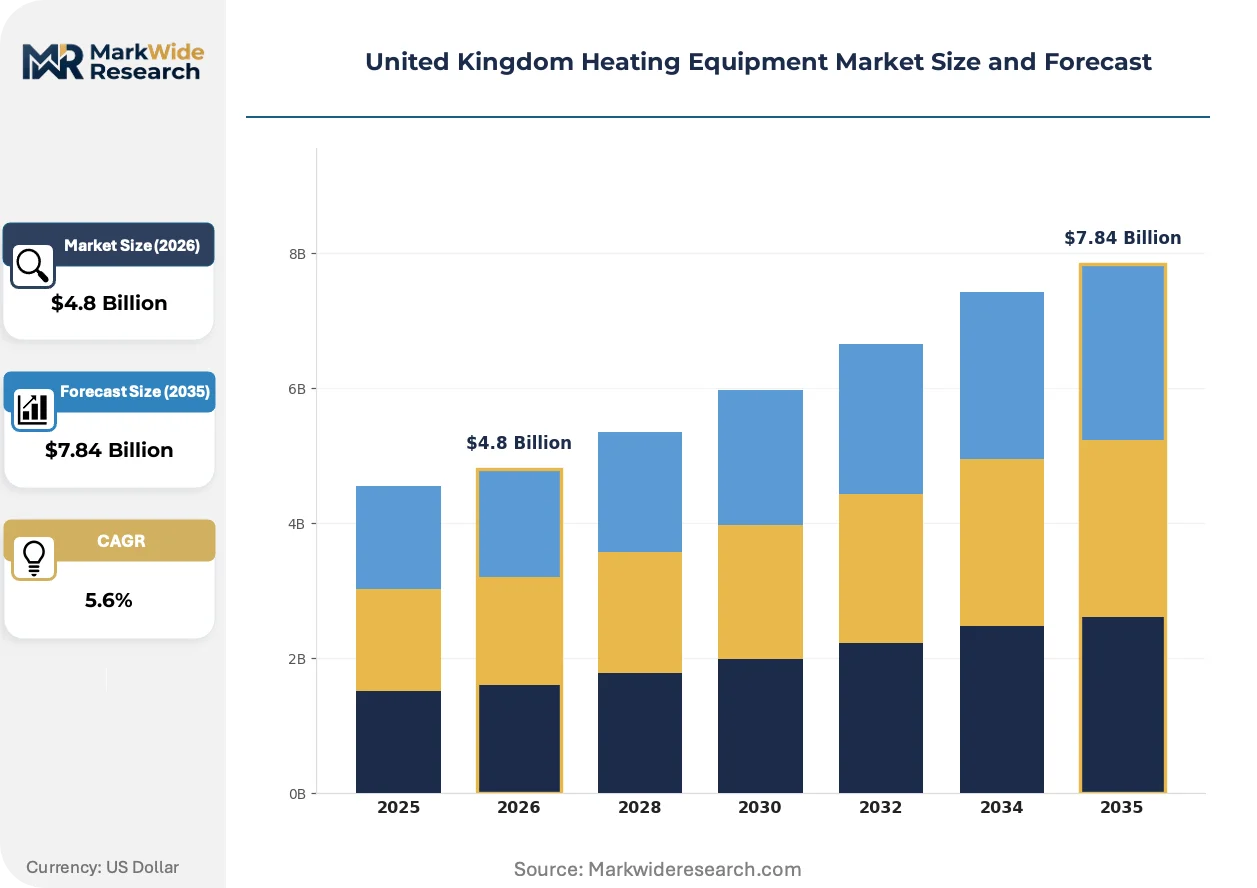
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boilers, Heat Pumps, Radiators, Underfloor Heating End User: Residential, Industrial, Commercial, Institutional Technology: Electric, Gas, Solar, Biomass Installation Type: New Construction, Retrofits, Upgrades, Maintenance |
| Companies Covered | Worcester Bosch, Vaillant, Ideal Boilers, Baxi, Trane Inc, Mitsubishi Electric Europe BV, Daikin Industries Ltd, Aermec SpA, Robert Bosch Gmbh, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Heating Equipment Market Evolving Landscape
Digitalization and refrigerant chemistry shifts are compressing system design cycles while regulatory tightening forces rapid product portfolio turnover across British manufacturers.
Refrigerant transition to lower-global-warming-potential blends is automating compliance redesign across compressor and heat exchanger engineering teams. Manufacturers face compressed retooling timelines as F-Gas Regulation phase-down schedules tighten quota availability for legacy hydrofluorocarbons. The shift is automating supplier qualification processes, with component vendors now pre-certifying aluminum microchannel coils and electronic expansion valves for R32 and R290 compatibility before specification lock-in.
Building Regulations Part L revisions are tightening efficiency minimums for space heating and hot water systems in English dwellings. The framework is filtering available product ranges, with condensing gas boilers facing efficiency thresholds that only modulating systems with enhanced flue recovery can satisfy. New-build developers are responding by pre-specifying monobloc air-source heat pumps with integrated cylinders, bypassing the compliance complexity of separate component sourcing.
Installer-direct procurement is displacing traditional merchant intermediaries in residential specification. Heating engineers now configure complete packages via manufacturer portals that bundle outdoor units, cylinders, controls, and commissioning support, collapsing the role of regional plumbing distributors. This pattern concentrates in southeastern England's dense housing corridors, where installer loyalty programs and next-day parts availability override price competition from generic wholesalers.
United Kingdom Heating Equipment Market Segmentation
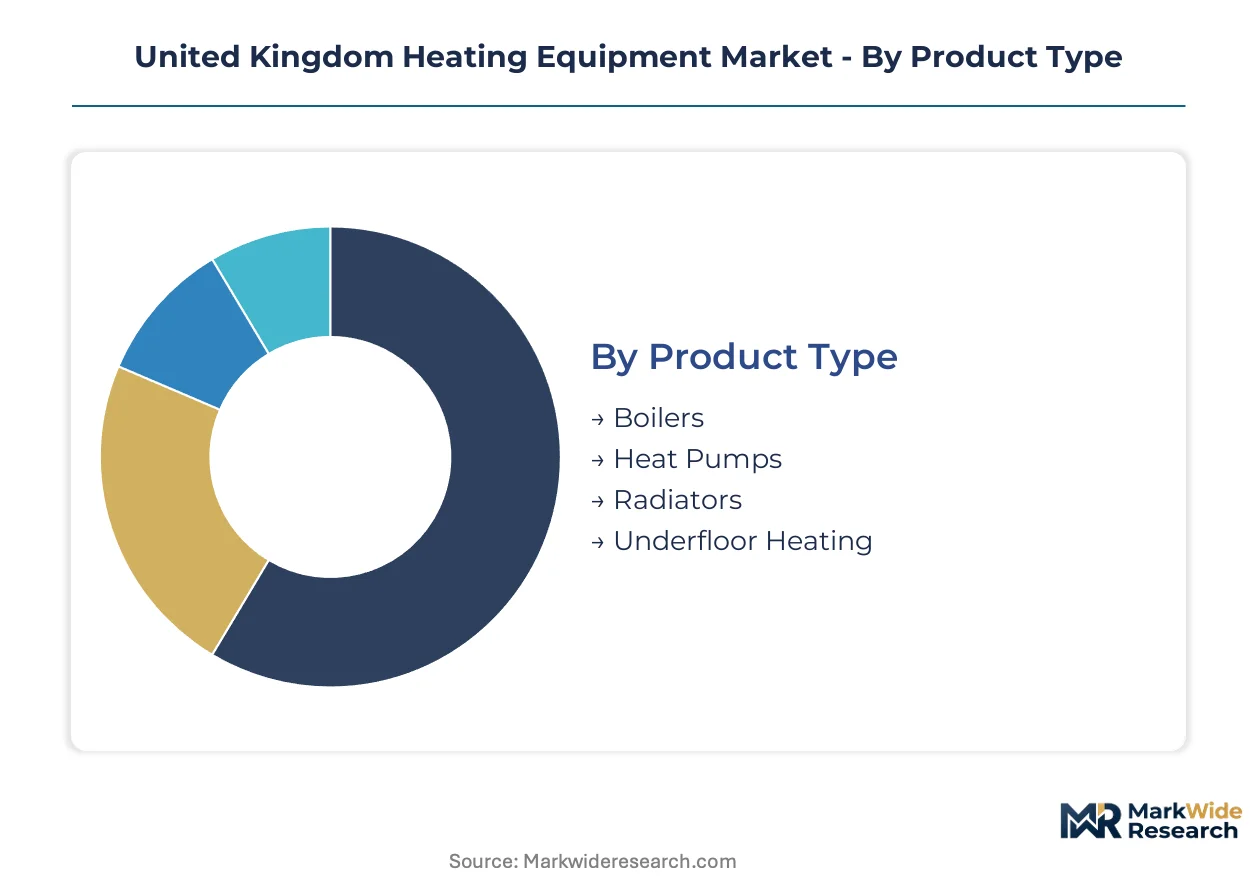
Segmentation in the United Kingdom heating equipment market reveals how regulatory pressure and installation economics split demand across product architectures and customer profiles. Understanding these divides exposes where electrification incentives penetrate deepest and where legacy gas infrastructure retains residual lock-in.
Product Type:
Standardized mass-market units dominate at one pole while bespoke integrated systems command premium specification at the other, with refrigerant chemistry and emitter compatibility driving the customization gradient.
- Boilers:Gas-fired condensing units with modulating burners and enhanced flue gas recovery systems remain the installed base majority across England's aging housing stock. Replacement demand concentrates in suburban owner-occupied properties where 15-year asset lifespans create predictable refresh cycles, though Boiler Upgrade Scheme grants are accelerating switching economics in eligible postcodes.
- Heat Pumps:Monobloc and split-system air-source configurations with variable-speed scroll compressors achieve coefficient of performance ratings between three and five depending on source temperature and emitter design. Southeast England corridors show densest adoption where housing turnover and grid capacity converge, while cold-climate compressor advances unlock rural northern installations previously deemed non-viable.
- Radiators:Low-temperature aluminum and steel panel emitters sized for heat pump flow temperatures represent a retrofit upgrade category, with demand clustering in social housing decarbonization programs.
- Underfloor Heating:Wet systems with polymer or composite piping integrated into screed layers command new-build specification where Future Homes Standard compliance is mandatory from 2025 onward.
Leading the category by volume: Boilers. Growing fastest: Heat Pumps.
End User:
Margin structure separates fragmented residential volume from concentrated commercial complexity, with project scale and engineering specificity determining supplier economics.
- Residential:Single-family and multi-occupancy dwellings account for absolute volume leadership, with retrofit installations expanding as households replace aging gas boilers under Ofgem-administered grant schemes. Demand concentrates in owner-occupied suburban stock with sufficient roof space and electrical capacity for air-source heat pump siting.
- Commercial:Offices, retail premises, and hospitality venues command stronger margins due to bespoke engineering requirements and extended maintenance contracting. Procurement aggregates through facilities management platforms that prioritize whole-life cost over capital expenditure.
- Industrial:Process heating and warehouse space conditioning applications favor high-capacity gas absorption or biomass systems where thermal load density exceeds electrification feasibility.
- Institutional:Schools, hospitals, and government buildings operate under public sector decarbonization frameworks with extended tender cycles and strict Microgeneration Certification Scheme accreditation requirements.
Volume leadership sits with Residential. Steepest expansion trajectory: Institutional retrofits tied to net-zero public building commitments.
Technology:
Primary energy source selection tracks grid decarbonization pace and building regulation stringency across English, Welsh, and Scottish jurisdictions.
- Electric:Air-source and ground-source heat pumps with inverter-driven compressors capture electrification momentum as distribution network operators upgrade rural capacity. F-Gas Regulation phase-down schedules are accelerating refrigerant transition to R32 and lower-global-warming-potential blends.
- Gas:Hydrogen-ready condensing boilers with 20% hydrogen blending capability extend asset relevance through transitional zones where heat pump feasibility remains constrained by fabric efficiency or connection delays.
- Solar:Thermal collector systems with evacuated tube or flat-plate configurations occupy niche specification for domestic hot water pre-heating in new-build compliance stacking.
- Biomass:Wood pellet and chip boilers serve off-grid rural estates and agricultural premises with accessible fuel supply chains and sufficient storage footprint.
Dominant by installed base: Gas. Climbing the fastest: Electric heat pumps under Boiler Upgrade Scheme deployment.
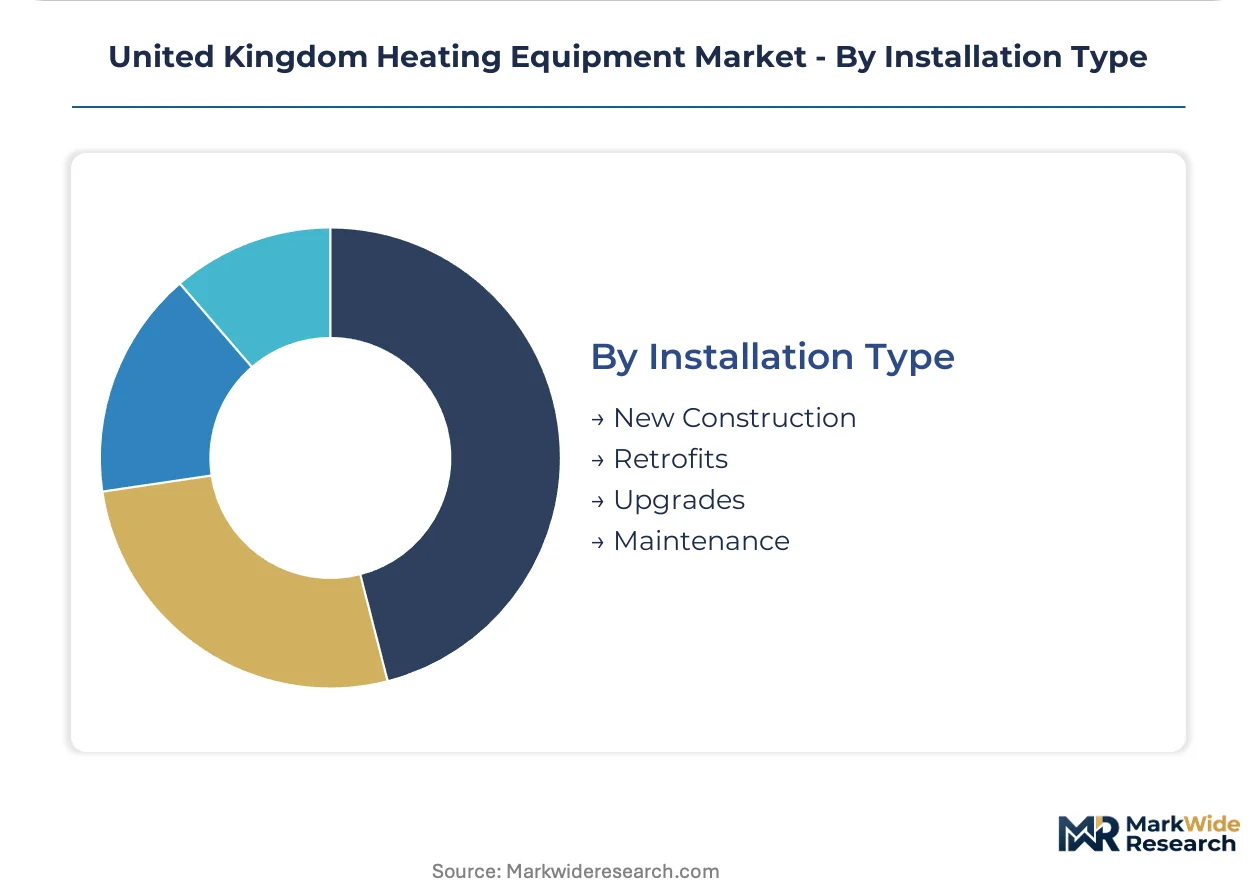
Installation Type:
Project origination splits between regulatory-mandated new-build specification and economically-driven replacement cycles, with maintenance bundling emerging as a recurring revenue anchor.
- New Construction:Developer-led specification of monobloc heat pump packages with integrated cylinders and smart controls is displacing separate component sourcing as Building Regulations Part L tightens efficiency minimums.
- Retrofits:Residential boiler-to-heat-pump conversions dominate grant-supported activity, though legacy emitter incompatibility and distribution pipework undersizing force disruptive civil works that erode project margins.
- Upgrades:Efficiency-focused replacements of pre-condensing boilers and uninsulated hot water cylinders concentrate in fuel-poor households targeted by local authority retrofit programs.
- Maintenance:Annual servicing contracts and extended warranty coverage generate recurring revenue for manufacturer-accredited installer networks with next-day parts availability.
Retrofits command near-term volume. New Construction shows steepest policy-driven acceleration under Future Homes Standard implementation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
England's southeast corridor concentrates heat pump deployment where grid capacity and housing turnover converge, while devolved administrations in Scotland and Wales pursue distinct decarbonization trajectories under separate building regulations.
London and Southeast England
Retrofit installations cluster in owner-occupied suburban stock across Kent, Surrey, and Essex where Ofgem-administered Boiler Upgrade Scheme grants accelerate switching economics. The Ministry of Housing, Communities and Local Government enforces Building Regulations Part L efficiency minimums that filter available product ranges. Installer-direct procurement concentrates in Greater London commuter belts where next-day parts availability from domestic manufacturing footprints overrides price competition.
Midlands
Social housing decarbonization programs aggregate fragmented demand into volume tenders across Birmingham, Nottingham, and Leicester metropolitan areas. Local authority retrofit frameworks prioritize modular heat pump packages with maintenance bundling. Worcester Bosch leverages its domestic manufacturing presence to sustain specification loyalty through accredited installer networks in West Midlands industrial corridors.
North England
Cold-climate compressor advances unlock rural northern installations previously deemed non-viable across Yorkshire, Lancashire, and Cumbria. Distribution network operators in rural sub-regions lack headroom for mass electrification, delaying connection timelines for clustered heat pump deployments. Hydrogen-ready boiler specifications extend relevance in transitional zones where fabric efficiency constraints persist.
Scotland
The Scottish Government's Heat in Buildings Strategy mandates zero-emission heating in off-gas-grid properties by 2030, accelerating air-source heat pump specification in Highland and Island communities. Building Standards Scotland enforce efficiency minimums distinct from English frameworks. F-gas certification and MCS accreditation requirements outstrip training pipeline capacity in Aberdeen and Edinburgh installer markets.
Wales
Building Regulations Wales compliance frameworks enforce efficiency minimums that filter available product ranges in Cardiff and Swansea new-build corridors. Grid capacity saturation in rural Powys and Gwynedd sub-regions delays connection timelines for clustered electrification. Biomass pellet systems retain niche specification in agricultural premises with accessible fuel supply chains.
United Kingdom Heating Equipment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The installed base majority in gas-fired condensing boilers faces phase-down pressure under carbon budgets, compressing replacement cycles and rewiring installer-specifier relationships. Three archetypes dominate: domestic manufacturers with captive distribution, multinational HVAC conglomerates with refrigerant expertise, and specialist boiler fabricants with hydrogen-transition portfolios. Competitive moves concentrate on installer certification lock-in and modular package standardization.
Among UK-based heating equipment fabricants, Worcester Bosch and Ideal Boilers anchor the domestic manufacturing tier, while Vaillant exemplifies continental European specialists with extensive training network investments. Daikin Industries Ltd occupies a position carried over from commercial air conditioning expertise. These three represent distinct strategic postures: domestic footprint leverage, installer relationship depth, and variable refrigerant flow technology transfer.
| Leading Market Players |
|---|
| Worcester Bosch |
| Vaillant |
| Ideal Boilers |
| Baxi |
| Trane Inc |
| Mitsubishi Electric Europe BV |
| Daikin Industries Ltd |
| Aermec SpA |
| Robert Bosch Gmbh |
| Others |
Value Network & Pricing Analysis
F-gas-certified engineer clusters across England's West Midlands anchor labor-cost differentials that widen pricing-tier spreads between MCS-accredited premium installations and uncertified economy alternatives. The scarcity of Microgeneration Certification Scheme-qualified technicians in rural Scotland and Wales forces contractors to absorb travel premiums or defer projects, compressing margins in sub-regions where electrification incentives run strongest.
Pricing Analysis
Lead-time premiums for next-day heat pump commissioning from domestic manufacturers like Worcester Bosch command standard-economy spreads of fifteen to twenty percent over spot inventory from merchant distributors. Price differentiation hinges on MCS accreditation tier and bundled maintenance contracting, with social housing aggregators driving the steepest volume discounts. Cost compression in economy-tier boiler replacements intensifies as hydrogen-ready specifications extend gas system relevance. Residential retrofits in grant-eligible southeast postcodes show lowest price sensitivity, while fuel-poor households targeted by local authority programs demand maximum capital subsidy capture.
Supply Chain Analysis
Freight cost exposure from East Asian compressor manufacturing feeds into landed cost volatility for variable-speed scroll units that British OEMs specify. Geographic supply concentration centers on China for rare-earth magnet windings, Germany for precision electronic expansion valves, and domestic West Midlands fabrication for sheet-metal housings. Raw material dependencies span London Metal Exchange copper for refrigerant piping, Chinese neodymium for compressor motors, and Korean aluminum microchannel coils. Single-source vulnerability sits with Taiwanese inverter drive suppliers. Distribution runs through manufacturer-direct portals that displace regional plumbing merchants in southeastern England's dense installer corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom heating equipment market reads as a consolidation play where Boiler Upgrade Scheme grant dependency and F-gas certification scarcity will force sub-scale fabricants toward strategic exit or acquisition.
For Market Incumbents: To counter installer network fragmentation, deepen captive certification pipelines through exclusive Microgeneration Certification Scheme training academies in West Midlands and Greater Manchester hubs. Secure backward integration into aluminum heat exchanger fabrication to buffer Korean coil supply volatility. Lock social housing aggregators into ten-year maintenance bundling that raises switching costs for rival modular package suppliers. For New Entrants and Emerging Players: Regional installer cooperatives in rural Scotland and Wales represent the most penetrable channel structure given incumbent neglect of grid-constrained sub-regions. Target off-gas-grid Highland and Island communities where Scottish Government zero-emission mandates outpace supply response. Pursue white-label heat pump cylinder manufacturing for merchant distributors seeking private-label alternatives to branded monobloc systems. For Investors and Strategic Acquirers: Re-rating potential sits with hydrogen-ready boiler specialists given transitional demand longevity and stranded asset risk mispricing. Long-term viability over a decade-long decarbonization window favors fabricants with dual electrification and hydrogen-transition portfolios. Acquisition targets should show MCS-accredited installer network density and domestic manufacturing footprint. The signal to watch is Clean Heat Market Mechanism obligation trading prices as a proxy for regulatory compliance cost pass-through.| Strategic Initiative | Industry Significance |
|---|---|
| MCS Accreditation Network Expansion | Exclusive training pipelines lock installer specification loyalty against generic competitors. |
| Backward Integration into Heat Exchangers | In-house aluminum microchannel coil production buffers Korean supply volatility and F-Gas retooling delays. |
| Social Housing Maintenance Bundling | Ten-year service contracts with local authorities generate recurring revenue and raise rival switching costs. |
| Hydrogen-Ready Boiler Portfolio Extension | Transitional zone positioning captures risk-averse retrofitters where heat pump feasibility remains constrained. |
| Installer-Direct Portal Investment | Digital procurement platforms displace merchant intermediaries and capture specification data for demand forecasting. |
Research Methodology
Independent corroboration across Ofgem grant disbursement records, Microgeneration Certification Scheme accreditation databases, and Building Regulations Part L compliance filings underwrites the qualitative findings in this study. Primary interviews with heat pump installation engineers, social housing procurement officers, distribution network planning managers, and manufacturer product directors combined with secondary validation from BEIS policy consultations, Ofgem market mechanism consultations, and domestic manufacturing trade association reports. Bottom-up project pipeline analysis across local authority retrofit frameworks triangulated against top-down carbon budget trajectory modeling.
Comparable-period anchoring to historical Boiler Upgrade Scheme deployment rates and Future Homes Standard consultation timelines established the forecast window boundaries. Segmentation dimensions modeled span product architecture, end-user category, primary energy source technology, and installation origination type across the projection horizon. CAGRs derived from grant uptake velocity curves, housing stock turnover rates, and grid capacity expansion schedules. Industry-specific forecast inputs include F-Gas Regulation phase-down quota trajectories and cold-climate compressor efficiency improvement curves.
Several conditions sit outside the modeled scope, including potential hydrogen grid injection mandate revisions, wholesale electricity price volatility beyond current forward curves, and unannounced deviations from Clean Heat Market Mechanism obligation schedules. Forecasts reflect documented assumptions regarding installer training pipeline expansion rates and distribution network reinforcement prioritization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Ventilation Equipment Market
HVAC Equipment
Air Conditioner Quilt Market
HVAC Equipment
Steam Boiler Systems Market
HVAC Equipment
HVAC Centrifugal Compressors Market
HVAC Equipment
HVAC Chillers Market
HVAC Equipment
Shell and Tube Heat Exchangers Market
HVAC Equipment
Helical Screw Blowers Market
HVAC Equipment
Refrigerant Compressors Market
HVAC Equipment
Residential Furnaces Market
HVAC Equipment
North America Gas Water Heater Market
HVAC Equipment
Kitchen Hood System Market
HVAC Equipment
HVAC System Analyzer Market
HVAC Equipment
Europe Air Conditioning Equipment Market
HVAC Equipment
Automatic Ducting Machine Market
HVAC Equipment
Air-Cooled Heat Exchangers Market
HVAC Equipment
Hydronic Radiators Market