
 Asia-Pacific Compressor Market | 2026-2036
Asia-Pacific Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Compressor Market Outlook
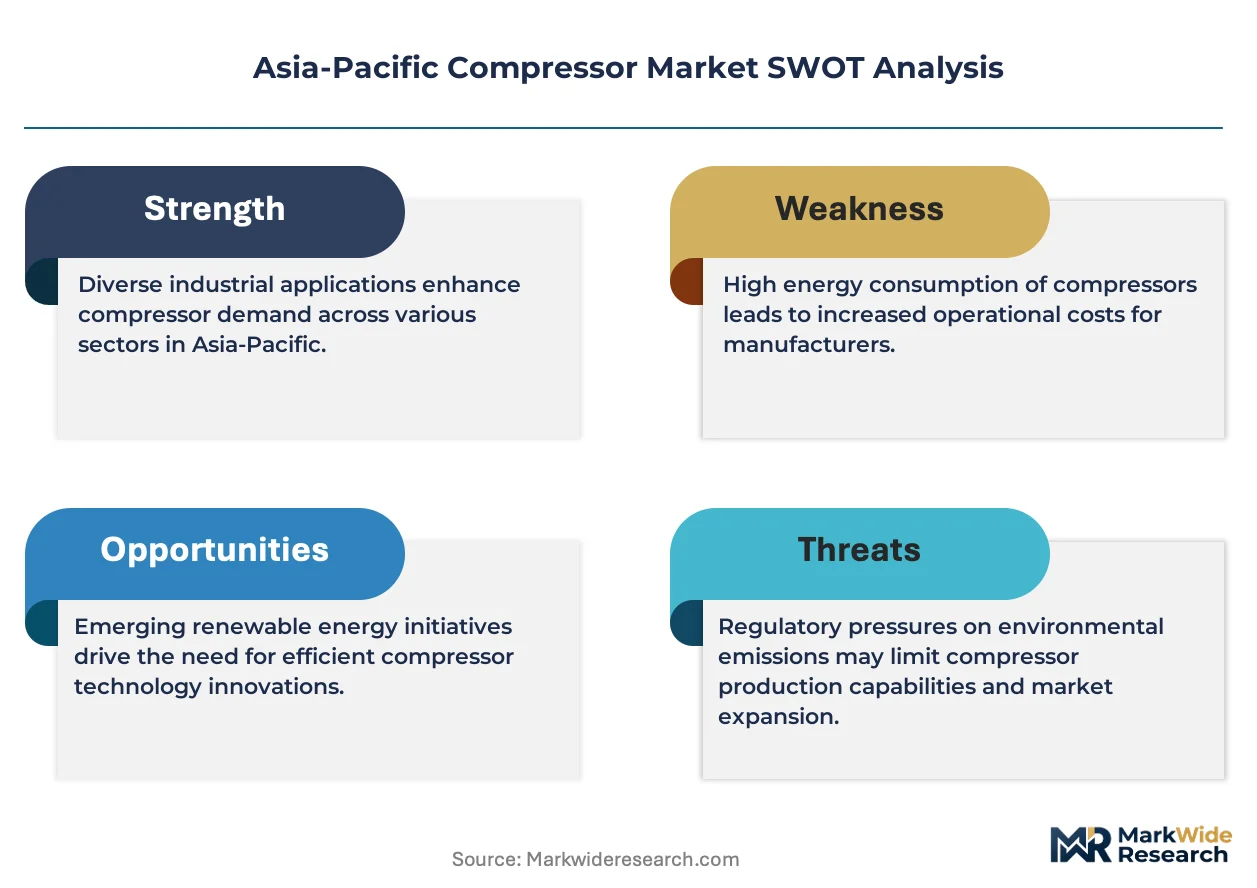
Data center operators and hydrogen electrolyzer developers is bifurcating the traditional buyer base that once centered on general manufacturing. Atlas Copco AB leverages its oil-free compressor portfolio to anchor positions in semiconductor cleanrooms across South Korea and Taiwan. ELGi Equipments Limited competes aggressively on aftermarket service density in India's tier-two industrial clusters. Mitsubishi Heavy Industries Ltd dominates large-frame centrifugal installations for LNG receiving terminals in Japan and Australia.
A compressor is a mechanical device that increases the pressure of a gas by reducing its volume, typically achieving discharge pressures from 100 psi to over 5,000 psi depending on stage configuration and driver power. Rotary screw compressors deliver continuous airflow with minimal pulsation, making them the default choice for automated manufacturing lines requiring steady pneumatic power. Reciprocating units retain structural importance in high-pressure applications such as CNG fueling and petrochemical injection, though their maintenance intensity constrains margin expansion. Oil-free technology commands premium positioning in food processing and pharmaceutical sectors where compressed air purity directly determines product certification eligibility.
Japan's METI enforces Top Runner efficiency standards that compel compressor OEMs to redesign motor-drive systems every three to four cycles. Australia's WHS regulations mandate pressure vessel inspection intervals that shape aftermarket service contracts and replacement timelines. China's GB 19153 standard for air compressor energy efficiency creates non-tariff barriers for imported units failing to meet revised specific power thresholds. Stakeholders must monitor how India's BIS certification timeline for oil-free compressor classes affects market entry sequencing for European and Japanese suppliers.
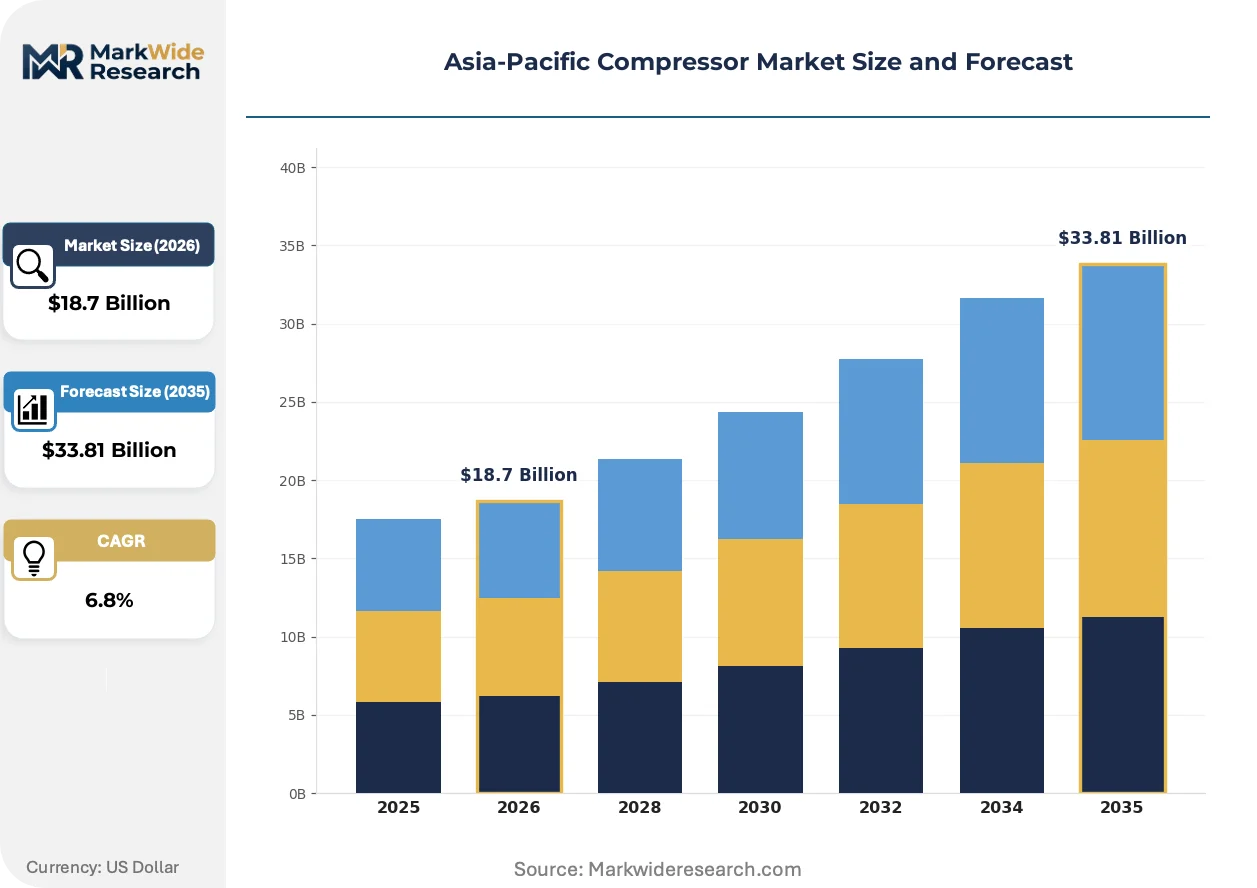
Market Dynamics
China's GB 19153 energy-efficiency standards are compressing margins for imported rotary screw units while accelerating domestic OEM redesign cycles across the Asia-Pacific compressor landscape.
Growth Catalysts
- Cold chain fleet expansion:Southeast Asian logistics operators are procuring refrigerated transport compressors at accelerated rates to serve temperature-sensitive pharmaceutical and fresh produce corridors linking Bangkok, Ho Chi Minh City, and Jakarta.
- GB standard tightening:China's revised specific power thresholds for air compressors are forcing technology upgrades that favor variable-speed drive integration and premium motor efficiencies.
- Oil-free deployment:Sterile processing lines in India's pharmaceutical manufacturing clusters around Hyderabad and Ahmedabad are mandating oil-free compressor installations for FDA-aligned certification eligibility.
Market Restraints
- Permanent magnet cost volatility:Rare earth price swings for neodymium and dysprosium are destabilizing variable-speed motor economics for mid-range rotary screw units.
- Import dependency for precision components:High-speed bearing assemblies and advanced coating systems concentrate supply among Japanese and German specialty manufacturers.
- Reciprocating maintenance intensity:Valve wear and ring replacement cycles in high-pressure CNG applications constrain total cost of ownership improvements versus rotary alternatives.
Strategic Opportunities
- Vietnam manufacturing emergence:Electronics assembly and textile processing growth in Bac Ninh and Dong Nai provinces is creating first-time compressor demand outside traditional China-India-Japan concentration.
- Hydrogen electrolyzer integration:Large-frame centrifugal and diaphragm compressor configurations for 700-bar hydrogen fueling are opening new specification conversations with energy infrastructure developers.
- PLI scheme alignment:India's production-linked incentive schemes for white goods and pharmaceuticals are indirectly subsidizing compressor procurement for qualifying facility expansions.
Industry Challenges
- Variable-speed control expertise gap:Tier-two industrial clusters lack technicians trained in drive parameter optimization and predictive vibration monitoring.
- BIS certification timeline uncertainty:India's Bureau of Indian Standards approval delays for oil-free compressor classes are disrupting European and Japanese supplier entry sequencing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Compressor Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reciprocating, Rotary Screw, Centrifugal, Diaphragm End User: Manufacturing, Oil & Gas, Energy, Food & Beverage Technology: Variable Speed Drive, Fixed Speed, Oil-Free, Portable Application: Aerospace, Automotive, HVAC, Chemical Processing |
| Companies Covered | Siemens AG, Kaeser Kompressoren SE, Atlas Copco AB, Gardner Denver Holdings Inc., ELGi Equipments Limited, Ingersoll Rand Inc., Hitachi Industrial Equipment Systems Co Ltd, Fusheng Group, Mitsubishi Heavy Industries Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Compressor Market Strategic Shifts
Digital compressor monitoring and hydrogen-ready pressure ratings are redefining equipment specification criteria across Asia-Pacific procurement departments.
Magnetic bearing centrifugal technology is displacing conventional oil-lubricated bearing systems in large-frame installations. Japanese LNG receiving terminals and Australian petrochemical complexes are specifying magnetic bearing packages for their maintenance elimination and efficiency gains. This displacement is compressing the addressable market for traditional centrifugal service contracts and lube oil system suppliers.
METI's Top Runner efficiency standards compel compressor OEMs to redesign motor-drive systems every three to four cycles. The industrial consequence is accelerated R&D amortization pressure and shortened product generation lifespans. Large-frame centrifugal and oil-free rotary segments face the steepest redesign cost absorption in Japan's domestic market.
Service contract unbundling is fragmenting traditional aftermarket relationships. Indian pharmaceutical and South Korean semiconductor buyers are separating preventive maintenance, spare parts procurement, and remote monitoring into discrete vendor relationships. This pattern is most visible in Hyderabad's sterile processing corridors and Hsinchu's fab clusters, where multi-vendor service architectures reduce single-source dependency risks.
Asia-Pacific Compressor Market Segmentation
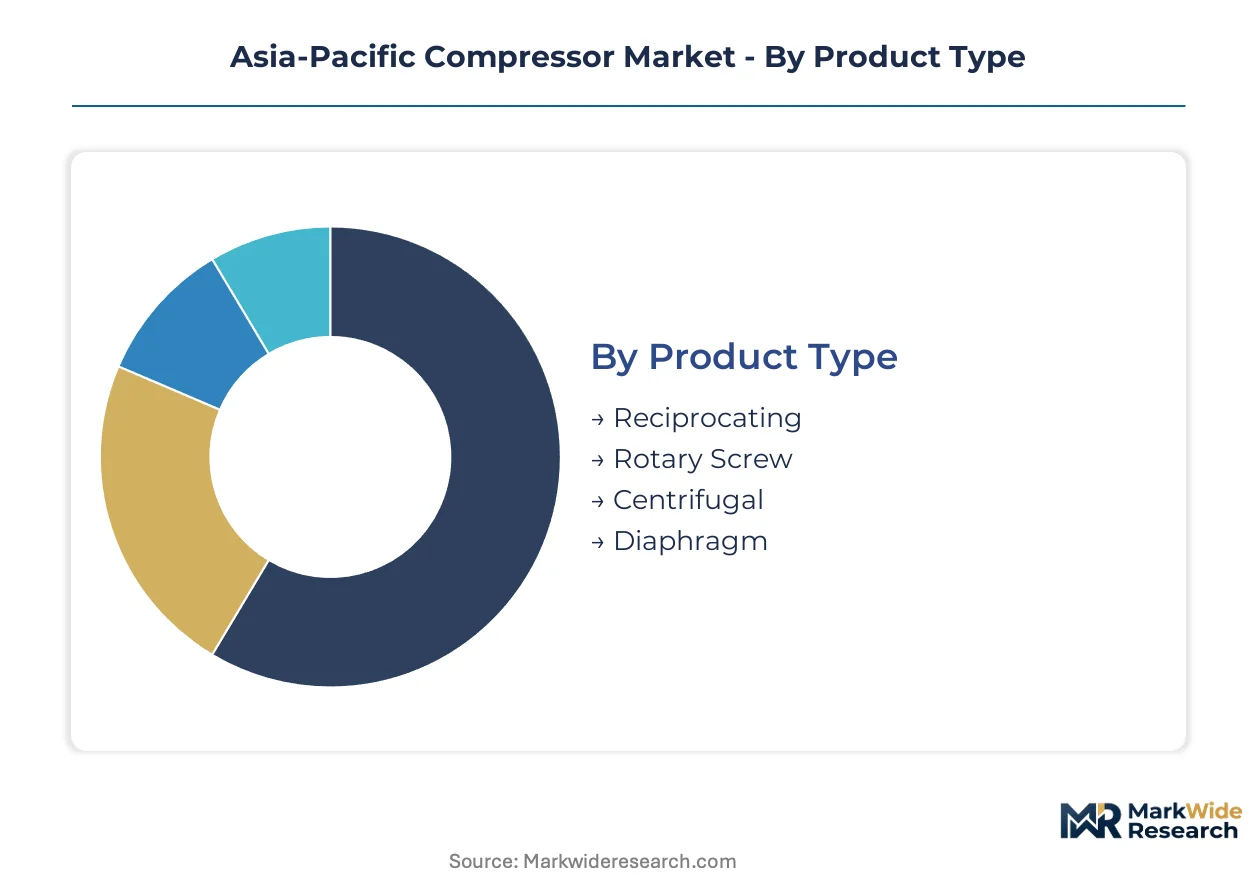
Compressor procurement patterns across Asia-Pacific diverge sharply by end-use purity requirements and energy-efficiency mandates. Understanding how product specifications map to channel strategies enables suppliers to align R&D cycles with regulatory deadlines in China, Japan, and India.
Product Type:
Rotary screw and centrifugal units dominate direct OEM sales to large industrial accounts, while reciprocating compressors flow through distributor networks serving CNG fueling and maintenance-intensive applications.
- Reciprocating:Piston-driven compression achieves discharge pressures exceeding 5,000 psi through multi-stage configurations. Valve wear and ring replacement cycles constrain total cost of ownership improvements in high-pressure CNG fueling stations across India and Thailand.
- Rotary Screw:Continuous airflow delivery with minimal pulsation suits automated manufacturing lines requiring steady pneumatic power. China's GB 19153 energy-efficiency standards are compressing margins for imported units while accelerating domestic OEM redesign cycles.
- Centrifugal:Large-frame installations for LNG receiving terminals in Japan and Australia specify magnetic bearing packages for maintenance elimination.
- Diaphragm:Hermetically sealed compression chambers handle toxic or ultra-pure gases in hydrogen electrolyzer and pharmaceutical applications.
By volume, rotary screw leads. By growth pace, centrifugal is gaining share fastest.
End User:
Cost tier segmentation separates premium oil-free specifications for pharmaceutical and semiconductor cleanrooms from standard lubricated units serving general manufacturing.
- Manufacturing:Automated assembly lines and robotic welding operations in Vietnam's Bac Ninh electronics corridor and India's tier-two industrial clusters generate steady demand for 100-150 psi rotary screw configurations.
- Oil & Gas:Upstream injection services and downstream refining operations in Australia's Northwest Shelf and Malaysia's Bintulu complex require high-pressure reciprocating and centrifugal packages.
- Energy:Hydrogen electrolyzer developers in Japan and South Korea are specifying 700-bar diaphragm compressor configurations for fueling infrastructure.
- Food & Beverage:Cold chain logistics operators across Southeast Asia are expanding refrigerated transport compressor procurement for temperature-sensitive pharmaceutical and fresh produce corridors.
Manufacturing commands the largest installed base. Energy applications are expanding most quickly.
Technology:
Application requirements determine technology selection, with sterile processing mandating oil-free and energy-conscious buyers prioritizing variable-speed drive integration.
- Variable Speed Drive:Motor speed modulation matches compressed air output to fluctuating demand profiles, cutting energy consumption in intermittent-load environments. Rare earth price volatility for neodymium and dysprosium is destabilizing motor economics for mid-range rotary screw units.
- Fixed Speed:Constant-speed operation suits baseload industrial applications with stable air demand patterns and limited operating hours.
- Oil-Free:Elimination of lubricant contact with compressed air stream enables FDA-aligned certification eligibility for sterile processing lines in Hyderabad and Ahmedabad pharmaceutical corridors.
- Portable:Trailer-mounted diesel or electric drive packages serve construction sites and emergency backup applications across remote Indonesian and Philippine project locations.
Fixed speed retains volume leadership. Oil-free technology is climbing the fastest.
Application:
Geography shapes application concentration, with semiconductor cleanrooms clustering in Taiwan and South Korea while chemical processing anchors in Singapore and Thailand.
- Aerospace:Precision air supply for composite autoclave curing and component testing in Japan's Nagoya aerospace manufacturing hub demands ultra-dry, oil-free compressed air.
- Automotive:Paint shop operations and stamping press automation in Thailand's Rayong province and India's Chennai corridor require high-volume, continuous-duty rotary screw installations.
- HVAC:Chiller compressor replacement cycles in Australia's commercial building stock and Singapore's data center cooling infrastructure drive aftermarket service contract volumes.
- Chemical Processing:Corrosive gas handling and high-purity process air in Singapore's Jurong Island petrochemical complex specify specialized metallurgy and coating systems.
HVAC represents the largest replacement market. Chemical processing shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compressor manufacturing concentrates in China, Japan, and South Korea, with assembly and component fabrication scaling across Southeast Asian industrial zones to serve localized demand and export markets. This supply-side clustering shapes procurement patterns, service network density, and technology transfer flows across the region.
China
GB 19153 energy-efficiency standards are forcing technology upgrades across rotary screw and centrifugal product lines, compressing margins for imported units while accelerating domestic OEM redesign cycles. MIIT enforcement timelines create non-tariff barriers for foreign suppliers failing revised specific power thresholds. Manufacturing clusters in Jiangsu and Zhejiang provinces are expanding variable-speed drive integration capacity to meet these mandates.
Japan
METI's Top Runner efficiency standards compel compressor OEMs to redesign motor-drive systems every three to four cycles, accelerating R&D amortization pressure. Large-frame centrifugal installations for LNG receiving terminals specify magnetic bearing packages for maintenance elimination. Kanto and Chubu industrial corridors anchor domestic demand from precision manufacturing and petrochemical processing facilities.
India
PLI schemes for white goods and pharmaceuticals indirectly subsidize compressor procurement for qualifying facility expansions in Hyderabad and Ahmedabad corridors. BIS certification timeline uncertainty for oil-free compressor classes disrupts European and Japanese supplier entry sequencing. Tier-two industrial clusters around Pune and Chennai generate aftermarket service density competition.
South Korea
Semiconductor cleanroom specifications drive oil-free compressor deployment in Hsinchu-adjacent fab clusters, with METI-aligned efficiency standards influencing procurement criteria. Hydrogen electrolyzer developers are specifying 700-bar diaphragm configurations for fueling infrastructure projects. Busan-Ulsan industrial zones concentrate demand from shipbuilding and petrochemical downstream operations.
Australia
WHS regulations mandate pressure vessel inspection intervals that shape aftermarket service contracts and replacement timelines across mining and LNG processing facilities. Magnetic bearing centrifugal packages are displacing conventional oil-lubricated systems in Northwest Shelf upstream operations. Queensland and Western Australia resource corridors anchor large-frame installation demand.
Asia-Pacific Compressor Market Competitive Environment
Concentration sits with diversified industrial conglomerates and specialized compressor OEMs competing across technology tiers. The market structure shows moderate consolidation at the premium oil-free and large-frame centrifugal segments, with fragmentation in standard rotary screw and reciprocating categories serving price-sensitive industrial accounts. Two strategic archetypes dominate: integrated industrial equipment suppliers leveraging cross-selling synergies, and focused compressor specialists competing on aftermarket service density. Competitive moves center on magnetic bearing technology licensing partnerships and geographic expansion into Vietnam's emerging manufacturing zones.
Among European-based industrial conglomerates, Siemens AG and Atlas Copco AB exemplify the integrated equipment supplier archetype, occupying positions that span multiple compressor technology categories. ELGi Equipments Limited represents the focused specialist model, anchoring competitive intensity in India's tier-two industrial service markets. These three companies illustrate the geographic and strategic bifurcation shaping procurement conversations across the region.
| Leading Market Players |
|---|
| Siemens AG |
| Kaeser Kompressoren SE |
| Atlas Copco AB |
| Gardner Denver Holdings Inc. |
| ELGi Equipments Limited |
| Ingersoll Rand Inc. |
| Hitachi Industrial Equipment Systems Co Ltd |
| Fusheng Group |
| Mitsubishi Heavy Industries Ltd |
| Others |
Value Chain & Pricing Dynamics
Forty-five to sixty-day lead times for high-speed bearing assemblies from Japanese and German specialty manufacturers concentrate pricing power with tier-one OEMs serving semiconductor cleanrooms and LNG terminals. This inventory compression amplifies cost pass-through capacity for magnetic bearing centrifugal packages while squeezing margin recovery for mid-range rotary screw configurations dependent on rare earth supply.
Pricing Analysis
China's GB 19153 energy-efficiency standards dictate the pricing tier structure across rotary screw and centrifugal categories. Three-tier pricing structure across premium, standard, and economy levels separates magnetic bearing centrifugal units for LNG terminals from variable-speed rotary screw for manufacturing and fixed-speed economy tiers for intermittent-use applications. Price differentiation rests on certification grade alignment with METI Top Runner thresholds and after-sales service bundling density. Cost compression in imported rotary screw tiers is intensifying because domestic OEM redesign cycles compress technology premiums. Tier-two industrial clusters in Vietnam and Indonesia exhibit highest price sensitivity; semiconductor cleanroom buyers in South Korea and Taiwan show least.
Supply Chain Analysis
Port congestion on Shanghai-Ningbo and Busan-Osaka trade lanes is extending inbound logistics cycles for precision coating systems and advanced motor-drive components. Manufacturing concentrates in China, Japan, and South Korea, with component fabrication scaling across Vietnam and Thailand to serve localized demand. Raw material dependencies center on neodymium and dysprosium for permanent magnet motors, high-grade steel alloys for pressure vessels, and specialty coatings for corrosive gas handling. Single-source vulnerability sits with Japanese and German suppliers of high-speed bearing assemblies. Distribution runs through direct OEM sales for large industrial accounts and distributor networks serving CNG fueling and maintenance-intensive reciprocating applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service contract unbundling in India's pharmaceutical corridors and South Korea's semiconductor clusters is expanding aftermarket revenue pools faster than hardware shipment growth. This service-attach acceleration redefines competitive positioning around remote monitoring density and spare parts logistics rather than unit shipment scale alone.
For Market Incumbents: Compound aftermarket service density in India's tier-two industrial clusters around Pune and Chennai before emerging competitors anchor preventive maintenance relationships. Magnetic bearing technology licensing partnerships with Japanese LNG terminal operators defend premium centrifugal positioning against domestic OEM cost aggression. Capacity addition in Vietnam's Bac Ninh and Dong Nai provinces captures first-time demand from electronics assembly expansion.
For New Entrants and Emerging Players: Lead with oil-free compressor deployments targeting Hyderabad and Ahmedabad pharmaceutical corridors where BIS certification delays disrupt European and Japanese supplier entry sequencing. Hydrogen electrolyzer integration for 700-bar diaphragm configurations in Japan and South Korea represents the most penetrable specification conversation. Go-to-market through energy infrastructure developers rather than traditional industrial procurement channels.
For Investors and Strategic Acquirers: Long-term, this sits as a service-arbitrage play because unbundled maintenance contracts and predictive monitoring subscriptions generate recurring revenue streams with lower capital intensity than manufacturing. Acquisition targets include aftermarket service specialists with dense technician networks in tier-two Indian industrial clusters and remote monitoring platform providers. Watch hydrogen fueling infrastructure deployment rates as the inflection signal for large-frame centrifugal and diaphragm compressor demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Magnetic Bearing Technology Licensing | Eliminates lube oil system maintenance for Japanese LNG terminal operators. |
| Variable-Speed Drive Integration | Aligns rotary screw portfolios with China's GB 19153 specific power thresholds. |
| Aftermarket Service Density Expansion | Captures unbundled maintenance contracts in India's pharmaceutical corridors. |
| Hydrogen-Ready Pressure Rating Development | Opens specification conversations with South Korean electrolyzer developers. |
| Vietnam Manufacturing Footprint Establishment | Serves first-time compressor demand from Bac Ninh electronics assembly growth. |
Study Parameters
Desk research of customs trade data, MIIT enforcement bulletins, and METI efficiency standard filings preceded structured interviews with plant engineers, aftermarket service heads, and OEM procurement teams across China, Japan, India, and South Korea. Primary fieldwork with maintenance directors at semiconductor cleanrooms and LNG terminal operators validated secondary estimates of technology substitution rates and service contract pricing. Bottom-up unit shipment analysis triangulated against top-down energy-efficiency mandate impact modeling.
Variance decomposition across product type, technology tier, end-use purity requirements, and geographic regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macro industrial production indices and energy infrastructure investment flows. Forecast inputs incorporated hydrogen electrolyzer deployment pipelines, PLI scheme facility expansion schedules, and cold chain fleet procurement timelines.
The analysis sits within stated boundaries; outcomes outside sustained rare earth price stability, BIS certification timeline resolution, or METI redesign cycle continuity would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology substitution elasticities. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Reciprocating Chiller Market
HVAC Equipment
Canada HVAC Equipment Market
HVAC Equipment
United Kingdom District Heating Market
HVAC Equipment
Industrial Electric Boiler Market
HVAC Equipment
Global Heat Exchangers Market
HVAC Equipment
North America Commercial Heating, Ventilation, and Air Conditioning (HVAC) Equipment Market
HVAC Equipment
Industrial Air Heaters Market
HVAC Equipment
Air Conditioning Systems Market
HVAC Equipment
Global Air Duct Market
HVAC Equipment
Air-Conditioning Natural Convection Refrigerator Market
HVAC Equipment
Equipment for HVAC Market
HVAC Equipment
Wall Hung Boilers Market
HVAC Equipment
Italy Commercial HVAC Market
HVAC Equipment
Steam Humidifiers Market
HVAC Equipment
China HVAC Market
HVAC Equipment
Japan Commercial HVAC Market