
 Commercial Water Heater Market | 2026-2036
Commercial Water Heater Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Water Heater Market Analysis
The EU Green Deal's building decarbonization targets is consolidating demand around high-efficiency heat pump and condensing technologies across European commercial real estate. A.O. Smith leverages its North American manufacturing footprint to dominate replacement cycles in the hospitality and healthcare verticals. Rheem Manufacturing competes through sustained R&D intensity in tankless gas and hybrid electric platforms. Bradford White Corporation anchors its position with specialized distribution control through the professional plumbing channel.
Commercial water heaters are pressurized thermal storage or on-demand systems engineered to deliver potable hot water at temperatures typically ranging from 49°C to 82°C for non-residential buildings. These units employ steel or glass-lined tanks, copper heat exchangers, or refrigerant-based thermal pumps to serve continuous draw profiles in food service, lodging, and institutional settings. Tankless water heaters command premium positioning in urban retrofit applications where mechanical room space constraints limit storage capacity. Heat pump water heaters represent the fastest-expanding fuel-type category as electrification mandates reshape new construction specifications. Natural gas storage systems retain volume leadership across existing building stock but face margin compression from carbon pricing mechanisms in multiple jurisdictions.
The US Department of Energy appliance efficiency standards, EU Ecodesign and Energy Labelling frameworks, and Japan's Top Runner program collectively dictate minimum performance thresholds and testing protocols for commercial water heating equipment. Compliance with these regimes determines market access eligibility and shapes manufacturer product development roadmaps across export markets. Stakeholders must monitor evolving refrigerant phase-down schedules under the Kigali Amendment and corresponding heat pump redesign cycles that will reshape supplier qualification requirements.
Market Dynamics
The US Department of Energy's 2023 efficiency standards for commercial water heating equipment are compressing replacement cycles and disqualifying legacy atmospheric gas storage models from new installations across federal buildings and healthcare facilities.
Growth Catalysts
- EU Ecodesign Directive:Mandates 91% minimum thermal efficiency for large commercial water heaters, forcing hospitality and healthcare operators in Germany, France, and Italy into accelerated equipment turnover.
- Heat pump technology maturation:CO2 refrigerant systems now deliver 65°C output at sub-zero ambient temperatures, opening Nordic and Alpine markets previously closed to electrification.
- Japan's building stock renovation wave:Tokyo's 2025 non-residential energy efficiency targets are driving condensing gas and hybrid electric replacements in ryokan and restaurant sectors.
Market Restraints
- Copper and nickel price volatility:Heat exchanger material costs fluctuate with Chilean and Indonesian mining output, compressing margins on condensing and tankless platforms.
- Refrigerant supply concentration:R-410A and R-32 production clusters in Chinese chemical manufacturing create vulnerability for heat pump water heater assembly lines in North America and Europe.
- Electrical infrastructure inadequacy:Many US commercial buildings constructed before 1990 lack 480V three-phase service required for high-capacity heat pump installations, limiting electrification in secondary markets.
Strategic Opportunities
- India's commercial real estate expansion:IT park and hospital construction in Bangalore, Hyderabad, and Pune creates first-mover positioning for heat pump and solar-thermal hybrid suppliers.
- US Inflation Reduction Act commercial credits:Section 179D deductions and 48C manufacturing incentives reduce effective cost barriers for heat pump water heater adoption in new construction.
- IoT-enabled predictive maintenance:Sensor-integrated units allowing remote diagnostics and failure prediction are commanding premium positioning in US hospitality chains with distributed property portfolios.
Industry Challenges
- Refrigerant handling certification gaps:EPA Section 608 technician shortages in the United States delay heat pump commissioning and inflate service costs for commercial installations.
- Legacy control system integration:BACnet and Modbus protocol mismatches between new high-efficiency units and existing building management systems in European commercial stock extend project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Water Heater Market |
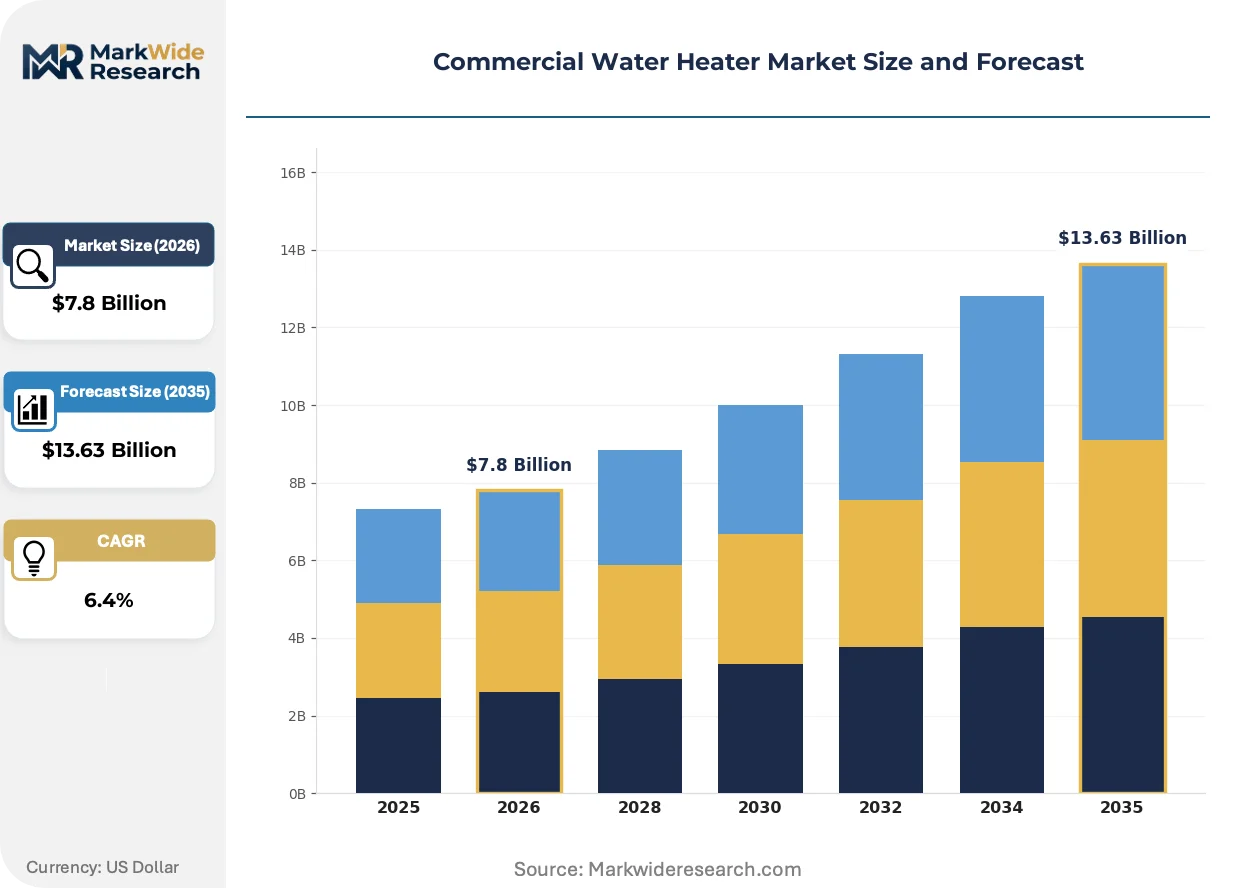
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Storage Water Heaters, Tankless Water Heaters, Heat Pump Water Heaters, Solar Water Heaters Fuel Type: Electric, Natural Gas, Diesel, Propane Application: Hospitality, Healthcare, Educational Institutions, Industrial Installation Type: Indoor, Outdoor, Wall-Mounted, Floor-Mounted |
| Companies Covered | A.O. Smith, Rheem Manufacturing, Bradford White Corporation, Rinnai Corporation, Bosch Thermotechnology, Ariston Thermo, Noritz Corporation, Midea Group, NIBE Industrier AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Water Heater Market Emerging Trajectories
Electrification mandates and refrigerant phase-down schedules are forcing simultaneous redesign of thermal generation hardware and control architectures. Manufacturers must navigate converging pressures from efficiency standards, grid integration requirements, and service model transformation.
CO2 transcritical heat pump water heaters are converging with smart grid demand-response protocols to enable thermal storage arbitrage in markets with time-of-use electricity pricing. Large hotel chains in California and Germany are piloting systems that pre-heat storage tanks during off-peak hours. This convergence is compressing the payback period differential between heat pump and gas-fired alternatives in high-labor-cost jurisdictions.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is forcing heat pump manufacturers to redesign systems around natural working fluids by 2027. Equipment redesign cycles now synchronize with refrigerant availability curves rather than standalone product roadmaps. Commercial heat pump water heater portfolios in Europe are consolidating around CO2 and propane architectures ahead of regulatory deadlines.
Food service operators are unbundling equipment purchase from lifecycle service, preferring performance-based contracts that guarantee hot water availability per seat or per room. Third-party energy service companies are capturing decision-making authority previously held by mechanical contractors. This shift is most advanced in US quick-service restaurant chains and UK care home portfolios, where capital constraints favor operational expenditure models.
Commercial Water Heater Market Segmentation
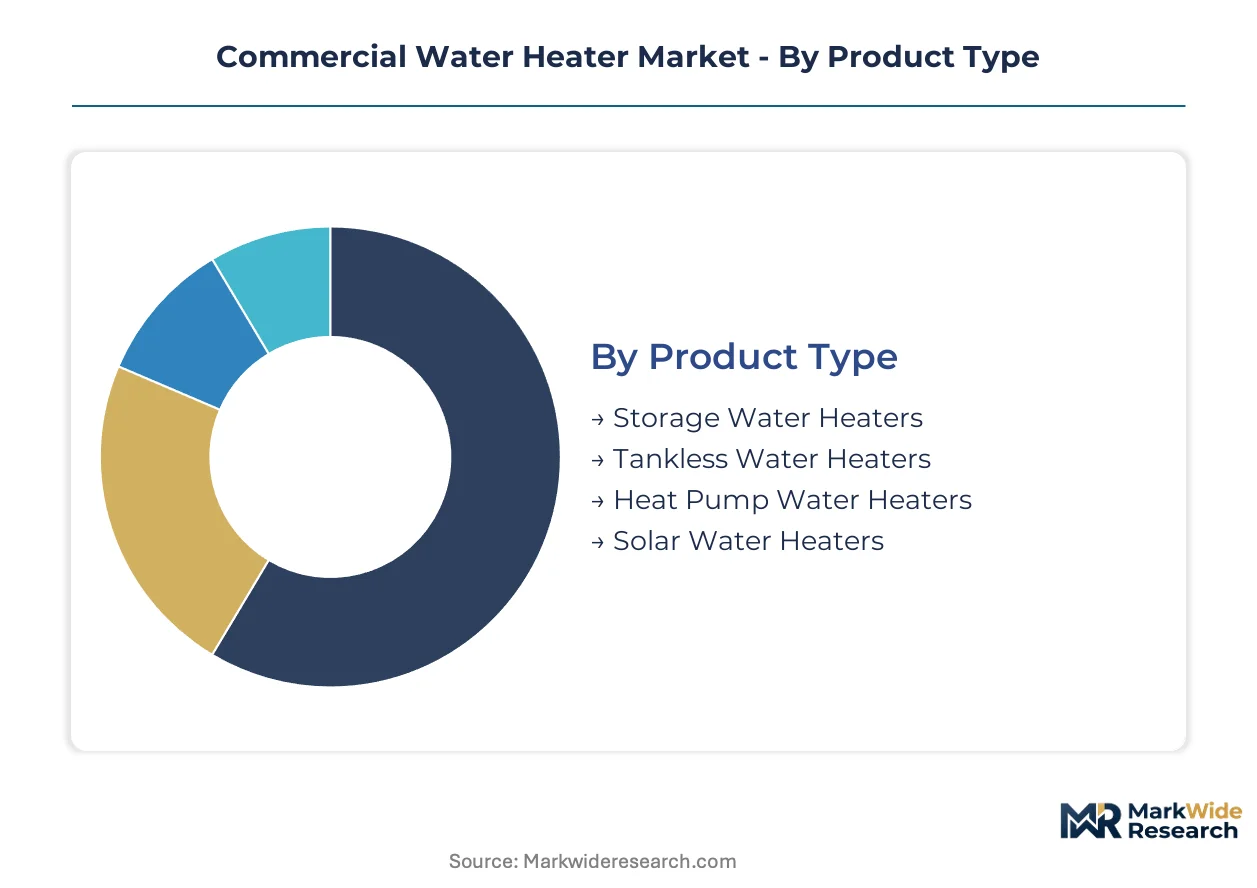
Commercial water heater procurement decisions split across thermal performance requirements, fuel availability constraints, and mechanical room specifications. Equipment selection varies sharply between new construction projects with electrification mandates and legacy buildings undergoing replacement cycles.
Product Type:
Storage systems dominate unit volumes while heat pump platforms command premium positioning and fastest share gains.
- Storage Water Heaters:Pressurized steel or glass-lined tanks ranging from 80 to 2,500 gallons maintain thermal reservoirs for high-peak-demand environments. Hospitality operators in the United States and Germany specify these for banquet halls and full-service hotels where simultaneous draw events exceed instantaneous capacity. The segment retains volume leadership across existing building stock but faces margin pressure from efficiency mandates.
- Heat Pump Water Heaters:Refrigerant-based systems extract ambient thermal energy to achieve coefficients of performance exceeding 3.0. California and Germany's new construction codes are accelerating specification of CO2 transcritical units for food service and lodging applications. These systems represent the steepest expansion trajectory as electrification deadlines approach in multiple jurisdictions.
- Tankless Water Heaters:On-demand gas or electric units with copper heat exchangers deliver continuous flow without storage losses. Urban retrofit projects in Japan and the United Kingdom favor these where mechanical room space is constrained.
- Solar Water Heaters:Evacuated tube or flat-plate collectors with electric or gas backup handle pre-heating loads in regions with high insolation. Australia's commercial sector and India's hospital construction pipeline show concentrated uptake.
Today's leader: Storage Water Heaters. Tomorrow's challenger: Heat Pump Water Heaters.
Fuel Type:
Electrification policies are reordering historic fuel hierarchies faster than equipment replacement cycles can accommodate.
- Electric:Resistance and heat pump configurations serve markets with low natural gas penetration or aggressive decarbonization targets. France's commercial sector and Japan's ryokan operators are shifting specifications toward electric platforms as grid carbon intensity declines.
- Natural Gas:Condensing and atmospheric storage systems remain the default for high-volume applications in gas-connected geographies. The fuel type faces regulatory compression from carbon pricing in Germany and the United Kingdom.
- Diesel:Standalone or backup-fired units serve remote industrial sites and emergency applications where grid reliability is insufficient. Mining operations in Australia and construction camps in Canada represent concentrated demand pockets.
- Propane:Liquefied petroleum gas systems fill gaps in rural commercial construction lacking natural gas infrastructure. Hospitality development in the United States Mountain West and agricultural processing in Brazil specify propane where pipeline extension is uneconomical.
Natural Gas still anchors installed base value. Electric platforms are climbing the fastest as building codes tighten.
Application:
End-use thermal profiles dictate capacity sizing, redundancy requirements, and maintenance scheduling intensity.
- Hospitality:Hotels and restaurants require 24/7 hot water availability with peak morning and evening draw profiles. German hotel chains and United States quick-service operators are consolidating procurement around performance-based service contracts rather than equipment ownership.
- Healthcare:Hospitals and long-term care facilities demand infection-control-grade temperatures and redundant system architecture. Japan's aging care home construction wave and United Kingdom NHS estate renovation are driving condensing gas and heat pump replacements.
- Educational Institutions:Universities and K-12 campuses face concentrated demand during term periods with extended low-load intervals. California's community college electrification mandates and India's IIT campus expansion are reshaping specifications.
- Industrial:Manufacturing and process applications require high-temperature delivery beyond standard potable ranges. Food processing in Germany and pharmaceutical manufacturing in Switzerland specify customized heat exchanger configurations.
Hospitality generates the densest replacement pipeline. Healthcare commands the strictest compliance overlay.
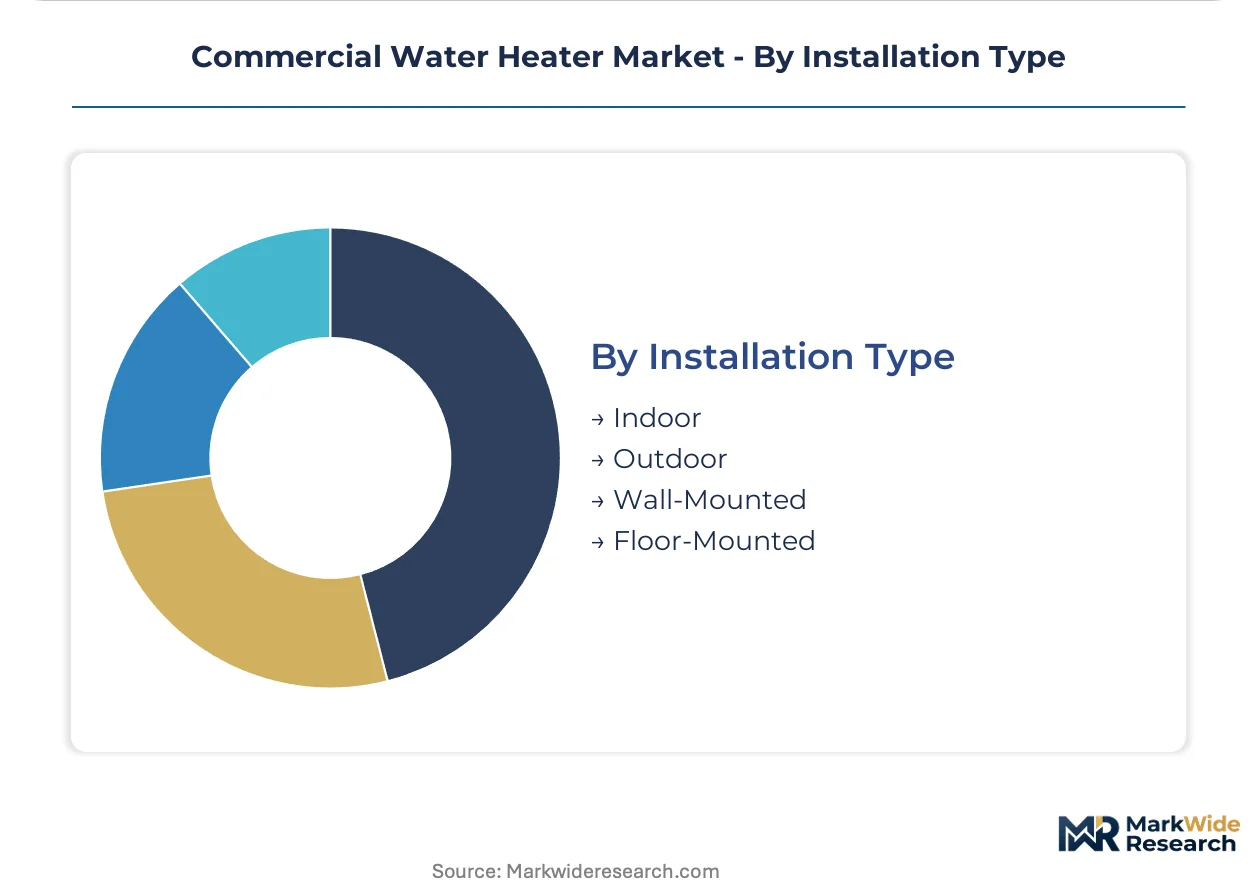
Installation Type:
Mechanical room constraints and climate exposure determine housing specifications and ventilation requirements.
- Indoor:Basement or dedicated mechanical room placement protects equipment from temperature extremes and permits direct venting. This configuration dominates northern European and North American commercial stock where freeze protection is mandatory.
- Outdoor:Weatherized enclosures with insulated piping serve markets with mild climates or severe space constraints. Australia's commercial sector and the United States Sun Belt favor outdoor placement to preserve interior square footage.
- Wall-Mounted:Vertical tankless or compact storage units attach to structural walls in high-density urban environments. Tokyo's restaurant sector and London's hotel retrofit market specify these where floor loading is restricted.
- Floor-Mounted:Large-capacity storage and heat pump systems require concrete pads or reinforced framing. Industrial laundries in Germany and hospital central plants in the United States default to this configuration.
Indoor installation retains specification dominance. Wall-mounted designs are gaining fastest in urban densification corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled plumbing and HVAC technician concentrations in Germany, Japan, and the United States anchor the three largest commercial water heater installation bases worldwide. These workforces enable rapid equipment turnover as efficiency mandates compress replacement cycles. Regional demand patterns diverge sharply between electrification-forward jurisdictions and markets retaining gas infrastructure.
United States
Federal building renovation programs and hospitality sector recovery are accelerating condensing gas and heat pump replacements in Chicago, Dallas, and Atlanta metro areas. The US Department of Energy's 2023 efficiency standards disqualify atmospheric gas storage models from federal healthcare and lodging facilities. Los Angeles and New York commercial real estate operators face simultaneous pressure from local building decarbonization ordinances and IRA tax credit eligibility windows.
Germany
EU Ecodesign Directive mandates and carbon pricing under the national emissions trading scheme are forcing hotel and hospital operators in Munich, Frankfurt, and Hamburg into accelerated heat pump and condensing gas upgrades. The country's building energy efficiency regulations now require 91% minimum thermal efficiency for large commercial water heating equipment. Bavaria's manufacturing belt and North Rhine-Westphalia's healthcare corridor generate concentrated demand for CO2 transcritical heat pump systems.
Japan
Tokyo's 2025 non-residential energy efficiency targets and METI's Top Runner program are driving condensing gas and hybrid electric replacements across the ryokan and restaurant sectors. Osaka and Nagoya commercial districts face compressed mechanical room footprints that favor tankless and wall-mounted configurations. The country's aging building stock renovation wave concentrates in Kanto and Kansai metropolitan corridors where electrification deadlines approach fastest.
India
IT park and hospital construction in Bangalore, Hyderabad, and Pune is creating first-mover positioning opportunities for heat pump and solar-thermal hybrid suppliers. The Bureau of Energy Efficiency's commercial building codes are tightening performance requirements for new construction in Tier-1 cities. Maharashtra and Karnataka state-level incentives for green building certification are reshaping procurement specifications in Mumbai and Bengaluru commercial developments.
Australia
Commercial solar-thermal pre-heating systems and heat pump specifications are gaining traction in Sydney, Melbourne, and Brisbane food service and lodging applications. The country's National Construction Code updates are elevating minimum efficiency thresholds for non-residential water heating equipment. Queensland and Western Australia mining camp and remote industrial sites sustain diesel and propane backup system demand outside major urban corridors.
Commercial Water Heater Market Vendor Landscape
Capital-heavy producers with integrated manufacturing footprints compete with asset-light designers relying on contract assembly and private-label distribution. The market structure tilts toward consolidation among full-line HVAC conglomerates, with mid-tier specialists defending position through regional distribution control and application-specific engineering. Three archetypes dominate: integrated thermal systems conglomerates with broad fuel-type coverage, regional specialists with plumber-channel capture, and Asian-scale manufacturers competing on cost-engineered platforms. Competitive moves center on refrigerant transition timing alignment and performance-based service contract expansion into hospitality chains.
Among North American integrated manufacturers, A.O. Smith Corporation, Rheem Manufacturing Company, and Bradford White Corporation exemplify the conglomerate archetype with full fuel-type portfolios and established specification relationships. A.O. Smith leverages its Milwaukee-based manufacturing footprint to dominate replacement cycles in hospitality and healthcare verticals. Rheem occupies a position emphasizing sustained R&D intensity in tankless gas and hybrid electric platforms. Bradford White anchors its competitive stance through specialized distribution control via the professional plumbing channel rather than retail presence. Japanese precision engineering specialists Rinnai Corporation and Noritz Corporation represent the tankless-specialist archetype, while European thermal systems players Bosch Thermotechnology and Ariston Thermo exemplify heat pump-forward positioning aligned with EU decarbonization trajectories.
| Leading Market Players |
|---|
| A.O. Smith |
| Rheem Manufacturing |
| Bradford White Corporation |
| Rinnai Corporation |
| Bosch Thermotechnology |
| Ariston Thermo |
| Noritz Corporation |
| Midea Group |
| NIBE Industrier AB |
| Others |
Supply Flow & Price Mechanics
Copper heat exchanger and refrigerant compressor costs cascade through three distinct pricing tiers as OEMs absorb upstream volatility or pass through to hospitality and healthcare operators. Equipment manufacturers in the United States and Germany face divergent margin pressures depending on whether they source CO2 transcritical components from Japanese suppliers or maintain captive assembly lines.
Pricing Analysis
The bundled-vs-unbundled service split now defines pricing architecture across commercial water heater procurement. Three-tier pricing structure across premium, standard, and economy levels separates performance-guaranteed service contracts from bare-equipment transactions and entry-level storage units. Price differentiation hinges on thermal efficiency certification tier and after-sales service bundling intensity. Cost compression in the standard tier is intensifying because Chinese-scale manufacturers are flooding European distribution channels with cost-engineered heat pump platforms. Quick-service restaurant chains exhibit highest price sensitivity, while hospital central plant operators prioritize redundancy guarantees over capital expenditure minimization.
Supply Chain Analysis
Regional distribution centers in Chicago, Frankfurt, and Tokyo anchor hub-and-spoke patterns that feed mechanical contractors and energy service companies. Manufacturing concentrates in the United States, Germany, and China, with Japanese specialists dominating tankless heat exchanger production. Supply chains draw from Chilean copper mines, Indonesian nickel processing, and Chinese refrigerant chemical manufacturing. Single-source vulnerability around R-410A and R-32 production clusters creates exposure for North American and European assembly lines. Distribution runs through professional plumbing wholesalers and HVAC distributor networks rather than retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The commercial water heater market functions as a regulatory compounder where efficiency mandate ratchets generate replacement demand irrespective of economic cycles. The US Department of Energy's 2023 standards and the EU Ecodesign Directive's 91% thermal efficiency floor together guarantee equipment turnover velocity.
For Market Incumbents: Cement specification relationships with hospitality chains and hospital systems before refrigerant redesign cycles reshape qualification requirements. Prioritize backward integration into CO2 compressor sourcing to defend margin position against Chinese cost-engineered entrants. Channel control through professional plumbing distributors remains the critical defensive moat as third-party energy service companies capture decision-making authority. For New Entrants and Emerging Players: Launch via performance-based service contracts targeting US quick-service restaurant chains with distributed property portfolios and capital constraints favoring operational expenditure models. India's IT park and hospital construction pipeline in Bangalore and Pune offers the most penetrable geography for heat pump and solar-thermal hybrid first-mover positioning. White-space capture requires local certification investment and technician training partnerships rather than equipment-only distribution. For Investors and Strategic Acquirers: Roll-up economics work for regional plumbing-channel specialists with concentrated geographic technician networks because efficiency mandate compression accelerates replacement cycle predictability. Target mid-scale manufacturers with established CO2 transcritical engineering capabilities and hospitality sector service contract books. Watch refrigerant phase-down implementation timing as the inflection signal for portfolio revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| CO2 Transcritical Platform Development | Positions suppliers ahead of EU F-Gas Regulation hydrofluorocarbon phasedown deadlines. |
| Performance-Based Service Contract Expansion | Captures hospitality chain procurement authority shifting from mechanical contractors to energy service companies. |
| Professional Plumbing Channel Deepening | Secures specification influence in replacement cycles where installer recommendations override brand preference. |
| Refrigerant Handling Certification Investment | Addresses EPA Section 608 technician shortages delaying heat pump commissioning and inflating service costs. |
| Smart Grid Demand-Response Integration | Enables thermal storage arbitrage in California and Germany time-of-use electricity pricing markets. |
Methodological Framework
Bottom-up hospitality and healthcare modeling reconciled against top-down heat pump and storage system production tracking forms the analytical core. Primary interviews with commercial plumbing contractors, hospital facility managers, hospitality procurement directors, and HVAC distributor principals combined with secondary validation against DOE appliance standards filings, EU Ecodesign implementing measures, and METI Top Runner program disclosures. Customs data on copper and nickel import flows, SEC 10-K equipment manufacturer disclosures, and Bureau of Labor Statistics plumbing contractor employment patterns provided triangulation anchors.
Input-output matrices map thermal capacity installations by fuel type, application vertical, and installation configuration across the projection horizon. Segmentation dimensions include product type, fuel source, end-use sector, and geographic regulatory cluster. CAGRs derive from equipment replacement cycle velocity under efficiency mandate compression and new construction permit trajectories. Forecast inputs incorporate refrigerant availability curves, electrical infrastructure upgrade timelines, and carbon pricing mechanism expansion patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under copper price volatility spikes or refrigerant supply disruption scenarios. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
North America HVAC Filter Change Service Market
HVAC Equipment
GCC Water Heater Market
HVAC Equipment
HVAC Systems Market
HVAC Equipment
Asia-Pacific Heat Exchanger Market
HVAC Equipment
Global HVAC Linesets Market
HVAC Equipment
Germany Commercial HVAC Market
HVAC Equipment
High Pressure Heat Exchanger Market
HVAC Equipment
Air Conditioning Compressor Market
HVAC Equipment
Asia-Pacific Industrial Heat Pump Market
HVAC Equipment
Middle East and Africa Commercial HVAC Market
HVAC Equipment
North America Gas Water Heater Market
HVAC Equipment
Middle-East and Africa Compressor Market
HVAC Equipment
Utility and Industrial Boilers Market
HVAC Equipment
Fume Extraction System Market
HVAC Equipment
Field-Erected Cooling Tower Market
HVAC Equipment
Air Conditioning Equipment Market