
 United Kingdom Commercial HVAC Market | 2026-2036
United Kingdom Commercial HVAC Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Commercial HVAC Market Insights
Performance-based maintenance contracts is realigning how commercial HVAC value gets captured in the United Kingdom. Johnson Controls International leverages its building automation footprint to bundle predictive service with equipment sales. Daikin Industries Ltd. anchors its UK position through VRF system specialization and contractor training networks. Mitsubishi Electric Europe BV competes on compact heat pump architectures suited to constrained urban plant rooms.
United Kingdom Commercial HVAC encompasses climate control systems designed for non-residential buildings, typically operating between 5 kW and 5 MW cooling capacity with coefficient of performance targets exceeding 3.0 for new installations. These systems regulate temperature, humidity, and air quality across retail, healthcare, and education environments where occupancy patterns vary sharply throughout operational hours. Rooftop units dominate volume in out-of-town retail and light industrial estates where single-story construction prevails. Variable Refrigerant Flow systems command premium positioning in London office refurbishments where zoned control and minimal ductwork renovation reduce disruption. Smart Controls represent the fastest-expanding technology layer as landlords face MEES compliance deadlines and seek remote diagnostic capability.
The UK's Building Regulations Part L, enforced by local authority building control bodies, mandates minimum seasonal efficiency metrics that filter out legacy replacement equipment. The F-Gas Regulation, implemented through the Environment Agency, phases down hydrofluorocarbon refrigerant quotas and pushes adoption of lower-GWP alternatives like R32 and R290. Stakeholders must weigh refrigerant transition timelines against equipment replacement cycles to avoid stranded asset risk in portfolios with concentrated 2020s installation vintages.
Market Dynamics
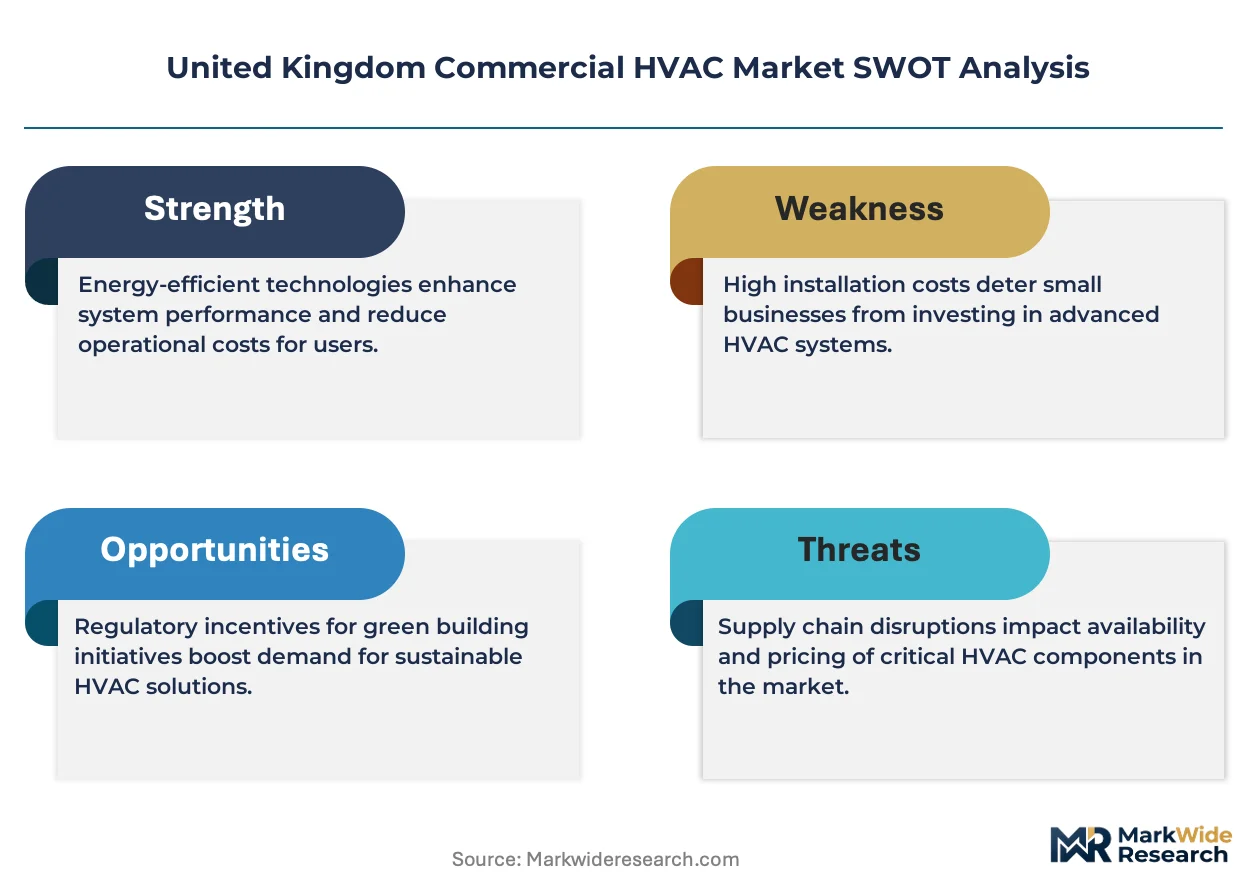
Building Regulations Part L enforcement is compressing replacement cycles across UK commercial property portfolios, forcing landlords to pre-empt equipment obsolescence before Minimum Energy Efficiency Standards deadlines trigger asset stranding.
Growth Catalysts
- MEES Compliance Deadlines:London office landlords facing 2027 and 2030 efficiency thresholds are accelerating HVAC refresh programs to avoid rental restrictions on sub-grade properties.
- Heat Pump Technology Maturation:Compact high-temperature units now serve constrained urban plant rooms in Greater Manchester and Birmingham commercial corridors previously dependent on gas boilers.
- Southeast England Construction Activity:Major logistics and life science developments around Cambridge, Oxford, and the Thames Valley are specifying high-efficiency VRF systems from ground-up.
Market Restraints
- F-Gas Quota Compression:The Environment Agency's phasedown of hydrofluorocarbon refrigerant allocations is constraining service capacity for legacy R410A systems during peak summer demand periods.
- Skilled Installer Bottleneck:MCS certification requirements for heat pump installation have created a qualified technician shortage concentrated in Northern England and Scottish commercial markets.
- Capital Intensity of Deep Retrofit:Full-system replacements in 1980s office stock require simultaneous fabric upgrades, doubling project costs versus equipment-only swaps.
Strategic Opportunities
- Scottish Commercial Decarbonization:Scotland's 2045 net-zero target and Heat in Buildings Strategy are creating concentrated demand for district heat interface units in Edinburgh and Glasgow office refurbishments.
- Smart Controls Integration:Landlords are bundling IoT-enabled building management systems with HVAC upgrades to capture real-time efficiency data for MEES reporting.
- R32 Refrigerant Transition:Early equipment refresh cycles ahead of 2027 F-Gas step-downs are opening replacement windows for lower-GWP systems in retail and hospitality portfolios.
Industry Challenges
- Refrigerant Transition Timing:Portfolio managers must synchronize equipment replacement with refrigerant phase-down schedules to avoid installing systems with constrained future service availability.
- Integration with 20th-Century Building Fabric:Victorian and Edwardian commercial stock in city centers presents ductwork routing constraints and load calculation uncertainties that inflate project risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Commercial HVAC Market |
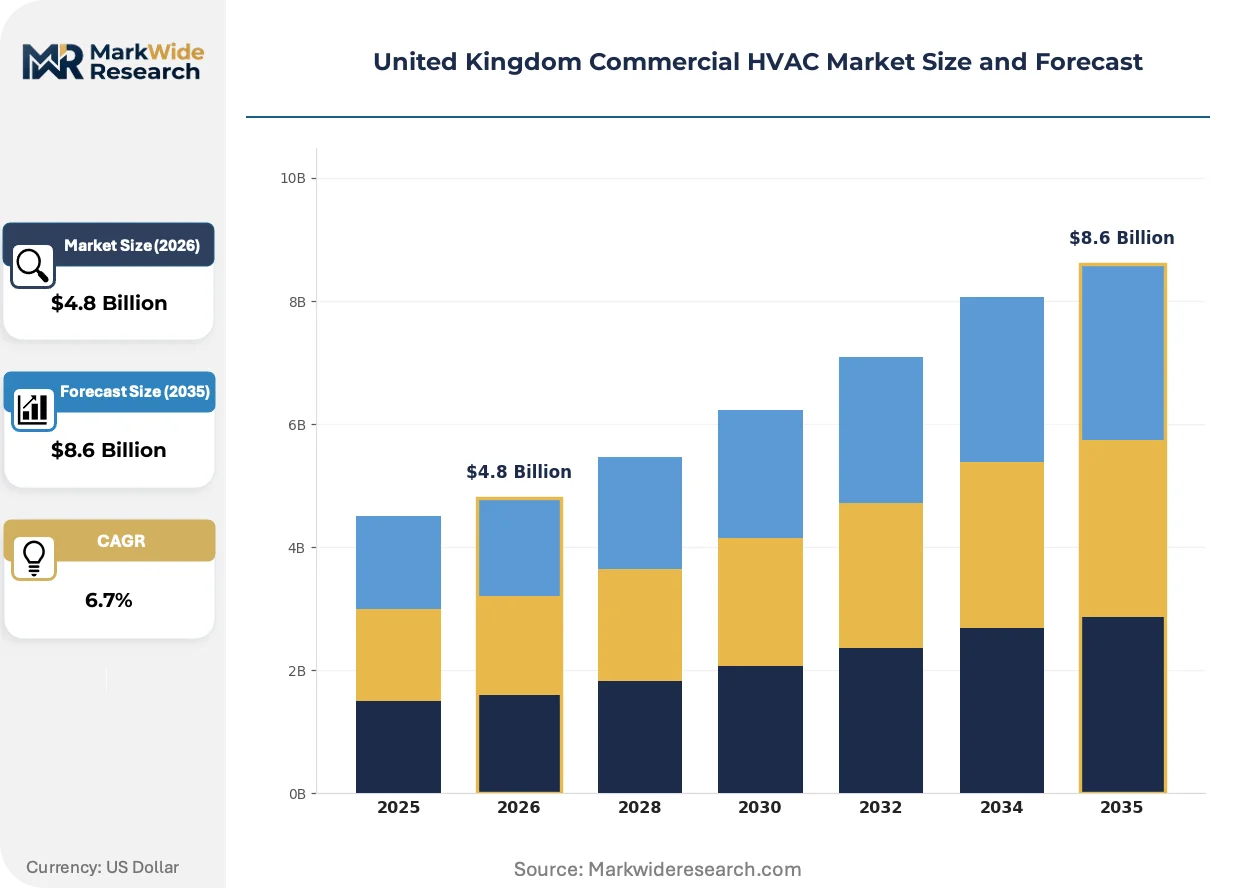
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chillers, Heat Pumps, Air Handlers, Rooftop Units Technology: Variable Refrigerant Flow, Ducted Systems, Fan Coil Units, Smart Controls Application: Office Buildings, Educational Institutions, Retail Spaces, Healthcare Facilities End User: Building Owners, Facility Managers, Contractors, Consultants |
| Companies Covered | Daikin Industries Ltd., Johnson Controls International, Robert Bosch GmbH, Mitsubishi Electric Europe BV, Carrier Corporation, Vaillant Group, Danfoss A/S, Lennox International Inc., LG Electronics Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Commercial HVAC Market Trends and Innovations
Digitalization of building operations is compressing the traditional split between equipment procurement and ongoing energy management, embedding predictive capability into specification criteria.
Artificial intelligence-driven fault detection is rewriting how commercial landlords manage distributed HVAC assets. Machine learning algorithms analyze vibration, temperature, and power draw patterns to flag degradation before failure. Property managers with multi-site retail or office portfolios are adopting these systems fastest. The technology is compressing reactive maintenance margins and shifting service contract value toward software subscriptions.
The Environment Agency's F-Gas Regulation phase-down is accelerating refrigerant chemistry transitions across UK commercial HVAC. R32 and R290 are displacing R410A in new equipment specifications. The regulation is forcing manufacturers to redesign compressor architectures and safety systems. London-based facilities managers are prioritizing R32-ready systems to future-proof 15-year asset lifecycles against supply constraints.
Performance-based service agreements are displacing traditional time-and-materials maintenance contracts in prime office and healthcare segments. Landlords now specify guaranteed availability or efficiency outcomes rather than visit frequencies. Contractors are absorbing operational risk and investing in remote monitoring infrastructure. This shift is most visible in Thames Valley science park developments where institutional investors demand predictable operating cost profiles.
United Kingdom Commercial HVAC Market Segmentation
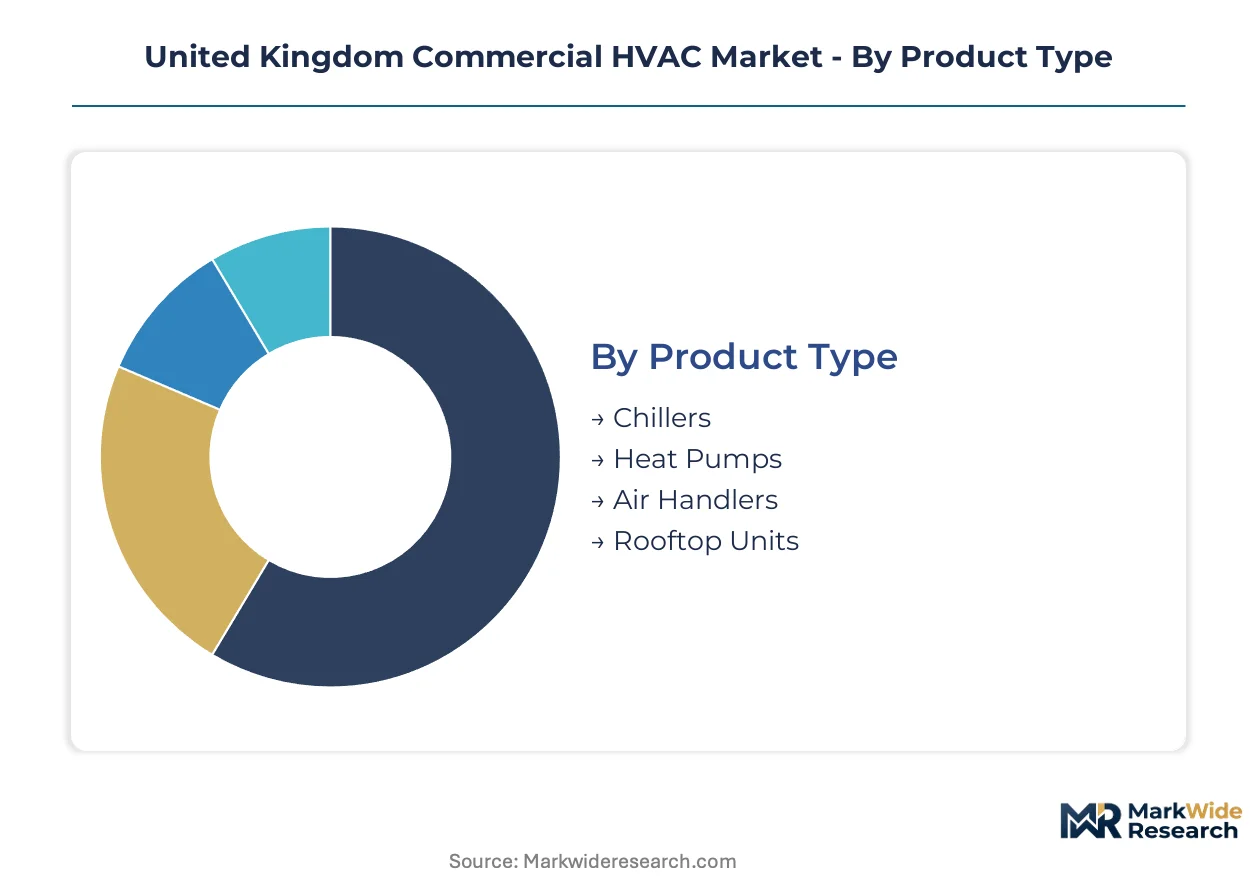
United Kingdom commercial HVAC procurement splits sharply between standardized equipment for volume deployment and engineered systems for constrained urban sites. Specification criteria diverge across London office refurbishments, Northern logistics estates, and Scottish healthcare estates where regulatory timelines and building fabric conditions dictate technology selection.
Product Type:
Standardized packaged systems dominate out-of-town retail and industrial applications, while custom-engineered solutions prevail in heritage building retrofits where plant room dimensions and structural load limits force bespoke configurations.
- Chillers:Water-cooled and air-cooled configurations serve large commercial footprints above 500kW cooling demand. London commercial landlords facing MEES deadlines are specifying magnetic bearing compressors for part-load efficiency in 1980s office stock. The Environment Agency's F-Gas phasedown is accelerating R1234ze and R513A adoption in new chiller specifications.
- Heat Pumps:Air-source and ground-source variants now deliver 65°C flow temperatures for direct gas boiler replacement. Greater Manchester and Birmingham commercial corridors are deploying compact high-temperature units in plant rooms previously sized for fossil fuel equipment. MCS certification requirements constrain installer availability in Northern England markets.
- Air Handlers:Modular configurations with heat recovery wheels address Part L ventilation efficiency mandates. Demand concentrates in Thames Valley life science facilities requiring precise humidity control.
- Rooftop Units:Packaged DX systems with factory-sealed refrigerant circuits minimize on-site installation labor. Volume deployment tracks out-of-town retail and light industrial estates across the Midlands.
Most installed capacity flows through Rooftop Units. Expansion is steepest in Heat Pumps.
Technology:
Cost tier stratification separates premium zoned control systems from commodity ducted alternatives, with smart controls capturing disproportionate margin as landlords bundle digital infrastructure with hardware procurement.
- Variable Refrigerant Flow:Multi-zone refrigerant distribution eliminates ductwork renovation in London office refurbishments. Heat recovery operation between simultaneous heating and cooling zones reduces landlord energy exposure. Part L efficiency thresholds favor VRF in prime commercial segments where MEES compliance risk concentrates.
- Smart Controls:IoT-enabled building management systems with predictive fault detection command premium positioning. Institutional investors in Thames Valley science parks are mandating real-time efficiency data for operating cost forecasting. The technology is compressing traditional maintenance contract structures toward outcome-based service agreements.
- Ducted Systems:Centralized all-air configurations persist in 1970s-1980s office stock where full system replacement is capital-constrained. Building control bodies enforce minimum seasonal efficiency metrics that filter out legacy replacement equipment.
- Fan Coil Units:Terminal units with two-pipe or four-pipe configurations serve perimeter zones in mixed-mode buildings. Demand tracks Edinburgh and Glasgow office refurbishments integrating with district heat networks.
Volume deployment still favors Ducted Systems. Value capture is climbing fastest in Smart Controls.
Application:
Customer type segmentation separates institutional owners with long-dated liability from speculative developers with shorter hold periods, driving divergent technology risk appetites and service contract structures.
- Office Buildings:London, Manchester, and Birmingham commercial stock dominates equipment refresh cycles. MEES 2027 and 2030 thresholds are forcing pre-emptive HVAC replacement in 1990s-vintage assets. Deep retrofit requirements often trigger simultaneous fabric upgrades that double project costs.
- Healthcare Facilities:NHS Trust procurement frameworks mandate infection control compliance and 24/7 resilience specifications. Critical care environments require redundant cooling capacity with N+1 configuration. The segment absorbs premium pricing for validated performance guarantees.
- Educational Institutions:University estates and secondary schools balance capital constraints against tightening Part L efficiency requirements. Summer peak cooling demand often exceeds winter heating load, favoring heat pump sizing for cooling-first operation.
- Retail Spaces:High street and out-of-town formats face divergent constraints. Urban retail contends with plant room scarcity; logistics-adjacent retail specifies rooftop units for single-story construction efficiency.
Equipment value concentrates in Office Buildings. Procurement momentum is building fastest in Healthcare Facilities.
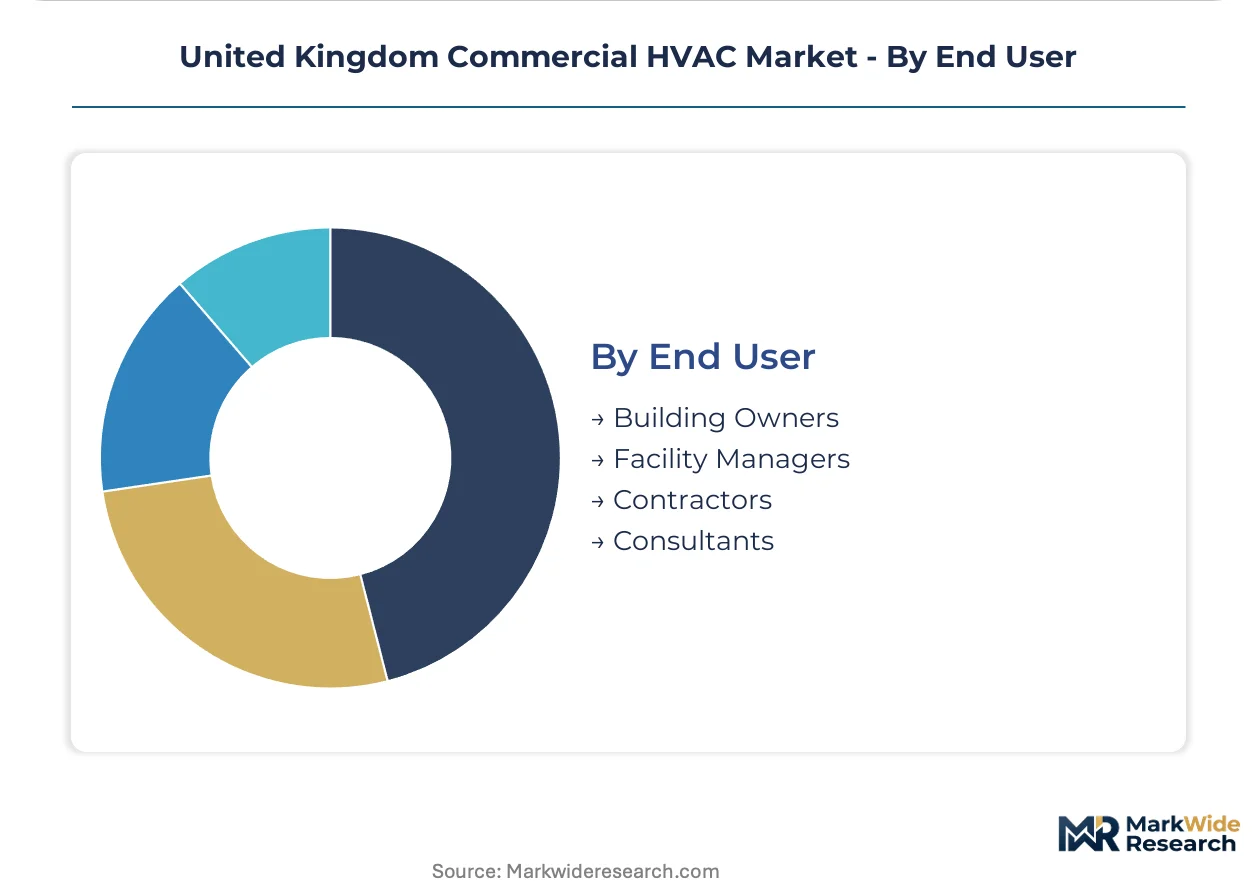
End User:
Supply concentration aligns with contractor certification networks and manufacturer training infrastructure, creating geographic pockets of competitive advantage around VRF specialization and heat pump competence.
- Building Owners:Institutional landlords with multi-asset portfolios are consolidating procurement through framework agreements. MEES compliance risk is driving specification of R32-ready systems with 15-year asset lifecycles. Performance-based maintenance contracts are displacing time-and-materials service structures.
- Facility Managers:Operational responsibility for energy performance contracts is elevating influence over technology selection. Remote diagnostic capability is becoming a mandatory specification criterion. The role is absorbing operational risk as service agreements shift toward guaranteed availability outcomes.
- Contractors:MCS certification requirements for heat pump installation have created qualified technician bottlenecks in Northern England and Scottish markets. Daikin and Mitsubishi Electric training networks are competitive differentiators in VRF system deployment.
- Consultants:MEP engineers and sustainability advisors are embedding refrigerant transition timelines into equipment replacement strategies. F-Gas quota compression is forcing synchronization of asset refresh cycles with 2027 step-down schedules.
Procurement authority concentrates with Building Owners. Technical specification influence is expanding fastest among Facility Managers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are minimal within the United Kingdom given uniform Building Regulations Part L enforcement, yet sub-regional variation in building stock age and MEES compliance timelines creates distinct demand pockets across England, Scotland, and Wales.
London and Southeast England
Prime office stock concentrated in the City and Canary Wharf drives premium VRF system demand as landlords face 2027 MEES thresholds. The Greater London Authority's net-zero pathway accelerates heat pump specification in commercial refurbishments. Cambridge and Oxford life science clusters specify high-efficiency air handlers for precise environmental control.
Midlands
Birmingham's 1990s office inventory requires simultaneous fabric and HVAC upgrades to meet efficiency standards. The West Midlands Combined Authority's retrofit funding programs reduce capital barriers for SME landlords. Out-of-town retail parks across Coventry and Leicester favor rooftop units for single-story logistics-adjacent formats.
North England
Manchester's commercial corridor deploys compact high-temperature heat pumps in plant rooms originally sized for gas boilers. MCS certification bottlenecks constrain installer capacity across Greater Manchester and Liverpool markets. Leeds healthcare estates drive demand for redundant cooling configurations under NHS procurement frameworks.
Scotland
Edinburgh and Glasgow office refurbishments integrate district heat interface units aligned with Scotland's 2045 net-zero target. The Heat in Buildings Strategy mandates efficiency standards that predate English MEES timelines. Scottish commercial landlords absorb premium pricing for validated performance guarantees in critical care environments.
United Kingdom Commercial HVAC Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-system integrators commanding premium positioning in London office refurbishments while standardized equipment suppliers dominate volume deployment in retail and industrial estates. The vendor base organizes around three strategic archetypes: Japanese conglomerates with VRF specialization, North American building automation platforms, and European heating technology heritage players. Competitive moves concentrate on predictive service bundling and refrigerant transition readiness ahead of 2027 F-Gas step-downs.
Among Japanese conglomerates with climate control divisions, Daikin Industries Ltd. and Mitsubishi Electric Europe BV occupy positions defined by contractor training infrastructure and compact heat pump architectures suited to constrained urban plant rooms. Johnson Controls International anchors the building automation tier, leveraging its control systems footprint to bundle predictive maintenance with equipment procurement. These three exemplify divergent competitive vectors: VRF system specialization, compact heat pump engineering, and integrated building management platforms.
| Leading Market Players |
|---|
| Daikin Industries Ltd. |
| Johnson Controls International |
| Robert Bosch GmbH |
| Mitsubishi Electric Europe BV |
| Carrier Corporation |
| Vaillant Group |
| Danfoss A/S |
| Lennox International Inc. |
| LG Electronics Inc. |
| Others |
Pricing and Supply Chain Analysis
R32 refrigerant transition is compressing cost structures across UK commercial HVAC procurement while redistributing manufacturing leverage toward Japanese and European compressor specialists with chemistry-ready platforms. Building Regulations Part L enforcement is simultaneously elevating premium-tier pricing for MEES-compliant equipment and squeezing margins on legacy R410A service capacity.
Pricing Analysis
Distributor margins on VRF systems range from 18-25% depending on contractor certification tier and volume commitments. Three-tier pricing structure across premium, standard, and economy levels tracks MEES compliance risk, with R32-ready systems commanding 15-20% premiums over transitional equipment. Pricing pressure stems from F-Gas quota compression limiting service revenue on installed base. Speculative developers with sub-five-year hold periods exhibit highest price sensitivity; institutional landlords with long-dated liability accept premium positioning for performance guarantees.
Supply Chain Analysis
Freight costs from Japanese compressor manufacturing centers to UK distribution hubs have stabilized following pandemic-era volatility, though Red Sea routing disruptions periodically inflate landed costs for air-cooled chiller components. Component sourcing concentrates in Japan, Germany, and China for magnetic bearing compressors, heat exchanger coils, and electronic expansion valves respectively. Copper and aluminum price volatility remains the dominant supply chain risk. Distribution runs through manufacturer-authorized dealer networks with MCS certification requirements creating qualified installer bottlenecks in Northern England markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK commercial HVAC market functions as a regulatory-arbitrage play where Scottish decarbonization timelines running ahead of English MEES deadlines create geographic cost and technology absorption differentials. Scotland's 2045 net-zero target and Heat in Buildings Strategy mandate efficiency standards that predate English thresholds, concentrating premium equipment demand in Edinburgh and Glasgow ahead of broader UK adoption curves.
For Market Incumbents: Deepen backward integration into R32 and R290 compressor manufacturing to secure refrigerant-transition readiness ahead of 2027 F-Gas step-downs. Absorb qualified installer capacity through captive training academy investments in Greater Manchester and Scottish markets where MCS certification bottlenecks constrain competitor deployment velocity. Lock prime London office landlords into 15-year performance-based service agreements before MEES 2027 deadlines force refresh decisions.
For New Entrants and Emerging Players: Enter via district heat interface unit specialization targeting Scotland's 2045 net-zero pathway where incumbent coverage remains thin relative to English VRF corridors. Capture Edinburgh and Glasgow office refurbishment demand by bundling heat pump specification with Heat in Buildings Strategy compliance consulting. Pursue NHS Trust procurement framework accreditation to access healthcare segment premium pricing with validated resilience guarantees.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional contractor networks with MCS certification infrastructure but limited manufacturer exclusivity. Long-term viability hinges on refrigerant-transition readiness and predictive service platform deployment rather than equipment-only revenue. Monitor F-Gas quota allocation announcements from the Environment Agency as inflection indicators for stranded asset risk in R410A-dependent service portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Transition Readiness | R32 and R290 platform investment future-proofs 15-year asset lifecycles against Environment Agency quota compression. |
| Predictive Service Platform Deployment | AI-driven fault detection compresses reactive maintenance margins and shifts contract value toward software subscriptions. |
| MCS Certification Network Expansion | Qualified installer capacity in Northern England and Scotland constrains heat pump deployment velocity for uncertified competitors. |
| District Heat Interface Unit Specialization | Scotland's 2045 net-zero target concentrates demand in Edinburgh and Glasgow ahead of English MEES timelines. |
| Performance-Based Service Agreement Structuring | Guaranteed availability outcomes align contractor incentives with institutional investor operating cost predictability requirements. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with facilities managers at London and Manchester commercial portfolios, NHS Trust estates directors, MCS-certified installation contractors, and MEP consulting engineers with secondary validation against Building Regulations Part L enforcement data, Environment Agency F-Gas quota filings, and UK Green Building Council retrofit program disclosures. Bottom-up equipment shipment analysis and top-down construction activity indices were triangulated to anchor market sizing.
Historical reference periods spanning pre-pandemic baseline through post-MEES announcement response windows anchored the forecast framework across the analysis window. Segmentation modeling incorporated product type, technology tier, application vertical, and end-user procurement authority dimensions alongside geographic regulatory cluster differentiation between English MEES and Scottish Heat in Buildings Strategy timelines. CAGRs were derived from equipment replacement cycle compression analysis and heat pump adoption curve calibration against European comparator markets.
Inputs from NHS procurement frameworks and local authority building control bodies were available through the study window; gaps in real-time MCS certification pipeline data introduce uncertainty bands around installer capacity forecasts in Northern England markets. Forecasts reflect assumptions regarding regulatory enforcement consistency and refrigerant chemistry transition timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Europe Bus HVAC Market
HVAC Equipment
US Compressed Air Treatment Equipment Market
HVAC Equipment
Modular Refrigeration Unit Market
HVAC Equipment
Global Portable Air Conditioner Market
HVAC Equipment
Foamer Pump Market
HVAC Equipment
Europe Industrial Heat Pump Market
HVAC Equipment
China Residential Heat Pump Market
HVAC Equipment
Industrial Ventilation Equipment Market
HVAC Equipment
ASEAN Heat Exchanger Market
HVAC Equipment
Recirculating Chillers Market
HVAC Equipment
HVAC Chillers Market
HVAC Equipment
Global HVAC Packaged Unit Market
HVAC Equipment
Kitchen Hood Market
HVAC Equipment
Residential Furnaces Market
HVAC Equipment
Air Humidifier and Dehumidifier Market
HVAC Equipment
Positive Displacement Blowers Market