
 Fiber Optic Connectivity Market | 2026-2036
Fiber Optic Connectivity Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Optic Connectivity Market Intelligence
The gap between premium single-mode fiber and commodity multi-mode offerings is consolidating around performance thresholds for 800G and 1.6T coherent transmission. Corning Incorporated leverages its proprietary low-loss glass formulations to sustain dominance in long-haul and submarine cable cores. Coherent Corporation anchors its position through vertical control over indium phosphide and silicon photonics chipsets for pluggable transceivers.
Fiber optic connectivity encompasses the physical layer infrastructure—optical fiber, connectors, splitters, amplifiers, and transceivers—that transmits data as modulated light pulses typically at wavelengths of 1310 nm or 1550 nm with attenuation below 0.2 dB per kilometer in single-mode fiber. Its primary purpose is to deliver terabit-scale bandwidth across distances from meters in data centers to thousands of kilometers in submarine systems. Single-mode fiber leads in revenue contribution due to its indispensability in telecom backbones and inter-data-center links, while wavelength division multiplexing technology captures expanding margin pools as carriers densify channels per fiber pair. Passive optical networks retain structural importance in residential and enterprise access networks where cost-per-subscriber economics govern deployment decisions.
FCC broadband subsidy rules, EU Gigabit Infrastructure Act targets, and China's MIIT dual carbon mandates are collectively tightening specifications for energy-efficient, high-density fiber deployments across their respective jurisdictions. The FCC's BEAD program specifically conditions funding on fiber-to-the-premises builds, redirecting carrier procurement toward qualified cable and equipment vendors. Stakeholders must track how national security screening of Chinese-origin equipment reshapes supplier qualification lists and inventory strategies.
Market Dynamics
Coherent transmission at 800G and 1.6T line rates is compressing upgrade cycles across metro and long-haul networks, forcing carriers to pre-position fiber infrastructure before transceiver economics mature. This technical inflection concentrates procurement power among hyperscalers and tier-one operators capable of absorbing early-adopter premiums.
Growth Catalysts
- FCC BEAD funding conditions:The program's fiber-to-the-premises mandate redirects carrier capital toward qualified cable vendors, accelerating last-mile construction in underserved census blocks.
- AI training cluster bandwidth density:Hyperscaler data centers are deploying MPO-16 and MPO-32 fiber configurations to support GPU interconnects at 51.2 Tbps switch capacities.
- Submarine cable renewal wave:Trans-Pacific and trans-Atlantic routes built during the 2000s fiber boom are approaching end-of-design-life, forcing consortiums to commission replacement systems.
Market Restraints
- High-purity silica sand concentration:Optical fiber preform manufacturing depends on feedstock from limited North Carolina and Minnesota deposits, exposing supply chains to geological and permitting risks.
- Indium phosphide wafer scarcity:Coherent DSP and laser chip production faces capacity constraints at foundries specializing in III-V compound semiconductors.
- Right-of-way access friction:Municipal permitting delays for aerial and underground fiber deployment extend project timelines by 8-14 months in dense urban jurisdictions.
Strategic Opportunities
- India BharatNet Phase III expansion:The government's rural broadband mandate creates volume demand for G.657.A2 bend-insensitive fiber in gram panchayat connections.
- EU Gigabit Infrastructure Act deadlines:Member state targets for universal 1 Gbps coverage by 2030 are unlocking public-private partnership financing for open-access fiber networks.
- Silicon photonics-CMOS convergence:Integration of optical engines with standard semiconductor fabrication is collapsing transceiver cost curves for 100G/lane applications.
Industry Challenges
- Fusion splicing technician shortage:Precision fiber termination requires certified installers whose training pipelines have not scaled with deployment velocity.
- Multi-vendor interoperability certification:Open Line System architectures demand extended validation cycles to confirm transceiver compatibility across switch and router platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Optic Connectivity Market |
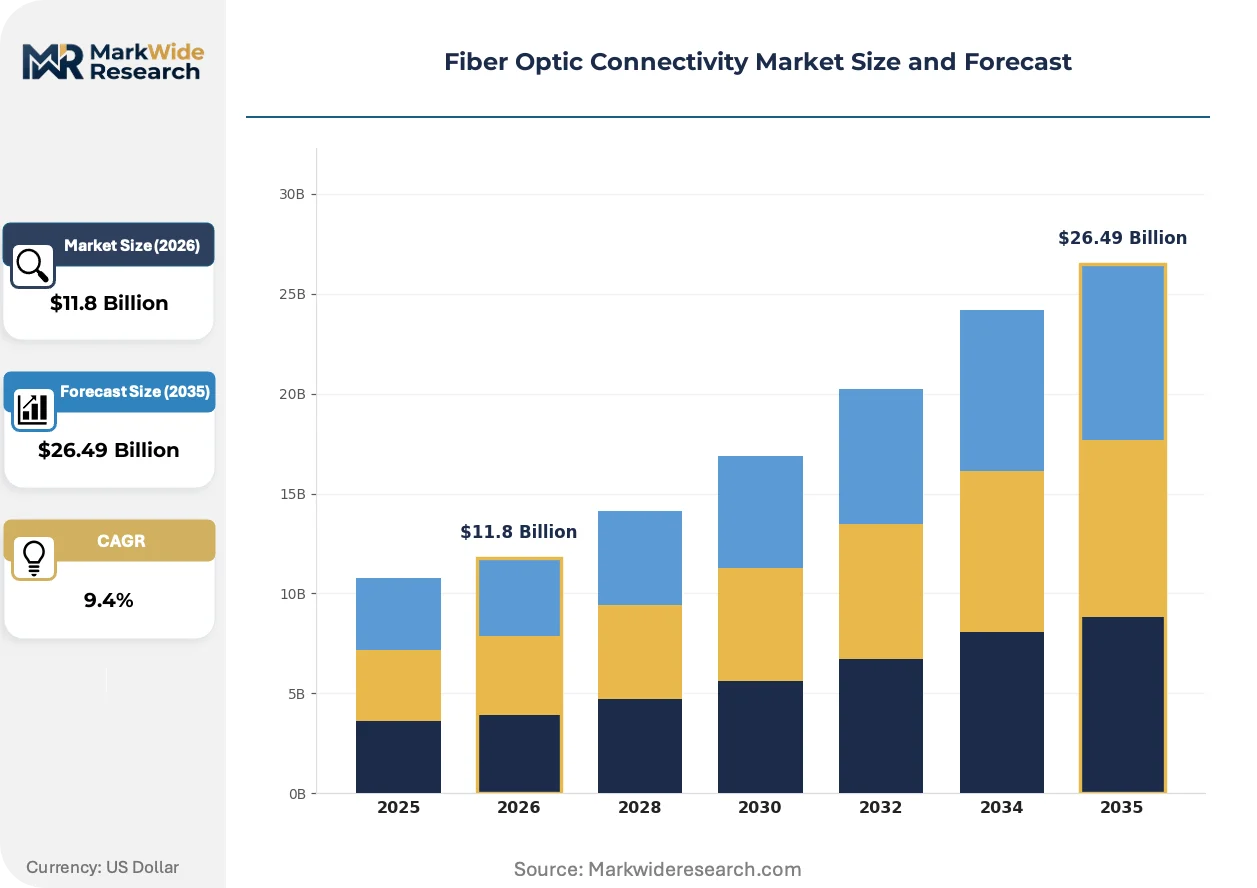
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $26.49 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Mode Fiber, Multi-Mode Fiber, Fiber Patch Cords, Fiber Optic Cables Technology: Wavelength Division Multiplexing, Passive Optical Network, Fiber Optic Sensing, Optical Amplifiers End User: Telecommunications, Data Centers, Government, Enterprises Installation: Indoor, Outdoor, Undersea, Aerial |
| Companies Covered | Corning Incorporated, Broadcom Inc., Coherent Corporation, Lumentum Holdings Inc., Sumitomo Electric Industries, TE Connectivity, ADTRAN Inc., Ciena Corporation, Huawei Technologies Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Optic Connectivity Market Strategic Shifts & Innovations
Hollow-core fiber and advanced modulation formats are compressing the performance gap between theoretical capacity limits and deployed system economics. These developments are forcing incumbents to accelerate R&D timelines while opening entry points for specialized component suppliers.
Multicore fiber is expanding into submarine and inter-data-center applications by multiplying spatial channels within a single cladding. Cable consortiums are piloting 4-core and 7-core designs on transoceanic routes to defer the cost of new wet plant installation. This topology is expanding into the market by enabling capacity scaling without additional fiber pairs, reshaping route engineering economics for Pacific and Atlantic systems.
The EU F-Gas Regulation phase-down is accelerating adoption of fluorine-free fiber coating chemistries and dry cable filling compounds. Manufacturers are reformulating acrylate buffer layers to eliminate perfluorinated substances while maintaining mechanical reliability across temperature extremes. European carriers are now specifying PFAS-free cables in tender documents, pushing supply chain conversion ahead of the 2030 prohibition deadlines.
Hyperscalers are consolidating optical component procurement through direct sourcing agreements that bypass traditional distribution channels. Amazon Web Services, Microsoft Azure, and Google Cloud are establishing technical qualification programs that pre-approve transceiver vendors for multi-year supply commitments. This concentration is most pronounced in the United States, where three operators account for the majority of 400G and 800G port deployments.
Fiber Optic Connectivity Market Segmentation
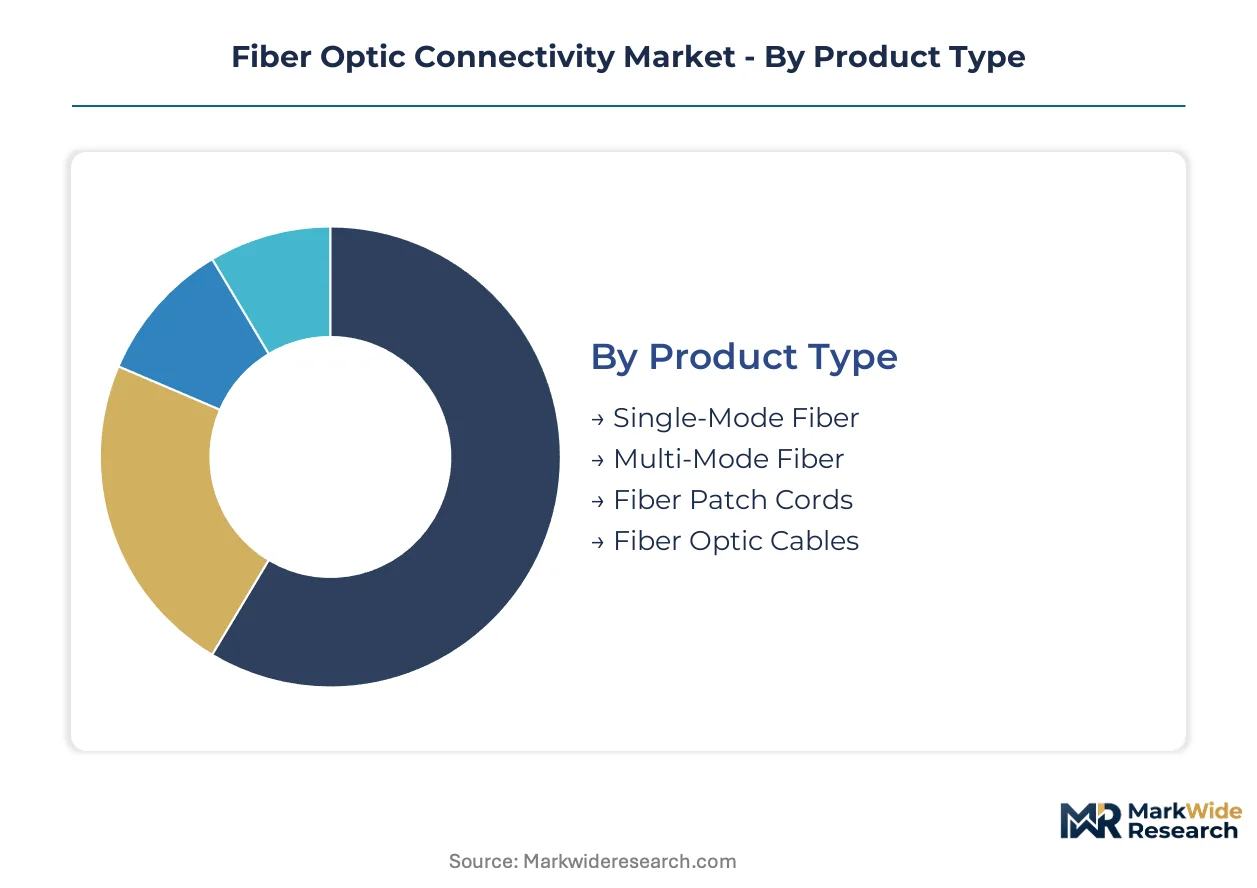
Fiber optic connectivity markets fragment across product architectures, transmission technologies, deployment environments, and customer procurement patterns. Each segmentation axis carries distinct margin profiles, certification requirements, and supply chain configurations that shape vendor positioning strategies.
Product Type:
Glass preform manufacturing concentrates among specialized chemical suppliers in North Carolina and Minnesota, locking feedstock access for premium fiber categories.
- Single-Mode Fiber:Engineered with 8-10 micron core diameters for 1310 nm and 1550 nm transmission windows, achieving attenuation below 0.2 dB per kilometer. Hyperscaler inter-data-center links spanning 10-120 kilometers absorb the majority of premium low-loss deployments, driven by coherent 800G transceiver rollouts requiring ultra-low nonlinearity specifications.
- Multi-Mode Fiber:Features 50 or 62.5 micron cores optimized for 850 nm vertical-cavity surface-emitting laser sources across shorter reaches. Enterprise data center fiber-to-the-server architectures in the United States concentrate demand for OM4 and OM5 graded-index formulations supporting 100G SR10 and 400G SR16 transceiver formats.
- Fiber Patch Cords:Factory-terminated duplex assemblies with polished ceramic ferrule connectors bridge equipment ports to structured cabling systems.
- Fiber Optic Cables:Bundled fiber counts from 12 to 864 strands within polyethylene sheaths serve outside plant trunk and distribution applications.
Single-mode fiber absorbs the bulk of installed capacity; multi-mode fiber is expanding most quickly in hyperscale data center rebuild cycles.
Technology:
Patent thickets and foundry capacity constraints concentrate value capture among coherent DSP and indium phosphide laser suppliers.
- Wavelength Division Multiplexing:Dense and coarse variants multiply spectral efficiency by transmitting 40-160 channels per fiber pair across the C- and L-bands. Submarine cable consortiums commissioning trans-Pacific system upgrades anchor procurement volumes, compelled by 25-year design lifecycles and 40% annual traffic growth on core routes.
- Passive Optical Network:Point-to-multipoint architectures split a single feeder fiber across 32-128 subscriber drops using unpowered optical splitters. FCC BEAD program fiber-to-the-premises mandates in rural United States census blocks are accelerating gigabit-capable XGS-PON and NG-PON2 equipment procurement.
- Fiber Optic Sensing:Distributed acoustic and temperature monitoring along standard telecom fiber enables pipeline integrity and perimeter security applications.
- Optical Amplifiers:Erbium-doped and Raman amplification stages compensate span losses across 80-120 kilometer unrepeatered terrestrial and submarine links.
Wavelength division multiplexing dominates carrier capital allocation; passive optical networks are climbing the fastest on subsidy-driven rural access builds.
End User:
Procurement scale and technical sophistication stratify sharply across customer categories, with hyperscalers bypassing traditional distribution channels entirely.
- Telecommunications:Incumbent and competitive local exchange carriers operate under universal service obligations and wholesale access regulations. Verizon, AT&T, and regional Bell operating companies in the United States are consolidating metro network upgrades around 400G coherent pluggables, replacing legacy 100G fixed transponder architectures.
- Data Centers:Colocation and cloud operators optimize for space, power, and cooling constraints at rack scale. Multi-tenant facilities in Ashburn, Virginia and Hillsboro, Oregon are standardizing on MPO-16 and MPO-32 trunk cables to support 51.2 Tbps switch fabrics and GPU cluster interconnects.
- Government:Defense and civilian agencies specify ruggedized, TEMPEST-certified, or Buy America-compliant fiber assemblies for classified and critical infrastructure networks.
- Enterprises:Financial services, healthcare, and manufacturing verticals deploy fiber for campus backbone and electromagnetic interference immunity.
Telecommunications retains the deepest installed base; data centers are gaining share fastest on AI training cluster buildouts.
Installation:
Environmental exposure and mechanical loading requirements dictate cable construction, with submarine and aerial deployments commanding specialized manufacturing capabilities.
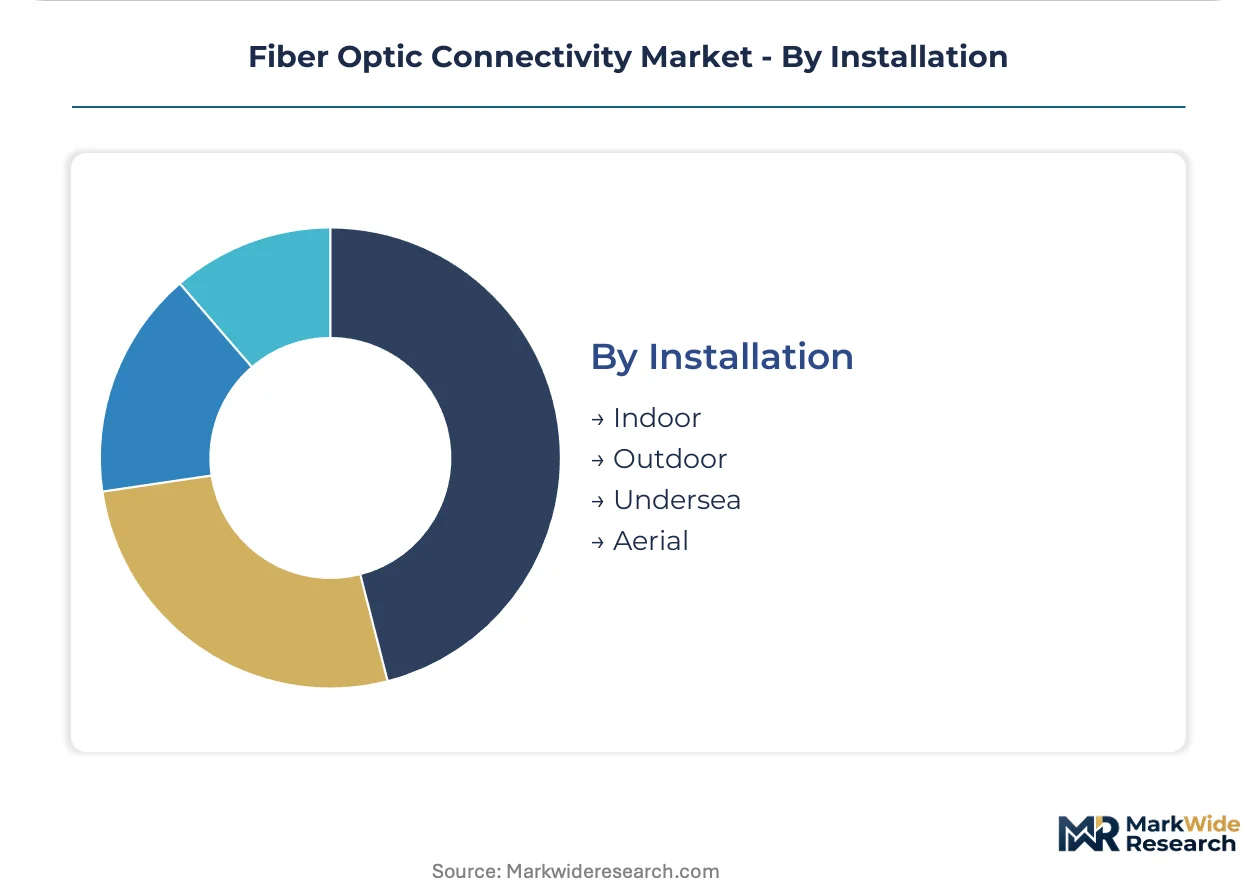
- Indoor:Riser-rated and plenum-rated tight-buffered cables with flame-retardant jackets comply with NFPA 70 National Electrical Code specifications for vertical shaft and air handling space deployment.
- Outdoor:Loose-tube gel-filled or dry-blocked cables with armor and polyethylene sheathing withstand moisture, rodent, and tensile stresses in direct-buried and duct applications.
- Undersea:Copper-wrapped, polyethylene-insulated, steel-wire-armored cable structures protect fiber pairs across 6,000 meter ocean depths. Trans-Pacific consortiums replacing systems from the 2000s fiber boom are commissioning 12-24 fiber pair designs with spatial division multiplexing readiness.
- Aerial:All-dielectric self-supporting or figure-eight lashed constructions attach to utility poles alongside power distribution lines.
Outdoor installation accounts for the majority of fiber-kilometers deployed; undersea cables are expanding most quickly on transoceanic route renewal cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ashburn, Virginia anchors hyperscaler fiber procurement volumes as cloud operators expand metro network capacity for AI training clusters. The United States concentrates submarine cable landing stations and data center interconnect demand. Regulatory programs across multiple jurisdictions are redirecting carrier capital toward fiber-to-the-premises builds.
United States
Hyperscalers in Northern Virginia and Hillsboro, Oregon are deploying MPO-16 and MPO-32 configurations for 51.2 Tbps switch fabrics. The FCC's BEAD program conditions rural broadband subsidies on fiber-to-the-premises construction, redirecting procurement toward qualified cable vendors. Carrier consolidation around 400G coherent pluggables is replacing legacy fixed transponder architectures in metro networks.
China
MIIT dual carbon mandates are tightening specifications for energy-efficient fiber deployments across provincial backbone networks. The national broadband strategy targets universal gigabit coverage through state-directed capital allocation to tier-one and tier-two cities. Yangtze River Delta fiber preform manufacturers supply domestic and export markets with low-loss single-mode formulations.
Japan
METI industrial policy supports submarine cable consortium participation for trans-Pacific route renewal cycles. Domestic carriers are standardizing on 800G coherent transmission for inter-data-center links spanning Tokyo-Osaka corridors. Chubu region optical component foundries specialize in indium phosphide laser chip production for pluggable transceivers.
Germany
The EU Gigabit Infrastructure Act deadlines are unlocking public-private partnership financing for open-access fiber networks in Bavaria and North Rhine-Westphalia. ECHA REACH compliance requirements are reformulating cable jacket chemistries to eliminate perfluorinated substances. Deutsche Telekom and regional carriers are racing to meet 2030 universal 1 Gbps coverage targets.
India
BharatNet Phase III expansion is creating volume demand for G.657.A2 bend-insensitive fiber in gram panchayat rural connections. TRAI infrastructure sharing regulations are accelerating tower fiberization for 5G backhaul. Tamil Nadu and Karnataka cable manufacturers are scaling production for domestic deployment and Southeast Asian export markets.
Fiber Optic Connectivity Market Key Industry Players
Premium-margin players sit above commodity-margin players across glass formulation and coherent chipset dimensions. The vendor base stratifies into three tiers: integrated preform-to-cable manufacturers, optical component specialists, and systems integrators. Two dominant competitive moves are reshaping positioning: hyperscaler direct sourcing agreements that bypass distribution channels, and submarine cable consortium pre-qualification requirements that lock in multi-year supply relationships.
Within the integrated manufacturing tier, Corning Incorporated and Coherent Corporation occupy anchor positions. Corning exemplifies upstream control over low-loss glass formulations for long-haul and submarine applications. Coherent represents vertical integration from indium phosphide and silicon photonics chipsets through pluggable transceiver assembly. Sumitomo Electric Industries sits within the diversified industrial conglomerate archetype with cable and component exposure across multiple transmission technologies.
| Leading Market Players |
|---|
| Corning Incorporated |
| Broadcom Inc. |
| Coherent Corporation |
| Lumentum Holdings Inc. |
| Sumitomo Electric Industries |
| TE Connectivity |
| ADTRAN Inc. |
| Ciena Corporation |
| Huawei Technologies Co. |
| Others |
Cost & Logistics Intelligence
Hyperscaler direct sourcing agreements for 800G coherent transceivers are compressing distributor margins and forcing cable manufacturers to absorb certification costs or forfeit qualification status. This buyer consolidation concentrates pricing power among three cloud operators while pushing tier-two vendors toward commodity multi-mode fiber segments.
Pricing Analysis
Throughput-guaranteed service level agreements anchor value-based pricing for submarine cable fiber pairs, with consortium members paying premiums for 25-year reliability warranties. Three-tier pricing structure across premium low-loss single-mode, standard G.652.D, and economy multi-mode grades reflects attenuation specifications and bend-insensitivity certifications. Cost compression in enterprise patch cord segments is intensifying because Chinese manufacturers are scaling MPO-16 assembly capacity. Data center operators exhibit the highest price sensitivity, while submarine cable consortiums prioritize reliability over unit cost.
Supply Chain Analysis
Fusion splicing technician shortages in North Carolina and Minnesota are constraining preform manufacturing expansion despite silica sand feedstock availability. Glass preform production draws from high-purity deposits in the United States, while indium phosphide wafer fabrication concentrates in Japan and specialized European foundries. Single-source vulnerability in III-V compound semiconductor capacity exposes coherent chipset supply to foundry allocation decisions. Distribution runs through hyperscaler direct contracts and carrier-approved vendor lists that bypass traditional distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around hyperscaler procurement concentration and submarine cable consortium pre-qualification barriers, forcing sub-scale component vendors toward acquisition or exit.
For Market Incumbents: Anchor dominance through captive supply of low-loss glass formulations and indium phosphide foundry capacity, locking submarine cable consortium relationships before renewal cycles peak. Defend against silicon photonics displacement by accelerating coherent DSP integration roadmaps. Prioritize BEAD program certification investment to capture rural fiber-to-the-premises subsidy flows. For New Entrants and Emerging Players: Hollow-core fiber manufacturing equipment offers a technology-first wedge into inter-data-center latency-sensitive applications where traditional fiber nonlinearities constrain performance. Target India's BharatNet Phase III rural access segment with G.657.A2 bend-insensitive formulations. Pursue open-access network operator partnerships in Germany and Spain to bypass hyperscaler channel concentration. For Investors and Strategic Acquirers: The window for entry favors specialized coating chemistry suppliers with fluorine-free formulations ahead of EU F-Gas prohibition deadlines. Long-term viability centers on component vendors with submarine cable consortium pre-approval status and hyperscaler technical qualification. Watch indium phosphide foundry capacity expansion announcements as inflection indicators for coherent transceiver supply elasticity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glass Preform Manufacturing | Corning's proprietary low-loss formulations lock submarine cable consortium supply relationships for 25-year design lifecycles. |
| Silicon Photonics Foundry Partnership | Coherent's CMOS-compatible optical engine production collapses transceiver cost curves for 100G/lane data center applications. |
| BEAD Program Vendor Qualification | FCC fiber-to-the-premises mandates redirect carrier procurement toward certified cable manufacturers in rural United States census blocks. |
| Submarine Cable Consortium Pre-Approval | Trans-Pacific route renewal cycles lock multi-year supply commitments for wet plant fiber pairs and repeaters. |
| Fluorine-Free Coating Chemistry Transition | EU F-Gas Regulation phase-down forces reformulation of acrylate buffer layers ahead of 2030 prohibition deadlines. |
Research Approach
SEC 10-K filings, FCC BEAD program disbursement records, and submarine cable consortium contract announcements formed the secondary backbone, cross-referenced against primary interviews with optical component procurement directors, submarine cable system engineers, and data center fiber infrastructure managers. Bottom-up fiber-kilometer deployment estimates from carrier capex disclosures were triangulated against top-down market sizing derived from preform manufacturing capacity and transceiver shipment data.
Historical trendline analysis of coherent transceiver port shipments and fiber preform production volumes established baseline growth trajectories across the projection horizon. The analytical framework modeled segmentation across fiber type, transmission technology, deployment environment, and end-user procurement pattern, with CAGRs derived from elasticity estimates against hyperscaler data center buildout schedules and subsidy-driven rural access programs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under indium phosphide foundry allocation disruptions or municipal permitting delays extending right-of-way access timelines. Forecasts reflect documented assumptions regarding subsidy program disbursement velocity and transceiver cost curve trajectories. Material deviation in FCC BEAD funding release schedules or MIIT dual carbon mandate enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Fiber Optic Development Tools Market
Optics
Beam Expanders Market
Optics
Smart Vision Systems Market
Optics
AR and VR Lens Market
Optics
Middle East and Africa Tunable Laser Market
Optics
Fiber-Optic Couplers Market
Optics
Fiber Optic Amplifier Market
Optics
Asia-Pacific Optical Imaging Market
Optics
Fiber Optic Switch Market
Optics
Optical Wavelength Service Market
Optics
Asia Pacific Smartphone Camera Lens Market
Optics
Global Nanophotonics Market
Optics
Fiber Optic Preform Market
Optics
Fiber Optics Market
Optics
Optical Lens for Mobile Phone Market
Optics
Asia-Pacific Anti-Blue Ray Myopia Lenses Market