
 Asia-Pacific Optical Imaging Market | 2026-2036
Asia-Pacific Optical Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Optical Imaging Market Outlook
Hospital procurement consolidation across Asia-Pacific is expanding as large health networks standardize imaging platforms across multiple facilities. Canon Medical Systems Corporation leverages its installed base in Japan to sustain service revenue streams throughout the region. Topcon Corporation anchors its position in ophthalmology through specialized diagnostic platforms designed for high-volume screening environments. Carl Zeiss Meditec AG competes on precision optics leadership across premium surgical microscopy segments.
Asia-Pacific optical imaging encompasses systems that capture, process, and visualize electromagnetic radiation in the visible through near-infrared spectrum, typically employing charge-coupled device or complementary metal-oxide-semiconductor sensors with spatial resolutions reaching sub-micron scales. These instruments serve clinical diagnosis, materials science, and semiconductor quality assurance by converting photonic signals into actionable structural or functional data. Endoscopes and optical coherence tomography systems dominate current revenue pools, while multispectral imaging represents the fastest-expanding technology category driven by precision agriculture and pharmaceutical quality control applications. Research laboratories and hospitals constitute the primary end-user segments, with pharmaceutical companies emerging as a concentrated growth channel for high-throughput screening platforms.
Japan's PMDA and Australia's TGA enforce stringent optical performance standards that shape product registration timelines and clinical validation requirements across the region. China's NMPA accelerates domestic innovation through streamlined approval pathways for Class II medical imaging devices. India's CDSCO alignment with international harmonization frameworks is reducing import dependency for critical diagnostic equipment. Stakeholders must monitor regulatory divergence between national approval systems as a primary determinant of market access speed and localization investment requirements.
Market Dynamics
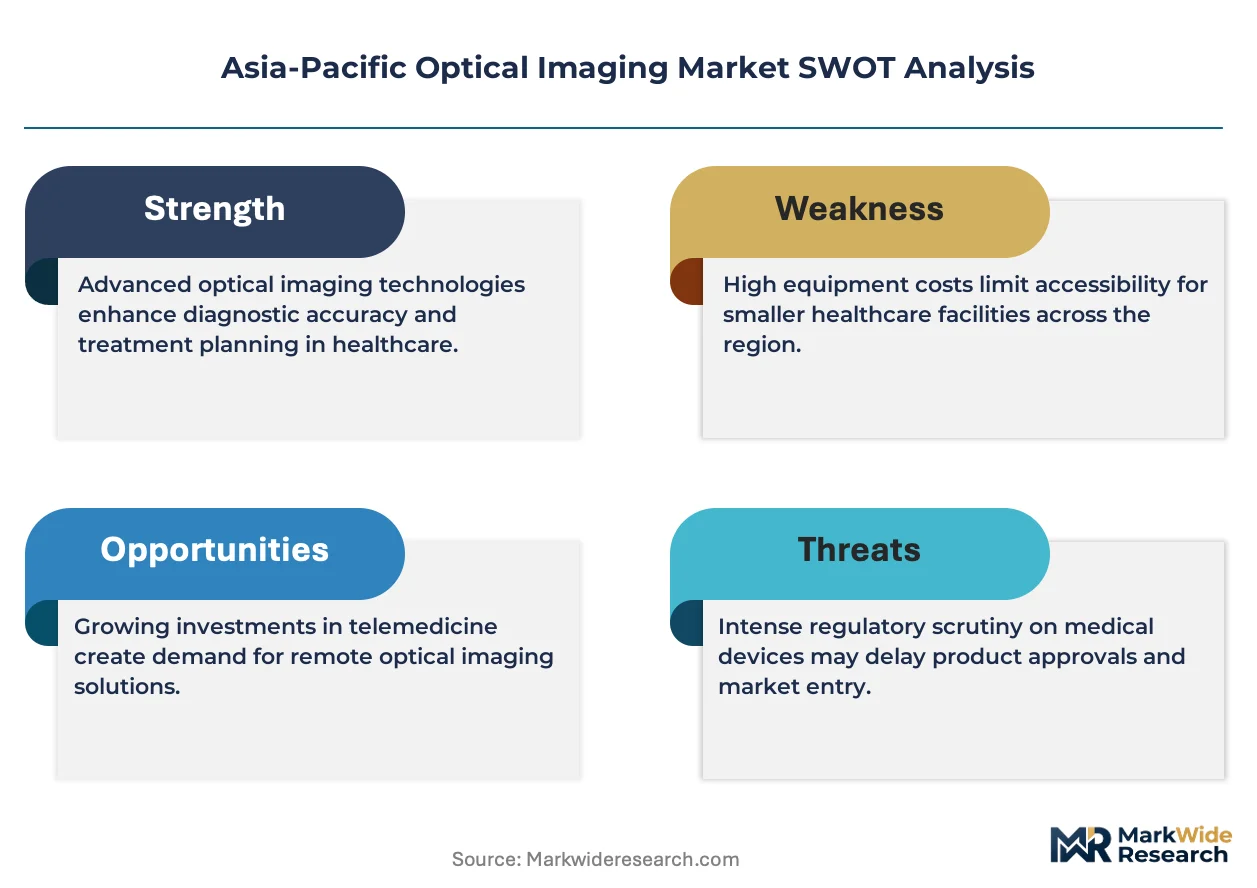
Hospital procurement consolidation across Asia-Pacific is compressing vendor margins while favoring integrated platform providers capable of multi-site standardization and unified service contracts. Tier-one cities in China and metropolitan Japan are driving this structural shift as ophthalmology networks expand screening volumes.
Growth Catalysts
- India's PLI scheme:The production-linked incentive framework for medical device manufacturing is accelerating domestic optical imaging assembly capacity and reducing import dependency for diagnostic equipment.
- Ophthalmology clinic networks:China's tier-one cities are scaling high-volume screening environments that demand specialized diagnostic platforms with rapid throughput capabilities.
- Multispectral imaging:Precision agriculture and pharmaceutical quality control applications are expanding the fastest-growing technology category beyond traditional clinical endpoints.
Market Restraints
- Precision optics input costs:German and Japanese optical component suppliers command premium pricing for specialized lenses and sensors, constraining margin flexibility for system integrators.
- PMDA validation timelines:Japan's pharmaceutical and medical device agency enforces stringent optical performance standards that extend product registration cycles and delay regional launches.
- Computed tomography substitution:Advanced CT modalities with optical fusion capabilities are displacing standalone optical coherence tomography in certain diagnostic workflows.
Strategic Opportunities
- India's tier-two hospital expansion:Secondary cities present underpenetrated demand for mid-range endoscopic systems as domestic manufacturing capacity matures under CDSCO harmonization frameworks.
- AI-integrated diagnostics:Machine learning algorithms converging with optical coherence tomography are enabling automated pathology detection in high-volume screening environments.
- Australia's TGA streamlined pathways:Conformance assessment procedures for Class II medical imaging devices are accelerating market access for innovative platform developers.
Industry Challenges
- Optical engineering talent scarcity:Specialized expertise in sub-micron sensor calibration and near-infrared system design remains concentrated in Japan and Germany, constraining regional R&D scaling.
- Legacy hospital IT integration:PACS and EMR compatibility requirements are extending deployment timelines and inflating implementation costs for new platform installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Optical Imaging Market |
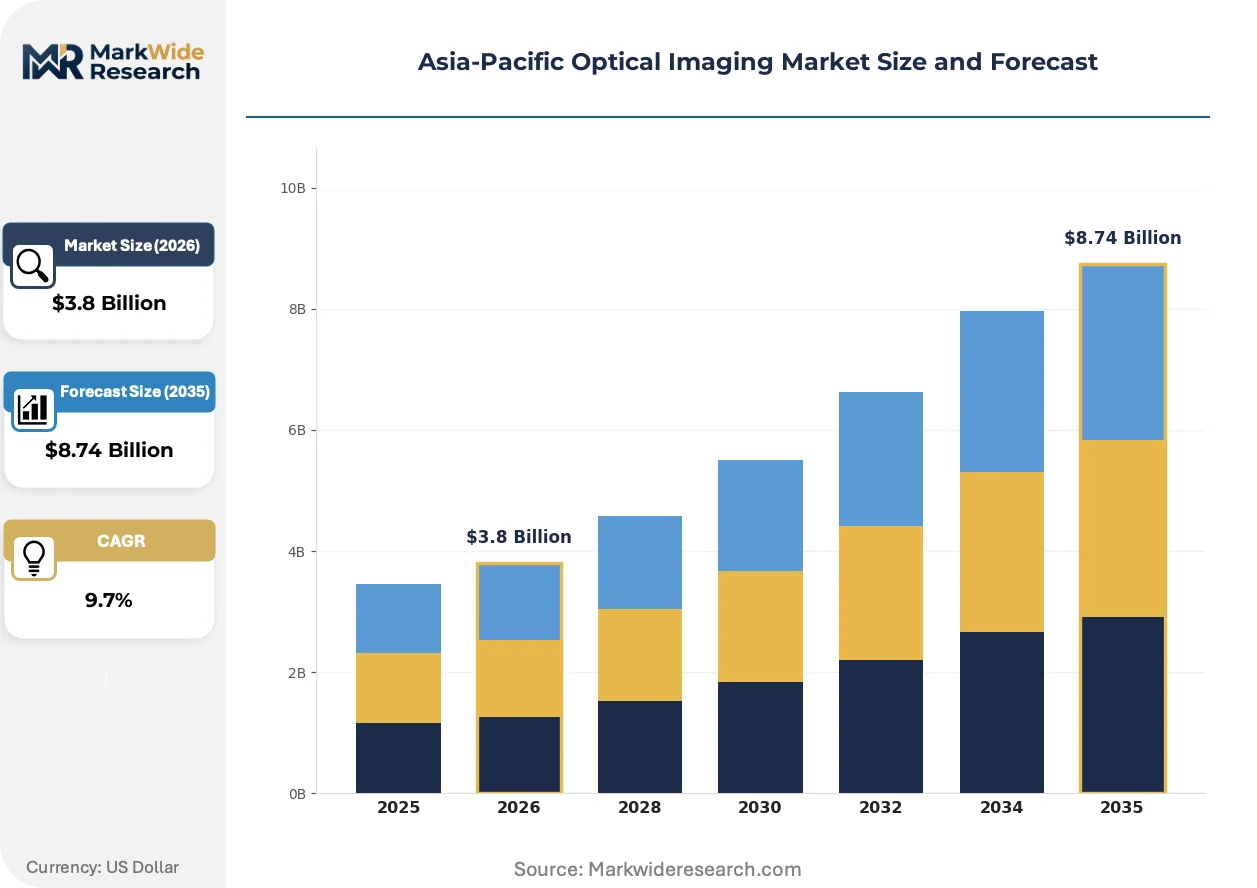
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoscopes, Microscopes, Imaging Sensors, Cameras Application: Medical Diagnostics, Research, Industrial Inspection, Quality Control Technology: Fluorescence Imaging, Confocal Imaging, Optical Coherence Tomography, Multispectral Imaging End User: Hospitals, Research Laboratories, Clinics, Pharmaceutical Companies |
| Companies Covered | Canon Medical Systems Corporation, Topcon Corporation, Carl Zeiss Meditec AG, Olympus Corporation, Leica Microsystems, Bruker Corporation, Cytoviva Inc., Heidelberg Engineering Inc., ASE Optics Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Optical Imaging Market Strategic Shifts
Optical imaging architectures are converging around computational enhancement and miniaturization, with sensor fusion and edge analytics redefining performance benchmarks across clinical and industrial endpoints.
Swept-source optical coherence tomography is unifying anterior and posterior segment examination capabilities into single-platform configurations. Ophthalmology clinic networks in Shanghai and Tokyo are adopting these consolidated systems to reduce capital footprints and streamline technician training protocols. The technology is compressing equipment procurement cycles by eliminating redundant specialty-device purchases across screening and surgical planning workflows.
China's NMPA has introduced accelerated review pathways for Class II medical imaging devices that demonstrate substantial equivalence to approved predicate systems. This regulatory shift is shortening time-to-market for domestic innovators and pressuring multinational registrants to localize clinical validation studies. Domestic manufacturers in Suzhou and Shenzhen are leveraging these streamlined procedures to challenge incumbent positions in mid-range endoscopy segments.
Service unbundling is separating hardware acquisition from maintenance and software subscription components across Asia-Pacific hospital procurement. Large health networks in Australia and South Korea are negotiating multi-year performance contracts that shift uptime risk to vendors while retaining capital expenditure flexibility. This model is most visible in Japan, where METI-promoted lifecycle cost accounting is displacing traditional upfront purchase evaluation frameworks.
Asia-Pacific Optical Imaging Market Segmentation
Segmentation reveals distinct procurement patterns across Asia-Pacific optical imaging. Hospital networks prioritize platform consolidation while industrial users demand modular sensor configurations. Understanding these divides clarifies where upgrade cycles concentrate versus where replacement timelines stretch.
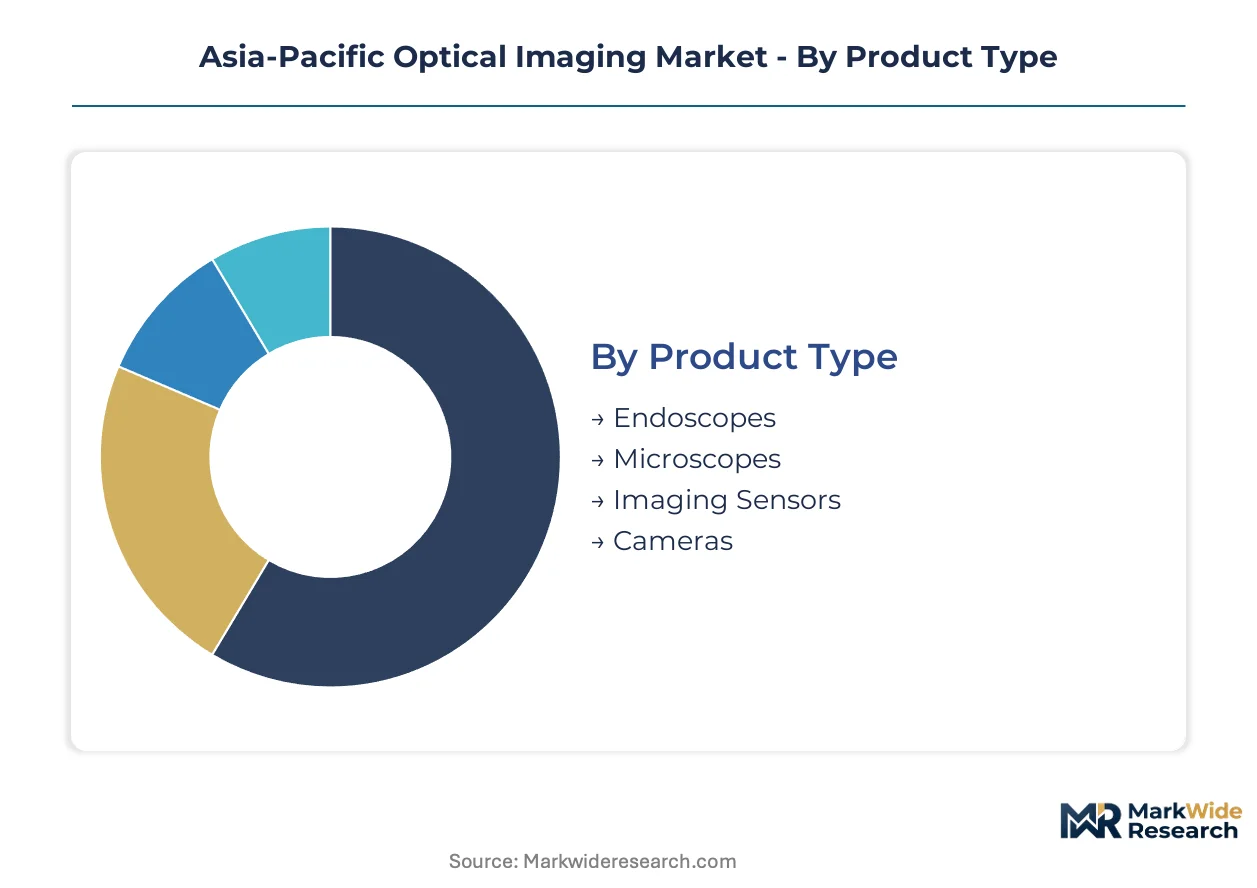
Product Type:
Upgrade cycles vary sharply by capital intensity and sensor obsolescence rates across hardware categories.
- Endoscopes:Flexible and rigid configurations with CMOS sensor arrays enabling 4K visualization. China's tier-one hospitals are replacing fiber-optic legacy systems with video endoscopy platforms as NMPA streamlines Class II approvals. Procurement concentrates in gastroenterology and pulmonology departments within Shanghai and Beijing hospital networks.
- Imaging Sensors:CCD and CMOS detectors with sub-micron spatial resolution for system integration. India's PLI scheme is accelerating domestic assembly capacity for mid-range sensors targeting tier-two hospital expansion. CDSCO harmonization is reducing import dependency for diagnostic equipment manufacturers in Pune and Hyderabad.
- Microscopes:Surgical and pathology platforms with precision optics for tissue examination.
- Cameras:Industrial and clinical-grade capture devices for documentation and analysis workflows.
Volume placements concentrate in Endoscopes; the faster expansion belongs to Imaging Sensors.
Application:
Cost tier differentiation separates premium diagnostic installations from scaled research and industrial deployments.
- Medical Diagnostics:Clinical imaging for disease detection and treatment planning across ophthalmology, gastroenterology, and pathology. Japan's PMDA enforces stringent optical performance standards that extend registration timelines for new platform launches. Hospital procurement consolidation across Tokyo and Osaka is compressing vendor margins while favoring integrated multi-site service contracts.
- Industrial Inspection:Semiconductor and electronics quality assurance with automated defect detection. China's Suzhou and Shenzhen manufacturing clusters are driving demand for high-throughput optical systems as domestic chip fabrication scales. MIIT standards alignment is accelerating substitution of imported inspection platforms.
- Research:Laboratory imaging for biological and materials science investigations.
- Quality Control:Pharmaceutical and food safety verification with spectral analysis capabilities.
Medical Diagnostics commands the largest installed base; Industrial Inspection is climbing the fastest on semiconductor localization.
Technology:
Application maturity determines whether segments face replacement pressure or greenfield expansion.
- Optical Coherence Tomography:Interferometric depth-resolved imaging for ophthalmic and intravascular diagnosis. Swept-source configurations are unifying anterior and posterior segment capabilities into single-platform systems across Shanghai and Tokyo clinic networks. The technology compresses procurement cycles by eliminating redundant specialty-device purchases.
- Multispectral Imaging:Wavelength-resolved capture for precision agriculture and pharmaceutical quality control. Australia's TGA streamlined pathways are accelerating market access for innovative platform developers in agricultural monitoring applications. This category is expanding most quickly beyond traditional clinical endpoints.
- Fluorescence Imaging:Contrast-enhanced visualization for surgical guidance and molecular research.
- Confocal Imaging:Optical sectioning microscopy for cellular and tissue-level analysis.
Optical Coherence Tomography dominates current revenue pools; Multispectral Imaging shows the steepest expansion trajectory.
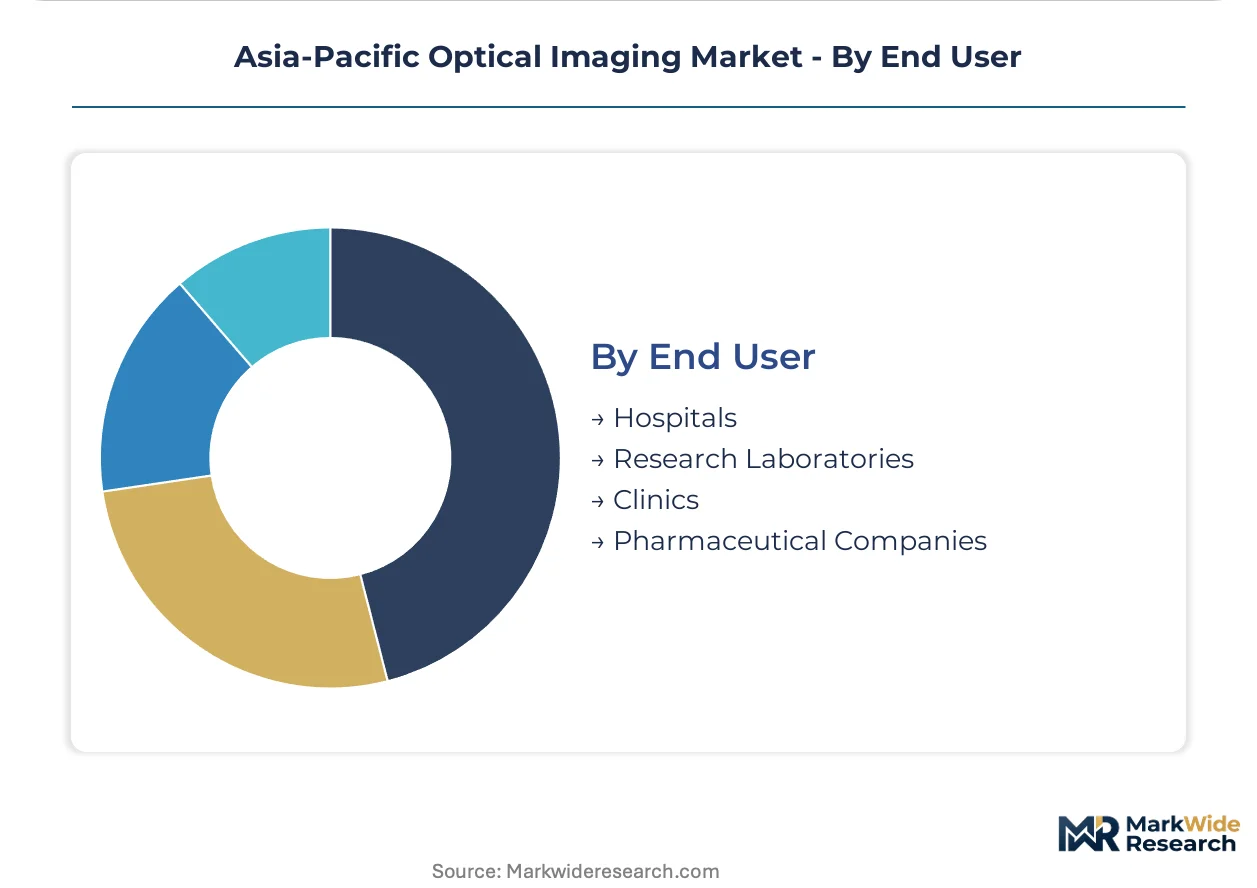
End User:
Customer type dictates procurement sophistication, contract structure, and service integration requirements.
- Hospitals:Acute care facilities with multi-department imaging needs and centralized capital planning. Australia's large health networks are negotiating multi-year performance contracts that shift uptime risk to vendors while retaining expenditure flexibility. METI-promoted lifecycle cost accounting in Japan is displacing traditional upfront purchase evaluation frameworks.
- Pharmaceutical Companies:High-throughput screening and quality verification operations with standardized protocols. South Korean biopharma clusters are driving demand for automated pathology detection integrated with machine learning algorithms. This segment is gaining share fastest on AI convergence with optical platforms.
- Research Laboratories:Academic and institutional facilities with diverse experimental requirements.
- Clinics:Outpatient and specialty diagnostic centers with focused service offerings.
Hospitals anchor volume demand; Pharmaceutical Companies are expanding most quickly on screening automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision optics feedstock anchors the Asia-Pacific optical imaging supply chain, with specialized lens assemblies and sensor substrates flowing through regional distribution nodes before system integration.
China
Ophthalmology clinic networks in Shanghai and Beijing are scaling high-volume screening environments that demand rapid-throughput diagnostic platforms. The NMPA accelerates domestic innovation through streamlined approval pathways for Class II medical imaging devices. Suzhou and Shenzhen manufacturing clusters are leveraging these procedures to challenge incumbent positions in mid-range endoscopy segments.
Japan
Tokyo and Osaka hospital procurement consolidation is compressing vendor margins while favoring integrated multi-site service contracts. The PMDA enforces stringent optical performance standards that extend product registration cycles and delay regional launches. METI-promoted lifecycle cost accounting is displacing traditional upfront purchase evaluation frameworks across Kanto health networks.
India
Tier-two hospital expansion in Pune and Hyderabad presents underpenetrated demand for mid-range endoscopic systems. The PLI scheme accelerates domestic optical imaging assembly capacity and reduces import dependency for diagnostic equipment. CDSCO alignment with international harmonization frameworks is maturing manufacturing capabilities in Maharashtra and Telangana.
Australia
Large health networks in Sydney and Melbourne are negotiating multi-year performance contracts that shift uptime risk to vendors. The TGA streamlined pathways accelerate market access for innovative platform developers in Class II medical imaging. Conformance assessment procedures are shortening validation timelines for emerging diagnostic technologies.
South Korea
Biopharma clusters in Seoul and Busan are driving demand for automated pathology detection integrated with machine learning algorithms. The MFDS maintains alignment with international medical device standards while supporting domestic innovation. Pharmaceutical companies are emerging as a concentrated growth channel for high-throughput screening platforms.
Asia-Pacific Optical Imaging Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue AI-integrated diagnostics and service unbundling models. The vendor base stratifies across three tiers: precision optics specialists with captive sensor supply, integrated platform providers with multi-site service capabilities, and domestic assemblers leveraging regulatory acceleration. Consolidation pressure favors players capable of unified procurement contracts across hospital networks. Two dominant competitive moves are reshaping positioning: backward integration into optical component supply and geographic expansion through localized clinical validation partnerships.
Within the precision optics tier, Canon Medical Systems Corporation and Carl Zeiss Meditec AG exemplify established archetypes with regional service infrastructure. Topcon Corporation occupies a specialized position in ophthalmology diagnostic platforms designed for high-volume screening environments. Among Asia-Pacific-based fabricators, Olympus Corporation anchors the endoscopy segment with legacy fiber-optic replacement cycles accelerating across Chinese tier-one hospitals.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| Topcon Corporation |
| Carl Zeiss Meditec AG |
| Olympus Corporation |
| Leica Microsystems |
| Bruker Corporation |
| Cytoviva Inc. |
| Heidelberg Engineering Inc. |
| ASE Optics Inc. |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between NMPA-registered Class II devices and unregistered imports manifests in pricing premiums exceeding 40 percent and supply chain segregation between validated domestic assemblers and gray-market distributors. Japanese and German precision optics feedstock anchors premium tiers while Indian PLI-subsidized assembly lines compress mid-range price floors.
Pricing Analysis
Warranty and service-bundling unbundling separates hardware acquisition from multi-year uptime guarantees across Asia-Pacific hospital procurement. Three-tier pricing structure across premium, standard, and economy levels reflects PMDA validation status, sensor resolution grade, and software subscription inclusion. Cost compression in mid-range endoscopy stems from Suzhou manufacturing clusters scaling CMOS sensor assembly. Tier-two hospitals in India exhibit highest price sensitivity; Tokyo ophthalmology networks prioritize optical performance over capital outlay.
Supply Chain Analysis
ISO 13485 and NMPA Class II qualification gating restricts component sourcing to certified German lens suppliers and Japanese sensor fabricators. Feedstock draws from Schott AG precision glass in Germany, Sony CMOS substrates from Kumamoto, and rare-earth optical coatings from Chinese refineries. Single-source vulnerability concentrates in specialized interferometric sensors for swept-source OCT platforms. Distribution runs through regional system integrators in Shanghai and Singapore before hospital installation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Optical engineering talent scarcity in sub-micron calibration and near-infrared system design props pricing for precision-tier equipment despite manufacturing automation advances.
For Market Incumbents: Anticipate displacement pressure from AI-integrated diagnostics by embedding machine learning modules into existing OCT platforms and securing exclusive data partnerships with Shanghai clinic networks. Backward integration into captive sensor supply through joint ventures with Kumamoto fabricators reduces German component dependency. Defend service revenue streams by converting installed bases in Japan to performance-based contracts with uptime penalties. For New Entrants and Emerging Players: CDSCO harmonization in India opens a window for mid-range endoscopic systems targeting Pune and Hyderabad tier-two hospital expansion. White-space concentration sits in pharmaceutical quality control multispectral platforms for South Korean biopharma clusters. Go-to-market leverage through Australia's TGA streamlined pathways accelerates Class II registration without predicate-matching delays. For Investors and Strategic Acquirers: Re-rating potential sits with AI-integrated diagnostic platform developers given NMPA accelerated review pathway expansion across the analysis window. Acquisition focus targets domestic assemblers with validated optical component supply relationships and installed base conversion capability. Signal to monitor: PMDA validation timeline compression for predicate-substantial-equivalence determinations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Supply | Captive CMOS sourcing from Kumamoto fabricators insulates margin from German lens premium escalation. |
| AI Companion Software Development | Machine learning pathology detection embedded in OCT platforms commands subscription pricing from Tokyo clinic networks. |
| CDSCO Harmonization Compliance Investment | Class II device registration alignment accelerates market access for Indian tier-two hospital procurement. |
| Performance-Based Service Contracting | Uptime risk transfer to vendors under METI-promoted lifecycle accounting displaces upfront purchase evaluation. |
| Multispectral Platform Expansion | Agricultural monitoring applications through Australia's TGA pathways diversify beyond clinical revenue concentration. |
Study Parameters
Document review covered NMPA registration databases, PMDA approval summaries, and CDSCO harmonization guidelines, complemented by interviews with hospital procurement managers, biomedical engineers at Tokyo ophthalmology networks, GPO contracts administrators, and precision optics sourcing directors. Secondary validation drew from customs import records for optical components, METI medical device trade statistics, and TGA conformance assessment publications. Bottom-up demand modeling triangulated against top-down healthcare expenditure forecasts.
Segmented outputs across product type, application, technology, and end-user dimensions calibrated penetration rates against hospital procurement consolidation patterns. CAGRs derived from installed base replacement cycles, clinic network expansion trajectories, and semiconductor quality assurance automation adoption. Forecast inputs incorporated PLI scheme capacity buildout timelines and NMPA streamlined pathway approval velocity.
The model assumes a particular technology adoption path; alternative pathways for swept-source OCT unification would alter the outlook if anterior-posterior segment consolidation stalls. Forecasts reflect assumptions regarding regulatory divergence persistence and optical component supply concentration. A model refresh is warranted upon material change in PMDA validation timeline policy or German-Japanese sensor supply agreement restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Fiber Optical Receivers Market
Optics
Excimer Laser Market
Optics
Latin America Optical Imaging Market
Optics
Laser Transmitter Market
Optics
Global Enhanced Vision System Market
Optics
Global Nanophotonics Market
Optics
Optical Fiber Market
Optics
Photostimulation Lasers Market
Optics
Smartphone Lenses Market
Optics
Polymeric Optical Fiber Market
Optics
Fiber Optic Preform Market
Optics
Optical Wavelength Service Market
Optics
Optical Receivers Market
Optics
Picosecond Lasers Market
Optics
Sports Optics Market
Optics
Collimating Lens Market