
 Asia Pacific Smartphone Camera Lens Market | 2026-2036
Asia Pacific Smartphone Camera Lens Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Smartphone Camera Lens Market Outlook
Market Context
Optical engineering talent shortages in Taiwan and Japan is reorganizing supply chain priorities across the Asia Pacific Smartphone Camera Lens Market. Largan Precision leverages its dominance in plastic aspheric lens molding to anchor high-volume contracts with flagship smartphone assemblers. Sunny Optical Technology sustains manufacturing scale through backward integration into wafer-level optics, while AAC Technologies competes on actuator and voice coil motor integration that reduces module thickness for slim handset designs.
Technical Definition and Segment Structure
Asia Pacific smartphone camera lens denotes precision-engineered refractive assemblies mounted within mobile device chassis, typically featuring five to eight molded elements with sub-micron surface tolerances and anti-reflective dielectric coatings to direct photons onto CMOS sensors for computational photography pipelines. Wide-angle configurations lead unit shipments as OEMs standardize ultra-wide modules across mid-tier price bands, while periscope telephoto designs command concentrated margin pools in flagship tiers due to complex prism-folded optical paths. Image stabilization technology differentiates premium offerings through sensor-shift and lens-shift architectures that compensate for hand tremor during low-exposure capture.
Regulatory Environment and Outlook
China's MIIT enforces GB standards for electromagnetic compatibility and optical performance testing that filter substandard camera module suppliers from domestic smartphone bill-of-materials. Japan's METI coordinates JIS standards for lens surface quality and environmental durability that shape export qualification protocols for Korean and Vietnamese assembly plants. India's BIS certification requirements for electronic components, including camera modules under compulsory registration, tighten market access for uncertified imports. Stakeholders must weigh regulatory compliance costs against localization incentives when situating lens grinding and coating operations across the region.
Market Dynamics
Computational photography pipelines are decomposing traditional optical specifications across the Asia Pacific Smartphone Camera Lens Market, forcing lens makers to optimize for AI-driven image synthesis rather than pure optical fidelity alone.
Growth Catalysts
- MIIT GB Standards Revision:Stricter camera module quality certifications in China are filtering substandard suppliers and consolidating procurement toward certified domestic and regional vendors.
- Multi-Lens Arrays:Content creators across Southeast Asia demand versatile capture capabilities, pulling smartphone OEMs toward triple and quad-camera configurations as baseline specifications.
- India PLI Scheme:Production-linked incentives for electronics manufacturing attract domestic assembly of premium camera modules for export-bound smartphone brands.
Market Restraints
- Optical Glass Price Volatility:Rare earth element dependencies in high-index glass formulations expose lens makers to input cost swings from concentrated mining geographies.
- Taiwan-Japan Talent Concentration:Optical engineering expertise clusters in limited metropolitan zones, creating single-point-of-failure risks for precision grinding and coating operations.
- Periscope Module Complexity:Prism-folded optical paths require sub-micron alignment tolerances that constrain yield rates and extend production cycles for telephoto designs.
Strategic Opportunities
- Vietnam Assembly Expansion:Smartphone final assembly migration into northern industrial provinces creates demand for localized camera module integration facilities.
- Wafer-Level Optics Convergence:Semiconductor fabrication techniques merging with lens production enable thinner form factors and direct sensor bonding.
- BIS Certification Arbitrage:India's compulsory registration scheme for electronic components creates first-mover advantages for certified suppliers in a market tightening import restrictions.
Industry Challenges
- Actuator Integration Complexity:Voice coil motor and sensor-shift stabilization mechanisms demand cross-disciplinary expertise spanning mechanical, electrical, and software engineering functions.
- Coating Equipment Capex:Anti-reflective dielectric deposition systems require multi-million dollar vacuum chamber investments with extended depreciation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Smartphone Camera Lens Market |
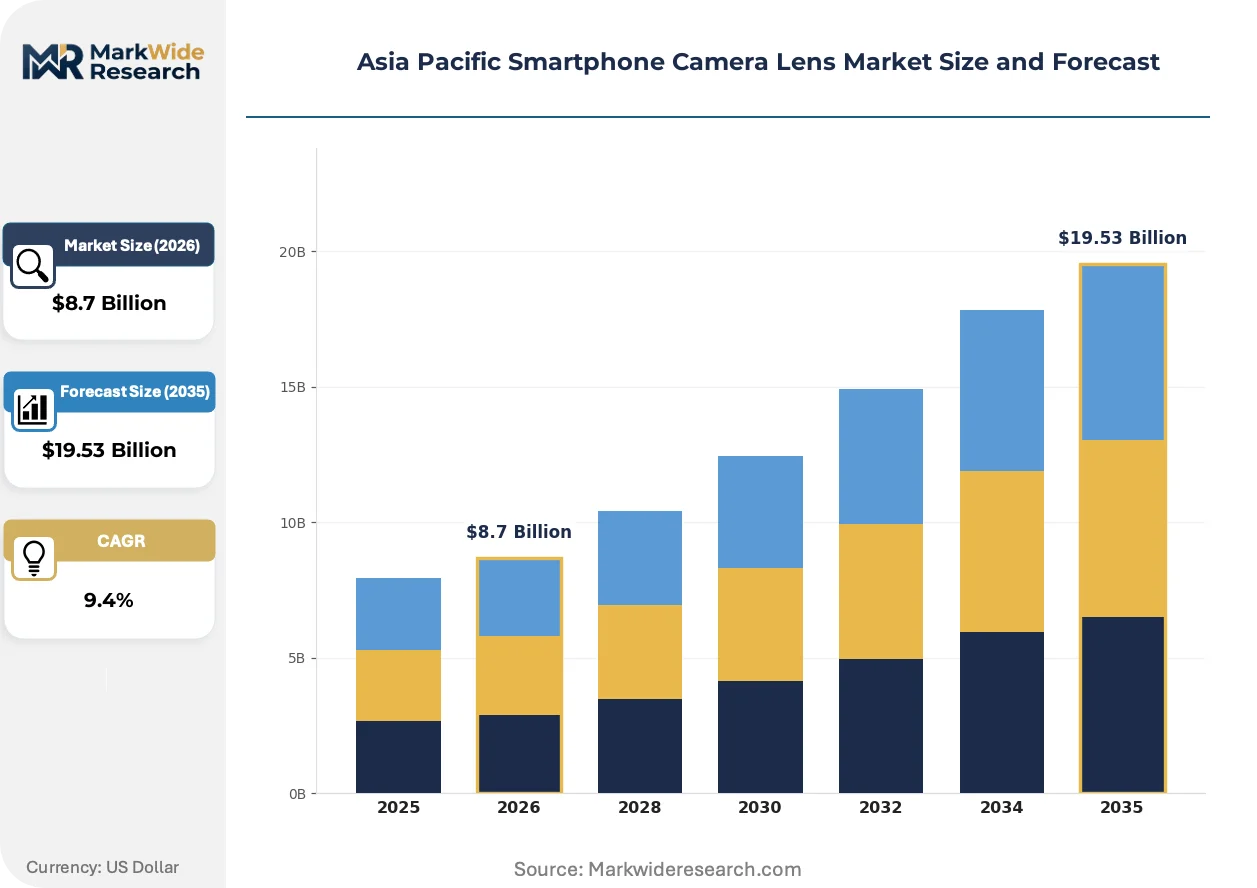
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wide-Angle, Telephoto, Macro, Fish Eye Technology: Optical Zoom, Digital Zoom, Image Stabilization, Night Mode End User: Professional Photographers, Content Creators, Everyday Users, Gamers Material: Glass, Plastic, Hybrid, Coated |
| Companies Covered | Largan Precision Company Limited, Sunny Optical Technology Company Limited, AAC Technologies, Genius Electronic Optical (GSEO), Kantatsu Co. Ltd, Sekonix, Asia Optical, Ability Opto-Electronics Technology Co. Ltd, Cowell Optics, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Smartphone Camera Lens Market Strategic Shifts
Optical hardware is surrendering standalone value to software-defined imaging stacks, compressing the traditional lens specification hierarchy while elevating module-level integration capabilities as the primary competitive differentiator.
Plastic aspheric lens molding is decomposing the cost structure of high-volume smartphone optics by replacing ground glass elements with precision-injected polymers that achieve comparable surface tolerances at scale. Mid-tier OEMs across India and Southeast Asia are adopting these molded arrays aggressively, collapsing the premium-mid pricing gap that previously separated flagship camera systems from mass-market configurations. This materials transition is decomposing the historical correlation between lens element count and perceived image quality, forcing suppliers to demonstrate computational compatibility rather than optical purity.
China's MIIT enforcement of revised GB standards for electromagnetic compatibility and optical performance testing is restructuring supplier qualification protocols across the Asia Pacific region. Domestic smartphone assemblers now demand documented compliance certificates before module integration, elevating regulatory affairs capabilities from administrative function to core competitive requirement. Korean and Vietnamese assembly plants serving export markets are adapting their incoming inspection procedures to match these certification thresholds, creating regional harmonization pressure.
Smartphone brand procurement teams are consolidating camera module vendor relationships from multi-source arrangements toward dual-source or sole-source partnerships with vertically integrated suppliers. This concentration pattern compresses negotiation leverage for pure-play lens makers while rewarding module houses with captive actuator, filter, and assembly capabilities. The shift is most visible in China's Guangdong and Jiangsu provinces, where flagship smartphone programs now require end-to-end module accountability from fewer qualified suppliers.
Asia Pacific Smartphone Camera Lens Market Segmentation
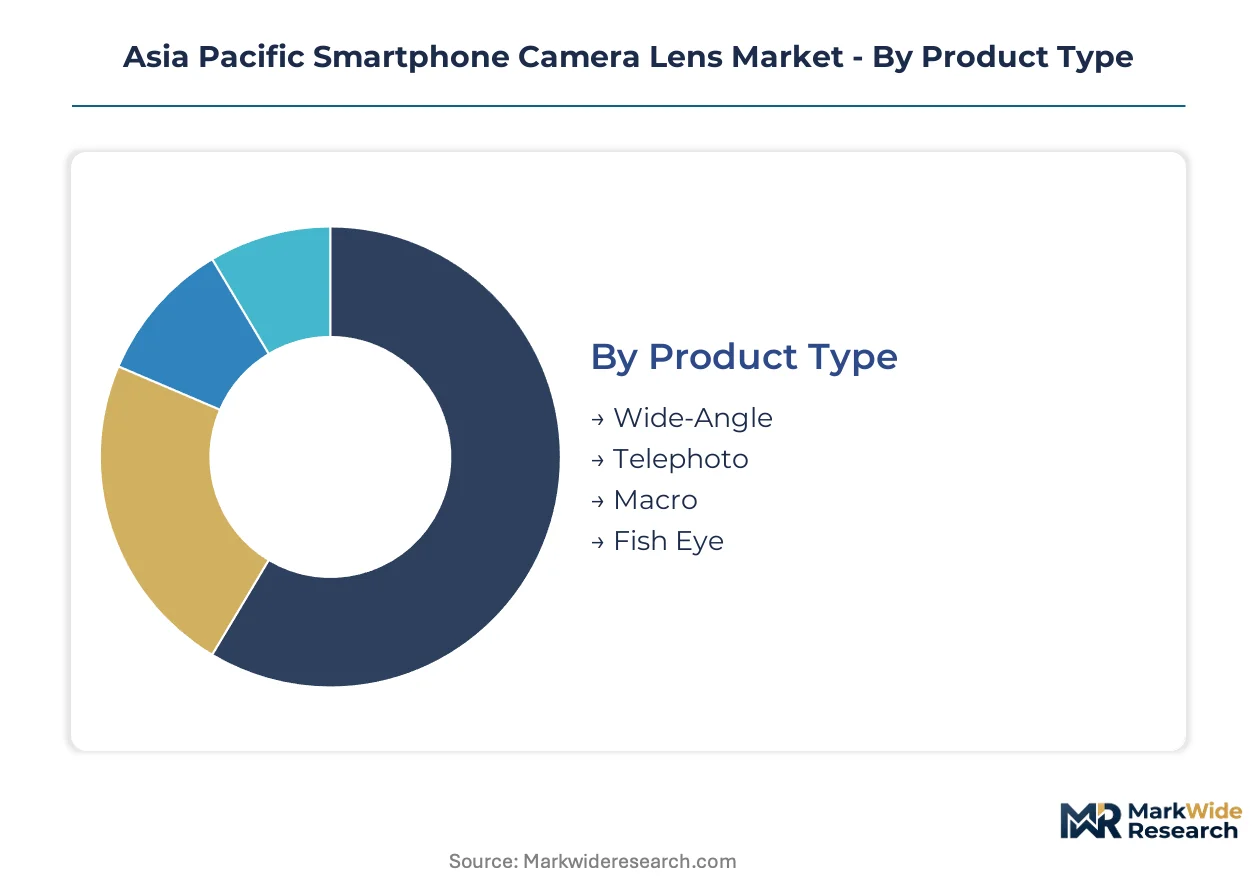
Segmentation reveals where optical engineering investments concentrate and which user behaviors reshape procurement priorities across the Asia Pacific smartphone camera lens supply chain. Lens suppliers align R&D roadmaps with distinct performance tiers rather than pursuing one-size-fits-all specifications.
Product Type:
Margin pools concentrate in configurations that balance optical complexity with manufacturing yield, rewarding suppliers who master specific light-bending architectures.
- Wide-Angle:Five to seven molded elements capture expansive fields of view with minimal edge distortion. OEMs in Vietnam and Indonesia standardize these modules across mid-tier handsets, pulling volume from dedicated point-of-view accessories.
- Telephoto:Prism-folded optical paths achieve 3x to 10x magnification within slim chassis constraints. Chinese flagship assemblers demand these for periscope integration, though alignment tolerances below one micron suppress yield rates and elongate production cycles.
- Macro:Short focal lengths enable centimeter-scale focusing for product photography and document capture. Indian content creators drive sporadic demand spikes during festival commerce seasons.
- Fish Eye:Extreme barrel distortion creates immersive spherical perspectives for gaming and social media effects. Niche volume concentrates in Korean smartphone accessory channels.
The dominant share belongs to Wide-Angle, while Telephoto is closing the gap fastest.
Technology:
Computational pipelines now determine which hardware capabilities OEMs prioritize, shifting value from pure optical performance to sensor-processor integration.
- Optical Zoom:Mechanical lens movement preserves image quality across focal lengths through physical element repositioning. Samsung and Chinese flagship programs sustain procurement of these heavier, more complex modules despite space constraints.
- Digital Zoom:Sensor cropping and algorithmic upscaling substitute for moving parts in cost-optimized designs. Southeast Asian mass-market OEMs default to this approach, accepting resolution trade-offs for thinner form factors.
- Image Stabilization:Sensor-shift and lens-shift architectures compensate hand tremor through micro-actuator control. Japanese component suppliers dominate voice coil motor integration for this function.
- Night Mode:Multi-frame stacking and noise reduction algorithms demand lenses with wide apertures and minimal flare. Chinese MIIT certification protocols now test low-light performance as a graded metric.
Optical Zoom retains the revenue concentration, though Image Stabilization is expanding most quickly as standard equipment.
End User:
User archetypes fragment procurement specifications, with professional demands bleeding into mainstream hardware faster than historical replacement cycles.
- Professional Photographers:Raw capture capability, manual control interfaces, and optical fidelity dominate lens selection criteria. These users cluster in Tokyo, Seoul, and Shanghai creative industries, purchasing flagship devices primarily for camera systems.
- Content Creators:Versatile focal range and stabilization for handheld video drive hardware preferences. Southeast Asian TikTok and YouTube ecosystems generate concentrated demand for multi-lens arrays with seamless switching.
- Everyday Users:Social sharing convenience and point-and-shoot reliability shape satisfaction. Volume concentrates here but price elasticity constrains supplier margins.
- Gamers:AR overlay accuracy and low-lens-distortion tracking enable immersive mobile experiences. Korean and Chinese gaming handset specialists specify these modules for e-sports-optimized devices.
Content Creators command the steepest expansion trajectory, while Everyday Users still represent the volume anchor.
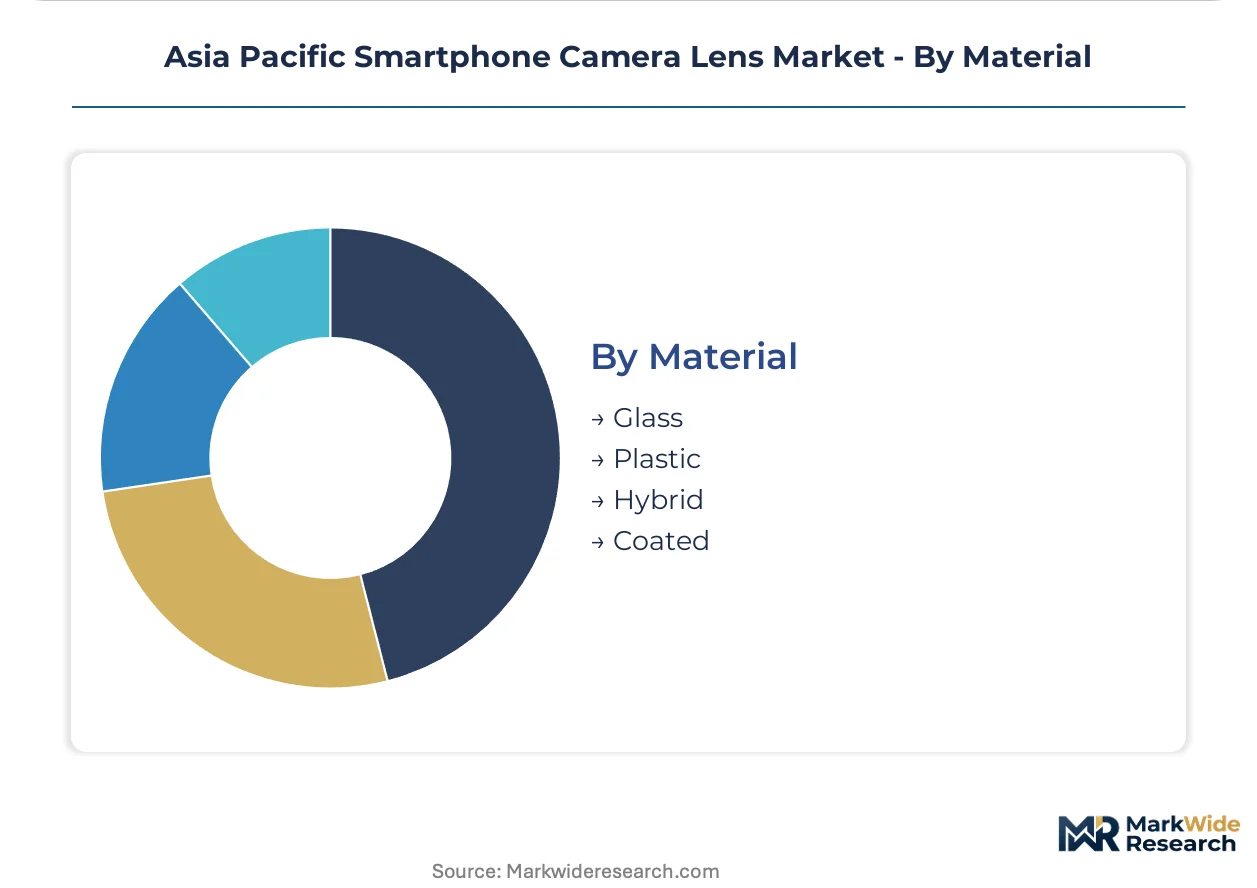
Material:
Cost structures and thermal performance separate material choices, with hybrid approaches gaining ground as pure solutions hit physical limits.
- Glass:Ground and polished optical elements deliver superior refractive index stability and scratch resistance. Japanese and Taiwanese suppliers maintain grinding expertise for high-index formulations used in premium telephoto designs.
- Plastic:Precision-injected aspheric lenses achieve comparable surface tolerances at scale. Chinese molding houses dominate high-volume wide-angle production for domestic and export-bound OEMs.
- Hybrid:Glass-plastic combinations balance optical performance with weight and cost. These configurations are becoming default for flagship tier modules seeking differentiation without periscope complexity.
- Coated:Anti-reflective dielectric layers reduce ghosting and flare across all substrate types. Vacuum deposition equipment requirements create barrier to entry for new coating facilities.
Plastic holds the volume leadership, though Hybrid is gaining share fastest as flagship programs seek performance-cost optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Chinese and Japanese optical clusters while assembly margins compress in Vietnamese and Indian integration facilities, creating a two-tier value capture structure across the Asia Pacific Smartphone Camera Lens Market.
China
Domestic smartphone assemblers drive module procurement volumes through Guangdong and Jiangsu manufacturing belts. MIIT enforces revised GB standards for electromagnetic compatibility and optical performance testing that filter uncertified suppliers from flagship bill-of-materials. Shenzhen and Dongguan anchor wafer-level optics convergence where semiconductor fabrication techniques merge with precision lens production.
Japan
Optical engineering expertise clusters in metropolitan zones around Tokyo and Osaka, creating single-point-of-failure risks for precision grinding operations. METI coordinates JIS standards for lens surface quality and environmental durability that shape export qualification protocols for regional assembly plants. Nagoya-based component suppliers dominate voice coil motor integration for image stabilization functions.
India
Domestic assembly of premium camera modules accelerates for export-bound smartphone brands under electronics manufacturing incentives. BIS certification requirements for electronic components tighten market access for uncertified imports through compulsory registration schemes. Tamil Nadu and Karnataka industrial corridors attract module integration facilities serving Southeast Asian handset markets.
Vietnam
Smartphone final assembly migration into northern industrial provinces creates demand for localized camera module integration facilities. Thai Nguyen and Bac Ninh manufacturing zones concentrate labor-intensive assembly operations while precision lens grinding remains imported. Regional procurement teams adapt incoming inspection procedures to match Chinese MIIT certification thresholds for export-bound production.
South Korea
Gaming handset specialists specify low-distortion tracking modules for e-sports-optimized devices, pulling optical customization demand. Seoul-based procurement teams consolidate vendor relationships toward dual-source partnerships with vertically integrated module houses. Gyeonggi-do assembly plants serving global flagship programs demand end-to-end module accountability from qualified suppliers.
Asia Pacific Smartphone Camera Lens Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Asia Pacific Smartphone Camera Lens Market, with precision grinding expertise concentrating in Japanese and Taiwanese houses while Chinese molding operations capture high-volume wide-angle production. The vendor structure organizes around three strategic tiers: vertically integrated module houses with captive actuator capabilities, pure-play lens makers specializing in aspheric molding or glass grinding, and assembly-focused integrators serving regional handset brands. Consolidation pressures favor backward integration into wafer-level optics and strategic partnerships that secure voice coil motor supply for stabilization functions.
Among Taiwan-based precision specialists, Largan Precision Company Limited exemplifies the plastic aspheric lens molding archetype that anchors high-volume flagship contracts. Sunny Optical Technology Company Limited occupies a position within the vertically integrated tier, sustaining manufacturing scale through upstream control over wafer-level optics production. AAC Technologies represents the module integration archetype, competing on actuator and voice coil motor convergence that reduces thickness for slim handset designs.
| Leading Market Players |
|---|
| Largan Precision Company Limited |
| Sunny Optical Technology Company Limited |
| AAC Technologies |
| Genius Electronic Optical (GSEO) |
| Kantatsu Co. Ltd |
| Sekonix |
| Asia Optical |
| Ability Opto-Electronics Technology Co. Ltd |
| Cowell Optics |
| Others |
Value Chain & Pricing Dynamics
China's MIIT GB certification regime gates both supply qualification and price differentiation simultaneously, filtering uncertified lens makers from flagship smartphone bill-of-materials while concentrating procurement premiums among compliant domestic and regional vendors. This regulatory filter compresses margins for non-certified suppliers in Vietnam and India assembly corridors while elevating price realization for qualified module houses in Guangdong and Jiangsu.
Pricing Analysis
Pricing spreads widen between Chinese domestic supply and Japanese import tiers, with three-tier pricing structure across premium, standard, and economy levels dominating procurement negotiations. Certification grade under MIIT GB standards and volume scale commitments to flagship OEMs drive price differentiation, while cost compression in standard-tier molded plastic lenses intensifies because of aggressive capacity expansion by Chinese molding houses. Mass-market OEMs in Southeast Asia exhibit highest price sensitivity, whereas Japanese flagship programs demonstrate lowest elasticity for telephoto periscope modules.
Supply Chain Analysis
Rare earth element transit through concentrated mining geographies in China and Myanmar constitutes a critical chokepoint for high-index optical glass formulations. Manufacturing gravity centers on China, Taiwan, and Japan, with supply chains drawing from germanium and lanthanum oxide dependencies for premium refractive elements. Single-source vulnerability concentrates in Taiwanese precision grinding operations for sub-micron surface tolerances. Distribution runs through Shenzhen and Dongguan module integration hubs before final handset assembly in Vietnam and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific smartphone camera lens demand cycles track smartphone replacement waves and content creator hardware upgrade cadences, positioning the market for recovery as Southeast Asian creator economies mature and Indian export assembly scales.
For Market Incumbents: Compound defensive positioning through backward integration into wafer-level optics production and captive voice coil motor supply for stabilization modules. Largan Precision and Sunny Optical must secure actuator technology partnerships before AAC Technologies consolidates module-level integration dominance. Certification investment under revised MIIT GB standards represents the critical lever for maintaining flagship procurement access against emerging Chinese molding houses. For New Entrants and Emerging Players: Anchor in India's BIS certification arbitrage opportunity before compulsory registration schemes fully tighten import restrictions on uncertified camera modules. Vietnam's northern industrial provinces present the most penetrable geography for localized module integration facilities serving export-bound smartphone brands. A go-to-market angle targeting mid-tier OEMs with hybrid glass-plastic lens configurations bypasses periscope complexity barriers while capturing premium-mid price points. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across wafer-level optics convergence as semiconductor fabrication techniques merge with precision lens production. The five-to-ten year viability window favors module houses with end-to-end integration capabilities over pure-play lens makers exposed to procurement consolidation. Acquisition targets should profile vertically integrated suppliers with captive actuator technology and MIIT GB certification credentials. The signal to watch is OEM procurement team consolidation from multi-source to dual-source vendor relationships, indicating preferred supplier status premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Wafer-Level Optics Convergence | Semiconductor fabrication techniques merging with lens production enable thinner form factors for flagship handsets. |
| MIIT GB Certification Investment | Compliance with China's revised electromagnetic compatibility standards gates access to domestic flagship smartphone programs. |
| Voice Coil Motor Integration | Captive actuator supply for image stabilization differentiates module houses in procurement consolidation environments. |
| Vietnam Assembly Localization | Proximity to Thai Nguyen and Bac Ninh smartphone final assembly reduces logistics costs for export-bound production. |
| Hybrid Glass-Plastic Lens Development | Balanced optical performance and weight configurations capture flagship tier differentiation without periscope yield constraints. |
Study Parameters
Cross-validation between primary interviews with optical engineering directors and secondary regulatory filings anchors the qualitative findings in documented certification protocols. Stakeholder consultations encompass lens grinding specialists in Tokyo and Osaka, module procurement leads at Guangdong smartphone assemblers, BIS registration officers in New Delhi, and wafer-level optics R&D heads in Shenzhen. Secondary sources include MIIT GB standard revision documents, METI JIS certification records, India PLI scheme disclosure filings, and customs trade data for optical glass imports. Bottom-up unit shipment estimates triangulate against top-down smartphone production forecasts across the analysis window.
Sensitivity analysis around rare earth element price volatility and periscope module yield rates tests forecast robustness across multiple scenario assumptions. Segmentation dimensions encompass lens configuration type, stabilization technology tier, end-user archetype, and material composition grade, with regional production cluster as an additional industry-specific dimension. CAGRs derive from modeled smartphone replacement cycles and content creator hardware penetration curves, incorporating computational photography pipeline evolution as a demand modifier and India PLI incentive phase adjustments as a supply-side variable.
Material uncertainties — optical glass price swings, Taiwan-Japan talent concentration disruptions, and MIIT regulatory enforcement intensity — sit outside the modeled envelope. Forecasts reflect assumptions around continued smartphone multi-lens array standardization and Southeast Asian creator economy expansion. Practitioners should keep alternative scenarios live as periscope yield improvements and wafer-level optics adoption curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Optical Fiber Raw Material Market
Optics
Fiber Optic Switch Market
Optics
Picosecond Lasers Market
Optics
Photonics Sensor Market
Optics
Fixed Focal Length Lenses Market
Optics
Fiber Optic Connectivity Market
Optics
Latin America Optical Imaging Market
Optics
APAC Smart Glass Market
Optics
US Photonics Market
Optics
Single-Mode Optical Fiber Market
Optics
Smartphone Camera Lenses Market
Optics
Optical Telescope Market
Optics
Optical Lens for Mobile Phone Market
Optics
AR and VR Lens Market
Optics
Fiber Optic Development Tools Market
Optics
3D Optical Microscope Market