
 Smart Vision Systems Market | 2026-2036
Smart Vision Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Vision Systems Market Insights
ISO 10218 safety certification for collaborative robots is reorganizing which vision suppliers qualify for factory deployments. Cognex Corporation leverages deep learning toolkits to sustain premium positioning in semiconductor inspection. Keyence Corporation anchors its dominance through direct sales channels and rapid customization turnaround in Japan and North America. Basler AG competes on camera modularity, offering GigE and USB3 interfaces that integrate with third-party processing stacks.
Smart vision systems combine industrial cameras, embedded sensors, and algorithmic software to capture, process, and interpret visual data for automated decision-making. These systems typically operate at frame rates exceeding 60 fps with sub-pixel measurement accuracy, enabling real-time defect detection and robotic guidance in manufacturing lines. Software incorporating machine learning and computer vision commands expanding margin pools as hardware commoditizes across camera and sensor categories. Industrial automation and autonomous vehicle applications attract the fastest investment, while surveillance remains a mature, price-sensitive segment. Healthcare diagnostic imaging represents an emerging frontier where regulatory clearance timelines currently limit supplier entry.
FDA premarket clearance pathways for AI-enabled diagnostic devices and the EU AI Act's risk-classification framework are tightening validation requirements for vision systems in medical and safety-critical applications. Germany's KBA enforces specific performance standards for automotive camera systems, shaping product development priorities for European road deployments. Stakeholders must monitor how divergent regulatory timelines between North American and European approval bodies affect go-to-market sequencing and R&D resource allocation.
Market Dynamics
ISO 10218 safety certification requirements are reorganizing supplier qualification for collaborative robot deployments, forcing vision system vendors to redesign hardware-software bundles for factory acceptance.
Growth Catalysts
- EU AI Act conformity mandates:Risk-classification frameworks for autonomous decision-making systems are accelerating validation investments across automotive and medical device supply chains in Germany and France.
- Vision-guided robotics:Automotive manufacturers in Stuttgart and Munich are expanding quality inspection automation, pulling embedded camera and processing demand.
- Sub-pixel measurement accuracy:Semiconductor fabrication lines now require 60+ fps frame rates for real-time defect detection, tightening performance specifications for inspection module procurement.
Market Restraints
- Sensor hardware commoditization:GigE and USB3 camera interfaces are standardizing, compressing margin pools for modular camera suppliers.
- FDA premarket clearance timelines:AI-enabled diagnostic devices face 18-36 month validation cycles, limiting supplier entry into healthcare imaging.
- Algorithmic software concentration:Deep learning toolkit development requires specialized talent pools concentrated in Japan and North America, creating geographic supply risk.
Strategic Opportunities
- Healthcare diagnostic imaging:Regulatory clearance backlogs currently block incumbent entry, creating white space for validated first-movers in radiology and pathology applications.
- Japan METI automation incentives:Direct sales channel investments by established players can leverage rapid customization turnaround for semiconductor and electronics manufacturing.
- Edge-AI processing convergence:Embedded sensor-algorithm integration is enabling standalone inspection modules that bypass centralized server dependencies.
Industry Challenges
- Computer vision engineering scarcity:Machine learning deployment for manufacturing lines requires rare combinations of optics, robotics, and software integration skills.
- Legacy MES integration complexity:Third-party processing stack compatibility demands extensive customization for existing factory automation architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Vision Systems Market |
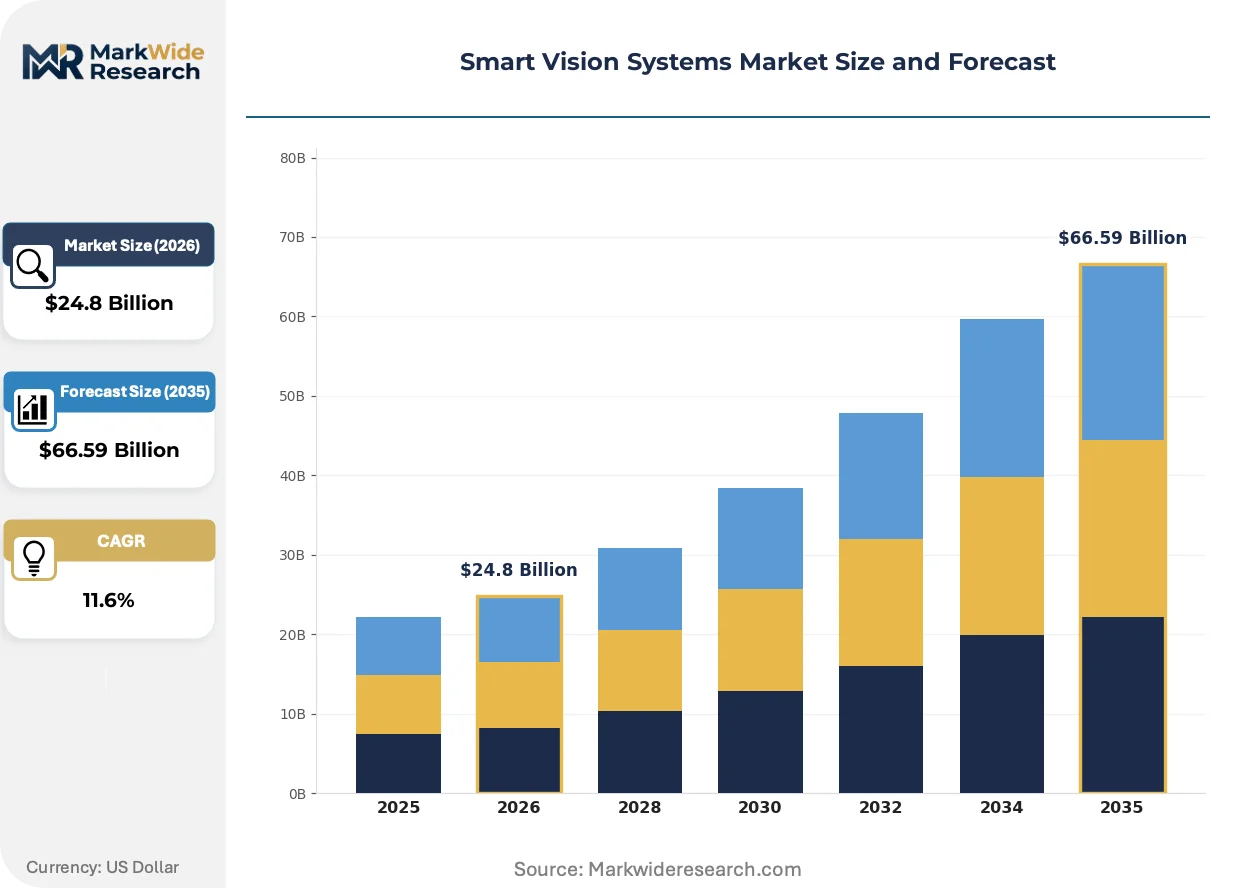
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $66.59 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cameras, Sensors, Software, Hardware Technology: Machine Learning, Image Processing, Computer Vision, Artificial Intelligence Application: Surveillance, Industrial Automation, Autonomous Vehicles, Healthcare End User: Manufacturers, Transportation, Retail, Defense |
| Companies Covered | Cognex Corporation, Keyence Corporation, Basler AG, Teledyne DALSA, Omron Corporation, FLIR Systems, Datalogic S.p.A., National Instruments Corporation, IDS Imaging Development Systems GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Vision Systems Market Trends and Innovations
Deep learning inference at the edge is restructuring how vision systems balance hardware cost against software capability, compressing the traditional camera-server architecture into single-device deployments.
Event-based vision sensors are supplanting frame-based cameras in high-speed inspection applications. Automotive tier-one suppliers in Germany are piloting neuromorphic cameras for quality control at conveyor speeds exceeding 5 meters per second. This architecture is supplanting conventional CMOS arrays by eliminating motion blur without expensive strobing infrastructure.
The EU AI Act's risk-classification framework is mandating conformity assessments for autonomous decision-making systems before CE marking. Medical device manufacturers face expanded documentation requirements for training data provenance and algorithmic transparency. German automotive suppliers are front-loading validation investments to secure KBA performance certifications for camera-based driver assistance systems.
Factory automation buyers are unbundling after-sales service contracts from initial hardware procurement. Semiconductor fabs in Japan and North America now prefer per-inspection pricing models over capital expenditure commitments. This consumption-pattern shift is visible most acutely in Taiwan and South Korea, where foundry operators are pressuring vision suppliers to absorb uptime risk through outcome-based service structures.
Smart Vision Systems Market Segmentation
Smart vision systems fragment across hardware-software boundaries and regulatory risk classes. Buyers prioritize different performance thresholds depending on whether systems feed factory automation, medical diagnostics, or safety-critical mobility applications.
Product Type:
Sensor hardware faces the most acute substitution pressure as interface standardization erodes camera margins and edge-AI integration collapses discrete component stacks.
- Cameras:Industrial cameras with GigE and USB3 interfaces deliver 60+ fps capture for real-time defect detection. Stuttgart automotive manufacturers are pulling demand for modular units that integrate with third-party processing stacks.
- Sensors:Event-based neuromorphic sensors eliminate motion blur without strobing infrastructure at conveyor speeds exceeding 5 meters per second. German tier-one suppliers pilot these for high-speed quality control, displacing conventional CMOS arrays in velocity-critical inspection.
- Software:Deep learning toolkits command expanding margin pools as hardware commoditizes, though algorithmic development concentrates talent pools in Japan and North America.
- Hardware:Embedded processing modules are consolidating camera-server architectures into single-device deployments, compressing system integration costs for semiconductor fabs.
Cameras anchor the volume base while sensors gain share at the steepest rate as event-based architectures displace frame-based imaging in speed-sensitive applications.
Technology:
Cost tier stratification separates premium deep learning stacks from commoditized image processing libraries, with regulatory validation requirements widening the spend gap between medical-grade and industrial deployments.
- Machine Learning:Supervised learning pipelines for defect classification require extensive training data provenance documentation under EU AI Act conformity mandates. Medical device manufacturers in France and Germany front-load validation investments to satisfy risk-classification frameworks.
- Image Processing:Traditional edge-detection and filtering algorithms serve mature surveillance applications where price sensitivity dominates procurement decisions.
- Computer Vision:Real-time robotic guidance systems in Munich industrial corridors demand sub-pixel measurement accuracy for precision assembly verification.
- Artificial Intelligence:Autonomous decision-making systems for driver assistance face KBA performance certification requirements that shape European road deployment timelines.
Image processing retains the largest installed base while machine learning expands most quickly as automotive and medical buyers absorb validation costs for higher-accuracy outcomes.
Application:
Volume concentration in industrial automation contrasts with emerging healthcare demand currently blocked by FDA and EMA clearance timelines, creating white space for validated first-movers.
- Surveillance:Mature security applications prioritize cost minimization over performance differentiation, with standardized hardware-software bundles dominating municipal and commercial procurement.
- Industrial Automation:Vision-guided robotics for quality inspection are expanding fastest in Germany's industrial corridor around Stuttgart and Munich, pulling embedded camera and processing demand from automotive manufacturers.
- Autonomous Vehicles:Camera-based driver assistance systems require KBA certification in Germany and face divergent NHTSA and EU regulatory timelines that complicate go-to-market sequencing.
- Healthcare:AI-enabled diagnostic imaging faces 18-36 month FDA premarket clearance cycles, limiting supplier entry into radiology and pathology despite clinical demand.
Industrial automation commands current revenue concentration while healthcare climbs the fastest as regulatory backlogs eventually clear for validated diagnostic platforms.
End User:
Customer type determines procurement modality, with manufacturers favoring capital expenditure models and transportation operators shifting toward per-inspection or outcome-based service structures.
- Manufacturers:Semiconductor fabs in Japan and Taiwan are unbundling after-sales service from hardware procurement, pressuring suppliers to absorb uptime risk through consumption-based pricing.
- Transportation:Automotive OEMs and tier-one suppliers in Germany validate camera systems against KBA performance standards for European road deployments.
- Retail:Inventory tracking and customer analytics applications favor low-cost, high-volume camera deployments with cloud-based processing to minimize edge hardware investment.
- Defense:Mission-critical imaging systems demand hardened specifications and extended supplier qualification timelines that favor established vendors with direct government contracting relationships.
Manufacturers represent the deepest current demand pool while transportation is expanding fastest as autonomous vehicle programs accelerate validation spending.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's KBA performance mandates for automotive camera systems are accelerating validation investments across European supply chains. Japan's METI automation incentives are pulling embedded vision demand into semiconductor fabrication. The United States FDA premarket clearance timelines are blocking supplier entry into diagnostic imaging despite clinical demand concentration.
Germany
Automotive manufacturers in Stuttgart and Munich are expanding vision-guided robotics for quality inspection, pulling embedded camera and processing demand. The KBA enforces specific performance standards for camera-based driver assistance systems, shaping European road deployment timelines. Baden-Württemberg's industrial corridor anchors tier-one supplier pilot programs for neuromorphic quality control.
Japan
Semiconductor fabs in Tokyo and Osaka are unbundling after-sales service from hardware procurement, pressuring consumption-based pricing models. METI automation incentives support rapid customization turnaround for electronics manufacturing. The Kanto region concentrates deep learning toolkit development talent pools that command expanding margin pools.
United States
AI-enabled diagnostic device developers face 18-36 month FDA premarket clearance cycles, limiting radiology and pathology entry. The Pacific Northwest and Greater Boston clusters house computer vision engineering talent for manufacturing line deployment. NHTSA regulatory timelines diverge from EU AI Act frameworks, complicating autonomous vehicle go-to-market sequencing.
China
Foundry operators in Taiwan and South Korea are pressuring vision suppliers to absorb uptime risk through outcome-based service structures. MIIT standards shape domestic camera interface specifications for factory automation. The Yangtze River Delta industrial belt concentrates demand for sub-pixel measurement accuracy in electronics assembly verification.
South Korea
Memory and logic chip manufacturers in the Seoul Capital Area require 60+ fps frame rates for real-time defect detection. MFDS regulatory pathways for AI-enabled medical devices create parallel validation requirements to FDA and EMA frameworks. Busan-Ulsan manufacturing complexes are piloting edge-AI processing modules that bypass centralized server dependencies.
Smart Vision Systems Market Competitive Landscape
Listed leaders compete with private specialists across hardware-software bundle configurations, creating tiered competitive dynamics. The supplier base fragments across modular camera manufacturers, deep learning toolkit developers, and integrated system architects. Three archetypes dominate: premium-tier full-stack providers, mid-market hardware specialists, and software-centric algorithm vendors. Strategic moves concentrate on M&A for talent acquisition and geographic expansion through direct sales channel investments.
Within the premium-tier full-stack segment, Cognex Corporation and Keyence Corporation exemplify integrated hardware-software positioning, while Basler AG occupies the modular camera specialist archetype with interface flexibility for third-party processing stacks.
| Leading Market Players |
|---|
| Cognex Corporation |
| Keyence Corporation |
| Basler AG |
| Teledyne DALSA |
| Omron Corporation |
| FLIR Systems |
| Datalogic S.p.A. |
| National Instruments Corporation |
| IDS Imaging Development Systems GmbH |
| Others |
Pricing and Supply Chain Analysis
Outcome-based service contracts in semiconductor fabrication are locking vision system suppliers into multi-year uptime commitments that compress hardware margins while guaranteeing recurring software revenue streams. German automotive OEMs in Stuttgart and Munich are migrating toward per-inspection pricing models that shift capital expenditure risk onto vendors.
Pricing Analysis
Certification level (ISO 10218/CE/FDA-grade) creates the primary spread between premium full-stack bundles and commoditized camera modules. Three-tier pricing structure across premium, standard, and economy levels reflects validation depth, with medical-grade systems commanding substantial premiums over industrial inspection tiers. Cost compression in sensor hardware is intensifying because GigE and USB3 interface standardization erodes modular camera margins. Surveillance end-users exhibit highest price sensitivity, while semiconductor fabs absorb premium pricing for sub-pixel accuracy guarantees.
Supply Chain Analysis
Strategic stockpiling of neuromorphic event sensors is emerging among German tier-one suppliers seeking to buffer against Taiwan foundry lead time volatility. Component sourcing draws from Japan for precision optics, Taiwan for CMOS fabrication, and Germany for automotive-grade assembly validation. Single-source vulnerability concentrates in advanced sensor die supply from East Asian wafer facilities. Distribution runs through direct sales channels for enterprise accounts and specialized distributors for mid-market industrial automation buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart vision systems are approaching a platform-economics inflection where edge-AI processing convergence collapses discrete hardware-software stacks into unified inference engines. Interoperability standards for third-party processing stack integration will determine which suppliers capture expanding margin pools.
For Market Incumbents: Consolidate algorithmic talent pools through targeted acquisitions in Japan and North America where deep learning toolkit development concentrates. Defend against modular camera commoditization by embedding proprietary inference accelerators into camera-server architectures, converting one-time hardware sales into recurring software licensing tied to inspection volume.
For New Entrants and Emerging Players: Anchor in healthcare diagnostic imaging where FDA premarket clearance backlogs currently block established suppliers, creating white space for validated first-movers in radiology and pathology applications. Target outcome-based service contracts with Taiwan and South Korea foundry operators seeking to offload uptime risk, bypassing capital-intensive direct sales channel buildouts.
For Investors and Strategic Acquirers: Edge-AI software specialists with healthcare regulatory pathways represent the highest-conviction acquisition archetype for medium-term value creation. Long-term viability hinges on differentiation durability as hardware commoditization accelerates across camera and sensor categories. Monitor EU AI Act conformity assessment timelines as the critical inflection signal for European market access valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Deep Learning Toolkit Acquisition | Consolidates scarce computer vision engineering talent concentrated in Japan and North America. |
| FDA Premarket Clearance Pathway | Unlocks healthcare diagnostic imaging revenue blocked by 18-36 month validation cycles. |
| Edge-AI Processing Module Launch | Bypasses centralized server dependencies for standalone semiconductor inspection deployments. |
| Direct Sales Channel Expansion | Mirrors Keyence's rapid customization turnaround model in Germany's Stuttgart-Munich corridor. |
| Outcome-Based Service Contract | Absorbs uptime risk for Taiwan foundry operators shifting from capital expenditure commitments. |
Research Methodology
Initial hypotheses were tested against primary input from semiconductor fab operations directors, automotive tier-one supplier procurement leads, vision system integration engineers, and healthcare regulatory affairs specialists and refined through secondary validation against SEC 10-K filings, EU AI Act conformity assessment databases, FDA premarket submission records, and Japanese METI automation incentive disclosures. Bottom-up demand modeling triangulated against top-down market sizing across hardware-software bundle configurations.
Variance decomposition across product type, technology tier, application vertical, and end-user procurement modality anchored the analytical framework throughout the projection horizon. CAGRs were derived from segment-level growth trajectory convergence. Forecast inputs incorporated KBA certification timeline assumptions for German automotive deployments and FDA clearance velocity scenarios for healthcare imaging market entry.
Decision-makers should treat outputs as directional under sustained EU AI Act enforcement and stable semiconductor capital expenditure cycles; material deviation in regulatory timeline convergence or foundry automation spending would warrant model refresh. Practitioners should keep alternative scenarios live as event-based sensor adoption rates and edge-AI processing cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Stroboscope Market
Optics
Global Fiber Optic Sensors Market
Optics
Optical Wavelength Service Market
Optics
Global Nanophotonics Market
Optics
Optical Fiber Market
Optics
Beam Combining Optics Market
Optics
Fixed Focal Length Lenses Market
Optics
Optical Measuring Systems Market
Optics
Optical Sensing Market
Optics
Excimer Lasers for DUV Lithography Market
Optics
Global Enhanced Vision System Market
Optics
Optical Imaging Market
Optics
Photonic Crystals Market
Optics
Europe Laser Interferometer Market
Optics
Photostimulation Lasers Market
Optics
Picosecond Lasers Market