
 Ceramic Chip Antenna Market | 2026-2036
Ceramic Chip Antenna Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramic Chip Antenna Market Outlook
Component licensing revenue is tilting from discrete antenna sales toward integrated RF front-end modules. Murata Manufacturing Co., Ltd. leverages its ceramic material science leadership to dominate high-frequency dielectric formulations. TDK Corporation anchors European automotive design-ins through proximity to BMW and Volkswagen RF engineering centers. Vishay Intertechnology, Inc. competes on thick-film process economies for cost-sensitive consumer electronics slots.
A ceramic chip antenna is a surface-mountable, low-profile RF component fabricated from high-permittivity dielectric ceramics such as barium titanate or zirconium tin titanate, typically measuring under 3.2 mm in longest dimension, designed to convert guided electromagnetic waves into radiated waves for wireless communication in space-constrained devices. Its primary purpose is enabling reliable wireless connectivity in smartphones, automotive telematics units, and IoT sensors where physical volume and parasitic losses must be minimized. Passive ceramic chip antennas occupy the largest volume share due to their zero-bias simplicity and lowest bill-of-materials cost, while integrated modules combining matching networks and switch elements capture expanding margin pools as OEMs outsource RF complexity. Multi-band designs for simultaneous Wi-Fi, Bluetooth, and GPS operation represent the fastest-growing product configuration, driven by smartphone OEM demand for consolidated RF subsystems.
The Federal Communications Commission enforces Part 15 emissions limits that constrain antenna efficiency-bandwidth tradeoffs in US-market devices, while the European Union Radio Equipment Directive mandates interoperability and spectrum efficiency certifications that shape product development roadmaps for CE-marked goods. Japan's Ministry of Internal Affairs and Communications sets stringent specific absorption rate thresholds that influence ceramic formulation choices for handsets sold domestically. Stakeholders must monitor evolving 6 GHz Wi-Fi 6E and 7 band allocations, as regulatory clarity on unlicensed spectrum access will determine whether manufacturers prioritize wideband ceramic designs or maintain discrete narrowband portfolios.
Market Dynamics
The ceramic chip antenna market pivots on the tension between miniaturization imperatives and multi-band performance requirements, as 5G millimeter-wave deployment forces dielectric material innovation at unprecedented frequency ranges.
Growth Catalysts
- Vehicle electrification mandates:Automotive telematics modules now require ceramic antennas for V2X communication, with EU CO2 regulations accelerating OEM design cycles.
- FCC Part 15 unlicensed spectrum expansion:New 6 GHz allocations for Wi-Fi 6E are forcing device manufacturers toward wideband ceramic formulations that cover legacy and emerging bands simultaneously.
- Barium titanate dielectric advances:South Korean materials labs have achieved permittivity values above 80 at sub-6 GHz, enabling smaller footprints without efficiency loss.
Market Restraints
- Precious metal electrode costs:Silver-palladium thick-film formulations face price volatility that compresses margins for passive antenna producers serving consumer electronics.
- Japanese ceramic powder concentration:High-purity titanate precursors originate from a narrow supplier base in Kyushu, creating single-source vulnerability for non-integrated manufacturers.
- Specific absorption rate ceilings:Japan's Ministry of Internal Affairs and Communications maintains SAR thresholds that limit radiated power in compact handset designs.
Strategic Opportunities
- India PLI scheme for telecom equipment:Localized antenna production incentives are attracting module integrators to establish ceramic firing capacity near Bengaluru EMS clusters.
- Wi-Fi 7 and UWB convergence:Tri-band antennas combining 2.4 GHz, 5 GHz, and 6-8 GHz UWB positioning open premium slots in asset-tracking and automotive keyless entry.
- Direct-to-module procurement:Smartphone OEMs are bypassing discrete component distributors, creating captive supply agreements with ceramic specialists for matched filter-antenna subassemblies.
Industry Challenges
- Electromagnetic simulation talent scarcity:Finite-element modeling for high-frequency dielectric behavior requires specialized RF engineers concentrated in Munich, Seoul, and San Diego.
- RoHS compliance recertification:Lead-free electrode formulations demand renewed reliability testing cycles that delay new product introductions by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramic Chip Antenna Market |
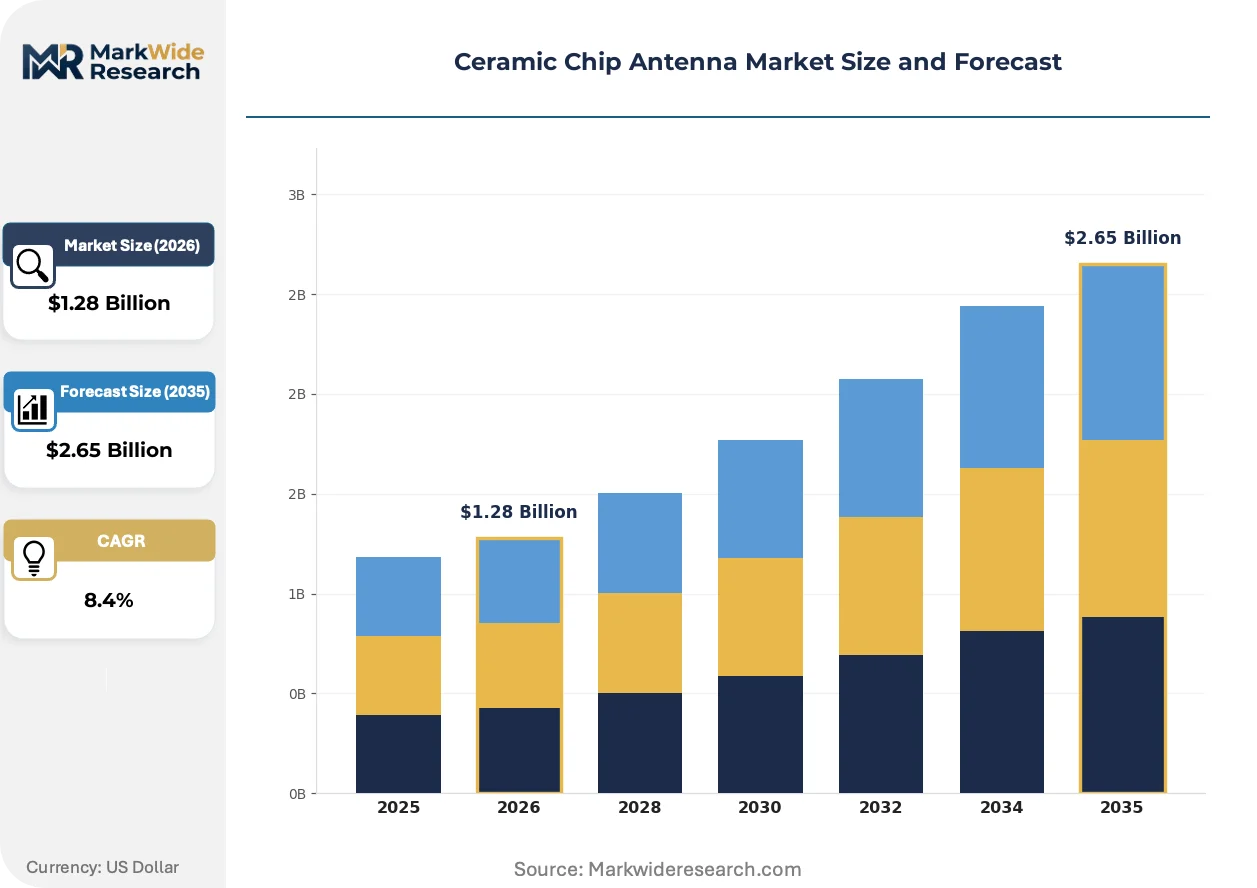
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive, Active, Integrated, Multi-band Application: Telecommunications, Automotive, Consumer Electronics, Industrial IoT Technology: Wi-Fi, Bluetooth, GPS, NFC End User: OEMs, Telecom Providers, Device Manufacturers, Researchers |
| Companies Covered | Vishay Intertechnology, Inc., Yageo Corporation, Johanson Technology, Inc., Mitsubishi Materials Corporation, Antenova Ltd., Murata Manufacturing Co., Ltd., TDK Corporation, INPAQ Technology Co., Ltd., Partron Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramic Chip Antenna Market Strategic Shifts
Dielectric engineering and spectrum policy are converging to reshape ceramic antenna architectures, with material science advances outpacing legacy manufacturing constraints.
Low-temperature co-fired ceramic (LTCC) multilayering is rendering obsolete traditional single-layer stamped antennas in premium smartphone slots. Samsung and Apple tier-one suppliers have shifted procurement toward 20-layer LTCC stacks that integrate matching networks, filters, and antenna elements in sub-2 mm z-height. This consolidation is rendering obsolete the discrete component supply chains that dominated 4G-era RF front-ends.
REACH restrictions on nickel-bearing electrodes are compelling European automotive suppliers to adopt copper-based metallization for ceramic antennas in BMW and Volkswagen telematics units. The substitution increases firing complexity but eliminates hazardous substance documentation burdens. German Tier-1 module houses are responding by qualifying Japanese copper-paste formulations ahead of 2025 model-year platforms.
Consolidated RF subsystem procurement is compressing vendor lists at major smartphone OEMs, with ceramic antenna specialists now competing for module-level design-ins rather than discrete component slots. This concentration favors suppliers offering simulation-to-production vertical integration. The shift is most visible in South Korea, where LG Innotek and Samsung Electro-Mechanics have absorbed antenna matching functions previously outsourced to independent specialists.
Ceramic Chip Antenna Market Segmentation
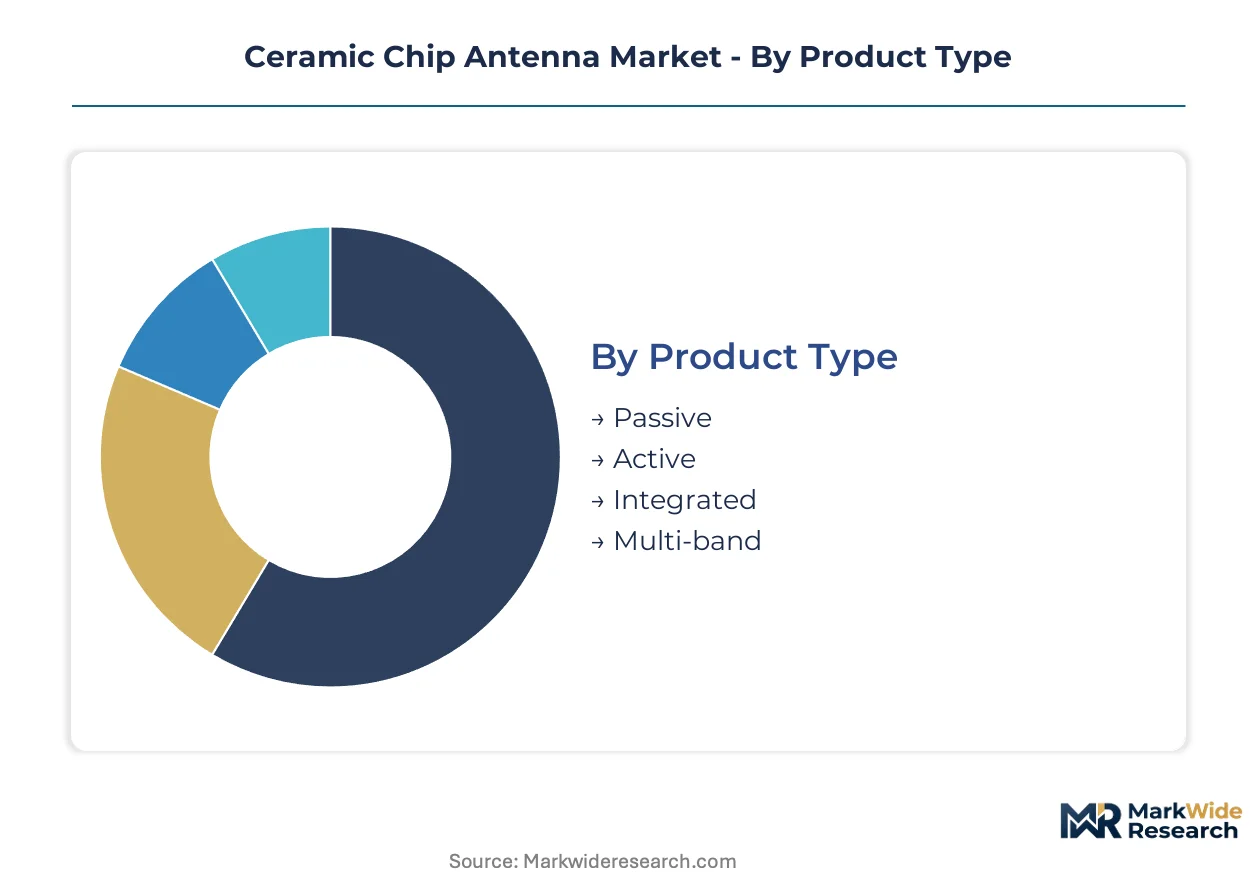
Ceramic chip antenna procurement patterns diverge sharply across product architectures and end-use applications, with RF subsystem integration levels determining supplier relationships and technical service intensity. Understanding these segment boundaries clarifies where margin pools concentrate versus where commoditization pressures dominate.
Product Type:
After-sales technical support intensity escalates with product complexity, as integrated modules demand field application engineering that passive components rarely require.
- Passive:Zero-bias surface-mount devices fabricated from barium titanate or zirconium tin titanate deliver the lowest bill-of-materials cost for single-band applications. Volume procurement concentrates in South Korean smartphone EMS clusters, where Samsung and LG device ecosystems drive high-volume, low-touch supply agreements with minimal technical support overhead.
- Multi-band:Consolidated 2.4 GHz, 5 GHz, and sub-6 GHz architectures enable simultaneous Wi-Fi, Bluetooth, and GPS operation in space-constrained wearables. Automotive telematics modules in Germany represent the fastest-expanding demand sink, as BMW and Volkswagen RF engineering centers specify wideband ceramic formulations for consolidated connectivity subsystems.
- Active:Amplified designs with integrated low-noise amplifiers address weak-signal environments in industrial IoT deployments.
- Integrated:Modules combining matching networks, filters, and antenna elements in LTCC stacks command premium positioning through reduced RF design cycle times.
Passive configurations hold the largest share; momentum sits with multi-band architectures.
Application:
Cost tier stratification separates premium RF subsystem outsourcing from price-sensitive direct procurement, with automotive and telecommunications occupying opposite ends of this spectrum.
- Automotive:Vehicle electrification mandates across the European Union are accelerating V2X communication module deployment, with ceramic antennas specified for telematics control units in BMW, Volkswagen, and emerging electric vehicle platforms. EU CO2 regulations compress OEM design cycles, forcing Tier-1 module houses to qualify copper-paste metallization ahead of REACH nickel restrictions.
- Telecommunications:5G base station and small-cell infrastructure demand high-efficiency dielectric formulations for sub-6 GHz and millimeter-wave bands. South Korean network equipment vendors drive volume procurement of multi-layer LTCC stacks, with localized firing capacity expanding near Seoul semiconductor clusters to reduce logistics exposure.
- Consumer Electronics:Smartphones and wearables prioritize sub-2 mm z-height solutions with minimal specific absorption rate compliance burden.
- Industrial IoT:Asset-tracking and smart manufacturing sensors require ruggedized ceramic packages for extended temperature ranges.
Automotive applications are climbing the fastest; telecommunications maintains the deepest volume base.
Technology:
Application maturity determines whether technology segments compete on performance specifications or on thick-film process economies alone.
- Wi-Fi:FCC Part 15 unlicensed spectrum expansion into 6 GHz for Wi-Fi 6E is forcing device manufacturers toward wideband ceramic formulations. US-market smartphone OEMs now specify antennas covering legacy 2.4 GHz and 5 GHz bands alongside emerging 6-8 GHz allocations in single dielectric packages.
- Bluetooth:Low-energy protocols in wearable devices and automotive keyless entry systems favor compact ceramic chip antennas with minimal footprint. South Korean consumer electronics EMS providers dominate procurement volume for sub-3.2 mm Bluetooth-specific designs.
- GPS:Precision positioning requirements in telematics and drone navigation demand tight phase-center stability.
- NFC:Payment and access control applications utilize ferrite-backed ceramic structures for magnetic field isolation.
Wi-Fi commands the largest installed base; Bluetooth is gaining share fastest in automotive and wearable slots.
End User:
Customer type dictates procurement channel structure, with OEM direct relationships displacing distributor intermediaries in high-volume segments.
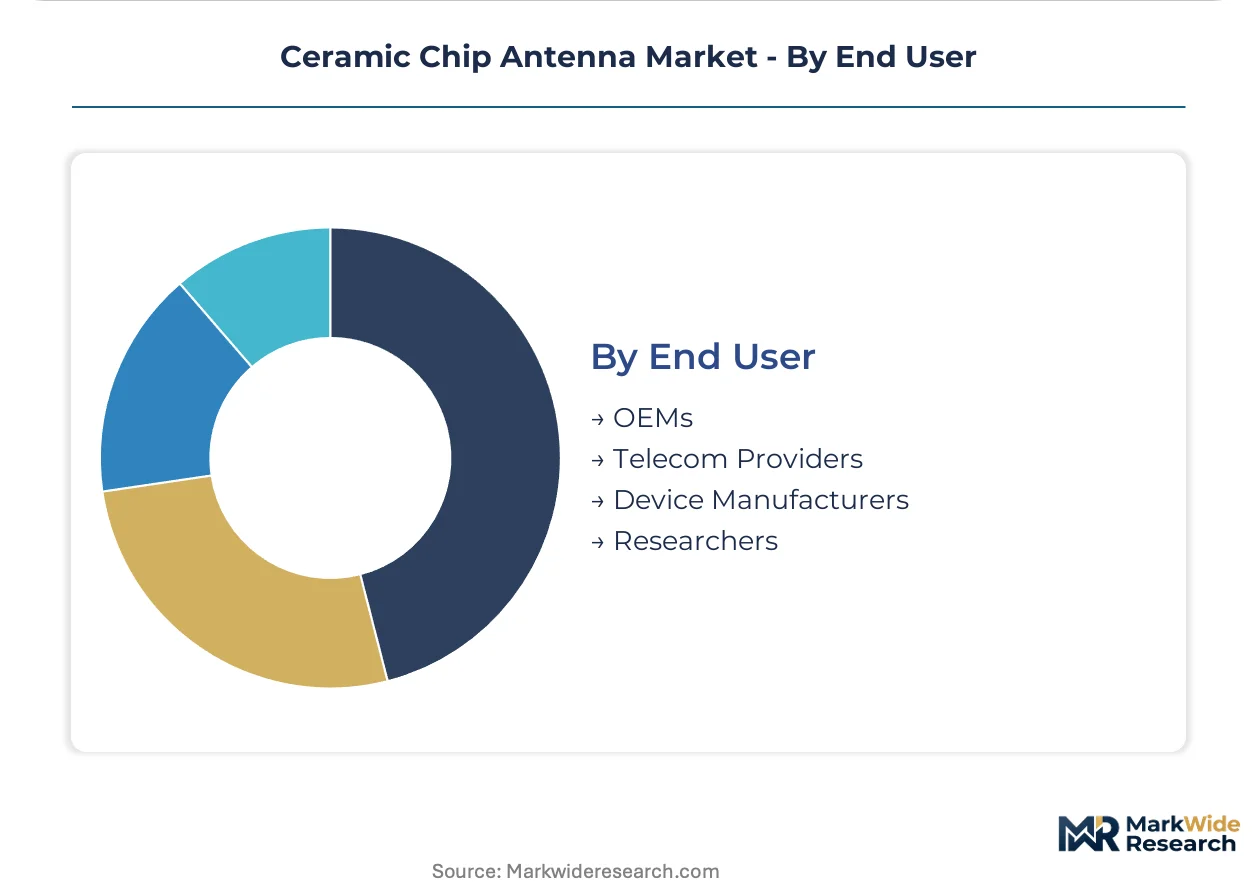
- Device Manufacturers:Samsung, Apple, and LG tier-one suppliers have shifted procurement toward 20-layer LTCC stacks that integrate matching networks and antenna elements. This consolidation is absorbing antenna matching functions previously outsourced to independent specialists, compressing vendor lists at major smartphone OEMs.
- OEMs:German automotive manufacturers specify ceramic antennas at the platform design stage, with BMW and Volkswagen RF engineering centers qualifying Japanese copper-paste formulations ahead of model-year transitions. Proximity to European design hubs anchors TDK Corporation's regional position.
- Telecom Providers:Network infrastructure procurement emphasizes reliability certification and multi-source supply assurance.
- Researchers:University and national laboratory demand focuses on experimental dielectric formulations and custom frequency specifications.
Device manufacturers hold the largest share; OEMs are expanding procurement most aggressively as vehicle connectivity mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean device manufacturers consume ceramic chip antennas primarily for smartphone multi-band consolidation, while German automotive OEMs prioritize telematics integration and Japanese suppliers focus on SAR-compliant handset formulations. This consumption-mix differential shapes regional specialization patterns across the forecast window.
South Korea
Samsung and LG device ecosystems drive volume procurement of multi-band ceramic chip antennas for 5G smartphones and wearables. The Ministry of Science and ICT enforces radio wave certification standards that accelerate wideband design validation cycles. Seoul semiconductor clusters concentrate LTCC firing capacity expansion as EMS providers localize supply chains to reduce logistics exposure.
Germany
BMW and Volkswagen RF engineering centers specify ceramic antennas for V2X communication modules in electrified vehicle platforms. EU CO2 regulations compress OEM design cycles and force Tier-1 module houses to qualify copper-paste metallization ahead of REACH nickel restrictions. Bavaria anchors European automotive design-ins through proximity to manufacturer engineering centers.
Japan
Domestic handset OEMs demand ceramic formulations meeting stringent specific absorption rate thresholds set by the Ministry of Internal Affairs and Communications. Kyushu hosts a concentrated supplier base for high-purity titanate precursors, creating single-source vulnerability for non-integrated manufacturers. Tokyo-based materials labs advance dielectric permittivity values for sub-6 GHz applications.
United States
FCC Part 15 emissions limits constrain antenna efficiency-bandwidth tradeoffs in devices targeting US-market distribution. The 6 GHz Wi-Fi 6E spectrum expansion forces manufacturers toward wideband ceramic formulations covering legacy and emerging bands simultaneously. San Diego and Austin RF engineering clusters concentrate electromagnetic simulation talent for high-frequency dielectric behavior modeling.
India
PLI scheme incentives for telecom equipment localize antenna production near Bengaluru EMS clusters. The Department of Telecommunications implements mandatory testing and certification requirements for wireless equipment that shape product development roadmaps. Karnataka semiconductor assembly operations expand ceramic firing capacity to serve domestic smartphone manufacturing.
Ceramic Chip Antenna Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another, creating a bifurcated competitive structure. Japanese and Korean materials specialists dominate high-frequency dielectric formulations through ceramic science leadership, while Taiwanese and Chinese fabricators compete on thick-film process economies for cost-sensitive slots. Three archetypes populate the landscape: integrated module houses with simulation-to-production verticality, pure-play antenna specialists with RF matching expertise, and diversified passive component conglomerates with firing capacity scale. Capacity expansion and direct-to-module procurement agreements constitute the dominant competitive moves as smartphone OEMs compress vendor lists.
Among Japanese manufacturers, Murata Manufacturing Co., Ltd. and TDK Corporation occupy positions exemplifying materials-led competitive advantage. Murata represents the integrated archetype through ceramic formulation leadership, while TDK anchors European automotive design-ins through regional engineering proximity. Vishay Intertechnology, Inc. sits within the diversified passive component tier, competing on thick-film process scale for consumer electronics procurement slots. These three entities collectively illustrate how geographic origin and corporate structure map to distinct positioning vectors in the competitive landscape.
| Leading Market Players |
|---|
| Vishay Intertechnology, Inc. |
| Yageo Corporation |
| Johanson Technology, Inc. |
| Mitsubishi Materials Corporation |
| Antenova Ltd. |
| Murata Manufacturing Co., Ltd. |
| TDK Corporation |
| INPAQ Technology Co., Ltd. |
| Partron Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Incheon-Seoul freight corridors carry barium titanate precursors from Kyushu firing facilities, with logistics cost volatility translating directly into margin compression for non-integrated passive antenna producers and premium pricing power for LTCC module houses serving Samsung and Apple tier-one suppliers.
Pricing Analysis
Long-term offtake contracts dominate procurement between Japanese materials specialists and South Korean EMS clusters, locking in silver-palladium paste pricing amid precious metal volatility. Three-tier pricing structure across premium LTCC modules, standard multi-band configurations, and economy passive chips reflects certification grade and simulation-to-production verticality. Cost compression in economy passive tiers intensifies because Vishay and Yageo compete on thick-film process scale for high-volume smartphone slots. Automotive OEMs exhibit least price sensitivity, prioritizing REACH-compliant copper-paste formulations and field application engineering over unit cost.
Supply Chain Analysis
Tariff exposure between Japan and South Korea dominates supply chain risk planning for ceramic powder shipments, though the narrow Kyushu supplier base for high-purity titanate precursors presents acute single-source vulnerability. Manufacturing concentrates in Japan, South Korea, and Taiwan, with raw material dependencies on barium carbonate, titanium dioxide, and silver-palladium electrode pastes. Distribution runs through captive supply agreements directly to smartphone OEM module houses, bypassing traditional component distributors as procurement consolidates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive V2X platform standardization creates ecosystem lock-in effects, with BMW and Volkswagen telematics architectures forcing supplier interoperability commitments that reshape competitive positioning across the forecast window.
For Market Incumbents: Entrench through backward integration into high-purity titanate precursor production, eliminating Kyushu single-source exposure. Secure captive supply agreements with Samsung and LG tier-one suppliers for matched filter-antenna subassemblies. Prioritize copper-paste metallization qualification ahead of REACH nickel restrictions to defend automotive design-ins.
For New Entrants and Emerging Players: Pursue India PLI scheme localization near Bengaluru EMS clusters, where telecom equipment incentives attract module integrators establishing ceramic firing capacity. Target industrial IoT asset-tracking segments with ruggedized wide-temperature ceramic packages, a white-space with limited incumbent focus. Lead with direct RF matching expertise rather than commodity passive volume.
For Investors and Strategic Acquirers: FCC Part 15 unlicensed spectrum expansion into 6 GHz and Wi-Fi 7 band allocations reshapes the acquisition landscape toward wideband dielectric formulation capabilities. Long-term viability centers on suppliers offering simulation-to-production verticality as OEM vendor lists compress. Watch for regulatory clarity on 6 GHz power limits as the signal indicating whether wideband or narrowband portfolio strategies prevail.
| Strategic Initiative | Industry Significance |
|---|---|
| LTCC Multilayer Capacity Expansion | 20-layer stack integration absorbs discrete matching functions previously outsourced to specialists. |
| Copper-Paste Metallization Qualification | REACH nickel restrictions force BMW and Volkswagen suppliers toward hazardous-substance-free electrodes. |
| Direct-to-Module Procurement Agreements | Samsung and Apple tier-one suppliers bypass distributors for captive antenna-filter subassemblies. |
| India PLI Scheme Localization | Bengaluru EMS clusters attract firing capacity to serve domestic smartphone manufacturing growth. |
| Wideband Dielectric Formulation R&D | FCC Part 15 6 GHz allocations require ceramic designs covering legacy and emerging bands simultaneously. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade records, and patent databases. RF engineering directors at smartphone OEMs, procurement leads at German Tier-1 automotive module houses, ceramic materials scientists at Japanese suppliers, and EMS operations managers in South Korean semiconductor clusters provided operating data. FCC Part 15 dockets, EU Radio Equipment Directive implementation guidance, Japan MIC radio wave certification standards, and India PLI scheme notifications furnished secondary validation. Bottom-up bill-of-materials analysis and top-down end-use consumption estimates were triangulated.
Forecast inputs include dielectric permittivity advancement trajectories, V2X module penetration rates in EU electrified vehicle platforms, and Wi-Fi 6E/7 device shipment patterns across the projection horizon. Segmentation dimensions encompass product architecture complexity, end-use application cost tier, wireless protocol technology, and customer procurement channel structure. CAGRs derive from installed base growth, replacement cycle dynamics, and content-per-device expansion in multi-band RF subsystems. Millimeter-wave deployment timing and SAR threshold evolution represent key scenario variables.
Sensitivities concentrate around 6 GHz regulatory clarity, precious metal electrode price volatility, and electromagnetic simulation talent scarcity in Munich, Seoul, and San Diego clusters. Forecasts reflect documented assumptions regarding OEM vendor list compression and module integration migration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Power Line Communication (PLC) Market
Communication Chips & Hardware
Global Narrowband IoT (NB IoT) Chipset Market
Communication Chips & Hardware
Asia-Pacific Embedded Antenna Systems Market
Communication Chips & Hardware
Communication Standard Logic IC Market
Communication Chips & Hardware
Zigbee Enabled Devices Market
Communication Chips & Hardware
Bluetooth Smart and Smart Ready Market
Communication Chips & Hardware
Zigbee System-On-Chip Market
Communication Chips & Hardware
Ethernet Phys Market
Communication Chips & Hardware
Global Wireless Gigabit Market
Communication Chips & Hardware
Smart TV Chip Market
Communication Chips & Hardware
Japan Digital Signal Processor Market
Communication Chips & Hardware
IPC Soc Chip Market
Communication Chips & Hardware
Wireless Connectivity Chipset Market
Communication Chips & Hardware
Ethernet PHY Chip Market
Communication Chips & Hardware
I2C Bus Market
Communication Chips & Hardware
Bluetooth Audio Soc Chips Market